
 Global Surgical Masks Market | 2026-2036
Global Surgical Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Masks Market Foresight
Multi-source procurement is repositioning how hospital systems secure surgical mask supply chains. 3M leverages its material science portfolio to sustain filtration performance leadership across North American acute care networks. Owens & Minor anchors distribution scale through direct-to-hospital logistics platforms that bypass traditional wholesale intermediaries.
A surgical mask is a loose-fitting, disposable device that creates a physical barrier between the wearer's mouth and nose and potential contaminants in the immediate environment, typically constructed from three layers of non-woven polypropylene with melt-blown filtration media achieving bacterial filtration efficiency thresholds. Its primary purpose is to protect the patient and sterile field from respiratory emissions of the wearer during medical procedures. Disposable masks dominate procurement volumes due to infection control protocols that mandate single-use disposal, while anti-fog variants command premium positioning in ophthalmic and endoscopic procedures where visual clarity is critical. Direct sales channels capture the largest margin pools by eliminating distributor markups on high-volume hospital contracts.
FDA enforcement of 510(k) clearance requirements and ASTM F2100 performance tiers shapes product differentiation and market access for manufacturers targeting the United States. EMA coordination with national competent authorities across Germany, France, and Italy enforces EN 14683 Type IIR standards that dictate bacterial filtration and splash resistance minimums for surgical masks entering European clinical settings. Stakeholders must monitor evolving biocompatibility testing protocols and regional stockpiling mandates that could abruptly reshape procurement volumes and supplier qualification timelines.
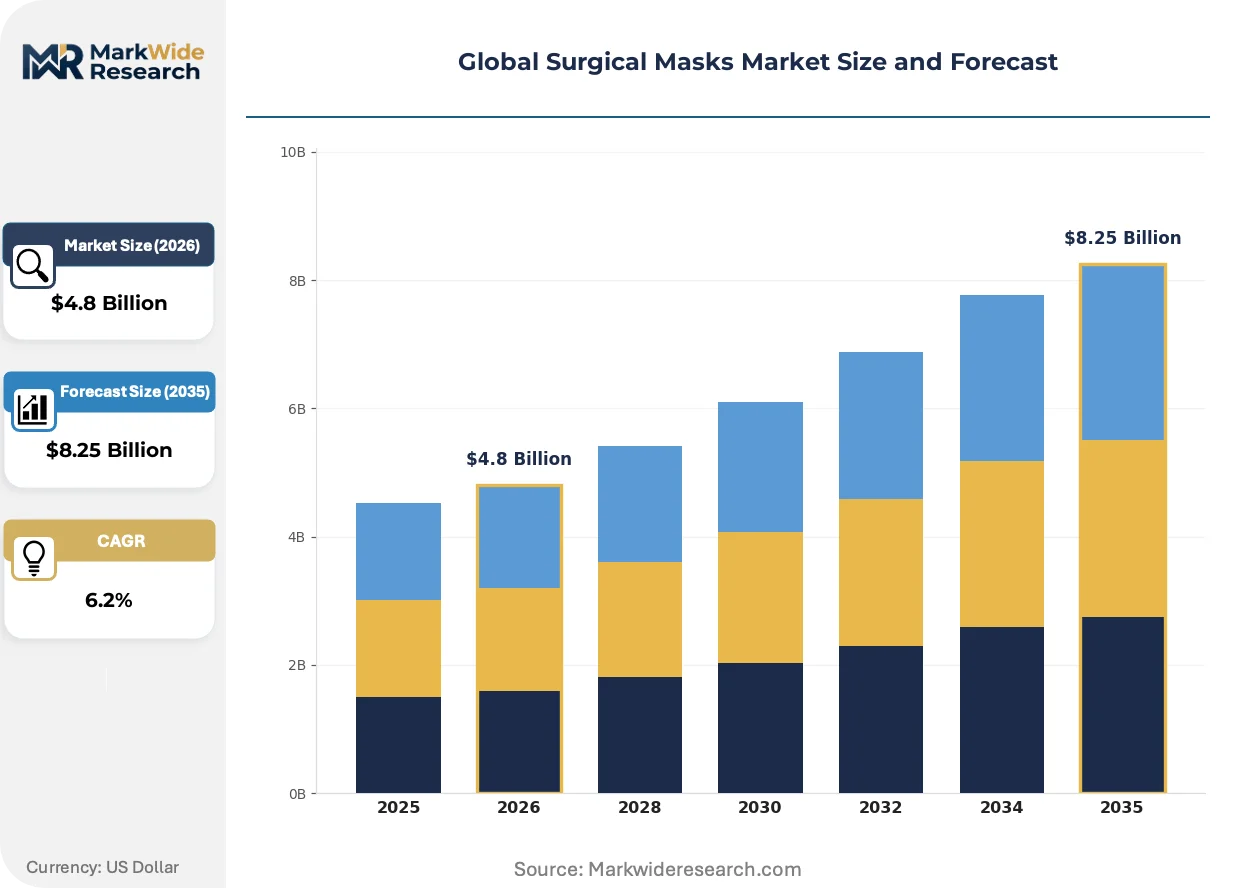
Market Dynamics
Hospital operating rooms are expanding mask procurement volumes as ASTM F2100 and EN 14683 standards tighten filtration benchmarks, forcing manufacturers to requalify product portfolios across multiple jurisdictions simultaneously.
Growth Catalysts
- ASTM F2100 Tier 3 Adoption:US acute care networks are mandating higher bacterial filtration efficiency thresholds, pulling premium mask volumes into hospital supply chains.
- India PLI Scheme:Domestic production incentives are expanding melt-blown non-woven capacity, reducing import dependency for Southeast Asian healthcare systems.
- Anti-Fog Ophthalmic Demand:Endoscopic and cataract procedure volumes are accelerating specialized mask variants with hydrophilic coating technologies.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer price swings compress margin stability for spunbond-meltblown-spunbond laminate producers.
- China Concentration Risk:Over 60% of global melt-blown fabric capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability.
- Reusable Elastomeric Substitution:Industrial respirator manufacturers are targeting healthcare adjacent segments with sterilizable alternatives.
Strategic Opportunities
- Brazil Domestic Manufacturing:ANVISA localization requirements are creating captive production incentives for multinational mask suppliers.
- Direct-to-Hospital E-Procurement:Digital tender platforms are bypassing traditional medical distributor markups in Vietnamese provincial health systems.
- Biodegradable PLA Films:Convergence of polylactic acid non-wovens with existing pleating equipment opens compostable positioning.
Industry Challenges
- FDA 510(k) Timeline Compression:Biocompatibility testing bottlenecks at third-party laboratories are extending clearance cycles for novel filtration media.
- Legacy ERP Integration:Hospital procurement systems require custom API development to automate mask consumption tracking against par-level protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Masks Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Masks, Reusable Masks, Anti-fog Masks, Sterile Masks Application: Hospital Operating Rooms, Dental Clinics, Laboratories, Ambulatory Surgery Centers, Veterinary Clinics End User: Surgeons, Dental Practitioners, Laboratory Technicians, Veterinary Professionals Distribution Channel: Direct Sales, Medical Distributors, Online Retailers, Pharmacies, Wholesale Suppliers |
| Companies Covered | Prestige Ameritech, Owens & Minor, 3M, Medline Industries, BYD Auto, Honeywell, Moldex-Metric, Cardinal Health, Kimberly-Clark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Masks Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while fragmenting competitive positioning across certification tiers.
Electrospun nanofiber membranes are achieving sub-micron filtration at reduced breathing resistance compared to conventional melt-blown polypropylene. German university medical centers are piloting these layers in cardiothoracic suites. This performance leap is electrifying the premium segment and forcing incumbent suppliers to accelerate R&D timelines or cede high-acuity contracts.
EMA coordination with Germany's BfArM and France's ANSM is tightening post-market surveillance for EN 14683 Type IIR splash resistance claims. Manufacturers must now submit batch-specific test data rather than design-dossier exemptions. European distributors are consolidating supplier panels to reduce audit burden, favoring vertically integrated producers with in-house testing laboratories.
Multi-year hospital system contracts are displacing spot-market purchasing that dominated pandemic-era procurement. US integrated delivery networks are consolidating mask specifications across 50-plus facility footprints to extract volume leverage. This consolidation is most visible in Texas and Florida health systems where procurement officers now mandate single-SKU standardization across OR, ER, and outpatient surgical units.
Global Surgical Masks Market Segmentation
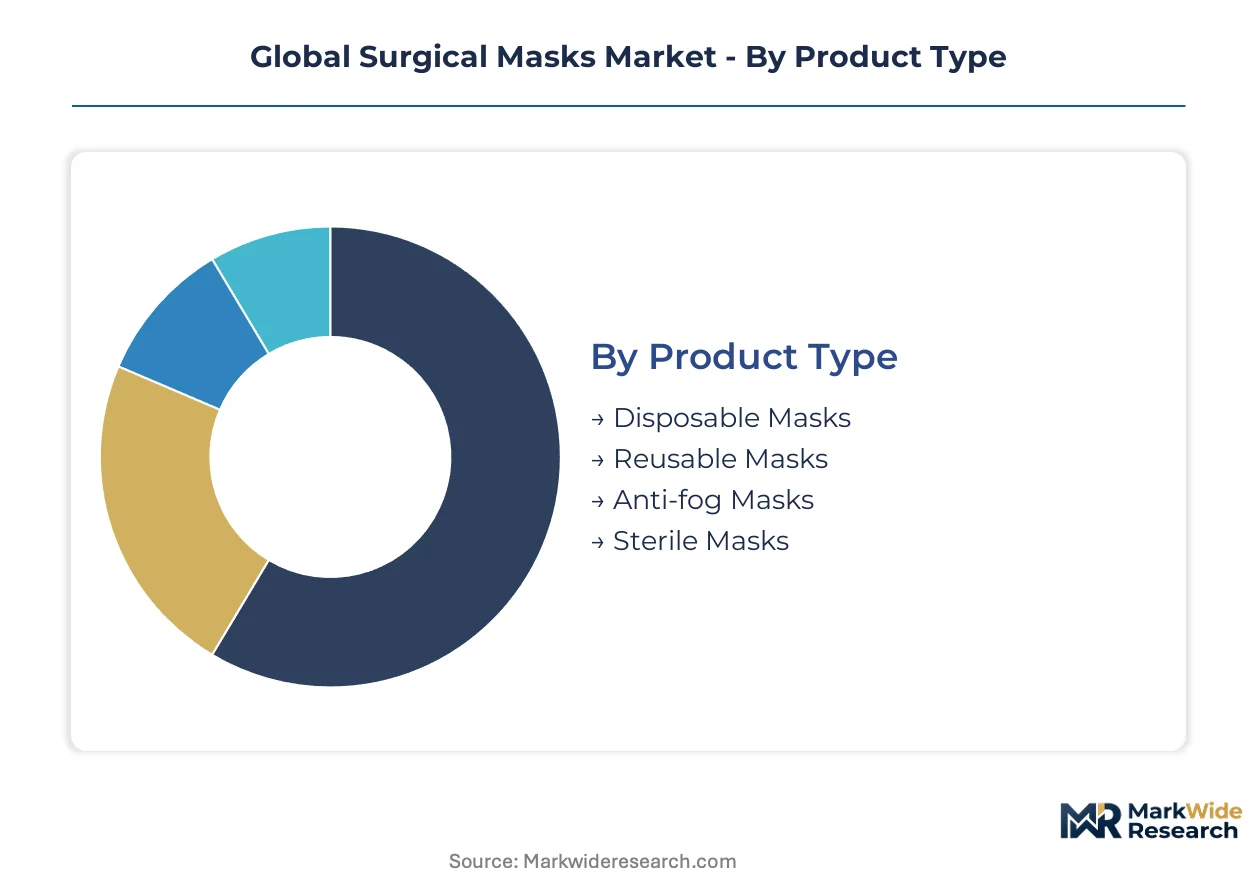
Surgical mask procurement patterns fragment sharply across clinical settings and supply chain configurations. Manufacturers must align filtration specifications, sterility protocols, and logistics models to distinct buyer requirements or forfeit contract eligibility.
Product Type:
Buyers in this category differentiate primarily by infection control mandates and procedure-specific performance needs rather than unit economics alone.
- Disposable Masks:Three-layer spunbond-meltblown-spunbond laminates dominate hospital procurement due to single-use protocols in US and European acute care networks. ASTM F2100 Tier 2 and Tier 3 specifications are becoming baseline requirements for integrated delivery network contracts.
- Anti-fog Masks:Hydrophilic coating technologies eliminate visual obstruction during ophthalmic and endoscopic procedures. Demand concentrates in German university medical centers and Indian metropolitan hospital chains where cataract and laparoscopic surgery volumes are climbing fastest.
- Sterile Masks:Gamma-irradiated or ethylene oxide-sterilized variants serve cardiothoracic and neurosurgical suites requiring aseptic field maintenance.
- Reusable Masks:Elastomeric respirator alternatives target industrial manufacturers seeking healthcare adjacent positioning through sterilizable silicone facepieces.
Disposable masks lead volumes today; anti-fog variants are gaining share fastest.
Application:
Procedure volume intensity and regulatory scrutiny depth separate application tiers in this market.
- Hospital Operating Rooms:Highest filtration efficiency mandates and bulk procurement scale define this segment. US hospital systems in Texas and Florida are consolidating specifications across 50-plus facility footprints to extract volume leverage from suppliers.
- Dental Clinics:EN 14683 Type I and ASTM F2100 Level 1 masks suffice for aerosol-generating procedures. Brazilian and Vietnamese provincial health systems are expanding dental surgical coverage, pulling mid-tier mask volumes into emerging market distribution channels.
- Ambulatory Surgery Centers:Freestanding facilities prioritize cost containment alongside basic splash resistance for outpatient procedures.
- Laboratories:Biosafety level considerations drive selection toward fluid-resistant variants for pathogen handling environments.
- Veterinary Clinics:Zoonotic disease protocols in large-animal practices are elevating mask specifications beyond basic barrier protection.
Hospital operating rooms anchor procurement value; ambulatory surgery centers are expanding most quickly.
End User:
Professional certification requirements and exposure risk profiles shape end user segmentation in surgical mask specification.
- Surgeons:Cardiothoracic and orthopedic specialists demand ASTM F2100 Tier 3 or EN 14683 Type IIR performance with documented bacterial filtration efficiency above 98 percent.
- Dental Practitioners:Oral surgery and implantology subspecialists are upgrading from basic procedural masks to fluid-resistant variants as aerosol awareness intensifies.
- Laboratory Technicians:Microbiology and pathology personnel require splash resistance combined with extended wear comfort for multi-hour specimen processing shifts.
- Veterinary Professionals:Large-animal practitioners in India and Brazil face heightened zoonotic respiratory pathogen exposure, driving specification convergence with human surgical standards.
Surgeons command premium product tiers; dental practitioners are upgrading specifications fastest.
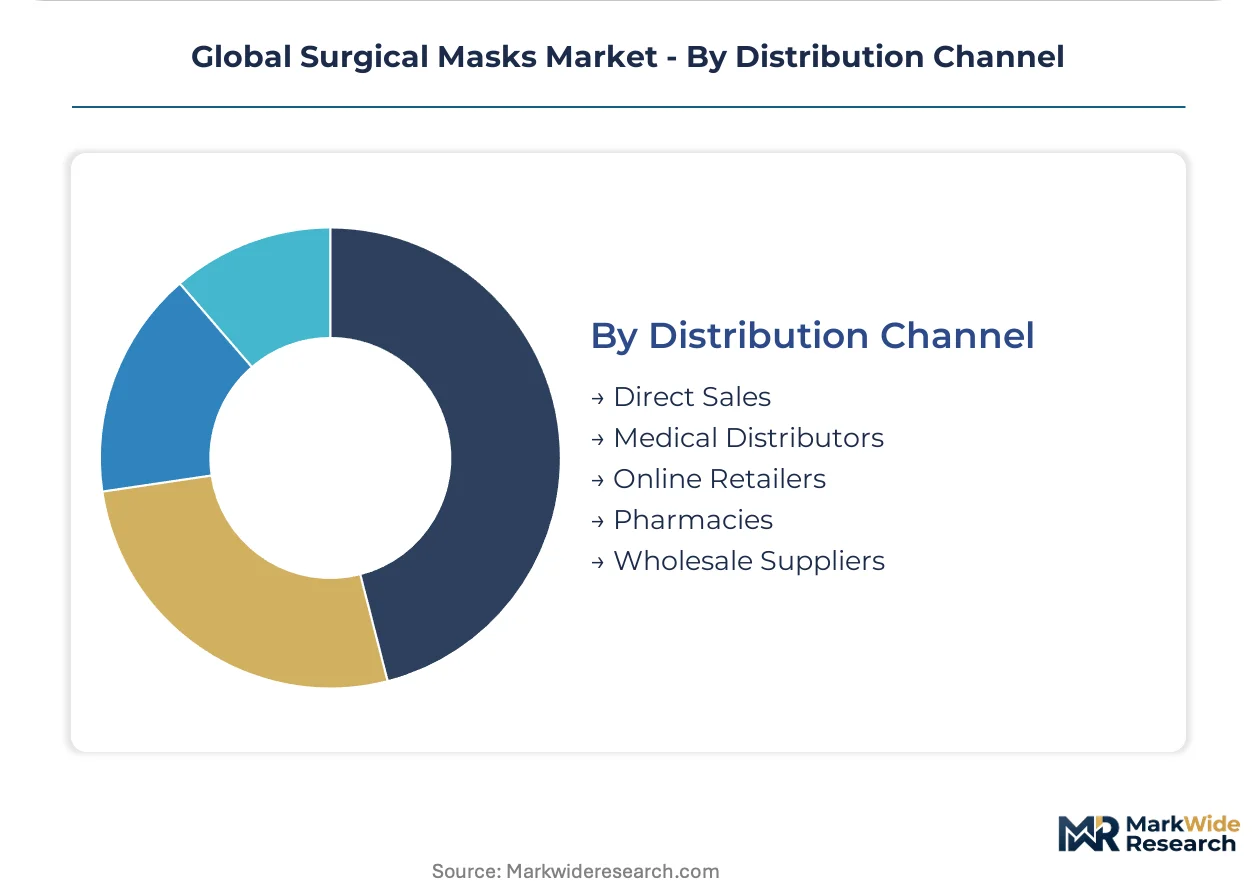
Distribution Channel:
Margin capture and procurement automation capabilities distinguish channel strategies for mask suppliers.
- Direct Sales:Hospital system contracts bypass distributor markups and enable consumption tracking integration with ERP par-level protocols. Owens & Minor anchors this channel through dedicated logistics platforms.
- Medical Distributors:Regional wholesalers retain relevance in fragmented European markets where ANSM and BfArM compliance documentation requirements favor established intermediaries with regulatory expertise.
- Online Retailers:Vietnamese provincial health systems and Indian tier-2 hospital networks are piloting digital tender platforms for mask procurement.
- Pharmacies:Retail channel serves dental and veterinary clinics with immediate replenishment needs.
- Wholesale Suppliers:Bulk spot-market positioning persists for pandemic stockpiling and emergency preparedness procurement.
Direct sales capture the largest margin pools; online retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor global melt-blown fabric capacity, concentrating over sixty percent of upstream non-woven supply. Hospital procurement volumes are expanding fastest in India, Brazil, and Vietnam as domestic production incentives reshape import dependency patterns.
United States
Texas and Florida health systems are consolidating mask specifications across fifty-plus facility footprints to extract volume leverage from suppliers. FDA enforcement of 510(k) clearance requirements shapes product differentiation and market access for manufacturers targeting acute care networks. 3M leverages its material science portfolio to sustain filtration performance leadership across North American hospital systems.
Germany
German university medical centers are piloting electrospun nanofiber membranes in cardiothoracic suites, achieving sub-micron filtration at reduced breathing resistance. BfArM coordination with EMA tightens post-market surveillance for EN 14683 Type IIR splash resistance claims. Owens & Minor anchors distribution scale through direct-to-hospital logistics platforms that bypass traditional wholesale intermediaries.
India
Metropolitan hospital chains in Delhi and Mumbai are driving anti-fog mask demand as cataract and laparoscopic surgery volumes climb. The PLI scheme expands domestic melt-blown non-woven capacity, reducing import dependency for Southeast Asian healthcare systems. Cataract procedure volumes are accelerating specialized mask variants with hydrophilic coating technologies.
Brazil
Provincial health systems are expanding dental surgical coverage, pulling mid-tier mask volumes into emerging market distribution channels. ANVISA localization requirements create captive production incentives for multinational mask suppliers. São Paulo and Rio de Janeiro anchor the domestic manufacturing push as ANVISA tightens import qualification timelines.
Vietnam
Provincial health systems are piloting digital tender platforms for mask procurement, bypassing traditional medical distributor markups. Domestic production capacity is expanding to serve Southeast Asian healthcare systems reducing China dependency. Ho Chi Minh City and Hanoi clusters are capturing regional supply chain repositioning as manufacturers seek alternative melt-blown fabric sources.
Global Surgical Masks Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent industrial respirator positioning through sterilizable alternatives. The vendor base separates into three tiers: multinational material science conglomerates with filtration media expertise, dedicated medical supply distributors with hospital logistics integration, and Asian industrial conglomerates with polymer conversion scale. Competitive moves concentrate on direct-to-hospital contract consolidation and melt-blown fabric capacity backward integration.
Among US-based producers, Prestige Ameritech and Owens & Minor exemplify the logistics-integrated archetype, while 3M represents material science leadership in filtration performance. BYD Auto occupies a position bridging industrial scale with healthcare adjacent positioning, reflecting the Asian industrial conglomerate pattern of polymer conversion expertise applied to medical supply diversification.
| Leading Market Players |
|---|
| Prestige Ameritech |
| Owens & Minor |
| 3M |
| Medline Industries |
| BYD Auto |
| Honeywell |
| Moldex-Metric |
| Cardinal Health |
| Kimberly-Clark |
| Others |
Supply & Pricing Matrix
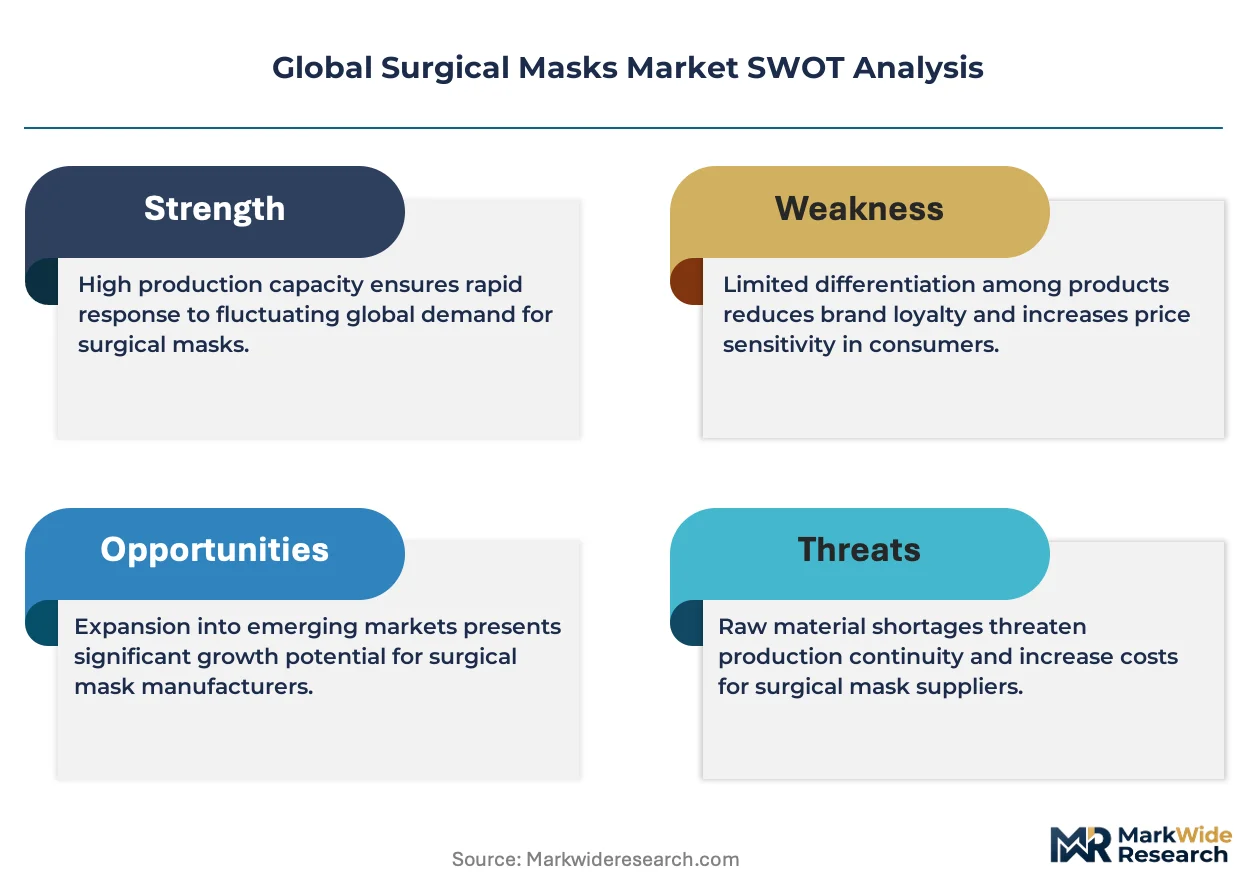
Family-owned mid-cap producers in Shandong and Jiangsu provinces anchor melt-blown fabric supply, wielding pricing discipline through captive polymer conversion and long-term offtake contracts with multinational mask assemblers. Their ownership structure insulates production decisions from quarterly earnings pressure, sustaining capacity utilization through demand cycles that destabilize publicly traded competitors.
Pricing Analysis
Propylene monomer cost pass-through dominates contract negotiations, with spunbond-meltblown-spunbond laminate producers indexing raw material exposure to regional petrochemical benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates ASTM F2100 Tier 3 hospital contracts from dental clinic spot purchases and veterinary bulk orders. Cost compression in the standard tier is intensifying because Indian and Vietnamese domestic capacity additions erode import premiums. Dental clinics and provincial Vietnamese health systems exhibit highest price sensitivity, while US integrated delivery networks absorb premium positioning for documented bacterial filtration efficiency above 98 percent.
Supply Chain Analysis
FDA 510(k) and EN 14683 Type IIR certification gating filters supplier panels, eliminating converters lacking in-house biocompatibility testing laboratories or documented quality management systems. Manufacturing concentrates in China, India, and Vietnam, with melt-blown fabric output anchored in Shandong and Jiangsu provinces and downstream conversion scaling in Ho Chi Minh City and Delhi clusters. Polypropylene resin, hydrophilic coating chemicals, and gamma-irradiation sterilization services constitute critical input dependencies. Single-source vulnerability in Chinese melt-blown capacity creates structural exposure to regional stockpiling mandates or export restriction protocols. Distribution runs through direct-to-hospital logistics platforms for US acute care networks and medical distributor intermediaries for fragmented European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical masks market reads as a late-cycle quality story, with ASTM F2100 Tier 3 and EN 14683 Type IIR specifications displacing lower-tier volumes as hospital systems consolidate procurement standards across multi-facility footprints.
For Market Incumbents: Extend certification coverage into emerging biocompatibility testing protocols before FDA timeline compression widens compliance gaps. Backward integration into melt-blown fabric production in India and Vietnam defends margin position against polypropylene feedstock volatility and Chinese concentration risk. Lock multi-year direct-to-hospital contracts with consumption tracking APIs that embed switching costs. For New Entrants and Emerging Players: ANVISA localization requirements in Brazil open a window for captive production facilities serving Latin American health systems bypassing import qualification delays. Target Vietnamese provincial digital tender platforms and Indian tier-2 hospital networks as the most penetrable procurement channels. Pursue biodegradable PLA film positioning as a sustainability-differentiated go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among logistics-integrated distributors with hospital ERP integration capabilities and regional medical supply wholesalers with ANSM and BfArM compliance expertise. Long-term viability hinges on exposure to premium filtration tier migration and direct channel share capture. Watch electrospun nanofiber membrane adoption in German university medical centers as signal of incumbent R&D response adequacy.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Biocompatibility testing bottlenecks favor early entrants with laboratory partnerships. |
| Backward Integration into Melt-Blown Capacity | Captive polymer conversion in India and Vietnam reduces China dependency exposure. |
| Hospital System Direct Contracting | ERP par-level integration with Texas and Florida health systems locks volume leverage. |
| Anti-Fog Hydrophilic Coating Development | German and Indian ophthalmic procedure volumes pull premium variant demand. |
| Biodegradable PLA Film Positioning | Compostable certification opens European sustainability procurement criteria. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and regulatory filing review — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and filtration media R&D directors. Secondary validation drew from FDA 510(k) clearances, EMA design dossiers, ASTM F2100 test reports, and EN 14683 certification records. Bottom-up facility-level demand modeling and top-down healthcare expenditure allocation were cross-referenced to triangulate volume estimates.
Historical procurement patterns were cross-referenced against panel input from supply chain executives and distribution channel managers to construct the projection framework across the analysis window. Segmentation dimensions included product type tier, application setting, end-user specialty, and distribution channel configuration. CAGRs were derived from procedure volume trajectories, regulatory mandate adoption curves, and domestic production capacity buildout schedules in India, Brazil, and Vietnam.
Revisions become necessary when FDA enforcement priorities shift, EMA post-market surveillance protocols tighten, or regional stockpiling mandates abruptly reshape procurement volumes. Forecasts reflect assumptions about certification timeline stability, polymer feedstock price regime continuity, and hospital system consolidation pace. A model refresh is warranted upon material change in electrospun nanofiber membrane clinical adoption or biodegradable non-woven cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
NPWT Canisters Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Global Disposable Syringes Market