
 Oral Syringes Market | 2026-2036
Oral Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Syringes Market Analysis
East Asian polymer processing capacity is restructuring oral syringe supply chains as regional resin specialization deepens. Terumo Corporation leverages in-house plastic compounding to control material consistency across its disposable syringe lines. Gerresheimer AG sustains glass-barrel dominance in European pharmaceutical packaging through precision molding investments. Becton, Dickinson and Company anchors North American hospital procurement networks with graduated-dose safety syringe portfolios.
An oral syringe is a calibrated, plunger-driven delivery instrument designed for enteral medication administration, typically constructed from medical-grade polypropylene or borosilicate glass with elastomeric seals and printed or molded volumetric graduations in milliliters. Its primary commercial purpose is enabling accurate liquid dosing for pediatric, geriatric, and dysphagic patients who cannot swallow solid dosage forms. Disposable plastic syringes occupy the highest volume tier due to infection control mandates in acute care facilities, while safety-engineered variants with retracting needles or locking caps command premium positioning. Home care channels represent the fastest-growing end-user segment as post-acute discharge protocols expand self-administration.
FDA 21 CFR Part 4 quality system requirements and ISO 7886-1 sterilized syringe standards govern product approval and cross-border commercialization, with EPA resin emissions rules affecting polymer sourcing decisions for U.S.-bound manufacturing. The EU Medical Device Regulation and REACH chemical compliance add layered certification burdens for European market access. Stakeholders must monitor evolving pharmacovigilance reporting obligations tied to dosing errors as a predicate for product liability exposure and design modification cycles.
Market Dynamics
FDA 21 CFR Part 4 quality system mandates are compressing supplier margins while accelerating consolidation among polymer compounders serving medical device OEMs. Home care discharge protocols are simultaneously shifting volume toward retail pharmacy chains and direct-to-patient channels.
Growth Catalysts
- ISO 7886-1 sterilization standards:Harmonized international testing protocols reduce redundant certification costs for cross-border commercialization, accelerating market entry for multi-regional suppliers.
- Pediatric home care:Post-acute discharge expansion creates sustained pull for calibrated dosing instruments in residential settings, particularly for chronic condition management.
- East Asian resin specialization:Regional polymer processing capacity concentration enables captive material supply for integrated manufacturers, compressing lead times and input cost volatility.
Market Restraints
- Medical-grade polypropylene cost structure:Specialized resin grades command premiums over commodity polymers, constraining margin flexibility for price-sensitive contract manufacturers.
- EU REACH chemical compliance:Layered substance authorization requirements extend certification timelines and increase testing expenditure for European market access.
- Glass-barrel substitution ceiling:Borosilicate precision molding retains dominance in high-value pharmaceutical packaging, limiting plastic displacement in premium segments.
Strategic Opportunities
- India CDSCO regulatory alignment:Streamlined medical device registration pathways under revised rules create first-mover positioning for compliant suppliers in an underpenetrated market.
- Telehealth-integrated dispensing:Remote patient monitoring platforms require calibrated home delivery instruments, opening channel partnerships with digital health providers.
- Retracting safety-engineered variants:Needlestick prevention mandates in acute care settings drive premium positioning for locking-cap and retraction mechanisms.
Industry Challenges
- Pharmacovigilance reporting integration:Dosing error tracking systems require real-time data infrastructure that smaller manufacturers lack capital to deploy.
- Elastomeric seal material validation:Extractables and leachables testing for novel polymer formulations extends product development cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Syringes Market |
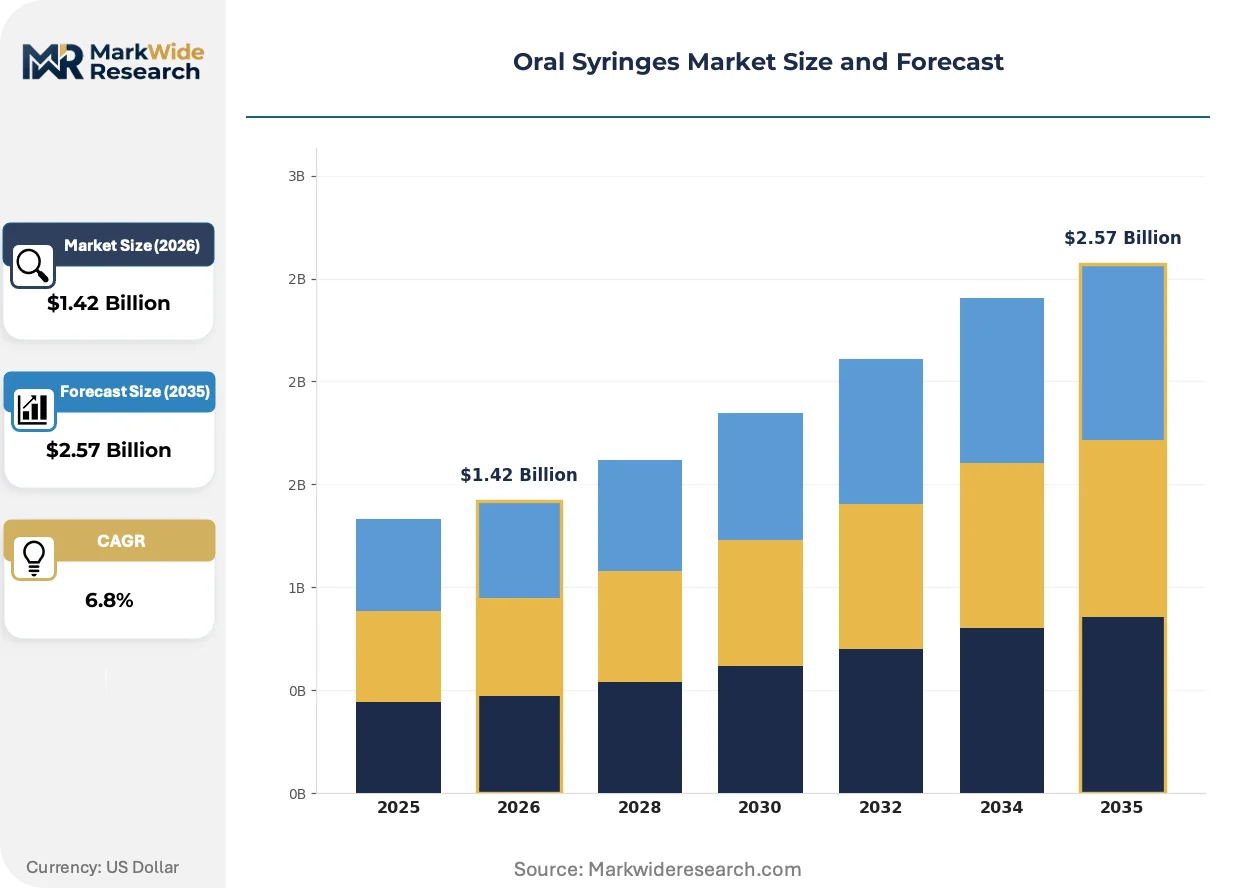
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Safety, Graduated Material: Plastic, Glass, Silicone, Rubber End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Terumo Corporation, Gerresheimer AG, Becton, Dickinson and Company, NIPRO Corporation, Comar, Baxter International Inc., B. Braun Melsungen AG, Schott AG, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Syringes Market Emerging Trajectories
Material science convergence with connected health infrastructure is redefining product specifications across the oral syringe value chain. Regulatory pressure on traceability and patient safety is compressing innovation cycles while elevating technical barriers to entry.
Co-extruded multi-layer polymer barrels are consolidating market share among safety-engineered syringe producers. Hospital procurement networks in North America are adopting these structures to eliminate glass breakage risk in high-throughput settings. The technology is consolidating supplier tiers by requiring in-house compounding capabilities that exclude pure converters.
EPA resin emissions rules are tightening polymer sourcing decisions for U.S.-bound manufacturing. Emissions-intensive production methods face escalating compliance costs, pushing compounders toward low-carbon feedstock certification. Medical-grade polypropylene suppliers with verified supply chain documentation are capturing preferred vendor status in hospital system tenders.
Retail pharmacy chains are consolidating dispensing protocol upgrades under centralized procurement mandates. Independent community pharmacies face exclusion from preferred supplier networks as volume concentrates among national banners. This concentration is most visible in United States markets where CVS Health and Walgreens Boots Alliance dictate graduated-dose safety specifications.
Oral Syringes Market Segmentation
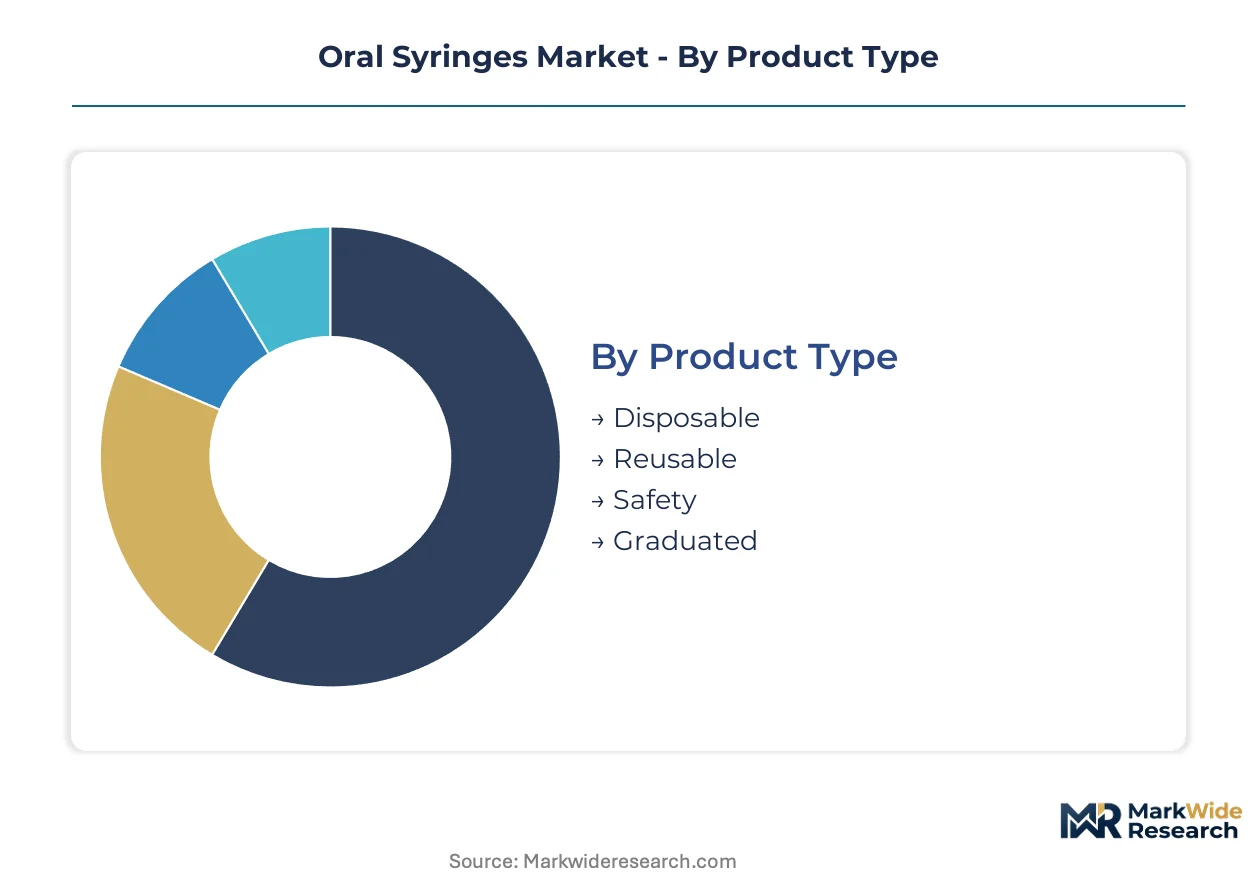
Oral syringe procurement patterns diverge sharply across clinical settings and patient populations, with material specifications and safety engineering driving tiered pricing architectures. Manufacturers must align production capacity to these segment-specific technical requirements to capture volume concentration in acute care while serving dispersed home care channels.
Product Type:
Supply concentration favors integrated manufacturers with in-house molding capabilities that can pivot between standard and safety-engineered configurations.
- Disposable:Single-use polypropylene barrels dominate hospital procurement networks due to infection control mandates. Acute care facilities in the United States absorb the highest volume as Joint Commission standards tighten reuse prohibitions.
- Safety:Retracting needle mechanisms and locking caps command premium positioning in occupational health-conscious institutions. OSHA needlestick prevention enforcement drives replacement cycles in American hospital systems.
- Reusable:Glass-barrel designs with sterilizable components retain niche positioning in cost-constrained veterinary and research applications.
- Graduated:Enhanced volumetric marking precision serves pediatric and geriatric dosing accuracy requirements in pharmacy dispensing.
Disposable configurations absorb the bulk of installed capacity; Safety variants are expanding most quickly.
Material:
Cost tier differentiation separates commodity resin supply from certified medical-grade compounds with full traceability documentation.
- Plastic:Medical-grade polypropylene and co-extruded multi-layer polymers enable high-throughput manufacturing with breakage resistance. Hospital procurement networks favor these structures for drop-risk reduction in busy medication preparation areas.
- Glass:Borosilicate precision molding retains dominance in European pharmaceutical packaging where extractables testing requirements exceed polymer capabilities. Gerresheimer AG sustains leadership through dimensional tolerance investments.
- Silicone:Elastomeric plunger coatings reduce friction in low-dose precision applications.
- Rubber:Traditional stopper materials face displacement by synthetic alternatives in FDA-regulated markets.
Plastic captures the majority of unit volume; Glass maintains margin concentration in premium pharmaceutical segments.
End User:
Application intensity varies by care setting complexity, with documentation requirements and liability exposure shaping product specification tiers.
- Home Care:Post-acute discharge expansion creates sustained demand for intuitive, error-resistant designs. Medicare reimbursement protocols in the United States favor calibrated instruments with clear patient instruction labeling.
- Hospitals:Centralized purchasing departments enforce safety-engineered standards across system-wide formularies. Group purchasing organizations consolidate vendor selection to reduce compliance audit burden.
- Clinics:Outpatient settings balance cost sensitivity with regulatory minimums in immunization and procedural sedation.
- Pharmacies:Retail chains upgrade dispensing protocols with graduated-dose specifications for liquid medication compounding.
Hospitals command the largest absolute volume; Home Care is climbing the fastest as self-administration protocols proliferate.
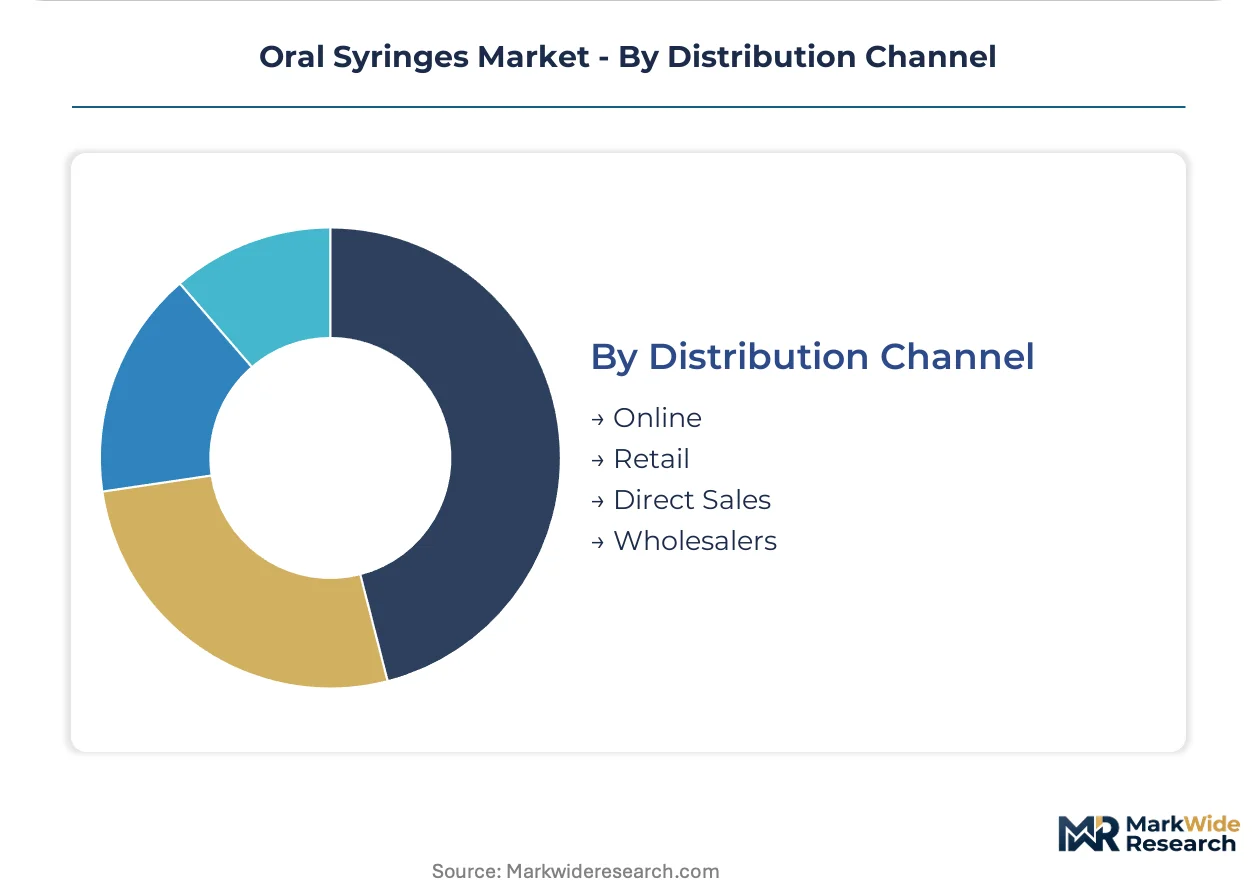
Distribution Channel:
Customer type fragmentation separates institutional procurement from direct-to-patient fulfillment with diverging service requirements.
- Direct Sales:Manufacturer relationships with hospital systems and pharmacy chains enable specification customization and volume pricing. Terumo Corporation leverages direct channels for integrated safety syringe portfolios.
- Wholesalers:McKesson and Cardinal Health consolidate inventory for independent pharmacies and smaller clinics with less specialized requirements.
- Retail:CVS Health and Walgreens Boots Alliance centralized procurement mandates exclude smaller suppliers lacking national distribution infrastructure.
- Online:E-commerce platforms serve direct-to-patient demand for home care accessories with comparison shopping convenience.
Direct Sales channels handle the predominant share of institutional volume; Online distribution is gaining share fastest in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polypropylene resin production clusters in South Korea and Saudi Arabia anchor supply chain decisions for oral syringe manufacturers serving diverse regulatory environments.
United States
Pediatric home care expansion and retail pharmacy chain consolidation drive procurement volume. FDA 21 CFR Part 4 quality system mandates tighten supplier qualification requirements. The Research Triangle Park corridor in North Carolina hosts sterile device manufacturing operations serving hospital group purchasing organizations.
Germany
Precision glass-barrel demand from pharmaceutical packaging specialists sustains premium segment activity. EU Medical Device Regulation and REACH chemical compliance create layered certification requirements. The Upper Franconia region around Münchberg maintains specialized borosilicate molding capabilities for extractables-sensitive applications.
China
Domestic polymer compounding capacity expansion reduces import dependency for disposable syringe production. NMPA medical device registration reforms accelerate local market entry timelines. The Yangtze River Delta cluster around Shanghai integrates resin processing with finished device assembly for regional hospital procurement networks.
India
CDSCO regulatory alignment under revised medical device rules opens streamlined registration pathways for compliant foreign suppliers. Government production-linked incentive schemes encourage domestic manufacturing investment. The Gujarat pharmaceutical manufacturing corridor near Ahmedabad attracts contract molding operations targeting export markets.
Japan
Aging population demographics expand geriatric dosing instrument demand in institutional and home settings. PMDA quality management system requirements maintain elevated technical barriers for market access. The Kansai region around Osaka retains precision plastic processing expertise serving domestic and Southeast Asian hospital networks.
Oral Syringes Market Vendor Landscape
Global majors compete with regional champions across material technology and regulatory certification dimensions. Market structure shows moderate consolidation with tiered positioning between integrated polymer compounders and pure-play device converters. Three archetypes dominate: captive resin producers controlling upstream material consistency, precision glass specialists serving pharmaceutical packaging, and safety-engineered portfolio builders targeting hospital procurement networks. Competitive dynamics center on backward integration into polymer compounding and geographic expansion through regulatory-first market entry strategies.
Among integrated Japanese manufacturers, Terumo Corporation and NIPRO Corporation exemplify the resin-captive archetype with in-house material processing capabilities. German precision glass specialist Gerresheimer AG occupies a position representing pharmaceutical packaging excellence requirements. These three entities anchor the competitive landscape across distinct technical and geographic vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Terumo Corporation |
| Gerresheimer AG |
| Becton, Dickinson and Company |
| NIPRO Corporation |
| Comar |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Schott AG |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
EPA resin emissions certification gates qualified supply for U.S.-bound manufacturers while locking in premium-tier pricing for medical-grade polypropylene suppliers with verified low-carbon documentation. Hospital procurement networks increasingly exclude uncertified compounders from preferred vendor lists, compressing margin flexibility for converters lacking backward integration into compliant resin sourcing.
Pricing Analysis
Service bundling separates safety-engineered syringe portfolios with pharmacovigilance support from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 7886-1 certification grade and extractables testing depth. Cost compression in the standard tier intensifies because retail pharmacy chains centralize procurement under graduated-dose specifications. Independent community pharmacies exhibit highest price sensitivity; integrated hospital systems absorbing safety-engineered variants show least.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Saudi Arabian medical-grade polypropylene resin production clusters anchoring global feedstock access. Finished device assembly draws from Chinese Yangtze River Delta integration, German Upper Franconia glass-barrel specialization, and Japanese Kansai precision molding. Tariff exposure on U.S.-bound shipments from East Asian polymer processing creates margin volatility for non-integrated converters. Distribution runs through McKesson and Cardinal Health wholesaler networks for fragmented clinic and independent pharmacy demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
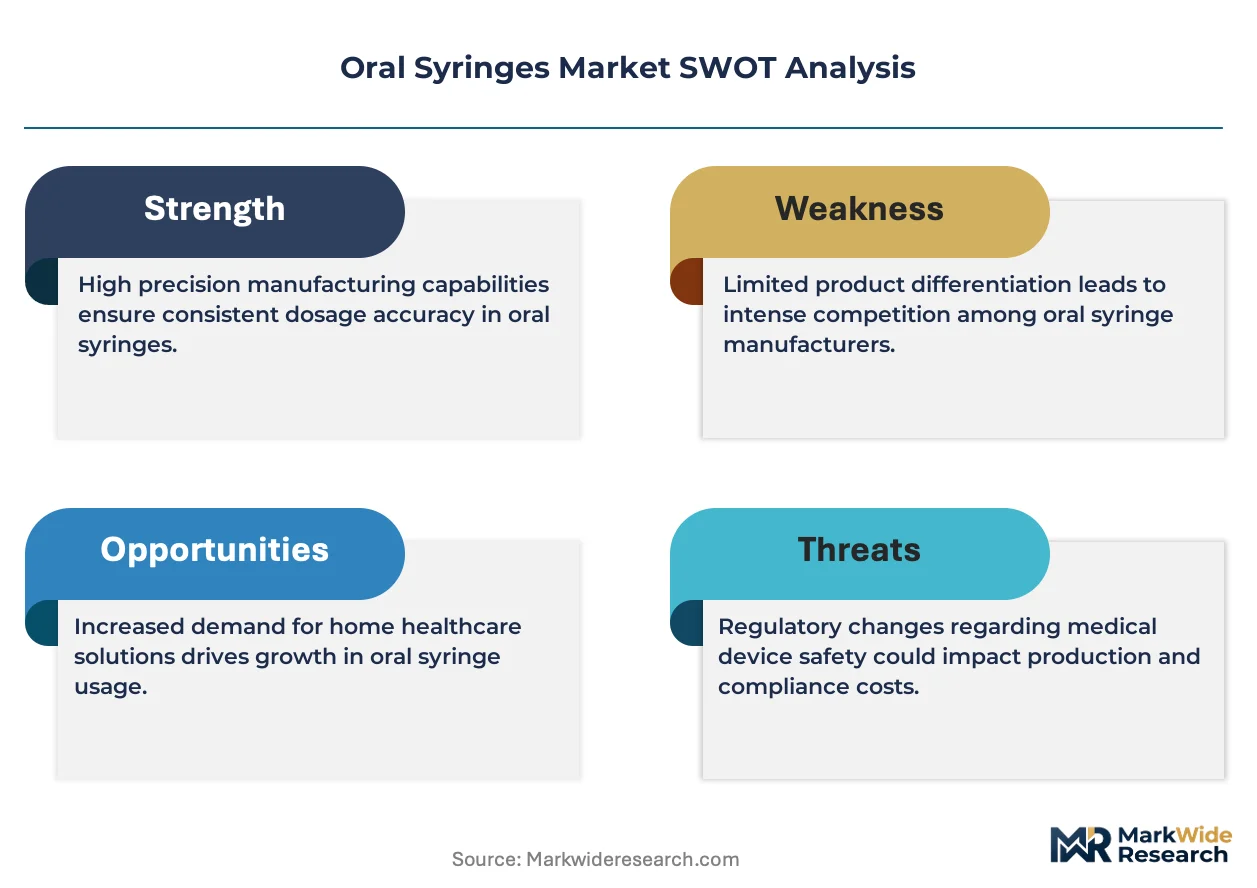
FDA 21 CFR Part 4 quality system mandates erect a cost-of-compliance barrier that entrenches incumbent compounders with capitalized validation infrastructure while screening out undercapitalized entrants.
For Market Incumbents: Anticipate displacement pressure from co-extruded multi-layer polymer technologies by securing captive resin compounding capacity in EPA-certified production corridors. Consolidation among polymer suppliers serving medical device OEMs accelerates as margin compression eliminates pure converters lacking in-house material processing. For New Entrants and Emerging Players: Telehealth-integrated dispensing platforms offer white-space positioning for calibrated home delivery instruments with patient instruction optimization. India's CDSCO streamlined registration pathway presents the most penetrable regulatory entry point for compliant foreign suppliers targeting government production-linked incentive zones. For Investors and Strategic Acquirers: Hospital group purchasing organization tender consolidation is the leading indicator that scale advantages are concentrating among integrated manufacturers with safety-engineered portfolios. Acquisition targets should screen for in-house polymer compounding capabilities and FDA establishment registration history. Watch for EPA enforcement actions against emissions-intensive resin production as inflection signals for preferred vendor status reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply secures EPA certification continuity and compresses input cost volatility for U.S. hospital contracts. |
| CDSCO Regulatory-First Market Entry | Streamlined device registration under India's revised medical device rules opens first-mover positioning in pharmaceutical manufacturing corridors. |
| Safety-Engineered Portfolio Expansion | Retracting needle mechanisms capture OSHA needlestick prevention mandate premiums in American acute care procurement networks. |
| Telehealth Platform Partnership | Remote patient monitoring integration creates channel access for calibrated home care instruments with digital health providers. |
| Glass-to-Polymer Substitution Investment | Co-extruded multi-layer barrels eliminate breakage risk for hospital systems consolidating safety specifications under Joint Commission standards. |
Methodological Framework
Document review covered FDA 510(k) filings, ISO 7886-1 sterilization standard documentation, and EPA resin emissions compliance records, complemented by interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and polymer compounding technical directors. Secondary validation drew from customs trade data, SEC 10-K medical device segment disclosures, and hospital system tender databases. Bottom-up demand modeling across end-user segments triangulated against top-down polymer resin consumption estimates.
Unit volume and value projections across the analysis window applied segment-specific adoption curves calibrated to Joint Commission standard enforcement timelines and Medicare reimbursement protocol revisions. Segmentation dimensions modeled include product type tier, material certification grade, end-user care setting, and distribution channel concentration. CAGRs derived from polynomial trend fitting to historical procurement volume series, with elasticity adjustments for regulatory mandate implementation schedules and retail pharmacy chain consolidation events.
Caveats apply where FDA quality system interpretation shifts, EPA emissions rule stringency changes, or polymer feedstock cost volatility could materially shift the outlook for converter margin structures and hospital system vendor selection. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
Global Sharps Containers Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Luer Plug Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Global Medical Supplies Market