
 Pharmacy Bags Market | 2026-2036
Pharmacy Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacy Bags Market Analytics
The EU Green Deal is decoupling pharmacy bag procurement from conventional plastic specifications across European retail pharmacy chains. Novolex leverages its North American manufacturing scale to supply compliant paper-based alternatives for institutional buyers. Mondi Group anchors European demand through integrated kraft paper operations and pharmaceutical-grade certification. Smurfit Kappa competes on recycled fiber formulations that meet emerging sustainability mandates from major pharmacy retailers.
Pharmacy bags are specialized containment vessels manufactured from plastic films, kraft paper, or biodegradable substrates, typically featuring tamper-evident closures and child-resistant mechanisms to ensure medication security during dispensing and transport. Production involves extrusion coating, flexographic printing, and adhesive lamination to achieve barrier properties against moisture and light degradation. Plastic remains the dominant material type due to cost efficiency and moisture barrier performance, though biodegradable alternatives are gaining fastest traction as regulatory pressure intensifies. Zipper and adhesive closure types occupy the highest volume share in institutional settings where resealability and dispensing efficiency matter most.
EMA guidelines on pharmaceutical packaging integrity, REACH restrictions on phthalate-containing plastics, and EU F-Gas Regulation indirect effects on polymer supply chains collectively reshape product specifications and supplier qualification requirements across the continent. Compliance with MDR traceability standards now extends to secondary packaging components including pharmacy bags in several member states. Stakeholders must monitor evolving ECHA substance restrictions and pharmacy chain sustainability scorecards to anticipate specification changes before they become procurement gatekeepers.
Market Dynamics
REACH restrictions on phthalate-containing plastics and EMA packaging integrity guidelines are forcing material transitions across European pharmacy supply chains, compressing incumbent polymer specifications while accelerating paper and biodegradable substrate qualification programs.
Growth Catalysts
- Hospital pharmacy expansion:Long-term care facilities and acute care institutions are scaling compliant dispensing packaging procurement to meet medication safety protocols and traceability requirements.
- EU Green Deal material mandates:The European Commission's single-use plastic reduction targets are redirecting retail pharmacy chain specifications toward kraft paper and certified biodegradable alternatives.
- Child-resistant mechanism innovation:Advancements in tamper-evident zipper and adhesive closure systems are expanding institutional adoption where resealability drives operational efficiency.
Market Restraints
- Polymer feedstock volatility:Fluctuating ethylene and propylene prices from naphtha cracking operations are compressing margin structures for conventional plastic film converters.
- Barrier performance gap:Paper-based alternatives face technical limitations in moisture and light protection compared to multi-layer plastic laminates, restricting substitution in sensitive medication categories.
- REACH compliance friction:ECHA substance restriction updates require continuous reformulation of adhesives and coatings, extending supplier requalification timelines.
Strategic Opportunities
- German retail pharmacy consolidation:The country's cooperative pharmacy networks present concentrated procurement channels for certified sustainable packaging suppliers.
- Biodegradable substrate convergence:PLA and PHA film technologies combined with water-based barrier coatings are opening premium positioning in urban pharmacy chains.
- CSRD reporting tailwinds:The EU Corporate Sustainability Reporting Directive is elevating secondary packaging sustainability scorecards to procurement gatekeeper status.
Industry Challenges
- Pharmaceutical-grade certification bottlenecks:ISO 15378 and EU GMP Annex 1 compliance for paper-based materials requires 18-24 month validation cycles, delaying commercialization.
- Flexographic printing skill scarcity:Qualified technicians for pharmaceutical-grade ink formulation and registration control are concentrated among legacy packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacy Bags Market |
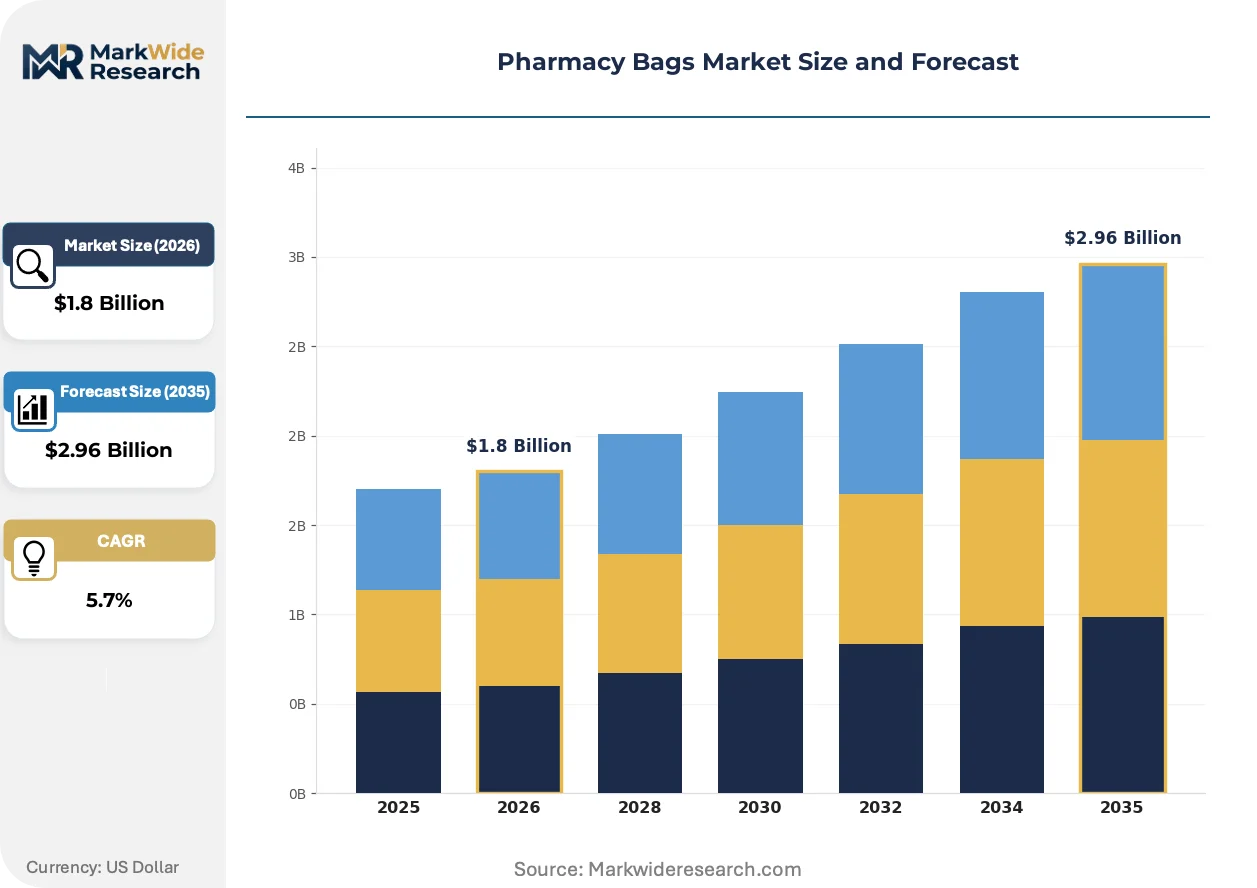
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Biodegradable, Reusable Closure Type: Zipper, Adhesive, Tuck Top, Drawstring Size: Small, Medium, Large, Extra Large Distribution Channel: Retail, Online, Wholesale, Direct Supply |
| Companies Covered | Novolex, Mondi Group, International Paper, Smurfit Kappa, Bag Makers, Inc., WestRock, ProAmpac, El Dorado Packaging, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacy Bags Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine pharmacy bag performance specifications, with sustainability credentials now inseparable from barrier functionality in buyer evaluation frameworks.
Water-based barrier coatings applied to kraft paper substrates are absorbing the technical requirements previously met by polyethylene laminates. Hospital pharmacy buyers in France and the United Kingdom are piloting these materials at scale for oral solid dose dispensing. The technology is absorbing moisture protection standards while eliminating fossil-derived content from secondary packaging layers.
EMA guidelines on pharmaceutical packaging integrity are extending traceability requirements to secondary components in several member states. Manufacturers must now document batch-level provenance for pharmacy bags used in investigational medicinal product distribution. Hospital pharmacies in Germany are responding by mandating supplier certification to MDR Article 10 quality management standards.
Retail pharmacy chains are consolidating supplier relationships around sustainability-verified packaging portfolios. Independent pharmacies in the United Kingdom are joining buying groups to access paper-based alternatives at competitive unit economics. This concentration is most visible in England's National Pharmacy Association procurement frameworks, where environmental criteria now weight 15-20% in tender evaluations.
Pharmacy Bags Market Segmentation
Pharmacy bag procurement decisions hinge on material compliance costs, closure mechanism reliability, and dispensing workflow integration. Segmentation reveals where capital deployment concentrates and which specifications command premium positioning across institutional and retail channels.
Material Type:
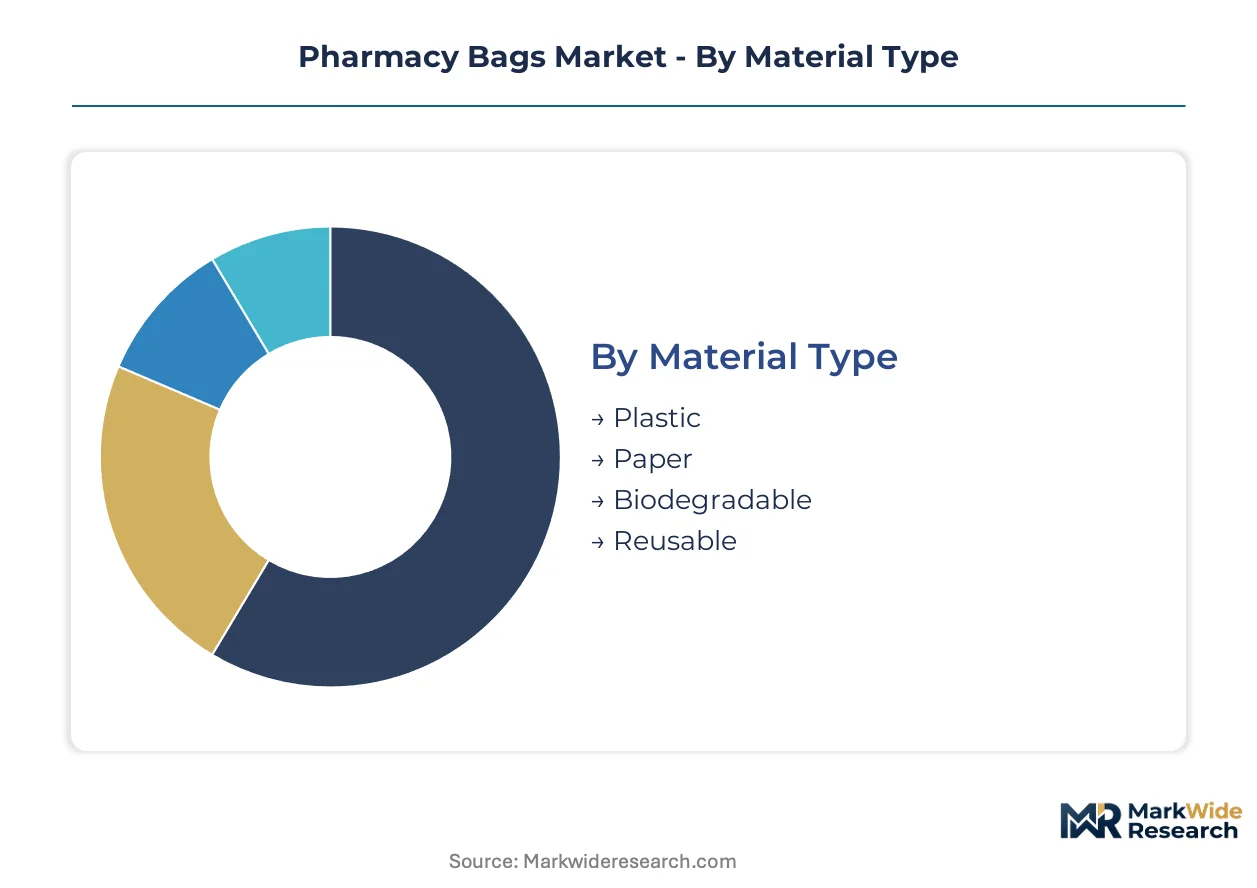
Capital intensity peaks with biodegradable substrate manufacturing, where fermentation infrastructure and compounding equipment demand the heaviest upfront outlays. Paper conversion requires integrated pulp-to-film operations for pharmaceutical-grade certification. Plastic extrusion remains the lowest barrier to entry despite rising regulatory compliance costs.
- Plastic:Multi-layer polyethylene and polypropylene laminates dominate current volume through cost-efficient moisture barrier performance. Hospital pharmacies in Germany specify these materials for light-sensitive medications where technical specifications remain stringent.
- Paper:Kraft paper substrates with water-based barrier coatings are absorbing specifications previously held by plastic films. Retail pharmacy chains in the United Kingdom are piloting these alternatives at scale under EU Green Deal procurement mandates.
- Biodegradable:PLA and PHA films require dedicated fermentation and polymerization assets.
- Reusable:Silicone-lined fabric containers serve closed-loop institutional dispensing systems with sterilization infrastructure.
Most installed capacity flows through Plastic. Expansion is steepest in Paper.
Closure Type:
Application context determines closure selection, with institutional dispensing prioritizing resealability and retail emphasizing tamper evidence. Zipper mechanisms command tooling investments for precision molding, while adhesive systems leverage coating technology transferable from label manufacturing.
- Zipper:Child-resistant zipper systems integrate dual-action release mechanisms meeting ISO 8317 standards. Long-term care facilities in France specify these for multi-dose dispensing protocols where patient safety audits are frequent.
- Adhesive:Permanent and resealable adhesive strips balance security with dispensing efficiency. Hospital pharmacies favor these for high-volume oral solid dose distribution where speed outweighs reclosure needs.
- Tuck Top:Fold-and-tuck designs suit low-cost retail dispensing without moisture protection requirements.
- Drawstring:Fabric and paper cord closures serve bulk compounding and veterinary pharmacy applications.
Zipper mechanisms anchor premium positioning. Adhesive closures are gaining share fastest in high-volume institutional procurement.
Size:
Dispensing volume and medication format dictate dimensional requirements, with acute care institutions driving large-format demand for IV admixture kits. Small formats concentrate in retail where unit-of-use dispensing dominates.
- Small:Dimensions under 150mm square accommodate single-unit oral solid doses. Community pharmacies in England specify these for prescription vial containment within automated dispensing systems.
- Medium:Standard 200-300mm formats handle multi-item prescriptions and inhaler packaging. This segment absorbs the broadest cross-section of retail and institutional demand.
- Large:Expanded formats serve hospital pharmacy bulk compounding and discharge medication bundles.
- Extra Large:Specialized dimensions accommodate medical device co-packaging and home infusion kits.
Medium sizes command the highest absolute volume. Large formats are expanding most quickly alongside hospital pharmacy centralization.
Distribution Channel:
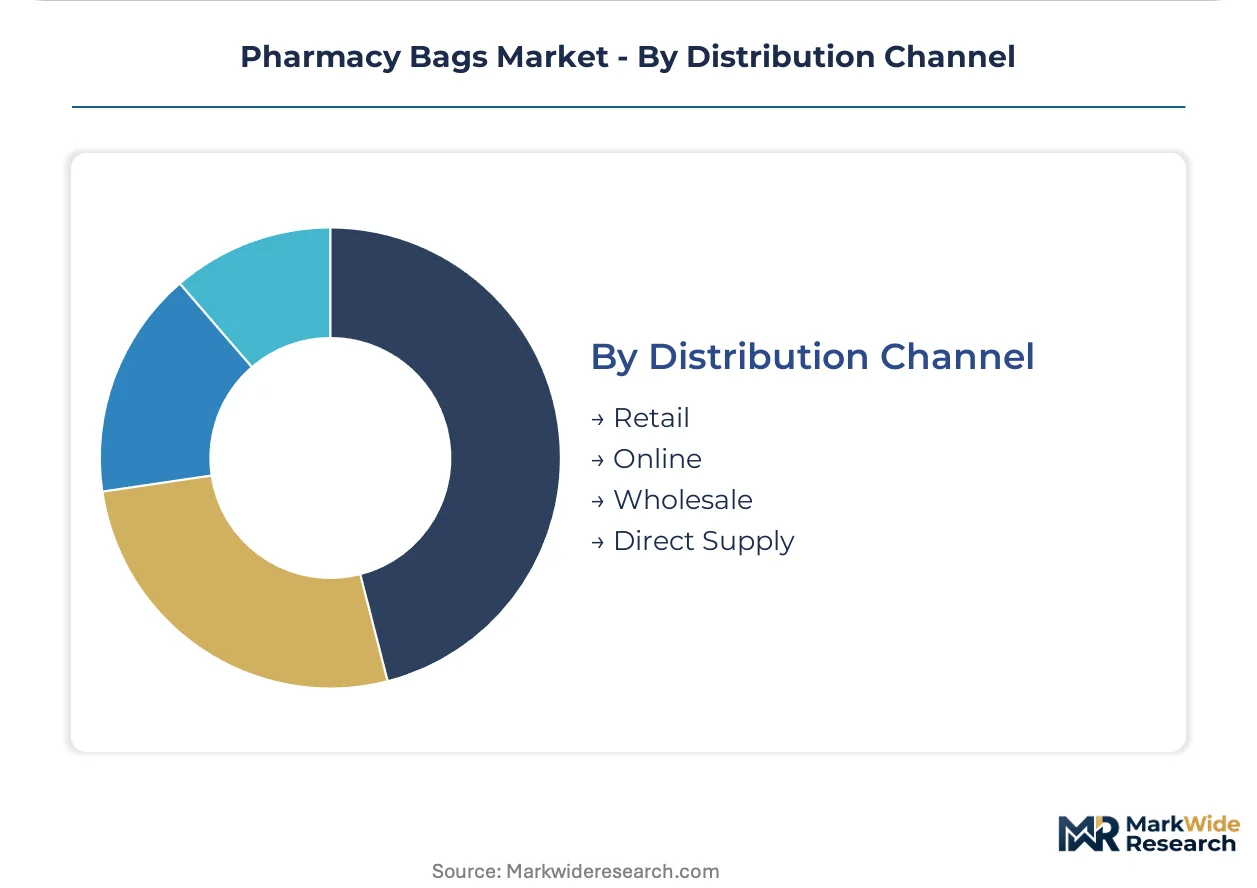
Customer type and order scale shape channel economics, with direct supply relationships capturing the largest institutional accounts. Online channels are restructuring procurement for independent pharmacy networks.
- Retail:Pharmacy chain buying groups aggregate demand for standardized specifications. Germany's cooperative pharmacy networks concentrate procurement through this channel with sustainability criteria weighted heavily.
- Online:Digital procurement platforms are penetrating independent pharmacy segments previously served by field sales. United Kingdom buying groups leverage these channels to access paper-based alternatives at competitive unit economics.
- Wholesale:Medical-surgical distributors bundle pharmacy bags with broader consumable portfolios.
- Direct Supply:Manufacturer-direct relationships serve health system integrated delivery networks with custom specifications.
Retail channels absorb the highest transaction volume. Online procurement is climbing the fastest as independent pharmacies consolidate purchasing through digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pharmacy bags industry traces its commercial origins to post-war pharmaceutical distribution networks in Germany, where tamper-evident packaging standards first codified the specifications now governing European procurement. Hospital pharmacy centralization across Western Europe subsequently scaled demand for compliant dispensing vessels, establishing material and certification protocols that persist in contemporary supply chains.
Germany
Cooperative pharmacy networks in North Rhine-Westphalia and Bavaria concentrate procurement for paper-based alternatives under EU Green Deal mandates. EMA packaging integrity guidelines require batch-level traceability documentation for secondary packaging used in investigational medicinal product distribution. Berlin-Brandenburg hosts validation laboratories where ISO 15378 certification cycles for kraft paper substrates compress toward 18-month timelines.
France
Hospital pharmacies in Île-de-France pilot water-based barrier coatings for oral solid dose dispensing at scale. ANSM enforcement of pharmaceutical-grade packaging standards extends to pharmacy bags in clinical trial supply chains. Lyon-based converters supply child-resistant zipper mechanisms to long-term care facilities where patient safety audits drive specification rigor.
United Kingdom
England's National Pharmacy Association procurement frameworks weight environmental criteria at 15-20% in tender evaluations for retail pharmacy chains. MHRA alignment with MDR traceability standards applies to secondary packaging components in several NHS trusts. Manchester buying groups aggregate independent pharmacy demand for certified sustainable alternatives through digital procurement platforms.
United States
Hospital integrated delivery networks in Texas and California scale compliant dispensing packaging procurement to meet medication safety protocols. FDA guidance on pharmaceutical packaging integrity influences specification development for institutional buyers. Chicago-area converters supply multi-layer polyethylene laminates where moisture barrier performance remains non-negotiable for light-sensitive medications.
India
CDSCO pharmaceutical packaging regulations are accelerating qualification programs for domestic kraft paper converters serving export markets. Maharashtra's pharmaceutical manufacturing clusters generate demand for tamper-evident dispensing vessels meeting EU import specifications. Ahmedabad-based suppliers validate biodegradable substrate formulations for European pharmacy chain sustainability scorecards.
Pharmacy Bags Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and material sophistication, with pharmaceutical-grade validation cycles creating defensive moats around incumbent supply relationships. The vendor base stratifies between integrated pulp-to-film operators, specialized plastic film converters, and emerging biodegradable substrate developers. Three archetypes dominate: multinational packaging conglomerates with pharmaceutical certification infrastructure, regional paper converters leveraging sustainability mandates, and specialty film manufacturers defending polymer specifications in moisture-critical applications. Capacity expansion and strategic partnerships represent the dominant competitive vectors as buyers consolidate supplier relationships around verified sustainability portfolios.
Among North American packaging conglomerates, Novolex leverages manufacturing scale to supply compliant paper-based alternatives for institutional buyers. Mondi Group anchors European demand through integrated kraft paper operations. Smurfit Kappa competes on recycled fiber formulations that meet emerging sustainability mandates from major pharmacy retailers. These three occupy positions across the premium-to-standard tier spectrum, with each representing distinct strategic postures on material transition timing and certification depth.
| Leading Market Players |
|---|
| Novolex |
| Mondi Group |
| International Paper |
| Smurfit Kappa |
| Bag Makers, Inc. |
| WestRock |
| ProAmpac |
| El Dorado Packaging |
| DS Smith |
| Others |
Value Network & Pricing Analysis
Backward integration into kraft pulp operations anchors both supply security and pricing power for European pharmacy bag converters facing EU Green Deal procurement mandates. Mondi Group's captive fiber supply and Smurfit Kappa's recycled fiber networks demonstrate how upstream control insulates margin structures from polymer feedstock volatility while commanding premium positioning in sustainability-weighted tenders.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade certified, standard commercial, and economy uncoated levels dominates procurement frameworks. Price differentiation hinges on ISO 15378 certification status and water-based barrier coating performance tier. Cost compression in economy plastic laminates is intensifying because naphtha-derived resin volatility compresses converter margins. Retail pharmacy chains in Germany exhibit highest price sensitivity, while hospital integrated delivery networks in France prioritize certification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German cooperative pharmacy networks and NHS trusts in England mandate multi-supplier qualification for critical dispensing packaging. Manufacturing concentrates in Germany, Sweden, and Poland for paper-based substrates, while plastic film extrusion centers on Belgium and the Netherlands. Raw material dependencies include northern European softwood pulp, bio-based PLA feedstocks, and water-based acrylic barrier coatings. Single-source vulnerability persists in pharmaceutical-grade ink formulation. Distribution runs through medical-surgical wholesalers bundling pharmacy bags with broader consumable portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between REACH-compliant European specifications and emerging Asian export capacity creates margin expansion opportunities for converters with dual-qualification capabilities. Cost differentials in fermentation-based PLA production between Thailand and European facilities exceed regulatory compliance investment thresholds.
For Market Incumbents: Anchor market position through ISO 15378 certification depth and backward integration into pharmaceutical-grade pulp supply. Invest in water-based barrier coating R&D to defend against biodegradable substrate substitution. Acquire distressed paper converters in Poland to secure low-cost capacity serving German retail pharmacy networks. For New Entrants and Emerging Players: Digital procurement platforms serving United Kingdom independent pharmacy buying groups offer lowest barrier to initial revenue. Target England's National Pharmacy Association procurement frameworks where sustainability criteria weighting creates specification entry points. Partner with Manchester-based buying groups to bypass legacy field sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap European paper converters with pharmaceutical-grade validation infrastructure because CSRD reporting mandates are elevating secondary packaging sustainability scorecards to procurement gatekeeper status. Acquisition focus: kraft paper specialists with 18-24 month ISO 15378 certification timelines already initiated. Watch ECHA substance restriction updates as inflection indicators for adhesive reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Pharmaceutical-grade validation compresses supplier qualification timelines for hospital pharmacy procurement. |
| Water-Based Barrier Coating Scale-Up | Kraft paper substrates absorb moisture protection standards previously met by polyethylene laminates. |
| Biodegradable Substrate Partnership | PLA and PHA film technologies open premium positioning in urban pharmacy chain sustainability scorecards. |
| Digital Procurement Platform Integration | United Kingdom buying groups aggregate independent pharmacy demand through online channels. |
| Backward Integration into Pulp Supply | Captive fiber operations insulate margin structures from recycled pulp price volatility. |
Research Methodology
Multiple input streams — regulatory filing analysis, supply chain participant interviews, and procurement database reconciliation — were combined to construct market estimates. Primary discussions included pharmaceutical packaging procurement managers at German hospital networks, regulatory affairs leads at kraft paper converters, and sustainability officers at United Kingdom retail pharmacy chains. Secondary validation drew from ECHA substance restriction updates, EU Green Deal implementation documents, and hospital procurement framework tenders. Bottom-up capacity assessments and top-down demand modeling were cross-referenced for triangulation.
Data-stream reconciliation across material type, closure mechanism, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro pharmaceutical dispensing volume trends. Forecast inputs included EU single-use plastic reduction target compliance timelines and EMA packaging integrity guideline adoption curves across member states.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA adhesive restriction scope and bio-based polymer cost parity achievement. Deviation in REACH phthalate ban enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
External Nasal Dilator and Nasal Strip Market
Medical Supplies
Americas Safety Lancet Market
Medical Supplies
Asia-Pacific Medical Clothing Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Microcarrier Market
Medical Supplies
Blood Collection Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Surgical Sealant and Adhesive Market