
 Sterile IV Containers Market | 2026-2036
Sterile IV Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile IV Containers Market Analytics
Hospital group purchasing organization procurement is tilting toward consolidated vendor contracts with integrated infusion system suppliers. Baxter International leverages its end-to-end parenteral nutrition platform to anchor long-term agreements with integrated delivery networks. B. Braun Melsungen AG sustains manufacturing scale across European and Asian plants, competing on volume commitments to national health systems. Fresenius Kabi AG specializes in oncology and critical care container formats, differentiating through therapy-specific packaging configurations.
Sterile IV containers are sealed, pyrogen-free vessels engineered to store and administer intravenous solutions without microbial contamination, typically constructed from multi-layer polymer films or borosilicate glass with specified breakthrough resistance and compatibility with common infusion sets. Flexible bags fabricated from polypropylene or polyvinyl chloride dominate acute care settings where collapsible designs eliminate air embolism risk and reduce storage volume, while glass bottles retain share in light-sensitive and high-pH drug applications where inert contact surfaces prove essential. Rigid containers occupy a narrowing niche in ambulatory surgical centers prioritizing crush resistance, and home care channels are expanding fastest as subcutaneous infusion therapies shift outside institutional walls.
FDA enforces container closure integrity standards under 21 CFR 211, while the EU MDR mandates biocompatibility documentation and post-market surveillance for Class IIa sterile devices, collectively elevating barrier testing costs and consolidation pressure on smaller converters. ISO 15747 sets global baseline requirements for plastic containers used in parenteral preparations, shaping supplier qualification protocols across export markets. Stakeholders must monitor evolving USP <1207> package integrity test method revisions and assess whether in-house blow-fill-seal capacity or outsourced sterile conversion delivers superior compliance economics.
Market Dynamics
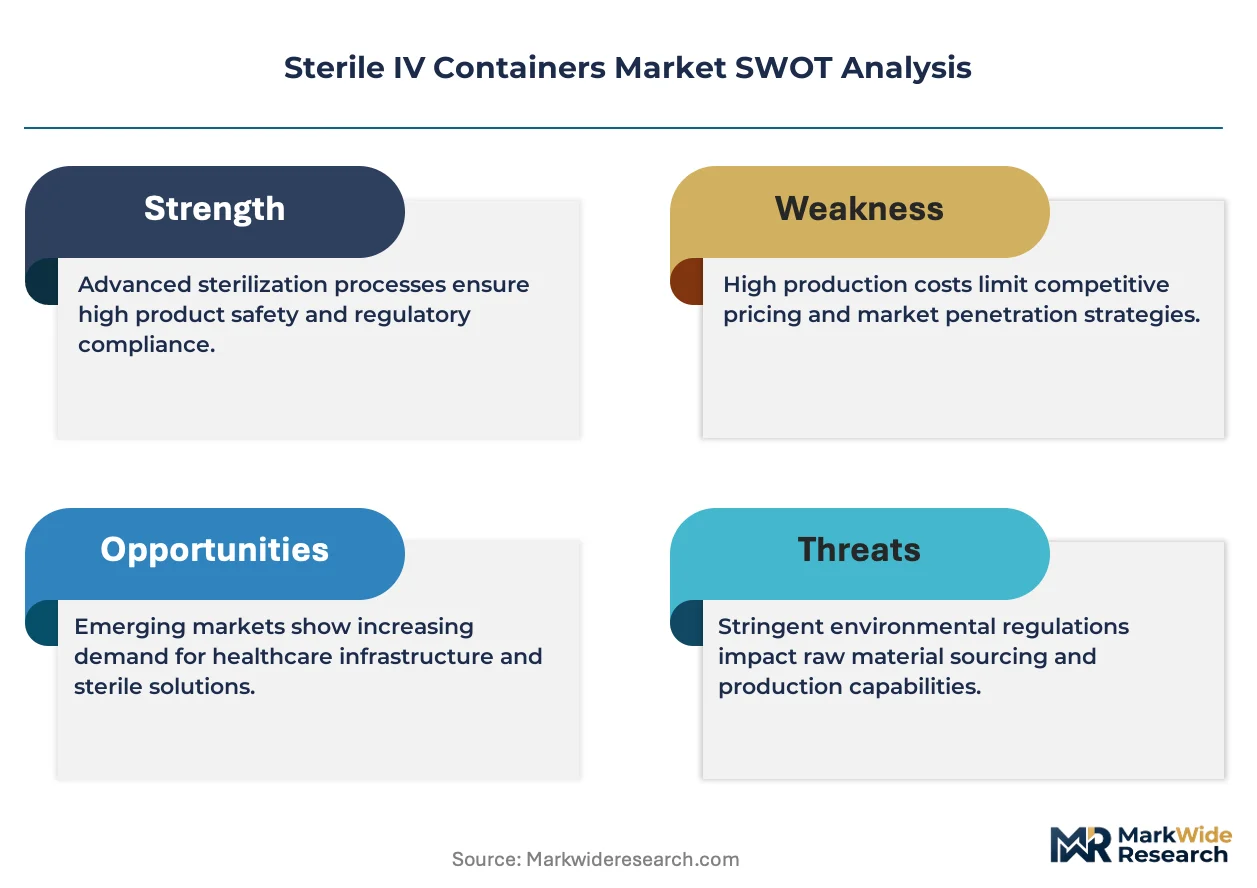
Hospital group purchasing organizations are consolidating vendor rosters around integrated infusion platform suppliers, compressing procurement cycles and elevating qualification barriers for standalone container manufacturers.
Growth Catalysts
- EU MDR compliance mandates:Biocompatibility documentation requirements for Class IIa sterile devices are accelerating manufacturer consolidation and favoring converters with in-house testing laboratories.
- Home infusion therapy expansion:Subcutaneous drug administration outside institutional walls is pulling demand toward portable, collapsible bag formats with extended shelf stability.
- Polypropylene film advances:Multi-layer coextrusion technologies are enabling thinner-walled containers with equivalent barrier performance, reducing resin consumption per unit.
Market Restraints
- Medical-grade polymer supply concentration:Production of compliant polypropylene and PVC compounds clusters among a limited set of petrochemical converters, exposing converters to feedstock allocation disruptions.
- Glass-to-plastic substitution limits:High-pH and light-sensitive oncology formulations remain tethered to borosilicate bottles due to extractables concerns, constraining flexible bag penetration in high-value therapeutic categories.
- FDA 21 CFR 211 validation costs:Container closure integrity testing protocols require specialized equipment and personnel, elevating fixed costs for entrants without established quality systems.
Strategic Opportunities
- Japan's aging infusion infrastructure:Hospital replacement cycles for rigid bottle systems present conversion opportunities for collapsible bag suppliers with METI-certified manufacturing.
- Oncology-specific packaging configurations:Therapy-optimized container geometries for cytotoxic drugs offer differentiation paths beyond commodity volume supply.
- Closed-system transfer device integration:Convergence of sterile containers with needle-free administration interfaces is creating premium positioning for engineered combination products.
Industry Challenges
- Blow-fill-seal technician scarcity:Qualified operators for aseptic forming and filling lines command wage premiums, constraining capacity expansion timelines.
- Legacy ERP integration:Track-and-trace serialization requirements under DSCSA and EU FMD are forcing container converters to reconfigure warehouse management systems.
- USP 1207 method validation:Transition from probabilistic to deterministic leak detection is extending qualification timelines for new container designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile IV Containers Market |
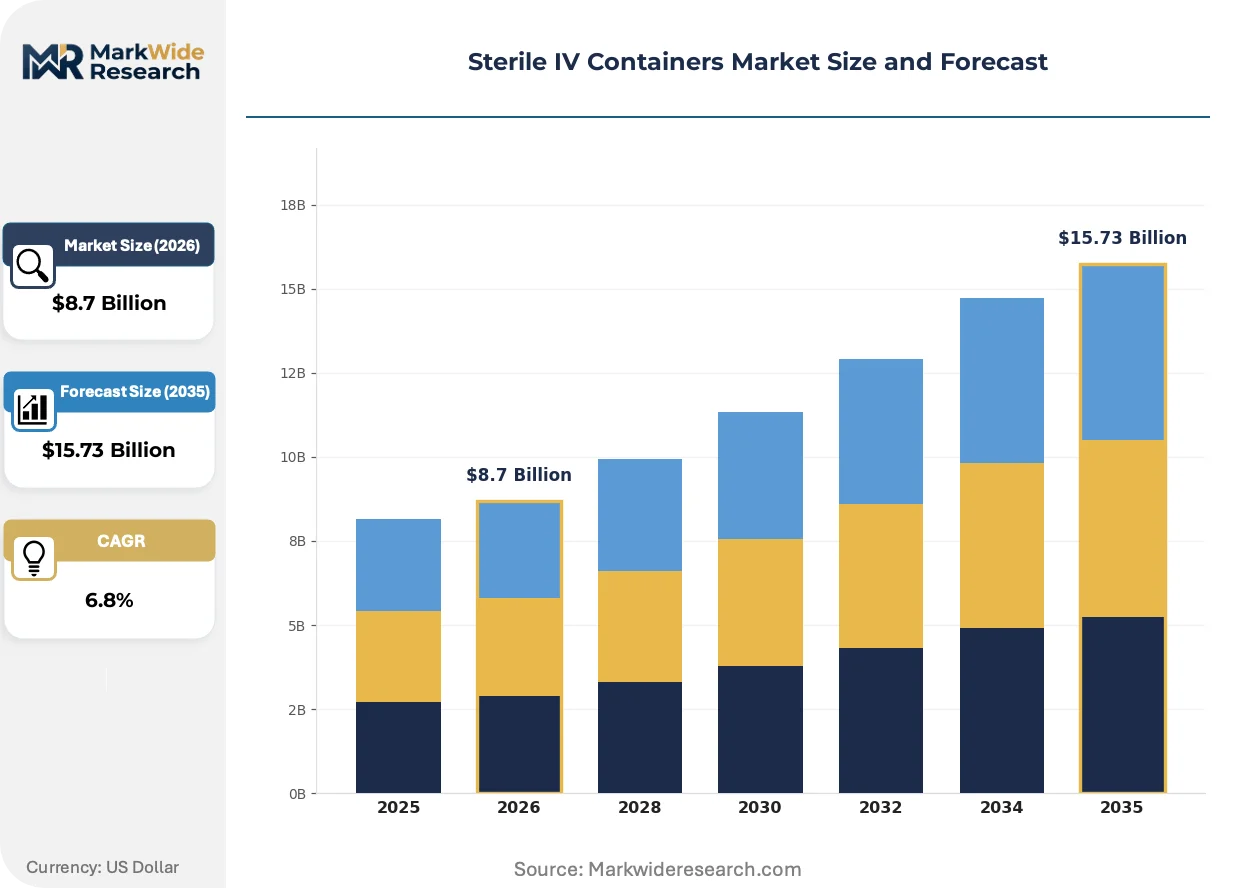
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Glass Bottles, Rigid Containers, Ampoules Material: Polypropylene, Polyvinyl Chloride, Glass, Others End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retail |
| Companies Covered | Terumo Corporation, Nipro Corporation, Baxter International Inc., Medline Industries, BD, B. Braun Melsungen AG, ICU Medical, Inc., Vioser SA, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile IV Containers Market Evolving Landscape
Digital integration of manufacturing execution systems with sterile packaging lines is compressing batch release timelines and enabling real-time quality monitoring across distributed production networks.
RFID-enabled inventory tracking is digitizing hospital supply chain visibility from manufacturer through patient administration. Integrated delivery networks in the United States are piloting smart cabinet replenishment tied to container-level serialization. This connectivity is digitizing demand signals and reducing safety stock requirements at individual facilities.
EU MDR post-market surveillance obligations are extending biocompatibility study requirements to legacy container designs previously grandfathered under prior directives. Manufacturers must now generate clinical evidence or equivalent documentation for existing product lines. German and French notified bodies are enforcing these timelines most aggressively, compressing portfolio rationalization decisions.
Consolidated vendor contracting is displacing spot purchasing for standalone container procurement. Hospital systems in the United States are bundling sterile supply agreements with infusion pump and administration set contracts, compressing the addressable market for unaffiliated converters. This concentration is most visible among the ten largest integrated delivery networks, which now control a disproportionate share of acute care volume.
Sterile IV Containers Market Segmentation
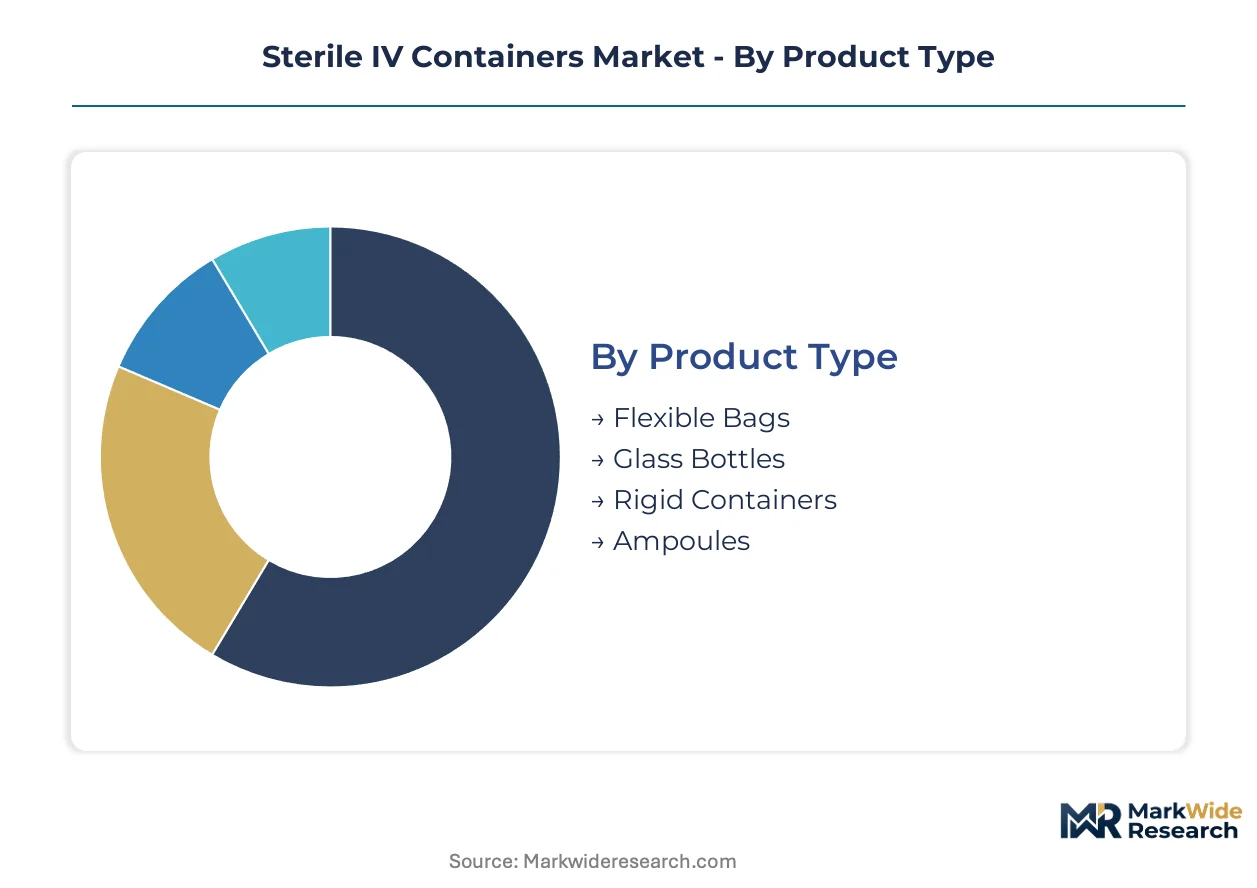
Sterile IV container procurement varies sharply by clinical setting, therapy type, and supply chain configuration. Understanding these segment boundaries clarifies where manufacturers must anchor volume commitments versus where specialized formats command premium positioning.
Product Type:
Use-case spectrum spans acute care volume efficiency through specialized drug stability requirements.
- Flexible Bags:Multi-layer polymer films—typically polypropylene or ethylene vinyl acetate coextrusions—enable collapsible designs that eliminate air embolism risk during gravity or pump-driven infusion. Hospital systems in the United States and Germany concentrate procurement here, driven by centralized purchasing contracts that favor integrated infusion platform suppliers with blow-fill-seal capacity.
- Glass Bottles:Borosilicate construction provides inert contact surfaces essential for light-sensitive oncology formulations and high-pH parenteral nutrition solutions. Demand clusters in Japanese university hospitals and European compounding pharmacies where extractables testing under EU MDR biocompatibility mandates constrains plastic alternatives.
- Rigid Containers:Blow-molded polyethylene or polycarbonate vessels prioritize crush resistance for ambulatory surgical centers and emergency medical services transport.
- Ampoules:Single-dose glass or polymer units serve vaccine reconstitution and diagnostic contrast media applications requiring precise unit-of-use packaging.
Established volume favors flexible bags; emerging adoption favors glass bottles in high-value therapeutic categories.
Material:
Cost tier stratification separates commodity resin supply from specialized barrier formulations.
- Polypropylene:Medical-grade homopolymer and random copolymer grades dominate flexible bag production, with multi-layer coextrusion technologies enabling thinner walls without compromising oxygen or moisture barrier performance. German and Japanese converters anchor supply through integrated resin-to-film operations.
- Polyvinyl Chloride:Plasticized PVC retains share in blood component storage and certain electrolyte solutions where proven compatibility with existing administration sets reduces clinical retraining burden. REACH and EU MDR scrutiny of phthalate plasticizers is accelerating migration toward non-DEHP alternatives.
- Glass:Type I borosilicate meets USP <660> and EP 3.2.1 requirements for hydrolytic resistance, anchoring share in biologic and cytotoxic drug packaging.
- Others:Cyclic olefin polymers and multilayer ethylene vinyl alcohol structures serve niche applications demanding ultra-low permeation or visible clarity for particulate inspection.
Polypropylene captures the steepest expansion trajectory as converters invest in coextrusion capacity; glass maintains defensive positioning in regulatory-sensitive therapeutic segments.
End User:
Customer type determines packaging format complexity and regulatory documentation depth.
- Hospitals:Integrated delivery networks drive consolidated contracting for standard infusion volumes, with GPO procurement tilting toward vendors offering pump-set-container bundles.
- Clinics:Outpatient infusion centers prioritize space-efficient storage and rapid inventory turnover, favoring pre-filled syringes and small-volume bags over traditional bottle formats.
- Home Care:Subcutaneous immunoglobulin and parenteral nutrition therapies are pulling demand toward ambulatory pumps with collapsible reservoirs, requiring extended shelf stability and patient-friendly handling instructions.
- Pharmacies:Compounding operations—both 503B outsourcing facilities and hospital-based cleanrooms—source containers with validated closure integrity for beyond-use dating extensions.
Hospital procurement anchors current revenue concentration; home care channels are climbing the fastest as infusion therapy decentralization accelerates.
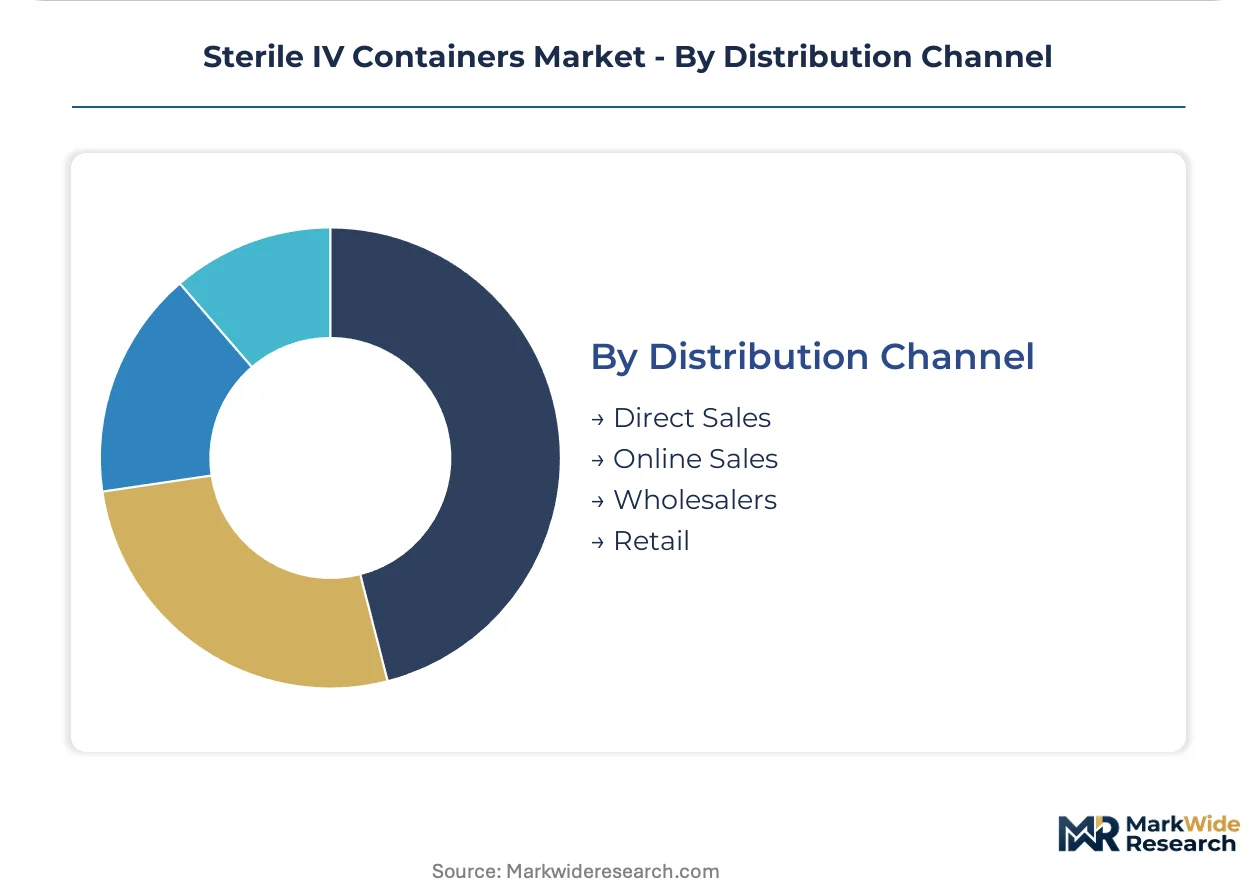
Distribution Channel:
Supply concentration determines margin structure and customer access economics.
- Direct Sales:Manufacturer field organizations manage multi-year agreements with the ten largest US integrated delivery networks and national health systems in Germany and Japan, embedding container supply within broader infusion platform contracts.
- Wholesalers:McKesson, Cardinal Health, and AmerisourceBergen intermediate volume for mid-tier hospital systems and independent clinics, capturing logistics value through consolidated sterile pharmaceutical distribution.
- Online Sales:E-procurement portals serve small ambulatory surgery centers and veterinary clinics with standardized bag configurations, though cold-chain and sterile handling requirements limit category penetration.
- Retail:Pharmacy chains and home medical equipment suppliers distribute pre-filled saline and dextrose containers for patient self-administration, particularly in US markets with direct-to-consumer reimbursement pathways.
Direct sales defend margin position through contract bundling; wholesaler relationships enable geographic coverage expansion without field sales infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Japan exceeds that in India by substantial margins, reflecting divergent procurement sophistication and regulatory stringency. Hospital systems in Munich and Tokyo negotiate multi-year container contracts with embedded pump-set bundling, while Indian state tenders favor lowest-unit-cost sourcing. This asymmetry shapes where manufacturers anchor premium positioning versus volume scale.
United States
Integrated delivery networks command consolidated procurement of flexible bag systems, with ten largest hospital systems controlling disproportionate acute care volume. FDA 21 CFR 211 container closure integrity standards elevate qualification barriers for standalone converters. Boston and Minneapolis medical device clusters host blow-fill-seal engineering talent pools that anchor sterile packaging innovation.
Germany
University hospital consortia drive demand for glass-to-plastic conversion in parenteral nutrition applications, prioritizing extractables documentation under EU MDR biocompatibility mandates. BfArM post-market surveillance requirements compress portfolio rationalization timelines for legacy container designs. Baden-Württemberg polymer film manufacturing corridor supplies multi-layer coextrusion capacity to European converters.
Japan
Aging infusion infrastructure in tertiary hospitals creates replacement demand for collapsible bag systems with METI-certified manufacturing traceability. PMDA pharmaceutical packaging guidelines enforce barrier performance testing that favors converters with in-house laboratories. Osaka-Kobe medical supply cluster concentrates blow-fill-seal technician training programs for regional capacity expansion.
India
Central government hospital procurement through HLL Lifecare channels volume toward cost-optimized PVC and polypropylene configurations. CDSCO medical device rules implementation is accelerating importer registration requirements for multinational container suppliers. Hyderabad and Ahmedabad pharmaceutical manufacturing zones are incubating domestic sterile conversion capacity for export markets.
China
Provincial centralized drug procurement reforms are extending to infusion device categories, compressing margins for imported container brands. NMPA sterile medical device registration requirements now mandate local biocompatibility testing for Class IIa packaging. Yangtze River Delta medical polymer compounding cluster supplies medical-grade polypropylene to domestic bag converters.
Sterile IV Containers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and sterile conversion. The market structure tilts toward consolidated vendor contracting, with hospital group purchasing organizations compressing procurement cycles around integrated infusion platform suppliers. Three archetypes dominate: diversified medical device conglomerates with end-to-end parenteral platforms; regional sterile packaging converters with blow-fill-seal specialization; and polymer film suppliers backward-integrated into container fabrication. Competitive moves center on multi-year supply contract anchoring and in-house biocompatibility laboratory accreditation to satisfy EU MDR documentation demands.
Within the diversified conglomerate tier, Baxter International Inc., B. Braun Melsungen AG, and Fresenius Kabi AG occupy positions that exemplify platform-integrated supply strategies. These Germany and US-based entities represent archetypes of vendors bundling container supply with infusion pump and administration set contracts to secure integrated delivery network loyalty. Their scale enables captive polymer film sourcing and distributed manufacturing footprints that satisfy multiple regulatory jurisdictions simultaneously. The concentration of named players from raw data in this tier underscores how hospital procurement consolidation favors entities with cross-product portfolio breadth rather than standalone container specialization.
| Leading Market Players |
|---|
| Terumo Corporation |
| Nipro Corporation |
| Baxter International Inc. |
| Medline Industries |
| BD |
| B. Braun Melsungen AG |
| ICU Medical, Inc. |
| Vioser SA |
| Fresenius Kabi AG |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp polymer freight corridors transmit resin cost volatility directly into European converter pricing, amplifying the spread between standardized multi-year hospital contracts and spot purchases by independent clinics. This logistics chokepoint concentrates bargaining power among integrated platform suppliers with captive film extrusion capacity, while smaller converters absorb margin compression from feedstock allocation disruptions.
Pricing Analysis
The customization-premium spread between configured-to-order oncology-specific containers and standard saline bags runs three to five multiples, reflecting therapy-specific barrier testing and EU MDR biocompatibility documentation tiers. Contract-based long-term offtake dominates hospital procurement, with volume scale and certification grade (FDA 21 CFR 211 vs. baseline ISO 15747) as primary price differentiation drivers. Cost compression in standard flexible bag tiers is intensifying because provincial centralized procurement in China extends to infusion device categories. Independent ambulatory surgery centers exhibit highest price sensitivity, while integrated delivery networks in the United States and Germany prioritize pump-set-container bundling over unit cost.
Supply Chain Analysis
Tariff exposure between United States and Chinese medical-grade polymer sources dominates supply chain risk assessment for converters without diversified resin qualification. Manufacturing gravity centers on Germany, Japan, and the United States for blow-fill-seal capacity, with China and India incubating domestic conversion for regional hospital procurement. Feedstock draws from Saudi Arabian and South Korean petrochemical complexes for medical-grade polypropylene homopolymer, plus Belgian and Dutch converters for specialized multilayer coextrusion films. Single-source vulnerability in DEHP-free plasticizer alternatives constrains PVC formulation flexibility. Distribution runs through three-tier structures: direct manufacturer field organizations for IDN contracts, McKesson-Cardinal-AmerisourceBergen wholesaler networks for mid-tier hospitals, and e-procurement portals for small ambulatory accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sterile IV container market sits in early-stage cyclical recovery as hospital capital expenditure cycles turn following pandemic-deferred infrastructure replacement. Replacement demand for aging rigid bottle systems in Japanese tertiary hospitals provides the cyclical driver.
For Market Incumbents: Build regulatory documentation moats through in-house biocompatibility laboratory accreditation to satisfy EU MDR post-market surveillance mandates. Consolidate blow-fill-seal technician training programs in Osaka-Kobe and Baden-Württemberg clusters to constrain competitor capacity expansion timelines. Anchor multi-year supply contracts with the ten largest United States integrated delivery networks before bundled pump-set-container procurement fully matures. Threat: standalone converters with specialized oncology formats erode share in high-value therapeutic categories. For New Entrants and Emerging Players: Indian state hospital procurement through HLL Lifecare channels offers the most penetrable geography, with CDSCO registration requirements still maturing for multinational suppliers. Target 503B compounding pharmacy outsourcing facilities in the United States with validated container closure integrity for beyond-use dating extensions. Go-to-market angle: METI-certified manufacturing traceability for Japanese hospital replacement cycles, leveraging domestic polymer film partnerships in the Yangtze River Delta for cost-optimized supply. For Investors and Strategic Acquirers: Regional sterile packaging converters with blow-fill-seal specialization and existing FDA 21 CFR 211 quality systems represent the priority acquisition archetype. Long-term viability across the analysis window hinges on EU MDR documentation depth and hospital GPO contract anchoring. Signal to watch: accelerated portfolio rationalization announcements from German and French notified bodies enforcing biocompatibility timelines on legacy container designs.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Biocompatibility Laboratory Accreditation | In-house testing capability satisfies notified body documentation demands for Class IIa sterile devices. |
| Hospital System Partnership | Integrated delivery network contracts embed container supply within pump-set bundling agreements. |
| Backward Integration into Polymer Film Extrusion | Captive resin-to-film operations insulate margin from Rotterdam-Antwerp freight corridor volatility. |
| Closed-System Transfer Device Integration | Needle-free administration interface convergence creates premium positioning for engineered combination products. |
| Geographic Manufacturing Footprint Expansion | METI-certified Japanese capacity and CDSCO-registered Indian facilities satisfy regional procurement localization mandates. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and blow-fill-seal operations directors anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and customs trade data for medical-grade polymer imports. Bottom-up facility capacity assessments and top-down hospital expenditure modeling triangulate volume estimates. The analysis combines field intelligence from German university hospital consortia, United States integrated delivery network headquarters, and Japanese tertiary hospital replacement planning committees with documentary evidence from BfArM and PMDA regulatory filings.
Calibration against historical hospital capital expenditure cycles and infusion infrastructure replacement timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include container format (flexible bag, glass bottle, rigid container, ampoule), material grade (polypropylene, PVC, borosilicate glass, cyclic olefin polymer), end-user setting (hospital, clinic, home care, pharmacy), and distribution channel structure (direct sales, wholesaler, online, retail). CAGRs derive from slope-intercept fitting of replacement demand curves and therapy volume extrapolations. Industry-specific forecast inputs incorporate EU MDR implementation pacing and home infusion therapy reimbursement pathway expansion.
Practitioners should monitor hospital capital expenditure committee approvals, EU MDR notified body enforcement consistency, and medical-grade polymer feedstock allocation announcements for early signals of forecast revision. Operating reality validation demands continuous tracking of blow-fill-seal technician wage premiums and DSCSA serialization compliance cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Casting and Splints Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Nipple Shield Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Retractable Needle Safety Syringes Market