
 Emesis Bag Market | 2026-2036
Emesis Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Emesis Bag Market Insights
Hospital group purchasing organizations is pivoting toward single-source contracts for disposable medical supplies, pressuring smaller distributors. SPIRIANT leverages its airline catering heritage to dominate travel-sickness emesis bag channels. Direct Air Flow sustains manufacturing scale across European healthcare systems through ISO-certified production lines. WK Thomas anchors the United Kingdom market with specialized biohazard containment designs.
An emesis bag is a sealed receptacle, typically constructed from polyethylene or polypropylene film with a rigid ring opening, engineered to contain vomitus and limit pathogen exposure during patient care. Wall thickness ranges from 0.03 mm to 0.08 mm depending on biohazard classification, with heat-sealed seams preventing leakage under pressure differential. Disposable product types command the largest volume share as hospitals phase out reusable alternatives to satisfy Joint Commission infection protocols. Emergency services applications represent the fastest-expanding segment, driven by ambulance fleet standardization and pre-hospital care expansion across municipal systems.
FDA medical device regulations classify emesis bags under Class I controls, while EPA Resource Conservation and Recovery Act provisions govern biohazard disposal pathways for contaminated units. The EU Medical Device Regulation imposes stricter clinical evaluation requirements on bags marketed for chemotherapy application, creating compliance cost divergence across Atlantic suppliers. ISO 10993 biocompatibility testing now extends to polymer additives, reshaping material selection for manufacturers serving multiple regulatory jurisdictions. Stakeholders must monitor evolving state-level pharmaceutical waste rules that could reclassify post-chemotherapy emesis bags as hazardous material.
Market Dynamics
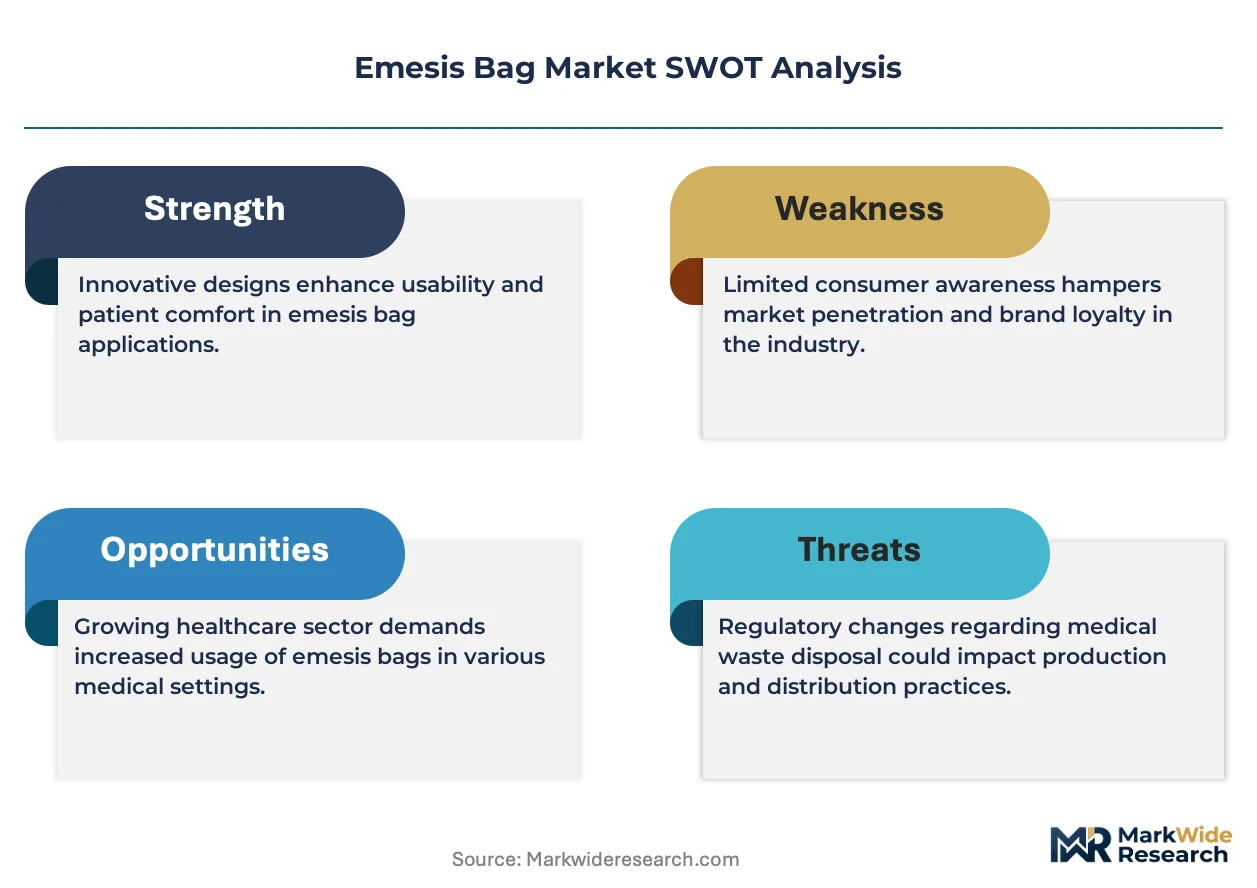
Hospital group purchasing organizations are consolidating vendor contracts for infection control supplies, compressing distributor margins and favoring manufacturers with ISO-certified production at scale.
Growth Catalysts
- Joint Commission infection protocols:US hospitals are phasing out reusable emesis containers in favor of single-use polyethylene bags, creating baseline demand across acute care facilities.
- Pre-hospital care expansion:Municipal ambulance fleet standardization across Germany and Japan is driving volume procurement for sealed-pathogen containment designs.
- EPA biohazard classification tightening:Stricter material specifications for contaminated medical waste disposal are forcing upgrades to heat-sealed, pressure-tested bag constructions.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings for medical-grade polymers squeeze converter margins and complicate long-term contract pricing.
- Supplier concentration in East Asian film extrusion:Dependence on a narrow base of certified film producers creates vulnerability to logistics disruption and quality variance.
- Reusable silicone alternatives:Some European outpatient clinics retain autoclavable containers for cost control, limiting disposable penetration in ambulatory settings.
Strategic Opportunities
- Chemotherapy application specialization:EU Medical Device Regulation clinical evaluation requirements for cytotoxic waste containment create premium positioning for compliant suppliers.
- Home healthcare delivery channels:Direct-to-patient distribution through specialty pharmacy networks is opening volume opportunities outside institutional procurement.
- Biodegradable polymer development:Convergence of polylactic acid films with existing heat-sealing equipment offers pathway to differentiate on sustainability credentials.
Industry Challenges
- ISO 10993 biocompatibility testing capacity:Extended laboratory queue times for polymer additive screening delay product launches across multiple regulatory jurisdictions.
- Legacy sterilization validation:Migration from ethylene oxide to alternative methods requires requalification of film-seal integrity under new processing parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emesis Bag Market |
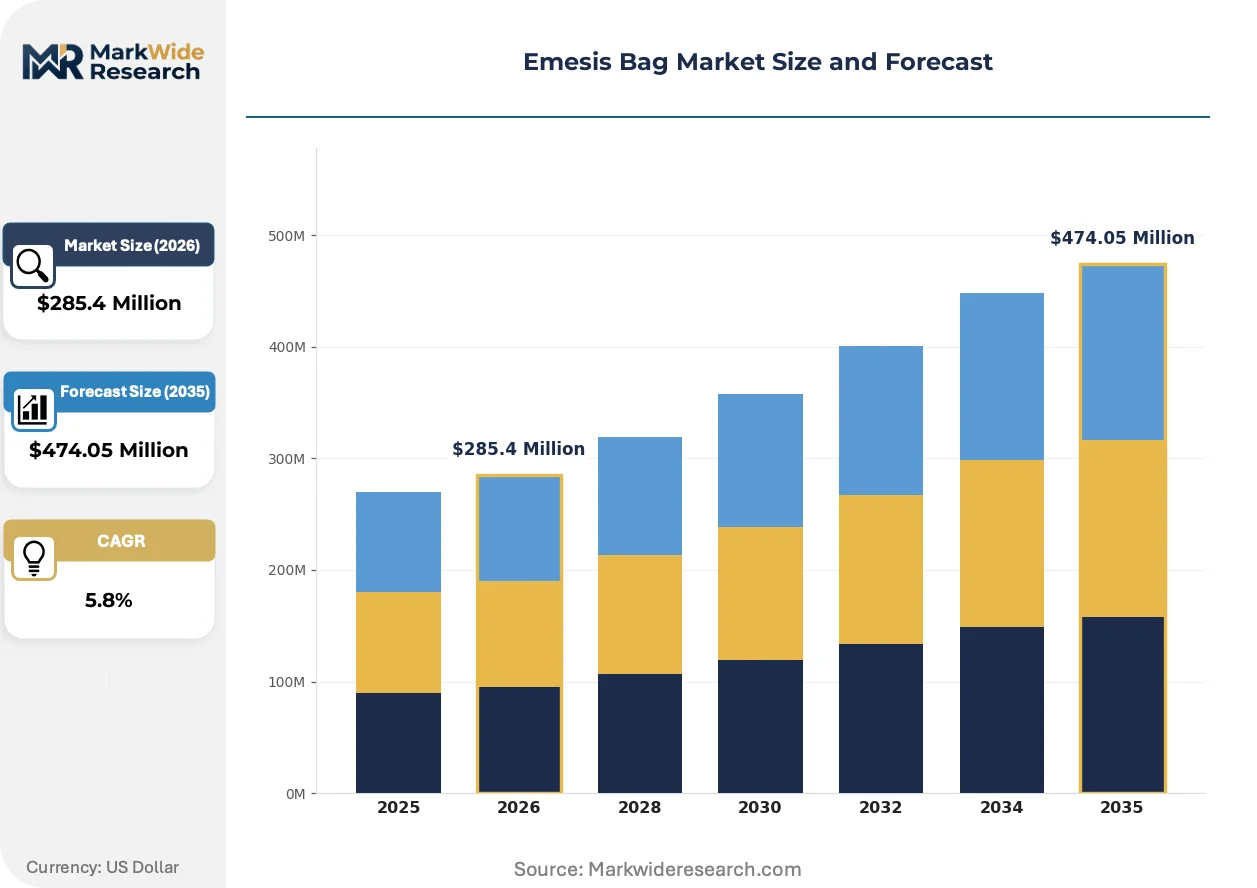
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biohazard, Customizable End User: Hospitals, Clinics, Home Care, Emergency Services Material: Plastic, Polypropylene, PVC, Latex Application: Chemotherapy, Surgical Procedures, Travel Sickness, Motion Sickness |
| Companies Covered | Direct Air Flow, ELAG Emballages, GOLD AWIN, International Plastic Industrie, Intex, Linstol, NOWARA, SPIRIANT, WK Thomas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emesis Bag Market Trends and Innovations
Material science advances and procurement centralization are redefining competitive positioning in emesis bag supply, with sustainability credentials and regulatory compliance emerging as primary differentiation vectors.
Antimicrobial additive integration is expanding into standard polyethylene formulations. Silver-ion and copper-based compounds embedded during extrusion inhibit pathogen survival on bag surfaces. Emergency medical services in the United States are adopting these upgraded specifications fastest, compressing the competitive window for untreated film suppliers.
REACH substance restrictions are reshaping European material sourcing. The European Chemicals Agency's expanding candidate list of substances of very high concern is forcing reformulation of plasticizers and slip agents used in medical films. Manufacturers serving chemotherapy applications face the steepest compliance costs, with some redirecting R&D budgets toward bio-based alternatives.
Consolidated contracting is displacing fragmented purchasing across hospital systems. Single-source agreements for disposable infection control supplies now span three-to-five year terms with volume guarantees, replacing spot-buying through multiple distributors. This pattern is most visible in Germany, where university hospital networks have centralized procurement for standardized product specifications.
Emesis Bag Market Segmentation
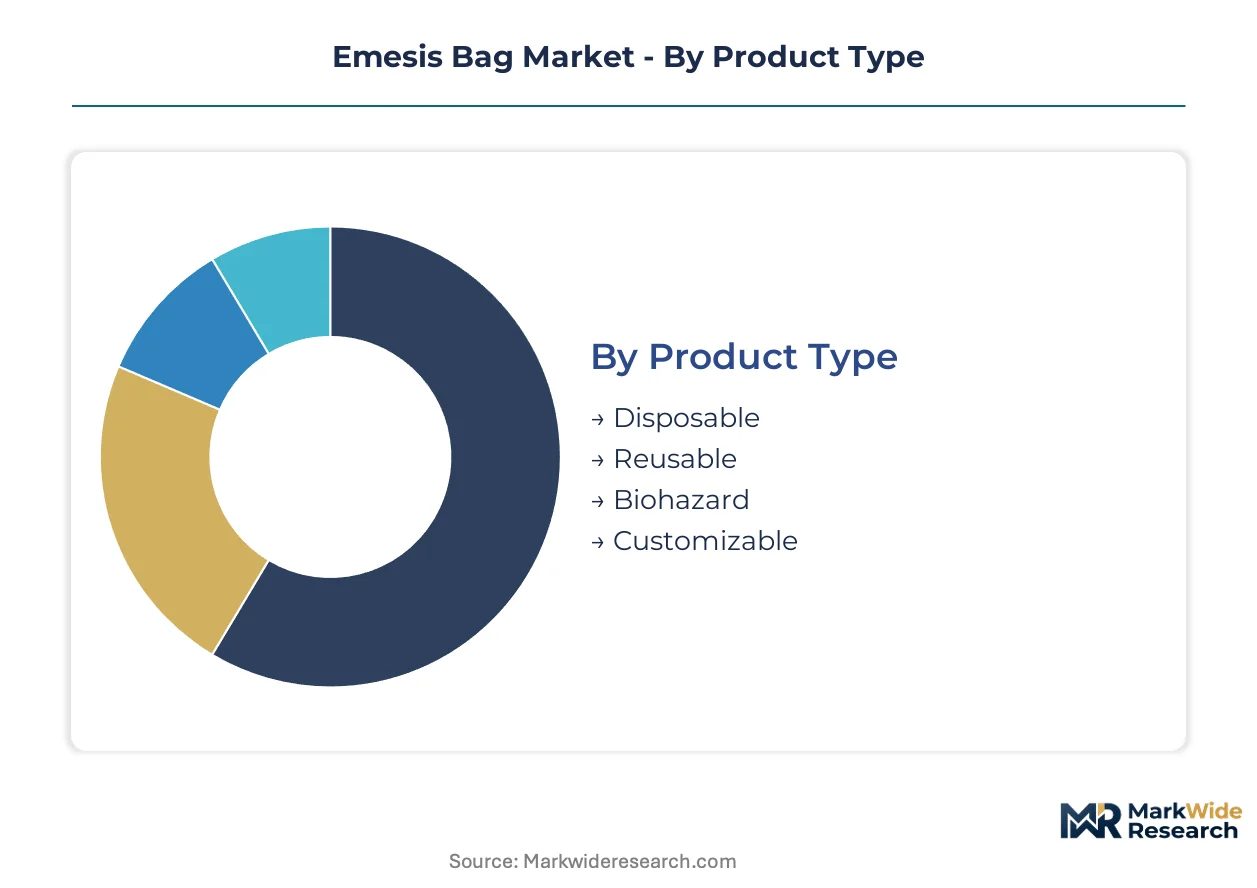
Emesis bag procurement patterns diverge sharply across product types and end-use settings, with infection control mandates and material specifications creating distinct investment profiles for manufacturers. Understanding these segment boundaries clarifies where capital deployment yields durable competitive positioning versus commodity exposure.
Product Type:
Capital intensity peaks with biohazard-rated constructions requiring validated heat-sealing equipment and dedicated cleanroom extrusion lines.
- Disposable:Polyethylene film constructions with 0.03-0.08 mm wall thickness dominate hospital procurement volumes. United States acute care facilities drive baseline demand through Joint Commission-mandated single-use protocols that eliminate reusable alternatives from infection control inventories.
- Biohazard:Pressure-tested seams and color-coded labeling satisfy EPA Resource Conservation and Recovery Act disposal pathways. Germany's municipal ambulance fleet standardization has elevated specifications for sealed-pathogen containment designs across pre-hospital care procurement.
- Reusable:Autoclavable silicone constructions retain foothold in European outpatient clinics prioritizing cost control over disposable convenience.
- Customizable:Branded configurations with antimicrobial additive integration command premium positioning in airline catering and cruise line channels.
Most installed capacity flows through Disposable. Expansion is steepest in Biohazard.
End User:
Customer concentration varies from fragmented home care delivery to consolidated hospital group purchasing organizations with multi-year contract horizons.
- Hospitals:Group purchasing organizations consolidate vendor contracts across three-to-five year terms with volume guarantees, compressing distributor margins and favoring ISO-certified manufacturers at scale.
- Emergency Services:Municipal ambulance fleet standardization across Germany and Japan drives sealed-pathogen containment procurement. Pre-hospital care expansion accelerates volume growth faster than institutional settings.
- Clinics:Ambulatory surgical centers balance infection protocol compliance against procedure volume economics, creating price-sensitive demand for standard polyethylene constructions.
- Home Care:Specialty pharmacy networks enable direct-to-patient distribution outside institutional procurement channels, opening volume opportunities in oncology supportive care.
Procurement consolidation concentrates in Hospitals. Volume is climbing the fastest in Emergency Services.
Material:
Feedstock cost volatility and regulatory compliance burdens create divergent margin structures across polymer categories.
- Polypropylene:Medical-grade resin with controlled melt flow index dominates extrusion lines serving chemotherapy applications. REACH substance restrictions on plasticizers and slip agents force ongoing reformulation for European market access.
- Plastic:Standard polyethylene formulations serve high-volume hospital contracts where cost minimization outweighs performance differentiation.
- PVC:Phthalate-free constructions retain niche positioning where clarity and pliability specifications exceed polyethylene capabilities.
- Latex:Natural rubber alternatives face declining utilization amid allergy protocol standardization across healthcare facilities.
Production scale concentrates in Polypropylene. Regulatory pressure is intensifying fastest on Plastic.
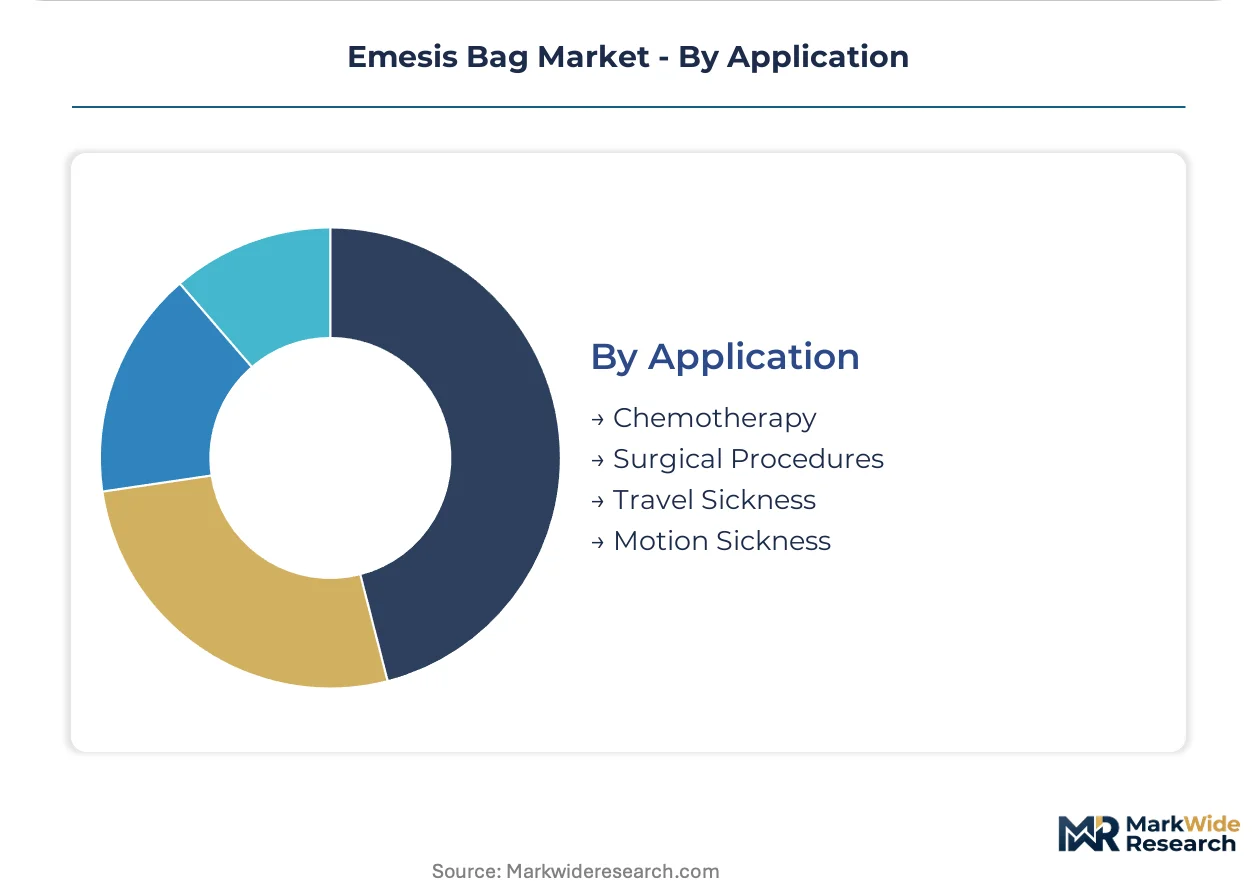
Application:
Clinical validation requirements and reimbursement pathways segment demand by procedure complexity and waste classification.
- Chemotherapy:EU Medical Device Regulation imposes clinical evaluation requirements for cytotoxic waste containment, creating compliance cost divergence across Atlantic suppliers. ISO 10993 biocompatibility testing for polymer additives extends development timelines.
- Surgical Procedures:Operating room standardization drives volume procurement for antimicrobial-integrated film constructions. Silver-ion and copper-based compounds embedded during extrusion inhibit pathogen survival on bag surfaces.
- Travel Sickness:Airline catering heritage suppliers dominate this channel with compact folded configurations optimized for seatback storage and rapid deployment.
- Motion Sickness:Marine and rail applications demand enhanced odor-sealing properties beyond standard healthcare specifications.
Revenue per unit peaks in Chemotherapy. Regulatory complexity is expanding most quickly in Surgical Procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal ambulance standardization outpaces Japan's hospital procurement consolidation, while the United States maintains the largest institutional volume base for infection control disposables.
United States
Joint Commission-mandated single-use protocols drive baseline demand across acute care facilities. FDA Class I medical device controls and EPA Resource Conservation and Recovery Act provisions govern biohazard disposal pathways. The Southeast hospital corridor concentrates group purchasing organization contract consolidation, compressing distributor margins in favor of ISO-certified manufacturers.
Germany
University hospital networks have centralized procurement for standardized product specifications across three-to-five year terms. REACH substance restrictions on plasticizers force ongoing reformulation of medical-grade films. The North Rhine-Westphalia industrial cluster hosts film extrusion capacity serving chemotherapy application specialization under EU Medical Device Regulation requirements.
Japan
Aging demographics expand hospital admission volumes and pre-hospital care fleet procurement. METI industrial standards and PMDA medical device oversight shape polymer additive screening protocols. The Kanto region around Tokyo anchors demand concentration for sealed-pathogen containment designs in municipal ambulance systems.
United Kingdom
WK Thomas anchors domestic market positioning with specialized biohazard containment designs. NHS procurement frameworks emphasize infection control compliance over cost minimization. The Midlands manufacturing belt sustains production scale for antimicrobial-integrated film constructions serving surgical procedure applications.
China
Domestic film extrusion capacity expansion reduces import dependence for medical-grade polyethylene. NMPA medical device registration and GB standards compliance reshape material selection for export-oriented manufacturers. The Yangtze River Delta concentration of polymer converters supplies both domestic hospital procurement and international distributor channels.
Emesis Bag Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Hospital group purchasing organization consolidation favors manufacturers with validated scale and multi-jurisdiction regulatory compliance. Three archetypes dominate: airline-catering heritage suppliers with travel-sickness channel control, ISO-certified healthcare specialists with institutional procurement access, and regional fabricators serving cost-sensitive ambulatory settings. Competitive moves concentrate on strategic partnerships with group purchasing organizations and geographic expansion through distributor network capture.
Among European-based fabricators, Direct Air Flow exemplifies ISO-certified production scale across healthcare systems, while WK Thomas occupies a position within the United Kingdom's specialized biohazard containment tier. SPIRIANT represents the airline-catering heritage archetype with travel-sickness channel dominance. These three companies anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Direct Air Flow |
| ELAG Emballages |
| GOLD AWIN |
| International Plastic Industrie |
| Intex |
| Linstol |
| NOWARA |
| SPIRIANT |
| WK Thomas |
| Others |
Pricing and Supply Chain Analysis
Heat-sealing equipment upgrades across East Asian film extrusion lines are compressing unit economics while concentrating certified capacity among producers capable of validating seam integrity under pressure differential. Hospital group purchasing organizations exploit this supply consolidation to extract multi-year contract concessions that lock in volume guarantees at fixed price tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard polyethylene constructions. Pricing stratifies across biohazard-rated, antimicrobial-integrated, and economy polyethylene tiers, with ISO 10993 compliance and FDA Class I registration commanding measurable premiums. Cost compression in standard disposable tiers is intensifying because resin feedstock volatility outpaces contract escalation clauses. Ambulatory surgical centers exhibit the highest price sensitivity, while chemotherapy application buyers prioritize clinical validation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German university hospital networks now require qualified backup suppliers for all heat-sealed film constructions. Medical-grade polypropylene resin draws from petrochemical complexes in China, South Korea, and Saudi Arabia, with controlled melt flow index specifications limiting substitution flexibility. Single-source vulnerability concentrates in East Asian film extrusion where ISO 14644 cleanroom certification creates qualification bottlenecks. Distribution runs through regional healthcare distributors capturing group purchasing organization contract administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Emesis Bag Market functions as a regulatory compounder where EPA biohazard classification tightening and EU Medical Device Regulation clinical evaluation requirements continuously elevate compliance barriers that filter marginal suppliers.
For Market Incumbents: To counter resin price volatility squeezing converter margins, anchor procurement scale through captive supply agreements with certified film extruders in the Yangtze River Delta. Defend market position by accelerating antimicrobial additive integration ahead of Joint Commission protocol revisions that will mandate pathogen-inhibiting surfaces in acute care settings. For New Entrants and Emerging Players: Specialty pharmacy networks serving oncology supportive care represent an underserved buyer archetype with fragmented procurement and limited incumbent penetration. Capture volume through direct-to-patient distribution partnerships that bypass consolidated hospital group purchasing organization channels. Prioritize biodegradable polylactic acid film development to differentiate on sustainability credentials as REACH substance restrictions tighten. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators serving cost-sensitive ambulatory settings without ISO 10993 testing capacity or multi-jurisdiction regulatory dossiers. Long-term viability favors targets with validated heat-sealing equipment and established hospital system contracts. Watch for EPA state-level pharmaceutical waste rule revisions that could reclassify post-chemotherapy emesis bags as hazardous material, triggering replacement demand for compliant containment designs.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Biocompatibility Certification | Polymer additive screening capacity unlocks chemotherapy application access under EU MDR. |
| Antimicrobial Film Integration | Silver-ion compound embedding during extrusion satisfies emerging Joint Commission pathogen protocols. |
| Group Purchasing Organization Partnership | Three-to-five year volume guarantees compress distributor margins and secure baseline hospital demand. |
| Biodegradable Polymer Transition | Polylactic acid film convergence with existing heat-sealing equipment addresses REACH substance restrictions. |
| Pre-Hospital Care Fleet Standardization | Municipal ambulance procurement across Germany and Japan drives sealed-pathogen containment volume growth. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, GPO contracts administrators, biomedical engineers, and film extrusion plant managers with secondary validation against FDA 510(k) filings, EPA hazardous waste manifests, hospital procurement databases, and customs trade records. Bottom-up unit demand estimates and top-down market sizing triangulated across infection control spend categories and medical waste generation rates.
Segment-weighted modeling distributed volume and value across product type, end user, material, and application dimensions throughout the forecast period. CAGRs derived from procedure volume growth, fleet standardization timelines, and regulatory compliance phase-in schedules. Model inputs incorporated Joint Commission protocol adoption curves, REACH substance restriction implementation, and municipal ambulance procurement cycles.
Underlying measurement precision varies by segment; disposable polyethylene hospital contracts carry tighter precision than emerging home care channels where direct-to-patient distribution remains nascent. Forecasts reflect assumptions on resin price stabilization and cleanroom capacity expansion. Deviation in EPA pharmaceutical waste reclassification timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Sterile Container Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Suture Wire Market
Medical Supplies
Medical Gloves Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Elbow Splints Market