
 Cryogenic Vials Market | 2026-2036
Cryogenic Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Vials Market Analysis
Preventive maintenance contracts for ultra-low temperature storage systems is hardening into a standard purchase requirement rather than an optional add-on. Thermo Fisher Scientific Inc. leverages its service network to lock in multi-year instrument-vial bundling agreements. DWK Life Sciences GmbH anchors its European position through specialized borosilicate glass vial production for vaccine cold chains. Sigma-Aldrich Corporation competes by extending its catalog breadth across polymer and metal formats for diverse laboratory protocols.
Cryogenic vials are sealed containers engineered from polypropylene, borosilicate glass, or metals, designed to withstand temperatures below -150°C while preserving biological specimen integrity through thermal cycling and long-term storage. Polymer vials dominate volume due to cost efficiency and disposability in high-throughput biobanking, though glass vials command premium positioning in vaccine preservation where inertness and seal reliability prove critical. Application demand skews heavily toward biobanking and stem cell storage as cell therapy pipelines mature, while pharmaceutical companies represent the most concentrated end-user margin pool due to bulk procurement scale and qualification rigor.
FDA 21 CFR Part 820 quality system regulations and EMA Good Manufacturing Practice standards govern vial material biocompatibility, leachable profiles, and closure integrity for clinical-grade specimens. ISO 20387 biobanking standards further shape product specifications for research institutions seeking accredited sample management. Stakeholders must monitor evolving cell therapy logistics requirements and dual-source qualification demands as supply security becomes inseparable from regulatory compliance in temperature-critical biological workflows.
Market Dynamics
Cell therapy commercialization timelines are compressing qualification cycles for clinical-grade storage containers, forcing manufacturers to pre-validate vial-closure systems against FDA and EMA stability protocols before biopharma clients initiate IND submissions.
Growth Catalysts
- ISO 20387 Biobanking Accreditation:Research institutions across Germany and China are mandating certified sample management infrastructure, directly expanding vial procurement for long-term specimen preservation.
- Cell Therapy Pipeline Maturation:Pharmaceutical companies are scaling cryogenic storage capacity to support autologous and allogeneic therapy manufacturing, driving bulk orders for validated container systems.
- Polypropylene Material Advancements:Enhanced polymer formulations now withstand thermal cycling below -150°C without cracking, reducing glass dependency in high-throughput biobanking operations.
Market Restraints
- Specialized Borosilicate Glass Supply Concentration:European glass vial production clusters in Germany and Switzerland, creating single-source vulnerability for vaccine cold chain applications requiring inert, non-leaching containers.
- FDA 21 CFR Part 820 Compliance Costs:Quality system documentation and validation testing for clinical-grade vials adds substantial overhead, squeezing margins for mid-scale manufacturers serving research markets.
- Metal Vial Substitution Pressure:Stainless steel containers for ultra-long-term germplasm storage offer superior thermal conductivity, threatening polymer vial positioning in agricultural biobanking segments.
Strategic Opportunities
- China Cryogenic Infrastructure Buildout:National biobank networks and cell therapy manufacturing parks in Shanghai and Suzhou are creating demand for qualified local vial suppliers with NMPA registration pathways.
- Automated Storage System Integration:Robotic biobank retrieval systems require standardized vial dimensions and barcode compatibility, opening specification partnerships with instrument manufacturers.
- EU Green Deal Sustainable Packaging Mandates:Regulatory pressure to reduce single-use plastics is accelerating development of recyclable polymer formulations and reusable metal vial programs for research applications.
Industry Challenges
- Dual-Source Qualification Burden:Biopharma procurement teams must validate secondary vial suppliers against identical FDA stability protocols, extending supplier onboarding timelines by months.
- Closure Integrity Verification Complexity:Ensuring seal reliability across polypropylene, glass, and metal formats requires specialized leak-testing equipment and trained technicians, constraining production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Vials Market |
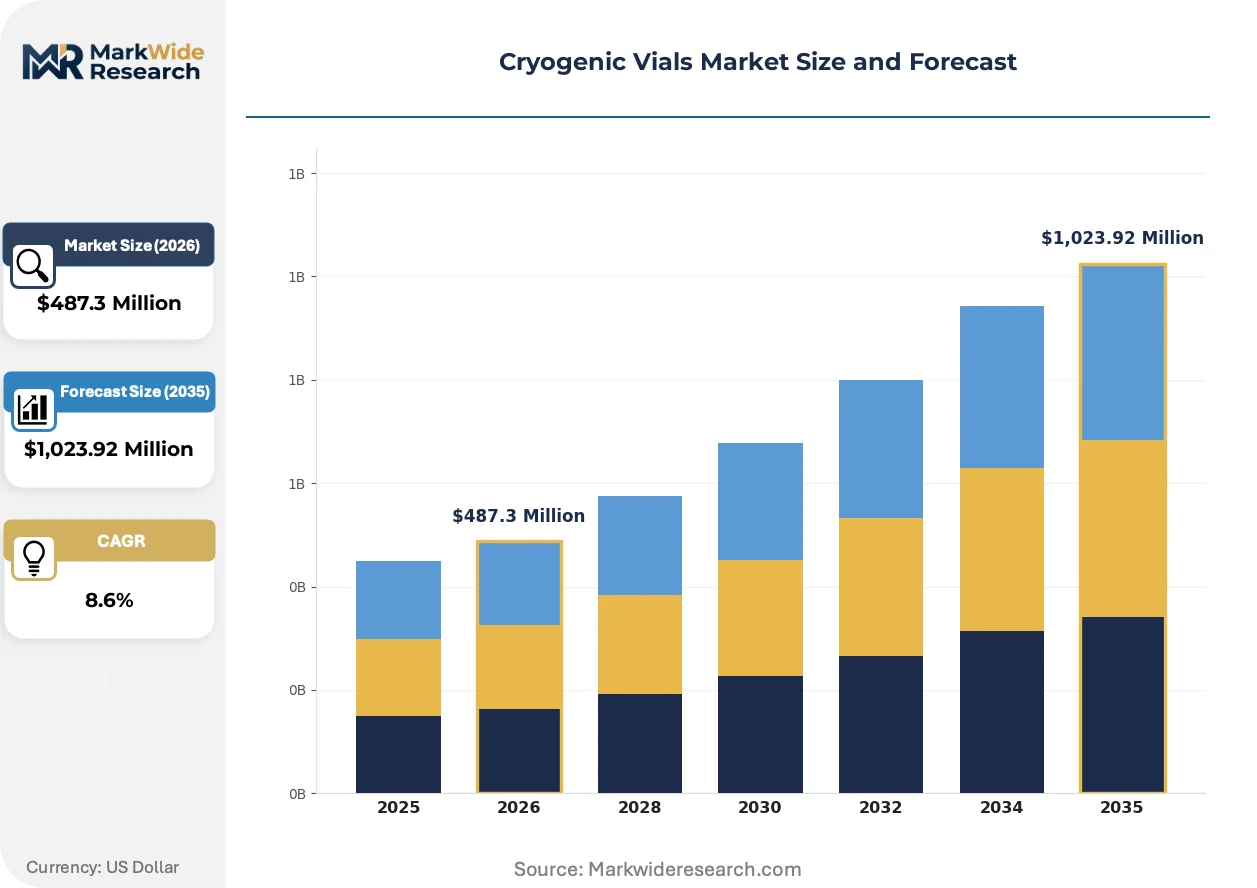
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Vials, Glass Vials, Aluminum Vials, Stainless Steel Vials Application: Biobanking, Stem Cell Storage, Laboratory Samples, Vaccine Preservation End User: Pharmaceutical Companies, Research Institutions, Hospital Laboratories, Biotech Firms Distribution Channel: Online Stores, Specialty Retailers, Direct Sales, Wholesalers |
| Companies Covered | Sigma-Aldrich Corporation, BioCision LLC, Thermo Fisher Scientific Inc., Starlab International GmbH, Sumitomo Bakelite Co. Ltd, Corning Incorporated, VWR International LLC, Incell Technologies, DWK Life Sciences GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Vials Market Emerging Trajectories
Pre-validated vial-closure systems are displacing custom qualification programs as cell therapy developers compress manufacturing readiness timelines. Material science advances and regulatory harmonization efforts are converging to reshape product specifications across research and clinical segments.
Pre-sterilized, ready-to-use polypropylene vials with integrated high-density barcode labels are overtaking conventional unmarked containers in automated biobanking facilities. High-throughput cell therapy manufacturers in the United States are specifying these formats to eliminate in-house labeling validation steps. This standardization is compressing supplier margins on custom-printed vial variants while rewarding scale players with validated manufacturing lines.
EMA Good Manufacturing Practice updates for cell-based therapy storage containers are tightening leachable and extractable testing requirements for all materials contacting clinical-grade specimens. Manufacturers must now submit comprehensive chemical characterization data across accelerated aging conditions. European biobanks and pharmaceutical companies are responding by consolidating procurement around suppliers with established EMA Master File documentation.
Service bundling is reshaping how research institutions acquire cryogenic storage infrastructure. Preventive maintenance contracts for ultra-low temperature freezers now routinely specify vial supply agreements as attached purchase conditions. This pattern is most pronounced in United States academic medical centers, where capital equipment procurement teams negotiate multi-year consumable lock-ins to secure service response guarantees.
Cryogenic Vials Market Segmentation
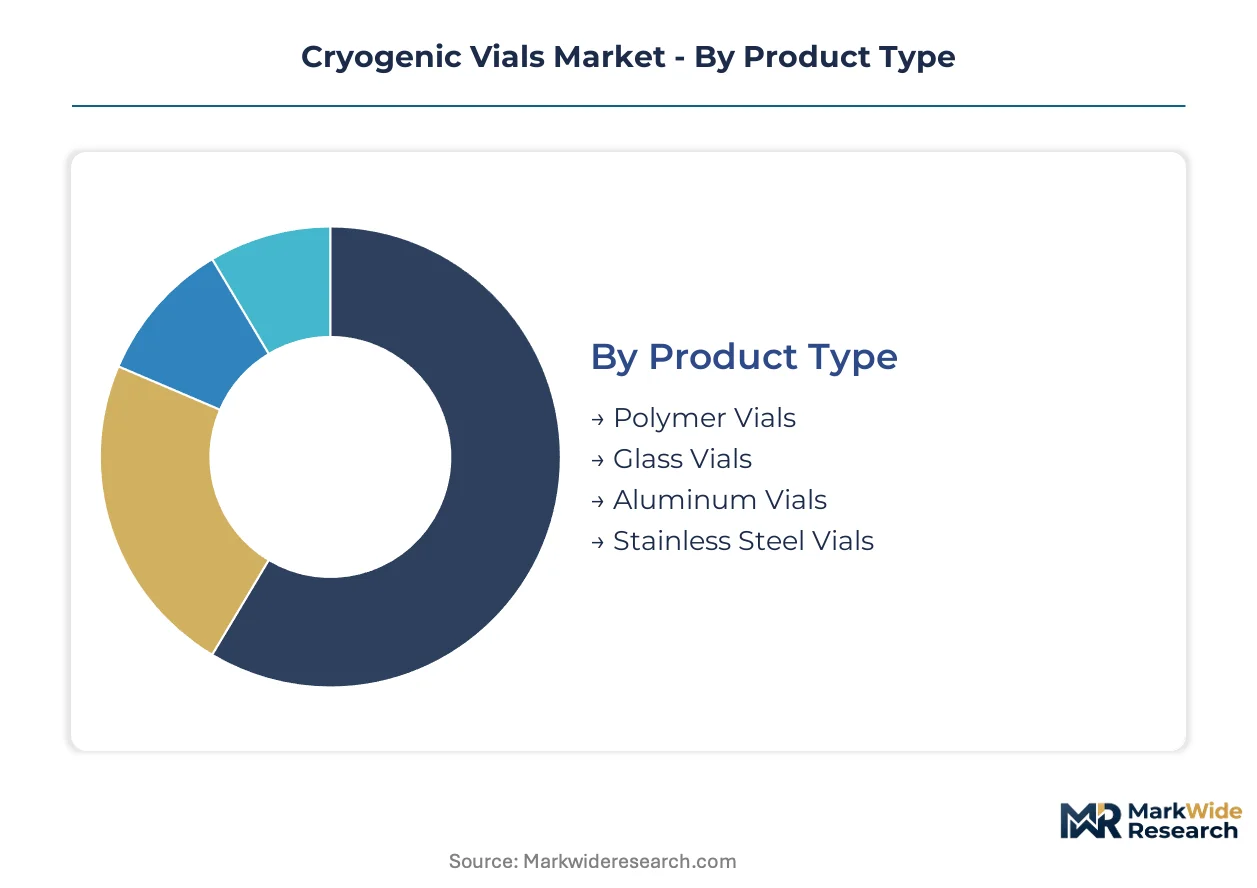
Cryogenic vial procurement splits sharply between standardized formats for high-throughput biobanking and custom-validated systems for cell therapy manufacturing. Material selection, application specificity, and end-user qualification rigor create distinct margin tiers across each segmentation dimension.
Product Type:
Standardization dominates polymer formats while glass and metal variants command premium positioning through specialized validation protocols.
- Polymer Vials:Polypropylene construction delivers cost-efficient disposability for high-throughput sample processing. Pharmaceutical companies in the United States and China specify these for bulk biobanking operations where thermal cycling resistance below -150°C meets ISO 20387 accreditation requirements.
- Glass Vials:Borosilicate formulations provide inert, non-leaching containment critical for vaccine cold chain integrity. German and Swiss production clusters supply European biobanks facing EMA Good Manufacturing Practice leachable testing mandates for clinical-grade specimens.
- Aluminum Vials:Lightweight metal construction suits portable cryogenic transport applications with moderate thermal conductivity demands.
- Stainless Steel Vials:Superior thermal conductivity supports ultra-long-term germplasm preservation in agricultural biobanking segments.
Leading the category by volume: Polymer Vials. Growing fastest: Stainless Steel Vials.
Application:
Clinical-grade applications impose heavier documentation burdens than research protocols, compressing supplier margins on standardized formats.
- Biobanking:Long-term specimen preservation at -150°C and below drives the largest addressable volume. German and Chinese research institutions mandate ISO 20387 certified infrastructure, expanding procurement for validated container systems with integrated barcode compatibility.
- Stem Cell Storage:Autologous and allogeneic therapy manufacturing requires pre-validated vial-closure systems against FDA stability protocols. United States cell therapy developers compress qualification cycles by specifying ready-to-use formats with pre-applied high-density labels.
- Laboratory Samples:Routine research applications favor cost-optimized polymer disposables with minimal validation overhead.
- Vaccine Preservation:Inert glass containment addresses EMA tightening of extractable profiles for temperature-sensitive biologicals.
Biobanking generates the highest absolute volume. Stem Cell Storage shows the steepest expansion trajectory as commercial cell therapies advance.
End User:
Procurement scale and qualification rigor separate concentrated pharmaceutical demand from fragmented research institution purchasing.
- Pharmaceutical Companies:Bulk procurement agreements with multi-year instrument-vial bundling dominate this segment. United States biopharma clients require dual-source qualification against identical FDA stability protocols, extending supplier onboarding timelines.
- Research Institutions:ISO 20387 accreditation mandates across Germany and China directly expand vial procurement for certified sample management infrastructure.
- Hospital Laboratories:Academic medical centers in the United States negotiate preventive maintenance contracts specifying attached vial supply agreements as standard purchase conditions.
- Biotech Firms:Emerging cell therapy developers prioritize pre-validated formats to accelerate IND submission timelines.
Pharmaceutical Companies anchor category value. Biotech Firms are climbing the fastest as cell therapy pipelines mature.
Distribution Channel:
Service bundling and automated procurement systems reshape how end-users acquire validated container systems.
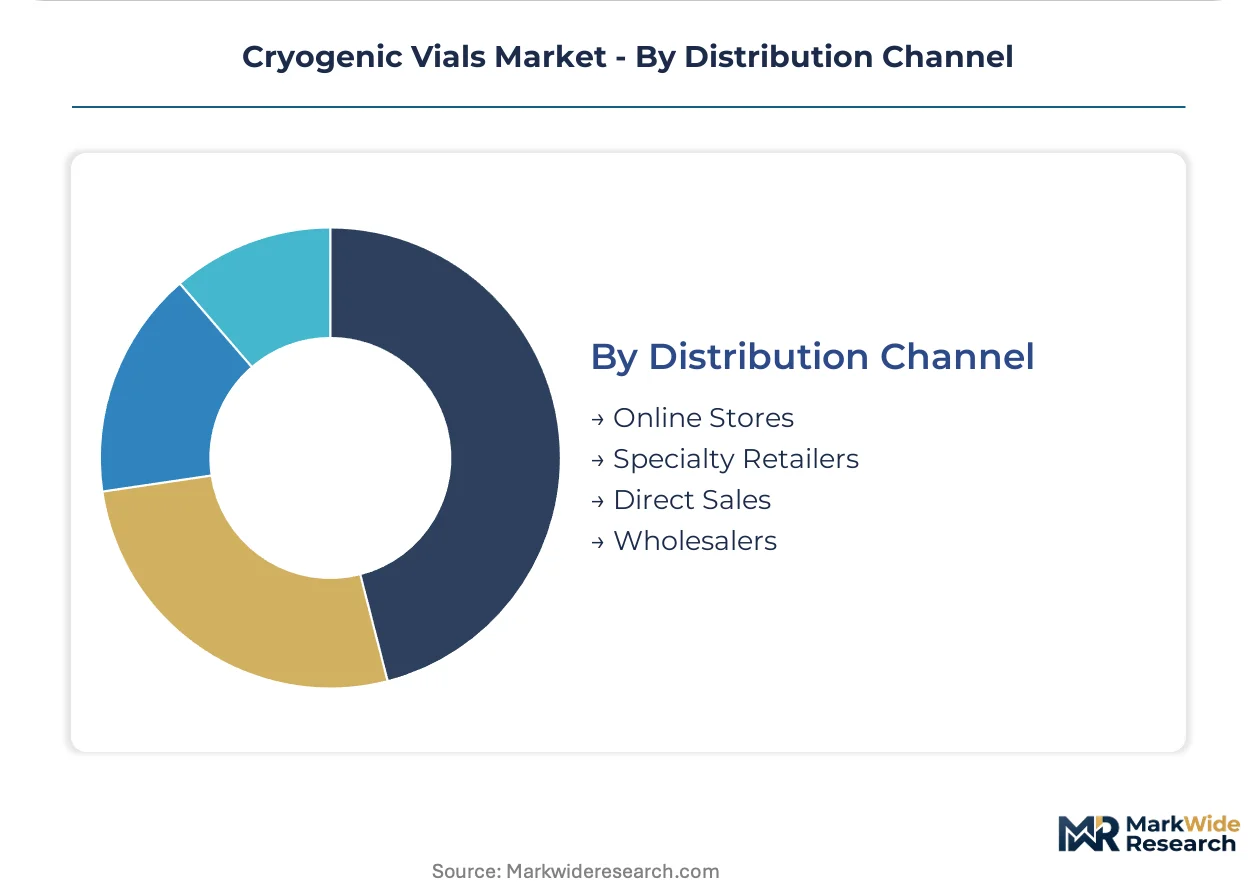
- Direct Sales:Multi-year agreements with instrument manufacturers lock in vial supply alongside ultra-low temperature freezer procurement. Thermo Fisher Scientific leverages its service network for this channel in United States academic medical centers.
- Specialty Retailers:DWK Life Sciences anchors European positioning through specialized borosilicate glass distribution for vaccine cold chain applications.
- Online Stores:Catalog breadth across polymer and metal formats supports diverse laboratory protocols for mid-scale research buyers.
- Wholesalers:Volume aggregation serves fragmented hospital laboratory demand with standardized polymer formats.
Direct Sales commands the highest value concentration. Online Stores are gaining share fastest among mid-scale research buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialized borosilicate glass production for vaccine cold chains, while the United States and China scale biobanking infrastructure fastest. Consumption patterns diverge between clinical-grade validation requirements in North America and research-volume procurement across Asia-Pacific.
United States
Academic medical centers in Boston and the San Francisco Bay Area negotiate multi-year instrument-vial bundling agreements with service guarantees. FDA 21 CFR Part 820 compliance documentation anchors procurement decisions for cell therapy developers preparing IND submissions. The National Institutes of Health-funded biobank networks expand validated container procurement across Maryland and North Carolina research corridors.
Germany
EMA Good Manufacturing Practice updates tighten leachable testing requirements for clinical-grade specimens, consolidating procurement around suppliers with established Master File documentation. The country's national pharmaceutical regulator mandates comprehensive chemical characterization data across accelerated aging conditions. DWK Life Sciences anchors European positioning through specialized borosilicate glass production clusters in Baden-Württemberg and Bavaria.
China
National biobank networks and cell therapy manufacturing parks in Shanghai and Suzhou create demand for qualified local suppliers with NMPA registration pathways. The national medical products administration accelerates review timelines for cryogenic storage containers supporting domestic cell therapy pipelines. Yangtze River Delta infrastructure buildout concentrates procurement scale in Jiangsu and Zhejiang provinces.
Switzerland
Swissmedic oversight of cell-based therapy storage containers reinforces premium positioning for inert, non-leaching containment systems. The national regulator coordinates with EMA on stability protocol harmonization for cross-border clinical trials. Basel and Zurich pharmaceutical clusters drive specialized glass vial demand for temperature-sensitive biological preservation.
Japan
PMDA guidelines on regenerative medicine storage infrastructure shape vial qualification requirements for domestic cell therapy developers. The national pharmaceutical regulator emphasizes closure integrity verification across polypropylene and glass formats. Kanto region biobanks and Osaka pharmaceutical manufacturing hubs standardize procurement around pre-validated, ready-to-use container systems.
Cryogenic Vials Market Vendor Landscape
Top-tier vendors anchor multi-year service bundling agreements with academic medical centers, while mid-scale specialists compete on catalog breadth and regional glass production expertise. The vendor base stratifies across instrument manufacturers with captive consumable programs, dedicated container fabricators with material science specialization, and diversified laboratory suppliers with broad format coverage. Two dominant competitive moves are reshaping positioning: geographic expansion through NMPA and EMA regulatory pathway establishment, and technology licensing partnerships for automated storage system compatibility.
Among diversified laboratory suppliers, Sigma-Aldrich Corporation and VWR International occupy positions exemplifying catalog breadth strategies across polymer and metal formats. Thermo Fisher Scientific represents the integrated instrument-consumable archetype, leveraging service network density for multi-year lock-in agreements. DWK Life Sciences GmbH anchors the specialized European glass fabricator tier, with geographic origin and corporate structure signaling material science depth rather than scale diversification.
| Leading Market Players |
|---|
| Sigma-Aldrich Corporation |
| BioCision LLC |
| Thermo Fisher Scientific Inc. |
| Starlab International GmbH |
| Sumitomo Bakelite Co. Ltd |
| Corning Incorporated |
| VWR International LLC |
| Incell Technologies |
| DWK Life Sciences GmbH |
| Others |
Supply Flow & Price Mechanics
Specialized polymer formulation chemists in Germany and Switzerland command wage premiums that widen spreads between clinical-grade and research-grade vial tiers. Labor-cost differentials between these European production clusters and Asian manufacturing bases directly translate into three-tier pricing stratification across premium borosilicate glass, validated polypropylene, and economy polymer formats.
Pricing Analysis
Margin tightening in research-grade polymer tiers reflects volume consolidation among Chinese manufacturers achieving ISO 20387 accreditation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated clinical systems from biobank-certified research formats and unvalidated laboratory disposables. Cost-down pressure on economy tiers accelerates because hospital laboratories prioritize bundled service contracts over standalone vial procurement. Pharmaceutical companies demonstrate lowest price sensitivity due to dual-source qualification requirements, while academic medical centers negotiate aggressively on multi-year instrument-vial packages.
Supply Chain Analysis
Direct-to-biopharma channels handle cell therapy developer demand for pre-validated vial-closure systems with attached stability documentation. Raw material supply concentrates in Germany and Switzerland for borosilicate glass, China for polypropylene resin, and Japan for specialized closure elastomers. Manufacturing draws from these inputs with single-source vulnerability concentrated in European glass production clusters serving vaccine cold chain applications. Tariff exposure on Chinese polymer imports threatens cost structures for mid-scale research suppliers. Distribution runs through instrument manufacturer captive networks, specialty distributors, and direct procurement portals serving fragmented laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic vial procurement is consolidating around suppliers with established regulatory documentation as FDA and EMA compliance costs eliminate marginal players. Cell therapy commercialization timelines compressing qualification cycles favor incumbents with pre-validated manufacturing lines.
For Market Incumbents: Acquire specialized borosilicate glass production assets in Baden-Württemberg or Bavaria to secure supply continuity for vaccine cold chain clients facing EMA leachable testing mandates. Expand backward integration into polypropylene resin compounding to control thermal cycling performance specifications and reduce dependency on Chinese material suppliers. Threats from metal vial substitution in agricultural biobanking segments require accelerated development of recyclable polymer formulations meeting EU Green Deal requirements. For New Entrants and Emerging Players: Mid-scale biotech firms in China's Yangtze River Delta represent the most penetrable buyer archetype, as these developers prioritize NMPA registration support over established brand relationships. Target automated storage system specification partnerships as the primary go-to-market angle, embedding barcode-compatible formats into robotic biobank retrieval platforms before incumbents lock in multi-year agreements. White space exists in sustainable packaging programs for European research institutions facing single-use plastic reduction mandates. For Investors and Strategic Acquirers: Re-rating potential sits with specialized European glass fabricators possessing EMA Master File documentation, given tightening leachable and extractable testing requirements for clinical-grade specimens. Long-term viability through the cell therapy manufacturing buildout window depends on regulatory pathway breadth across FDA, EMA, and NMPA jurisdictions. The signal to watch is accelerated dual-source qualification activity among top-20 biopharma procurement teams, indicating inflection toward supply security premiums over pure cost optimization.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Master File Documentation Investment | Positions suppliers for EMA Good Manufacturing Practice compliance as leachable testing requirements tighten. |
| NMPA Registration Pathway Establishment | Unlocks procurement from Shanghai and Suzhou cell therapy manufacturing parks building domestic capacity. |
| Automated Storage System Specification Partnership | Secures barcode-compatible format adoption in robotic biobank retrieval systems before competitor lock-in. |
| Recyclable Polymer Formulation Development | Addresses EU Green Deal single-use plastic reduction mandates affecting research institution procurement. |
| Pre-Validated Vial-Closure System Launch | Compresses client qualification timelines for cell therapy developers preparing IND submissions. |
Methodological Framework
Independent corroboration across primary interviews with biobank operations directors, pharmaceutical procurement managers, regulatory affairs specialists, and polymer formulation chemists underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 820 guidance documents, EMA Good Manufacturing Practice updates, ISO 20387 biobanking standards, and NMPA registration pathway disclosures. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from trade data and industry association reports.
Historical reference periods anchor the projection framework across the analysis window, with CAGRs derived from segment-level growth rate reconciliation against macro biobanking infrastructure investment trends. Segmentation dimensions include material type, application specificity, end-user qualification rigor, and regional regulatory cluster. Forecast inputs incorporate cell therapy pipeline maturation timelines, ISO 20387 accreditation adoption curves, and automated storage system penetration rates.
Revisions become necessary when FDA or EMA stability protocol updates alter validation requirements, when NMPA accelerates domestic supplier qualification timelines, or when raw material supply disruptions affect borosilicate glass or specialized polymer availability. Periodic stress-testing of base assumptions against cell therapy commercialization delays and biobank network buildout pace is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Pyonex Needles Market
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
Global Needles Market
Medical Supplies
Foley Trays Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Dissolvable Stitches Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Children's Antipyretic Patch Market
Medical Supplies
Global Swab Market