
 Europe Syringe Market | 2026-2036
Europe Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Syringe Market Insights
Asset-light leasing models for injection device production lines is rewriting competitive entry dynamics across the Europe Syringe Market. Becton Dickinson and Company leverages its scale in safety-engineered systems to sustain manufacturing flexibility. B. Braun SE anchors its position through deep specialization in regional hospital supply chains. Gerresheimer AG differentiates via glass primary packaging expertise that supports biologic drug compatibility.
A syringe is a cylindrical medical instrument with a plunger mechanism, typically manufactured with barrel capacities ranging from 0.5 mL to 60 mL, designed to aspirate or inject fluids with calibrated dosing precision. The device serves essential functions in parenteral drug administration, diagnostic specimen collection, and flush procedures across clinical and non-clinical settings. Prefilled syringes command premium positioning due to their integration with biologics and reduced medication preparation errors. Safety syringes represent the fastest-expanding product category as needlestick prevention mandates intensify across European healthcare systems. Conventional syringes retain volume dominance in vaccination and generic injectable applications where cost sensitivity prevails.
The EU Medical Device Regulation and EMA guidelines on combination products enforce stringent biocompatibility, sterility assurance, and unique device identification requirements that elevate compliance costs for market participants. REACH and RoHS frameworks further constrain material selection, pushing manufacturers toward medical-grade polymer innovations and glass substitution strategies. Stakeholders must weigh regulatory compliance investments against the margin compression from commoditized conventional segments while positioning for biologic-driven prefilled growth.
Market Dynamics
The EU Medical Device Regulation is compressing manufacturing timelines while elevating sterility assurance requirements, forcing producers to reconfigure quality systems and supplier validation protocols across European production networks.
Growth Catalysts
- Homecare administration expansion:Chronic disease management programs in Germany and France are routing injectable therapies outside hospital walls, expanding addressable volume for prefilled formats.
- REACH material compliance:The ECHA framework is accelerating substitution of legacy plasticizers with medical-grade cyclic olefin polymers that improve biologic drug stability.
- Needlestick prevention mandates:National occupational safety directives across EU member states are converting conventional syringe demand into safety-engineered replacements.
Market Restraints
- Borosilicate glass supply concentration:European sourcing of Type I glass tubing depends on a limited supplier base concentrated in Germany and Switzerland, creating input vulnerability for prefilled syringe producers.
- MDR certification timelines:The EU Medical Device Regulation's notified body capacity constraints are extending product registration cycles by 12-18 months for novel combination products.
- Silicone oil alternatives:Protein aggregation risks from conventional lubricants are forcing costly qualification of novel barrel coatings without established supply chains.
Strategic Opportunities
- Central and Eastern Europe hospital modernization:Poland and Romania are allocating EU cohesion funds to upgrade infusion and injection capabilities, opening new territory for safety syringe penetration.
- Biologic cold-chain integration:Prefilled syringes with embedded temperature indicators are capturing share from vial-and-syringe formats in mRNA and cell therapy distribution.
- Single-use system standardization:The EU Green Deal's waste reduction targets are creating pull for closed-system transfer devices that eliminate preparation steps and sharps exposure.
Industry Challenges
- Polymer extrusion expertise scarcity:Qualified engineers capable of tuning cyclic olefin polymer molding parameters for thin-wall syringe barrels are concentrated among a handful of specialized contract manufacturers.
- Legacy filling line reconfiguration:Converting existing aseptic processing equipment to handle nested prefilled syringe formats requires capital outlays that strain mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Syringe Market |
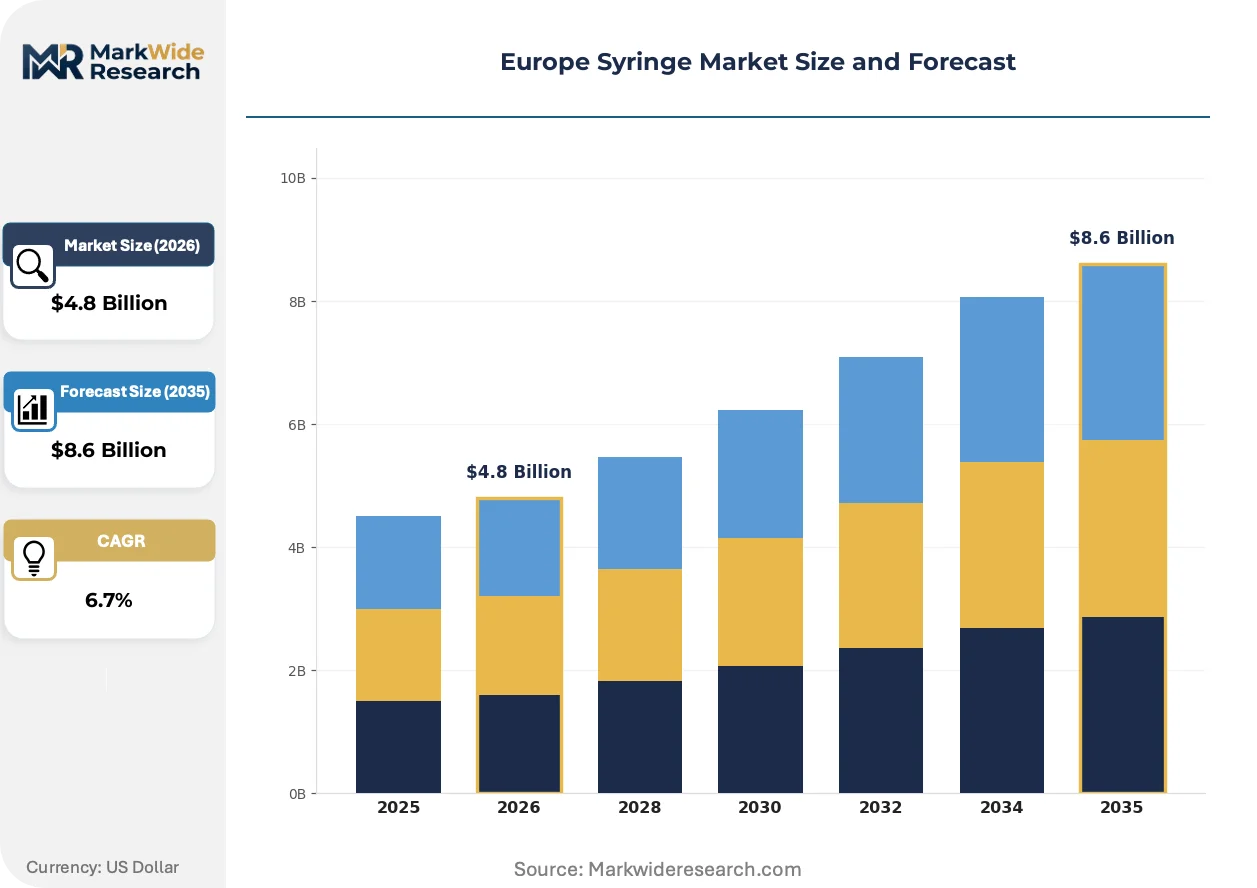
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto-Injectors, Safety Syringes, Conventional Syringes, Prefilled Syringes End User: Hospitals, Clinics, Homecare, Pharmacies Material: Plastic, Glass, Rubber, Metal Application: Vaccination, Insulin Delivery, Pain Management, Hormonal Therapy |
| Companies Covered | Becton Dickinson and Company, B. Braun SE, Gerresheimer AG, Terumo Corporation, Codan Medizinische Geräte Gmbh & Co Kg, Nipro Corporation, Schott AG, Fresenius SE & Co. KGaA, ICU Medical Inc. (Smiths Medical), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Syringe Market Trends and Innovations
Active materials science and digital traceability layers are converging to redefine syringe functionality beyond simple fluid containment, with implications for supply chain verification and patient adherence monitoring.
Glass primary packaging is migrating from traditional borosilicate formulations to aluminosilicate and surface-modified alternatives that withstand higher autoclave temperatures and reduce protein adsorption. Biologics manufacturers in the United Kingdom and Netherlands are qualifying these materials for high-value monoclonal antibody portfolios. The shift is migrating from niche oncology applications toward broader immunology and rare disease segments, compressing the addressable market for conventional glass tubing suppliers.
The EU Medical Device Regulation's Unique Device Identification mandate is forcing serialization infrastructure investments across European contract manufacturers. Sterile packaging operations must now integrate aggregation software and tamper-evident labeling that links individual syringes to batch records. Small-to-mid sized producers in Italy and Spain are most affected, responding through consortium-based shared service platforms to distribute compliance costs.
Hospital procurement consortia are consolidating purchasing power across regional health systems, displacing fragmented buying by individual facilities. France's UNIOPSS and Germany's EKAP networks now negotiate multi-year safety syringe supply agreements that bundle volume across dozens of hospitals. This concentration is most visible in Benelux and Nordic markets where national tendering has compressed supplier margins while locking in three-to-five year contracts.
Europe Syringe Market Segmentation
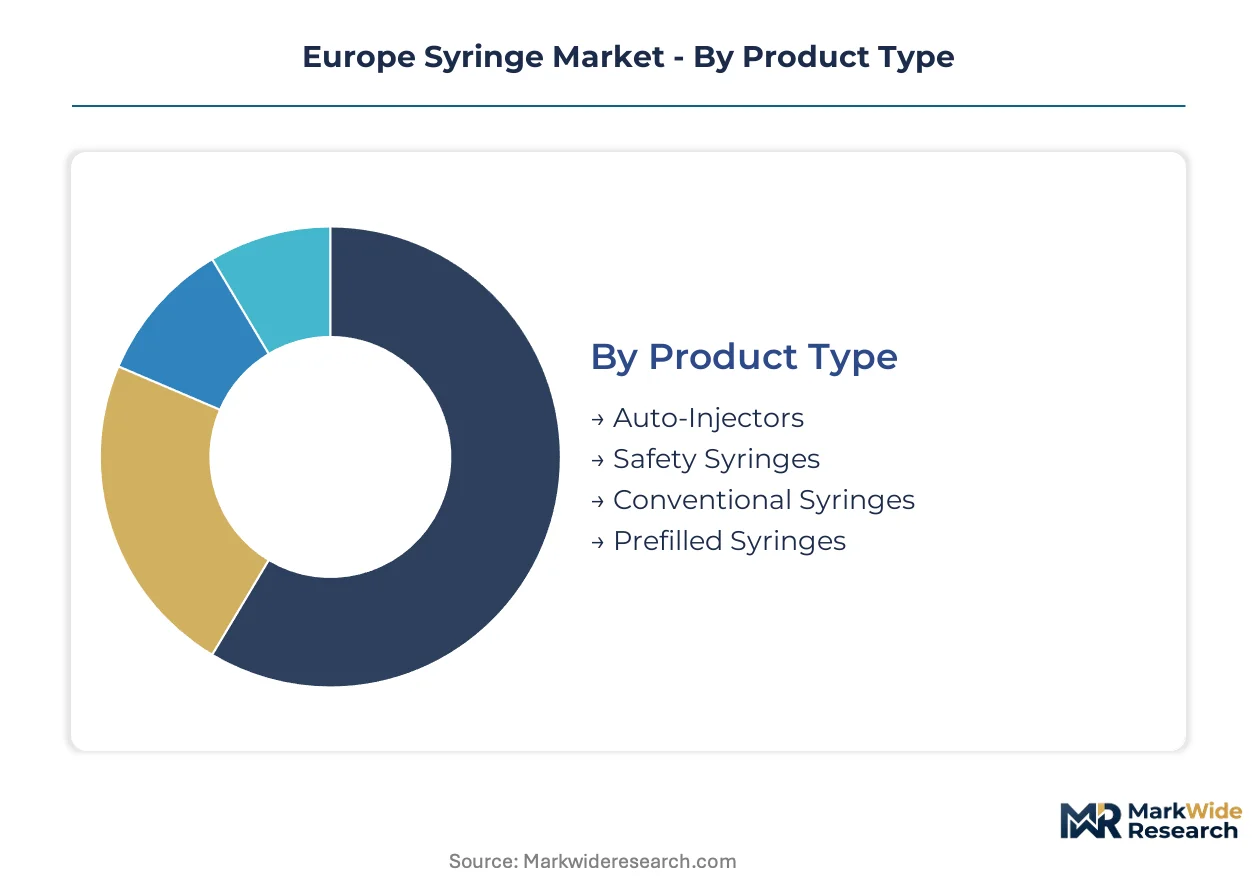
Segmentation in the Europe Syringe Market reveals how regulatory pressure and therapy evolution are redrawing category boundaries. Manufacturers must align product portfolios with distinct compliance burdens and end-user workflows across each dimension.
Product Type:
Mature formats face displacement as emerging safety-engineered and prefilled alternatives capture premium positioning and regulatory preference.
- Prefilled Syringes:These single-use units arrive sterile with pre-measured biologic or small-molecule doses, eliminating compounding errors. Demand concentrates in Germany and the Netherlands where monoclonal antibody therapies for immunology and rare diseases are expanding fastest under EMA combination product guidelines.
- Safety Syringes:Integrated needlestick prevention mechanisms—retractable needles or protective sheaths—dominate hospital procurement tenders. France's UNIOPSS and Germany's EKAP consortia mandate these formats for occupational safety compliance, converting conventional volume at the fastest clip.
- Conventional Syringes:Basic luer-lock or slip-tip designs remain the workhorse for mass vaccination campaigns and cost-sensitive generic injectables.
- Auto-Injectors:Spring-loaded devices with prefilled drug cartridges enable patient self-administration in homecare settings.
Conventional syringes retain volume leadership; safety syringes hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-rich hospital systems from price-sensitive retail channels and emerging homecare segments.
- Hospitals:Acute care facilities drive demand for safety-engineered systems and closed transfer devices. Procurement concentration through regional consortia in Benelux and the Nordic countries compresses margins while locking in multi-year supply agreements.
- Homecare:Chronic disease management programs in France and Germany are routing insulin, hormonal, and pain therapies outside institutional walls. This segment is expanding most quickly as patients and payers favor reduced hospital exposure.
- Clinics:Outpatient settings balance cost constraints with moderate safety requirements for routine injections.
- Pharmacies:Retail channels supply over-the-counter and prescription syringes for self-managed therapies.
Hospitals retain volume leadership; homecare holds the steepest expansion curve.
Material:
Supply concentration in European glass tubing and REACH-driven polymer substitution are reshaping sourcing strategies across the value chain.
- Glass:Type I borosilicate and emerging aluminosilicate formulations dominate biologic drug compatibility requirements. Sourcing concentrates among German and Swiss suppliers, creating input vulnerability for prefilled syringe producers.
- Plastic:Cyclic olefin polymers and copolymers are displacing legacy PVC and polycarbonate under ECHA restrictions. These materials enable thin-wall designs with improved moisture barrier properties for sensitive biologics.
- Rubber:Elastomeric plunger stoppers and needle shields require halobutyl formulations to minimize extractables.
- Metal:Stainless steel needles and spring components for auto-injector and safety mechanisms.
Glass retains volume leadership; plastic holds the steepest expansion curve.
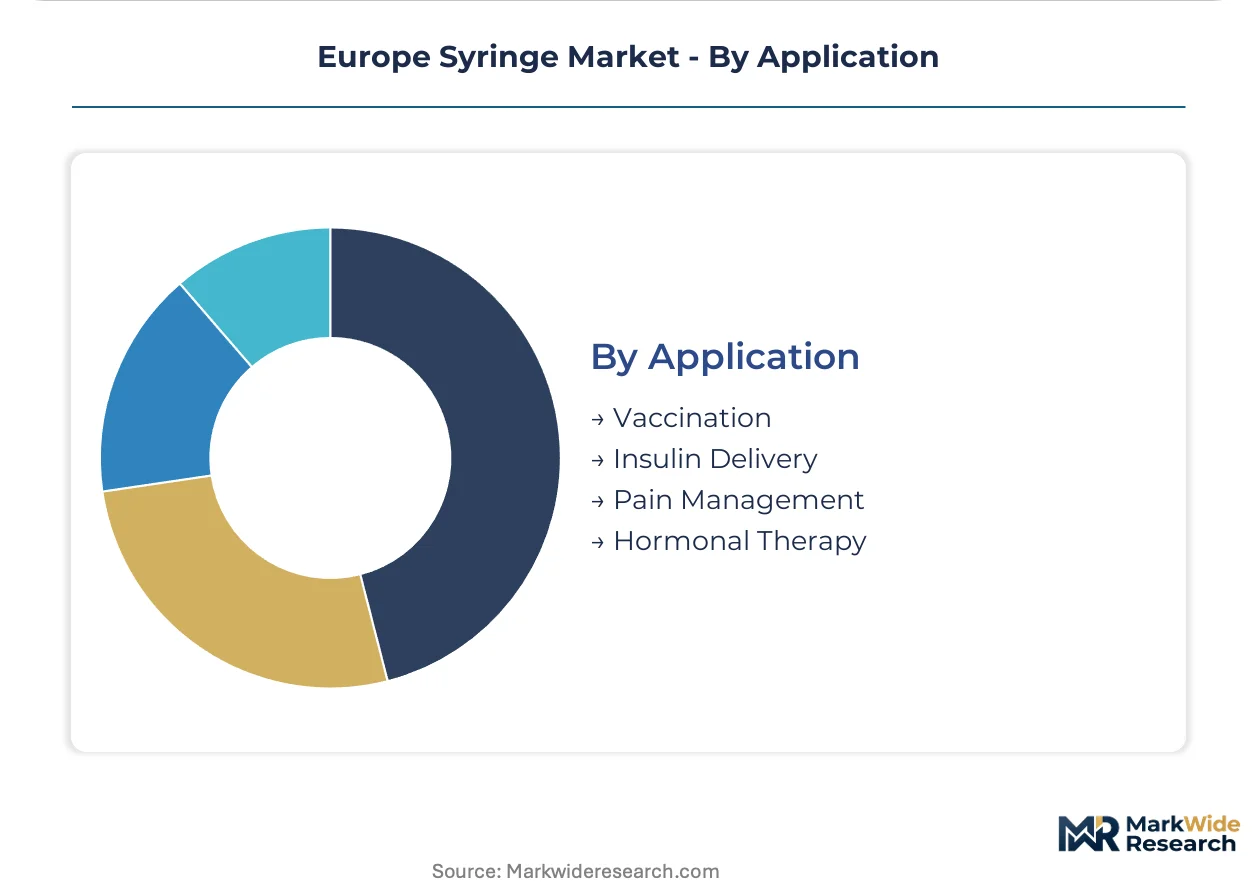
Application:
Volume scale separates mass preventive programs from targeted chronic therapy segments with diverging device performance requirements.
- Vaccination:National immunization programs across EU member states generate high-volume, low-margin demand for conventional disposable syringes. Cold-chain distribution requirements favor robust, cost-minimized designs.
- Insulin Delivery:Prefilled pens and syringes for diabetes management concentrate in homecare channels. Germany's disease management programs and France's ALD long-term illness coverage drive sustained volume.
- Pain Management:Opioid and non-opioid injectables for acute and chronic pain require precise dosing and safety features.
- Hormonal Therapy:Fertility treatments and endocrine disorders use specialized syringes with fine-gauge needles.
Vaccination retains volume leadership; insulin delivery holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's syringe trade flows reveal a pronounced import dependency for specialized glass tubing and polymer resins, while finished safety-engineered devices and prefilled formats circulate outward to Middle Eastern and African markets. The regional production footprint clusters along the Rhine corridor and Alpine manufacturing belt.
Germany
Chronic disease management programs for diabetes and autoimmune conditions are routing injectable therapies into homecare channels. The EKAP hospital procurement consortium bundles multi-year safety syringe contracts across regional health networks. Manufacturing concentrates in Baden-Württemberg and Hesse, where specialized polymer extrusion facilities supply thin-wall cyclic olefin barrels for biologic drug compatibility.
France
The UNIOPSS purchasing alliance mandates needlestick-prevention devices for occupational safety compliance in public hospitals. ALD long-term illness coverage expands reimbursement for self-administered hormonal and pain therapies outside institutional settings. The Île-de-France cluster hosts serialization infrastructure investments driven by MDR Unique Device Identification requirements.
United Kingdom
NHS England's national tendering for vaccination campaigns sustains high-volume demand for conventional disposable formats. Monoclonal antibody portfolios in immunology and rare diseases are qualifying aluminosilicate glass alternatives to reduce protein adsorption. Manufacturing activity concentrates in the Midlands and Greater Manchester, where contract sterilization providers serve prefilled syringe assemblers.
Netherlands
Rotterdam's port logistics and cold-chain infrastructure position the country as a distribution hub for mRNA and cell therapy prefilled formats with embedded temperature indicators. EMA combination product guidelines enforce stringent biocompatibility validation for devices co-packaged with biologics. The Brabant region hosts polymer compounding specialists supplying moisture-barrier materials to syringe molders.
Poland
EU cohesion fund allocations are modernizing hospital infusion and injection capabilities in regional medical centers. The national health fund's procurement centralization is consolidating safety syringe purchasing across voivodeship hospital networks. Manufacturing investment concentrates in the Łódź and Silesian regions, where contract molders serve Western European device assemblers.
Europe Syringe Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated device-drug combination specialists, regional hospital supply anchors, and component-focused materials suppliers. Scale-driven multinationals with safety-engineered portfolios compete against mid-tier European fabricators with deep hospital relationships. Dominant competitive moves include strategic partnerships with biologics manufacturers for prefilled co-development and geographic expansion into Central and Eastern European hospital modernization programs.
Among Germany-based specialists, B. Braun SE and Gerresheimer AG exemplify contrasting archetypes—one anchored in regional hospital supply chain integration, the other in glass primary packaging expertise for biologic drug compatibility. Becton Dickinson and Company occupies a position representing the scale-driven, safety-engineered systems tier with manufacturing flexibility across multiple European production networks. These three entities collectively illustrate the competitive segmentation between device integration, materials specialization, and global scale that defines the European market structure.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| B. Braun SE |
| Gerresheimer AG |
| Terumo Corporation |
| Codan Medizinische Geräte Gmbh & Co Kg |
| Nipro Corporation |
| Schott AG |
| Fresenius SE & Co. KGaA |
| ICU Medical Inc. (Smiths Medical) |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Swiss Type I borosilicate glass tubing suppliers determines both pricing tier spreads and supply chain shape across the Europe Syringe Market. REACH-driven substitution toward cyclic olefin polymers widens the cost gap between premium prefilled formats and commodity conventional syringes while forcing manufacturers toward captive polymer compounding arrangements.
Pricing Analysis
Hospital procurement consortia anchor three-tier pricing structure across premium, standard, and economy levels in the Europe Syringe Market. Price differentiation stems from MDR certification grade and volume scale commitments under multi-year EKAP and UNIOPSS contracts. Cost compression in conventional vaccination syringes is intensifying because NHS England national tendering bundles massive single-source awards. Retail pharmacy channels exhibit highest price sensitivity, while biologics manufacturers qualifying aluminosilicate glass formats show lowest sensitivity due to protein stability requirements.
Supply Chain Analysis
Export-control restrictions on advanced polymer extrusion equipment limit technology transfer to qualified European contract manufacturers. Supply concentrates in Germany, Switzerland, and the Netherlands for glass tubing, polymer resins, and serialization infrastructure respectively. Raw material dependencies include halobutyl rubber for plunger stoppers, medical-grade cyclic olefin polymers, and stainless steel needle alloys. Single-source vulnerability in German borosilicate glass tubing creates input chokepoints for prefilled syringe assemblers. Distribution runs through Rotterdam cold-chain hubs for mRNA and cell therapy formats, with regional hospital consortia handling last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Syringe Market functions as a service-attach opportunity where serialization compliance and sterilization validation contracts expand faster than hardware sales. Prefilled syringe producers increasingly bundle UDI aggregation software and batch record integration as recurring revenue layers.
For Market Incumbents: Build regulatory certification moats by accelerating MDR notified body relationships ahead of capacity constraints. Becton Dickinson and B. Braun SE should deepen backward integration into cyclic olefin polymer compounding to offset ECHA supply restrictions. Consolidation of Italian and Spanish contract manufacturers through shared serialization platforms defends margin position against mid-tier price competition. For New Entrants and Emerging Players: Central and Eastern European hospital modernization presents the most penetrable white-space target, with Poland and Romania allocating EU cohesion funds to upgrade injection capabilities. Safety-engineered syringe demand outpaces local supply in these markets. A go-to-market angle targeting voivodeship procurement centralization with bundled training and compliance support bypasses established Western European consortia relationships. For Investors and Strategic Acquirers: MDR Unique Device Identification mandates reshape the acquisition landscape toward serialization-ready contract manufacturers. Long-term viability over the next decade hinges on positioning for biologic-driven prefilled growth rather than commoditized conventional volume. Acquisition targets should display polymer extrusion expertise for thin-wall cyclic olefin barrels. The signal to watch is EMA combination product guideline enforcement tightening biocompatibility validation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Acceleration | Notified body capacity constraints extend registration cycles for novel combination products. |
| Polymer Compounding Integration | Cyclic olefin polymer substitution under REACH reduces dependency on legacy plasticizer supply chains. |
| Hospital Consortium Partnership | EKAP and UNIOPSS multi-year agreements lock in volume across regional health networks. |
| Cold-Chain Infrastructure Expansion | Rotterdam hub positioning captures mRNA and cell therapy prefilled distribution flows. |
| Serialization Platform Consolidation | Shared service platforms distribute MDR UDI compliance costs among Italian and Spanish producers. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EMA submission databases, EU notified body registries, hospital procurement databases, and GPO contract repositories. Bottom-up volume modeling across product type, material, end user, and application segments triangulated against top-down market sizing from trade flow analysis.
Scenario-bracketing anchored projections across low, base, and high cases reflecting MDR implementation pace and biologics pipeline advancement. The analytical framework modeled demand across product type, material formulation, end-user channel, therapeutic application, and national regulatory cluster throughout the forecast period. CAGRs derived from segment-level growth trajectory analysis incorporating therapy expansion rates, substitution dynamics, and procurement pattern shifts. Forecast inputs included monoclonal antibody portfolio expansion in Germany and Netherlands, and needlestick prevention mandate enforcement across EU member states.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier polymer specialists would shift outcomes. Material shifts in EMA combination product guideline enforcement or sudden borosilicate glass supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Physiological Saline Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Mexico Hospital Supplies Market
Medical Supplies
Global Lancets Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Finger Splint Market
Medical Supplies
Pyonex Needles Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Disposable Hospital Supplies Market