
 Centrifuge Bottles Market | 2026-2036
Centrifuge Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifuge Bottles Market Analysis
Asset-light leasing models for high-performance centrifuge systems is reconfiguring how smaller laboratories access premium consumables without capital expenditure. Thermo Fisher Scientific leverages its integrated distribution network to sustain recurring revenue from bundled instrument-consumable contracts. Corning Incorporated anchors its position through proprietary polymer formulations that withstand extreme g-forces in ultracentrifugation protocols. Eppendorf AG differentiates by specializing in precision-molded bottles optimized for temperature-sensitive biological separations.
Centrifuge bottles are rigid vessels engineered from polypropylene, polycarbonate, or borosilicate glass, designed to contain liquid samples during rotational acceleration typically ranging from hundreds to over 100,000 times gravitational force. These containers seal via screw-cap, snap-cap, or gasket mechanisms to prevent aerosol escape and maintain sample integrity across temperature differentials in clinical diagnostics, pharmaceutical manufacturing, and academic research settings. Polypropylene bottles dominate routine laboratory workflows due to chemical resistance and cost efficiency, while polycarbonate variants command premium positioning in high-speed applications where optical clarity and impact strength prove critical. The 50 mL volume capacity segment leads unit shipments globally, though 250 mL configurations are gaining traction in industrial bioprocessing where batch-scale separations require larger single-use volumes.
The US FDA governs centrifuge bottles intended for diagnostic specimen handling under quality system regulations, while the EPA monitors disposal pathways for contaminated polymeric consumables in clinical and research settings. ISO 13485 certification requirements for medical device suppliers are elevating documentation burdens for manufacturers serving regulated end-users. REACH compliance in Europe restricts certain plasticizers and additives in polymer formulations, compelling reformulation investments across the supply base. Stakeholders must monitor evolving biologics manufacturing standards and polymer sustainability mandates to align product development with purchaser qualification criteria.
Market Dynamics
Single-use adoption in pharmaceutical bioprocessing is restructuring procurement patterns, as contract manufacturers prioritize contamination control over capital equipment depreciation cycles. This shift concentrates purchasing power among sterile processing facilities and accelerates specification tightening for polymer purity grades.
Growth Catalysts
- Biologics manufacturing expansion:Cell and gene therapy facilities in Germany's Rhine-Main cluster are scaling sterile processing capacity, driving demand for certified single-use consumables that eliminate cleaning validation burdens.
- REACH polymer reformulation:ECHA restrictions on phthalate plasticizers are compelling suppliers to develop bio-based alternatives, opening qualification pathways for next-generation polypropylene formulations with enhanced chemical resistance.
- ISO 13485 certification elevation:Medical device quality system mandates are filtering out non-compliant regional suppliers, consolidating procurement toward documented supply chains that reduce audit risk for diagnostic laboratories.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to propylene monomer supply disrupt margin planning for molders serving price-sensitive academic research segments.
- Optical-grade polycarbonate concentration:High-clarity polymer supply concentrates among Asian petrochemical complexes, exposing European ultracentrifugation users to extended lead times and currency fluctuation risk.
- Glass substitution ceiling:Borosilicate vessels retain irreplaceable positions in extreme pH protocols and solvent-heavy workflows, capping polymer penetration in legacy pharmaceutical quality control departments.
Strategic Opportunities
- India biopharma infrastructure buildout:CDSCO manufacturing incentives and PLI scheme benefits are attracting sterile processing investments in Hyderabad and Bengaluru, creating demand for import-substituted consumable supply.
- Closed-system aseptic processing:Integration of single-use centrifuge bottles with automated filling lines addresses containment requirements for potent compound handling in oncology manufacturing suites.
- Leasing model penetration:Asset-light access programs for high-speed centrifuge systems bundle premium consumables without capital expenditure, capturing mid-tier contract research organizations previously priced out of advanced separation workflows.
Industry Challenges
- Precision molding talent scarcity:Tooling engineers capable of maintaining sub-10-micron tolerances for high-speed rotor compatibility command premium compensation, constraining capacity expansion at mid-scale manufacturers.
- Multi-jurisdictional certification lag:Simultaneous FDA 510(k) pathway navigation and EU MDR technical documentation preparation extends product launch timelines by 14-22 months for novel polymer formulations.
- Legacy instrument compatibility:Proprietary rotor geometries from installed equipment bases force consumable suppliers to maintain extensive adapter portfolios, fragmenting production runs and elevating tooling amortization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifuge Bottles Market |
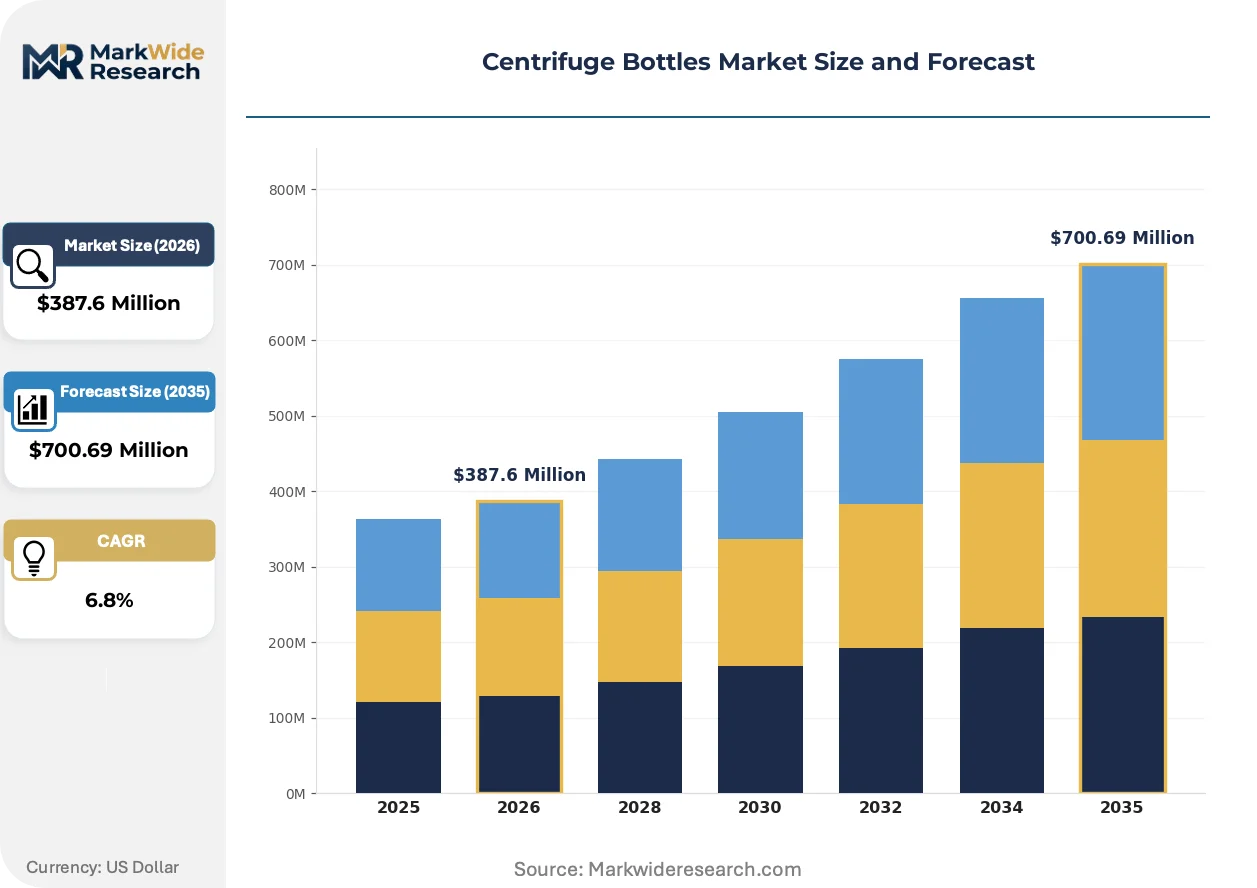
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polycarbonate, Glass, High-Density Polyethylene Cork Type: Screw-Cap, Snap-Cap, Sealing Gasket, Plug Seal Volume Capacity: 15 mL, 50 mL, 100 mL, 250 mL Application: Laboratory Use, Clinical Diagnostics, Research, Industrial Applications |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, Danaher Corporation, Eppendorf AG, Sartorius AG, CELLTREAT Scientific Products, Sigma-Aldrich, DURAN Group, Biomedical Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifuge Bottles Market Emerging Trajectories
Digital specification management and predictive inventory systems are compressing traditional procurement cycles, while polymer science advances enable thinner-walled designs that withstand equivalent g-forces with reduced material inputs.
Computational fluid dynamics simulation is virtualizing rotor and bottle design validation, replacing physical prototype iterations with finite element analysis. Bioprocess engineers at sterile manufacturing facilities are adopting these tools to optimize fill volumes and reduce aerosol risk before mold fabrication. This virtualization compresses development timelines from 18 months to under 6 months for custom geometries, accelerating supplier responsiveness to proprietary bioreactor integration requirements.
EMA's tightened guidance on extractables and leachables testing for container closure systems is elevating analytical documentation burdens. Suppliers must now submit comprehensive migration studies using multiple solvent systems and accelerated aging protocols. Pharmaceutical end-users in the European Economic Area are responding by consolidating qualified vendor lists to those with in-house toxicology assessment capabilities, effectively raising competitive barriers for regional molders without analytical chemistry infrastructure.
Contract research organizations are unbundling after-sales service from equipment procurement, negotiating consumable-only supply agreements with third-party logistics providers. This disintermediation bypasses traditional distributor markups and enables direct vendor-managed inventory at multi-site research campuses. The shift is most visible in the United States, where national laboratory networks consolidate purchasing through group procurement organizations that mandate price transparency and volume rebate structures previously obscured by bundled service contracts.
Centrifuge Bottles Market Segmentation
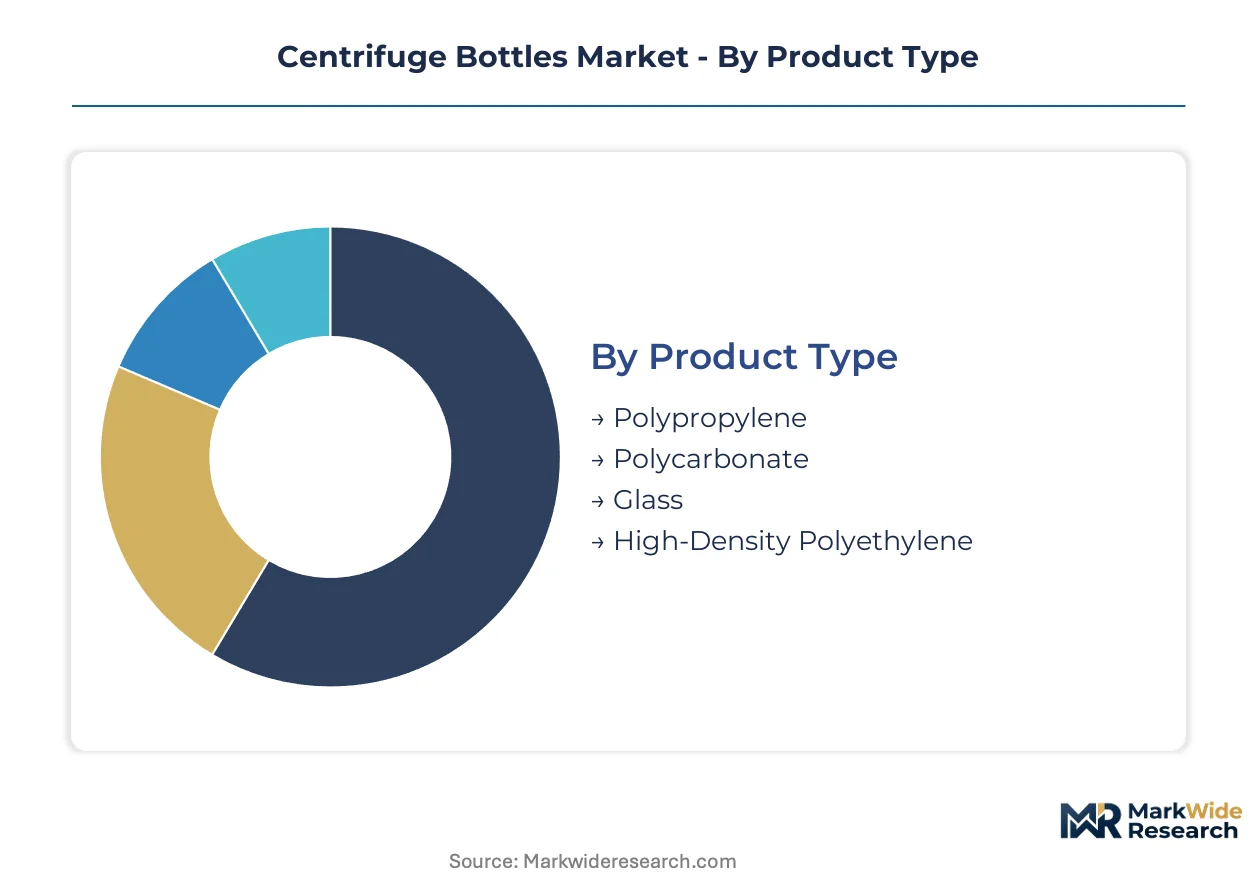
Centrifuge bottle procurement patterns diverge sharply across material grades and closure systems. Polymer purity specifications and rotor compatibility requirements create distinct purchasing workflows that suppliers must navigate simultaneously.
Product Type:
Polypropylene bottles turn inventory fastest in high-throughput academic settings, while glass vessels cycle slowly through validated pharmaceutical quality control labs.
- Polypropylene:Molded from propylene homopolymer with chemical resistance against acids, bases, and organic solvents. Diagnostic laboratories in Germany's Rhine-Main cluster specify medical-grade resin to satisfy ISO 13485 documentation requirements for sterile processing workflows.
- Polycarbonate:Engineered for optical clarity and impact strength under extreme g-forces exceeding 100,000 × g. Ultracentrifugation protocols at US National Institutes of Health facilities favor this material for density gradient separations where visual monitoring proves essential.
- Glass:Borosilicate construction withstands aggressive pH extremes and solvent exposure that degrade polymers. Legacy pharmaceutical QC departments specify these for compendial testing methods.
- High-Density Polyethylene:Lower-cost alternative for non-critical separations with moderate chemical exposure. Academic teaching laboratories favor this grade for undergraduate training protocols.
Polypropylene dominates installed base. Polycarbonate is where expansion concentrates.
Cork Type:
Closure cost tiers separate premium sterile processing from economy research applications, with gasket systems commanding 3-4× markup over basic plug seals.
- Screw-Cap:Threaded polypropylene or metal closures with silicone gaskets prevent aerosol escape during high-speed rotation. EMA extractables testing requirements are pushing European bioprocessors toward certified low-leach formulations.
- Snap-Cap:One-piece polyethylene closures enable rapid sample access in high-throughput screening workflows. Contract research organizations in Hyderabad specify these for plate-based assay integration.
- Sealing Gasket:Multi-component assemblies with fluoropolymer or EPDM seals for potent compound containment. Oncology manufacturing suites require these for closed-system aseptic processing.
- Plug Seal:Tapered polyethylene stoppers for economy-grade bottles in non-hazardous separations. Price-sensitive academic buyers favor this format for routine cell pelleting.
Screw-cap systems anchor sterile processing demand. Snap-cap configurations are climbing the fastest in CRO procurement.
Volume Capacity:
Batch economics favor larger formats in bioprocessing, while miniaturization pressures concentrate 15 mL demand in genomics workflows.
- 50 mL:Conical-bottom design compatible with standard swinging-bucket and fixed-angle rotors. This format anchors global unit shipments across clinical diagnostics and research settings.
- 250 mL:Cylindrical profiles for industrial-scale batch separations in single-use bioprocessing. Germany's expanding sterile manufacturing capacity is driving specification tightening for this segment.
- 15 mL:Miniature format for PCR cleanup and nucleic acid extraction protocols. Genomics service providers specify these for automated liquid handling integration.
- 100 mL:Intermediate capacity for pilot-scale bioprocess development. Contract manufacturers use these for process validation before scale-up to production volumes.
50 mL commands the broadest installed base. 250 mL formats are gaining share fastest in pharmaceutical manufacturing.
Application:
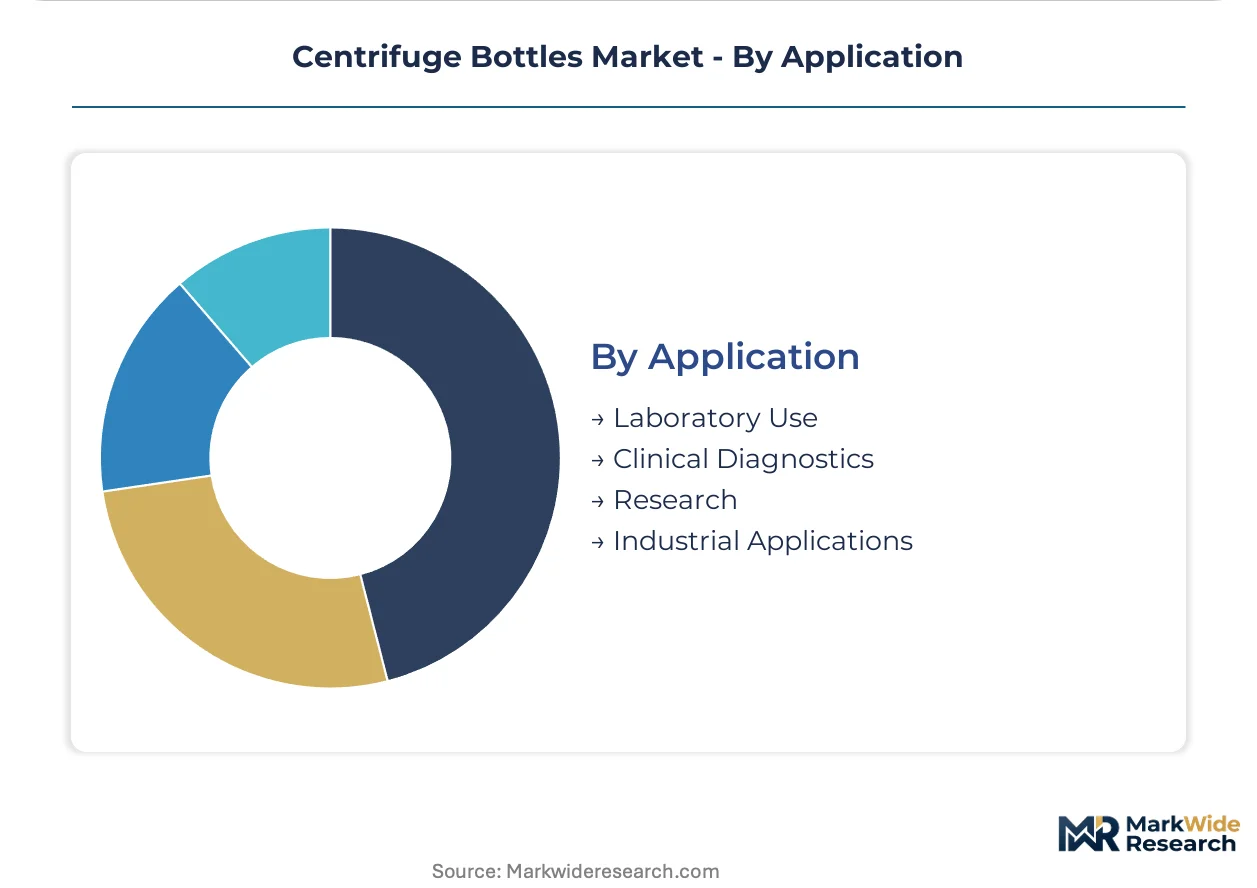
Regulatory burden intensity separates clinical diagnostics from research use, with FDA quality system requirements filtering supplier participation in medical device channels.
- Laboratory Use:General research workflows spanning molecular biology, biochemistry, and cell culture. Academic procurement concentrates in national laboratory networks with consolidated purchasing through group procurement organizations.
- Clinical Diagnostics:Specimen handling under FDA quality system regulations for in vitro diagnostic devices. US reference laboratories require ISO 13485-certified supply chains with documented change control.
- Research:Discovery-stage applications without regulatory submission requirements. Biotechnology startups favor leasing models that bundle premium consumables with instrument access.
- Industrial Applications:Manufacturing-scale separations in food, chemical, and environmental testing. REACH polymer reformulation is compelling material transitions in European industrial settings.
Laboratory use represents the deepest installed base. Clinical diagnostics is where qualification barriers are steepest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in centrifuge bottles concentrate in high-value polycarbonate grades, where Asian petrochemical complexes supply optical-grade resin to European ultracentrifugation users. North American laboratories import certified single-use polypropylene formats for sterile bioprocessing workflows. Domestic molding capacity expansion in India and Southeast Asia is gradually displacing some import dependency for standard research-grade formats.
United States
FDA quality system regulations for in vitro diagnostic devices drive specification tightening among reference laboratories. The National Institutes of Health facilities in Maryland anchor demand for optical-grade polycarbonate bottles in density gradient separations. Leasing models for high-speed centrifuge systems bundle premium consumables, capturing mid-tier contract research organizations.
Germany
EMA extractables and leachables testing requirements elevate analytical documentation burdens for suppliers serving bioprocessors. The Rhine-Main biotechnology cluster concentrates sterile manufacturing capacity expansion among contract manufacturing organizations. REACH polymer reformulation mandates compel bio-based plasticizer alternatives in next-generation polypropylene formulations.
India
CDSCO manufacturing incentives and PLI scheme benefits attract sterile processing investments in Hyderabad and Bengaluru. Import-substituted consumable supply chains develop around domestic molding capacity for standard research formats. Contract research organizations in Hyderabad specify snap-cap configurations for plate-based assay integration.
Japan
PMDA medical device quality system mandates filter supplier participation in diagnostic channels toward documented supply chains. Precision molding talent scarcity constrains capacity expansion for sub-10-micron tolerance tooling. METI industrial policy supports domestic polymer formulation capabilities for temperature-sensitive biological separations.
China
NMPA biologics manufacturing standards tighten material qualification requirements for container closure systems. Yangtze River Delta petrochemical complexes concentrate optical-grade polycarbonate supply for regional ultracentrifugation users. Domestic molders face extended product launch timelines navigating simultaneous FDA 510(k) and EU MDR technical documentation preparation.
Centrifuge Bottles Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in consumables and materials. The centrifuge bottles market structures around three tiers: multinational life science conglomerates with integrated distribution networks, mid-scale polymer specialists with proprietary formulations, and regional molders serving price-sensitive academic segments. Strategic archetypes include instrument-consumable bundlers, precision molding specialists, and certified sterile processing suppliers. Competitive moves concentrate on M&A for analytical chemistry capabilities and capacity expansion in India and Southeast Asia to capture import substitution demand.
Among the named players, Thermo Fisher Scientific exemplifies the integrated platform archetype with recurring revenue from bundled instrument-consumable contracts. Corning Incorporated anchors the materials innovation tier through proprietary polymer formulations. Eppendorf AG occupies a position within the precision-molded segment optimized for temperature-sensitive biological separations. These three represent distinct competitive vectors: distribution integration, materials science, and application-specific engineering.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| Danaher Corporation |
| Eppendorf AG |
| Sartorius AG |
| CELLTREAT Scientific Products |
| Sigma-Aldrich |
| DURAN Group |
| Biomedical Polymers |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European optical-grade polycarbonate resin production drives both supplier allocation discipline and premium pricing posture for ultracentrifugation-grade bottles. German and Swiss molders respond with extended lead times and certificate-of-analysis surcharges, while Asian petrochemical complexes capture margin expansion through long-term offtake contracts with US National Institutes of Health facilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 13485 certification grade and volume scale, with diagnostic laboratories paying 40-60% premiums for documented supply chains. Pricing pressure stems from propylene monomer volatility compressing margins in academic research segments. Contract research organizations exhibit highest price sensitivity, while sterile processing facilities prioritize contamination control over unit cost.
Supply Chain Analysis
Propylene monomer supply concentrates in Saudi Arabia, South Korea, and the US Gulf Coast, with polymerization capacity clustering in Germany, China, and Japan. Molders draw from medical-grade polypropylene, optical-grade polycarbonate, and fluoropolymer gasket materials. Single-source vulnerability in high-clarity resin exposes European ultracentrifugation users to currency fluctuation risk. Distribution runs through integrated life science distributors, direct vendor-managed inventory at multi-site campuses, and third-party logistics providers serving contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where ISO 13485 certification and FDA quality system documentation create switching costs that lock diagnostic laboratories into qualified vendor relationships.
For Market Incumbents: Harden analytical chemistry infrastructure to preempt EMA extractables and leachables documentation requirements. Acquire precision molding capacity in Hyderabad and Bengaluru to capture India's import-substitution demand before domestic molders scale. Vertical integration into polymer formulation insulates margin compression from REACH-driven plasticizer reformulation cycles. For New Entrants and Emerging Players: Establish a beachhead in India's contract research organization segment, where CDSCO manufacturing incentives attract sterile processing investments but qualified consumable supply remains constrained. Target snap-cap configurations for plate-based assay integration, bypassing screw-cap sterile processing barriers dominated by incumbents. Pursue direct vendor-managed inventory contracts with national laboratory networks to disintermediate traditional distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among instrument-consumable bundlers with installed rotor bases that enforce proprietary bottle geometries. Five-to-ten-year viability favors analytical chemistry-capable molders over commodity polymer processors. Watch for FDA 510(k) pathway acceleration signals as inflection indicators for novel polymer formulation qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | REACH compliance in Europe compels in-house bio-based plasticizer development to maintain margin structure. |
| Capacity Expansion in India | CDSCO incentives and PLI scheme benefits in Hyderabad attract sterile processing investments requiring local consumable supply. |
| Analytical Chemistry Acquisition | EMA extractables documentation requirements filter qualified vendors toward those with toxicology assessment capabilities. |
| Closed-System Aseptic Processing Integration | Oncology manufacturing suites demand single-use bottles compatible with automated filling lines for potent compound containment. |
| Leasing Model Penetration | Asset-light programs capture mid-tier contract research organizations previously priced out of advanced ultracentrifugation workflows. |
Methodological Framework
A standing panel of sterile processing engineers, diagnostic laboratory procurement managers, polymer formulation scientists, and contract manufacturing quality directors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EMA submission databases, REACH registration dossiers, and customs trade records for medical-grade polymer imports. Bottom-up modeling of unit shipments by volume capacity and material grade triangulated against top-down expenditure estimates from national laboratory network procurement disclosures.
Scenario bracketing anchored projections across base, upside, and downside cases reflecting propylene monomer price volatility and regulatory timeline uncertainty. Segmentation dimensions spanned material type, closure system, volume capacity, and application intensity across clinical diagnostics, pharmaceutical manufacturing, and academic research settings. CAGRs derived from curve-fitting historical shipment patterns against bioprocessing capacity expansion announcements and sterile processing facility buildout pipelines.
Sensitivities concentrate around REACH polymer reformulation timelines, FDA guidance updates on container closure systems, and polycarbonate resin allocation decisions by Asian petrochemical complexes. Forecasts embed assumptions regarding certification burden persistence and import-substitution momentum in India. Cross-checking against sterile processing facility capital expenditure tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Medical Bags Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
South America Syringe Market