
 Swab Cups Market | 2026-2036
Swab Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Swab Cups Market Analytics
The Swab Cups Market is pivoting between premium bio-compatible formulations and commodity plastic variants as diagnostic laboratories enforce stricter material certification protocols. Oil States Industries leverages its elastomer expertise to anchor supply relationships with oilfield service firms seeking swab cups for wellbore cleaning. Thermo Fisher Scientific sustains R&D intensity across sterile and single-use formats for clinical diagnostics. BD differentiates through vertical control over polymer sourcing for its laboratory consumables portfolio.
Swab cups are cylindrical collection vessels, typically molded from polypropylene or borosilicate glass with nominal volumes of 1–30 milliliters, designed to capture, transport, and preserve biological specimens for downstream analysis. Sterile swab cups command premium positioning due to terminal sterilization validation and endotoxin testing burdens, while non-sterile variants serve environmental and forensic applications where aseptic assurance is less critical. Bio-compatible materials represent the fastest-expanding material category as cell culture and regenerative medicine workflows displace conventional plastics. Multi-sample swab cups concentrate margin pools through integrated barcode tracking and chain-of-custody features that reduce laboratory handling errors.
The FDA enforces 21 CFR Part 820 quality system requirements on domestic swab cup manufacturers, while the EU MDR imposes stricter biocompatibility and clinical evidence standards on devices entering European diagnostic markets. ISO 13485 certification has become a de facto market access threshold for suppliers serving regulated healthcare segments. Laboratories and device buyers must monitor evolving material disclosure rules from ECHA under REACH amendments that target microplastic release from single-use clinical consumables.
Market Dynamics
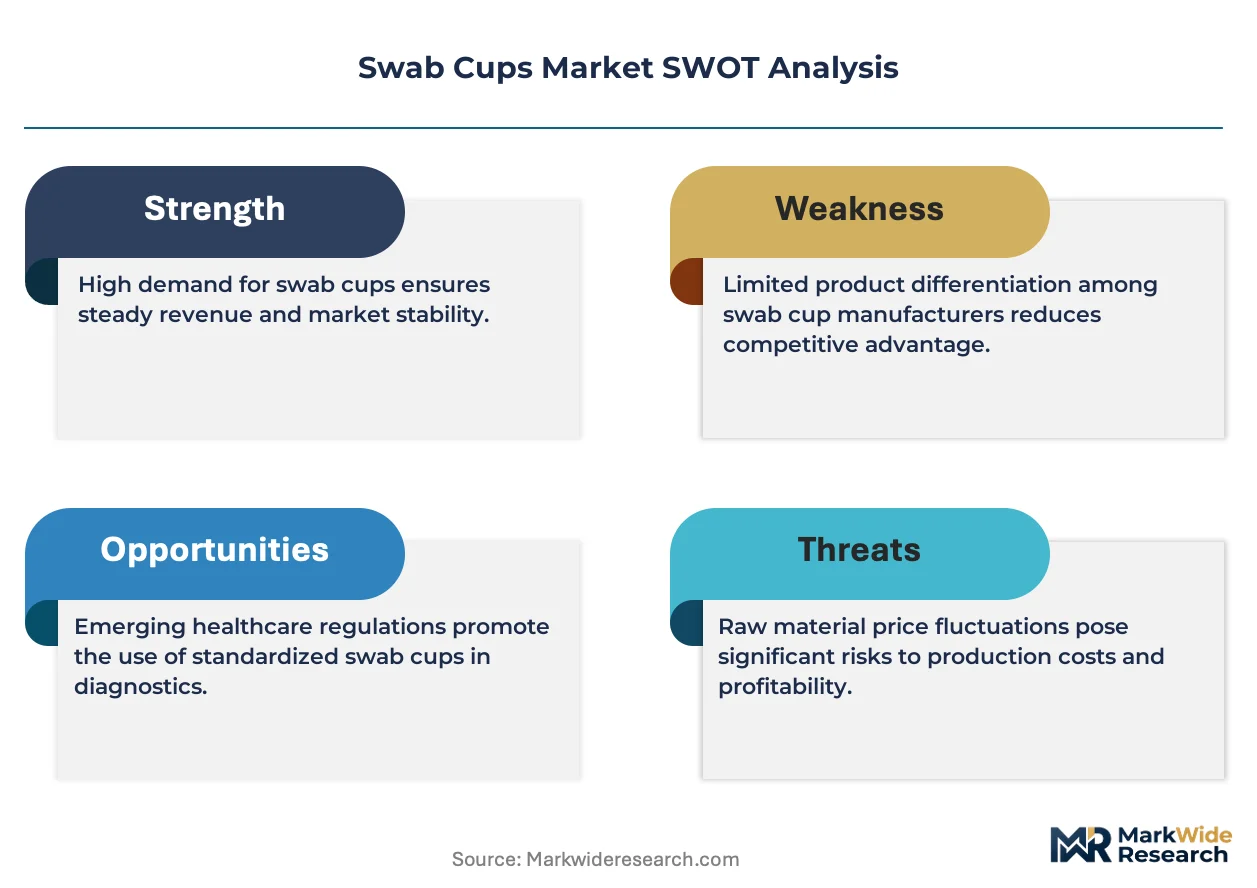
Diagnostic laboratories are forcing material traceability upgrades through automated sample processing workflows, compressing margins for commodity plastic suppliers while rewarding bio-compatible formulations with validated sterilization protocols.
Growth Catalysts
- EU MDR biocompatibility mandates:European diagnostic markets now require elevated clinical evidence standards, accelerating ISO 13485 certification adoption among sterile swab cup suppliers.
- Cell culture workflow expansion:Regenerative medicine applications are absorbing bio-compatible materials at the expense of conventional polypropylene in precision diagnostics clusters.
- Munich-Heidelberg precision corridor:Germany's concentrated diagnostics infrastructure is concentrating demand for multi-sample swab cups with integrated barcode tracking capabilities.
Market Restraints
- Terminal sterilization cost burdens:Endotoxin validation and gamma irradiation protocols add fixed cost layers that commodity producers cannot absorb without margin erosion.
- Polypropylene feedstock volatility:Propylene monomer price swings transmit directly to molded cup production economics, destabilizing contract pricing for high-volume buyers.
- REACH microplastic disclosure amendments:ECHA's evolving material disclosure rules threaten single-use clinical consumables with compliance cost escalations and potential substitution mandates.
Strategic Opportunities
- Environmental and forensic non-sterile segments:Lower certification barriers in these applications create white space for regional molders priced out of clinical markets.
- Chain-of-custody integration:RFID-enabled swab cups with tamper-evident seals command premium positioning in forensic and legal-sample workflows.
- 21 CFR Part 820 alignment services:FDA quality system consulting for domestic manufacturers represents a services-layer opportunity alongside hardware supply.
Industry Challenges
- Polymer sourcing certification timelines:ISO 13485-compliant material traceability requires 18-24 month supplier qualification cycles that constrain rapid scaling.
- Automated handling compatibility:Dimensional tolerances for robotic sample processors vary across laboratory equipment brands, fragmenting design standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swab Cups Market |
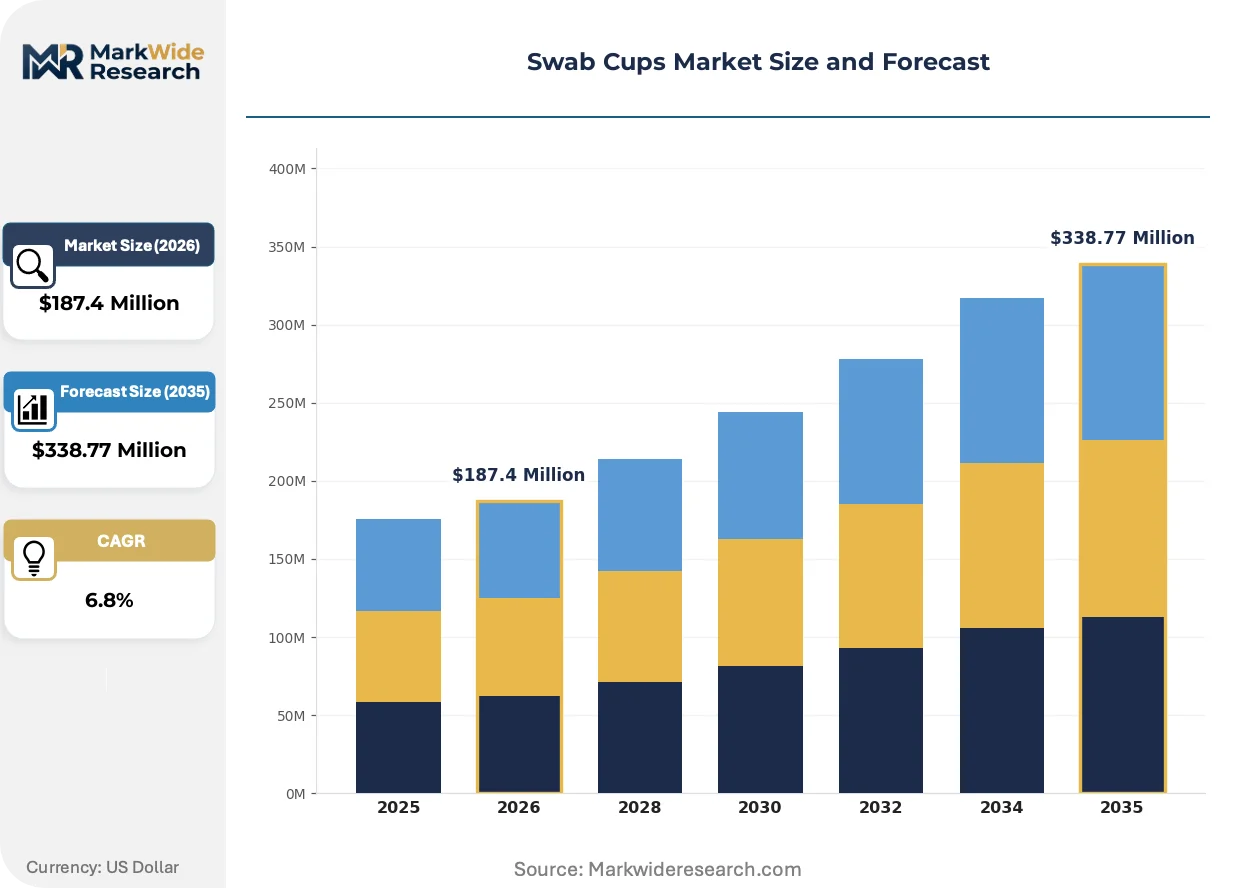
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Swab Cups, Non-Sterile Swab Cups, Multi-Sample Swab Cups, Single-Use Swab Cups Material: Plastic, Glass, Composite, Bio-Compatible Material Application: Clinical Testing, Research, Forensic Analysis, Environmental Testing End User: Hospitals, Laboratories, Research Institutions, Diagnostic Centers |
| Companies Covered | Oil States Industries, Thermo Fisher Scientific, BD, Abbott Laboratories, Merck KGaA, Western Silverline, Petro Rubber Products, Global Elastomeric Products, Brangus Oil Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swab Cups Market Evolving Landscape
Bio-compatible material formulations are absorbing R&D investment as sterile processing requirements tighten, while regulatory disclosure mandates and procurement consolidation reshape competitive positioning across diagnostic supply chains.
Additive manufacturing is absorbing prototype-to-production transitions for custom swab cup geometries in cell culture applications. Niche diagnostic device developers in Switzerland and the Netherlands are adopting printed molds for low-volume validation batches. This distributed production model is absorbing tooling cost barriers that previously favored mass-production incumbents.
REACH amendments targeting microplastic release from single-use clinical consumables are forcing material substitution roadmaps across European supply chains. ECHA's disclosure thresholds now require granular polymer composition documentation for devices entering diagnostic workflows. German and French laboratory procurement departments are responding with supplier scorecards that weight biodegradability credentials alongside sterility assurance.
Consolidated laboratory networks are compressing vendor panels to reduce qualification overhead. Large diagnostic service operators in the United States are unbundling after-sales technical support from consumables contracts, forcing suppliers to compete on pure hardware economics. This procurement rationalization is most visible in North American reference laboratory chains where centralized purchasing now dominates swab cup selection criteria.
Swab Cups Market Segmentation
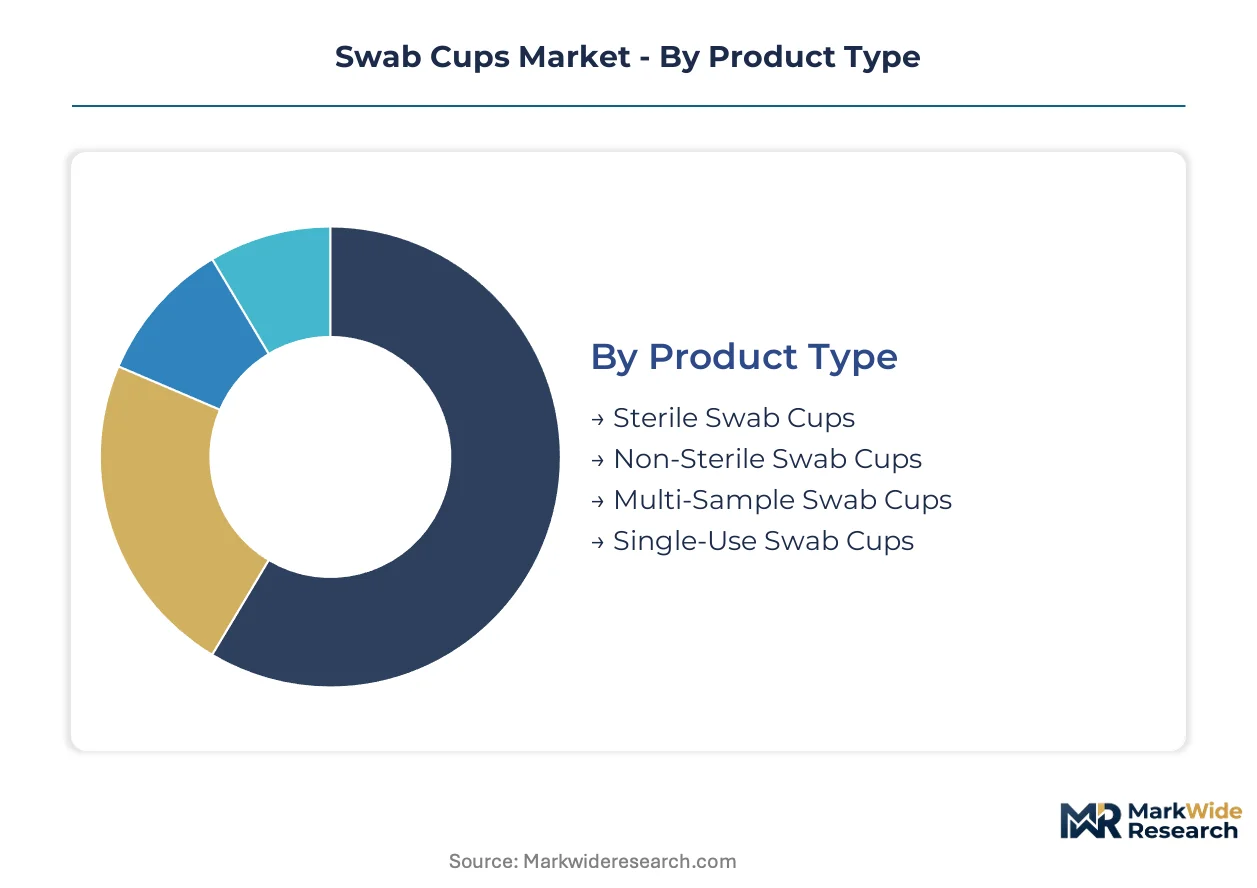
Swab cup procurement splits sharply between regulated clinical workflows demanding validated sterilization and cost-sensitive applications tolerating commodity specifications. Material traceability requirements and automated handling compatibility now determine supplier selection across every segment tier.
Product Type:
The customization-vs-standardization spectrum runs from fully validated sterile formats to unregulated single-use disposables with minimal certification overhead.
- Sterile Swab Cups:Terminal sterilization via gamma irradiation or ethylene oxide with endotoxin validation below 0.25 EU/mL. Demand concentrates in US hospital networks and German precision diagnostics clusters where FDA 21 CFR Part 820 and EU MDR biocompatibility mandates enforce material documentation. Terminal sterilization cost burdens compress margins for suppliers lacking validated production scale.
- Multi-Sample Swab Cups:Integrated barcode tracking and chain-of-custody features for high-throughput laboratory workflows. Munich-Heidelberg corridor laboratories are absorbing these formats fastest as automated sample processing reduces handling errors. RFID-enabled variants with tamper-evident seals command premium positioning in forensic workflows.
- Non-Sterile Swab Cups:Environmental and forensic applications where aseptic assurance is non-critical. Lower certification barriers create white space for regional molders priced out of clinical markets.
- Single-Use Swab Cups:Commodity polypropylene formats for high-volume disposal protocols. REACH microplastic disclosure amendments threaten compliance cost escalations across European supply chains.
Most installed capacity flows through Single-Use Swab Cups. Expansion is steepest in Multi-Sample Swab Cups.
Material:
Cost tier stratification separates premium bio-compatible formulations from commodity plastics vulnerable to feedstock volatility.
- Bio-Compatible Material:Cell culture and regenerative medicine workflows are absorbing these formulations fastest as precision diagnostics displace conventional plastics. ISO 13485-compliant material traceability requires 18-24 month supplier qualification cycles that constrain rapid scaling. German and French laboratory procurement departments now weight biodegradability credentials alongside sterility assurance.
- Plastic:Polypropylene dominates molded cup production economics. Propylene monomer price swings transmit directly to contract pricing instability for high-volume buyers.
- Glass:Borosilicate formats for thermal stability and chemical inertness in specialized research protocols. Niche positioning limits volume scale.
- Composite:Hybrid material structures balancing cost and performance for mid-tier diagnostic applications.
Procurement volume concentrates in Plastic. Steepest expansion trajectory belongs to Bio-Compatible Material.
Application:
Customer type determines specification intensity, with regulated clinical testing imposing the strictest material certification protocols.
- Clinical Testing:Diagnostic laboratories enforce automated sample processing compatibility with dimensional tolerances varying across equipment brands. FDA quality system requirements and EU MDR clinical evidence standards fragment design standards.
- Research:Cell culture workflow expansion drives bio-compatible material absorption. Additive manufacturing is absorbing prototype-to-production transitions for custom geometries in Swiss and Dutch device development.
- Forensic Analysis:Chain-of-custody integration with tamper-evident seals commands premium positioning. Lower regulatory barriers than clinical segments.
- Environmental Testing:Non-sterile formats for field collection protocols. Commodity pricing dominates procurement criteria.
Revenue concentration sits with Clinical Testing. Share gains are fastest in Research.
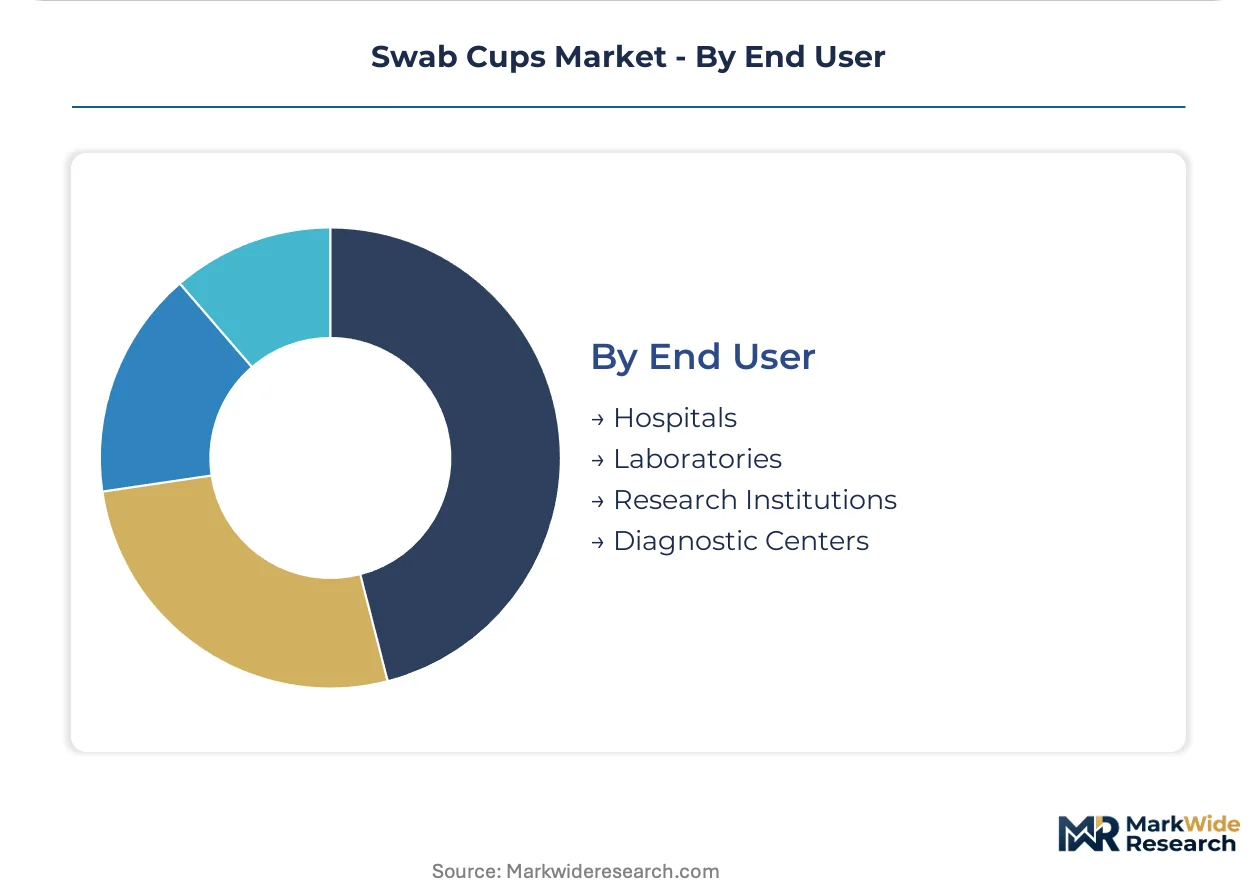
End User:
Supply concentration varies by procurement sophistication, with consolidated laboratory networks compressing vendor panels to reduce qualification overhead.
- Laboratories:Large US reference laboratory chains now dominate swab cup selection through centralized purchasing. Automated handling compatibility requirements fragment design standards across robotic processor brands.
- Hospitals:Sterile processing requirements and endotoxin validation burdens favor suppliers with validated gamma irradiation capacity. FDA 21 CFR Part 820 enforcement tightens material traceability.
- Diagnostic Centers:Mid-tier procurement volume with mixed sterile and non-sterile requirements. Price sensitivity limits premium material adoption.
- Research Institutions:Custom geometries and low-volume validation batches favor additive manufacturing adoption. Distributed production models reduce tooling cost barriers.
Procurement volume flows predominantly through Laboratories. Expansion is climbing the fastest in Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision diagnostics demand around the Munich-Heidelberg corridor, whereas the United States distributes procurement across consolidated reference laboratory chains and hospital networks with divergent sterilization requirements.
United States
Large reference laboratory chains dominate swab cup selection through centralized purchasing, compressing vendor panels to reduce qualification overhead. FDA enforces 21 CFR Part 820 quality system requirements on domestic manufacturers, tightening material traceability protocols. The Greater Boston and San Diego biotech clusters absorb bio-compatible formulations for cell culture workflows.
Germany
Precision diagnostics infrastructure concentrates demand for multi-sample swab cups with integrated barcode tracking capabilities. EU MDR biocompatibility mandates impose stricter clinical evidence standards than predecessor directives. The Munich-Heidelberg corridor laboratories are scaling automated sample processing workflows fastest.
China
Domestic diagnostic device manufacturers are absorbing ISO 13485 certification requirements to serve export markets. NMPA medical device regulations align with international standards for sterile consumables. The Yangtze River Delta manufacturing base supplies molded polypropylene formats for regional diagnostic centers.
United Kingdom
NHS procurement consolidation favors suppliers with validated gamma irradiation capacity and endotoxin testing protocols. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR standards for biocompatibility. The Oxford-Cambridge biotech corridor drives custom geometry demand for research applications.
India
Domestic diagnostic laboratories are upgrading from commodity plastics to certified sterile formats as private healthcare chains expand. CDSCO medical device rules impose quality system requirements on domestic manufacturers. The Maharashtra-Gujarat pharmaceutical belt concentrates molders serving both clinical and research segments.
Swab Cups Market Competitive Landscape
Top-tier vendors anchor sterile diagnostics supply, while regional molders occupy non-sterile environmental and forensic niches. The vendor base stratifies across three tiers: multinational life sciences conglomerates with validated sterilization infrastructure, mid-cap specialists with ISO 13485 certification, and commodity producers serving price-sensitive segments. Two dominant competitive moves are reshaping positioning: backward integration into polymer sourcing to control material traceability, and additive manufacturing adoption for low-volume custom geometries.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and BD exemplify the premium-tier archetype with captive sterilization validation and endotoxin testing capabilities. Oil States Industries occupies a distinct position, representing the industrial-to-medical crossover archetype that leverages elastomer expertise from oilfield applications.
| Leading Market Players |
|---|
| Oil States Industries |
| Thermo Fisher Scientific |
| BD |
| Abbott Laboratories |
| Merck KGaA |
| Western Silverline |
| Petro Rubber Products |
| Global Elastomeric Products |
| Brangus Oil Tools |
| Others |
Value Network & Pricing Analysis
Backward integration into polymer sourcing anchors supply position and pricing power for sterile swab cup manufacturers serving FDA-regulated diagnostic markets, while commodity producers remain exposed to propylene monomer volatility and margin compression.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing base are reshaping price floors for commodity polypropylene formats, intensifying cost compression among non-sterile suppliers. Three-tier pricing structure across sterile-certified, ISO 13485-compliant, and unregulated economy levels separates suppliers by validation burden and material traceability depth. Pricing pressure stems from REACH microplastic disclosure amendments elevating compliance costs across European supply chains. Environmental testing laboratories exhibit highest price sensitivity, while Munich-Heidelberg precision diagnostics clusters absorb premium positioning for multi-sample formats with integrated barcode tracking.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from consolidated US reference laboratory chains, while distributor networks serve fragmented diagnostic centers and research institutions. Supply concentrates in China, Germany, and the United States for molded polypropylene and borosilicate glass formats. Raw material flows draw from propylene monomer feedstocks, gamma irradiation sterilization capacity, and bio-compatible polymer formulations. Single-source vulnerability characterizes gamma irradiation infrastructure, where qualified terminal sterilization providers remain limited across European and North American markets. Distribution runs through GPO contracts for hospital networks and direct procurement for automated laboratory workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Swab Cups Market functions as a stable compounder, with diagnostic laboratory automation sustaining replacement demand for validated sterile formats across regulated clinical workflows.
For Market Incumbents: Lock in supply relationships with oilfield service firms seeking elastomer-based wellbore cleaning applications, and deepen captive sterilization validation capacity to defend against mid-cap ISO 13485-certified entrants eroding clinical market share. Prioritize backward integration into bio-compatible polymer sourcing to control material traceability timelines and pricing power. For New Entrants and Emerging Players: E-commerce distribution channels targeting forensic analysis laboratories offer the most penetrable entry point, given lower certification barriers and fragmented procurement compared to consolidated hospital networks. White space exists in RFID-enabled chain-of-custody formats for legal-sample workflows and additive-manufactured custom geometries for Swiss and Dutch cell culture device developers. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification timelines constrain rapid scaling and automated handling compatibility requirements fragment design standards across robotic processor brands. Mid-cap specialists with validated sterilization infrastructure and established supplier qualification cycles represent the optimal acquisition archetype. Monitor ECHA REACH amendment enforcement intensity as an inflection indicator for material substitution mandates and compliance cost escalations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates market access across EU MDR-regulated diagnostic corridors in Germany and France. |
| Backward Integration into Polymer Sourcing | Reduces supplier qualification cycles and secures bio-compatible material traceability for cell culture workflows. |
| Additive Manufacturing Adoption | Enables distributed production of custom geometries for Swiss and Dutch niche device developers. |
| RFID-Enabled Chain-of-Custody Integration | Commands premium positioning in forensic and legal-sample workflows with tamper-evident seals. |
| Gamma Irradiation Capacity Expansion | Addresses single-source vulnerability in terminal sterilization infrastructure across North American markets. |
Research Methodology
Multiple input streams — laboratory procurement manager interviews, biomedical engineer consultations, GPO contracts managers, and regulatory affairs leads at sterile consumables manufacturers — were reconciled against secondary validation from FDA 510(k) filings, EMA medical device registrations, hospital procurement databases, and customs trade data for polypropylene and borosilicate glass imports. Bottom-up demand modeling across product type, material, application, and end user segments was cross-checked against top-down macroeconomic indicators and diagnostic laboratory capital expenditure disclosures.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning sterile versus non-sterile formats, bio-compatible versus commodity materials, and automated handling compatibility tiers. CAGRs were derived from fitted growth curves applied to installed base replacement cycles and precision diagnostics infrastructure expansion trajectories. Industry-specific forecast inputs incorporated EU MDR biocompatibility mandate compliance timelines and REACH microplastic disclosure amendment implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for additive manufacturing in low-volume custom geometries would alter the outlook for distributed production versus mass-incumbent dominance. Forecasts reflect base-case assumptions regarding regulatory enforcement intensity, raw material price stability, and laboratory automation penetration rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Medical Foam Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Syringes and Cannulas Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Suture Wire Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Disposable Medical Gloves Market