
 Global Medical Waste Containers Market | 2026-2036
Global Medical Waste Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Waste Containers Market Foresight
The gap between premium safety-engineered containers and commodity-grade disposal bins is broadening as infection control budgets diverge across healthcare systems. BD leverages its integrated manufacturing footprint to sustain dominant positions in sharps containment across North American hospital networks. Thermo Fisher Scientific Inc. competes through specialized laboratory waste solutions that anchor its presence in biopharma research corridors. Cardinal Health differentiates via extensive distribution control, extending same-day replenishment services that occupy critical supply chain nodes for mid-sized clinics.
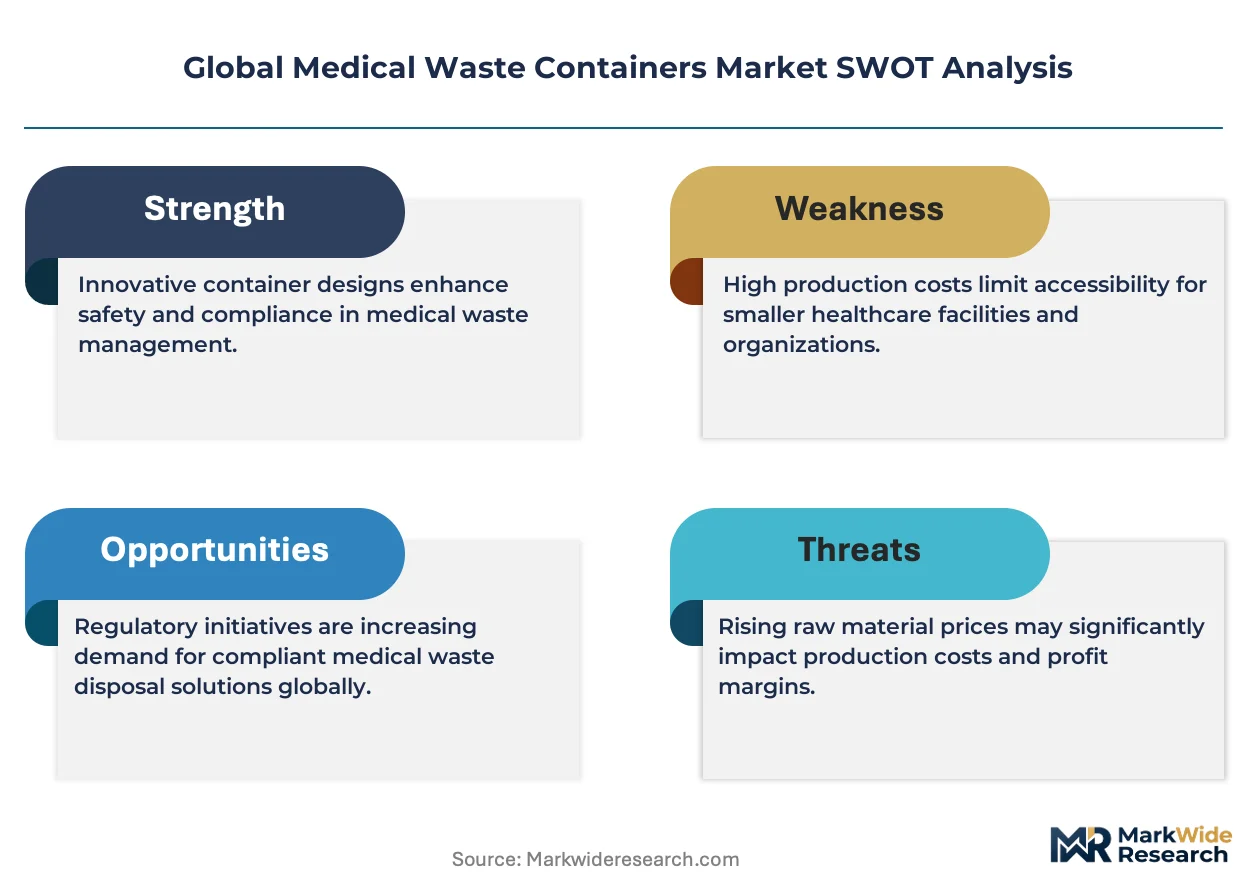
Medical waste containers are rigid receptacles engineered to specifications including puncture resistance, leak-proof seams, and UN-certified markings for regulated substance transport, serving the primary purpose of preventing occupational exposure and environmental contamination during the collection, storage, and transit of infectious, sharp, or pharmaceutical refuse. Sharps containers command the largest volume share within product type segmentation as needle-intensive therapies expand, while pharmaceutical waste containers represent the fastest-growing category driven by DEA disposal mandates for controlled substances. Plastic formulations, particularly polypropylene and high-density polyethylene, dominate material segmentation due to chemical resistance and autoclave compatibility, though metal alternatives persist in cytotoxic applications requiring extreme thermal stability.
The FDA governs container performance through 510(k) premarket notification requirements, while OSHA's Bloodborne Pathogens Standard mandates engineering controls including approved sharps disposal units in clinical workplaces. The EPA's Resource Conservation and Recovery Act provisions classify certain pharmaceutical wastes as hazardous, forcing healthcare facilities to source dual-compliant containers that satisfy both DOT transport rules and state-level environmental statutes. Stakeholders must monitor evolving state legislation on single-use plastic bans that could force material transitions in container manufacturing without equivalent regulatory clarity on acceptable substitutes.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around suppliers capable of delivering UN-certified, color-coded containment systems that satisfy simultaneous FDA, DOT, and state environmental mandates, compressing the supplier base toward integrated manufacturers with full regulatory documentation capabilities.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:US clinical workplaces must deploy engineering controls including approved sharps disposal units, mandating replacement cycles for legacy containers and sustaining baseline demand for puncture-resistant receptacles.
- Needle-intensive therapies:Biologics administration and self-injection regimens are expanding sharps waste volumes in outpatient settings, driving consumption of portable containment systems designed for home healthcare environments.
- DEA disposal mandates:Controlled substance regulations require dual-compliant pharmaceutical waste containers that satisfy both transport and environmental statutes, creating specialized demand for tamper-evident, permanently lockable units.
Market Restraints
- Polypropylene feedstock volatility:Resin price swings compress margins for molded container producers unable to pass through material cost fluctuations to contracted hospital purchasing groups.
- Single-supplier concentration:North American acute care networks rely heavily on distributors with captive container manufacturing, limiting competitive entry for specialized or regional producers lacking established replenishment infrastructure.
- Autoclave temperature thresholds:Standard plastic formulations degrade under repeated sterilization cycles, restricting reuse applications and forcing higher replacement frequency than metal alternatives in cytotoxic waste streams.
Strategic Opportunities
- Indian hospital expansion:Private healthcare infrastructure buildout under government insurance schemes is creating first-time demand for standardized containment systems in tier-2 and tier-3 cities lacking legacy waste management protocols.
- RFID-enabled tracking:Integration of wireless identification with container logistics is enabling real-time fill-level monitoring and route optimization for waste haulers serving distributed clinic networks.
- E-commerce direct channels:Small outpatient practices and dental clinics are bypassing traditional distribution to source certified containers through specialized medical supply platforms, opening access for niche manufacturers with digital fulfillment capabilities.
Industry Challenges
- 510(k) clearance timelines:FDA premarket notification requirements for novel needle-stick prevention mechanisms extend product development cycles, delaying revenue recognition for redesigned wall-mounted and portable units.
- State plastic ban fragmentation:Inconsistent legislation across US jurisdictions on single-use plastic restrictions forces manufacturers to maintain multiple material formulations without regulatory clarity on acceptable polymer substitutes.
- Waste stream integration:Healthcare facilities struggle to harmonize container color-coding and labeling protocols across infectious, pharmaceutical, and chemical waste categories, complicating staff training and compliance auditing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Waste Containers Market |
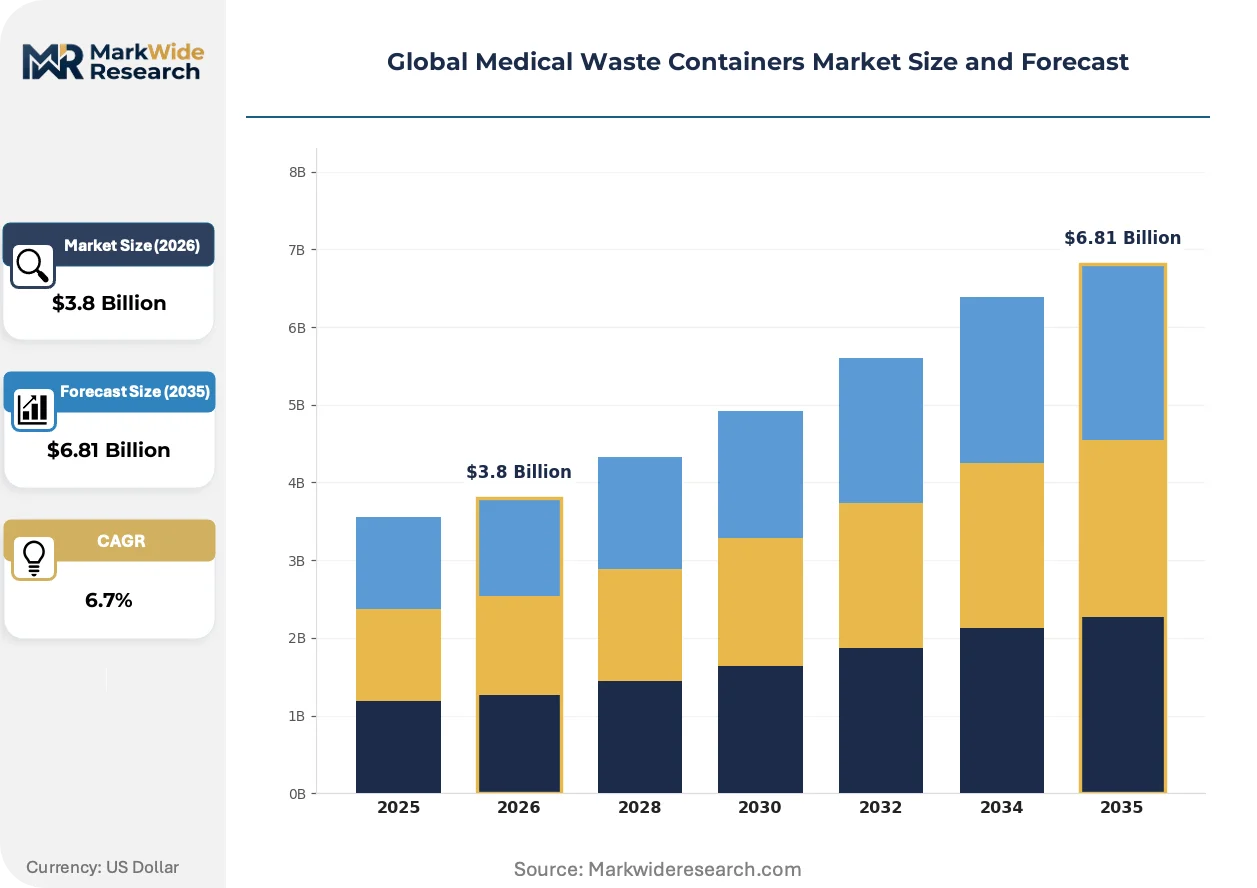
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sharps Containers, Biohazard Containers, Pharmaceutical Waste Containers, General Medical Waste Bins, Cytotoxic Waste Containers Application: Hospitals, Laboratories, Dental Clinics, Veterinary Clinics, Diagnostic Centers Material: Plastic, Metal, Polypropylene, Polyethylene, High-Density Polyethylene End User: Healthcare Facilities, Research Institutes, Waste Management Companies, Municipal Health Services |
| Companies Covered | BD, Bemis Manufacturing Company, Thermo Fisher Scientific Inc., Cardinal Health, Daniels Sharpsmart Inc., Bondtech Corporation, BWAY Corporation, EnviroTain, LLC, Sharps Compliance, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Waste Containers Market Shifts & Advancements
Container engineering is pivoting from passive containment toward active safety systems that intervene before occupational exposure occurs, with material science and digital connectivity converging to reshape product architecture and procurement criteria.
Modular sharps container design is modularizing the traditional single-use receptacle into separable base, lid, and liner components that hospitals can autoclave, replace, or recycle independently. Large integrated delivery networks in the United States are piloting these systems to reduce plastic waste volumes and simplify compliance reporting. The approach is modularizing supplier relationships, as facilities now source lids and liners from different vendors than base units.
REACH substance restrictions are compelling European manufacturers to reformulate colorants and stabilizers in polypropylene containers, eliminating phthalates and heavy metal pigments from formulations destined for EU healthcare markets. The industrial consequence is accelerated R&D spending on bio-based polymer alternatives that maintain puncture resistance without restricted additives. German hospital procurement cooperatives are now requiring full material disclosure documentation, shifting competitive advantage toward producers with transparent supply chains.
Consolidated purchasing by US hospital networks is compressing vendor lists and extending contract durations, with materials managers demanding volume rebates and same-day replenishment guarantees that only distributors with regional warehouse footprints can satisfy. This behavior is displacing independent medical supply dealers who lack inventory positioning near acute care clusters. The shift is most visible in the southeastern United States, where health system mergers have reduced the number of approved sharps container suppliers by half across multi-state networks.
Global Medical Waste Containers Market Segmentation
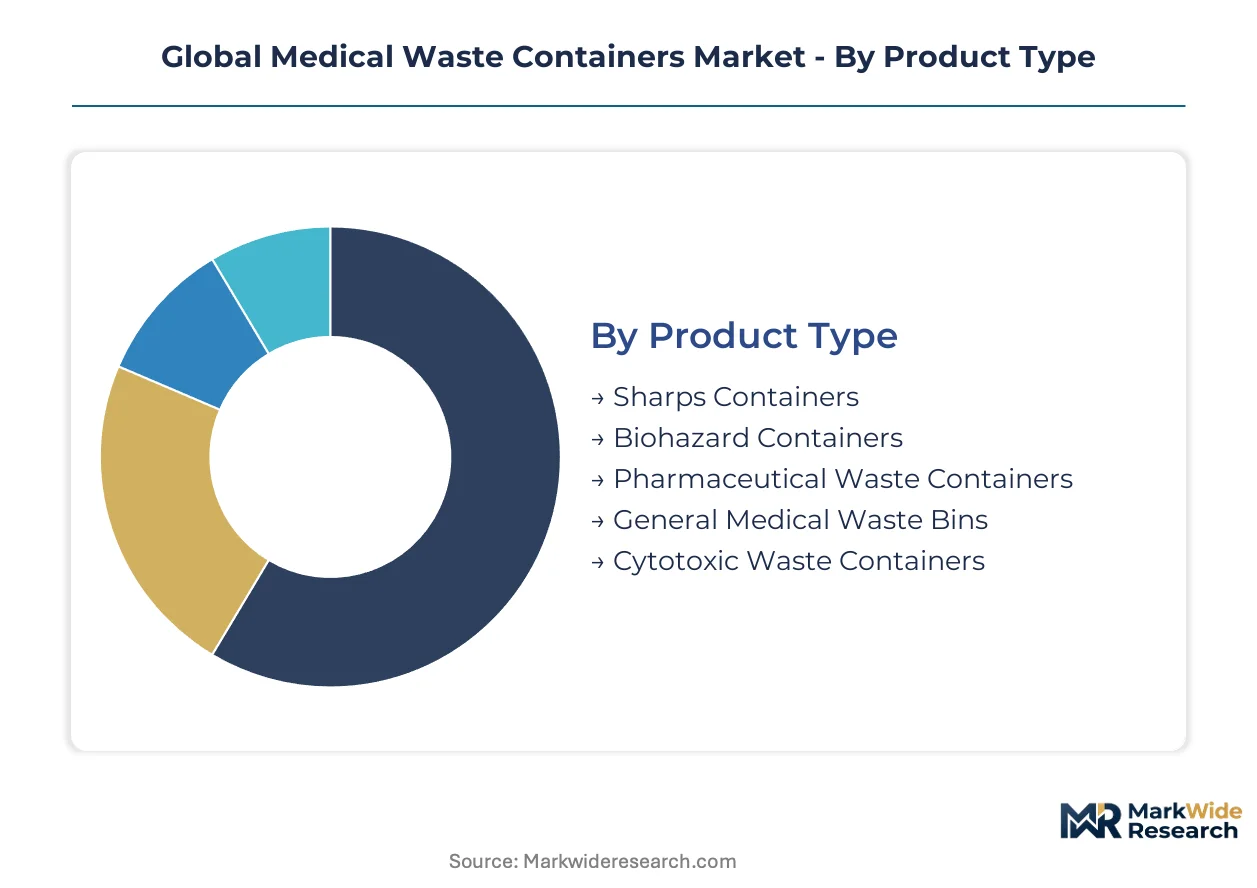
Segmentation in medical waste containers reflects divergent regulatory compliance burdens and sterilization requirements across waste streams. Procurement patterns vary sharply between acute care networks managing high-volume sharps disposal and research facilities handling cytotoxic compounds. Understanding these divisions clarifies where formulation investments and certification efforts concentrate.
Product Type:
Supply concentration clusters around sharps and biohazard categories where FDA 510(k) clearance creates manufacturing barriers that exclude commodity producers.
- Sharps Containers:Puncture-resistant receptacles engineered with needle-stick prevention mechanisms and UN-certified markings for regulated transport. Demand concentrates in United States hospital networks replacing legacy units under tightened OSHA Bloodborne Pathogens enforcement, with outpatient surgery centers driving portable unit adoption.
- Pharmaceutical Waste Containers:Dual-compliant systems satisfying DEA disposal mandates for controlled substances with tamper-evident permanent locking. Specialized demand from United States acute care facilities is climbing fastest as regulators tighten chain-of-custody documentation for narcotic disposal.
- Biohazard Containers:Leak-proof rigid receptacles with color-coded labeling for infectious waste segregation.
- General Medical Waste Bins:Standard containment for non-sharp, non-pharmaceutical refuse streams.
- Cytotoxic Waste Containers:Metal or high-temperature polymer formulations for antineoplastic drug disposal.
Today's leader: Sharps Containers. Tomorrow's challenger: Pharmaceutical Waste Containers.
Application:
Cost tier differentiation separates premium-engineered hospital systems from economy-grade clinic solutions with reduced certification documentation.
- Hospitals:Integrated delivery networks procure UN-certified, color-coded systems with same-day replenishment guarantees. United States acute care facilities dominate volume, with procurement departments consolidating vendor relationships around full-regulatory-documentation suppliers.
- Laboratories:Specialized containment for biopharma research corridors requiring chemical resistance and autoclave compatibility. Thermo Fisher Scientific anchors presence here through technical specification leadership.
- Dental Clinics:Smaller-scale procurement increasingly bypassing traditional distribution for e-commerce direct channels.
- Veterinary Clinics:Emerging demand segment with distinct waste stream profiles from companion animal practices.
- Diagnostic Centers:High-throughput phlebotomy and imaging facilities generating concentrated sharps volumes.
Volume concentrates in Hospitals. Margin expansion targets Laboratories.
Material:
Application requirements dictate material selection, with chemical resistance and thermal stability driving formulation decisions across regulated waste categories.
- Polypropylene:Dominant formulation offering chemical resistance and autoclave compatibility for reusable base units in modular systems. German hospital procurement cooperatives now require full material disclosure documentation, shifting advantage toward transparent supply chains.
- High-Density Polyethylene:Lower-cost alternative for single-use liners and general medical waste applications where thermal cycling demands are reduced.
- Plastic:Broad category encompassing multiple polymer formulations for standard containment.
- Metal:Persisting in cytotoxic applications requiring extreme thermal stability beyond plastic degradation thresholds.
- Polyethylene:Intermediate-grade resin for non-critical waste streams with moderate chemical exposure.
Polypropylene commands specification leadership. High-Density Polyethylene captures cost-sensitive substitution.
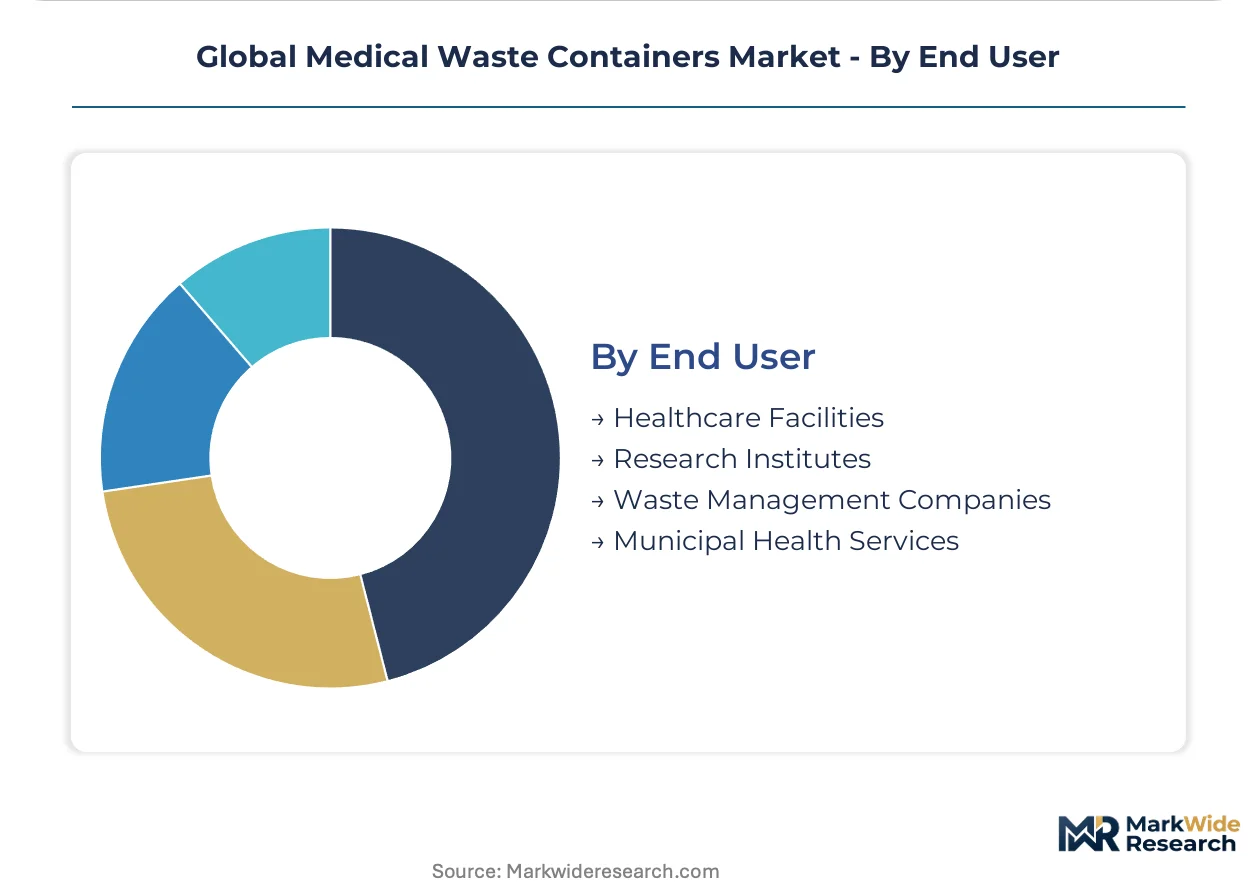
End User:
Customer type determines procurement complexity, from integrated healthcare networks with consolidated purchasing to fragmented municipal services with decentralized decision-making.
- Healthcare Facilities:Primary demand source encompassing hospitals, clinics, and long-term care with synchronized regulatory compliance requirements across FDA, DOT, and state environmental mandates.
- Waste Management Companies:Intermediate handlers requiring transport-certified containers with route optimization compatibility for distributed collection networks.
- Research Institutes:Specialized biopharma corridors with distinct containment protocols for laboratory-generated waste.
- Municipal Health Services:Public sector procurement with extended tender cycles and price-sensitive specifications.
Healthcare Facilities anchor demand scale. Waste Management Companies are concentrating logistics influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical waste management specialists concentrate procurement authority in hospital systems across five national markets where regulatory enforcement diverges sharply.
United States
Acute care networks in Texas and Florida are replacing legacy containers with UN-certified systems as OSHA intensifies Bloodborne Pathogens Standard inspections. The FDA's 510(k) clearance requirements for needle-stick prevention features are extending product development timelines for manufacturers serving outpatient surgery centers in the Southeast. Hospital procurement departments in Atlanta and Dallas are consolidating vendor relationships around distributors with same-day replenishment guarantees.
Germany
REACH substance restrictions are compelling manufacturers to eliminate phthalates and heavy metal pigments from polypropylene formulations destined for Bavarian hospital cooperatives. The country's national pharmaceutical regulator is requiring full material disclosure documentation for containment systems entering Baden-Württemberg research corridors. Industrial clusters around Stuttgart and Munich are piloting modular container designs with separable base and liner components.
India
Private healthcare infrastructure buildout under government insurance schemes is creating first-time demand for standardized containment systems in tier-2 cities across Maharashtra and Karnataka. The Central Drugs Standard Control Organization is tightening import documentation for puncture-resistant receptacles entering Delhi-NCR hospital networks. Manufacturing activity is concentrating in Gujarat and Tamil Nadu as domestic producers scale polypropylene molding capacity.
Japan
Metropolitan hospital systems in Tokyo and Osaka are adopting RFID-enabled tracking for container logistics under revised infectious waste handling guidelines. The Pharmaceuticals and Medical Devices Agency is evaluating active safety systems with intervention mechanisms before occupational exposure occurs. Biopharma research facilities in Kansai are driving specialized demand for autoclave-compatible containment with chemical resistance specifications.
Brazil
São Paulo state health authorities are mandating color-coded segregation protocols for infectious and pharmaceutical waste streams in public hospital networks. The national health surveillance agency is aligning container certification requirements with WHO transport guidelines for regulated substances. Private clinic chains in Rio de Janeiro and Minas Gerais are sourcing dual-compliant systems through specialized medical supply distributors.
Global Medical Waste Containers Market Competitive Landscape
Top-tier vendors anchor integrated manufacturing and distribution platforms, while mid-scale specialists occupy niche certification segments. Supply concentration favors producers with captive resin molding and regional warehouse positioning near acute care clusters. Three archetypes dominate: diversified healthcare conglomerates with full regulatory documentation capabilities, laboratory-focused technical specialists, and distribution-integrated logistics players. Competitive moves center on vendor list consolidation through extended contract durations and same-day replenishment infrastructure expansion.
Within the diversified healthcare tier, BD and Cardinal Health exemplify integrated manufacturing and distribution control. Thermo Fisher Scientific Inc. represents the laboratory-specialist archetype with technical specification leadership in biopharma research corridors. Among mid-scale focused operators, Daniels Sharpsmart Inc. occupies a position emphasizing safety-engineered design differentiation.
| Leading Market Players |
|---|
| BD |
| Bemis Manufacturing Company |
| Thermo Fisher Scientific Inc. |
| Cardinal Health |
| Daniels Sharpsmart Inc. |
| Bondtech Corporation |
| BWAY Corporation |
| EnviroTain, LLC |
| Sharps Compliance, Inc. |
| Others |
Supply & Pricing Matrix
Polypropylene resin indices cascade through medical waste container manufacturing into three distinct pricing tiers that separate UN-certified safety-engineered systems from commodity-grade alternatives. Hospital purchasing groups exploit this feedstock transparency to negotiate volume rebates that compress margins for molded producers lacking backward integration into polymer supply.
Pricing Analysis
Container procurement splits between bundled service contracts with waste haulers and unbundled product-only transactions through distributors. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) certification status and puncture-resistance ratings. Pricing pressure stems from consolidated hospital networks extracting same-day replenishment guarantees. Small outpatient clinics exhibit highest price sensitivity, while integrated delivery networks prioritize compliance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Ohio, and California anchor hub-and-spoke replenishment networks serving acute care clusters. Manufacturing concentrates in the United States, Germany, and India with polypropylene resin drawn from Gulf Coast petrochemical complexes and European polymer producers. Single-source vulnerability runs through concentrated resin suppliers and captive molding operations. Distribution runs through GPO-affiliated distributors with regional warehouse positioning near hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical waste containers rests on modular system architectures that reduce per-unit resin content while commanding premium positioning through RFID-enabled tracking capabilities.
For Market Incumbents: Anchor market position through captive polypropylene compounding capabilities that insulate against resin volatility while extending contract durations with integrated delivery networks. Consolidate vendor lists by acquiring regional distributors with established replenishment infrastructure. Defend against specialized safety-engineered entrants by accelerating FDA 510(k) submissions for active needle-stick prevention mechanisms. For New Entrants and Emerging Players: Specialized medical supply platforms offer direct channel access to dental clinics and small outpatient practices bypassing traditional GPO distribution. Target tier-2 Indian cities where private hospital buildout creates first-time demand for standardized containment lacking legacy supplier relationships. Pursue modular component supply agreements with large US health systems seeking to separate lid, liner, and base unit procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale manufacturers possessing transparent material disclosure documentation and EU REACH compliance capabilities. Five-to-ten year viability favors producers with bio-based polymer R&D pipelines and digital logistics integration. Monitor state-level single-use plastic ban legislation as inflection indicator for material transition investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for needle-stick prevention features in sharps containers. |
| Backward Integration into Polypropylene Compounding | Captures margin compression from resin volatility while ensuring supply security. |
| RFID-Enabled Tracking Integration | Enables real-time fill-level monitoring for waste haulers serving distributed clinic networks. |
| Hospital System Partnership | Secures same-day replenishment contracts with integrated delivery networks consolidating vendor relationships. |
| Modular Component Development | Reduces plastic waste volumes while fragmenting supplier relationships across separable base, lid, and liner units. |
Research Methodology
Direct dialogue with hospital procurement managers, biomedical engineers, GPO contracts specialists, and waste management logistics coordinators grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) filings, EPA RCRA hazardous waste documentation, hospital procurement databases, and OSHA enforcement records. Bottom-up and top-down triangulation cross-checked volume estimates against resin consumption patterns and distributor shipment data.
Bottom-up modeling aggregated facility-level container procurement across acute care networks, outpatient surgery centers, and research laboratories. Segmentation dimensions included product type, application setting, material formulation, and end-user category. CAGRs were derived from regression analysis of historical procurement patterns against regulatory enforcement timelines and hospital construction activity. Industry-specific inputs incorporated DEA disposal mandate expansion rates and state plastic ban legislative trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polypropylene feedstock volatility, FDA clearance timeline extensions, and fragmented state environmental legislation. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hospital consolidation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Global Swab Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Arterial Blood Collection Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
IV Infusion Gravity Bags Market