
 Disposable Lead Wires Market | 2026-2036
Disposable Lead Wires Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Lead Wires Market Intelligence
Hospital infection control protocols is repositioning procurement priorities toward single-use patient monitoring accessories. 3M leverages its materials science portfolio to dominate adhesive electrode wire assemblies. BD anchors North American supply through its hospital distribution network. Cardinal Health competes on channel density, sustaining shelf presence across integrated delivery networks.
Disposable lead wires are single-patient-use conductive cables that transmit bioelectric signals from skin surface electrodes to monitoring equipment, typically manufactured from PVC or TPE insulated copper conductors with snap or pinch connectors. They serve primarily to eliminate cross-contamination between patients in clinical monitoring environments. ECG lead wires command the largest volume share within product type segmentation, though telemetry leads are expanding fastest as ambulatory monitoring migrates to wireless platforms. Hospitals absorb the majority of end-user demand, while homecare settings represent the emerging margin pool as remote patient monitoring programs scale.
FDA enforces biocompatibility and electrical safety standards under 21 CFR requirements for patient-connected devices, while ISO 10993 governs cytotoxicity and sensitization testing for materials in prolonged skin contact. The EU MDR imposes stricter clinical evidence requirements on disposable accessories classified as Class I medical devices, reshaping market access timelines for non-European manufacturers. Stakeholders must monitor evolving reimbursement codes for remote monitoring to anticipate whether homecare demand accelerates faster than hospital replacement cycles.
Market Dynamics
Hospital infection control departments are systematically retiring reusable lead wire inventory in favor of single-use alternatives, driven by FDA scrutiny of reprocessing validation and liability exposure from nosocomial transmission events. This structural shift is compressing replacement cycles and elevating biocompatibility testing to a procurement gate.
Growth Catalysts
- FDA reprocessing guidance:The agency's tightened validation requirements for reusable accessories are forcing hospitals to quantify cross-contamination risk, accelerating disposable conversion in acute care settings.
- TPE material substitution:Thermoplastic elastomer formulations are displacing PVC in lead wire insulation, satisfying DEHP-free mandates while maintaining signal fidelity during extended monitoring.
- Ambulatory telemetry expansion:Wireless patient monitoring platforms are proliferating across cardiology practices, creating pull-through demand for disposable lead sets optimized for mobile form factors.
Market Restraints
- Copper conductor cost volatility:Spot price fluctuations in refined copper directly compress margins on standard PVC-insulated lead wire SKUs, pressuring mid-tier manufacturers without forward contracts.
- Supply concentration in Malaysian molding:Overreliance on Penang-based contract manufacturers for connector overmolding creates single-source vulnerability during regional logistics disruptions.
- Reusable system sunk costs:Hospitals with capital investment in automated lead wire reprocessing equipment face write-down friction that delays full disposable conversion.
Strategic Opportunities
- Remote patient monitoring reimbursement:CMS expansion of CPT codes for home-based cardiac telemetry is opening margin pools outside traditional hospital procurement channels.
- EU MDR Class I accessory pathway:The streamlined conformity assessment for disposable patient-connected devices is reducing market access timelines for non-European manufacturers willing to establish authorized representatives.
- RFID-enabled traceability:Embedding wireless identification chips in lead wire connectors is enabling automated expiration tracking and recall management, differentiating premium product lines.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies are experiencing extended turnaround at accredited laboratories, delaying product launches.
- Legacy monitor interoperability:Ensuring snap-connector compatibility with installed bases of GE, Philips, and Nihon Kohden monitoring equipment requires maintaining multiple tooling configurations.
- Cleanroom molding capacity constraints:Medical-grade TPE overmolding demands ISO 14644 Class 8 environments, and qualified floor space is tightening across Southeast Asian manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Lead Wires Market |
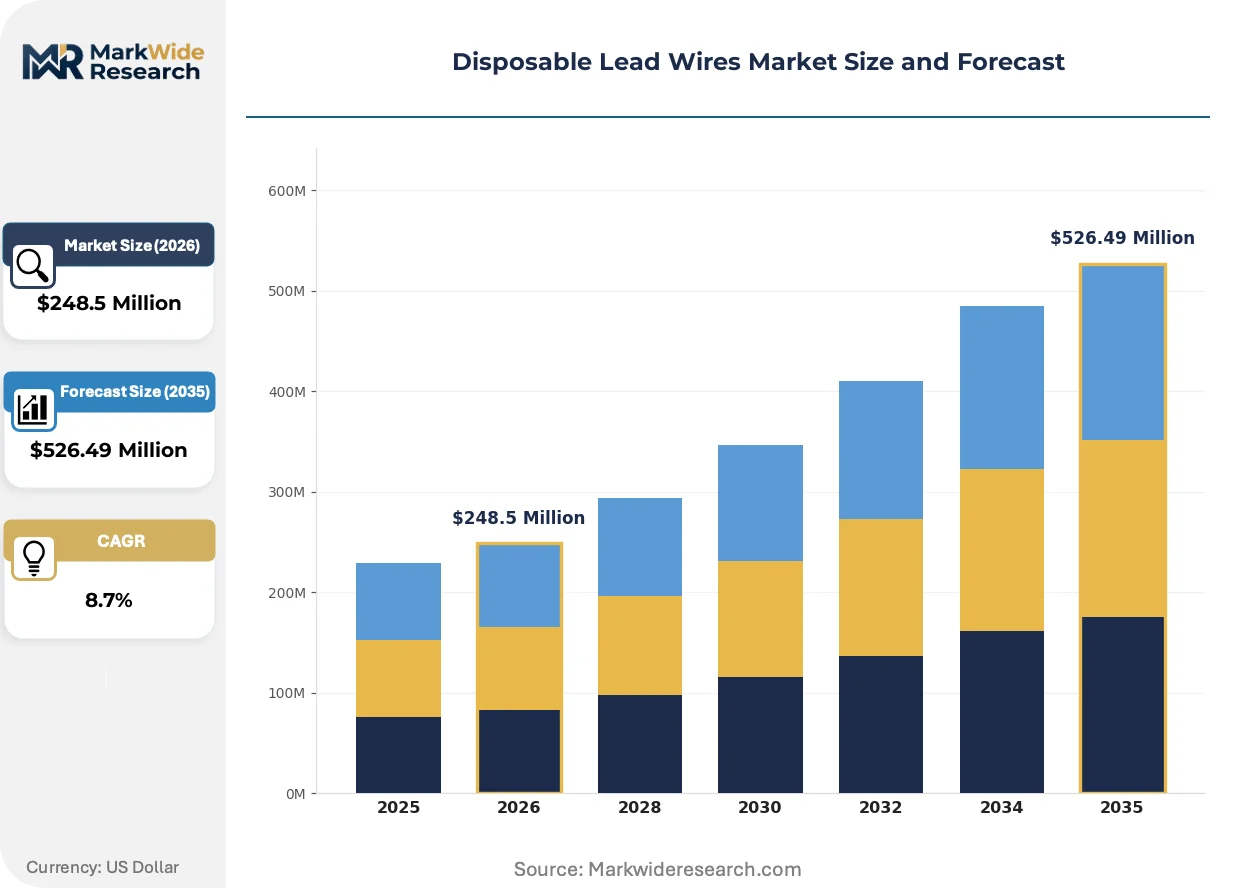
| Market Size in 2026 | $248.5 Million |
| Market Size in 2035 | $526.49 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrode Wires, ECG Lead Wires, Telemetry Leads, SpO2 Sensors End User: Hospitals, Clinics, Homecare Settings, Diagnostic Centers Technology: Wireless, Wired, Single-use, Multi-use Application: Cardiology, Neurology, Respiratory Care, Emergency Services |
| Companies Covered | Schiller AG, OSI Systems, Inc., 3M, Hill-Rom Services, Inc., CONMED, BD, Carlisle Medical Technologies, Cardinal Health, Mindray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Lead Wires Market Strategic Shifts & Innovations
Wireless telemetry architectures are fragmenting the traditional wired monitoring paradigm, creating demand for hybrid disposable assemblies that bridge hardwired reliability with radio-frequency transmission flexibility.
Polymer conductive inks are decentralizing electrode manufacturing by enabling screen-printed bioelectric sensors directly onto disposable lead wire terminations. Cardiology device OEMs are piloting these additive formulations to eliminate snap-connector assembly steps. The technology is decentralizing production geography, allowing regional converters to compete with centralized molding operations.
EU MDR Article 10 clinical evidence requirements are reshaping technical documentation burdens for disposable accessories previously exempt from systematic data collection. Manufacturers must now compile biocompatibility rationales and post-market surveillance plans for Class I patient-connected devices. European notified bodies are extending review timelines, compressing first-mover advantage windows for product line refreshes.
Hospital materials management departments are consolidating supplier panels around vendors offering comprehensive electrode-lead-wire bundles rather than discrete component sourcing. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements that lock in disposable lead wire volumes alongside monitoring equipment placements. This bundling behavior is most pronounced in IDNs with centralized procurement functions across 15-plus acute care facilities.
Disposable Lead Wires Market Segmentation
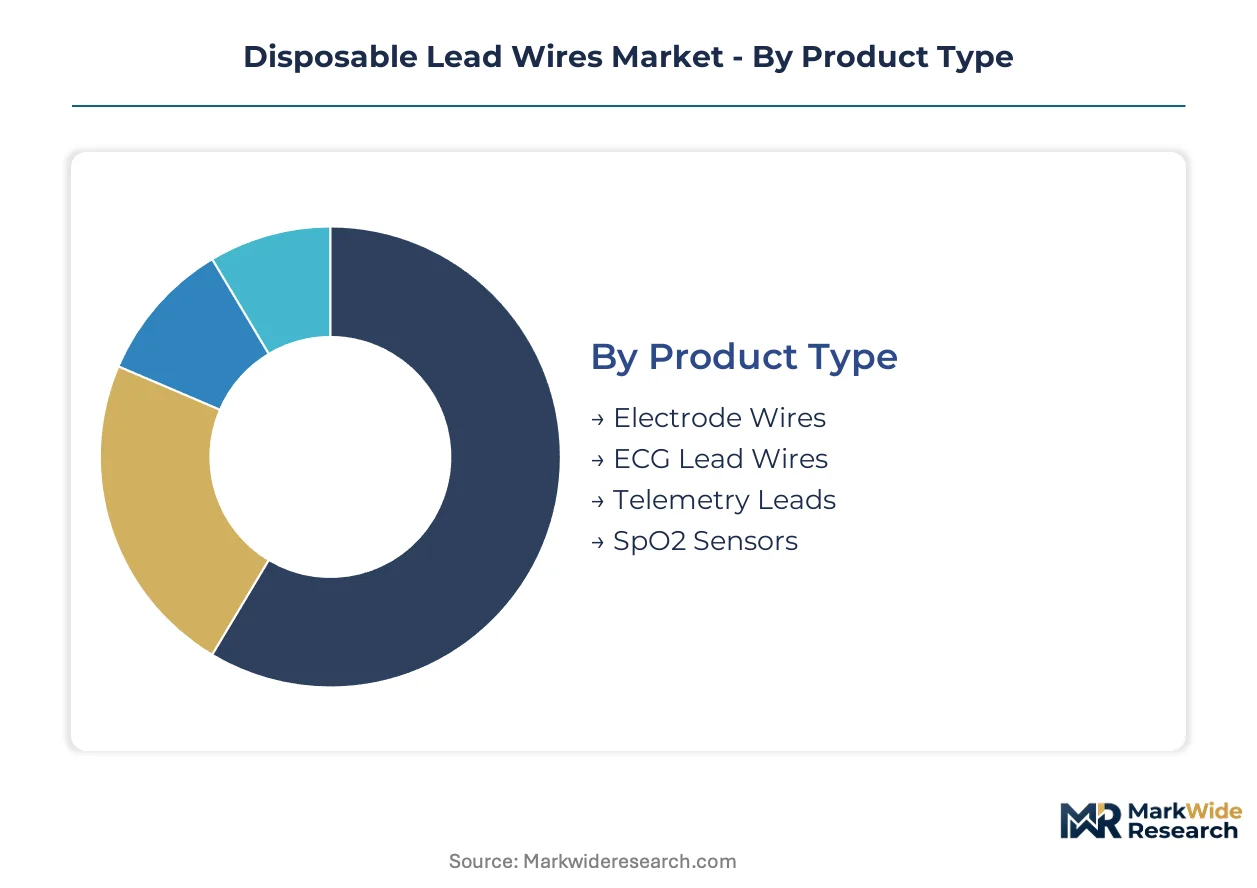
Disposable lead wire segmentation reveals distinct procurement patterns across clinical settings. Integration depth varies sharply between standalone monitoring accessories and embedded system components bundled with capital equipment.
Product Type:
Standalone electrode assemblies dominate low-acuity deployments, while embedded lead systems integrate directly with monitoring platforms requiring OEM validation.
- Electrode Wires:These PVC or TPE insulated conductors terminate in snap or pinch connectors for surface electrode attachment. Demand concentrates in United States emergency departments where rapid patient turnover necessitates single-use protocols. FDA biocompatibility requirements under 21 CFR elevate testing costs for new entrants.
- ECG Lead Wires:Multi-conductor cable assemblies transmit cardiac electrical signals from limb and precordial electrodes to ECG machines. Hospital cath labs in Germany and France absorb the highest per-facility volumes due to procedural intensity. EU MDR Class I classification imposes post-market surveillance obligations that compress refresh cycles.
- Telemetry Leads:Lightweight cable sets optimized for ambulatory cardiac monitoring with radio-frequency transmission compatibility.
- SpO2 Sensors:Disposable pulse oximetry probes combining optical emitters with conductive lead pathways.
Volume placements concentrate in ECG Lead Wires; the faster expansion belongs to Telemetry Leads.
End User:
Procurement sophistication tiers separate acute care institutions from distributed care networks, with reimbursement codes dictating adoption velocity.
- Hospitals:Integrated delivery networks negotiate multi-year sole-source agreements locking disposable lead volumes to monitoring equipment placements. Infection control departments in United States academic medical centers are systematically retiring reusable inventory. Capital depreciation schedules for automated reprocessing equipment create conversion friction.
- Clinics:Outpatient cardiology and neurology practices purchase through distributor channels with limited technical specification involvement. Cost sensitivity is acute among independent physician-owned facilities in India and Brazil.
- Homecare Settings:Remote patient monitoring programs are scaling fastest where CMS reimbursement expansion covers home-based cardiac telemetry.
- Diagnostic Centers:High-throughput imaging facilities prioritize lead wire bundles compatible with multimodal diagnostic platforms.
Procurement volume clusters in Hospitals; reimbursement tailwinds are accelerating Homecare Settings most aggressively.
Technology:
Signal transmission architecture determines regulatory pathway complexity and manufacturing location strategy.
- Wireless:Radio-frequency enabled lead sets eliminate tethering constraints for ambulatory patients. United States cardiology practices are piloting hybrid assemblies bridging hardwired reliability with RF flexibility. FCC Part 15 compliance adds electromagnetic compatibility testing burden.
- Wired:Traditional conductive cable assemblies maintain signal fidelity in high-interference environments like operating rooms. Malaysian contract manufacturers concentrate connector overmolding capacity for this segment.
- Single-use:One-patient disposable protocols mandated by stringent infection control standards.
- Multi-use:Reprocessable lead systems facing accelerated obsolescence from FDA reprocessing validation requirements.
Wired configurations retain placement dominance; Wireless architectures are climbing the fastest as telemetry platforms proliferate.
Application:
Clinical use case intensity shapes lead wire durability specifications and replacement frequency.
- Cardiology:Continuous cardiac monitoring demands the highest lead wire consumption per patient bed. United States hospitals with centralized procurement across 15-plus acute facilities negotiate bundled electrode-lead-wire agreements. Signal fidelity requirements during extended monitoring favor TPE insulation over PVC formulations.
- Neurology:EEG and evoked potential monitoring requires shielded lead assemblies with enhanced noise rejection. European neurophysiology labs in Switzerland and the Netherlands specify ISO 10993 cytotoxicity certification for prolonged skin contact.
- Respiratory Care:Pulse oximetry and capnography lead sets optimized for bedside and transport monitoring.
- Emergency Services:Pre-hospital and trauma applications prioritize rapid deployment and disposable convenience over extended durability.
Cardiology absorbs the deepest volume; Emergency Services are gaining share fastest as pre-hospital monitoring protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian contract manufacturers dominate connector overmolding capacity, while United States hospitals absorb the deepest consumption volumes. European notified bodies extend regulatory review timelines, compressing market access for non-European suppliers. Chinese material suppliers are scaling TPE formulation capacity to serve shifting insulation preferences.
United States
Academic medical centers in Boston and Houston are systematically retiring reusable lead wire inventories under intensified FDA reprocessing scrutiny. CMS reimbursement expansion for remote cardiac telemetry is accelerating homecare channel development. Minnesota-based materials science operations supply adhesive electrode assemblies to integrated delivery networks negotiating multi-year sole-source agreements.
Germany
Cardiac catheterization laboratories in Munich and Berlin maintain the highest per-facility ECG lead wire consumption in Europe. EU MDR Article 10 clinical evidence requirements are reshaping technical documentation burdens for Class I patient-connected devices. The Rhine-Main manufacturing cluster hosts specialized cleanroom molding operations serving neurophysiology shielded lead specifications.
China
NMPA biocompatibility enforcement under GB standards is elevating entry barriers for domestic and imported disposable accessories alike. Yangtze River Delta medical device clusters are expanding ISO 14644 Class 8 cleanroom capacity for TPE overmolding operations. Shenzhen-based contract manufacturers are piloting polymer conductive ink formulations for screen-printed electrode terminations.
Japan
PMDA electrical safety standards under JIS requirements maintain stringent signal fidelity specifications for patient-connected cables. Kansai region hospitals prioritize TPE insulation formulations for extended cardiac monitoring protocols. Osaka-based distributors are consolidating procurement panels around comprehensive electrode-lead-wire bundles rather than discrete component sourcing.
India
CDSCO medical device rules are tightening quality control obligations for disposable patient monitoring accessories entering the domestic market. Maharashtra and Gujarat-based hospital chains are expanding single-use protocols in tertiary care facilities. Cost sensitivity among independent physician-owned cardiology practices in Bangalore and Hyderabad sustains demand for standard PVC-insulated configurations.
Disposable Lead Wires Market Key Industry Players
Top-tier vendors anchor hospital procurement through integrated delivery network agreements, while mid-tier specialists compete on distributor channel density. The vendor base stratifies across materials science conglomerates, diversified medical device manufacturers, and regional contract assemblers. Three archetypes dominate: adhesive technology leaders, distribution-anchored conglomerates, and telemetry-focused innovators. Capacity expansion in Southeast Asian molding operations and strategic bundling of electrode-lead-wire portfolios constitute the dominant competitive moves.
Among diversified medical technology conglomerates, 3M and BD occupy positions exemplifying materials science and distribution-anchored archetypes respectively. Cardinal Health represents the channel-density competitive vector through integrated delivery network penetration. Schiller AG and OSI Systems, Inc. sit within the monitoring equipment-integrated tier, where disposable lead wire volumes tie to capital equipment placements.
| Leading Market Players |
|---|
| Schiller AG |
| OSI Systems, Inc. |
| 3M |
| Hill-Rom Services, Inc. |
| CONMED |
| BD |
| Carlisle Medical Technologies |
| Cardinal Health |
| Mindray |
| Others |
Cost & Logistics Intelligence
Copper futures volatility on the London Metal Exchange cascades through disposable lead wire manufacturing, compressing margins on standard PVC-insulated SKUs while amplifying pricing power for TPE-formulation suppliers with forward-contract coverage. Hospital procurement departments absorb these swings through multi-year sole-source agreements that lock in volumes alongside monitoring equipment placements.
Pricing Analysis
Margin tightening in mid-tier configurations reflects spot-price exposure to refined copper cathode and Malaysian ringgit-denominated molding costs. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled traceability bundles from basic snap-connector assemblies and unbranded distributor SKUs. Cost-down pressure on standard PVC lines accelerates because integrated delivery networks consolidate supplier panels around comprehensive electrode-lead-wire bundles. Independent cardiology clinics in India and Brazil exhibit acute price sensitivity, while United States academic medical centers prioritize biocompatibility certification over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA localization preferences are reshaping sourcing patterns for non-Asian manufacturers. Supply concentrates in Malaysia for connector overmolding, China for TPE formulation and copper conductor drawing, and the United States for adhesive electrode assembly. Raw material flows draw from Chilean copper cathode, Saudi petrochemical feedstock for TPE polymerization, and German specialty chemical additives for DEHP-free formulations. Single-source vulnerability in Penang-based cleanroom molding creates exposure during regional logistics disruptions. Distribution runs through integrated delivery network procurement committees, group purchasing organizations, and cardiology-focused distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom molding capacity constraints across Southeast Asian manufacturing clusters prop pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbents with captive ISO 14644 Class 8 floor space.
For Market Incumbents: Lock in multi-year sole-source agreements with United States integrated delivery networks before EU MDR Article 10 compliance costs elevate competitive barriers. Defend against polymer conductive ink substitution by embedding RFID traceability chips in premium lead wire connectors, creating switching costs that delay decentralized manufacturing adoption. Prioritize backward integration into TPE compounding to secure insulation material supply against petrochemical price volatility. For New Entrants and Emerging Players: Enter via homecare telemetry lead sets optimized for CMS-reimbursed remote cardiac monitoring, the fastest-expanding margin pool outside hospital procurement channels. Target independent cardiology practices in India and Brazil with standard PVC configurations that undercut distributor markups on multinational brands. Lead with polymer conductive ink pilot programs that eliminate snap-connector assembly steps and enable regional screen-printing production. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with established cleanroom molding capacity and pending EU MDR technical documentation. Long-term viability hinges on consolidation plays that aggregate Malaysian connector overmolding assets with United States distribution relationships. Watch FDA reprocessing guidance enforcement intensity as the inflection signal for disposable conversion velocity in acute care settings.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class I Technical Documentation | Accelerates market access timelines for non-European manufacturers establishing authorized representatives. |
| RFID-Enabled Traceability Integration | Differentiates premium lead wire lines through automated expiration tracking and recall management capabilities. |
| TPE Material Backward Integration | Secures DEHP-free insulation supply against petrochemical feedstock volatility and Malaysian ringgit exposure. |
| Homecare Telemetry Lead Development | Captures CMS reimbursement expansion for remote cardiac monitoring outside traditional hospital procurement. |
| Polymer Conductive Ink Pilot Programs | Enables decentralized electrode manufacturing through screen-printed bioelectric sensors on lead terminations. |
Research Approach
Document review covered FDA 21 CFR guidance documents, EU MDR Article 10 technical specifications, ISO 10993 biocompatibility standards, and hospital procurement database records, complemented by interviews with biomedical engineers, GPO contracts managers, cardiology department heads, and Malaysian contract manufacturing executives. Secondary validation drew from SEC 10-K filings of listed medical device manufacturers, customs trade data for copper conductor and TPE resin flows, and CMS reimbursement code expansions. Bottom-up unit economics modeling triangulated against top-down hospital bed and monitoring equipment installation data.
Segmentation outputs across product type, end user, technology, and application dimensions were generated through the projection horizon. CAGRs were derived from replacement cycle compression rates in acute care settings and telemetry platform proliferation curves in ambulatory cardiology. Industry-specific inputs included FDA reprocessing validation timelines, EU notified body review queue lengths, and copper LME forward curve assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended biocompatibility testing backlogs or Malaysian logistics disruptions. Forecasts reflect assumptions regarding infection control protocol stringency, reimbursement code stability, and raw material price trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Lab Trays Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Anesthesia Disposables Market