
 Plate and Frame Heat Exchangers Market | 2026-2036
Plate and Frame Heat Exchangers Market Size, Share, and Industry Trends Forecast 2026-2036
Plate and Frame Heat Exchangers Market Intelligence
A shift from component-level multi-sourcing to single-source procurement of integrated systems is consolidating the supply base. ALFA LAVAL dominates the high-end segment with its vast product portfolio and global service network. Danfoss specializes in compact brazed plate units for HVAC and refrigeration applications. GEA Group leverages its deep process technology expertise, particularly within the food, beverage, and marine engineering industries.
A plate and frame heat exchanger facilitates thermal transfer between two fluids using a series of corrugated metal plates. This design creates a large surface area for efficient thermal exchange within a compact footprint, serving critical industrial heating and cooling functions. Gasketed models constitute the largest product type, valued for their serviceability and operational flexibility. The chemical processing and HVAC systems applications command the largest share of market volume.
Regulatory frameworks, such as the EU's F-Gas Regulation and efficiency mandates from the US EPA, compel industries to adopt more effective thermal management solutions. In China, compliance with GB standards for pressure vessels and energy performance governs market access and product design. The critical decision for manufacturers involves balancing material costs, like those for titanium and nickel alloys, against meeting increasingly stringent regional performance benchmarks.
Market Dynamics
A global regulatory push for greater energy efficiency and sustainable industrial operations is the central force shaping the plate and frame heat exchanger market. Mandates like the EU's F-Gas Regulation and China's GB standards compel industries to adopt superior thermal management technology.
Growth Catalysts
- EU F-Gas Regulation:This framework accelerates the replacement of high-GWP refrigerants in HVAC and refrigeration systems, creating direct demand for plate heat exchangers optimized for next-generation, environmentally friendly coolants.
- Food Processing Hygiene:Demand from the food and beverage industry for efficient pasteurization and cooling systems drives adoption of gasketed units, which offer the necessary cleanability and material compliance for sanitary applications.
- Chinese Chemical Sector Expansion:China's continued investment in large-scale chemical manufacturing facilities creates a concentrated geographic demand center for high-capacity, corrosion-resistant plate and frame heat exchangers for process temperature control.
Market Restraints
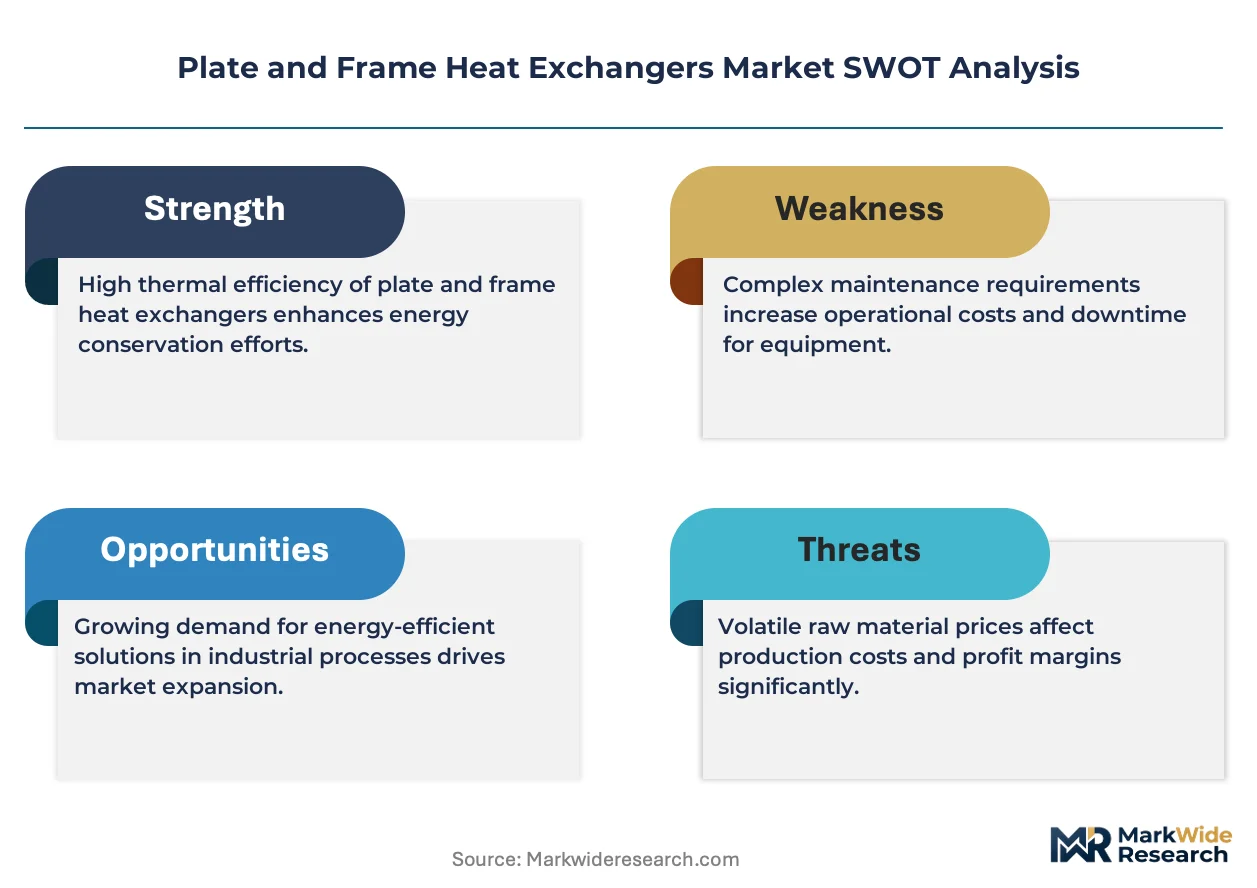
- Material Price Volatility:The fluctuating costs of essential metals like titanium, nickel alloys, and high-grade stainless steel create significant margin pressure and complicate long-term pricing strategies for manufacturers.
- Gasket Material Limitations:While offering serviceability, the elastomer gaskets in GPHEs have temperature and pressure limits and are susceptible to degradation with aggressive chemicals, restricting their use in some severe-service applications.
- Substitution from Brazed Units:In standard HVAC and refrigeration duties, the lower upfront cost and compact, non-serviceable design of brazed plate heat exchangers can present a significant substitution threat to gasketed models.
Strategic Opportunities
- Data Center Liquid Cooling:The increasing power density of modern data centers creates a substantial opportunity for compact and efficient plate heat exchangers to be used in advanced liquid cooling loops.
- Smart System Integration:Incorporating IoT sensors and predictive analytics into heat exchanger systems allows for remote monitoring and condition-based maintenance, creating new value-added service and revenue models for manufacturers.
- Industrial Waste Heat Recovery:Tighter emissions rules and energy costs incentivize the adoption of heat exchangers in industrial settings to capture and repurpose waste heat, improving overall plant efficiency.
Industry Challenges
- Divergent Regional Standards:Manufacturers face significant design and certification costs to comply with a patchwork of regional regulations, including the EU's CE marking, China's GB standards, and US EPA mandates.
- Specialized Material Sourcing:Securing a stable supply of high-performance alloys like titanium is a persistent challenge, as production is concentrated in a few regions and vulnerable to geopolitical tensions and trade policy shifts.
- Legacy System Retrofits:Integrating modern, compact heat exchangers into existing industrial plants often requires costly and complex modifications to legacy piping, mounting points, and control systems, slowing adoption in brownfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plate and Frame Heat Exchangers Market |
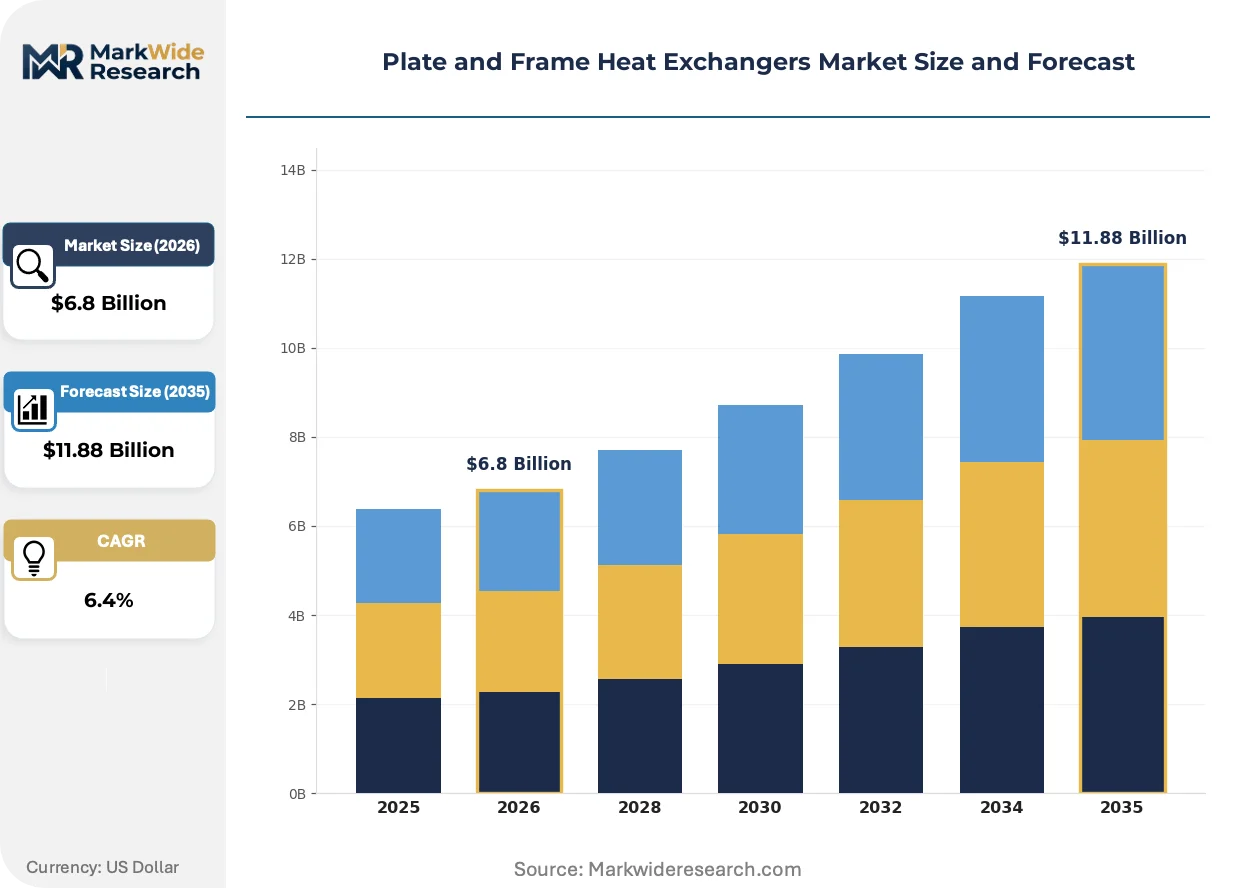
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
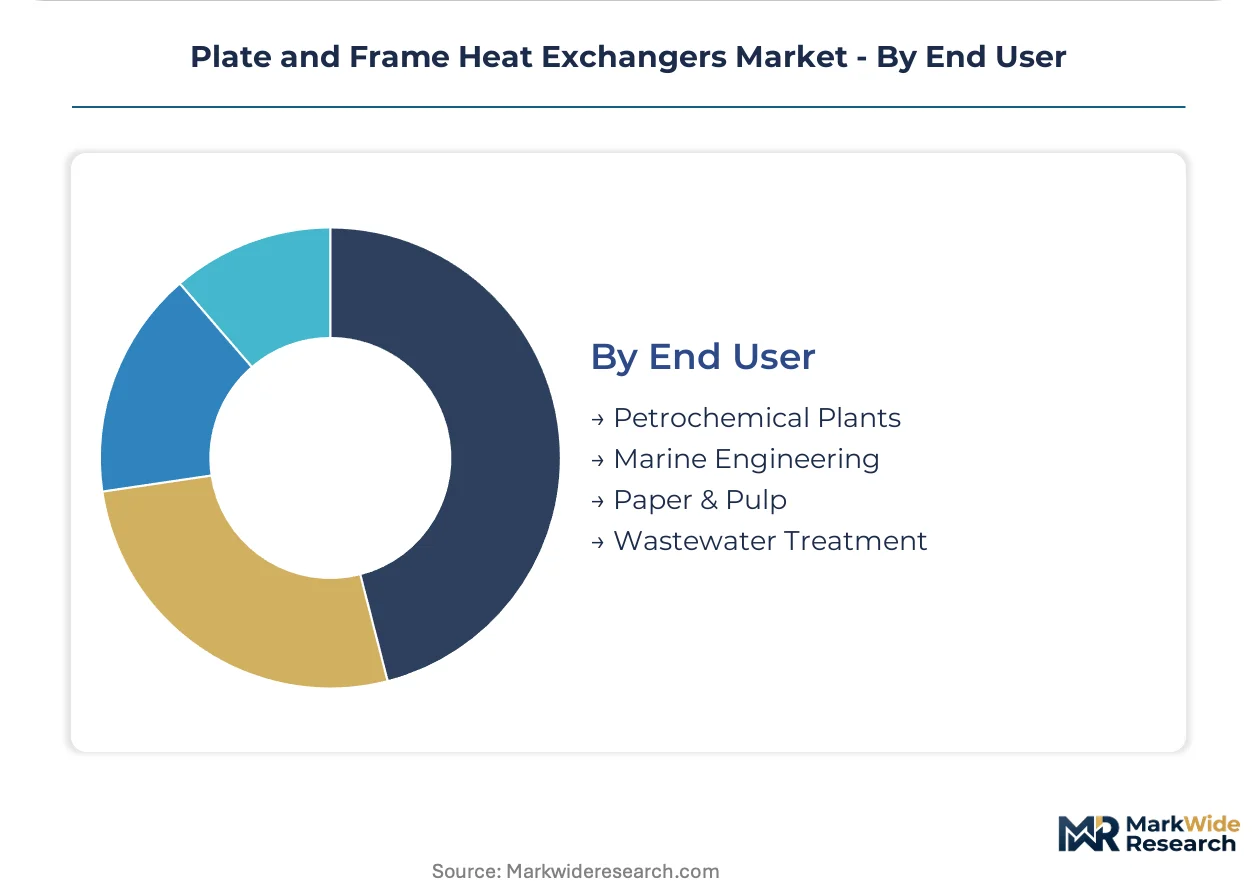
| Segmentation | Product Type: Gasketed, Brazed, Welded, Semi-Welded Material: Stainless Steel, Titanium, Nickel Alloys, Copper Application: Chemical Processing, HVAC Systems, Food Processing, Power Generation End User: Petrochemical Plants, Marine Engineering, Paper & Pulp, Wastewater Treatment |
| Companies Covered | ALFA LAVAL, Danfoss, Kelvion Holding GmbH, API Heat Transfer, SPX Flow, GEA Group, Tranter Inc., HISAKA WORKS LTD, Nexson Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plate and Frame Heat Exchangers Market Strategic Shifts & Innovations
System-level intelligence and application-specific customization are defining the market's technological trajectory. The focus is evolving from selling a standalone component to delivering an integrated thermal management solution engineered for specific performance outcomes and regulatory environments.
Additive manufacturing enables the creation of highly complex plate geometries and optimized internal flow paths that were previously impossible. High-performance sectors like aerospace and specialized chemical processing are the initial adopters of this technology. This advanced manufacturing capability is absorbing the design constraints of traditional metal stamping, enabling a new class of ultra-efficient, custom-engineered heat exchangers.
The EU's F-Gas Regulation is a primary driver of innovation, mandating a phase-down of refrigerants with high global warming potential. This forces HVAC and refrigeration OEMs to redesign their equipment for alternative coolants like CO2, ammonia, or propane. Plate heat exchangers are directly affected, as these natural refrigerants require units specifically engineered to handle their unique pressure and temperature characteristics safely.
Consolidation of procurement is altering the supply chain, as end-users increasingly prefer single-source suppliers for complete thermal modules. This model bypasses the traditional multi-sourcing of individual components, favoring manufacturers who can deliver integrated skids with pumps, controls, and heat exchangers. This shift is most visible in large-scale HVAC installations and new food processing facilities where project owners seek to minimize integration risk.
Plate and Frame Heat Exchangers Market Segmentation
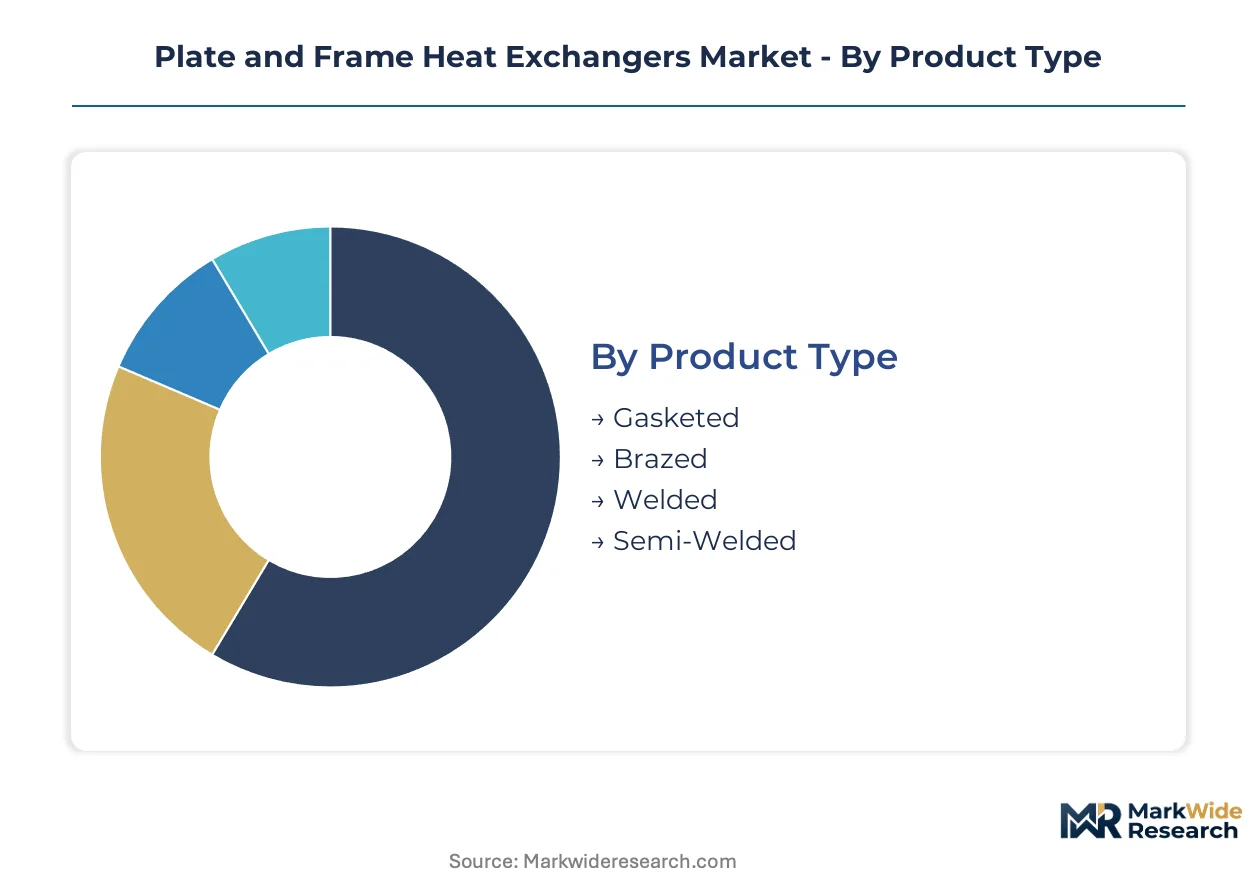
Understanding the segmentation of the plate and frame heat exchanger market reveals the specific design choices and material considerations driven by diverse industrial demands. This granular analysis helps manufacturers align product development with high-growth applications and regional regulatory pressures. Each segment reflects distinct performance requirements and operational environments.
Product Type:
The product type segmentation differentiates plate and frame heat exchangers based on their design for standalone operation versus integration into larger systems, impacting their serviceability and pressure ratings.
- Gasketed:These units utilize elastomeric gaskets between plates to create fluid channels, offering easy disassembly for cleaning and maintenance. Gasketed models constitute the largest product type, valued for their serviceability and operational flexibility, especially in food processing hygiene applications.
- Brazed:Brazed plate heat exchangers feature plates permanently joined by a brazing material, creating a compact and robust unit without gaskets. Danfoss specializes in these compact units for HVAC and refrigeration applications, where they are optimized for next-generation, environmentally friendly coolants due to the EU's F-Gas Regulation.
- Welded:Welded plate heat exchangers offer high-pressure and high-temperature capabilities, suitable for aggressive media where gaskets would degrade.
- Semi-Welded:Combining features of gasketed and welded types, semi-welded units allow one fluid channel to be gasketed and the other welded, often used for corrosive fluids.
Volume placements concentrate in Gasketed units; the faster expansion belongs to Brazed models.
Material:
Material selection for plate and frame heat exchangers directly impacts both performance and overall unit cost, dictating corrosion resistance and thermal conductivity.
- Stainless Steel:This material offers good corrosion resistance and mechanical strength, making it a common choice for general industrial applications like HVAC systems and various process heating tasks. Its balance of cost and performance makes it a widely adopted option across multiple sectors.
- Titanium:Titanium provides exceptional corrosion resistance, particularly in chloride-rich environments such as marine engineering and certain chemical processes. Manufacturers balance material costs for titanium against meeting stringent regional performance benchmarks in demanding applications.
- Nickel Alloys:These alloys deliver superior resistance to highly corrosive chemicals and high temperatures, often specified for specialized chemical processing.
- Copper:Copper offers excellent thermal conductivity, making it suitable for applications where rapid heat transfer is critical, such as some HVAC and refrigeration systems.
The choice of material heavily influences the operational lifespan and maintenance requirements of plate heat exchangers.
Application:
Application segments categorize plate and frame heat exchangers by their primary end-use function and the specific process demands they address.
- Chemical Processing:This application demands robust, corrosion-resistant heat exchangers for precise temperature control in various reactions and separations. The chemical processing sector commands the largest share of market volume, particularly with China's continued investment in large-scale manufacturing facilities.
- HVAC Systems:Plate heat exchangers in HVAC systems manage building climate control and refrigeration, driven by efficiency mandates and the EU's F-Gas Regulation for next-generation coolants. This sector also commands a significant share of market volume due to global energy efficiency pushes.
- Food Processing:The food and beverage industry uses these units for pasteurization, sterilization, and cooling, requiring hygienic designs and cleanability.
- Power Generation:Heat exchangers in power plants manage turbine cooling, exhaust heat recovery, and condensate preheating to improve overall plant efficiency.
Specific application requirements drive material selection and design configurations across the market.
End User:
End-user categories define the specific industries deploying plate and frame heat exchanger technology, each presenting unique operational environments and regulatory compliance needs.
- Petrochemical Plants:These facilities utilize heat exchangers for critical process heating, cooling, and condensation, handling aggressive chemicals and high-pressure conditions. China's continued investment in large-scale chemical manufacturing facilities creates a concentrated geographic demand center for these high-capacity units.
- Marine Engineering:In marine applications, heat exchangers manage engine cooling, oil cooling, and HVAC systems on vessels, requiring robust designs resistant to saltwater corrosion. GEA Group leverages its deep process technology expertise, particularly within the marine engineering industry.
- Paper & Pulp:The paper and pulp industry uses heat exchangers for process heating, chemical recovery, and wastewater treatment, often in corrosive and fouling environments.
- Wastewater Treatment:Heat exchangers in wastewater treatment facilities manage sludge heating and energy recovery processes to optimize biological activity and reduce energy consumption.
Each end-user industry presents unique demands regarding operational reliability and regulatory compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's vast industrial manufacturing base anchors significant demand for plate and frame heat exchangers. The global push for greater energy efficiency and sustainable industrial operations drives adoption across diverse applications. Regulatory frameworks worldwide compel industries to seek more effective thermal management solutions.
China
China's continued investment in large-scale chemical manufacturing facilities creates a concentrated geographic demand center. Compliance with GB standards for pressure vessels and energy performance governs market access. The Yangtze River Delta region, with its robust chemical and advanced manufacturing sectors, integrates high-capacity, corrosion-resistant heat exchangers for process temperature control.
United States
The United States market sees demand from next-generation HVAC systems and the expanding data center liquid cooling segment. Efficiency mandates from the US EPA compel industries to adopt superior thermal management technology. Petrochemical hubs along the Gulf Coast are increasingly adopting these units for process heating and cooling applications, driven by operational efficiency goals.
Germany
Germany's industrial sector drives demand for plate heat exchangers in waste heat recovery and advanced food processing. The EU's F-Gas Regulation accelerates the replacement of high-GWP refrigerants in HVAC systems. Bavaria's strong manufacturing base and focus on sustainable industrial practices utilize these technologies for improved energy performance and reduced emissions.
India
India's growing petrochemical sector and infrastructure development projects contribute to the demand for plate and frame heat exchangers. BIS standards for industrial equipment ensure product quality and safety across various applications. Gujarat, a hub for chemical and pharmaceutical industries, requires specialized units for precise temperature control and material compatibility.
Saudi Arabia
Saudi Arabia's petrochemical expansion and significant investments in desalination plants represent key demand drivers. Local content requirements and national energy efficiency goals influence equipment procurement. Jubail Industrial City, a major industrial complex, deploys large-scale heat exchangers for critical process applications in its refining and chemical operations.
Plate and Frame Heat Exchangers Market Key Industry Players
Portfolio diversification dominates the current landscape, as manufacturers seek to offer integrated thermal management solutions. The market exhibits a tiered structure, with a few global leaders at the high-end and numerous regional specialists. Strategic archetypes include integrated system providers, compact unit specialists, and broad industrial suppliers. Geographic expansion and technology licensing represent common competitive moves.
Specialists in integrated solutions, such as ALFA LAVAL, exemplify the premium-tier offerings with vast product portfolios and global service networks. Danfoss occupies a position as a key supplier for compact brazed plate units, particularly for HVAC and refrigeration applications. GEA Group leverages its deep process technology expertise, sitting within the food, beverage, and marine engineering industries.
| Leading Market Players |
|---|
| ALFA LAVAL |
| Danfoss |
| Kelvion Holding GmbH |
| API Heat Transfer |
| SPX Flow |
| GEA Group |
| Tranter Inc. |
| HISAKA WORKS LTD |
| Nexson Group |
| Others |
Cost & Logistics Intelligence
Material costs, particularly for high-performance alloys, trace a path from concentrated global mining and processing to impact final product pricing for specialized plate and frame heat exchangers. Fluctuations in these upstream inputs directly influence manufacturing margins and downstream pricing strategies across various application tiers.
Pricing Analysis
After-sales service bundling significantly influences final pricing, with comprehensive maintenance packages often integrated into project-based contracts for complex industrial installations. Pricing stratifies across premium, standard, and economy tiers, driven by factors such as material quality grade and specific regulatory certifications like CE marking. Material price volatility, especially for titanium and nickel alloys, creates margin pressure for manufacturers. Chemical processing and marine engineering clients exhibit lower price sensitivity due to critical performance requirements, while standard HVAC applications are more cost-sensitive.
Supply Chain Analysis
Direct sales channels frequently manage complex project requirements for large industrial clients, particularly in the chemical processing and power generation sectors. Geographic supply concentration for key raw materials like titanium and nickel alloys primarily rests in regions with specialized mining and refining capabilities. The supply chain sources essential components such as elastomer gaskets from a diverse global base. Single-source vulnerability for specialized alloys represents a structural risk. Distribution runs through a combination of direct sales for large-scale projects and regional distributors for standard units and aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as the increasing complexity of regulatory compliance and the need for integrated solutions force weaker, less diversified players out. Strategic moves are critical for sustained growth.
For Market Incumbents: Lock in core customer relationships through long-term service contracts and expanded integrated system offerings. Invest heavily in research and development for plate heat exchangers optimized for natural refrigerants, mitigating the threat from evolving F-Gas regulations. Deepen vertical integration into specialized alloy manufacturing to control material costs and ensure supply stability against geopolitical shifts.
For New Entrants and Emerging Players: Launch into niche applications leveraging advanced manufacturing capabilities, such as additive manufacturing for highly customized units. The data center liquid cooling segment represents a penetrable white-space target due to its rapid growth and demand for compact, efficient solutions. A partnership-driven go-to-market angle with specialized system integrators can accelerate market entry.
For Investors and Strategic Acquirers: Accelerated adoption of liquid cooling in data centers is the leading indicator that high-efficiency thermal solutions will command premium valuations over the long term. Target acquisition archetypes include specialists in additive manufacturing or firms with strong intellectual property in natural refrigerant heat exchanger designs. The growth rate of industrial waste heat recovery projects is a specific signal to watch as an inflection indicator for broader market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Integrated Thermal Solutions | Offers end-to-end value, consolidating procurement for large projects. |
| Invest in Additive Manufacturing | Enables complex plate geometries for superior thermal efficiency. |
| Develop Natural Refrigerant Compatibility | Aligns products with EU F-Gas Regulation and global sustainability goals. |
| Acquire Data Center Cooling Specialists | Captures a high-growth segment driven by increasing power density. |
| Strengthen After-Sales Service Network | Enhances customer loyalty and provides recurring revenue streams. |
Research Approach
Industry reports, corporate annual filings, and regulatory documentation formed the secondary backbone for this market analysis. Primary interviews with plant managers, HVAC system designers, chemical engineers, and procurement specialists provided crucial qualitative insights. This approach ensured robust bottom-up and top-down triangulation of market data.
Historical trendline analysis established foundational growth patterns across key segments, including product type, material, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical performance and projected demand drivers, such as energy efficiency mandates and industrial expansion projects. The analytical framework projected market evolution over the forecast period.
The model assumes a particular technology adoption path; alternative pathways for advanced materials or additive manufacturing would alter the outlook. Forecasts reflect assumptions regarding economic stability and regulatory enforcement. Geopolitical shifts impacting material supply or unforeseen regulatory changes represent specific risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Thawing System Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Cooling Tower Rental Market