
 Air-Cooled Gas Coolers Market | 2026-2036
Air-Cooled Gas Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Cooled Gas Coolers Market Insights
Aftermarket service revenue is tilting toward predictive maintenance contracts and thermal performance audits as operators seek to extend cooler bundles beyond original design life. GEA Group Aktiengesellschaft leverages its extensive installed base across European power stations to secure long-term service agreements. SPX Cooling Technologies anchors its position through specialized fin-tube manufacturing capabilities that reduce thermal degradation in cyclic gas turbine duty. Kelvion Holding GmbH competes on modular platform architectures that slash field installation timelines for retrofit projects.
Air-cooled gas coolers reject process heat to ambient air through finned-tube bundles forced by axial fans, typically achieving approach temperatures of 8–15°C above dry-bulb conditions; they eliminate evaporative water losses that plague cooling towers in thermoelectric and hydrocarbon processing plants. The power generation application segment leads absolute volume due to combined-cycle gas turbine buildouts in water-stressed regions, while the oil and gas end user category generates premium margins through corrosion-resistant alloy specifications for sour gas service. Modular installation configurations are gaining share against fixed designs as project developers prioritize site mobility and phased capacity additions.
The EPA enforces thermal discharge limits under the Clean Water Act that restrict once-through cooling, while ISO 13706 governs air-cooled heat exchanger mechanical design for petroleum and petrochemical service. OSHA process safety management requirements and EU F-Gas Regulation phase-down schedules are reshaping coolant selection and leak detection specifications for hybrid cooler variants. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional water pricing trajectories to validate air-cooled economics against emerging dry-cooling alternatives.
Market Dynamics
Water scarcity across thermoelectric corridors is compressing project timelines toward air-cooled architectures, while EPA Section 316(b) enforcement eliminates once-through cooling as a viable design option for new combined-cycle gas turbine installations.
Growth Catalysts
- EPA Section 316(b) Cooling Water Intake Structures Rule:The regulation mandates closed-cycle cooling for new facilities, eliminating once-through designs and redirecting capital toward air-cooled gas coolers in thermoelectric plant expansions.
- Combined-cycle gas turbine buildouts:Power developers in water-stressed basins specify air-cooled heat rejection systems to secure permitting and reduce long-term water procurement costs.
- Texas and southwestern US drought conditions:Persistent aridity in the ERCOT and CAISO balancing authority areas makes evaporative cooling economically unviable, concentrating demand for dry-cooling alternatives.
Market Restraints
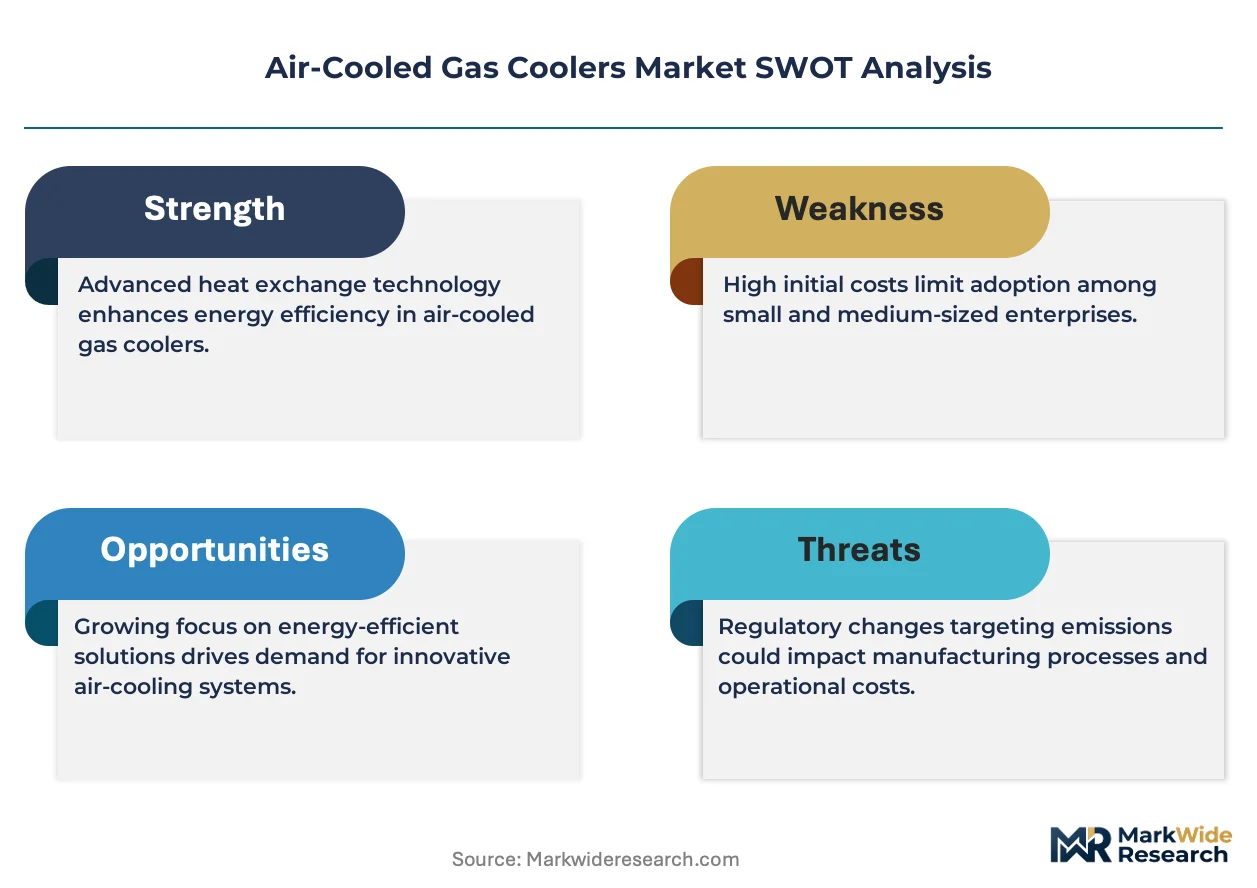
- Aluminum and copper price volatility:Fin-tube bundles require substantial non-ferrous metal content, exposing project economics to commodity swings that compress equipment margins.
- Fan and motor supplier concentration:High-efficiency axial fan production clusters in Germany and China, creating lead time vulnerability for North American project schedules.
- Thermal performance degradation in cyclic duty:Gas turbine peaking operations impose thermal fatigue on fin-tube joints, shortening bundle life below baseload design assumptions.
Strategic Opportunities
- Hybrid cooler variants integrating adiabatic pre-cooling:Manufacturers combining dry air-cooling with evaporative assist are capturing projects in marginal climates where pure dry cooling underperforms.
- Retrofit of legacy water-cooled plants:Existing thermoelectric stations facing cooling tower replacement cycles present conversion opportunities to air-cooled designs.
- EU F-Gas Regulation phase-down schedules:The refrigerant transition is opening specification windows for ammonia and CO2-based hybrid coolers in European hydrocarbon processing applications.
Industry Challenges
- Thermal-hydraulic modeling expertise shortage:Field installation of large air-cooled bundles requires specialized fin-tube layout optimization that outstrips available engineering capacity.
- ISO 13706 compliance documentation burden:Mechanical design verification for petroleum service creates protracted approval timelines that delay project commercial operation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Cooled Gas Coolers Market |
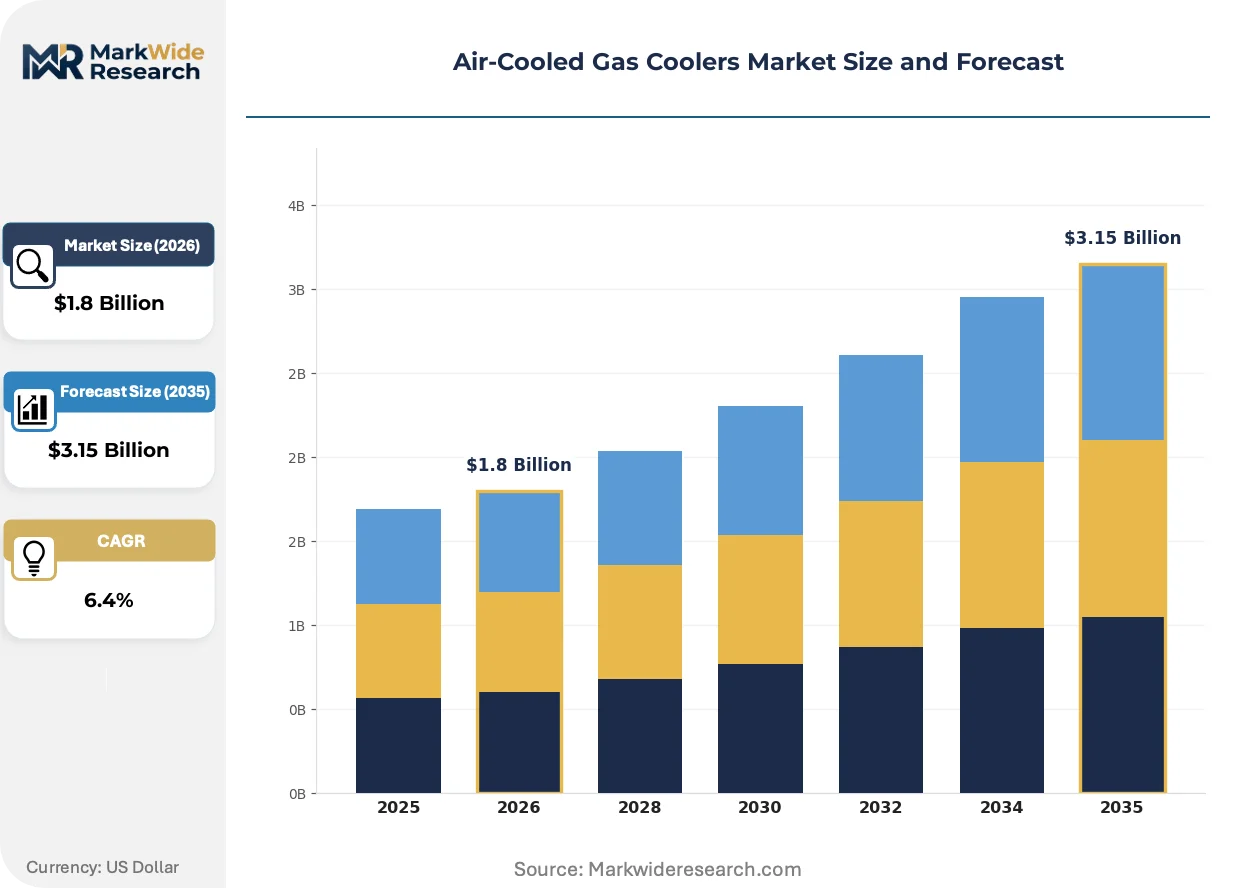
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Evaporative, Hybrid, Refrigerant Application: Industrial Cooling, Power Generation, HVAC, Food Processing Installation: Modular, Skid-Mounted, Fixed, Portable End User: Manufacturing, Oil & Gas, Mining, Chemical |
| Companies Covered | SPX Cooling Technologies, GEA Group Aktiengesellschaft, EVAPCO, Inc., Baltimore Aircoil Company, ALFA LAVAL, SPG Dry Cooling, Kelvion Holding GmbH, Thermax Limited, AXH air-coolers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Cooled Gas Coolers Market Trends and Innovations
Equipment architectures are pivoting from fixed-field erection toward modular skidded configurations that compress site labor requirements and enable phased capacity deployment.
Variable-frequency drive control of axial fan arrays is rendering obsolete fixed-speed motor installations that cannot modulate heat rejection capacity against ambient temperature swings. Combined-cycle operators in the ERCOT and CAISO regions are specifying VFD-equipped coolers to maintain turbine efficiency across diurnal load cycles. The technology is compressing auxiliary power consumption and extending mechanical component life through reduced start-stop cycling.
The EPA's ongoing Section 316(b) enforcement is eliminating once-through cooling intake structures from new thermoelectric permitting pathways. Project developers must now demonstrate closed-cycle heat rejection compliance before construction authorization, redirecting engineering resources toward air-cooled and hybrid system validation. Gas turbine original equipment manufacturers are responding with standardized air-cooled balance-of-plant packages that accelerate customer project schedules.
Aftermarket service contracts are unbundling from original equipment supply, with operators separating thermal performance guarantee obligations from installation scope. Power generation utilities now procure predictive maintenance and bundle cleaning as standalone subscriptions rather than bundled warranties. The shift is most visible in Texas and California, where merchant plant operators prioritize uptime certainty over capital equipment vendor relationships.
Air-Cooled Gas Coolers Market Segmentation
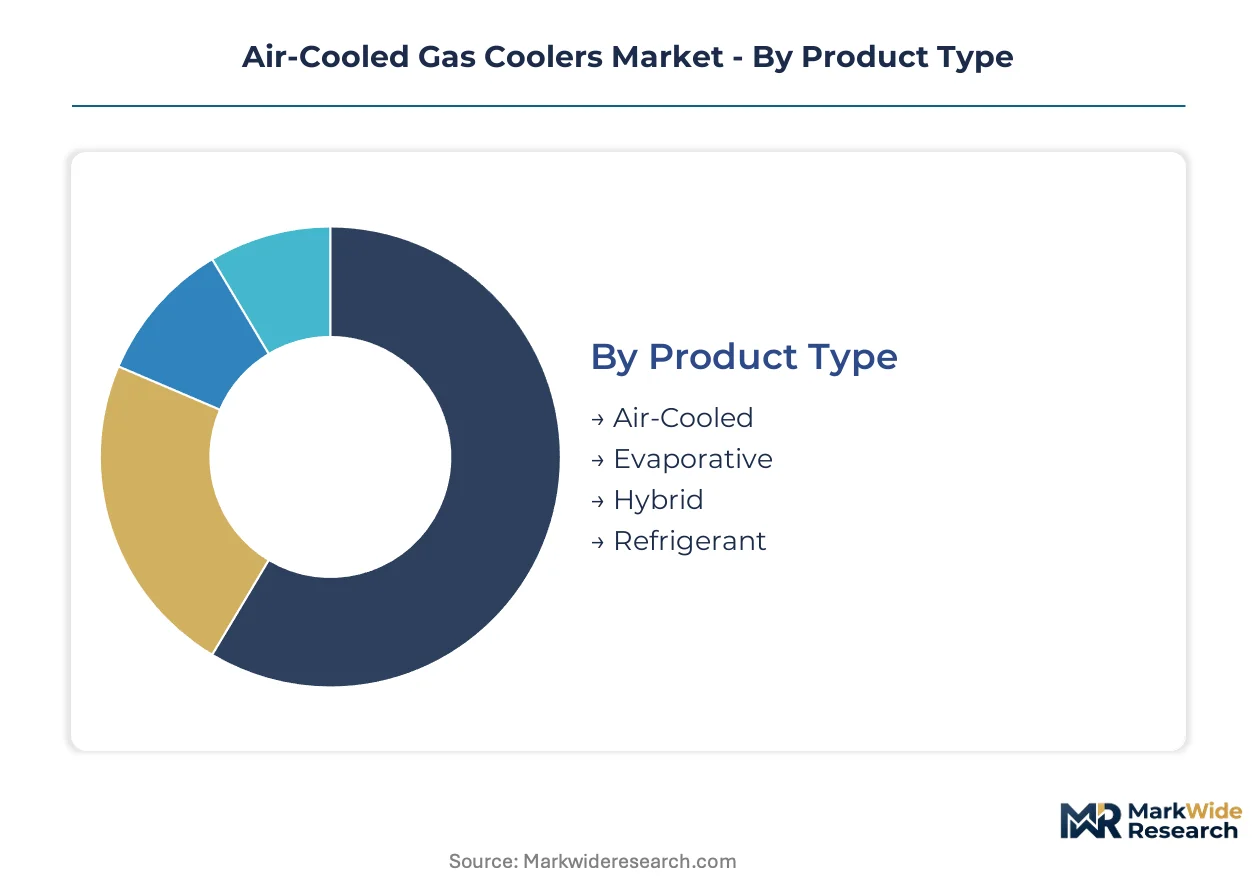
Air-cooled gas cooler procurement patterns diverge sharply by thermal duty intensity and site constraints, with power developers prioritizing different architectures than hydrocarbon processors. Segmentation clarity enables suppliers to align fin-tube specifications, fan array configurations, and service contract structures against actual operating conditions rather than nominal capacity ratings.
Product Type:
Replacement cycles stretch from 15 years for dry air-cooled bundles to 8-10 years for refrigerant-based systems, creating divergent aftermarket revenue profiles across the installed base.
- Air-Cooled:Finned-tube bundles reject heat directly to ambient air without water consumption, achieving approach temperatures 8–15°C above dry-bulb conditions. Power generation utilities in Texas and the southwestern United States specify these systems to secure EPA Section 316(b) compliance and eliminate cooling water procurement costs in drought-stressed basins.
- Evaporative:Wet-surface cooling pads or spray systems augment air-side heat transfer, cutting required air volume by 30–40% versus pure dry designs. The technology captures projects in marginal climates where ambient temperatures periodically exceed pure air-cooled performance limits, though water treatment chemistry adds operational complexity.
- Hybrid:Combines dry air-cooling with adiabatic pre-cooling stages that activate only during peak ambient conditions, balancing water conservation against thermal performance guarantees.
- Refrigerant:Closed-loop vapor compression systems enable sub-ambient heat rejection for process cooling duties, with EU F-Gas Regulation phase-down schedules reshaping coolant selection toward ammonia and CO2 variants.
Air-cooled designs anchor the volume base while hybrid configurations gain share at the steepest rate as developers seek thermal performance without full evaporative water dependency.
Application:
Margin structures compress from power generation through food processing, with industrial cooling commanding intermediate returns based on alloy specification intensity.
- Industrial Cooling:Process heat rejection for refineries, petrochemical complexes, and steel mills drives demand for corrosion-resistant fin-tube alloys in sour gas and high-sulfur environments. Oil and gas end users in the Permian Basin and Gulf Coast corridors specify duplex stainless steel bundles to withstand cyclic thermal stress and aggressive atmospheric conditions.
- Power Generation:Combined-cycle gas turbine installations constitute the dominant demand pool, with ERCOT and CAISO balancing authority developers mandating air-cooled heat rejection to satisfy EPA cooling water intake regulations. The segment generates premium pricing for thermal performance guarantees and long-term service bundling.
- HVAC:Commercial and institutional building systems prioritize acoustic attenuation and footprint minimization over thermal efficiency extremes.
- Food Processing:Ammonia-based refrigeration integration and sanitary design requirements dominate specification criteria for cold storage and blast freezing applications.
Power generation commands the revenue concentration while industrial cooling climbs fastest as hydrocarbon processing capacity expands in water-constrained shale basins.
Installation:
Site labor economics and project phasing flexibility separate premium modular configurations from cost-optimized fixed erection approaches.
- Modular:Factory-assembled fin-tube bundles and fan arrays ship as pre-tested skids, cutting field installation timelines by 40–60% versus stick-built alternatives. Project developers in the Permian Basin and Texas power corridors specify modular architectures to compress construction schedules and enable phased capacity additions aligned with gas turbine commissioning sequences.
- Skid-Mounted:Complete cooler assemblies integrate on structural steel frames for rapid site placement, dominating retrofit applications where existing infrastructure constrains construction access.
- Fixed:Traditional field-erected configurations persist in greenfield installations with unconstrained site access and single-phase development timelines.
- Portable:Trailer-mounted rental units serve temporary cooling needs during maintenance outages and emergency heat rejection requirements.
Fixed installations retain the installed base majority while modular systems expand most quickly as labor cost inflation and schedule risk reshape project economics.
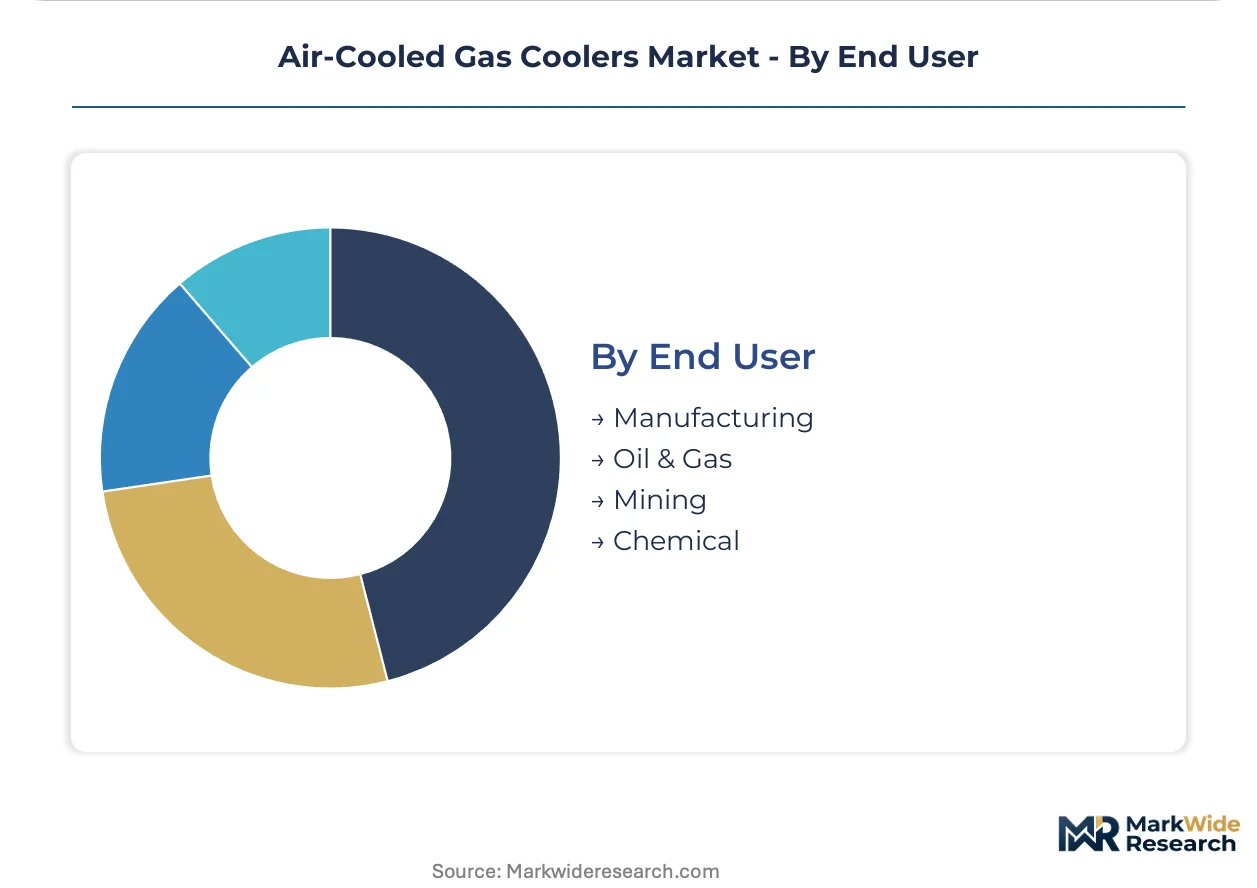
End User:
Procurement sophistication spans from standardized catalog specifications in manufacturing to fully engineered corrosion-resistant alloys in sour gas service.
- Manufacturing:Automotive, semiconductor, and heavy industrial facilities specify air-cooled gas coolers for compressed air systems, welding equipment cooling, and process fluid temperature control, with ISO 13706 mechanical design standards governing petroleum-adjacent applications.
- Oil & Gas:Upstream production, midstream gas processing, and downstream refining operations drive demand for high-alloy fin-tube specifications resistant to hydrogen sulfide corrosion and thermal fatigue from cyclic turndown operations.
- Mining:Remote site operations prioritize dry-cooling to eliminate water logistics burden in arid extraction regions.
- Chemical:Specialty and commodity chemical producers balance thermal performance against materials compatibility with aggressive process streams.
Oil and gas anchors the specification intensity while mining end users are expanding fastest as water access constraints tighten across copper, lithium, and rare earth extraction corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabricators cluster in Germany and the United States, where precision fin-tube manufacturing and power sector engineering capabilities concentrate. Demand patterns diverge sharply between water-stressed basins mandating dry-cooling and regions where hybrid architectures capture marginal climate projects.
United States
Texas and southwestern utilities drive combined-cycle gas turbine installations requiring air-cooled heat rejection systems. EPA Section 316(b) enforcement eliminates once-through cooling from new permitting pathways, redirecting capital toward closed-cycle designs. The ERCOT and CAISO balancing authority corridors concentrate procurement as merchant developers prioritize water independence.
Germany
Industrial cooling demand from chemical complexes and automotive manufacturing sustains premium equipment specifications. EU F-Gas Regulation phase-down schedules reshape coolant selection for hybrid cooler variants in hydrocarbon processing applications. The Rhine-Ruhr industrial belt anchors fabrication capacity for export-oriented suppliers.
China
Power sector expansion in water-constrained northern provinces accelerates dry-cooling adoption for thermal generation assets. The Ministry of Ecology and Environment tightens thermal discharge standards that disadvantage once-through cooling intake structures. Inner Mongolia and Shanxi coal-to-gas conversion projects specify air-cooled architectures to reduce water logistics burden.
India
Central Electricity Authority guidelines promote closed-cycle cooling for new thermal capacity to reduce freshwater withdrawal intensity. Gujarat and Maharashtra industrial corridors specify air-cooled gas coolers for refinery expansions and petrochemical complexes. The country's national environmental regulator enforces Zero Liquid Discharge mandates that compress evaporative cooling economics.
Saudi Arabia
Desalination-dependent power generation economics make air-cooled heat rejection systems cost-competitive against water-intensive alternatives. The Saudi Energy Efficiency Center mandates thermal performance standards for gas turbine installations that favor dry-cooling architectures. The Eastern Province industrial cities concentrate demand from integrated gas-to-power complexes.
Air-Cooled Gas Coolers Market Competitive Landscape
Integrated thermal engineering conglomerates and specialized heat transfer equipment fabricators split the market between bundled service offerings and component-focused supply. Consolidation pressure intensifies as project developers seek single-source accountability for performance guarantees and long-term maintenance obligations. European-headquartered suppliers leverage legacy installed bases across power stations to secure aftermarket contracts, while Asian fabricators compete on modular platform cost structures. Capacity expansion and strategic partnerships dominate competitive moves as manufacturers seek to anchor positions in water-stressed growth corridors.
Among Germany-based engineering groups, GEA Group Aktiengesellschaft and Kelvion Holding GmbH exemplify the integrated conglomerate archetype with extensive service infrastructures. SPX Cooling Technologies anchors the specialized fabricator tier through fin-tube manufacturing capabilities. These three companies occupy positions spanning premium thermal performance guarantees and cost-optimized modular configurations.
| Leading Market Players |
|---|
| SPX Cooling Technologies |
| GEA Group Aktiengesellschaft |
| EVAPCO, Inc. |
| Baltimore Aircoil Company |
| ALFA LAVAL |
| SPG Dry Cooling |
| Kelvion Holding GmbH |
| Thermax Limited |
| AXH air-coolers |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European fin-tube manufacturing is compressing lead times and hardening supplier pricing power across premium alloy specifications. German and Chinese fabricators are prioritizing long-term service contracts over spot equipment orders, tilting procurement economics toward bundled performance guarantees.
Pricing Analysis
Aftermarket service revenue tiers—spanning predictive maintenance contracts, thermal performance audits, and bundle replacement cycles—drive lifetime value capture for equipment suppliers. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated thermal guarantees from third-party service providers and unbundled component suppliers. Cost compression in standard-grade aluminum fin-tube bundles is intensifying because of LME price volatility and Chinese import competition. Merchant power developers in ERCOT exhibit the highest price sensitivity, while oil and gas operators in sour gas service accept premium corrosion-resistant alloy specifications with minimal negotiation.
Supply Chain Analysis
Upstream feedstock supply for high-efficiency axial fans and precision fin-tube bundles draws from Germany, China, and the United States. Aluminum coil stock, copper tubing, and specialized axial fan motors constitute critical input dependencies. Single-source vulnerability concentrates in German axial fan production, where two manufacturers control premium efficiency segments. Distribution runs through EPC contractors and OEM balance-of-plant integrators rather than direct end-user procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air-cooled gas cooler procurement is approaching a platform-economics inflection as modular skidded architectures enable interoperability across gas turbine OEM ecosystems. Standardized interface specifications between cooler bundles and turbine balance-of-plant packages are collapsing field integration costs.
For Market Incumbents: Insulate installed-base positions by deepening predictive maintenance subscription penetration and securing exclusive thermal performance audit rights in legacy power stations. Aluminum price volatility and Chinese modular competition threaten margin stability in new equipment sales, making aftermarket service bundling the priority lever for revenue retention. For New Entrants and Emerging Players: Pursue retrofit conversion opportunities in water-cooled thermoelectric stations facing cooling tower replacement cycles, where incumbent relationships are weakest. Mining extraction corridors in Chile and Australia represent the most penetrable geography given water access constraints and limited established supplier presence. Partner with regional EPC contractors to bypass direct OEM qualification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular platform manufacturing as factory pre-assembly displaces field labor. Long-term viability favors suppliers with captive fin-tube production and established service infrastructures. Target acquisition profile centers on European engineering groups with legacy power station installed bases. The signal to watch is EPA Section 316(b) enforcement intensity in pending combined-cycle permitting decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Secures recurring revenue streams from ERCOT and CAISO merchant plant operators seeking uptime certainty. |
| Backward Integration into Fin-Tube Manufacturing | Reduces aluminum price exposure and compresses delivery timelines for modular skid assemblies. |
| Hybrid Cooler Adiabatic Pre-Cooling Module Development | Captures marginal climate projects where pure dry cooling underperforms during peak ambient conditions. |
| Retrofit Conversion Partnership with Regional EPCs | Accelerates market entry in legacy water-cooled plant replacement cycles without direct OEM competition. |
| EU F-Gas Regulation Compliance Certification | Opens specification windows for ammonia and CO2-based systems in European hydrocarbon processing applications. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Plant engineers at combined-cycle facilities, aftermarket service directors at major suppliers, EPC procurement leads, and environmental compliance officers at power utilities provided operational perspective. EPA cooling water intake structure permits, FERC interconnection filings, ISO 13706 mechanical design standards, and EIA thermoelectric water use data supplied external validation. Bottom-up project pipeline tracking and top-down installed base modeling were reconciled to establish volume baselines.
Calibration against historical replacement cycles and commodity price sensitivity bands informed the projection framework. Segmentation dimensions span product architecture, thermal duty intensity, installation configuration, and regional regulatory cluster. CAGRs were derived from equipment order backlogs, service contract renewal rates, and capacity expansion announcements across the analysis window. Aluminum and copper price elasticity assumptions, combined-cycle gas turbine commissioning schedules, and drought severity indices in southwestern US basins constitute industry-specific forecast inputs.
Sensitivities concentrate around EPA enforcement intensity, commodity price volatility, and modular platform adoption rates in retrofit applications. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution patterns. Cross-checking against EIA thermoelectric cooling water withdrawal benchmarks and utility capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Global Air Cooled Condenser Market