
 Flue Gas Coolers Market | 2026-2036
Flue Gas Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Flue Gas Coolers Market Foresight
Buyer concentration among utility companies is realigning procurement patterns across the flue gas coolers landscape. GEA Group leverages its plate heat exchanger expertise to sustain long-term service contracts with European power generators. Alfa Laval anchors its position through seawater-compatible cooling designs for coastal installations. Babcock & Wilcox Enterprises competes on boiler-integrated cooler packages that dominate North American retrofit cycles.
Flue gas coolers are heat exchange devices that recover thermal energy from exhaust streams, typically operating at inlet temperatures between 120°C and 350°C depending on upstream process configuration, and redirect that heat to preheat combustion air, feedwater, or district heating loops. Shell and tube configurations remain the installed base standard in power plants due to tolerance for particulate-laden streams, while plate heat exchanger technology captures growing share in chemical processing where compact footprint and modularity offset higher filtration requirements. Water-cooled systems occupy the largest value pool across steel mills and cement production, though hybrid designs are gaining traction in waste incineration where seasonal ambient variation demands operational flexibility.
EPA MATS compliance deadlines and EU F-Gas Regulation phase-down schedules are forcing utilities to validate cooler performance against tighter emission benchmarks, while China's MEE enforces ultra-low emission standards that mandate stack temperature reductions below 50°C in key industrial zones. ISO 13705 and ASME Section VIII pressure vessel codes govern material selection and welding protocols, creating certification barriers for non-compliant suppliers. Stakeholders must weigh thermal efficiency gains against corrosion risk from acid dew point excursions when specifying alloy grades for sour gas service.
Market Dynamics
Retrofit cycles across coal and waste-to-energy fleets are compressing procurement timelines as EPA MATS Phase II and EU Industrial Emissions Directive deadlines force simultaneous compliance upgrades. This regulatory synchronization concentrates buyer power among integrated utilities while fragmenting vendor access for project-specific awards.
Growth Catalysts
- EPA Mercury and Air Toxics Standards:Phase II compliance deadlines mandate stack temperature reductions below 75°C, forcing utilities to install secondary heat recovery systems ahead of 2028 enforcement windows.
- Waste-to-energy capacity expansion:Municipal solid gasification projects in Germany and the Netherlands specify flue gas coolers as mandatory pre-treatment for downstream scrubber efficiency.
- Corrosion-resistant alloy advances:Duplex stainless grades with enhanced sulfuric acid resistance extend service intervals in sour gas applications, reducing lifecycle cost barriers for retrofit economics.
Market Restraints
- Specialized alloy supply concentration:Super-duplex plate production concentrates among Scandinavian and Japanese mills, exposing EPC contractors to 16-24 week lead time volatility.
- Acid dew point engineering complexity:Sulfur trioxide condensation risk below 110°C limits low-temperature heat recovery in high-sulfur coal service without exotic metallurgy.
- Competing heat pump economics:Industrial-scale vapor compression systems achieve comparable COP in sub-150°C applications with lower capital intensity.
Strategic Opportunities
- India coal fleet upgrades:Central Electricity Authority mandates for 660MW supercritical retrofits create first-mover positioning for vendors with local fabrication partnerships.
- Hydrogen-ready boiler integration:Ammonia co-firing trials in Japanese power stations require modified cooler designs for altered flue gas moisture profiles.
- Digital twin commissioning:Physics-based performance modeling reduces startup risk for complex hybrid cooling configurations in seasonal waste incineration plants.
Industry Challenges
- Welding procedure qualification bottlenecks:ASME Section IX certification for exotic alloy joints extends fabrication schedules by 8-12 weeks at specialized shops.
- Legacy DCS integration complexity:Analog-era power plants lack I/O capacity for real-time cooler performance monitoring without costly control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flue Gas Coolers Market |
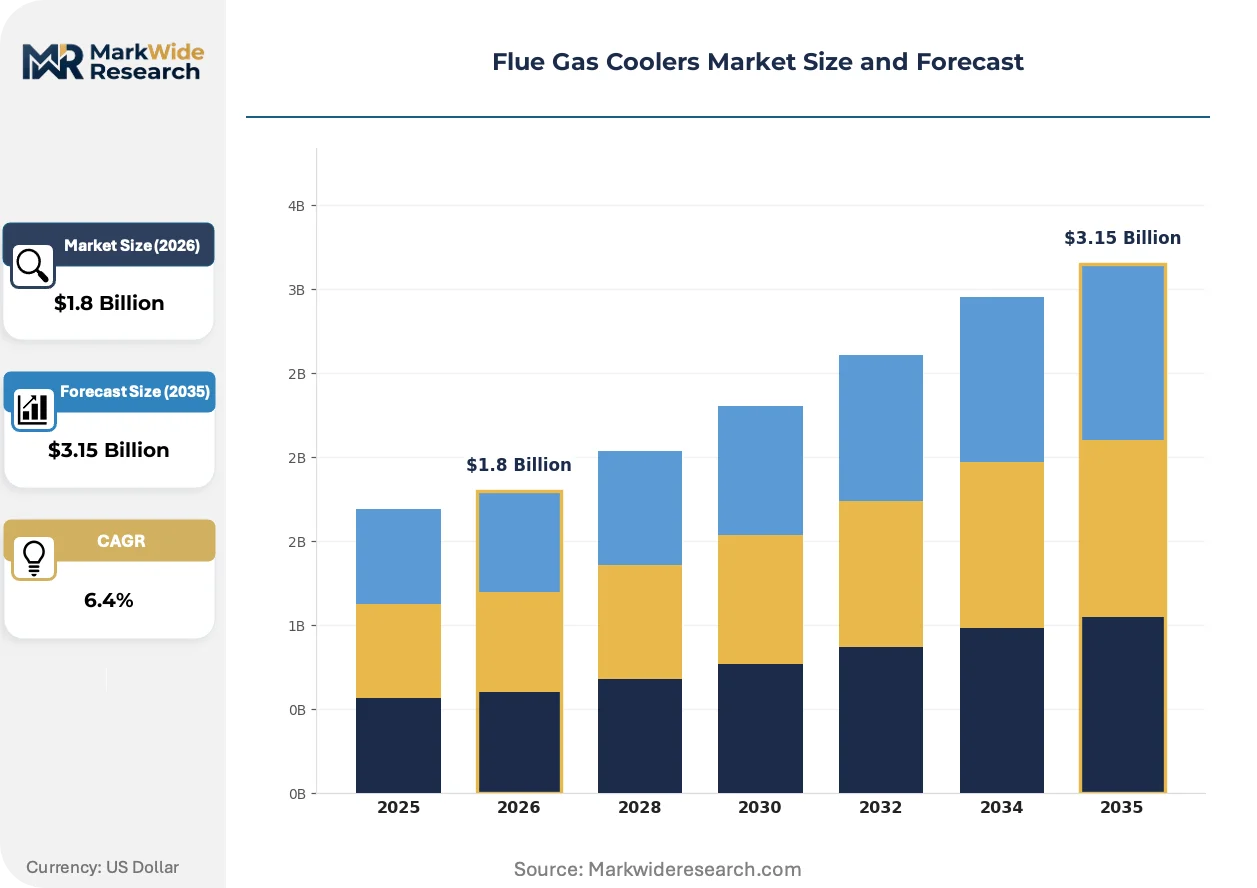
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Water-Cooled, Air-Cooled, Hybrid, Steam-Cooled, Evaporative Technology: Plate Heat Exchanger, Shell & Tube, Spiral Heat Exchanger, Finned Tube, Plate-Fin Application: Power Plants, Chemical Processing, Cement Production, Steel Mills, Waste Incineration End User: Utility Companies, Manufacturing Facilities, HVAC Contractors, Emission Control Firms, Energy Producers |
| Companies Covered | GEA Group, Alfa Laval, SPX Cooling Technologies, Hamon Group, Babcock & Wilcox Enterprises, Kelvion Holdings, Baltimore Aircoil Company, ENEXIO, Dürr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flue Gas Coolers Market Shifts & Advancements
Additive manufacturing of heat exchanger components is compressing prototyping cycles for optimized fin geometries. Vendors now iterate channel designs within weeks rather than months, accelerating field validation for next-generation compact units.
Printed circuit heat exchanger technology is rewriting thermal duty density benchmarks in chemical processing applications. Dow Chemical and BASF have piloted units achieving 4x surface area per volume against shell-and-tube baselines. This footprint reduction enables modular installation in congested refinery corridors where space constraints previously blocked heat recovery projects.
EU F-Gas Regulation phase-down schedules are accelerating adoption of ammonia and CO2 secondary refrigerants in hybrid cooling systems. The prohibition of high-GWP working fluids above 1500 GWP from 2030 forces redesign of intermediate loops in waste-to-energy plants. German operators E.ON and RWE are front-loading this transition to avoid stranded asset risk.
Utility procurement departments are unbundling after-sales service from equipment supply, creating standalone performance contracting opportunities. Long-term thermal efficiency guarantees now sit with specialized O&M providers rather than OEMs. This shift is most visible in the UK and Netherlands where power sector unbundling has separated asset ownership from operational control.
Flue Gas Coolers Market Segmentation
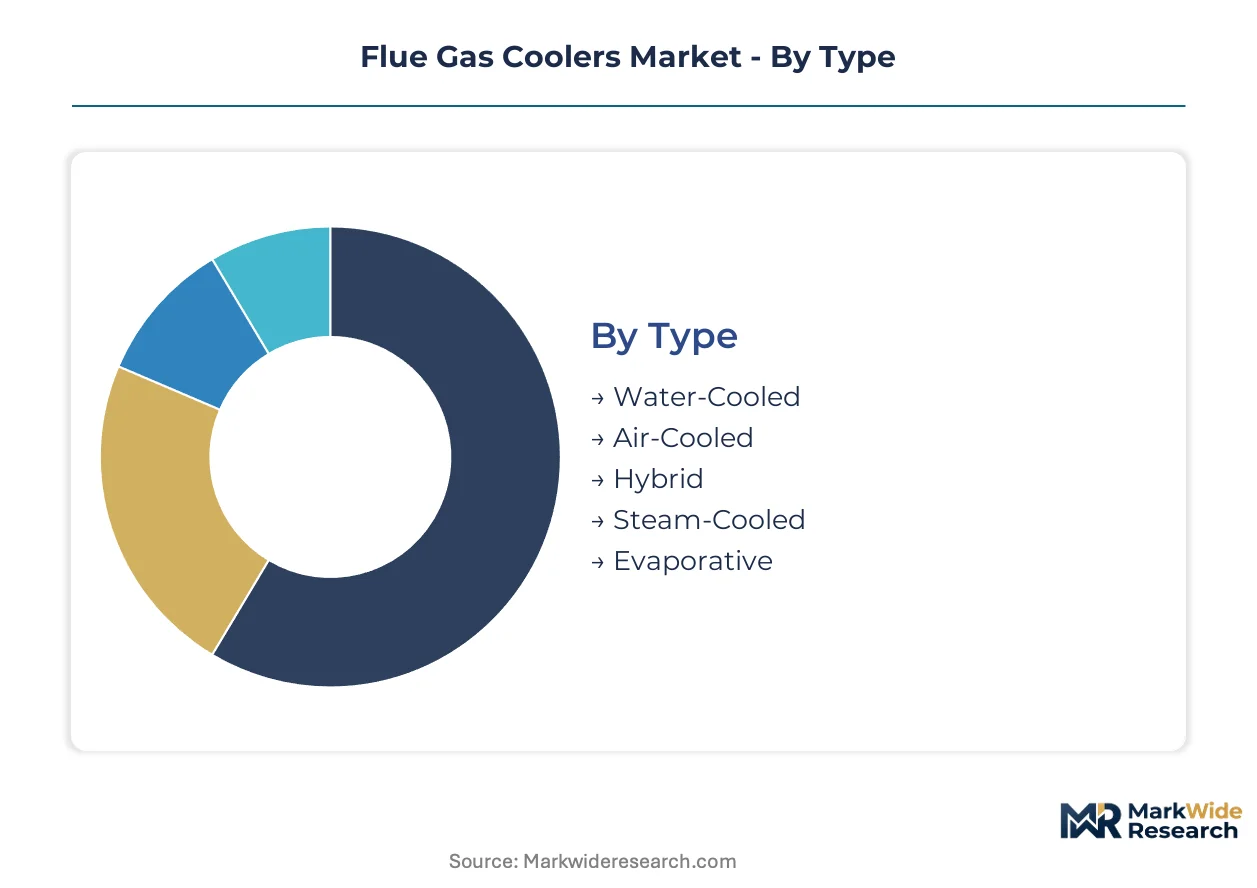
Flue gas cooler procurement patterns diverge sharply across cooling media, heat exchange architecture, and industrial application. Capital allocation decisions hinge on thermal duty requirements, particulate loading, and integration complexity with existing boiler island equipment.
Type:
Capital intensity varies dramatically across cooling media, with water-cooled systems demanding extensive civil works and hybrid configurations requiring dual heat rejection infrastructure.
- Water-Cooled:Closed-loop water circulation through shell-and-tube bundles handles the highest thermal loads in coal-fired power plants. China and India dominate procurement as utilities retrofit 660MW supercritical units ahead of MEE ultra-low emission deadlines.
- Air-Cooled:Finned tube arrays eliminate water consumption in arid regions, though larger footprint requirements limit deployment in congested European industrial zones. Demand concentrates in Australian mining corridors and Middle Eastern combined-cycle plants where water scarcity overrides efficiency penalties.
- Hybrid:Seasonal switching between air and water rejection optimizes performance in waste-to-energy plants with variable ambient conditions. German operators E.ON and RWE front-load procurement to meet EU F-Gas Regulation phase-down schedules.
- Steam-Cooled:Integrates with existing turbine cycle for maximum thermal integration in combined heat and power facilities.
- Evaporative:Delivers intermediate cost-positioning for chemical processing where moderate cooling loads meet water availability constraints.
Most installed capacity flows through water-cooled systems. Expansion is steepest in hybrid configurations.
Technology:
Footprint constraints and modularity requirements are fragmenting technology selection across end-use verticals.
- Plate Heat Exchanger:Compact stainless steel plate stacks achieve 3x surface density against shell-and-tube alternatives. Chemical processors at BASF and Dow Chemical specify units for congested refinery corridors where space constraints previously blocked heat recovery.
- Shell & Tube:Tolerance for particulate-laden flue gas sustains dominance in coal power retrofits despite larger footprint. Indian Central Electricity Authority mandates anchor procurement for 660MW supercritical upgrades.
- Spiral Heat Exchanger:Self-cleaning flow geometry suits high-fouling waste incineration streams.
- Finned Tube:Extended surface area compensates for poor air-side heat transfer coefficients in dry cooling applications.
- Plate-Fin:Aluminum brazed construction achieves lowest weight for offshore and modular installations.
Shell and tube configurations retain the largest installed base. Plate heat exchangers are climbing the fastest as chemical processors prioritize footprint reduction.
Application:
Regulatory enforcement calendars are synchronizing procurement waves across power generation and heavy industry.
- Power Plants:EPA MATS Phase II and EU Industrial Emissions Directive deadlines compress retrofit timelines for coal and waste-to-energy fleets. Stack temperature mandates below 75°C force secondary heat recovery installation ahead of enforcement windows.
- Waste Incineration:Municipal solid gasification projects in Germany and the Netherlands specify coolers as mandatory pre-treatment for downstream scrubber efficiency. Seasonal ambient variation drives hybrid cooling adoption.
- Chemical Processing:Printed circuit heat exchanger pilots at Dow Chemical and BASF validate 4x surface density improvements.
- Cement Production:Preheater exhaust recovery targets kiln efficiency improvements in European carbon border adjustment exposed facilities.
- Steel Mills:Sinter plant and coke oven gas cooling dominates procurement in Chinese integrated steel corridors.
Power plants anchor current demand volume. Waste incineration is gaining share fastest as European capacity expansion accelerates.
End User:
Procurement authority fragmentation is reshaping vendor engagement models across asset ownership structures.
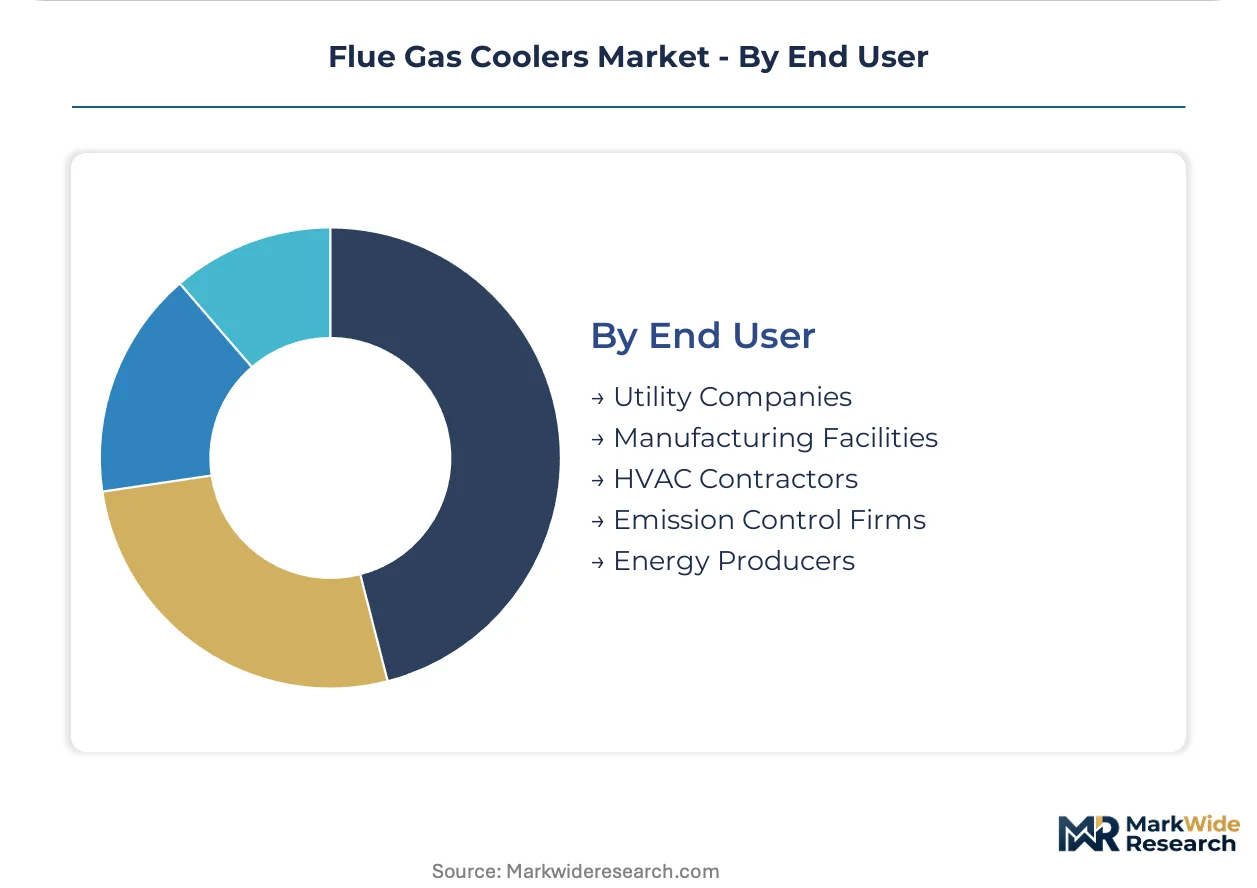
- Utility Companies:Integrated generators concentrate buyer power through multi-unit fleet standardization. Unbundling in UK and Netherlands separates asset ownership from operational control, shifting long-term performance guarantees to specialized O&M providers.
- Manufacturing Facilities:Cement and steel producers pursue captive heat recovery for carbon border adjustment compliance. Process integration complexity favors EPC contractors with sector-specific welding procedure qualifications.
- Energy Producers:Independent power developers specify modular packages for rapid deployment in emerging markets.
- Emission Control Firms:Specialist integrators bundle coolers with downstream scrubber and filtration systems.
- HVAC Contractors:Limited to ancillary building services integration in power plant auxiliary systems.
Utility companies direct the largest procurement volumes. Manufacturing facilities are expanding their share fastest as industrial decarbonization pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China pursue divergent procurement strategies for flue gas cooling infrastructure. German operators prioritize hybrid system retrofits under EU F-Gas Regulation timelines. Chinese utilities accelerate supercritical unit upgrades ahead of MEE ultra-low emission enforcement.
United States
Utility procurement concentrates on MATS Phase II compliance for coal fleet retrofits. EPA stack temperature mandates below 75°C drive secondary heat recovery installation ahead of 2028 deadlines. Texas and Ohio anchor demand as integrated generators standardize multi-unit cooler packages.
Germany
Waste-to-energy capacity expansion in municipal solid gasification projects specifies coolers as mandatory pre-treatment. EU Industrial Emissions Directive enforcement tightens stack requirements across existing incineration assets. E.ON and RWE operations in North Rhine-Westphalia front-load hybrid cooling transitions to avoid stranded asset risk.
China
Central Electricity Authority mandates for 660MW supercritical retrofits create procurement waves across provincial power bureaus. MEE ultra-low emission standards mandate stack temperature reductions below 50°C in key industrial zones. Yangtze River Delta steel corridors drive sinter plant and coke oven gas cooling demand.
India
Coal fleet upgrades concentrate procurement authority with NTPC and state gencos pursuing efficiency improvements. CEA technical specifications for supercritical retrofits require heat recovery system validation. Gujarat and Maharashtra industrial clusters anchor manufacturing facility captive heat recovery projects.
Netherlands
Waste incineration plant operators specify coolers for downstream scrubber efficiency optimization. EU F-Gas Regulation phase-down schedules force ammonia and CO2 secondary refrigerant redesigns. Rotterdam and Amsterdam port-industrial complexes concentrate hybrid cooling adoption for seasonal ambient variation management.
Flue Gas Coolers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement cycles. The vendor base clusters around three strategic archetypes: integrated boiler OEMs bundling cooler packages, dedicated heat transfer equipment fabricators, and emission control integrators unbundling aftermarket service. Consolidation pressure intensifies as utilities standardize fleet-wide specifications. Dominant competitive moves include welding procedure qualification investments and digital twin commissioning capability development.
Among European-based diversified industrial groups, GEA Group and Alfa Laval occupy positions representing plate heat exchanger specialization and long-term service contracting archetypes. Babcock & Wilcox Enterprises anchors the North American retrofit-focused tier. These three exemplify divergent strategic positioning: GEA Group and Alfa Laval leverage compact footprint technology for chemical processing and coastal power applications, while Babcock & Wilcox Enterprises represents boiler-integrated packaging dominance in utility procurement cycles.
| Leading Market Players |
|---|
| GEA Group |
| Alfa Laval |
| SPX Cooling Technologies |
| Hamon Group |
| Babcock & Wilcox Enterprises |
| Kelvion Holdings |
| Baltimore Aircoil Company |
| ENEXIO |
| Dürr |
| Others |
Supply & Pricing Matrix
Nickel alloy price indices from the London Metal Exchange cascade through flue gas cooler supply chains, compressing margins for EPC contractors sourcing super-duplex plate while amplifying pricing power for Scandinavian and Japanese mills with captive melt capacity. This raw material volatility stratifies procurement tiers: integrated boiler OEMs absorb cost swings through long-term offtake agreements, while project-specific bidders face quote validity windows as narrow as 30 days.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade shell-and-tube configurations, forcing European fabricators toward premium positioning. Three-tier pricing structure across super-duplex alloy, standard stainless, and carbon steel grades separates utility fleet contracts from chemical processing spot orders. Cost compression in the carbon steel tier intensifies because Indian mills are expanding plate rolling capacity. Independent power developers exhibit highest price sensitivity, while integrated utilities with multi-unit standardization programs trade volume for locked-in service rates.
Supply Chain Analysis
Refurbishment flows for spiral heat exchanger bundles create secondary material loops, with German and Dutch waste-to-energy operators returning fouled units to specialized reconditioning shops in Belgium and northern France. Super-duplex plate production concentrates in Sweden, Finland, and Japan, drawing from nickel ore feedstocks anchored in Indonesian and Philippine mining corridors. Single-source vulnerability persists for ASME Section IX-qualified welding consumables. Distribution runs through EPC contractor networks with direct mill relationships, bypassing traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European F-Gas Regulation compliance costs exceed Chinese MEE enforcement expenditures by a factor that rewards early relocation of fabrication capacity to Yangtze River Delta industrial zones.
For Market Incumbents: Cement long-term service contract renewal rates by embedding digital twin commissioning capabilities into standard equipment packages. Industrial heat pump vendors are eroding the sub-150°C heat recovery segment, making ASME Section IX certification investments the priority defensive lever. Backward integration into exotic alloy plate distribution secures margin protection against Scandinavian mill pricing power. For New Entrants and Emerging Players: Enter via India's 660MW supercritical retrofit wave, where CEA technical specifications create first-mover windows for fabricators with local welding procedure qualifications. Municipal solid gasification projects in the Netherlands represent the most penetrable white-space segment. A joint-venture model with established European emission control integrators accelerates reference plant acquisition without stranded certification costs. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play heat transfer specialists holding ASME and ISO 13705 dual certification, as utility fleet standardization pressures consolidate vendor lists. The five-to-ten year viability horizon favors targets with demonstrated hydrogen-ready boiler integration capabilities. Watch ammonia co-firing trial results from Japanese power stations as the inflection signal for altered flue gas moisture profile demand.| Strategic Initiative | Industry Significance |
|---|---|
| Welding Procedure Qualification Investment | ASME Section IX certification barriers protect incumbent margins against low-cost imports from uncertified shops. |
| Digital Twin Commissioning Capability | Physics-based modeling reduces startup risk for E.ON and RWE hybrid cooling configurations in seasonal plants. |
| Backward Integration into Alloy Distribution | Captive super-duplex plate sourcing insulates Babcock & Wilcox from 16-24 week lead time volatility at Japanese mills. |
| Hydrogen-Ready Design Modification | Ammonia co-firing trials at Japanese power stations require altered flue gas moisture handling specifications. |
| Long-Term Performance Contracting | Unbundled O&M guarantees in UK and Netherlands shift revenue streams from equipment sale to thermal efficiency outcomes. |
Research Methodology
Coverage spans Germany, China, India, the United States, and the Netherlands, with primary inputs from each market cluster combining interviews with utility planning officers, EPC contractor procurement leads, plant engineers at steel and cement facilities, and aftermarket service heads at heat transfer equipment fabricators. Secondary validation draws from EPA MATS enforcement calendars, EU Industrial Emissions Directive implementation reports, China MEE ultra-low emission zone designations, and customs data tracking nickel alloy plate trade flows. Bottom-up unit installation tracking triangulates against top-down power sector capex analysis.
Rate-of-change decomposition separates volume effects from price mix shifts across the projection horizon. Segmentation dimensions modeled include cooling media type, heat exchange architecture, application vertical, and regional regulatory framework cluster. CAGRs derive from regression against historical retrofit cycle timing and enforcement deadline proximity. Industry-specific forecast inputs incorporate CEA supercritical retrofit mandates and EU F-Gas Regulation phase-down schedules.
Inputs from EPA, EU ECHA, and China MEE regulatory filings were available through the study window; gaps in real-time alloy price index reporting introduce uncertainty bands around fabrication cost assumptions. Forecasts reflect documented assumptions about enforcement timeline adherence and technology substitution rates. Practitioners should monitor ammonia co-firing trial scale-up and industrial heat pump COP improvements for early signals of demand displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Process Chillers Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Global Chiller Market
Cooling Systems
Solar Fan Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
United States Heat Pump Market