
 Roll Bond Evaporator Market | 2026-2036
Roll Bond Evaporator Market Size, Share, and Industry Trends Forecast 2026-2036
Roll Bond Evaporator Market Analysis
ISO 9001 certification is redrawing competitive boundaries in the roll bond evaporator supply base. Bundy Refrigeration leverages its vertically integrated aluminum rolling and brazing operations to sustain cost leadership in bonded heat exchanger production. Kelong Group anchors its position through captive coil manufacturing and dominant share of Chinese refrigeration OEM supply chains. CGA differentiates via specialized tooling for custom roll bond profiles serving European appliance makers.
A roll bond evaporator consists of two aluminum sheets roll-bonded together with internal channels chemically etched to form refrigerant pathways, typically operating at pressures up to 25 bar and designed for direct expansion cooling circuits in commercial and domestic refrigeration. The commercial end user segment leads volume absorption, with food processing facilities driving replacement cycles amid stricter hygiene standards. Fixed installation types occupy the largest share of current deployment, though portable configurations are gaining traction in mobile cold storage and temporary pharmaceutical distribution.
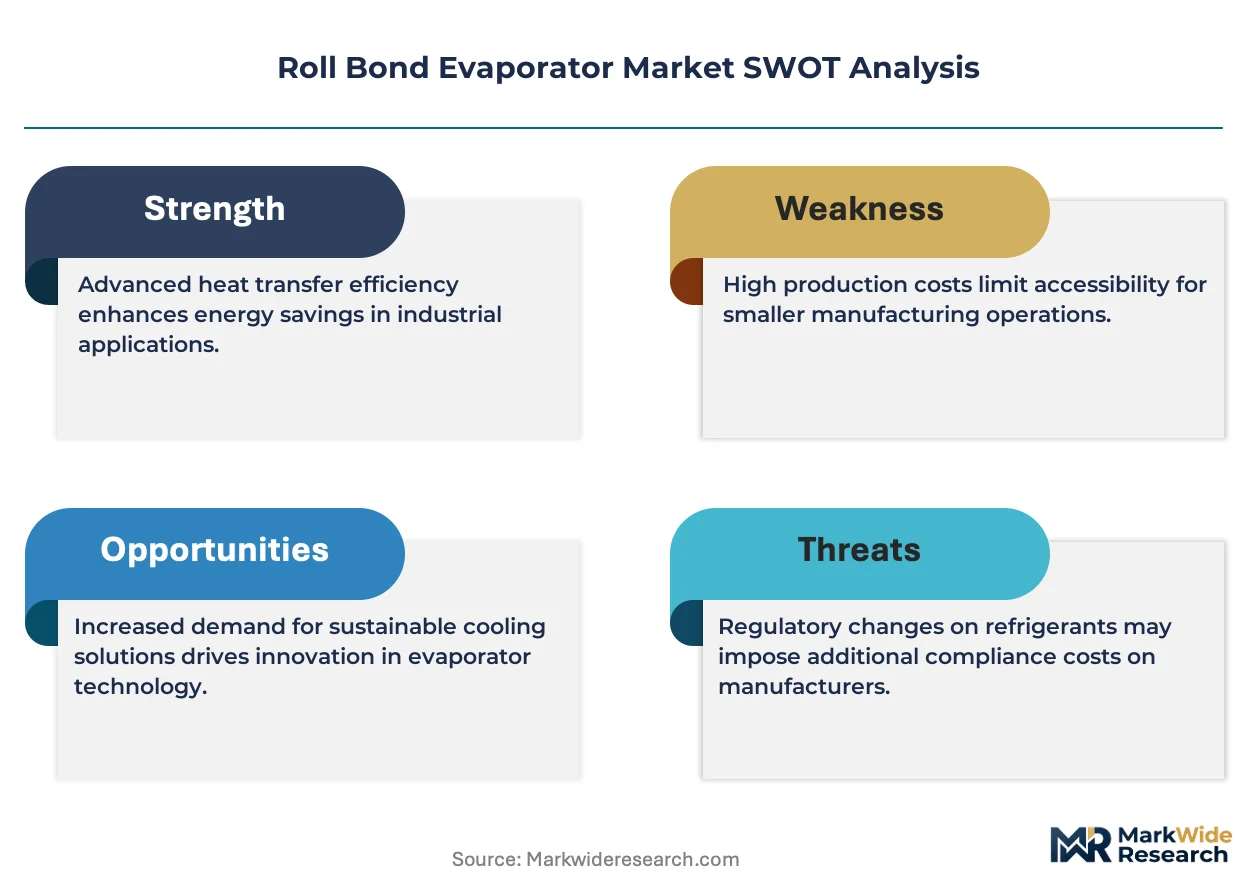
The US EPA SNAP program and EU F-Gas Regulation jointly constrain refrigerant choices, compelling evaporator redesigns for compatibility with propane and hydrofluoroolefin blends. China's GB standards for refrigeration safety and energy efficiency add compliance layers for export-oriented manufacturers. India's BIS certification requirements for cooling equipment components further fragment market access protocols. Stakeholders must weigh refrigerant transition timelines against capital commitments to roll bond tooling and channel geometries.
Market Dynamics
Refrigerant chemistry transition is compressing product lifecycles across the roll bond evaporator supply base, forcing simultaneous retooling for flammable refrigerant compatibility and pressure-rating upgrades. OEM procurement teams now specify dual-certification requirements before supplier qualification, tightening qualification windows from twenty-four to twelve months.
Growth Catalysts
- EU F-Gas Regulation phase-down schedules:The staged reduction in hydrofluorocarbon quotas accelerates equipment replacement cycles across European commercial refrigeration fleets. Cold chain operators front-load evaporator procurement to secure pre-2027 inventory.
- Food processing hygiene mandates:Stricter HACCP protocols in protein and dairy processing facilities drive replacement demand for corrosion-resistant aluminum roll bond designs. Facilities prioritize seamless internal channel geometries that eliminate bacterial harborage points.
- Mobile cold storage expansion:Pharmaceutical distribution networks deploy portable refrigerated containers for last-mile vaccine delivery. Roll bond evaporators with enhanced vibration resistance capture specification share in temporary cold chain infrastructure.
Market Restraints
- Aluminum sheet supply concentration:Primary aluminum rolling capacity clusters with Chinese state-owned metal producers. European and North American evaporator fabricators face input cost volatility and extended lead times during quota allocation periods.
- Pressure-rating technical ceilings:Conventional roll bond channel geometries encounter structural limits above thirty bar operating pressure. Carbon dioxide transcritical systems require alternative heat exchanger architectures that bypass roll bond construction.
- Refrigerant safety code fragmentation:Divergent national standards for hydrocarbon charge limits—Germany's DVGW requirements versus France's CSTB protocols—force SKU proliferation and inventory duplication.
Strategic Opportunities
- Indian cold chain infrastructure gaps:Post-harvest food loss rates exceeding sixteen percent create addressable demand for decentralized refrigeration. Roll bond evaporator suppliers can anchor early relationships with domestic cold storage developers before import substitution policies mature.
- Heat pump dryer convergence:Residential heat pump clothes dryers integrate compact roll bond evaporators for moisture extraction. Appliance OEMs in Italy and Poland source lightweight aluminum heat exchangers to meet energy-labeling tier upgrades.
- US IRA commercial refrigeration incentives:Tax credits for low-global-warming-potential equipment accelerate restaurant and supermarket retrofit timelines. Qualified roll bond designs compatible with R-290 propane capture specification preference in incentive-eligible procurement.
Industry Challenges
- Multi-refrigerant certification timelines:ISO 5149 and IEC 60335-2-89 testing protocols require sequential validation for each refrigerant chemistry. Engineering teams face eighteen-month validation queues that delay product launches.
- Etching chemistry supply reconfiguration:Traditional ferric chloride etchants face environmental discharge restrictions. Fabricators must qualify alternative chemistries—cupric chloride or hydrogen peroxide-sulfuric acid blends—without compromising channel dimensional tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll Bond Evaporator Market |
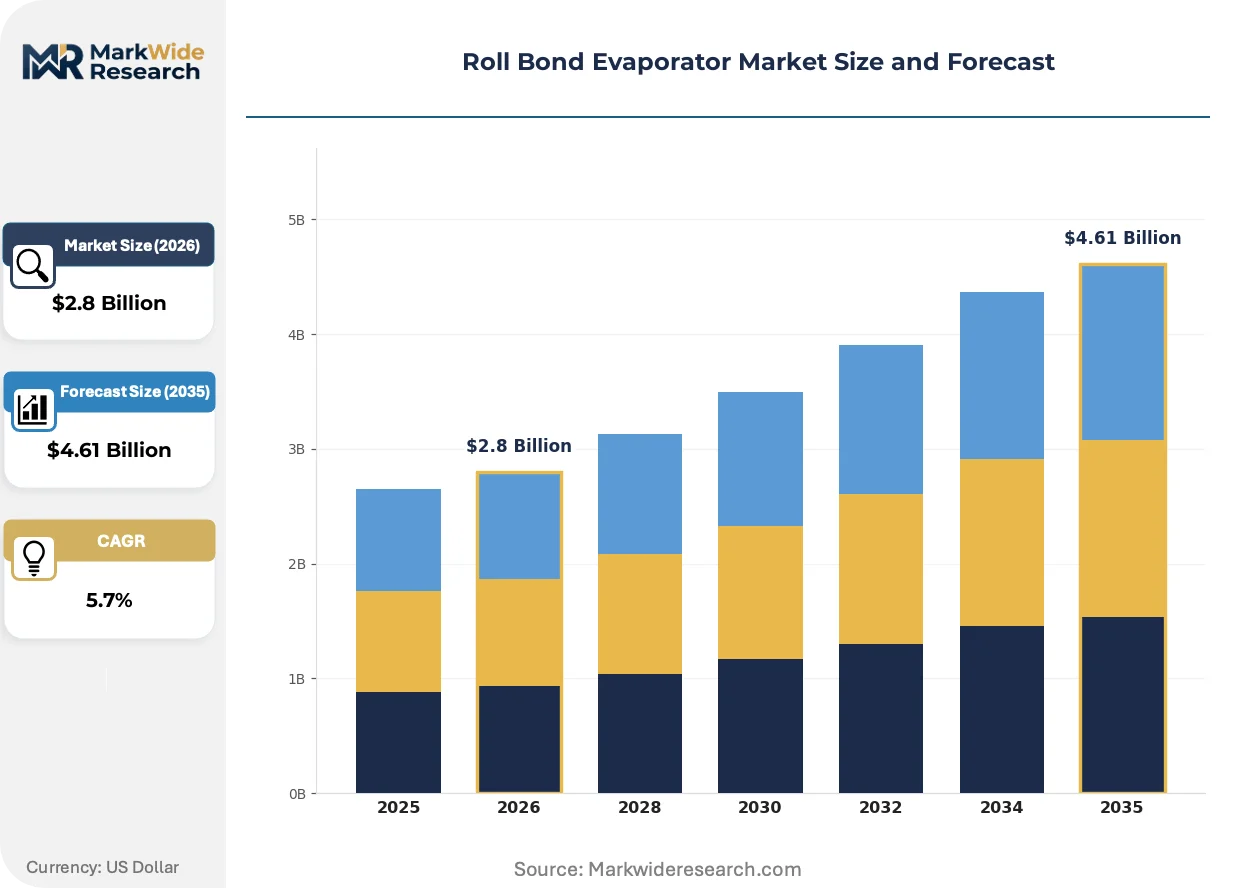
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
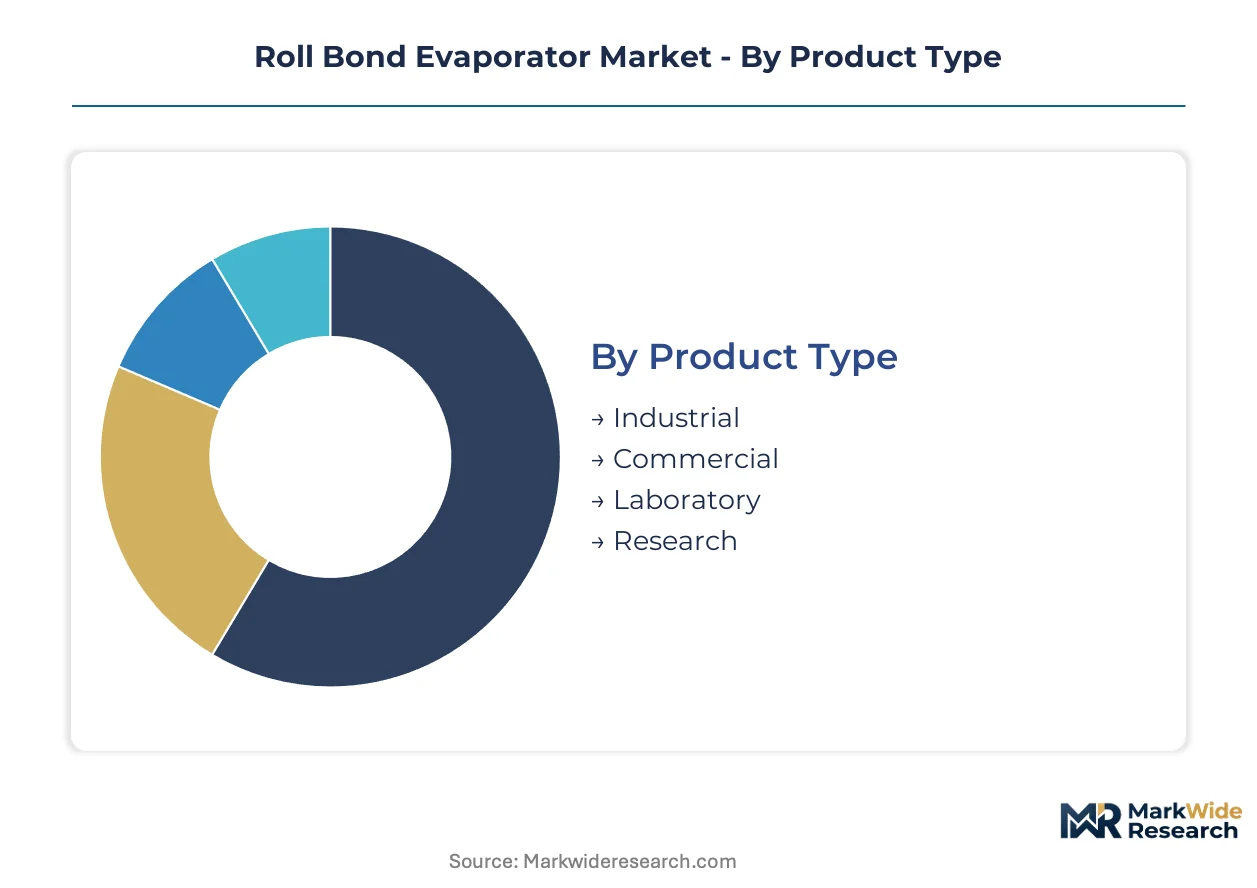
| Segmentation | Product Type: Industrial, Commercial, Laboratory, Research End User: Chemical Industry, Food Processing, Pharmaceutical, Beverage Installation Type: Fixed, Portable, Mobile, Custom-Made Size: Small, Medium, Large, Extra Large |
| Companies Covered | CGA, BRIGHT METAL, Kelong Group, Korel, Bundy Refrigeration, BMR HVAC, Changzhou Xinxin Refrigerating Equipment, Rubanox, Changzhou Changfa Refrigeration Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll Bond Evaporator Market Emerging Trajectories
Active innovation fronts in roll bond evaporator technology cluster around refrigerant compatibility architecture, precision manufacturing control, and modular system integration. Three developments currently reshape competitive positioning and procurement specifications.
Microchannel roll bond designs with sub-millimeter hydraulic diameters are bifurcating the market between premium precision-bonded products and conventional etched-channel alternatives. Medical refrigeration OEMs in Switzerland and Germany specify these geometries for ultra-low-temperature cascade systems. The technology compresses refrigerant charge volumes while enabling compatibility with flammable hydrofluoroolefin blends.
REACH authorization requirements for chromium trioxide in etching surface treatments are forcing chemistry transitions across European fabrication facilities. Suppliers must qualify trivalent chromium or chromium-free passivation layers without sacrificing bond strength or corrosion resistance. German appliance manufacturers now require full material disclosure documentation extending through tier-three suppliers.
Buyer consolidation among multinational cold chain operators is concentrating specification authority with centralized engineering teams. Regional equipment distributors lose influence as procurement committees at headquarters standardize evaporator designs across national fleets. This pattern is most visible in pharmaceutical logistics networks spanning Belgium, the Netherlands, and Germany.
Roll Bond Evaporator Market Segmentation
Roll bond evaporator procurement channels diverge sharply by segment. OEM appliance manufacturers source through long-term supply agreements, while cold chain operators and food processors rely on specialized distributors for replacement cycles.
Product Type:
Commercial-grade units move through dedicated HVAC-R distributors, whereas laboratory and research configurations channel through scientific equipment suppliers with validation documentation.
- Industrial:Heavy-duty aluminum roll bond constructions rated for continuous operation in large-scale refrigeration plants. Demand concentrates in German chemical manufacturing complexes upgrading to F-Gas-compliant systems. These facilities specify pressure-tested channels for ammonia and CO₂ secondary circuits.
- Commercial:Mid-capacity designs serving supermarket display cases and restaurant walk-in coolers. Food processing facilities in Poland and Italy drive replacement demand amid HACCP hygiene mandates. Operators prioritize seamless internal geometries that eliminate bacterial harborage.
- Laboratory:Precision-bonded units for controlled-environment scientific storage. Swiss pharmaceutical research institutes specify ultra-low-temperature cascade compatibility.
- Research:Custom-channel prototypes for experimental refrigerant evaluation. National laboratories in France and Germany commission small-batch production for next-generation cooling chemistry testing.
By volume, Commercial leads. By growth pace, Laboratory configurations are climbing the fastest.
End User:
Cost tier stratification separates premium pharmaceutical specifications from standard food service procurement, with chemical industry buyers occupying the mid-tier performance band.
- Chemical Industry:Corrosion-resistant roll bond arrays for process cooling and solvent recovery. BASF and Dow facilities in Ludwigshafen and Terneuzen specify nickel-plated channel variants for aggressive chemical environments. These buyers demand twenty-year service life guarantees.
- Food Processing:Hygienic-design evaporators for dairy, meat, and prepared meal cold chains. Danish Crown and FrieslandCampina operations prioritize CIP-compatible surface finishes and crevice-free channel geometries. Replacement cycles compress to seven years under intensified EU hygiene audits.
- Pharmaceutical:Validated units for GMP-compliant drug storage and distribution. Cold chain operators in Belgium and the Netherlands standardize designs across Benelux distribution networks.
- Beverage:High-capacity configurations for brewery fermentation control and soft drink bottling. Heineken and Carlsberg facilities in the Netherlands and Denmark source modular roll bond arrays for flexible production scaling.
Food Processing absorbs the greatest unit volume. Pharmaceutical applications show the steepest margin expansion trajectory.
Installation Type:
Application mobility requirements determine supply chain configuration, with fixed installations anchoring OEM relationships and portable units flowing through rental equipment channels.
- Fixed:Permanent-mount evaporators integrated into built-up refrigeration systems. German supermarket chains Edeka and Rewe standardize fixed roll bond specifications across national retrofit programs. These installations dominate replacement demand from pre-F-Gas equipment.
- Portable:Containerized units for temporary cold storage and event catering. Pharmaceutical logistics operators in Belgium deploy portable configurations for vaccine distribution surge capacity.
- Mobile:Vibration-resistant designs for refrigerated transport and field operations. Cold chain fleets serving Dutch flower auctions specify enhanced structural bonding for road stress tolerance.
- Custom-Made:Application-specific channel geometries for non-standard cabinet dimensions. Italian appliance OEMs commission custom profiles for premium refrigerator energy-label tier optimization.
Fixed installations command the largest installed base. Mobile configurations are gaining specification share fastest in transport refrigeration.
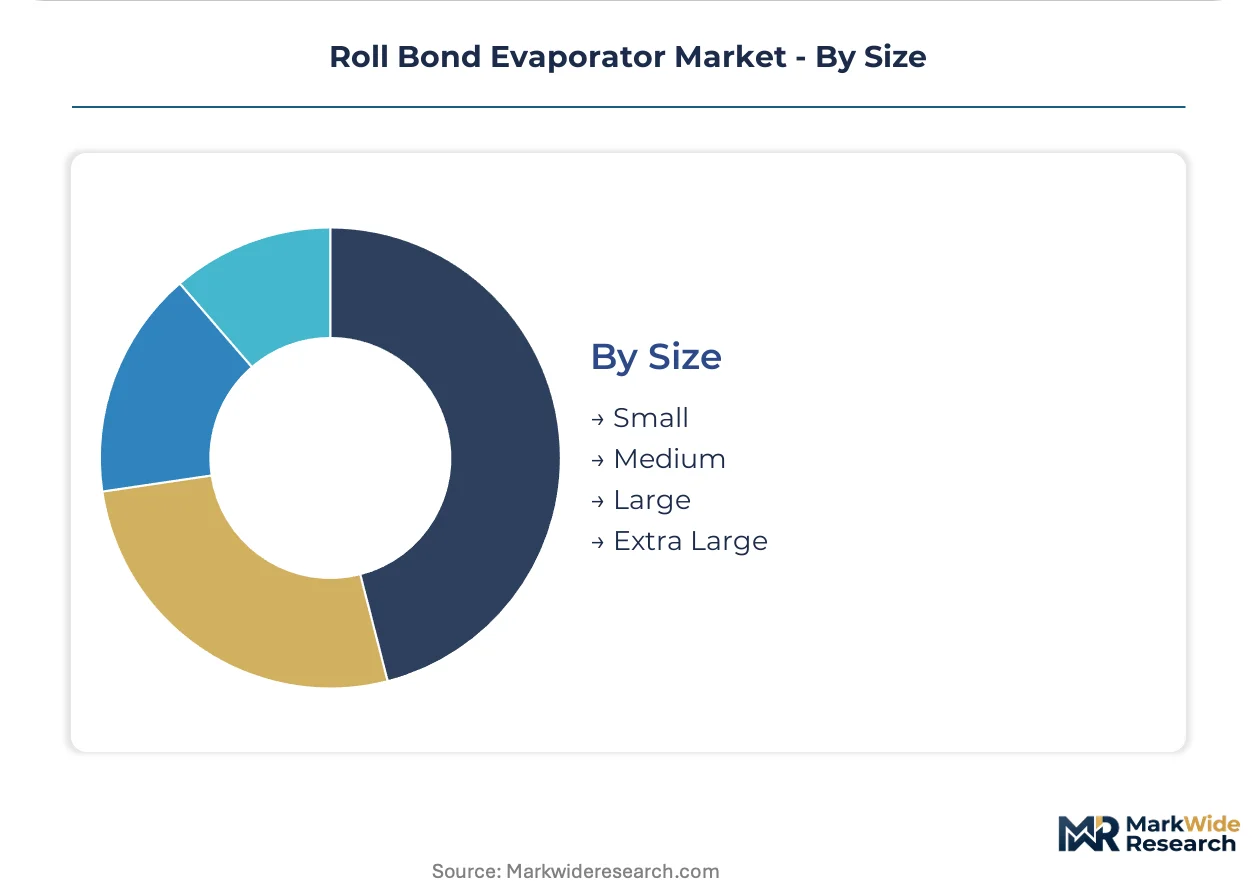
Size:
Customer type segmentation separates industrial-scale buyers seeking extra-large arrays from residential and light commercial operators sourcing small and medium units.
- Small:Compact roll bond cores for medical refrigerators and beverage coolers. German dental equipment manufacturers integrate these into practice-grade vaccine storage.
- Medium:Standard-capacity units for commercial kitchen equipment and retail display cases. Polish appliance OEMs source medium formats for EU energy-label A+++ product lines.
- Large:Extended-surface designs for warehouse cold storage and industrial process cooling. French logistics operator STEF deploys large roll bond arrays in automated frozen food distribution centers.
- Extra Large:Multi-circuit configurations for distribution hubs and centralized refrigeration plants. Dutch cold storage developer NewCold specifies extra-large units for automated high-bay warehouses.
Medium sizes lead in unit shipments. Extra Large formats show the strongest revenue-per-unit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure anchors European distribution networks for roll bond evaporator procurement. German appliance OEMs source precision-bonded aluminum heat exchangers through this logistics corridor. The Rhine-Alpine rail freight corridor connects aluminum rolling mills to fabrication clusters across the continent.
Germany
Supermarket retrofit programs at Edeka and Rewe drive fixed-installation demand for F-Gas-compliant systems. The EU F-Gas Regulation phase-down compels equipment replacement before 2027 quotas tighten. Bavarian industrial zones host appliance manufacturing clusters where OEMs specify precision-bonded channels for energy-label optimization.
United States
Restaurant and supermarket operators accelerate retrofit timelines under IRA commercial refrigeration tax credits. EPA SNAP program constraints on hydrofluorocarbon refrigerants reshape evaporator specifications. Midwestern cold storage developers deploy large-format roll bond arrays in automated distribution centers near Chicago logistics hubs.
China
Domestic refrigeration OEM supply chains concentrate procurement through captive coil manufacturers. GB standards for refrigeration safety and energy efficiency add compliance layers for export-oriented fabricators. Yangtze River Delta industrial zones integrate aluminum rolling with brazing operations for cost-optimized production.
India
Post-harvest food loss exceeding sixteen percent creates addressable demand for decentralized cold storage infrastructure. BIS certification requirements for cooling equipment components fragment market access protocols. Gujarat and Maharashtra states attract early supplier relationships before import substitution policies mature.
Netherlands
Pharmaceutical logistics operators standardize evaporator designs across Benelux distribution networks. Cold chain fleets serving Dutch flower auctions specify vibration-resistant configurations for road stress tolerance. The Port of Rotterdam's refrigerated container throughput supports mobile configuration deployment for vaccine distribution surge capacity.
Roll Bond Evaporator Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The supply base fragments between vertically integrated aluminum processors and specialized fabrication houses. Three archetypes dominate: captive coil manufacturers serving domestic OEM chains, precision-bonding specialists targeting European appliance makers, and diversified HVAC-R component suppliers. Consolidation pressure manifests through backward integration into aluminum rolling and strategic partnerships for refrigerant compatibility testing.
Among European-based fabricators, CGA exemplifies the precision-specialist archetype through its tooling capabilities for custom roll bond profiles. Bundy Refrigeration anchors the vertically integrated tier with in-house aluminum rolling and brazing operations. Kelong Group occupies a position within the captive-supply archetype, serving Chinese refrigeration OEM chains through dominant coil manufacturing share.
| Leading Market Players |
|---|
| CGA |
| BRIGHT METAL |
| Kelong Group |
| Korel |
| Bundy Refrigeration |
| BMR HVAC |
| Changzhou Xinxin Refrigerating Equipment |
| Rubanox |
| Changzhou Changfa Refrigeration Technology |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between European appliance OEMs and aluminum rolling mills lock in both primary metal access and eighteen-month price visibility, insulating fabricators from spot volatility while committing capital to dedicated channel geometries. These contracts concentrate procurement power with vertically integrated specialists who can guarantee F-Gas-compliant refrigerant compatibility across contract durations.
Pricing Analysis
Volume-discount tiering structures separate annual procurement commitments above ten thousand units from spot purchases and project-based custom orders. ISO 9001 certification and dual-refrigerant validation status command measurable premiums over single-chemistry alternatives. Cost compression in standard commercial-grade products intensifies as Chinese captive coil manufacturers extend export pricing into European distributor channels. Food processing facilities demonstrate highest price sensitivity due to compressed replacement cycles, while pharmaceutical cold chain operators absorb premiums for validated documentation packages.
Supply Chain Analysis
China anchors primary aluminum rolling and captive coil manufacturing, with Germany and Italy hosting precision-bonding fabrication for European appliance OEMs. The supply chain draws from aluminum sheet, ferric chloride etching chemistry, and brazing alloy inputs. Single-source vulnerability concentrates in Chinese state-owned metal producers during quota allocation periods. Distribution runs through dedicated HVAC-R distributors for commercial replacement cycles and direct OEM supply agreements for original equipment integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment—specifically multi-refrigerant certification requirements—creates eighteen-month validation barriers that protect qualified incumbents from rapid displacement.
For Market Incumbents: Fortify certification portfolios by accelerating IEC 60335-2-89 validation for propane-compatible designs before EU F-Gas quotas tighten. Deepen upstream control over aluminum rolling capacity in Germany to offset Chinese input volatility. Threat substitution from microchannel heat exchangers in CO₂ transcritical applications demands preemptive R&D positioning in alternative geometries. For New Entrants and Emerging Players: After-sales technical support for multi-refrigerant retrofit guidance represents the most penetrable service-layer gap, as incumbent fabricators under-serve independent cold chain operators navigating chemistry transitions. Target Indian decentralized cold storage developers before BIS certification requirements mature into import substitution barriers. Lead with bundled validation documentation and field engineering support rather than price competition. For Investors and Strategic Acquirers: Capital is best deployed toward precision-bonding specialists with established European appliance OEM relationships and captive etching chemistry capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch for inflection signals in Indian cold storage policy implementation and US IRA incentive utilization rates as demand pull-through indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Refrigerant Certification Investment | IEC 60335-2-89 validation for R-290 propane compatibility captures IRA-eligible procurement preference. |
| Backward Integration into Aluminum Rolling | German fabricators secure input cost stability against Chinese quota volatility. |
| Custom Profile Tooling Expansion | Italian appliance OEMs commission application-specific channel geometries for energy-label optimization. |
| Indian Market Development Partnership | Gujarat cold storage developers anchor early relationships before BIS localization mandates. |
| Etching Chemistry Transition | REACH-compliant cupric chloride qualification avoids chromium trioxide authorization delays. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with refrigeration OEM procurement directors, cold chain engineering managers, and HVAC-R distributor category buyers; and secondary validation through SEC filings of listed component suppliers, EU F-Gas Regulation implementation reports, and customs trade data for aluminum heat exchanger categories. Bottom-up unit demand modeling triangulated against top-down market sizing from appliance production forecasts and cold chain infrastructure investment disclosures.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, end-use industry, installation configuration, and regional regulatory cluster. CAGRs derived from segment-specific growth drivers including refrigerant transition timelines, hygiene mandate enforcement intensity, and cold chain infrastructure gap closure rates. Industry-specific inputs incorporated F-Gas quota phase-down schedules and IRA incentive program utilization assumptions.
Underlying assumptions cover refrigerant chemistry adoption curves and aluminum price band stability, with deviation risk concentrated in regulatory enforcement timing and Indian import substitution policy acceleration. Recalibration cycles align with material shifts in EU F-Gas implementation and US EPA SNAP program revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Solar Fan Market
Cooling Systems
Air to Air Heat Pumps Sales Market