
 Concentrated Photovoltaic System Market | 2026-2036
Concentrated Photovoltaic System Market Size, Share, and Industry Trends Forecast 2026-2036
Concentrated Photovoltaic System Market Outlook
Direct sales channels between cell manufacturers and utility-scale EPC contractors is reconfiguring procurement patterns across the concentrated photovoltaic value chain. SolAero Technologies Corp. leverages its heritage in space-grade multi-junction cells to command premium positioning in terrestrial HCPV deployments. Sumitomo Electric Industries Ltd. anchors downstream module assembly through disciplined backward integration into III-V epitaxy. Soitec competes on wafer-bonding intellectual property that enables lattice-engineered substrates for next-generation cells.
Concentrated photovoltaic systems deploy optical elements—Fresnel lenses, parabolic dishes, or reflective assemblies—to focus sunlight onto small-area, high-efficiency multi-junction cells achieving conversion efficiencies above 40 percent under direct normal irradiance. These systems require dual-axis tracking and clear-sky conditions, restricting commercial viability to arid and semi-arid zones with annual direct normal irradiance exceeding 2,000 kWh per square meter. HCPV technology dominates the premium tier where land constraints and high insolation justify capital intensity, while utility-scale application segments absorb the majority of installed capacity as developers optimize levelized cost of energy through scale economies. Off-grid applications occupy a narrower niche where diesel displacement economics prove favorable in remote mining and telecommunications installations.
FERC interconnection standards and state-level renewable portfolio obligations in the United States shape grid-access pathways for concentrated solar assets, while the EU Green Deal and delegated acts under the Renewable Energy Directive establish sustainability criteria for module imports into European markets. China's MIIT governs domestic manufacturing standards for concentrating solar equipment through GB certification protocols that constrain foreign supplier participation. Stakeholders must monitor evolving carbon border adjustment mechanisms and country-of-origin rules that threaten to fragment supply chains optimized for free trade in germanium wafers and precision glass optics.
Market Dynamics
Dual-axis tracking architectures are compressing system-level costs while III-V multi-junction cell efficiency gains tighten germanium substrate supply chains, redirecting procurement from conventional flat-panel PV toward concentrated architectures in high-insolation zones.
Growth Catalysts
- NEOM Clean Energy Procurement:Saudi Arabia's government-backed procurement mandates are redirecting capital toward high-concentration systems in desert corridors with optimal direct normal irradiance.
- III-V Epitaxy Advances:Lattice-matched multi-junction cell architectures are achieving conversion efficiencies above 40 percent under concentrated illumination, tightening supply-demand balances for precision substrates.
- FERC Interconnection Standards:Streamlined grid-access pathways in the United States are reducing permitting friction for utility-scale concentrated solar assets.
Market Restraints
- Germanium Substrate Concentration:Supply chains for lattice-engineered germanium wafers concentrate among a limited supplier base, creating input cost volatility and allocation risk.
- Clear-Sky Dependency:HCPV systems require annual direct normal irradiance exceeding 2,000 kWh per square meter, restricting commercial viability to arid zones and excluding humid subtropical markets.
- Dual-Axis Capex Intensity:Precision tracking mechanics and optical assemblies impose capital costs that flat-panel PV undercuts in moderate-insolation regions.
Strategic Opportunities
- Al Dhafra Utility Clusters:The UAE's government-backed clean energy procurement is creating concentrated demand pockets for high-efficiency systems in the Middle East.
- Carbon Border Adjustment Mechanisms:Evolving EU sustainability criteria under delegated acts of the Renewable Energy Directive are favoring traceable supply chains for precision glass optics and III-V materials.
- Remote Mining Diesel Displacement:Off-grid HCPV installations are capturing niche economics in telecommunications and extractive operations where fuel logistics dominate levelized costs.
Industry Challenges
- Multi-Junction Cell Fabrication Talent:Epitaxial growth and wafer-bonding expertise for III-V materials concentrates among space-grade heritage facilities, constraining terrestrial capacity expansion.
- GB Certification Protocols:China's MIIT domestic manufacturing standards for concentrating solar equipment create compliance friction for foreign precision-optic and tracking-system suppliers.
- Supply Chain Reconfiguration:Country-of-origin rules and carbon border mechanisms are fragmenting optimized free-trade flows in germanium wafers and Fresnel lens assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concentrated Photovoltaic System Market |
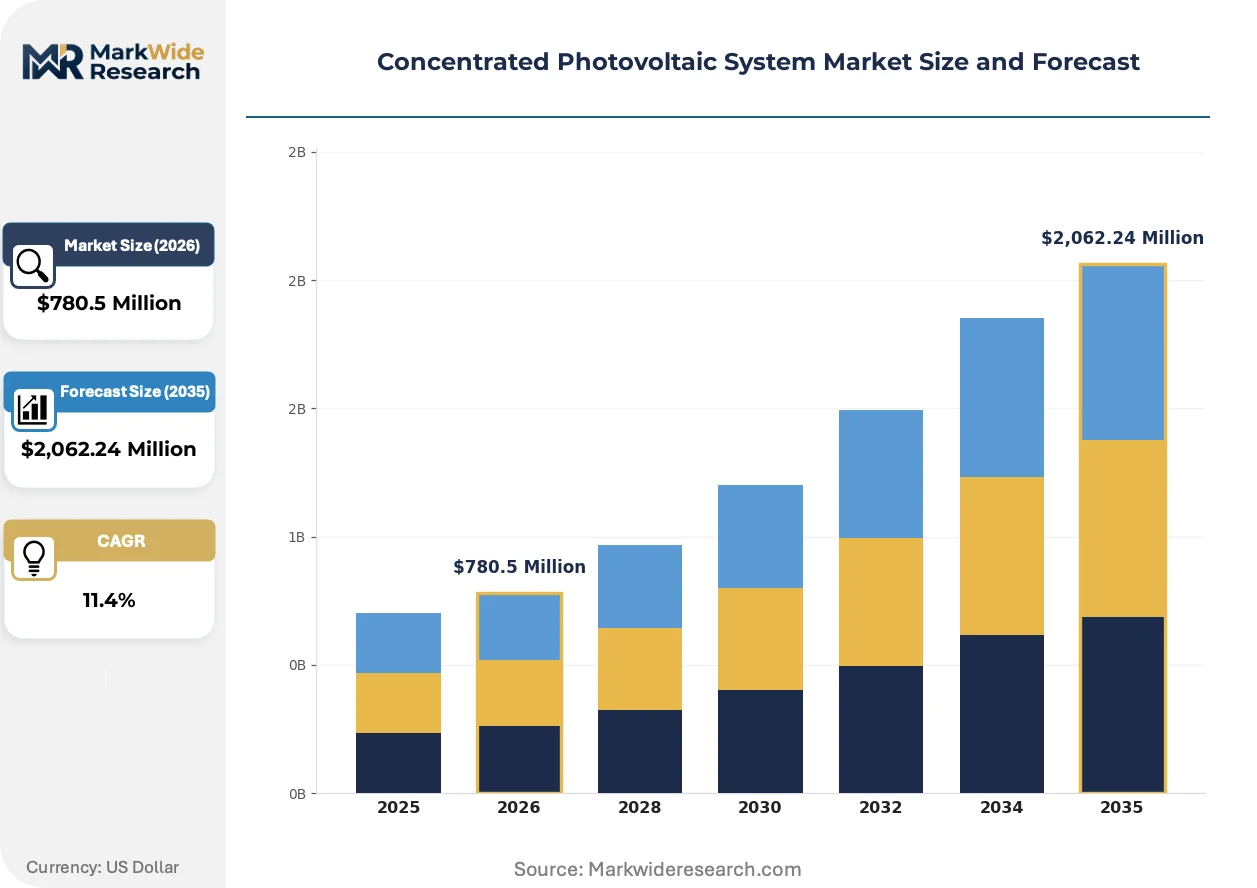
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $2,062.24 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fresnel Lens, Parabolic Dish, HCPV, Optical Concentrators Application: Utility Scale, Commercial, Residential, Off-Grid End User: Energy Providers, Industrial Users, Residential Users, Government Installation: Ground Mounted, Rooftop, Hybrid Systems, Portable |
| Companies Covered | Radical Sun Systems Inc., SolAero Technologies Corp., Arzon Solar LLC, Cool Earth Solar, Morgan Solar Inc., Suncore Photovoltaic Technology Company Limited, Sumitomo Electric Industries Ltd., Soitec, Amonix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concentrated Photovoltaic System Market Strategic Shifts
Active digitization of tracking control systems and cell-level performance monitoring is reshaping operational architectures, while regulatory sustainability mandates and procurement model evolution compress traditional value chain structures.
Metamorphic buffer layer engineering on germanium substrates is enabling higher-bandgap cell architectures without lattice-matching constraints. Utility-scale EPC contractors in Saudi Arabia and the UAE are adopting these substrates for next-generation field deployments. This materials innovation is digitizing performance telemetry at the cell-string level, enabling predictive maintenance algorithms that compress operational expenditure structures.
The EU Green Deal's delegated acts under the Renewable Energy Directive are establishing lifecycle carbon-intensity thresholds for module imports into European markets. Manufacturers must now document embodied emissions across germanium mining, III-V epitaxy, and precision glass molding stages. HCPV system integrators targeting European utility tenders are responding by securing auditable supply chains through captive substrate production or long-term offtake agreements with certified refiners.
Direct contracting between cell manufacturers and utility-scale developers is disintermediating traditional module distributor channels. Procurement teams at Saudi Aramco and Emirates Water and Electricity Company are negotiating multi-year supply agreements that bundle cell supply with tracking-system integration services. This channel compression is most visible in the Middle East, where government-backed procurement vehicles favor single-source accountability over fragmented vendor management.
Concentrated Photovoltaic System Market Segmentation
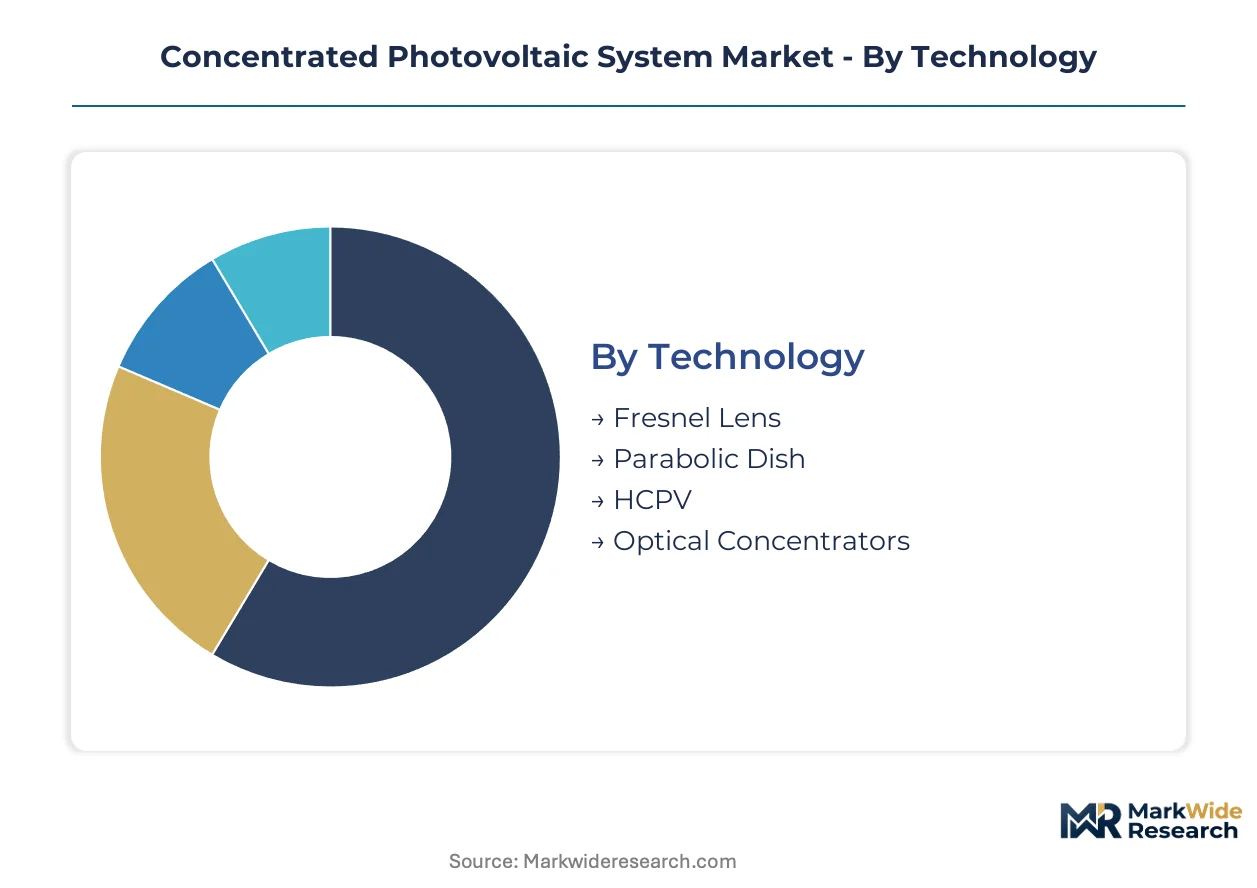
Segmentation in concentrated photovoltaic systems reveals how capital intensity, tracking complexity, and irradiance requirements fragment procurement patterns across customer archetypes. Each dimension exposes distinct margin structures and service dependencies that reshape vendor positioning.
Technology:
After-sales service intensity varies sharply across optical architectures, with precision tracking systems demanding predictive maintenance contracts and remote diagnostics capabilities.
- HCPV:High-concentration systems deploy III-V multi-junction cells under dual-axis tracking to achieve conversion efficiencies above 40 percent. Procurement concentrates among Saudi Aramco and Emirates Water and Electricity Company tenders in the Middle East, where land constraints and optimal direct normal irradiance justify capital intensity.
- Fresnel Lens:Flat-grooved optical elements focus sunlight onto small-area receivers with lower cost structures than dish architectures. Demand clusters in utility-scale deployments across Spain and the southwestern United States, where mature EPC contractor networks streamline installation logistics.
- Parabolic Dish:Curved reflective surfaces achieve high concentration ratios with modular, scalable footprints. Remote mining operations in Australia and Chile deploy these systems for off-grid diesel displacement.
- Optical Concentrators:Reflective and refractive assemblies channel diffuse and direct irradiance onto photovoltaic receivers. Experimental deployments in Japan's NEDO research programs test hybrid concentration approaches.
By volume, Fresnel Lens leads. By growth pace, HCPV is ahead.
Application:
Capital deployment cycles and offtake contract durations segment procurement economics, with utility-scale buyers negotiating decade-long power purchase agreements that reshape vendor cash flow profiles.
- Utility Scale:Grid-connected installations exceeding 10 MW capacity dominate capacity additions through Saudi Arabia's NEOM corridor and the UAE's Al Dhafra region. Government-backed clean energy procurement mandates redirect capital from conventional flat-panel PV toward concentrated architectures in high-insolation zones.
- Off-Grid:Standalone systems displace diesel generation in telecommunications towers and extractive operations. Remote Australian mining camps and Chilean copper belt installations capture favorable levelized cost economics where fuel logistics dominate operational expenditure.
- Commercial:Behind-the-meter installations serve industrial facilities with high daytime load profiles. Limited penetration reflects tracking infrastructure requirements and clear-sky dependency constraints.
- Residential:Rooftop and ground-mounted systems for individual consumers remain commercially marginal. Dual-axis mechanics and optical precision exceed cost thresholds for distributed generation markets.
Utility Scale commands installed capacity. Off-Grid climbs the fastest.
End User:
Procurement sophistication and technical specification authority fragment across buyer types, with government vehicles imposing sustainability auditing requirements that reshape supplier qualification protocols.
- Energy Providers:State-owned utilities and independent power producers negotiate bundled supply agreements combining cell procurement with tracking-system integration. Saudi Aramco and Emirates Water and Electricity Company contracts disintermediate traditional module distributor channels.
- Government:Sovereign procurement vehicles under the EU Green Deal establish lifecycle carbon-intensity thresholds for module imports. Delegated acts under the Renewable Energy Directive mandate traceable supply chains through germanium mining and III-V epitaxy stages.
- Industrial Users:Mining conglomerates and telecommunications operators deploy off-grid systems where diesel displacement economics prove favorable. Remote site logistics dominate procurement criteria over grid-interconnection standards.
- Residential Users:Individual consumers represent minimal commercial presence. Tracking complexity and capital intensity exclude this segment from viable addressable markets.
Energy Providers absorb capacity. Government procurement is expanding most quickly.
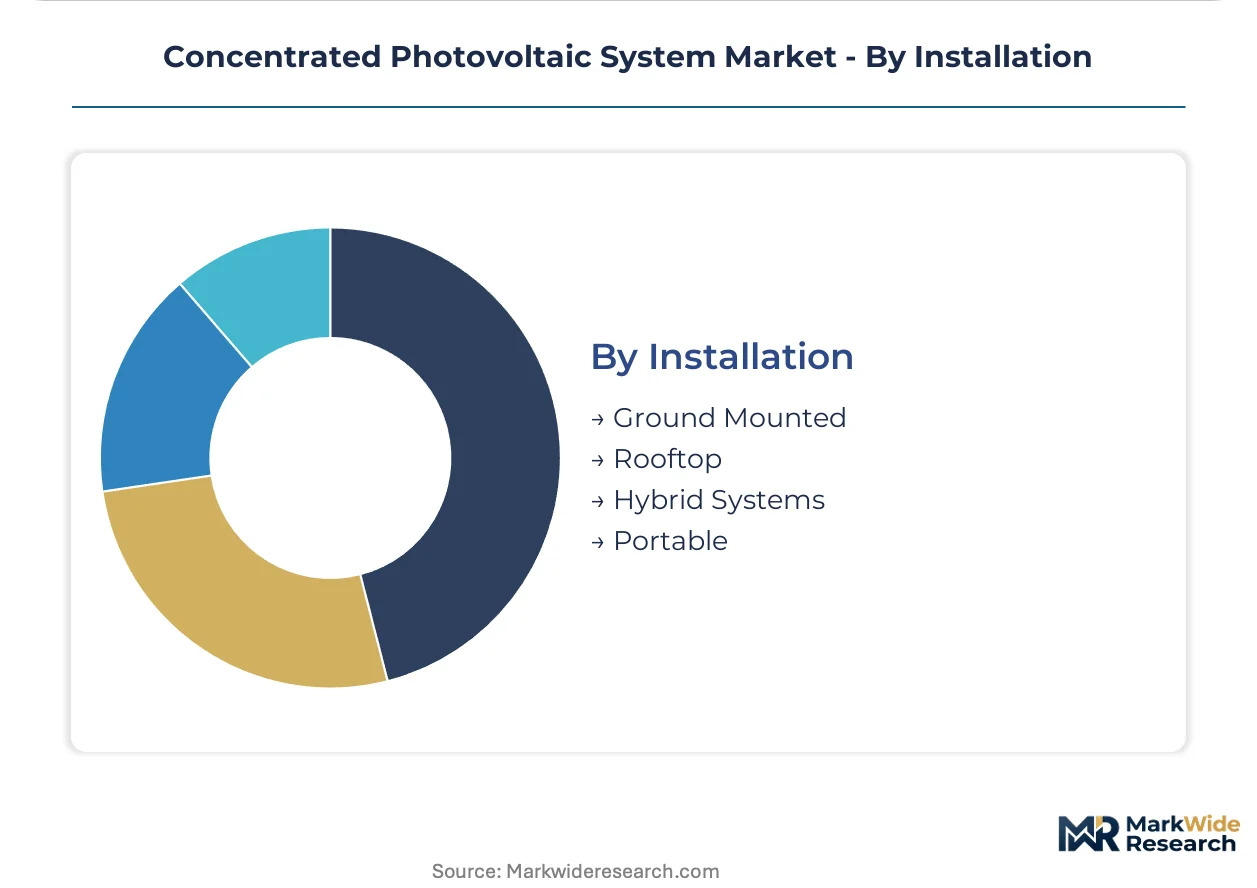
Installation:
Site preparation requirements and civil engineering intensity segment project economics, with ground-mounted systems demanding geotechnical surveys that rooftop configurations circumvent.
- Ground Mounted:Fixed and tracking structures on prepared terrain accommodate utility-scale capacity. Saudi Arabia's desert corridors and the UAE's Al Dhafra region favor dual-axis tracking architectures with precision foundation engineering.
- Hybrid Systems:Combined concentrating and flat-panel configurations optimize output across variable irradiance conditions. Experimental deployments in Japan test grid-stabilization capabilities.
- Rooftop:Building-integrated and building-applied systems face structural load and tracking mechanics constraints. Minimal commercial deployment reflects weight and wind-loading limitations.
- Portable:Deployable units for military and emergency response applications. Niche demand from defense procurement programs in the United States tests ruggedized optical and tracking assemblies.
Ground Mounted dominates deployment. Hybrid Systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection standards anchor procurement pathways in the United States, while government-backed clean energy mandates in Saudi Arabia and the UAE redirect capital toward high-concentration architectures. Desert insolation conditions across multiple geographies favor dual-axis tracking deployments.
Saudi Arabia
NEOM corridor tenders and Saudi Aramco procurement vehicles drive utility-scale HCPV demand. The country's renewable energy program mandates traceable supply chains for III-V materials. Al Dhafra-adjacent desert zones host dual-axis tracking clusters serving government-backed clean energy offtake.
United States
Southwestern utilities and remote mining operators deploy Fresnel lens and parabolic dish configurations. FERC Order 2023 streamlines interconnection queues for concentrated solar assets. California's Imperial Valley and Arizona's Sonoran Desert host experimental high-concentration pilots testing metamorphic buffer substrates.
United Arab Emirates
Emirates Water and Electricity Company bundles cell procurement with tracking-system integration. MOHAP and federal energy regulators establish sustainability auditing for module imports. Al Dhafra region concentrates government-backed procurement creating demand pockets for premium-tier systems.
China
Domestic MIIT GB certification protocols constrain foreign supplier participation in concentrating solar equipment. State-owned utilities pilot hybrid concentration-flat-panel configurations in Qinghai and Gansu provinces. Yangtze River Delta fabricators supply precision glass optics under carbon-intensity documentation requirements.
Spain
Mature EPC contractor networks streamline Fresnel lens installations across Andalusia and Extremadura. EU Green Deal delegated acts mandate lifecycle carbon thresholds for module imports. Seville and Granada host utility-scale clusters where annual direct normal irradiance exceeds concentration viability thresholds.
Concentrated Photovoltaic System Market Competitive Environment
Heritage space-grade cell fabricators and precision optic specialists split the market into technology-tiered competitive bands. The vendor base concentrates among III-V epitaxy houses with backward integration into substrate production and tracking-system integrators with desert-deployment expertise. Two strategic archetypes dominate: multi-junction cell manufacturers leveraging lattice-engineered intellectual property, and module assemblers anchoring downstream through captive supply agreements. Competitive moves center on long-term offtake negotiations with Middle East utility vehicles and carbon-border compliance documentation for EU market access.
Within the heritage space-grade tier, SolAero Technologies Corp. and Soitec exemplify multi-junction cell positioning through substrate and wafer-bonding capabilities. Sumitomo Electric Industries Ltd. anchors the module-assembly vector through disciplined upstream control over III-V epitaxy. These three entities represent the competitive core where terrestrial HCPV procurement intersects with government-backed clean energy mandates.
| Leading Market Players |
|---|
| Radical Sun Systems Inc. |
| SolAero Technologies Corp. |
| Arzon Solar LLC |
| Cool Earth Solar |
| Morgan Solar Inc. |
| Suncore Photovoltaic Technology Company Limited |
| Sumitomo Electric Industries Ltd. |
| Soitec |
| Amonix |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in III-V epitaxy facilities across the Yangtze River Delta is compressing germanium substrate availability and amplifying supplier pricing power. This utilization squeeze forces procurement teams at Middle East utility vehicles to accept indexed pricing clauses that pass through raw material volatility.
Pricing Analysis
Price spreads between HCPV systems in Saudi Arabia and Fresnel lens deployments in Spain reflect land-constraint premiums and tracking complexity differentials. Three-tier pricing structure across premium, standard, and economy levels segments by cell efficiency grade and dual-axis precision. Cost compression in standard-tier modules is intensifying because Chinese precision-glass fabricators are expanding Fresnel lens capacity. Utility-scale EPC contractors in the Middle East exhibit lowest price sensitivity due to government-backed procurement mandates, while remote mining operators in Australia and Chile face acute capital constraints.
Supply Chain Analysis
Contract manufacturing for III-V multi-junction cells concentrates at Soitec's wafer-bonding facilities and Sumitomo Electric's epitaxy houses. Geographic supply concentration centers on China for precision glass optics, Germany for tracking-system mechanical assemblies, and the United States for space-grade cell heritage. Raw material dependencies draw from germanium mining in Russia and Canada, gallium refining in China, and arsenic processing in Japan. Single-source vulnerability in lattice-engineered germanium substrates threatens allocation risk during demand surges. Distribution runs through direct sales channels between cell manufacturers and utility-scale developers, bypassing traditional module distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts for dual-axis tracking systems are expanding faster than hardware sales, creating a service-attach opportunity that reshapes vendor economics. Recurring revenue from performance telemetry and remote diagnostics now commands higher margin multiples than initial equipment procurement.
For Market Incumbents: Entrench position through captive germanium substrate production and long-term offtake agreements with Middle East utility vehicles. SolAero Technologies Corp. and Soitec demonstrate the defensive value of backward integration into III-V epitaxy when allocation risk threatens competitor supply. Expand predictive maintenance service contracts to lock in decade-long revenue streams from Saudi Aramco and Emirates Water and Electricity Company installations. For New Entrants and Emerging Players: Establish a beachhead in remote mining diesel displacement segments where fuel logistics dominate levelized costs and procurement criteria favor modular, deployable systems. The off-grid telecommunications tower market in Australia and Chile offers penetrable white space with less entrenched incumbent presence. Pursue partnership models with established tracking-system integrators to circumvent multi-junction cell fabrication expertise barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tracking-system integrators bundling predictive maintenance with hardware supply. Long-term viability across the projection horizon hinges on carbon-border compliance documentation for EU market access and traceable supply chains through germanium mining stages. Acquisition targets should demonstrate captive substrate production or certified refiner relationships. Monitor FERC interconnection queue processing speeds as an inflection indicator for US utility-scale deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Germanium Substrate Production | Secures allocation priority during III-V epitaxy capacity crunches for HCPV manufacturers. |
| Predictive Maintenance Service Contracts | Converts Saudi Aramco and EWEC hardware sales into decade-long recurring revenue streams. |
| Carbon-Border Compliance Documentation | Enables EU Green Deal delegated act qualification for module imports into European tenders. |
| Direct Sales Channel Development | Disintermediates module distributors to capture margin from Middle East utility procurement. |
| Metamorphic Buffer Layer Engineering | Unlocks higher-bandgap cell architectures without lattice-matching constraints for next-generation deployments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted to triangulate market sizing and growth assumptions. Primary interviews engaged utility-scale EPC contractors in Saudi Arabia and the UAE, III-V cell fabrication engineers at heritage space-grade facilities, tracking-system procurement officers at Emirates Water and Electricity Company, and remote mining energy managers in Australia and Chile. Secondary validation drew from FERC interconnection filings, EU Green Deal delegated act documentation, MIIT GB certification protocols, and project development databases tracking NEOM corridor tenders. Bottom-up capacity assessments and top-down procurement forecasts were reconciled to produce segment-level outputs.
Calibration against historical deployment data and announced capacity additions anchored the analytical framework across the analysis window. Segmentation dimensions modeled include technology tier, application scale, end-user procurement sophistication, and installation site preparation intensity. CAGRs were derived from slope analysis of year-over-year capacity additions and capital commitment trajectories. Forecast inputs incorporated direct normal irradiance thresholds, dual-axis tracking cost curves, and germanium substrate supply-demand balances.
Stress conditions across III-V epitaxy capacity utilization, carbon-border adjustment implementation timelines, and Middle East sovereign procurement continuity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology cost trajectories and regulatory stability. Quarterly review of FERC interconnection queue lengths, EU delegated act enforcement patterns, and Saudi renewable energy tender issuance cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Agriculture Solar Water Pumps Market