
 Global Power Distribution Component Market | 2026-2036
Global Power Distribution Component Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Distribution Component Market Foresight
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales across the Global Power Distribution Component Market. Schneider Electric leverages its digital services platform to capture recurring revenue from predictive maintenance contracts. Siemens sustains technology leadership through its hybrid switchgear portfolio that bridges analog and digital architectures. ABB anchors its competitive position with deep domain expertise in medium-voltage distribution systems across European and Asian utility networks.
Power distribution components encompass electromechanical and solid-state apparatus engineered to control, protect, and route electrical energy across voltage classes from low-voltage residential circuits to extra-high-voltage transmission substations, typically manufactured from copper or aluminum conductors with epoxy resin or SF6 insulation systems rated for thermal stability under fault conditions. Circuit breakers and switchgear command the largest share of product-type revenue due to their critical protective function in industrial and utility installations. Smart and digital technologies represent the fastest-expanding technology segment as grid operators prioritize real-time monitoring and automated fault isolation. The utilities end-user segment occupies the deepest margin pools given the long-term service agreements and technical specification complexity inherent to transmission-scale procurement.
The EU Green Deal and F-Gas Regulation are accelerating demand for SF6-free switchgear alternatives across European utility procurement frameworks, while India's Central Electricity Authority mandates stricter efficiency standards for distribution transformers under its national grid code. The US EPA and DOE jointly enforce minimum efficiency regulations for dry-type transformers and medium-voltage switchgear through updated appliance standards. Stakeholders must monitor how divergent regional efficiency timelines reshape supplier certification requirements and factory allocation decisions.
Market Dynamics
The transition from SF6-insulated to dry-air or vacuum-insulated switchgear architectures is compressing incumbent equipment margins while opening service revenue streams for retrofit engineering and asset migration consulting.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Mandated SF6 emission reductions are forcing utilities across Germany, France, and Italy to accelerate procurement of fluorinated-gas-free medium-voltage switchgear, creating replacement demand cycles independent of organic grid expansion.
- Data Center Load Growth:Hyperscale facility construction in Virginia, Singapore, and Ireland is pulling high-capacity transformers and intelligent switchgear with integrated power quality monitoring.
- Copper Conductor Upgrades:India's Central Electricity Authority efficiency mandates for distribution transformers are driving aluminum-to-copper winding conversions in industrial corridor substations.
Market Restraints
- Epoxy Resin Supply Concentration:Asian petrochemical suppliers control over 70 percent of specialized electrical-grade resin feedstock, exposing European and North American switchgear manufacturers to input cost volatility and allocation risk.
- SF6 Inventory Stranding:Utilities holding substantial installed bases of gas-insulated switchgear face accelerated depreciation and remediation liability as national regulators tighten handling permits and leak-rate thresholds.
- Technical Limitation of Vacuum Interrupters:Current vacuum bottle designs face dielectric stress challenges above 145kV, constraining direct substitution in extra-high-voltage transmission substations.
Strategic Opportunities
- Vietnam Grid Modernization:State-owned EVN's ten-year capital plan for rural electrification and urban ring-main upgrades creates first-mover positioning for digital switchgear with integrated SCADA compatibility.
- Battery Storage Coupling:Hybrid inverter-transformer units that bridge solar PV, battery, and grid interconnection represent an emerging application with limited incumbent competition.
- US Inflation Reduction Act Domestic Content:Tax credit incentives for domestically manufactured electrical equipment are reshaping factory location decisions and supplier certification pathways.
Industry Challenges
- Medium-Voltage Engineering Talent Scarcity:Retirement waves among utility protection and control specialists are lengthening commissioning timelines and inflating contractor rates for substation automation integration.
- Multi-Standard Certification Burden:Concurrent compliance with IEC 62271, IEEE C37, and country-specific seismic or altitude derating requirements extends product development cycles and testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Distribution Component Market |
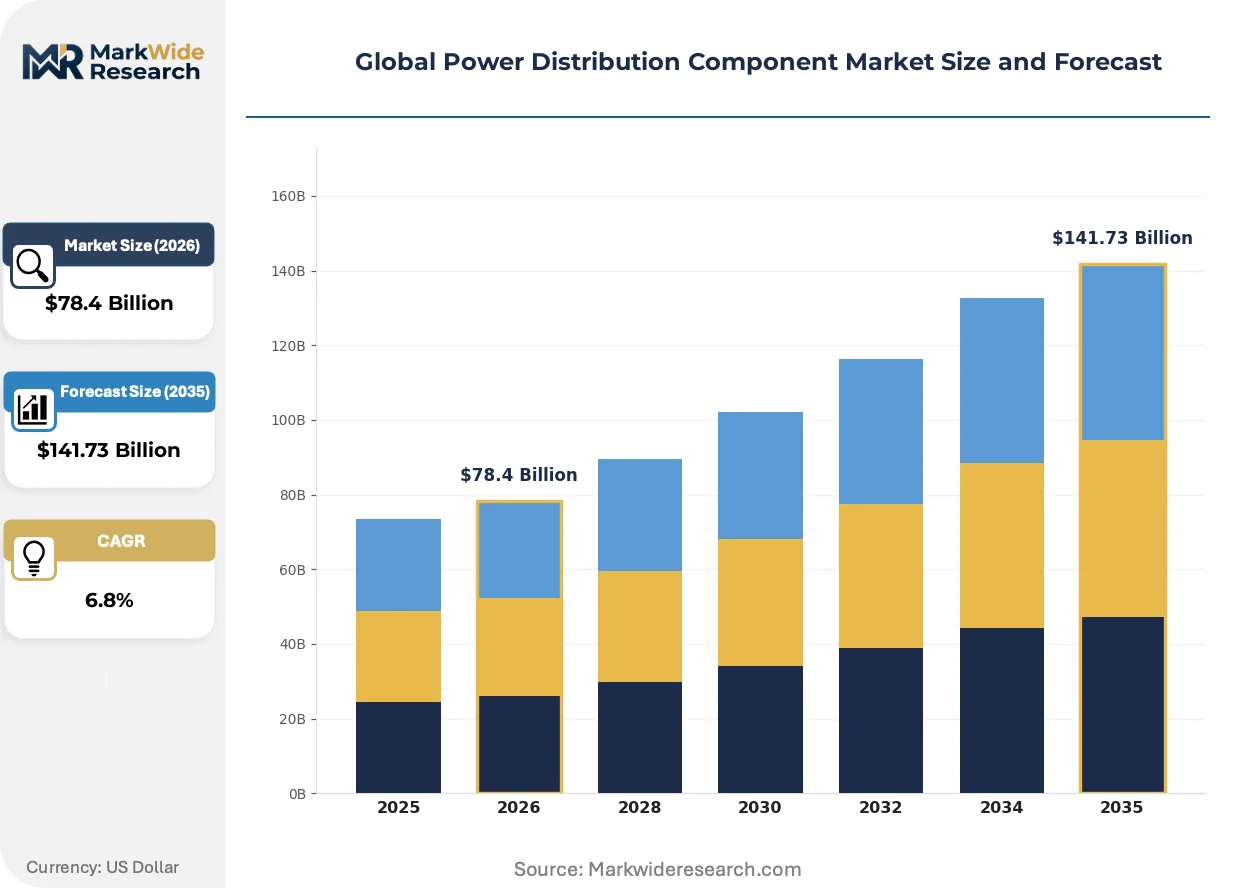
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Switchgear, Transformers, Busbars Installation Type: Indoor, Outdoor, Portable, Modular End User: Industrial, Commercial, Residential, Utilities Technology: Analog, Digital, Smart, Hybrid |
| Companies Covered | Eaton, Mitsubishi Electric, Schneider Electric, Hubbell, Hitachi Energy, ABB, General Electric, Powell Industries, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Distribution Component Market Shifts & Advancements
Digitalization is collapsing the traditional boundary between primary electrical equipment and information infrastructure, enabling predictive asset management and real-time grid optimization that were technically infeasible a decade prior.
Hybrid switchgear architectures are hybridizing conventional air-insulated bus compartments with digitally monitored vacuum interrupter modules. European transmission utilities in Germany and the Netherlands are piloting these configurations for urban substation retrofits where space constraints prohibit full air-insulated designs. The technology is hybridizing procurement evaluation criteria, forcing buyers to weigh integrated sensor value against pure capital cost metrics.
The EU F-Gas Regulation's 2030 phase-down targets are accelerating manufacturer investment in dry-air insulation R&D and vacuum interrupter scaling. Industrial consequence includes premature end-of-life for SF6-dependent product lines and stranded engineering knowledge in gas handling and recycling. Medium-voltage switchgear procurement in France, Italy, and Spain now explicitly penalizes fluorinated gas content through technical scoring algorithms.
Service unbundling is separating equipment supply from long-term performance contracts. Industrial and data center end-users in Singapore and Ireland increasingly procure switchgear through availability-based agreements where vendors retain ownership and risk. This compresses upfront capital recognition for manufacturers while expanding recurring revenue pools and binding customers through proprietary diagnostic platforms.
Global Power Distribution Component Market Segmentation
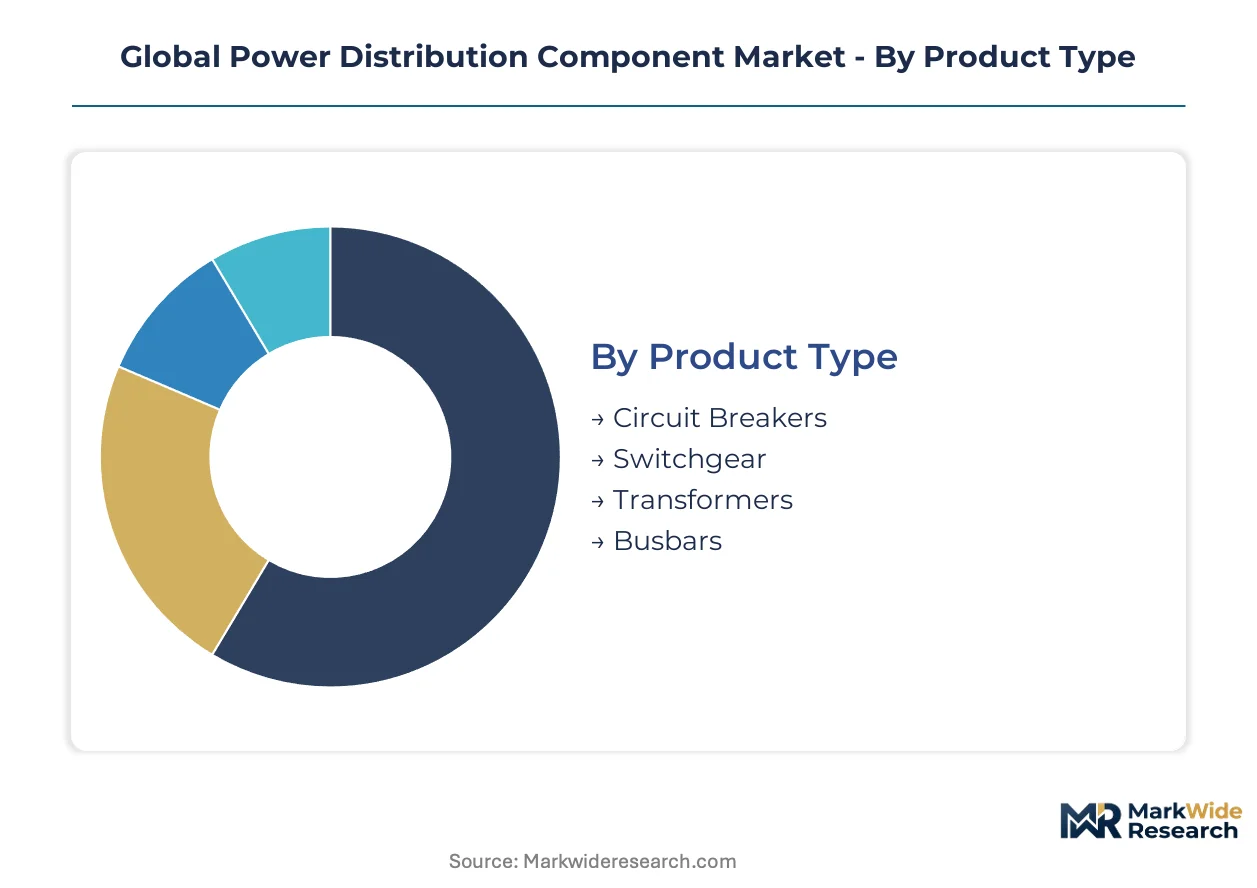
Segmentation in power distribution components determines procurement pathways, margin structures, and service attachment rates. Equipment complexity and operational criticality vary sharply across voltage classes and end-use environments, reshaping supplier engagement models and aftermarket revenue capture.
Product Type:
After-sales service intensity diverges dramatically across product categories, with protective equipment demanding continuous calibration and gas management while passive conductors require minimal lifecycle intervention.
- Circuit Breakers:Electromechanical and solid-state interruption devices engineered to isolate fault currents across low-voltage through extra-high-voltage classes. Demand concentrates in German and French utility substations where the EU F-Gas Regulation accelerates SF6-to-vacuum retrofits. The protective function mandates recurring inspection contracts and arc-flash testing protocols.
- Switchgear:Integrated assemblies of circuit breakers, disconnectors, and protective relays housed in metal-enclosed or metal-clad configurations. Indian industrial corridor investments and Vietnamese rural electrification programs pull medium-voltage air-insulated and gas-insulated variants. Modular designs with withdrawable breaker modules shorten outage windows during maintenance cycles.
- Transformers:Electromagnetic voltage conversion apparatus utilizing copper or aluminum windings with oil-immersed or dry-type insulation. India's Central Electricity Authority efficiency mandates drive aluminum-to-copper winding conversions in distribution networks.
- Busbars:Rigid or flexible conductor systems for power aggregation and distribution within switchgear assemblies and substations. Data center builds in Virginia and Singapore specify low-impedance copper busbar trunking for high-density power distribution.
Circuit breakers hold the largest share; momentum sits with switchgear as digital monitoring integration expands.
Installation Type:
Cost tier stratification separates capital-intensive fixed infrastructure from deployable systems serving temporary or emergency power requirements.
- Indoor:Equipment housed within climate-controlled electrical rooms or dedicated substation buildings, typical of urban commercial facilities and industrial plants. Singapore data centers and German manufacturing campuses specify IP-rated indoor switchgear with integrated arc-flash containment.
- Outdoor:Weather-hardened apparatus mounted on concrete pads or elevated platforms for transmission substations and rural distribution networks. Vietnamese EVN grid modernization deploys outdoor ring-main units for urban feeder automation.
- Portable:Trailer-mounted or skid-based systems for construction sites, events, and emergency response. Temporary power for India's industrial corridor expansion pulls mobile transformer and switchgear rentals.
- Modular:Prefabricated electrical buildings and containerized substations enabling rapid deployment and future expansion. Irish hyperscale data centers specify modular medium-voltage substations to compress commissioning timelines.
Outdoor installations dominate utility-scale procurement; modular configurations are climbing the fastest as time-to-energization pressures intensify.
End User:
Customer type determines specification complexity, contract duration, and the depth of technical integration required from component suppliers.
- Utilities:Transmission and distribution network operators procuring equipment for grid infrastructure and substation assets. Long-term service agreements and technical specification complexity create the deepest margin pools in this segment. German, French, and Italian transmission operators now embed SF6-free requirements into procurement scoring algorithms.
- Industrial:Manufacturing, mining, and processing facilities requiring reliable power distribution for continuous operations. India's Central Electricity Authority mandates stricter efficiency standards for distribution transformers serving industrial loads.
- Commercial:Office complexes, retail centers, and institutional buildings with lower fault duty requirements and shorter equipment lifecycles. Singapore commercial developments specify smart switchgear with integrated power quality monitoring.
- Residential:Single-family and multi-family housing with standardized low-voltage distribution panels and circuit protection. Copper conductor upgrades penetrate this segment slowly due to cost sensitivity.
Utilities command the largest equipment volumes; industrial end-users are gaining share fastest through corridor investments and reshoring manufacturing loads.
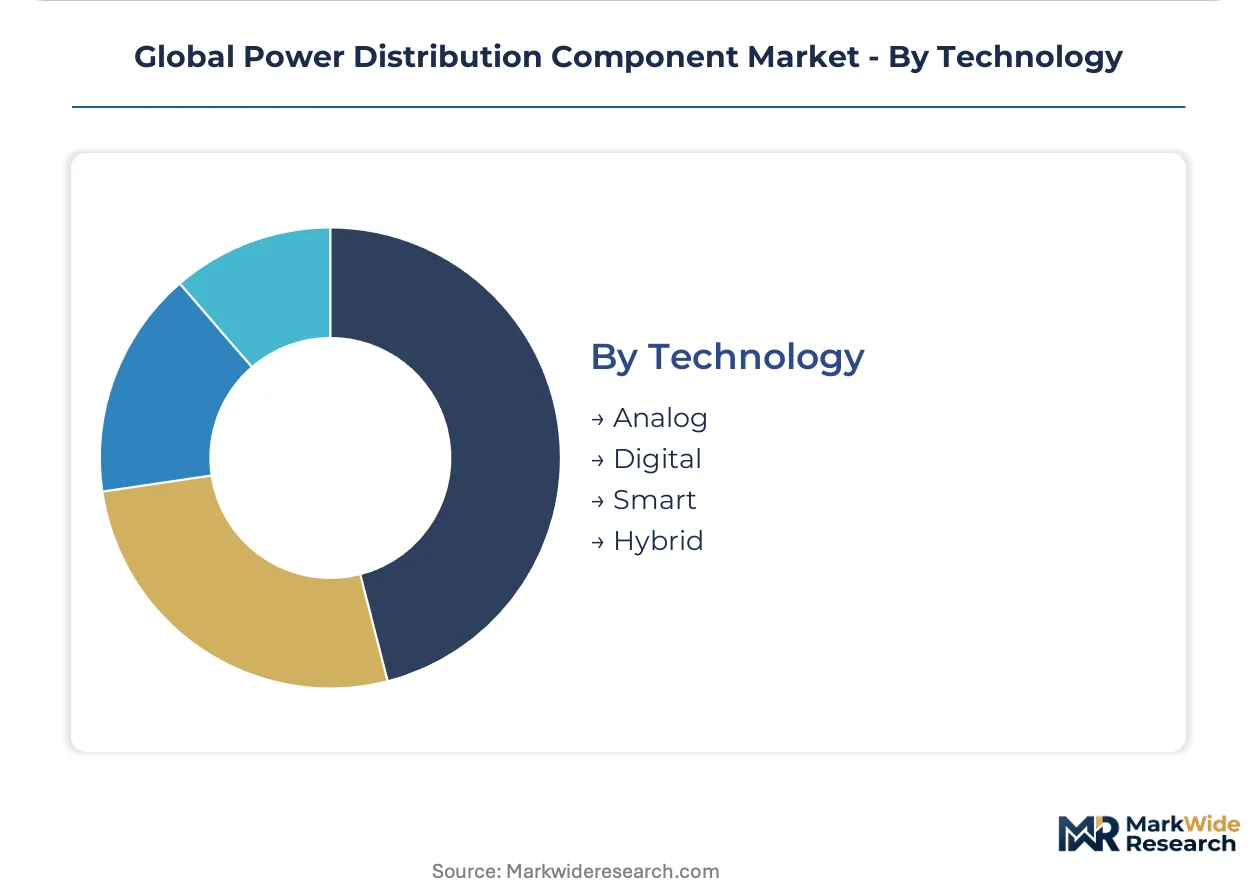
Technology:
Technology maturity curves separate legacy electromechanical systems from digitally native architectures that collapse the boundary between primary equipment and information infrastructure.
- Digital:Solid-state protection, communication-enabled monitoring, and software-configurable control functions embedded within primary equipment. German and Dutch transmission utilities pilot digitally monitored vacuum interrupter modules for urban substation retrofits where space constraints prohibit full air-insulated designs.
- Smart:Grid-interactive devices with bidirectional communication, automated fault location, and self-healing network coordination. Real-time monitoring and automated fault isolation capabilities drive the steepest expansion trajectory in this category.
- Hybrid:Architectures combining conventional air-insulated bus compartments with digitally monitored interrupter modules. European procurement evaluation criteria now weigh integrated sensor value against pure capital cost metrics.
- Analog:Electromechanical relays, magnetic trip units, and manually operated disconnectors without embedded intelligence. Stranded engineering knowledge and limited service revenue potential characterize this declining segment.
Digital technology holds the largest share; smart systems are expanding most quickly as grid operators prioritize predictive asset management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German utilities prioritize SF6-free switchgear retrofits under EU mandates, while Indian industrial corridors drive copper-winding transformer upgrades, and US hyperscale data centers pull modular substation configurations.
Germany
Transmission operators accelerate medium-voltage switchgear replacement cycles independent of organic grid expansion. The EU F-Gas Regulation mandates fluorinated-gas-free procurement scoring algorithms. Urban substation retrofits in the Ruhr industrial cluster deploy hybrid air-insulated configurations where space constraints prohibit full conventional designs.
United States
Virginia data center construction pulls high-capacity transformers with integrated power quality monitoring. The EPA and DOE jointly enforce minimum efficiency regulations for dry-type transformers through updated appliance standards. Northern Virginia's Loudoun County hosts the densest concentration of hyperscale facility electrical infrastructure investment globally.
India
Industrial corridor investments in Gujarat and Maharashtra drive aluminum-to-copper winding conversions. The Central Electricity Authority mandates stricter efficiency standards for distribution transformers under the national grid code. Tamil Nadu's manufacturing belt sees concentrated procurement of smart switchgear with SCADA compatibility.
Vietnam
State-owned EVN's ten-year capital plan for rural electrification creates first-mover positioning opportunities. The national utility prioritizes urban ring-main upgrades with digital switchgear integration. Ho Chi Minh City's southern industrial zones anchor demand for outdoor ring-main units with feeder automation capabilities.
France
Transmission procurement frameworks now explicitly penalize fluorinated gas content through technical scoring algorithms. The EU Green Deal accelerates manufacturer investment in dry-air insulation R&D. Lyon and Marseille urban substation pilots test digitally monitored vacuum interrupter modules for space-constrained retrofits.
Global Power Distribution Component Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified electrical conglomerates. The market structures around three tiers: integrated multinationals with full voltage-class coverage, regional specialists with deep utility relationships, and emerging Asian fabricators competing on cost-position. Dominant competitive moves include portfolio diversification into digital services platforms and strategic partnerships for SF6-free technology licensing.
Within the integrated multinational tier, Schneider Electric, Siemens, and ABB exemplify divergent strategic positioning. The French limited company anchors recurring revenue capture through predictive maintenance contracts. The German Aktiengesellschaft sustains technology leadership through hybrid switchgear architectures bridging analog and digital domains. The Swiss-Swedish multinational leverages deep domain expertise in medium-voltage distribution systems across European and Asian utility networks. Each represents a distinct archetype: service-platform monetization, technology-transition bridging, and geographic-specialization depth.
| Leading Market Players |
|---|
| Eaton |
| Mitsubishi Electric |
| Schneider Electric |
| Hubbell |
| Hitachi Energy |
| ABB |
| General Electric |
| Powell Industries |
| Siemens |
| Others |
Supply & Pricing Matrix
Epoxy resin supply concentration among Asian petrochemical suppliers determines both three-tier pricing structure across premium, standard, and economy levels and supply chain shape in the power distribution component market. This single-source dependency for specialized electrical-grade feedstock exposes European and North American switchgear manufacturers to input cost volatility that compresses margins at the standard tier while inflating premiums for certified low-carbon alternatives.
Pricing Analysis
Long-term offtake agreements dominate utility procurement frameworks, insulating transmission operators from spot volatility while compressing supplier margins through volume commitments. Price differentiation rests on IEC 62271 certification tier and integrated digital monitoring capability, with SF6-free switchgear commanding substantial premiums under EU F-Gas Regulation scoring algorithms. Cost compression in the standard tier is intensifying because aluminum-to-copper winding conversions in India pull material cost escalations through the value chain. Data center end-users exhibit the lowest price sensitivity due to availability-based contracting models, while residential distributors face acute margin pressure from commoditized low-voltage panel competition.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for transformer and switchgear manufacturers with cross-border component flows. Manufacturing gravity centers on China, Germany, and India for core apparatus, with Vietnam emerging as an alternative fabrication hub for medium-voltage assemblies. Raw material dependencies span electrical-grade copper, cold-rolled grain-oriented steel, and specialized epoxy resin systems. Single-source vulnerability concentrates in Asian petrochemical suppliers controlling over seventy percent of resin feedstock. Distribution runs through authorized distributor networks for industrial accounts and direct procurement channels for utility-scale transmission operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power distribution component market sits at a replacement-cycle recovery phase driven by EU F-Gas Regulation-mandated SF6 equipment phase-downs. Grid operators across Germany, France, and Italy are accelerating procurement timelines independent of organic load growth, creating a cyclical uplift that favors suppliers with certified fluorinated-gas-free portfolios.
For Market Incumbents: Harden defensive positions through backward integration into copper conductor processing and captive supply of electrical-grade steel laminations. Incumbents must accelerate certification investment for dry-air and vacuum interrupter technologies before EU procurement scoring algorithms fully penalize SF6 content. Channel control through exclusive service agreements with German and French transmission operators locks out emerging Asian fabricators from premium tier access.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given limited incumbent service infrastructure and price-sensitive procurement practices. Vietnamese state-owned EVN's rural electrification programs create first-mover positioning for modular switchgear with integrated SCADA compatibility. A go-to-market angle through availability-based performance contracts bypasses capital-intensive upfront equipment sales and binds customers through proprietary diagnostic platforms.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialists with SF6-free intellectual property and established utility relationships. Long-term viability over the next decade hinges on regulatory alignment with EU Green Deal efficiency mandates and IRA domestic content incentives in the United States. Acquisition target archetypes include regional engineering houses with deep medium-voltage expertise and stranded digital services capabilities. The signal to watch is accelerating procurement timeline compression in German transmission operator frameworks as F-Gas Regulation deadlines approach.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Technology Licensing | EU F-Gas Regulation scoring algorithms now penalize fluorinated gas content in French and Italian procurement. |
| Backward Integration into Copper Processing | India's CEA efficiency mandates for distribution transformers drive aluminum-to-copper conversion demand. |
| Digital Services Platform Launch | Predictive maintenance contracts capture recurring revenue from German utility substation retrofits. |
| Modular Subsystem Manufacturing Scale-Up | Irish hyperscale data centers specify containerized medium-voltage substations for rapid commissioning. |
| Joint Venture for Vacuum Interrupter R&D | Dielectric stress challenges above 145kV constrain direct substitution in extra-high-voltage transmission substations. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, EPC contractors, switchgear procurement managers, and aftermarket service directors and refined through secondary validation. Utility planning officers provided demand-side intelligence on replacement cycle timing and specification evolution. EPC contractors supplied installation cost structures and commissioning timeline data. Switchgear procurement managers detailed scoring algorithm weightings under EU F-Gas Regulation frameworks. Aftermarket service directors illuminated recurring revenue capture mechanics and diagnostic platform economics. Secondary sources included IEC standard documentation, national grid code filings, customs trade data for copper and steel inputs, and SEC filings from listed electrical equipment manufacturers. Bottom-up equipment unit economics were triangulated against top-down utility capex forecasts.
Demand-supply-balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled encompassed voltage class, insulation technology, end-user type, and regional regulatory framework. CAGRs were synthesized from equipment replacement cycle analysis, efficiency mandate implementation schedules, and data center load growth projections. Industry-specific forecast inputs included EVN's ten-year capital plan disclosure for Vietnamese rural electrification and EPA appliance standard revision timelines for dry-type transformer efficiency tiers.
Practitioners should monitor EU F-Gas Regulation enforcement intensity, copper price volatility, and vacuum interrupter dielectric scaling breakthroughs for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Distribution
Global Electric Power Distribution Automation Systems Market
Power Distribution
North America and Europe Power Distribution Component Market
Power Distribution
Power Distribution Cables Market
Power Distribution
AI in Energy Distribution Market
Power Distribution
Brazil City Gas Distribution Market
Power Distribution
Distribution Panel Market
Power Distribution
Lighting and Distribution Panel Board Market
Power Distribution
Power Distribution Unit (PDU) Market
Power Distribution
Europe DC Distribution Network Market
Power Distribution
Distribution Board Market
Power Distribution
Medium Voltage AC Power Distribution Units (PDU) Market