
 Oil and Gas Waste Heat Recovery Market | 2026-2036
Oil and Gas Waste Heat Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Waste Heat Recovery Market Outlook
Power purchase agreement financing and energy-as-a-service leasing is reconfiguring competitive entry barriers for mid-scale operators. Ormat Technologies leverages its geothermal project finance expertise to anchor long-term waste heat contracts. Siemens AG competes through integrated digital twin platforms that optimize thermal cycle performance. ABB Ltd. differentiates via modular electrical integration packages that reduce installation downtime.
Oil and gas waste heat recovery captures thermal energy from exhaust streams, flue gases, and process cooling through heat exchangers, organic Rankine cycle turbines, or thermoelectric generators to produce electricity or reusable heat. Systems typically operate between 150°C and 400°C source temperatures with thermal efficiencies ranging from 10% to 25% depending on cycle selection and working fluid. Heat exchangers dominate installed capacity due to mature supply chains and broad temperature compatibility across refinery applications. Organic Rankine cycle systems represent the fastest-growing technology segment as low-boiling-point working fluids unlock economic viability at moderate waste heat temperatures. Retrofit installations command premium margins where existing facility constraints demand custom engineering and minimal process interruption.
The EPA enforces emissions limits under the Clean Air Act that compel refineries to reduce flue gas temperatures and capture usable thermal energy. The EU Green Deal's industrial decarbonization framework and China's MEE dual carbon enforcement collectively tighten allowable waste heat discharge across major petrochemical jurisdictions. Stakeholders must monitor evolving carbon border adjustment mechanisms and local emissions trading schemes that alter project payback calculations.
Market Dynamics
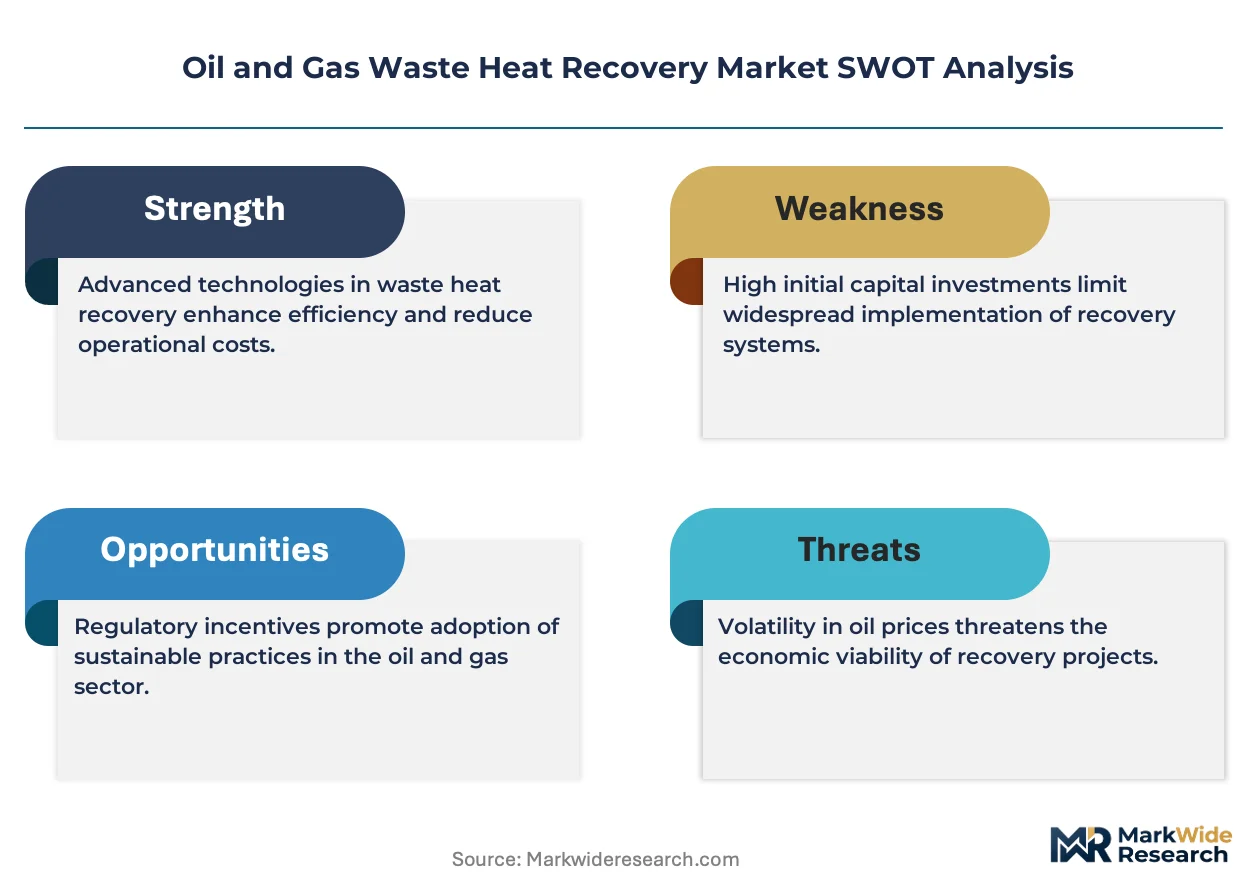
Refinery operators face mounting pressure to capture thermal energy from flue gas streams as EPA emissions mandates and EU industrial decarbonization frameworks tighten allowable waste heat discharge temperatures. The structural shift toward integrated energy recovery is compressing project payback timelines and reshaping vendor procurement criteria.
Growth Catalysts
- EPA Clean Air Act enforcement:Refineries in Texas and Louisiana must reduce stack temperatures, driving installation of heat exchangers and organic Rankine cycle systems to capture otherwise vented thermal energy.
- EU Green Deal industrial framework:Petrochemical clusters in Rotterdam and Antwerp face binding decarbonization targets that classify waste heat recovery as qualifying infrastructure for green financing.
- China MEE dual carbon enforcement:Provincial environmental bureaus now audit refinery energy intensity metrics, compelling Sinopec and private operators to retrofit existing facilities with thermoelectric generators.
Market Restraints
- Specialized alloy supply concentration:Heat exchanger fabrication depends on nickel-chromium alloys concentrated in Chinese and Russian smelter output, exposing project timelines to raw material availability shocks.
- Retrofit engineering complexity:Existing refinery layouts impose space constraints and process interruption risks that inflate custom engineering costs beyond standardized greenfield installations.
- Working fluid regulatory friction:EU F-Gas Regulation and EPA SNAP program restrict hydrofluorocarbon-based organic Rankine cycle fluids, forcing refrigerant reformulation and recertification cycles.
Strategic Opportunities
- Offshore platform electrification:North Sea and Gulf of Mexico operators seek compact thermoelectric systems to reduce generator fuel consumption and helicopter supply runs to unmanned installations.
- Hydrogen production integration:Steam methane reforming facilities in Germany and the Netherlands can channel recovered heat into electrolysis feedwater preheating, improving overall plant efficiency.
- Energy-as-a-service leasing:Mid-scale refineries in India and Brazil avoid upfront capital deployment through performance-contracting structures where vendors retain equipment ownership and capture shared savings.
Industry Challenges
- Thermal engineering talent scarcity:Organic Rankine cycle design requires expertise in low-grade heat optimization that outpaces university pipeline output, forcing vendors to poach from geothermal and nuclear sectors.
- Legacy DCS integration friction:Refinery distributed control systems from the 1990s lack native communication protocols for modern waste heat recovery monitoring, demanding costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Waste Heat Recovery Market |
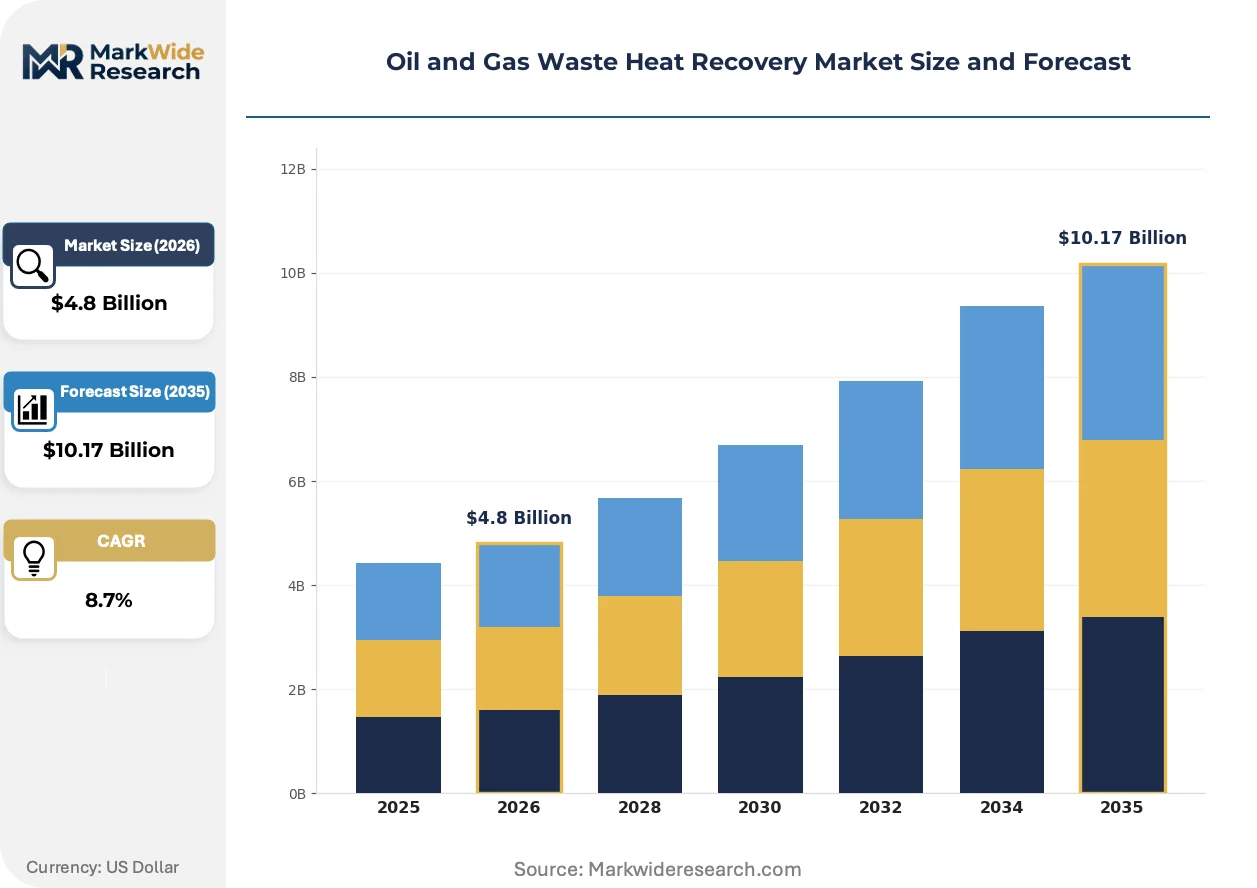
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Organic Rankine Cycle, Steam Rankine Cycle, Thermoelectric Generators, Heat Exchangers Application: Power Generation, District Heating, Industrial Heat Recovery, Combined Heat and Power End User: Refineries, Petrochemical Plants, Power Plants, Manufacturing Facilities Solution: Standalone Systems, Integrated Solutions, Retrofit Installations, Custom Designs |
| Companies Covered | Ormat Technologies, ABB Ltd., General Electric Company, Siemens AG, Mitsubishi Heavy Industries Ltd., Echogen Power Systems Inc., Thermax Limited, Alfa Laval, Wood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Waste Heat Recovery Market Strategic Shifts
Equipment manufacturers are converging on modular architectures that slash installation downtime and enable phased capacity expansion. Digital twin deployment and novel working fluid chemistry are compressing performance optimization cycles.
Supercritical carbon dioxide power cycles are collapsing the economic threshold for moderate-temperature waste heat sources. Refinery operators in Germany and Japan are piloting these compact turbine systems at 250°C to 350°C source temperatures. The technology is collapsing the historical gap between heat exchanger simplicity and organic Rankine cycle efficiency, forcing incumbent vendors to defend their technology portfolios.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin and hydrocarbon working fluid adoption in organic Rankine cycle systems. Equipment suppliers must redesign seals and safety systems to accommodate flammable or mildly flammable refrigerants. The regulatory pressure is most acute in German chemical parks where integrated energy networks demand high-availability heat recovery.
Refinery procurement departments are unbundling long-term service contracts from initial equipment supply. Operators in the United States now separate heat exchanger inspection and organic Rankine cycle maintenance into discrete competitive tenders, pressuring bundled vendors to demonstrate transparent lifecycle cost models. This behavior is most visible among integrated majors with centralized engineering standards in Houston and Singapore.
Oil and Gas Waste Heat Recovery Market Segmentation
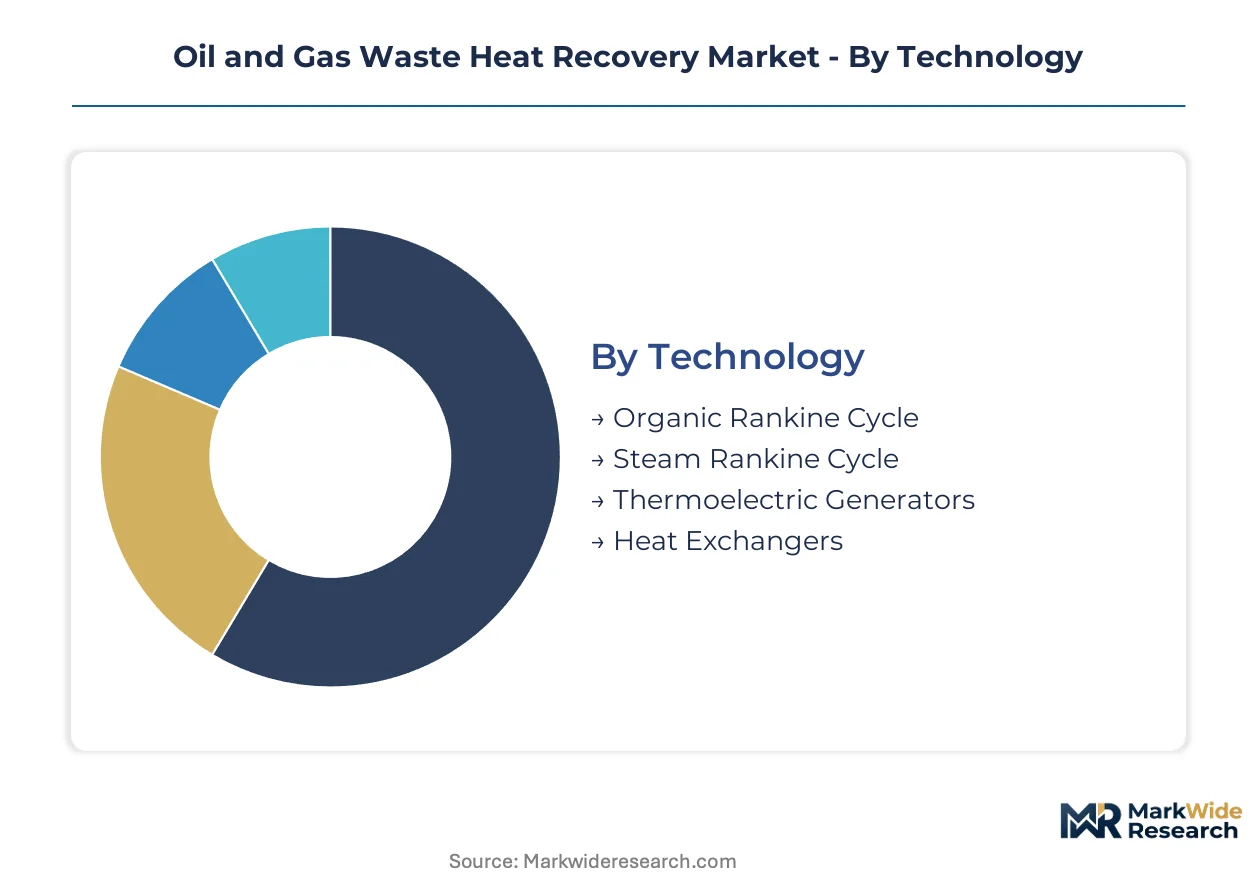
Technology selection in waste heat recovery determines maintenance schedules, spare parts inventories, and technical service requirements across multi-decade asset lifecycles. Procurement teams weigh these after-sales obligations against upfront capital outlays when structuring vendor contracts.
Technology:
After-sales service intensity varies sharply across thermal conversion technologies, with rotating machinery demanding predictive maintenance programs and static systems requiring periodic inspection protocols.
- Organic Rankine Cycle:Closed-loop systems using low-boiling-point working fluids to extract power from moderate-temperature waste streams between 150°C and 400°C. Demand concentrates in German chemical parks and Dutch refinery clusters where EU F-Gas Regulation compliance drives fluid selection and service contracting. The technology commands premium service agreements due to working fluid management and turbine overhaul cycles.
- Heat Exchangers:Shell-and-tube and plate-fin configurations transfer thermal energy between process streams without phase change. Refineries in Texas and Louisiana deploy these widely under EPA Clean Air Act enforcement, favoring established vendors with rapid tube bundle replacement capabilities and localized fabrication support.
- Thermoelectric Generators:Solid-state semiconductor devices convert temperature gradients directly to electricity, eliminating moving parts. Offshore platforms in the North Sea and Gulf of Mexico favor these for unmanned installations where helicopter maintenance access is costly.
- Steam Rankine Cycle:Conventional water-based systems require high-temperature heat sources above 350°C, limiting applicability to specific refinery furnace exhaust streams.
Heat exchangers hold the largest share; momentum sits with organic Rankine cycle systems.
Application:
Application selection tracks closely to facility energy balance requirements and local electricity grid economics, with power export viability shaping project returns.
- Power Generation:Electricity production from recovered thermal energy via turbine or thermoelectric conversion. Large petrochemical complexes in China under MEE dual carbon enforcement prioritize this application to reduce grid dependence and secure green financing certification.
- Combined Heat and Power:Simultaneous electricity and useful heat production maximizes exergy recovery from high-temperature sources. District heating networks in Rotterdam and Antwerp integrate refinery waste heat, qualifying infrastructure under EU Green Deal decarbonization frameworks.
- Industrial Heat Recovery:Direct thermal reuse within process heating, boiler feedwater preheating, or absorption cooling circuits. Refineries favor this where heat demand and supply profiles align temporally.
- District Heating:Export of recovered heat to municipal or industrial district heating networks requires long-term offtake contracts and seasonal demand matching.
Power generation dominates current deployment; combined heat and power is climbing the fastest as integrated energy systems expand.
End User:
End user category determines project scale, technical specifications, and regulatory exposure, with emission-intensive sectors facing the steepest compliance pressure.
- Refineries:Complex facilities with multiple high-temperature process streams and substantial flue gas volumes. Operators in the United States, China, and Germany account for the majority of installed capacity as environmental enforcement tightens stack temperature limits and energy intensity metrics.
- Petrochemical Plants:Steam crackers and aromatics units generate significant waste heat at temperatures suitable for organic Rankine cycle recovery. Antwerp and Rotterdam clusters lead European deployment.
- Power Plants:Gas turbine and reciprocating engine exhaust streams offer consistent heat profiles but compete with bottoming cycle investments in merchant power economics.
- Manufacturing Facilities:Cement, steel, and glass producers with high-temperature processes represent emerging demand as carbon border adjustment mechanisms expand scope beyond oil and gas.
Refineries command the dominant position; petrochemical plants show steepest expansion trajectory as cracker electrification drives heat integration.
Solution:
Solution architecture reflects facility vintage, available footprint, and operational flexibility requirements, with brownfield constraints dictating engineering approach.
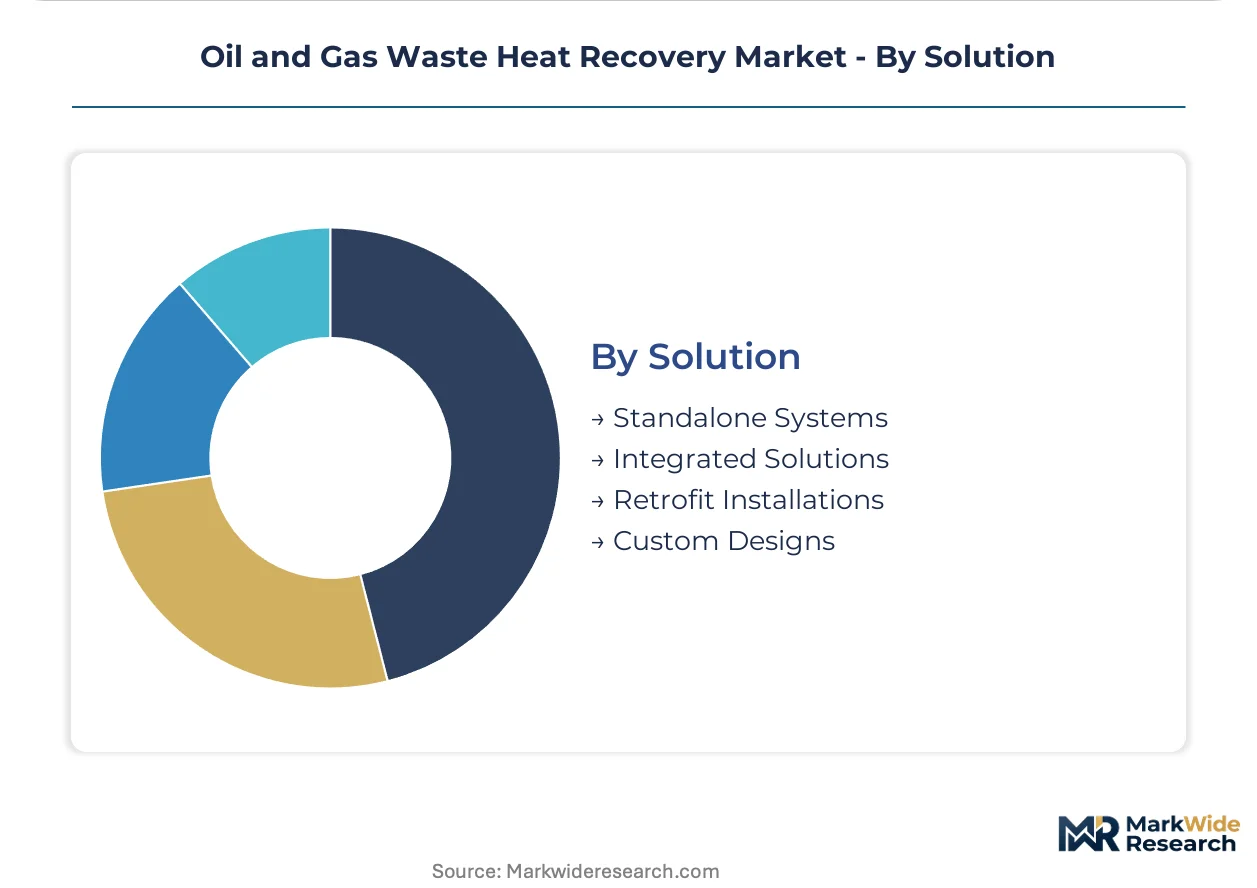
- Retrofit Installations:Custom-engineered systems integrated into existing process layouts with minimal production interruption. These command premium margins where space constraints and tie-in complexity demand specialized project execution, particularly in mature refinery corridors of Texas and Louisiana.
- Integrated Solutions:Waste heat recovery designed concurrently with process units, enabling optimal heat integration and control system architecture. Greenfield chemical parks in China and the Middle East favor this approach.
- Standalone Systems:Modular, skid-mounted packages with standardized interfaces reduce engineering overhead for smaller facilities and pilot deployments.
- Custom Designs:Bespoke engineering for unique heat source characteristics or extreme operating conditions, typical of offshore platform applications.
Retrofit installations represent the largest revenue pool; integrated solutions are gaining share fastest as newbuild petrochemical investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's Clean Air Act enforcement and the EU Green Deal's industrial decarbonization framework are redirecting capital toward waste heat recovery infrastructure. Refinery clusters in Texas, Rotterdam, and the German Rhine-Ruhr corridor face binding stack temperature limits that compress project payback timelines. China's MEE dual carbon audits are compelling Sinopec and private operators to retrofit existing facilities with thermoelectric and organic Rankine cycle systems.
United States
Refinery operators in Texas and Louisiana confront EPA emissions mandates that require reduced flue gas temperatures. The Clean Air Act enforcement has triggered procurement of shell-and-tube heat exchangers and organic Rankine cycle packages across the Gulf Coast petrochemical corridor. Houston-area engineering firms are securing long-term service contracts for heat exchanger inspection and tube bundle replacement.
Germany
Chemical parks in Ludwigshafen and Leverkusen operate under EU F-Gas Regulation phase-down schedules that restrict hydrofluorocarbon working fluids. The EU Green Deal classifies waste heat recovery as qualifying infrastructure for green financing, accelerating supercritical carbon dioxide pilot deployments. Rhine-Ruhr refinery clusters are integrating recovered heat into electrolysis feedwater preheating for hydrogen production.
China
Provincial environmental bureaus under MEE authority now audit refinery energy intensity metrics as part of dual carbon enforcement. Sinopec facilities in Shandong and Jiangsu are retrofitting with thermoelectric generators to minimize process interruption during compliance upgrades. Yangtze River Delta petrochemical complexes prioritize power generation applications to reduce grid dependence.
Netherlands
Rotterdam and Antwerp port authorities have established integrated energy networks that qualify refinery waste heat for district heating export under EU Green Deal frameworks. Binding decarbonization targets for petrochemical clusters are accelerating organic Rankine cycle adoption with hydrofluoroolefin working fluids. Dutch engineering contractors are unbundling long-term service contracts from initial equipment supply.
Saudi Arabia
SABIC and domestic refiners in the Eastern Province are expanding waste heat recovery as part of national industrial diversification programs. The kingdom's petrochemical megaprojects incorporate integrated heat recovery designs concurrent with process unit construction. Jubail Industrial City operators favor modular skid-mounted packages that reduce engineering overhead for standardized deployments.
Oil and Gas Waste Heat Recovery Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: integrated industrial conglomerates with project finance capabilities, specialized thermal engineering firms with organic Rankine cycle expertise, and modular equipment fabricators serving retrofit markets. Equipment vendors compete through technology licensing arrangements and energy-as-a-service leasing structures that transfer ownership risk to operators. Strategic moves center on portfolio diversification into hydrogen production integration and geographic expansion through regional fabrication partnerships.
Among diversified industrial technology providers, Siemens AG and General Electric Company exemplify the integrated conglomerate archetype with digital platform and power generation heritage. Ormat Technologies occupies a specialist position leveraging geothermal project finance structures for long-term waste heat contracting. These three anchors represent distinct competitive vectors: industrial digitization, rotating equipment scale, and alternative energy financing expertise.
| Leading Market Players |
|---|
| Ormat Technologies |
| ABB Ltd. |
| General Electric Company |
| Siemens AG |
| Mitsubishi Heavy Industries Ltd. |
| Echogen Power Systems Inc. |
| Thermax Limited |
| Alfa Laval |
| Wood |
| Others |
Value Chain & Pricing Dynamics
Nickel-chromium alloy smelter output concentrated in Chinese and Russian supply channels anchors cost structures for heat exchanger fabricators serving refinery retrofits. This upstream concentration funnels margin pools toward specialized alloy traders and regional fabrication shops with long-term offtake agreements, compressing equipment vendors' procurement leverage.
Pricing Analysis
Certification level (ISO/CE/ASME-grade) creates the primary spread between premium and standard equipment tiers. Project-based contracting dominates, with price differentiation tracking customization depth and after-sales service bundling. Cost compression in standard heat exchanger segments is intensifying because Chinese fabricators are expanding European distribution. Mid-scale refineries in India and Brazil exhibit highest price sensitivity; integrated majors with centralized engineering standards in Houston and Singapore are least sensitive.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from alloy traders are becoming prerequisites for fabrication contract awards. Heat exchanger fabrication draws from nickel-chromium alloy output concentrated in China, Russia, and South Africa; turbine components for organic Rankine cycle systems rest on precision machining capacity in Germany and Japan. Single-source vulnerability in specialty alloy supply exposes project timelines to raw material availability shocks. Distribution runs through engineering-procurement-construction contractors with established refinery relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of organic Rankine cycle thermal engineers—whose expertise in low-grade heat optimization outpaces university pipeline output—creates a capability bottleneck that reshapes competitive dynamics. Vendors who secure this talent anchor through acquisition or exclusive contracting gain disproportionate leverage in project bidding.
For Market Incumbents:Insulate service revenue streams by unbundling long-term maintenance contracts from initial equipment supply, mirroring the procurement behavior shift visible among integrated majors with centralized engineering standards in Houston and Singapore. Deepen backward integration into nickel-chromium alloy supply through offtake agreements with Chinese and Russian smelters to defend margin position against raw material availability shocks. Prioritize certification investment in hydrofluoroolefin working fluid systems to capture EU F-Gas Regulation compliance premiums.
For New Entrants and Emerging Players:Mid-scale refineries in India and Brazil represent the most penetrable entry point, where energy-as-a-service leasing structures bypass upfront capital barriers that favor incumbents with project finance capabilities. Offshore platform electrification in the Gulf of Mexico offers a second white-space target, with unmanned installations demanding compact thermoelectric systems that reduce helicopter maintenance access costs. Go-to-market execution should anchor on performance-contracting structures where equipment ownership retention aligns vendor incentives with operator savings capture.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with private equity-backed thermal engineering specialists who consolidated organic Rankine cycle design capabilities during the last decade. Long-term viability across a five-to-ten year window hinges on hydrogen production integration positioning, where recovered heat channels into electrolysis feedwater preheating. The signal to watch is Sinopec and private operator retrofit acceleration under MEE dual carbon enforcement, which would validate demand inflection for thermoelectric generator suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel-chromium sourcing from Chinese and Russian smelters insulates fabrication margins against raw material shocks. |
| Hydrofluoroolefin Fluid Certification | EU F-Gas Regulation compliance unlocks green financing eligibility for Rotterdam and Antwerp petrochemical clusters. |
| Energy-as-a-Service Leasing Launch | Performance-contracting structures transfer ownership risk while capturing shared savings from mid-scale Indian and Brazilian refineries. |
| Hydrogen Production Integration | Recovered heat channeling into electrolysis feedwater preheating improves plant efficiency at German steam methane reforming facilities. |
| Digital Twin Platform Deployment | Siemens AG-style thermal cycle optimization compresses commissioning timelines and enables predictive maintenance revenue streams. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery maintenance directors, organic Rankine cycle engineering leads, EPC contractor procurement managers, and aftermarket service heads. Secondary validation drew from EPA Clean Air Act enforcement records, EU ETS transaction databases, MEE dual carbon audit disclosures, and customs trade data for nickel-chromium alloy shipments. Bottom-up project pipeline tracking across Texas, Rotterdam, and Shandong refinery corridors was triangulated against top-down market sizing from equipment vendor revenue disclosures.
Calibration against historical deployment trajectories in German chemical parks and Gulf Coast petrochemical corridors anchored the analytical framework across the analysis window. Segmentation dimensions modeled include technology type, application, end user category, and solution architecture, with additional granularity on working fluid chemistry and retrofit versus greenfield project status. CAGRs were derived from regression analysis of installed capacity additions against regulatory enforcement timelines and green financing availability. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and China MEE energy intensity audit protocols.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, alloy commodity prices, or carbon credit valuations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology cost reduction curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
United States Waste to Energy Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Shipboard Incineration Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Southeast Asia Waste-To-Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Europe Waste-To-Energy Market