
 Chile Solar Energy Market | 2026-2036
Chile Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Solar Energy Market Outlook
Buyer concentration among Chilean utility providers is pivoting toward a smaller cohort of large-scale off-takers with multi-decade power purchase agreements. AES Andes leverages its integrated generation portfolio to secure long-term contracting positions in northern Chile. Enel Green Power sustains technology leadership through monocrystalline cell deployments across its Atacama installations. Engie Energía Chile anchors its competitive stance with ground-mounted system expertise and grid interconnection capabilities.
Solar energy in Chile encompasses photovoltaic systems, concentrated solar power, and solar thermal heating technologies that convert electromagnetic radiation into electrical or thermal energy, with utility-scale photovoltaic installations typically employing monocrystalline or bifacial panels rated above 400 watts peak to maximize yield per hectare in high-irradiance zones. Photovoltaic systems dominate capacity additions due to modular deployment speed and declining module costs, while concentrated solar power retains structural relevance for hybrid projects requiring thermal storage dispatchability. Ground-mounted systems command the installation-type margin pool given economies of scale in Atacama and Antofagasta regions, whereas rooftop installations grow fastest among mining-sector commercial installations seeking behind-the-meter supply.
Chile's Ministry of Energy oversees net-billing regulations that shape distributed generation economics, while the Superintendency of Electricity and Fuels enforces grid code compliance for utility-scale interconnection. Environmental impact assessment requirements under the Environmental Evaluation Service condition project timelines and technology selection for solar park development. Stakeholders must monitor transmission congestion in northern corridors and evolving storage mandates that will determine project bankability and offtake contract structures.
Market Dynamics
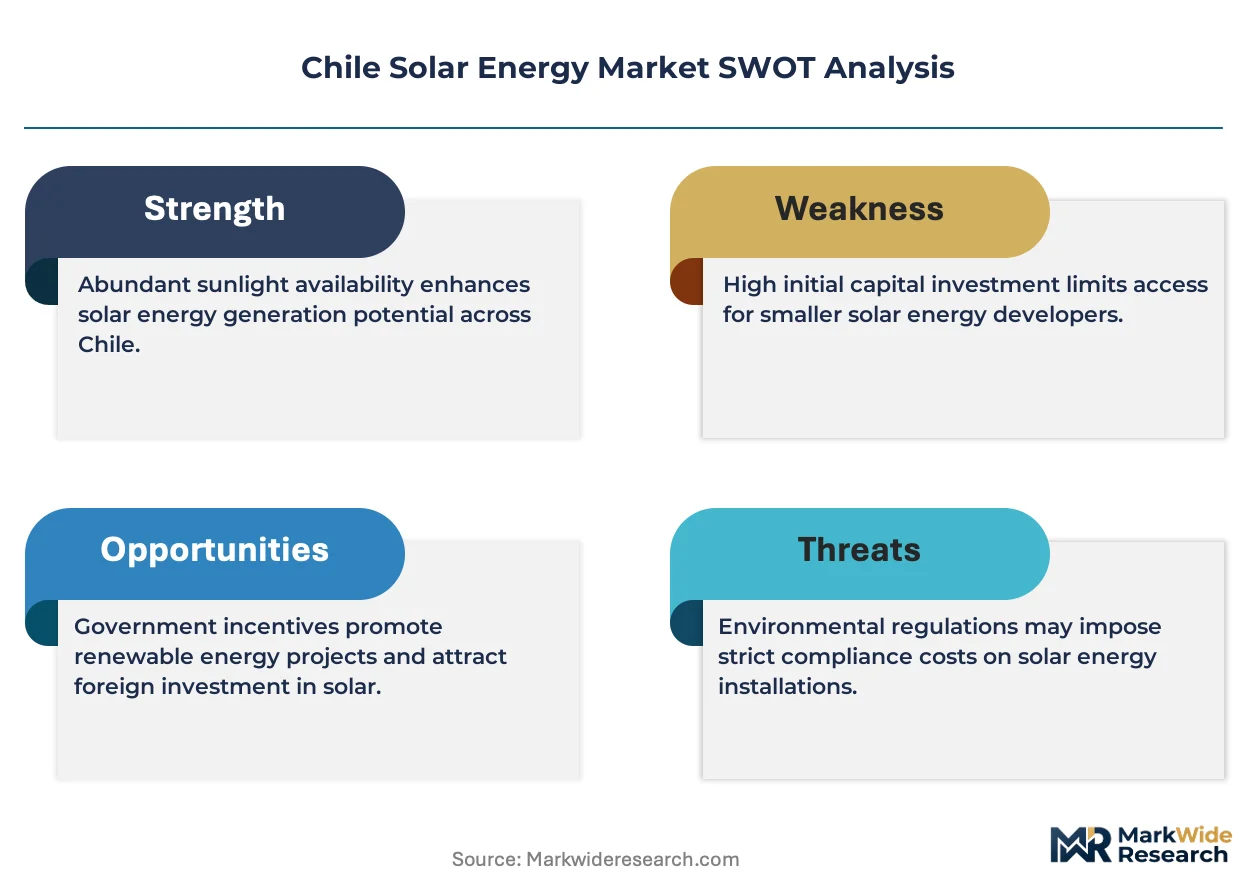
Chile's solar sector pivots on transmission infrastructure lag in northern corridors, where gigawatt-scale project queues outpace grid reinforcement schedules and force developers into merchant exposure or storage co-location.
Growth Catalysts
- Net-billing framework:Chile's Ministry of Energy regulations accelerate distributed generation adoption among commercial mining operations seeking behind-the-meter supply autonomy.
- Atacama irradiance concentration:The desert region's 2,700 annual equivalent sun hours attract multi-gigawatt photovoltaic pipelines from utility-scale offtakers.
- Bifacial module technology:Ground-mounted installations deploy bifacial panels rated above 400 watts peak to maximize yield per hectare in high-albedo desert conditions.
Market Restraints
- Polysilicon supply concentration:Chilean developers face input cost volatility tied to concentrated polysilicon refining capacity in East Asian supply basins.
- Environmental impact assessment timelines:Chile's Environmental Evaluation Service approval processes extend project development cycles and compress developer returns.
- Transmission congestion:Northern grid corridors suffer interconnection queue delays that strand capacity and force curtailment risk onto project finance structures.
Strategic Opportunities
- Antofagasta mining corridor:Underpenetrated commercial rooftop installations serve copper extraction operations with 24-hour demand profiles and carbon reduction mandates.
- Hybrid solar-storage configurations:Technology convergence between photovoltaic arrays and lithium-ion battery systems enables dispatchable capacity participation in Chile's ancillary services market.
- Green hydrogen offtake:Emerging electrolyzer demand from state-backed H2V initiatives creates new long-term contracting anchors for solar developers.
Industry Challenges
- Grid code compliance expertise:Chile's Superintendency of Electricity and Fuels enforces evolving interconnection standards that outstrip local engineering talent pools.
- Merchant price exposure:Projects without contracted offtake face spot market volatility in Chile's central-southern pricing nodes where solar generation profiles overlap.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Solar Energy Market |
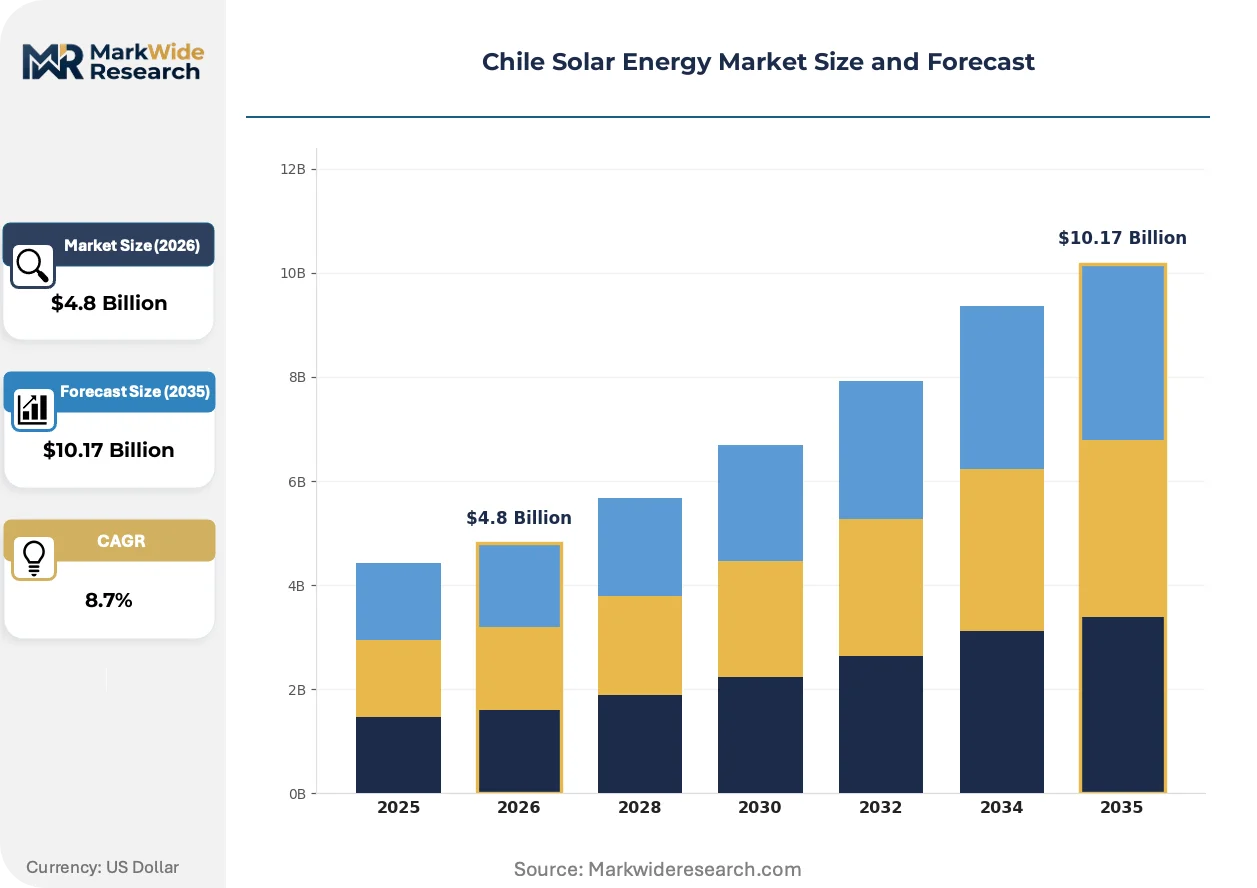
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Thermal Heating, Concentrated Solar Power, Bifacial Panels End User: Utility Providers, Commercial Installations, Residential Users, Government Facilities Installation Type: On-Grid Systems, Off-Grid Systems, Rooftop Installations, Ground-Mounted Systems Technology: Thin-Film Technology, Monocrystalline Cells, Polycrystalline Cells, Smart Inverters |
| Companies Covered | AES Andes, Enel Green Power, Engie Energía Chile, Grenergy Renovables, Atlas Renewable Energy, Acciona, Sonnedix Chile, Mainstream Renewable Power, ContourGlobal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Solar Energy Market Strategic Shifts
Technology deployment patterns in Chilean solar are compressing development timelines while regulatory pressure forces storage integration and merchant risk management into standard project structures.
Bifacial photovoltaic modules with tracking systems are rewriting project economics in Atacama installations. Mining consortiums and utility offtakers deploy these configurations across greenfield developments. The technology is rewriting capacity factor assumptions and pushing single-axis tracker suppliers into dominant procurement positions.
Chile's Ministry of Energy storage mandates reshape project bankability requirements for utility-scale interconnection. Developers must now co-locate battery systems or absorb curtailment penalties. Northern transmission-constrained zones face the steepest compliance costs and fastest adoption of DC-coupled storage architectures.
Long-term power purchase agreement tenors are compressing as offtakers resist merchant exposure beyond fifteen-year terms. Mining-sector buyers in Antofagasta and Tarapacá regions drive this contraction, favoring shorter contracts with renegotiation clauses over traditional twenty-five-year structures. This pattern concentrates in copper extraction operations with volatile commodity-linked cash flows.
Chile Solar Energy Market Segmentation
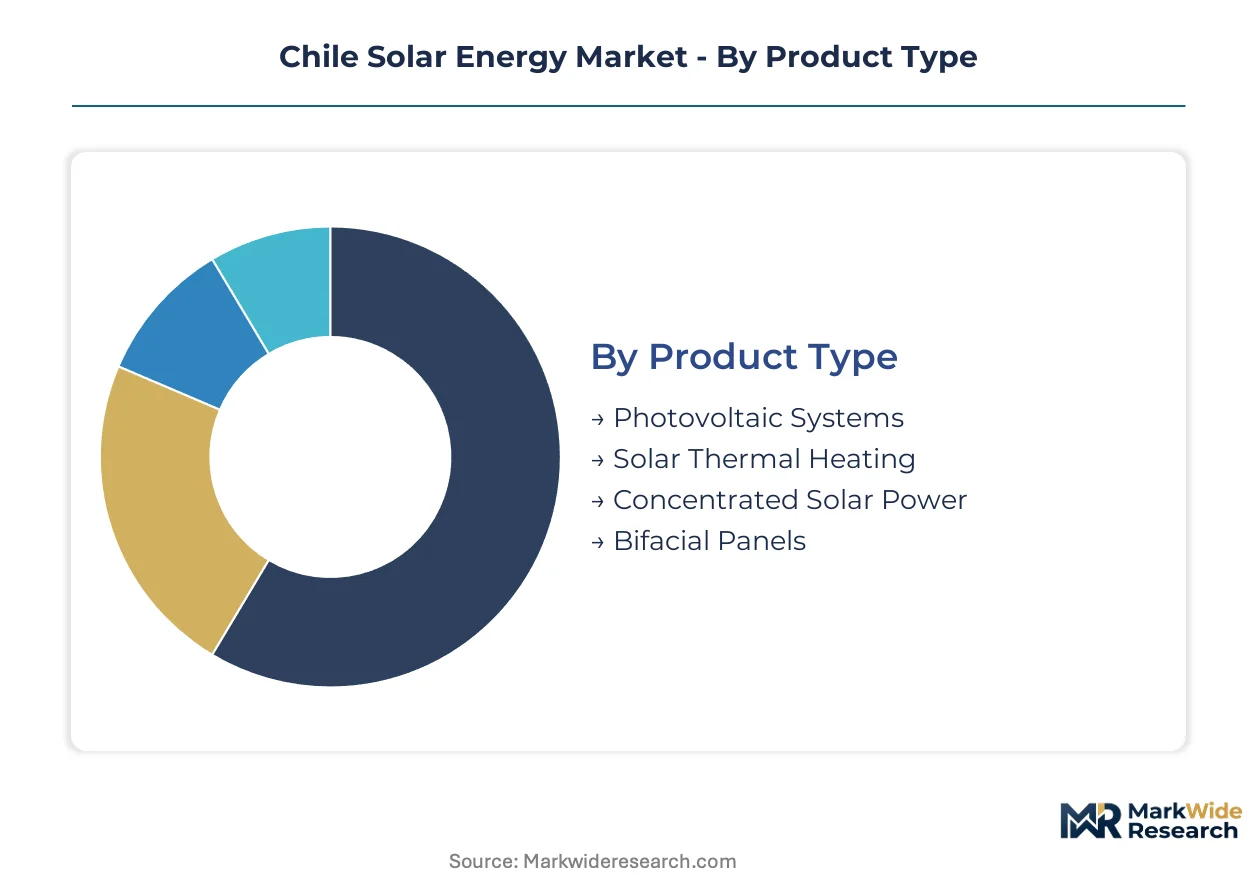
Technology and installation choices in Chile's solar sector reflect the tension between Atacama Desert utility-scale economics and distributed generation mandates under the Ministry of Energy's net-billing framework. Segment performance diverges sharply across northern transmission corridors versus mining-sector commercial demand clusters.
Product Type:
Upgrade cycles in Chilean solar infrastructure favor modular technologies that minimize downtime during capacity expansions and retrofits in high-irradiance zones.
- Photovoltaic Systems:Modular silicon-based arrays dominate capacity additions through rapid deployment speed and declining module costs. Utility providers in Antofagasta and Tarapacá regions anchor procurement of monocrystalline and bifacial configurations rated above 400 watts peak to maximize yield per hectare.
- Bifacial Panels:Dual-sided cell technology captures reflected irradiance from high-albedo desert surfaces, rewriting capacity factor assumptions for ground-mounted installations. Northern Chilean developers prioritize these panels with single-axis tracking systems to optimize land-use efficiency in multi-gigawatt pipelines.
- Concentrated Solar Power:Thermal collection systems with molten salt storage retain structural relevance for hybrid projects requiring dispatchable evening capacity. The technology serves grid operators facing curtailment risk in transmission-constrained corridors.
- Solar Thermal Heating:Low-temperature collectors address process heat requirements in mining operations and residential water heating. Deployment concentrates in off-grid commercial sites seeking thermal energy independence from diesel alternatives.
Volume placements concentrate in Photovoltaic Systems; the faster expansion belongs to Bifacial Panels.
End User:
Customer-type economics in Chile split between regulated utility procurement with long-term contracting power and behind-the-meter installations seeking supply autonomy.
- Utility Providers:Centralized offtakers including AES Andes and Engie Energía Chile drive multi-gigawatt procurement through power purchase agreements. These entities prioritize grid-scale projects in Atacama with twenty-year contracting horizons and firm capacity requirements.
- Commercial Installations:Mining consortiums in the Antofagasta corridor deploy rooftop and ground-mounted systems to secure 24-hour demand coverage and meet carbon reduction mandates. Copper extraction operations favor shorter contract tenors with renegotiation clauses tied to commodity price volatility.
- Residential Users:Distributed generation adoption accelerates under net-billing regulations, though penetration remains concentrated in affluent Santiago metropolitan zones with grid interconnection access.
- Government Facilities:Public sector procurement supports rural electrification and municipal building retrofits, typically through centralized purchasing frameworks administered by the Ministry of Energy.
Revenue concentration sits with Utility Providers; Commercial Installations are climbing the fastest as mining-sector decarbonization timelines compress.
Installation Type:
Configuration choices reflect site constraints, grid proximity, and the Superintendency of Electricity and Fuels interconnection standards that shape project bankability.
- Ground-Mounted Systems:Large-scale desert installations command the margin pool through economies of scale in land preparation and shared infrastructure. These configurations dominate Atacama project pipelines where flat terrain and minimal shading optimize tracker deployment.
- Rooftop Installations:Commercial and residential building-integrated systems grow through net-billing economics and mining-sector behind-the-meter demand. Antofagasta copper operations drive fastest adoption among industrial rooftops with heavy daytime load profiles.
- On-Grid Systems:Grid-connected configurations face transmission congestion penalties in northern corridors, forcing co-located storage or curtailment risk absorption into financing structures.
- Off-Grid Systems:Standalone installations serve remote mining camps and rural communities beyond transmission reach, typically pairing photovoltaic arrays with diesel backup or battery storage.
Capacity deployment concentrates in Ground-Mounted Systems; Rooftop Installations gain share fastest among mining-sector commercial sites.
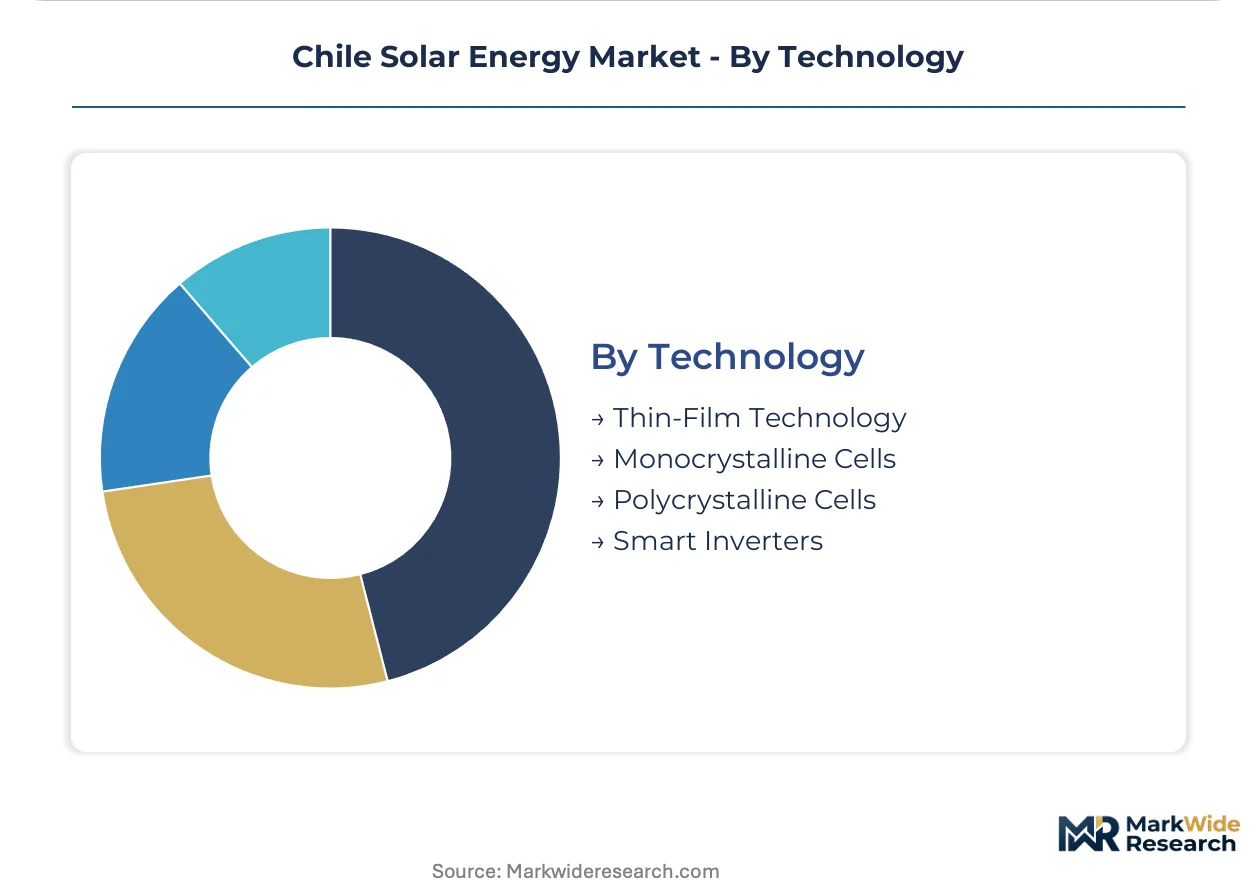
Technology:
Cell architecture and power electronics selection determines yield optimization, degradation rates, and compatibility with Chile's evolving grid code requirements.
- Monocrystalline Cells:Single-crystal silicon technology delivers highest conversion efficiency for space-constrained or high-value installations. Enel Green Power and utility-scale developers prioritize these cells for Atacama projects where land costs and yield per hectare drive returns.
- Smart Inverters:Grid-supporting power electronics with reactive power capability and fault ride-through functionality satisfy Superintendency of Electricity and Fuels interconnection mandates. Northern project queues increasingly require these inverters for grid stability services.
- Thin-Film Technology:Cadmium telluride and amorphous silicon alternatives offer temperature coefficient advantages in extreme desert heat, though market share remains limited by lower efficiency and established crystalline supply chains.
- Polycrystalline Cells:Multi-crystal silicon technology retains cost-sensitive applications in residential and small commercial segments where efficiency premiums do not justify monocrystalline price differentials.
Procurement volume concentrates in Monocrystalline Cells; Smart Inverters are expanding most quickly as grid code compliance tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale offtakers concentrate procurement in Chile's northern mining corridors, where copper extraction operations and grid-scale developers co-locate around transmission infrastructure. The Atacama Desert's irradiance profile attracts multi-gigawatt project pipelines from international capital providers.
Atacama Region
Mining consortiums and utility providers anchor demand in this high-irradiance zone. The Ministry of Energy's net-billing regulations shape distributed generation adoption among commercial operations. Calama and Antofagasta host the densest concentrations of bifacial photovoltaic installations with single-axis tracking systems.
Antofagasta Region
Copper extraction operations drive behind-the-meter solar procurement with 24-hour demand profiles. The Superintendency of Electricity and Fuels enforces grid code compliance for utility-scale interconnection in this corridor. Mejillones and Tocopilla industrial clusters concentrate ground-mounted systems serving port and processing facilities.
Tarapacá Region
Grid congestion in northern transmission corridors forces developers toward storage co-location or merchant exposure. Environmental Evaluation Service approval processes condition project timelines for solar park development. Iquique and Alto Hospicio host emerging commercial rooftop installations among logistics and free-zone enterprises.
Metropolitan Santiago
Affluent residential zones drive distributed generation adoption under net-billing economics. The Ministry of Energy oversees centralized purchasing frameworks for government facility retrofits. Santiago's grid interconnection access supports fastest penetration among urban commercial installations.
Coquimbo Region
Agricultural processing and wine industry operations anchor commercial solar demand with daytime load matching. The Environmental Evaluation Service regulates project development cycles for ground-mounted installations. La Serena and Ovalle concentrate emerging utility-scale pipelines seeking southern grid node access.
Chile Solar Energy Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hybrid solar-storage configurations and green hydrogen offtake partnerships. The vendor base clusters around three archetypes: integrated generation portfolios securing long-term contracting positions, renewable pure-plays deploying monocrystalline and bifacial technologies, and international developers leveraging ground-mounted expertise with grid interconnection capabilities. Competitive moves concentrate on transmission-constrained zone access and storage mandate compliance ahead of regulatory deadlines.
Among integrated generation portfolios, AES Andes anchors long-term contracting positions in northern Chile through its diversified asset base. Enel Green Power exemplifies technology leadership archetypes with monocrystalline cell deployments across Atacama installations. Engie Energía Chile occupies a position among ground-mounted system specialists with grid interconnection capabilities in transmission-constrained corridors.
| Leading Market Players |
|---|
| AES Andes |
| Enel Green Power |
| Engie Energía Chile |
| Grenergy Renovables |
| Atlas Renewable Energy |
| Acciona |
| Sonnedix Chile |
| Mainstream Renewable Power |
| ContourGlobal |
| Others |
Value Chain & Pricing Dynamics
Polysilicon spot price indices from East Asian commodity benchmarks cascade through Chilean solar project economics, compressing developer margins on crystalline module procurement while bifacial premium tiers retain pricing power through yield-per-hectare guarantees.
Pricing Analysis
Volume procurement concentrates in standardized monocrystalline modules where cost compression intensifies from polysilicon supply concentration, while premium bifacial configurations with single-axis tracking command margin premiums based on albedo-enhanced yield guarantees and bankability certifications. Price differentiation hinges on module efficiency tier and Superintendency of Electricity and Fuels grid code compliance bundling. Utility providers exhibit lowest price sensitivity given long-term power purchase agreement anchoring, whereas commercial mining offtakers resist term premiums beyond fifteen-year contracting horizons.
Supply Chain Analysis
Superintendency of Electricity and Fuels certification requirements gate module and inverter qualification, filtering supplier pools to Tier 1 manufacturers with Chile-specific grid code validation. Manufacturing concentrates in China, Vietnam, and Malaysia for crystalline silicon cells, while tracker hardware sources from Spain and the United States. Polysilicon refining capacity in Xinjiang and Inner Mongolia creates single-source vulnerability for Chilean developers. Distribution runs through engineering-procurement-construction contractors with established Atacama project execution track records.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's solar sector reads as a consolidation play where transmission congestion penalties and storage mandate compliance costs force sub-scale developers into distressed exits or acquisition.
For Market Incumbents: Anchor long-term contracting positions through backward integration into battery storage co-location capabilities, securing grid interconnection queue priority in northern corridors. AES Andes and Engie Energía Chile should reinforce project development talent pools against Superintendency of Electricity and Fuels grid code expertise scarcity. Defensive consolidation targets include stranded pipeline developers with Environmental Evaluation Service permits but without storage capital deployment capacity. For New Entrants and Emerging Players: Engineering-procurement-construction partnerships with Spanish and Chinese tracker suppliers offer the most penetrable entry vector into Atacama ground-mounted installations. White-space targets concentrate in Antofagasta commercial rooftop segments serving copper extraction operations with 24-hour demand profiles and carbon reduction mandates. Green hydrogen electrolyzer offtake agreements with state-backed H2V initiatives provide differentiated contracting anchors against utility-scale merchant exposure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale developers with permitted pipelines in transmission-constrained Tarapacá corridors where storage co-location mandates have compressed valuations. Long-term viability centers on hybrid solar-storage configuration capabilities and lithium-ion battery supply chain relationships. The signal to watch is Ministry of Energy storage mandate timeline acceleration or grid reinforcement auction announcements that revalue stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Mandate Compliance | Battery system integration satisfies Superintendency of Electricity and Fuels interconnection requirements in northern corridors. |
| Bifacial Module Technology Licensing | Dual-sided cell deployments maximize yield per hectare in Atacama high-albedo desert conditions. |
| Green Hydrogen Offtake Partnership | Electrolyzer demand from state-backed H2V initiatives creates long-term contracting anchors beyond traditional utilities. |
| Transmission Queue Priority Securing | Early grid interconnection commitment mitigates curtailment risk in congested northern corridors. |
| Net-billing Framework Expansion | Commercial mining sector participation accelerates behind-the-meter distributed generation adoption under Ministry of Energy regulations. |
Study Parameters
Chilean Ministry of Energy policy filings, Superintendency of Electricity and Fuels interconnection databases, and Environmental Evaluation Service project registries formed the secondary backbone, supplemented by customs import records for module and inverter trade flows. Primary interviews with utility planning officers, independent power project developers, engineering-procurement-construction contractors, and grid operators validated capacity pipeline data and contracting tenor assumptions. Bottom-up project-level aggregation and top-down regulatory framework analysis triangulated market sizing across technology and installation segments.
Historical capacity additions and power purchase agreement tenor trends anchored projection modeling across the analysis window, with segmentation by product type, end user, installation configuration, and cell technology architecture. CAGRs derived from regression analysis of module cost decline curves, net-billing adoption elasticities, and transmission infrastructure investment schedules. Forecast inputs incorporated bifacial technology penetration rates and lithium-ion battery cost trajectories for hybrid project economics.
Caveats apply where polysilicon supply disruption, Environmental Evaluation Service approval timeline extension, or grid reinforcement delays could materially shift the outlook. Forecasts reflect assumptions regarding Ministry of Energy storage mandate implementation pace and copper price-linked commercial demand volatility. A model refresh is warranted upon material change in northern transmission corridor congestion pricing or green hydrogen offtake contract standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Roofing Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Distributed Solar Energy Market