
 Lithium Battery Liquid Cooling Pump Market | 2026-2036
Lithium Battery Liquid Cooling Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Liquid Cooling Pump Market Insights
Modular pump-heat-exchanger units is repositioning procurement patterns across battery pack integrators. Panasonic Corporation leverages its cell-to-pack expertise to bundle cooling hardware with module supply contracts. Grundfos Holding A/S anchors European production capacity for high-pressure centrifugal designs. NIDEC Corporation dominates compact brushless DC motor integration for Asian EV platforms.
A lithium battery liquid cooling pump circulates dielectric fluid through battery pack cold plates to maintain cell temperatures between 15°C and 35°C, preventing thermal runaway and capacity fade during fast-charging cycles. Centrifugal pumps occupy the largest share of product type demand due to their flow-rate efficiency in high-voltage EV architectures. Positive displacement pumps compete in energy storage solutions where precise low-flow control protects stationary battery racks. End-user concentration in electric vehicles concentrates margin pools with OEMs specifying sealed-for-life designs exceeding 15,000-hour operational targets.
FDA, EPA, and NHTSA standards in the US shape coolant material compatibility and crash-safety sealing requirements for automotive applications. REACH and RoHS frameworks in Europe restrict heavy-metal content in pump housings and magnetic drive assemblies. Stakeholders must monitor how China's GB standards and dual carbon goals accelerate domestic pump qualification timelines versus import certification pathways.
Market Dynamics
Cell-to-pack battery architectures are eliminating redundant cooling interfaces, forcing pump suppliers to integrate directly with module manufacturers rather than selling through tier-one thermal system integrators. This structural compression is redrawing procurement hierarchies across electric vehicle supply chains.
Growth Catalysts
- EU Green Deal decarbonization mandates:OEMs face binding fleet emissions targets that require active thermal management to enable fast-charging capability without battery degradation. Liquid cooling pumps become essential infrastructure for compliance-driven vehicle architectures.
- 800V high-voltage platforms:Premium EV architectures from Porsche, Hyundai, and Lucid generate heat loads that passive cooling cannot dissipate. Centrifugal pump demand concentrates around these performance-oriented vehicle programs.
- Stuttgart-Munich automotive cluster:Germany's battery pack engineering density creates concentrated specification authority, with local OEMs setting cooling system standards that cascade to global supplier qualifications.
Market Restraints
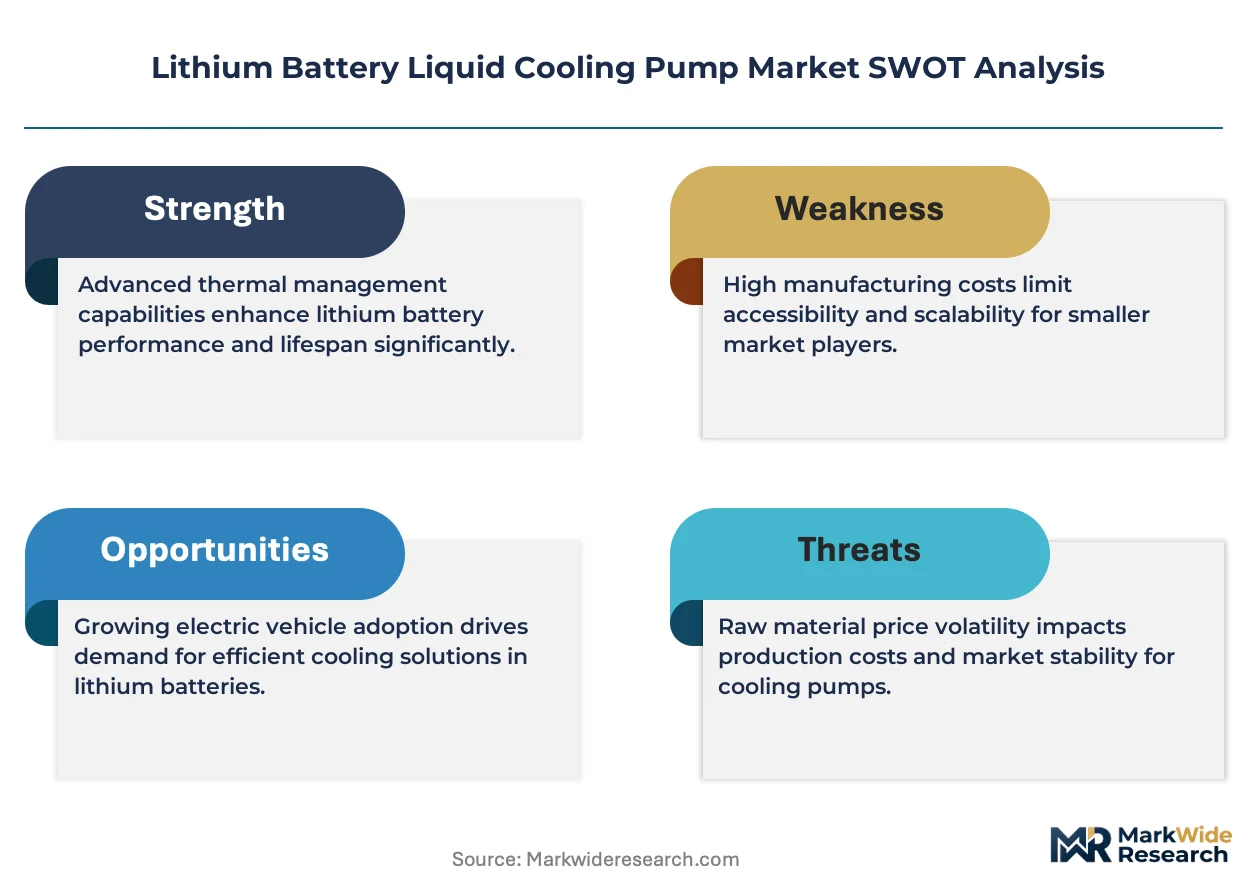
- Rare-earth magnet supply concentration:Brushless DC motors depend on neodymium processing dominated by Chinese refiners. Western pump manufacturers face input cost volatility and qualification delays when sourcing outside this concentrated supply base.
- Dielectric fluid compatibility certification:Pump seals and housings must demonstrate long-term chemical stability against proprietary coolant formulations from Castrol, Shell, and 3M. Each fluid qualification cycle extends product development timelines by 18-24 months.
- Stationary air-cooled alternatives:Grid-scale battery installations in temperate climates increasingly specify ambient cooling with thermal mass buffers, displacing liquid pumps in utility-scale storage applications below 50 MWh capacity.
Strategic Opportunities
- India's PLI scheme for battery manufacturing:Domestic cell production incentives are attracting pack integrators to Gujarat and Tamil Nadu. Pump suppliers can establish local assembly ahead of import substitution requirements.
- Second-life EV battery repurposing:Retired automotive packs deployed in stationary storage require cooling retrofit. Modular pump-heat-exchanger units sized for degraded thermal profiles represent an emerging aftermarket segment.
- China's dual carbon goals:Provincial energy intensity targets are accelerating qualification timelines for domestic pump manufacturers. Joint ventures with local motor suppliers offer faster market access than independent import certification.
Industry Challenges
- Systems engineering talent scarcity:Pump suppliers must hire thermal-fluid specialists capable of simulating two-phase flow and cold plate manifold optimization. Competition for these skills intensifies against battery cell and power electronics manufacturers.
- 15,000-hour sealed-for-life validation:OEM specifications require accelerated aging protocols that compress five-year operational testing into 18-month program schedules. Test facility capacity constraints bottleneck product launches.
- Legacy vehicle platform integration:Retrofit cooling architectures for converted combustion vehicle platforms demand compact pump designs that fit existing underbody packaging without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Liquid Cooling Pump Market |
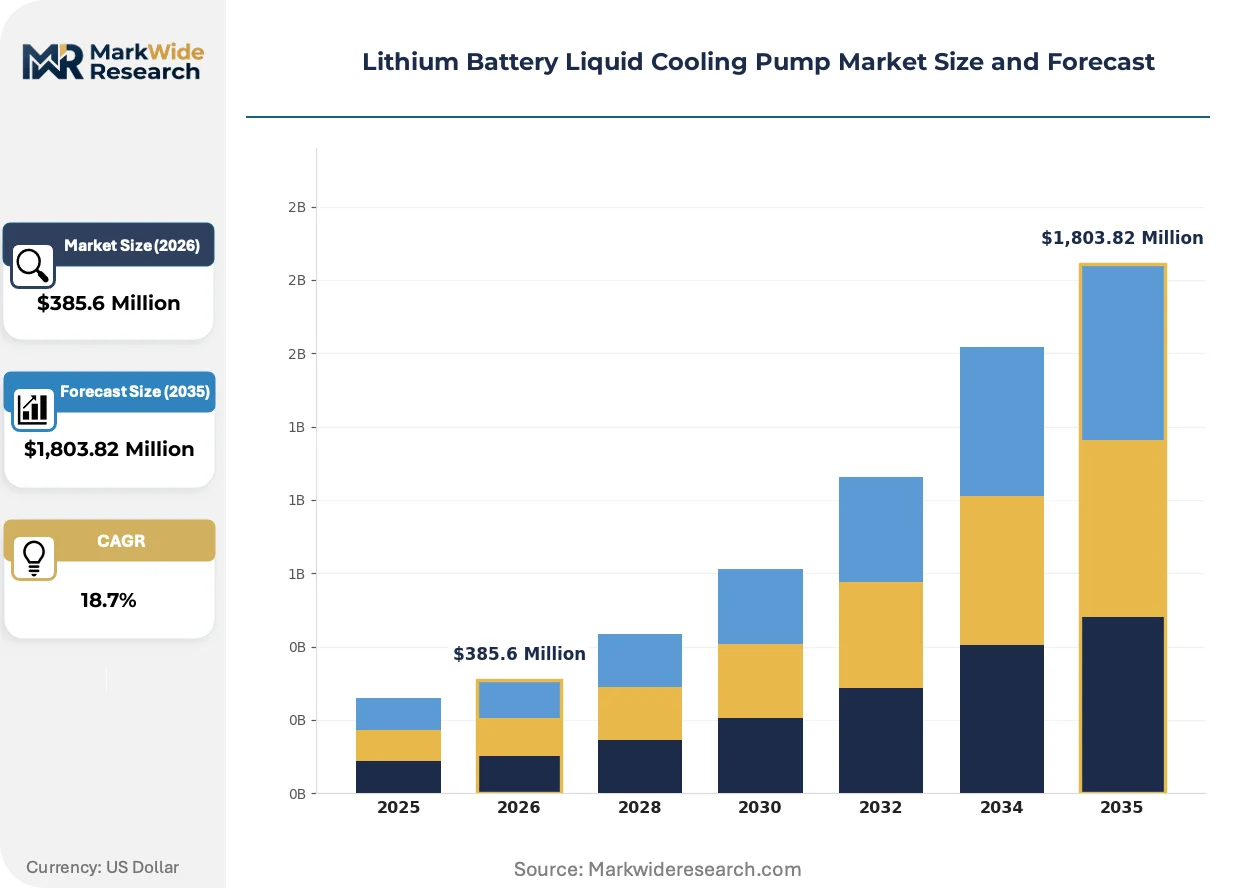
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Immersible Pumps Technology: Thermal Management, Liquid Cooling, Heat Exchanger, Fluid Dynamics End User: Electric Vehicles, Renewable Energy Systems, Data Centers, Industrial Applications Application: Battery Thermal Regulation, Cooling Systems, Energy Storage Solutions, Power Electronics |
| Companies Covered | Panasonic Corporation, WILO SE, Grundfos Holding A/S, Johnson Electric Holdings Limited, NIDEC Corporation, Pentair, Boyd Thermal Division, Miba, Laird Thermal Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Liquid Cooling Pump Market Trends and Innovations
Smart pump control algorithms and additive manufacturing of flow-optimized housings are converging to redefine performance benchmarks. Suppliers are racing to embed condition-monitoring capabilities that predict seal degradation before coolant leakage triggers battery safety shutdowns.
Integrated pump-inverter-heat-exchanger modules are consolidating discrete thermal management components into single procurement SKUs. Tier-one suppliers including Hanon Systems and Mahle are specifying these consolidated units for 2026 vehicle platforms. The consolidation is compressing margins for standalone pump manufacturers while rewarding full-system integrators with multi-year supply agreements.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing coolant formulation changes across European vehicle programs. ECHA's proposed PFAS ban threatens dielectric fluids currently qualified for pump seal compatibility. German OEMs are accelerating alternative fluid validation with fluorine-free chemistries from Fuchs and BASF, compressing supplier recertification timelines ahead of anticipated enforcement.
Cell manufacturers are unbundling cooling system procurement from pack assembly contracts. CATL and BYD now specify pump performance requirements directly, bypassing traditional thermal system integrators. This disintermediation is visible across Chinese EV platforms where battery suppliers wield greater specification authority than vehicle OEMs. Western pump manufacturers must reconfigure sales organizations to engage cell producers as primary customers.
Lithium Battery Liquid Cooling Pump Market Segmentation
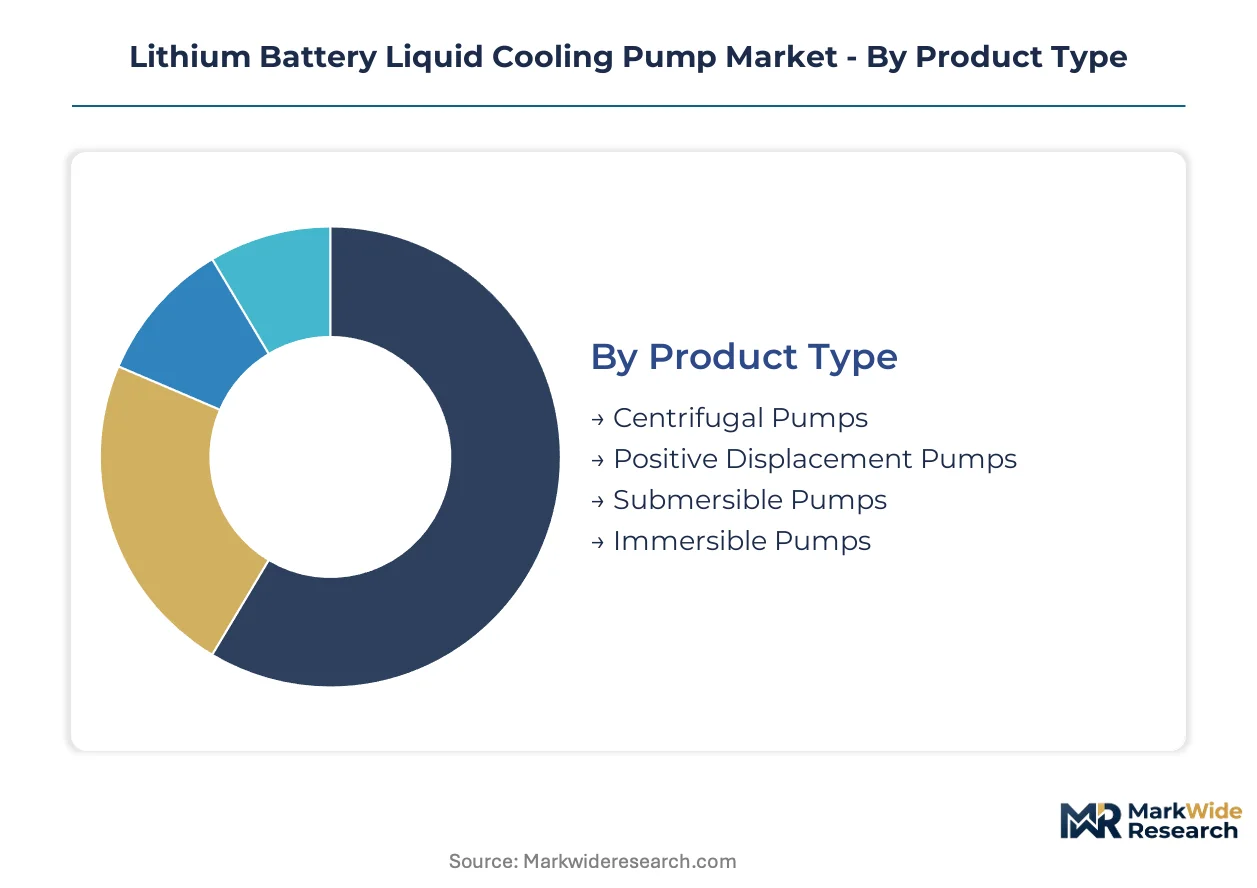
Liquid cooling pump procurement varies sharply across thermal architectures. Specification authority sits with different stakeholders depending on whether pumps integrate into vehicle platforms, stationary storage, or industrial systems.
Product Type:
Impeller geometry and motor integration define performance ceilings across voltage classes and flow-rate requirements.
- Centrifugal Pumps:Radial impeller designs deliver high flow rates with minimal pulsation for 800V EV architectures. German OEMs around Stuttgart specify these for premium electric vehicle programs where thermal loads exceed passive dissipation capacity.
- Positive Displacement Pumps:Gear or vane mechanisms provide precise volumetric control for low-flow battery rack protection. Energy storage integrators in stationary applications favor these where coolant volume must track exactly with cell temperature rise.
- Submersible Pumps:Fully sealed motor-casing integration eliminates shaft seals for immersion-rated battery enclosures.
- Immersible Pumps:Partial submersion tolerance suits modular pack designs with flooded cooling channels.
Centrifugal pumps lead on scale across automotive volume; positive displacement pumps lead on momentum in grid-scale storage deployments.
Technology:
Control sophistication separates commodity hardware from specification-grade thermal infrastructure.
- Thermal Management:Integrated sensor arrays enable real-time flow adjustment based on cell temperature mapping. CATL and BYD specify these smart-control variants directly, bypassing traditional tier-one thermal integrators in Chinese EV supply chains.
- Liquid Cooling:Dielectric fluid circulation through cold plate manifolds remains the baseline architecture for fast-charging capability. OEMs binding to EU Green Deal fleet targets require these systems to prevent battery degradation under rapid charge cycles.
- Heat Exchanger:Pump-heat-exchanger bundled units consolidate procurement SKUs for 2026 vehicle platforms.
- Fluid Dynamics:Computational flow optimization reduces pump power draw and extends sealed-for-life operational windows.
Liquid cooling leads on scale as the foundational architecture; thermal management leads on momentum as smart-control integration accelerates.
End User:
Operational duty cycles and safety certification requirements fragment demand across mobility, stationary, and compute infrastructure.
- Electric Vehicles:Sealed-for-life designs exceeding 15,000-hour targets dominate procurement, with crash-safety sealing per NHTSA requirements. The Stuttgart-Munich automotive cluster concentrates specification authority for these programs.
- Renewable Energy Systems:Grid-tied battery installations in temperate climates increasingly favor ambient cooling with thermal mass buffers, displacing liquid pumps below 50 MWh capacity thresholds.
- Data Centers:Hyperscale compute facilities require redundant cooling for UPS battery backup systems.
- Industrial Applications:Forklift and material handling equipment demand ruggedized pump housings for vibration-intensive environments.
Electric vehicles lead on scale; renewable energy systems lead on momentum as second-life battery repurposing creates cooling retrofit demand.
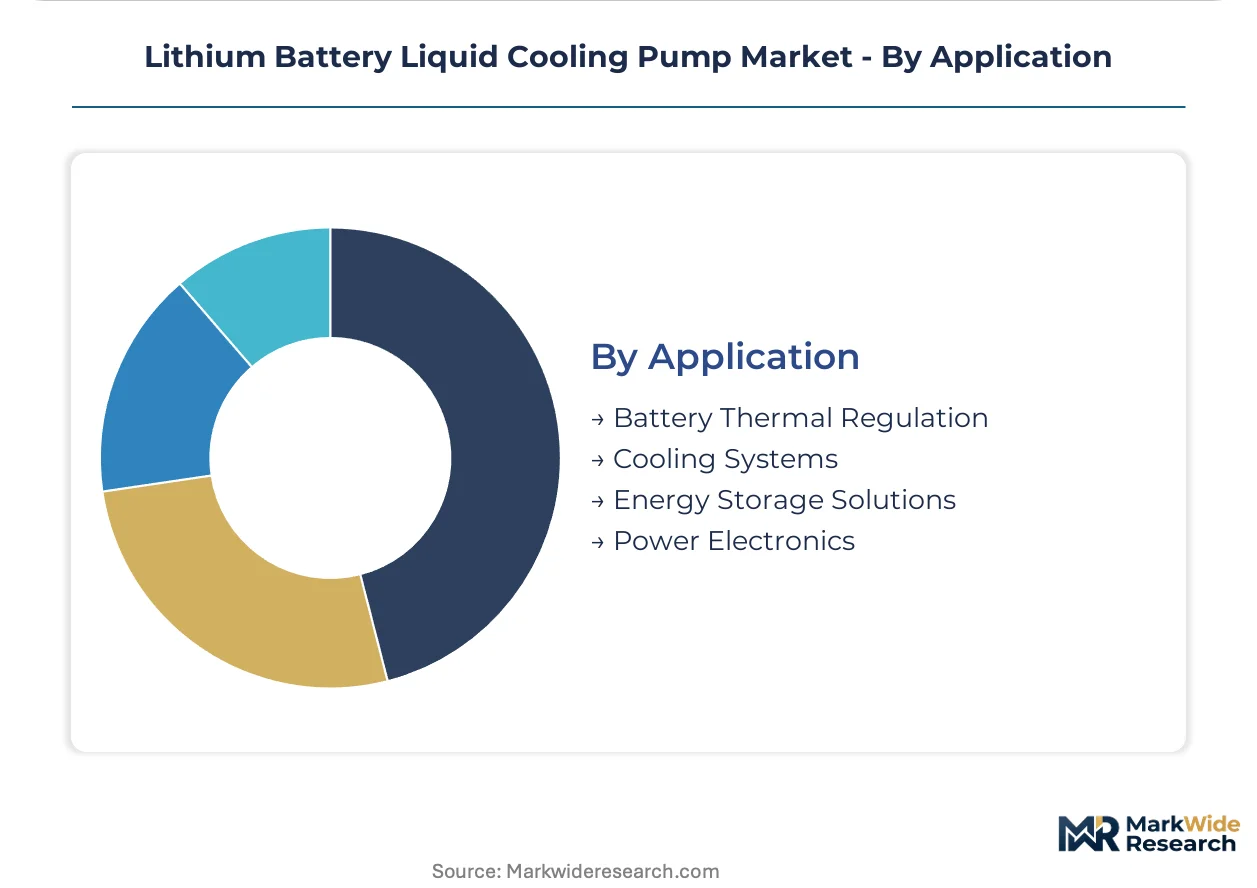
Application:
Functional positioning within the thermal loop determines pump specification authority and margin capture.
- Battery Thermal Regulation:Cell-to-pack architectures eliminate redundant cooling interfaces, forcing direct pump integration with module manufacturers rather than tier-one system integrators. This structural compression redrew procurement hierarchies across electric vehicle supply chains.
- Cooling Systems:Chiller-integrated loops for high-performance computing and power electronics require corrosion-resistant alloys for long-term dielectric fluid compatibility.
- Energy Storage Solutions:Utility-scale installations specify pumps with wide turndown ratios for variable load following.
- Power Electronics:Inverter and converter cooling demands compact form factors for underbody packaging constraints.
Battery thermal regulation leads on scale; cooling systems lead on momentum as 800V platform proliferation intensifies heat dissipation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive thermal management engineering through Stuttgart's powertrain heritage, establishing specification authority that now extends to electric vehicle cooling architectures worldwide.
Germany
The Stuttgart-Munich automotive cluster concentrates battery pack engineering density, with OEMs setting cooling system standards that cascade to global supplier qualifications. EU Green Deal fleet emissions mandates bind German manufacturers to active liquid cooling for fast-charging capability without battery degradation. Bavaria's manufacturing corridor hosts qualification facilities for 15,000-hour sealed-for-life pump validation protocols.
China
Domestic cell production from CATL and BYD now specifies pump performance requirements directly, bypassing traditional thermal system integrators. NMPA battery safety standards and provincial dual carbon goals accelerate qualification timelines for domestic manufacturers versus import certification pathways. The Yangtze River Delta hosts joint ventures between local motor suppliers and Western pump manufacturers seeking faster market access.
United States
800V high-voltage platform proliferation from premium EV manufacturers generates heat loads that passive cooling cannot dissipate, concentrating centrifugal pump demand. NHTSA crash-safety sealing requirements and EPA coolant material compatibility standards shape procurement specifications for automotive applications. Michigan's automotive engineering base maintains thermal-fluid simulation expertise for cold plate manifold optimization.
India
PLI scheme incentives for domestic battery manufacturing attract pack integrators to Gujarat and Tamil Nadu, creating localized assembly opportunities ahead of import substitution requirements. Central Electricity Authority grid codes for utility-scale storage influence cooling system specifications for stationary applications. The Delhi-Mumbai Industrial Corridor hosts emerging qualification facilities for pump-heat-exchanger module testing.
Japan
Compact brushless DC motor integration expertise supports Asian EV platform requirements, with METI industrial policy directing supply chain resilience investments. JIS standards for automotive electrical components provide qualification frameworks for pump motor assemblies. The Nagoya-Toyota manufacturing belt maintains precision machining capacity for high-pressure centrifugal impeller production.
Lithium Battery Liquid Cooling Pump Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal integration depth, with full-system bundlers capturing multi-year supply agreements while standalone component suppliers face margin compression. The vendor base stratifies between cell-to-pack integrators, motor specialists, and fluid handling conglomerates. Three archetypes dominate: automotive-tier thermal system suppliers, precision motor manufacturers, and diversified pump engineering groups. Competitive moves concentrate on M&A for thermal integration capabilities and capacity expansion near battery cell production clusters.
Among diversified pump engineering groups, Grundfos Holding A/S and WILO SE exemplify European production capacity for high-pressure designs, while NIDEC Corporation anchors compact motor integration expertise for Asian platforms. Panasonic Corporation represents the cell-to-pack bundling archetype, leveraging module supply contracts to attach cooling hardware procurement. These three occupy positions across the value chain spectrum from component supply to integrated thermal system provision, reflecting the structural compression redrawing procurement hierarchies.
| Leading Market Players |
|---|
| Panasonic Corporation |
| WILO SE |
| Grundfos Holding A/S |
| Johnson Electric Holdings Limited |
| NIDEC Corporation |
| Pentair |
| Boyd Thermal Division |
| Miba |
| Laird Thermal Systems |
| Others |
Pricing and Supply Chain Analysis
Backward integration into brushless DC motor production anchors both supply security and margin retention for pump manufacturers confronting rare-earth magnet price volatility. This captive production choice separates specification-grade suppliers from commodity assemblers in procurement hierarchies reshaped by cell-to-pack architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sealed-for-life automotive designs from industrial retrofit units. Premium tiers command certification-grade positioning against NHTSA crash-safety and EU REACH substance restrictions, while economy segments serve stationary storage with reduced validation burdens. Cost compression in mid-tier centrifugal designs is intensifying because CATL and BYD now specify pump performance directly, bypassing traditional thermal integrator markups. Fleet operators and second-life battery repurposers exhibit highest price sensitivity; German OEMs around Stuttgart demonstrate lowest sensitivity due to 15,000-hour operational targets.
Supply Chain Analysis
Dielectric fluid compatibility certification gates supplier entry, with each Castrol, Shell, or 3M formulation qualification extending development timelines. Neodymium magnet processing concentrates in China, while precision impeller machining clusters in Germany and Japan. Pump housings and magnetic drive assemblies draw from aluminum and engineered polymer feedstocks. Single-source vulnerability runs through Chinese rare-earth refiners. Distribution runs through direct engagement with cell manufacturers and tier-one thermal system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the shift toward 800V high-voltage platforms demanding specification-grade thermal management. Premium pump designs with embedded condition-monitoring now capture multi-year supply agreements unavailable to commodity competitors.
For Market Incumbents: Anchor qualification capacity in Bavaria's testing corridor to defend against emerging Asian motor suppliers accelerating domestic certification under China's dual carbon goals. Deepen captive magnet sourcing through joint ventures with Yangtze River Delta refiners. Prioritize smart-control algorithm development as CATL and BYD disintermediate traditional thermal integrators. For New Entrants and Emerging Players: Direct-to-cell-manufacturer sales channels bypass entrenched tier-one relationships in Chinese EV supply chains. Target India's PLI scheme beneficiaries in Gujarat and Tamil Nadu before import substitution requirements mature. Second-life battery cooling retrofits offer penetrable white-space with degraded thermal profile specifications. For Investors and Strategic Acquirers: Roll-up economics work for precision motor specialists because cell-to-pack bundling compresses standalone pump margins and rewards integrated thermal system provision. Five-to-ten year viability favors suppliers with sealed-for-life validation protocols and direct cell manufacturer relationships. Watch for ECHA PFAS enforcement timing as inflection indicator for coolant formulation recertification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Local Motor Suppliers | Accelerates NMPA qualification timelines versus independent import certification pathways in China. |
| Smart-Control Algorithm Development | Enables predictive seal degradation monitoring before coolant leakage triggers battery safety shutdowns. |
| Capacity Expansion Near Cell Production Clusters | Positions suppliers for CATL and BYD direct procurement specifications bypassing thermal integrators. |
| Additive Manufacturing of Flow-Optimized Housings | Reduces pump power draw and extends sealed-for-life operational windows for 800V platforms. |
| Fluorine-Free Coolant Validation Partnership | Secures compatibility certification ahead of anticipated ECHA PFAS ban enforcement in European vehicle programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured thermal system engineers at German OEMs, procurement leads at CATL and BYD, pump R&D directors at Grundfos and NIDEC, and aftermarket specialists in second-life battery repurposing. Secondary validation drew from NHTSA safety filings, ECHA substance restriction proposals, EU Green Deal fleet target documentation, and production databases tracking 800V platform rollouts. Bottom-up pump shipment modeling triangulated against top-down EV thermal system spend estimates.
Comparable-period anchoring used historical adoption curves from high-voltage platform introductions to inform projection pacing across the analysis window. Segmentation dimensions modeled included pump product type, control technology sophistication, end-use operational duty cycle, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to cell-to-pack architecture penetration assumptions and fast-charging infrastructure buildout trajectories. Dielectric fluid formulation change cycles and rare-earth magnet price volatility informed scenario bounds.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook. Forecasts reflect assumptions about 800V platform proliferation rates and PFAS regulatory enforcement timing. A model refresh is warranted upon material change in cell manufacturer procurement centralization or coolant chemistry qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Fan Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Global Chiller Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Thawing System Market
Cooling Systems
Energy Storage Temperature Control Equipment Market