
 Europe Air Source Heat Pump Market | 2026-2036
Europe Air Source Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Source Heat Pump Market Analysis
Residential retrofit buyers are unwinding the historical dominance of new-build developers in European heat pump procurement. Vaillant Group leverages its captive distribution network across Germany and Central Europe to secure installer loyalty. NIBE Industrier AB anchors its position through backward integration into controller electronics and buffer tank manufacturing. Daikin Industries competes on inverter compressor technology leadership, particularly in cold-climate air-to-water systems.
Europe air source heat pumps are electrically driven vapor-compression devices that extract thermal energy from ambient air and transfer it via refrigerant cycle to hydronic distribution or forced-air systems, typically achieving coefficient of performance ratings between 3.0 and 5.0 depending on source temperature and emitter design. Monoblock systems dominate volume in Northern Europe due to simpler installation and reduced refrigerant handling requirements, while split systems concentrate margin pools in Mediterranean markets where cooling integration commands premium positioning. Air-to-water technology leads the commercial and residential heating replacement segment, whereas air-to-air configurations occupy the fastest-growing niche in hybrid renovation projects pairing heat pumps with existing radiator infrastructure.
The EU Green Deal, F-Gas Regulation, and CE marking under the Ecodesign Directive collectively mandate minimum seasonal performance factors and restrict high-global-warming-potential refrigerants, reshaping manufacturer R&D priorities and product qualification pathways. National transpositions vary, with Germany's Building Energy Act and France's RE2020 environmental regulation imposing the strictest fossil-fuel phase-out timelines. Stakeholders must monitor refrigerant transition timelines and national subsidy exhaustion rates to calibrate production allocation and channel investment across the European installation base.
Market Dynamics
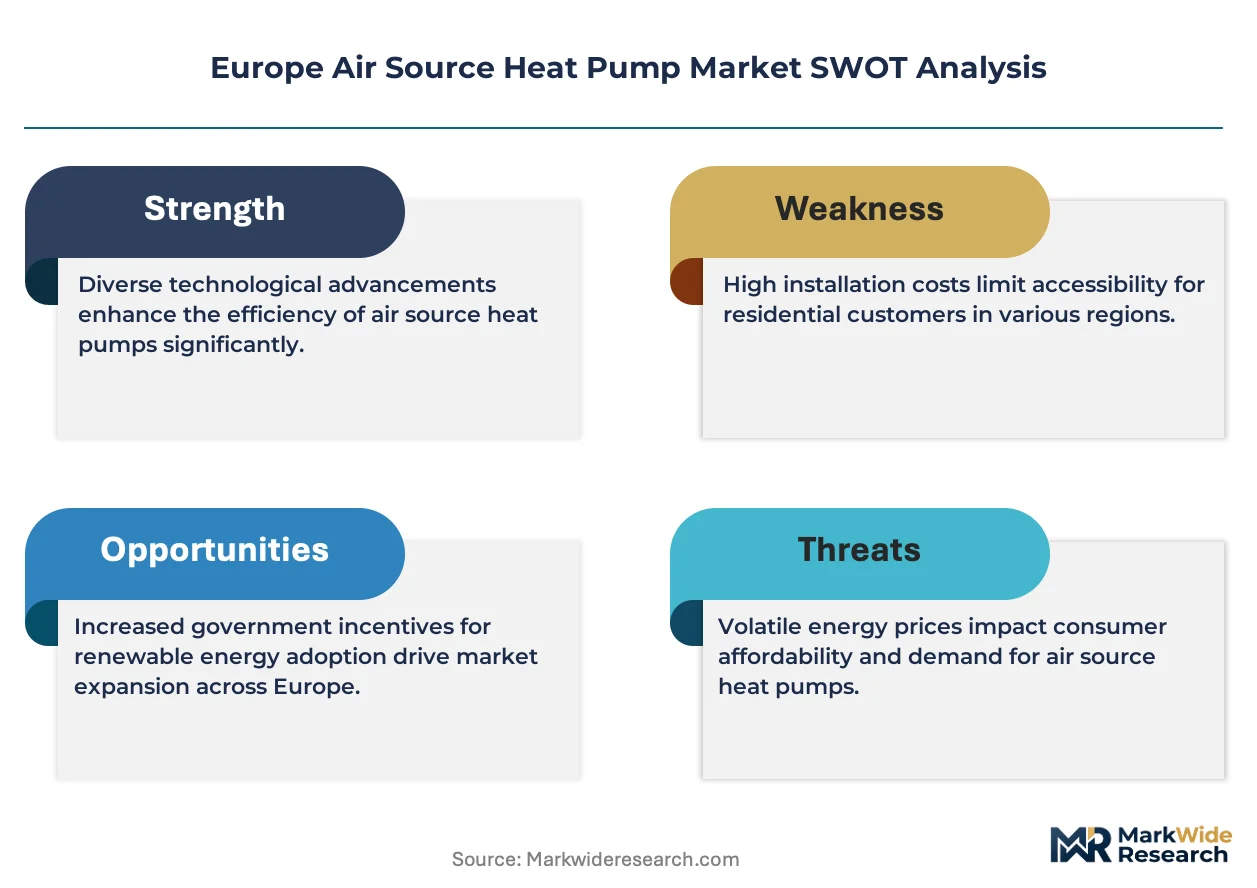
The residential retrofit segment is displacing new-build developers as the dominant procurement channel across Europe, driven by fossil-fuel boiler bans in national building codes and subsidy exhaustion timelines that favor immediate replacement cycles over greenfield construction.
Growth Catalysts
- EU Green Deal building renovation mandates:Member states must double renovation rates, creating replacement demand for fossil heating systems in existing residential stock.
- Germany's Building Energy Act:Mandates renewable heating in new buildings and replacement scenarios, accelerating air-to-water heat pump specification.
- R-32 refrigerant transition:Lower global-warming-potential alternatives are qualifying products for enhanced subsidy tiers under national clean heat programs.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and coil material costs swing with commodity markets, compressing manufacturer margins on fixed-price contracts.
- Installer capacity concentration:Certified technician pools cluster in Germany, France, and Northern Italy, creating bottlenecks for retrofit deployment in Eastern Europe.
- Grid reinforcement lag:Distribution network upgrades in rural France and Southern Italy trail heat pump electrification loads, delaying connection approvals.
Strategic Opportunities
- Polish and Romanian residential markets:Coal boiler replacement programs and EU cohesion funding create underpenetrated demand for air-to-water systems.
- Hybrid heating configurations:Air-to-air heat pumps paired with existing radiator infrastructure unlock renovation projects where full hydronic replacement is cost-prohibitive.
- France's MaPrimeRénov' subsidy scaling:Income-graded incentives for low-carbon heating are pulling mid-income households into heat pump procurement.
Industry Challenges
- Refrigerant handling certification gaps:F-Gas Regulation compliance requires technician retraining across the installation base, slowing deployment velocity.
- Buffer tank and controller integration complexity:Legacy heating system retrofits demand custom hydraulic design, extending project timelines and callback rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Source Heat Pump Market |
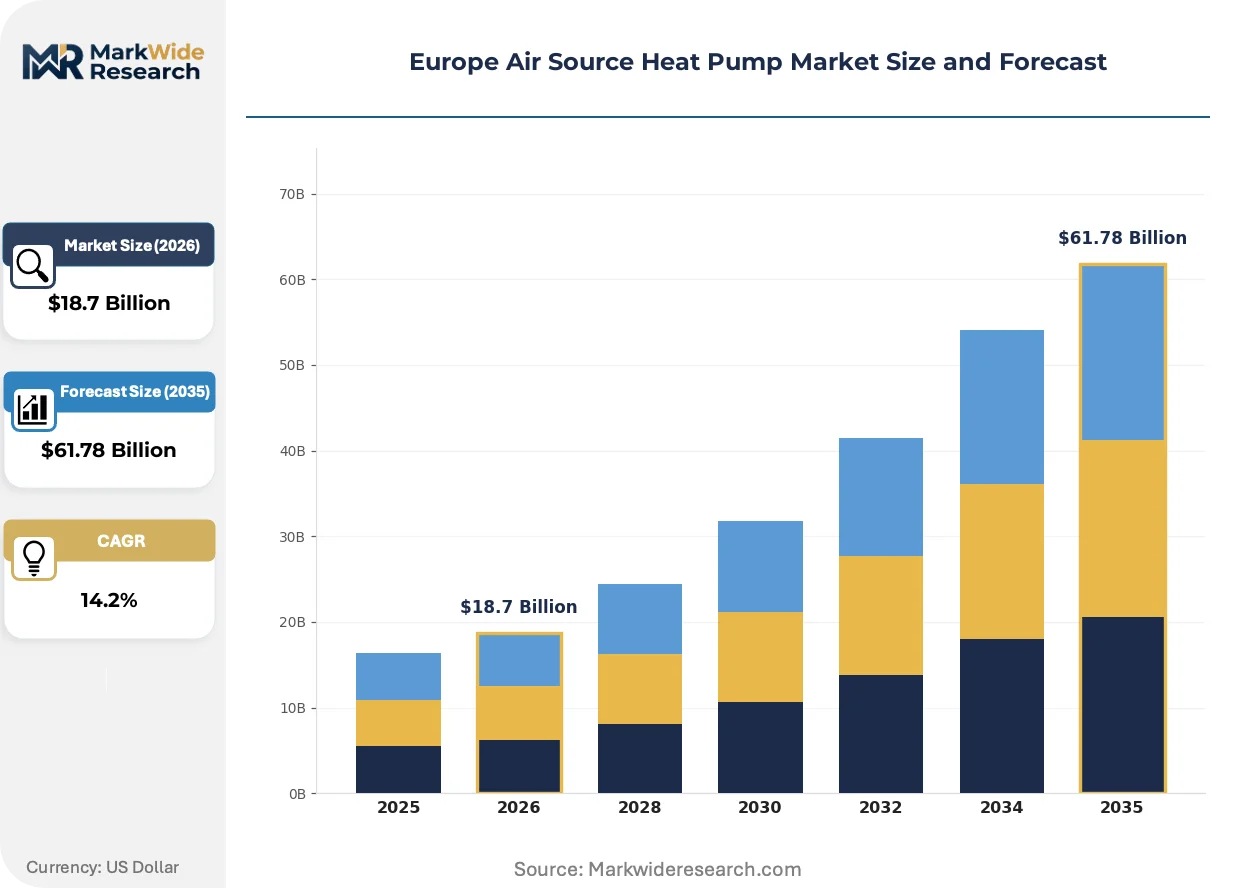
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Monoblock Systems, Hybrid Systems, Variable Refrigerant Flow Technology: Air-to-Water, Air-to-Air, Inverter Technology, Reverse Cycle End User: Residential, Commercial, Industrial, Government Application: Space Heating, Water Heating, Underfloor Heating, Swimming Pools |
| Companies Covered | Vaillant Group, Viessmann Group, NIBE Industrier AB, Daikin Industries, Stiebel Eltron, Mitsubishi Electric Corporation, Alpha Innotec, ELCO, Kensa Heat Pumps, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Source Heat Pump Market Emerging Trajectories
Refrigerant chemistry, compressor architecture, and distribution logistics are converging to reshape product qualification pathways and channel economics across European markets.
Inverter-driven scroll compressors with vapor injection circuits are miniaturizing cold-climate air-to-water units, enabling outdoor monoblock footprints that fit narrow urban utility spaces. Scandinavian residential buyers are specifying these systems for sub-zero operation without auxiliary resistance heating. The technology is compressing installation labor hours and refrigerant charge volumes, shifting margin capture toward manufacturers with captive controller electronics.
The F-Gas Regulation's phasedown schedule is forcing R-410A exit and R-32 or R-454B transition across the European product portfolio. Equipment qualification timelines have lengthened as manufacturers resubmit CE marking documentation under Ecodesign Directive seasonal performance factor thresholds. Cold-climate air-to-water systems face the steepest recertification burden, concentrating compliance investment among integrated producers.
Installer loyalty programs are displacing wholesale distributor rebates as the primary channel incentive mechanism across Germany and Austria. National heating contractors are consolidating procurement through direct manufacturer agreements, bypassing traditional HVAC merchants. This concentration is most visible in Bavaria and Baden-Württemberg, where multi-unit residential retrofits dominate volume and project bundling favors single-source supply relationships.
Europe Air Source Heat Pump Market Segmentation
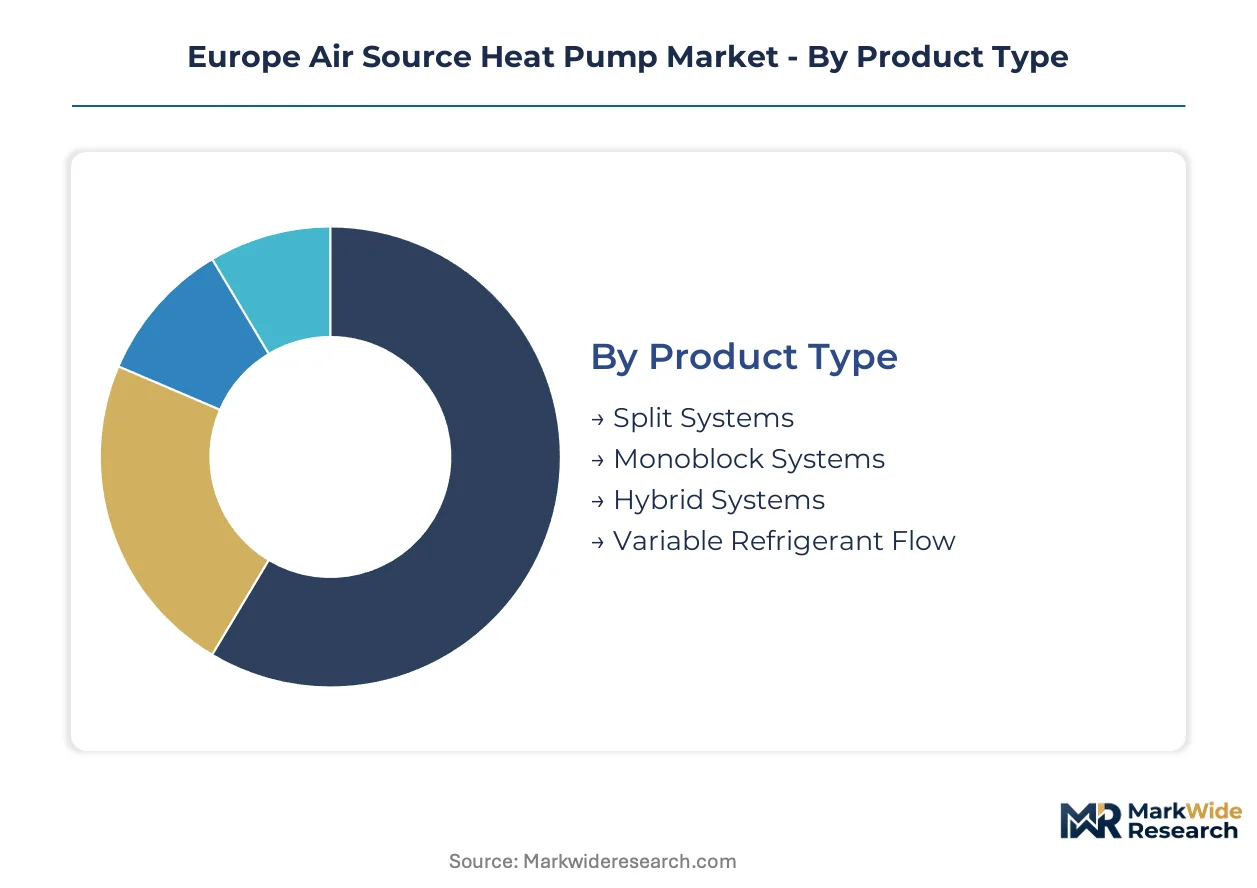
Segmentation in the Europe air source heat pump market reveals how refrigerant architecture, distribution hydraulics, and end-use thermal loads allocate margin across fundamentally different equipment categories. Understanding these divisions exposes where manufacturers capture value versus where price competition erodes returns.
Product Type:
Margin pools concentrate in configurations that minimize field refrigerant handling and accelerate installation velocity.
- Monoblock Systems:Factory-sealed refrigerant circuits eliminate on-site charging requirements and reduce F-Gas Regulation compliance burdens for installers. Northern European retrofits specify these units for their simplified hydronic connection and reduced callback rates in sub-zero climates.
- Split Systems:Separate indoor and outdoor modules allow flexible placement in constrained urban utility spaces. Mediterranean markets absorb this architecture where cooling integration commands premium positioning alongside heating functionality.
- Hybrid Systems:Bivalent configurations pairing heat pumps with fossil-fuel backup address grid capacity constraints in rural France and Southern Italy.
- Variable Refrigerant Flow:Multi-zone commercial applications drive specification where building automation integration justifies higher equipment complexity.
Monoblock systems hold installed capacity. Split systems are rotating up the share rankings in renovation-heavy Southern European markets.
Technology:
Coefficient of performance thresholds under the Ecodesign Directive segment value capture between basic and advanced thermodynamic cycles.
- Air-to-Water:Hydronic distribution systems dominate residential boiler replacements across Germany, France, and Italy where existing radiator or underfloor infrastructure reduces retrofit capital intensity. The technology anchors manufacturer R&D investment for cold-climate seasonal performance factor compliance.
- Inverter Technology:Variable-speed compressor modulation matches thermal output to building load curves, trimming electricity consumption during partial-load conditions. Scandinavian specification rates for these systems exceed continental averages due to extended heating season runtimes.
- Air-to-Air:Direct forced-air delivery occupies hybrid renovation niches where hydronic replacement is cost-prohibitive.
- Reverse Cycle:Cooling-capable units capture seasonal utilization premiums in markets with summer air conditioning demand.
Air-to-water technology holds installed capacity. Inverter-equipped systems are rotating up the share rankings as efficiency thresholds tighten.
End User:
Procurement authority and subsidy access patterns concentrate volume differently across customer types.
- Residential:Individual households accessing national clean heat programs drive replacement cycles for fossil-fuel boilers. Germany's Building Energy Act and France's MaPrimeRénov' structure create immediate demand pull through income-graded incentives.
- Commercial:Multi-unit residential and light commercial buildings specify higher-capacity monoblock units through consolidated contractor procurement. Bavarian and Baden-Württemberg project bundling favors direct manufacturer agreements bypassing traditional HVAC merchants.
- Industrial:Process heat applications remain limited by temperature lift constraints in current vapor-compression architectures.
- Government:Public building renovation mandates under EU Green Deal targets create procurement volume with extended tender timelines.
Residential retrofits hold installed capacity. Commercial project bundling is rotating up the share rankings through installer consolidation.
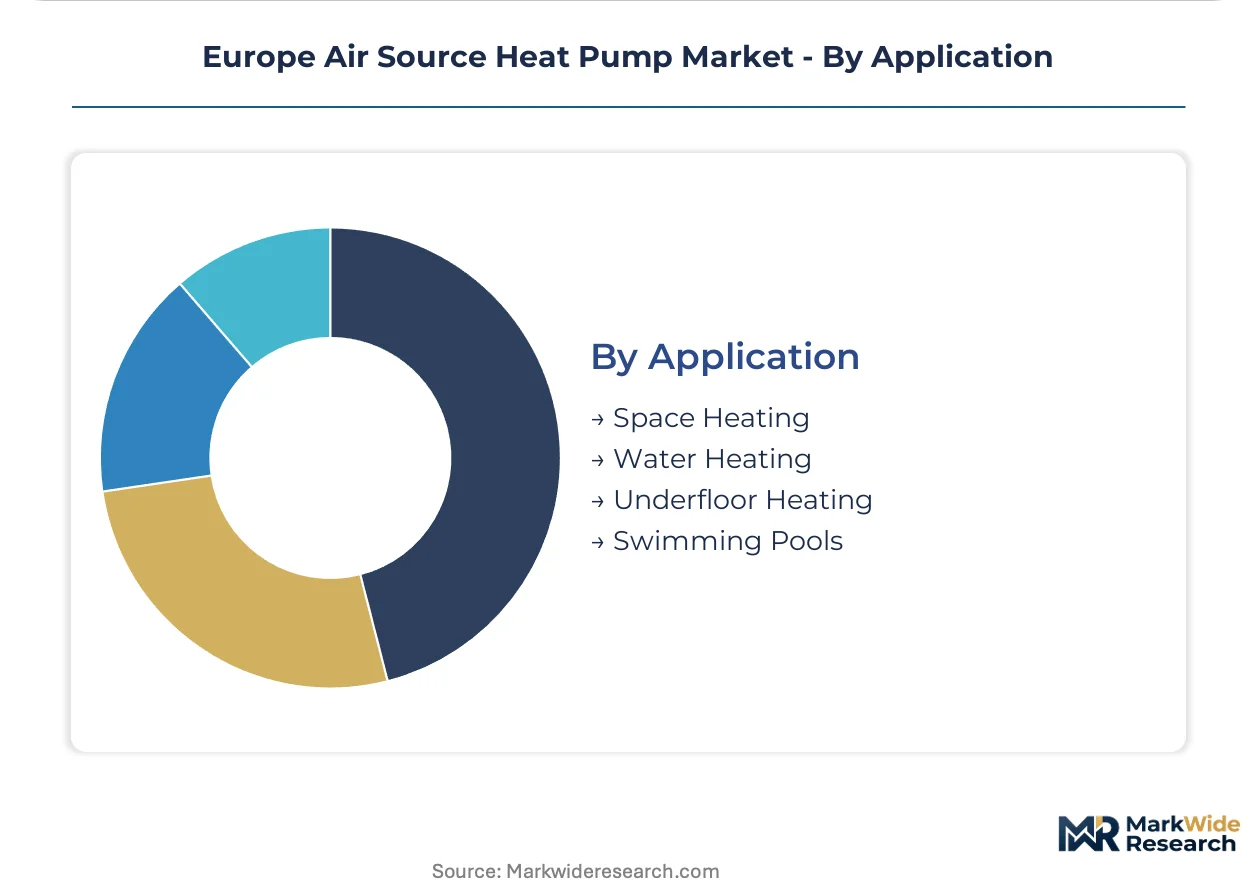
Application:
Temperature requirements and emitter design determine equipment specification and margin structure.
- Space Heating:Low-temperature hydronic distribution through underfloor or oversized radiators optimizes heat pump coefficient of performance. New-build specifications in Germany and France increasingly mandate this configuration under renewable heating requirements.
- Water Heating:Dedicated domestic hot water cylinders with compressor-integrated or separate heat pump modules address year-round thermal demand independent of space heating seasons.
- Underfloor Heating:Low-temperature emitter design enables smaller compressor capacity for equivalent thermal output, reducing equipment capital cost.
- Swimming Pools:Seasonal operation in Mediterranean climates absorbs air-to-air configurations with limited cold-climate relevance.
Space heating holds installed capacity. Water heating applications are rotating up the share rankings as all-electric building codes advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic electricity interconnector corridor underwrites Northern Europe's heat pump electrification, while Alpine hydropower reservoirs stabilize Southern European grid capacity for residential retrofits.
Germany
Coal district heating conversions in the Ruhr and Lusatia regions drive air-to-water system demand. The Building Energy Act mandates renewable heating in replacement scenarios, accelerating specification timelines. Bavarian and Baden-Württemberg installer networks concentrate procurement through direct manufacturer agreements, bypassing traditional HVAC merchants.
France
MaPrimeRénov' income-graded subsidies pull mid-income households into heat pump procurement ahead of fossil-fuel phase-out deadlines. RE2020 environmental regulation imposes strict carbon thresholds on new construction and major renovations. The Lyon-Grenoble industrial corridor hosts controller electronics manufacturing clusters serving cold-climate monoblock production.
Italy
Northern Italian coal boiler replacement programs create concentrated demand in Lombardy and Veneto. National building code transpositions of EU Green Deal mandates vary by region, with stricter enforcement in emissions-controlled zones. The Po Valley manufacturing belt supplies heat exchanger components to German and French system integrators.
Poland
EU cohesion funding for coal-dependent regions finances residential retrofits in Silesia and Lesser Poland. The country's national energy regulator structures grid connection queues to prioritize heat pump electrification in urban districts. Warsaw and Krakow installer training centers address technician certification gaps under F-Gas Regulation requirements.
United Kingdom
The Boiler Upgrade Scheme caps grant values below continental European levels, constraining uptake in cost-sensitive segments. Ofgem distribution network operators lag in rural grid reinforcement for heat pump loads in Wales and Northern England. Scottish Highlands cold-climate specifications favor monoblock systems with vapor injection compressors.
Europe Air Source Heat Pump Market Vendor Landscape
Listed leaders compete with private specialists across captive distribution networks and refrigerant handling certification assets. The market structure concentrates around integrated manufacturers with backward control over controller electronics and buffer tank production, alongside regional specialists leveraging installer loyalty programs. Three archetypes dominate: full-system integrators with captive distribution, component specialists supplying branded OEMs, and cold-climate technology developers. Competitive moves center on direct contractor procurement agreements and F-Gas Regulation compliance bundling with installation training.
Within the full-system integrator tier, Vaillant Group and NIBE Industrier AB exemplify manufacturers capturing margin through captive supply chain control and direct installer channel access. Daikin Industries occupies a position representing inverter compressor technology leadership in cold-climate applications. These three anchors illustrate how competitive positioning depends on whether manufacturers control distribution logistics, core thermodynamic components, or both.
| Leading Market Players |
|---|
| Vaillant Group |
| Viessmann Group |
| NIBE Industrier AB |
| Daikin Industries |
| Stiebel Eltron |
| Mitsubishi Electric Corporation |
| Alpha Innotec |
| ELCO |
| Kensa Heat Pumps |
| Others |
Supply Flow & Price Mechanics
Factory utilization rates above 80% at German and Italian monoblock assembly plants compress per-unit fixed costs and establish price floors that smaller Eastern European competitors struggle to match. This scale concentration enables tiered pricing structures while copper and aluminum volatility forces margin discipline across the supply base.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates inverter-equipped cold-climate systems from basic air-to-air units and entry-level monoblock configurations. Price differentiation rests on F-Gas Regulation compliance certification and seasonal performance factor ratings under Ecodesign Directive thresholds. Cost compression in the economy tier is intensifying because Polish and Romanian buyers access EU cohesion subsidies that cap acceptable price points. Residential retrofit households in France and Germany show least price sensitivity when MaPrimeRénov' and Building Energy Act incentives cover 40-50% of installed cost.
Supply Chain Analysis
Germany and Italy anchor heat pump system integration and controller electronics manufacturing, while China supplies compressor motors and copper tubing. The European supply chain draws from aluminum smelters in Norway and Spain for heat exchanger coils, with refrigerant gas production concentrated in Belgian and Dutch chemical complexes. Single-source vulnerability sits with inverter controller chipsets sourced from East Asian semiconductor fabricators. Distribution runs through direct manufacturer agreements with consolidated heating contractors in Bavaria and Baden-Württemberg, bypassing traditional HVAC wholesale merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through F-Gas certification requirements and installer loyalty programs creates durable barriers against price competition.
For Market Incumbents: Fortify captive distribution networks by embedding buffer tank and controller electronics production within German and Italian assembly plants. Deepen backward integration into refrigerant handling certification programs to lock installer loyalty before subsidy exhaustion timelines accelerate replacement cycles. The threat of emerging Polish and Romanian system integrators accessing EU cohesion funding demands preemptive channel control in Silesia and Lesser Poland.
For New Entrants and Emerging Players: Anchor in hybrid heating configurations for French and Italian rural retrofits where grid capacity constraints delay full electrification. The most penetrable segment is mid-income French households accessing MaPrimeRénov' income-graded tiers below premium cold-climate specifications. A service-bundled go-to-market angle combining equipment supply with F-Gas Regulation compliance training addresses installer certification gaps.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive controller electronics and buffer tank production that generate aftermarket parts demand across 15-20 year system lifespans. Long-term viability favors integrated producers with cold-climate seasonal performance factor compliance already certified. The acquisition target archetype is regional specialists with installer loyalty concentration in coal-dependent transition regions. The signal to watch is national subsidy exhaustion rates relative to fossil-fuel boiler ban phase-in timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| R-32 Refrigerant Transition | F-Gas Regulation compliance qualifies products for enhanced national clean heat subsidy tiers. |
| Installer Certification Program | Direct training partnerships address technician gaps under F-Gas Regulation deployment requirements. |
| Backward Integration into Controllers | In-house electronics production captures margin pools shifting from equipment to system intelligence. |
| Poland Market Entry | EU cohesion funding for coal-dependent regions creates underpenetrated air-to-water replacement demand. |
| Hybrid System Development | Bivalent configurations unlock rural French and Italian retrofits facing grid reinforcement delays. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with heat pump manufacturer product managers, HVAC contractor procurement heads, and national energy regulator policy leads; and secondary validation against Ecodesign Directive seasonal performance factor databases, CE marking documentation, and EU Green Deal national transposition records. Bottom-up triangulation across installer channel interviews in Germany, France, Italy, Poland, and the United Kingdom reconciled with top-down subsidy allocation data from national clean heat programs.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, refrigerant chemistry, end-user procurement authority, and application temperature requirements. CAGRs were derived from replacement cycle velocity against fossil-fuel boiler stock and subsidy exhaustion trajectories. Industry-specific forecast inputs included F-Gas Regulation phasedown schedules and national building code amendment timelines.
Material uncertainties — copper and aluminum commodity volatility, grid reinforcement lag in rural distribution networks, and refrigerant handling certification velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions about subsidy continuity and regulatory enforcement consistency. Recalibration cycles align with material shifts in national transpositions of EU Green Deal mandates and F-Gas Regulation compliance deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Process Chillers Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Solar Cooling Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
United States Heat Pump Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Thawing System Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Portable Chiller Market