
 APAC Waste Heat Recovery Systems Market | 2026-2036
APAC Waste Heat Recovery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Waste Heat Recovery Systems Market Outlook
Market Context with Strategic Players
The performance gap between premium integrated systems and commodity heat exchanger packages is expanding across APAC industrial zones. Mitsubishi Heavy Industries leverages its turbine-generator integration to anchor large-scale steel and cement projects in Japan and Southeast Asia. Siemens Energy competes through electrical energy recovery architectures that sustain higher efficiency thresholds in power generation applications. Thermax Limited dominates the Indian subcontinent with localized manufacturing and channel control over aftermarket services.
Technical Definition and Structural Segments
Waste heat recovery systems capture thermal energy from exhaust streams, flue gases, and process cooling loops, converting it into usable electricity or process heat through equipment operating at temperatures from 80°C to over 1,000°C depending on source quality. Organic Rankine Cycle technology leads technology adoption in low-to-medium temperature industrial applications where thermal energy recovery faces efficiency constraints. Heat exchangers occupy the largest product volume tier due to retrofit compatibility across existing manufacturing and chemical plant infrastructure. Hybrid systems integrating thermal and electrical recovery represent the fastest-growing technology configuration as oil and gas operators pursue process integration targets.
Regulatory Frame and Forward-Looking Close
China's Ministry of Ecology and Environment enforces dual carbon goals that mandate waste heat utilization benchmarks for heavy industry, while India's Bureau of Energy Efficiency administers Perform Achieve and Trade compliance that directly links energy recovery to tradable certificates. Japan's METI directs industrial decarbonization subsidies toward heat-to-power installations exceeding specified efficiency thresholds. Stakeholders must weigh technology selection against evolving carbon border adjustment mechanisms and country-specific efficiency mandates before committing capital to long-tenor industrial contracts.
Market Dynamics
China's dual carbon goals and India's Perform Achieve and Trade scheme are compressing payback periods for waste heat recovery investments across APAC heavy industry, forcing technology selection toward higher-efficiency configurations.
Growth Catalysts
- Steel sector decarbonization mandates:China's Ministry of Ecology and Environment enforces waste heat utilization benchmarks for blast furnace and coke oven operations, accelerating ORC unit deployment in Tangshan and Jiangsu industrial corridors.
- India's PAT scheme:The Bureau of Energy Efficiency links energy recovery performance to tradable certificates, creating direct revenue streams for cement and aluminum producers investing in waste heat boilers.
- Low-temperature ORC advancement:Organic Rankine Cycle technology now captures thermal energy from exhaust streams below 250°C, opening recovery potential in chemical processing and food manufacturing previously deemed uneconomical.
Market Restraints
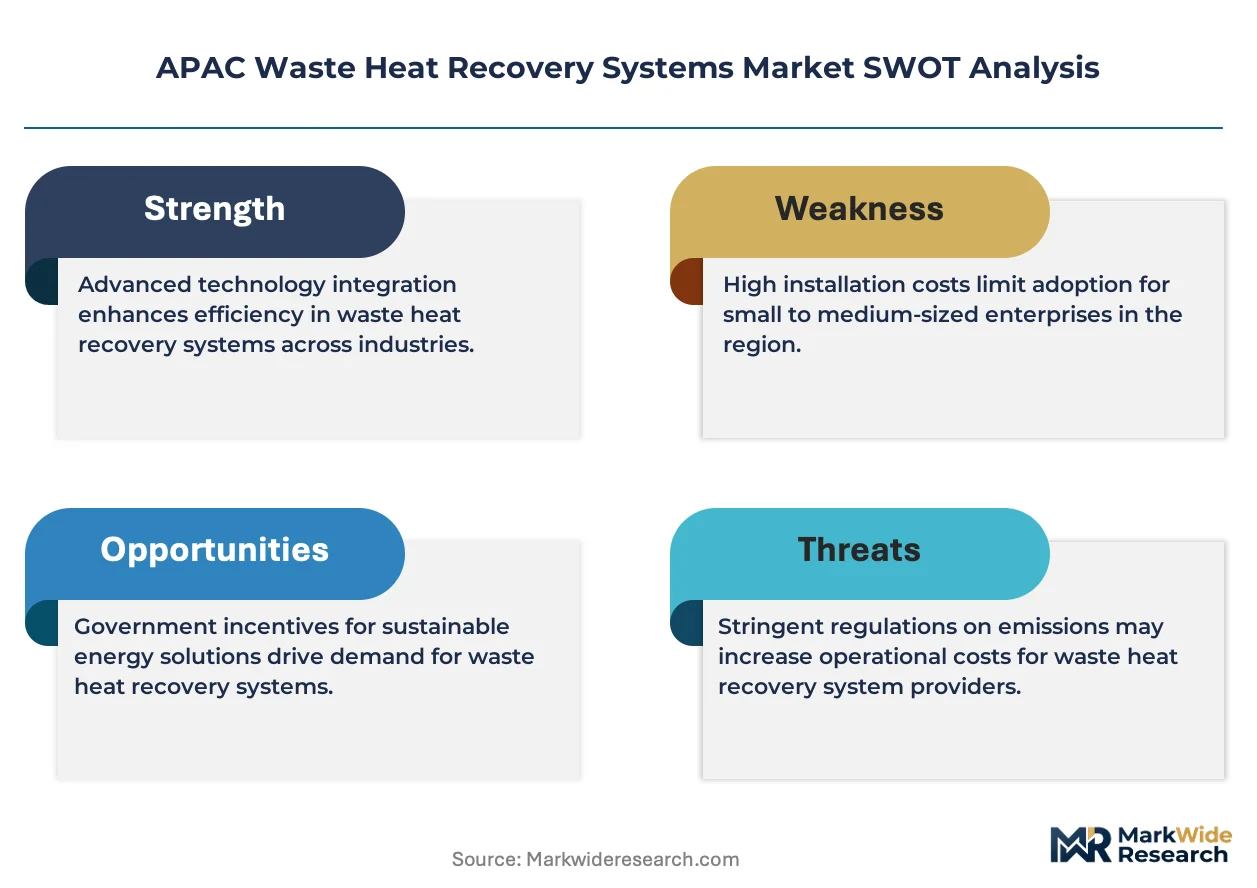
- Capital intensity barriers:Integrated waste heat-to-power systems require upfront investment exceeding commodity heat exchanger packages by substantial multiples, limiting adoption among mid-scale industrial operators.
- Site-specific engineering constraints:Each installation demands customized thermal mapping and exhaust stream analysis, preventing standardization and extending project development timelines.
- Competing efficiency investments:Direct process optimization and electrification retrofits sometimes offer faster payback than heat recovery, diverting capital from WHRS projects in margin-constrained sectors.
Strategic Opportunities
- Vietnam's emerging industrial zones:Steel and cement capacity expansion in northern provinces lacks legacy heat recovery infrastructure, presenting greenfield installation opportunities without retrofit complexity.
- Hybrid system convergence:Integration of thermal storage with ORC generation enables dispatchable power output, addressing grid stability concerns that previously limited industrial self-generation.
- Japan's METI decarbonization subsidies:Heat-to-power installations exceeding specified efficiency thresholds qualify for accelerated depreciation and direct capital grants, improving project economics for petrochemical complexes.
Industry Challenges
- Thermal engineering specialization gap:Qualified engineers capable of optimizing heat exchanger networks across variable exhaust conditions remain concentrated in Japan and select Chinese research institutes, constraining deployment velocity.
- Legacy system integration friction:Retrofitting waste heat recovery into operating cement kilns and steel furnaces requires extended shutdown windows that conflict with continuous production mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Waste Heat Recovery Systems Market |
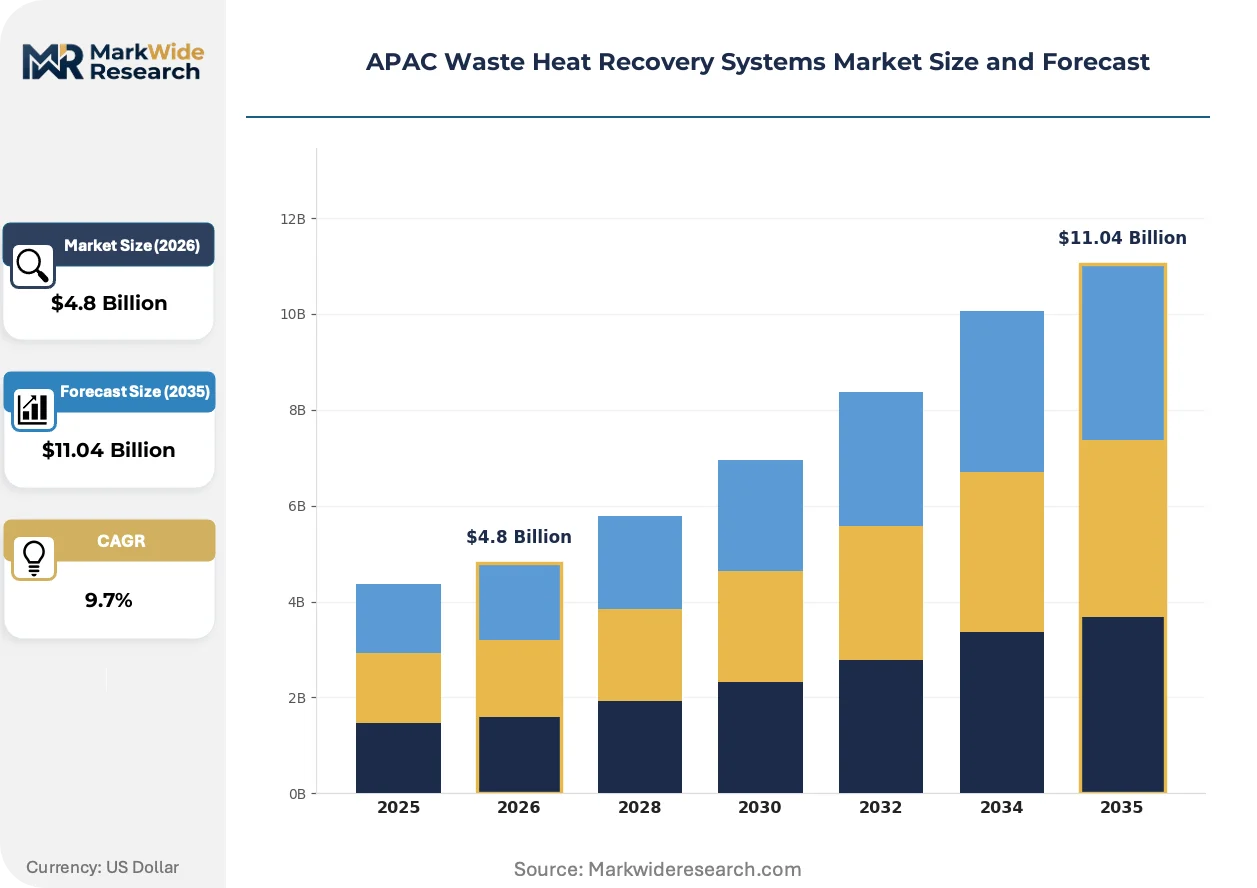
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbines, Organic Rankine Cycle, Heat Exchangers, Generators Technology: Thermal Energy Recovery, Electrical Energy Recovery, Hybrid Systems, Process Integration End User: Manufacturing, Chemical Plants, Power Generation, Oil & Gas Application: Industrial Processes, District Heating, Exhaust Heat Recovery, Pre-Heating |
| Companies Covered | Mitsubishi Heavy Industries Ltd, Siemens Energy AG, GE Aerospace, ABB Ltd, IHI Corp, Thermax Limited, Bosch Industriekessel GmbH, Ormat Technologies Inc, Wood, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Waste Heat Recovery Systems Market Strategic Shifts
Technology convergence between thermal storage and power generation architectures is redefining system design priorities across APAC industrial zones, with efficiency thresholds and grid interconnection capabilities now dominating procurement specifications.
Supercritical CO2 power cycles are integrating waste heat recovery applications above 400°C, offering compact footprints and reduced cooling water requirements compared to traditional steam Rankine systems. Japanese steel producers are piloting these configurations in blast furnace gas recovery, with early installations demonstrating improved thermal efficiency and faster ramp rates. This technology is integrating distributed generation architectures that reduce reliance on centralized power purchase agreements.
China's dual carbon goals mandate sector-specific emission intensity reductions that directly penalize unrecovered waste heat in cement, steel, and chemicals production. The Ministry of Ecology and Environment enforces compliance through provincial environmental credit systems that restrict expansion permits for non-compliant facilities. Heavy industry operators in Hebei and Shandong provinces are responding by accelerating ORC and waste heat boiler procurement ahead of 2025 assessment deadlines.
Long-term performance contracting is displacing equipment-only sales in large-scale cement and steel deployments, with vendors assuming operational risk for heat recovery efficiency guarantees. This model transfers capex burden to technology providers while locking in multi-year service relationships. Procurement teams at Indian cement majors and Chinese state-owned steel groups are driving this shift, prioritizing vendors with demonstrated operational track records over lowest-first-cost equipment bids.
APAC Waste Heat Recovery Systems Market Segmentation
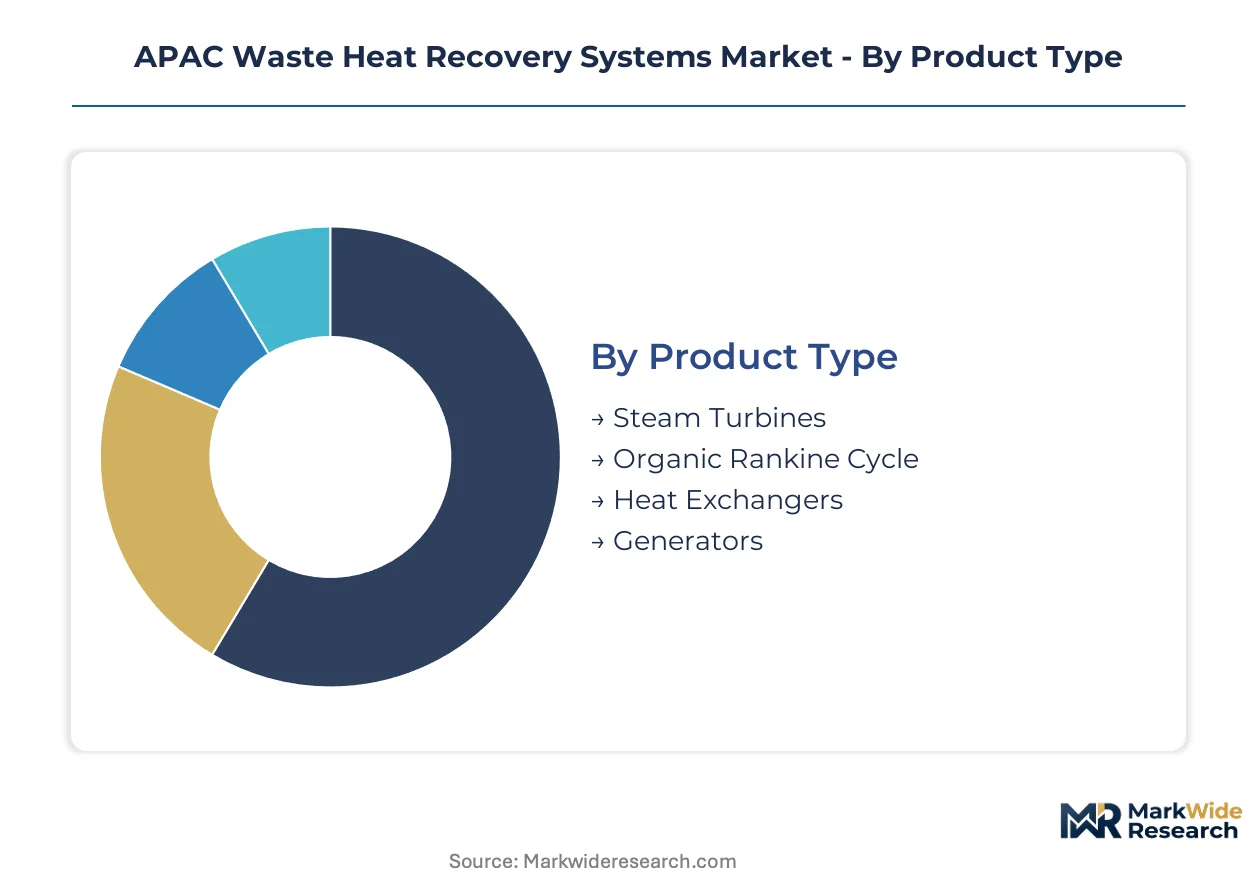
Waste heat recovery systems demand precise matching between thermal source characteristics and conversion technology. Procurement decisions across APAC heavy industry hinge on temperature thresholds, exhaust stream composition, and integration complexity with existing process infrastructure.
Product Type:
Standardization dominates high-volume heat exchanger manufacturing, while steam turbines and ORC units require extensive customization for site-specific thermal profiles and grid interconnection protocols.
- Steam Turbines:These systems convert high-temperature exhaust streams above 400°C into mechanical power through conventional Rankine cycles. Chinese steel producers in Hebei province deploy these for blast furnace gas recovery under MEE emission intensity mandates. Capital costs and extended installation timelines constrain adoption outside state-backed industrial groups.
- Organic Rankine Cycle:ORC technology employs organic working fluids to capture thermal energy from low-to-medium temperature sources between 80°C and 300°C. Cement plants across India's Rajasthan and Gujarat states favor these units for kiln exhaust recovery under PAT scheme compliance. Working fluid selection and turbine blade erosion remain persistent operational challenges.
- Heat Exchangers:Shell-and-tube and plate configurations dominate retrofit installations across existing chemical and food processing infrastructure due to modular deployment and minimal process disruption.
- Generators:Synchronous and induction generator sets convert recovered mechanical energy to grid-compliant electrical output, with specifications varying by local utility interconnection standards.
Most installed capacity flows through Heat Exchangers. Expansion is steepest in Organic Rankine Cycle.
Technology:
Electrical energy recovery commands premium pricing and higher engineering margins, while thermal energy recovery maintains volume leadership through simpler integration requirements.
- Thermal Energy Recovery:Direct heat transfer systems redirect exhaust thermal energy to pre-heating, drying, or process steam applications without intermediate conversion. Indian cement producers leverage these for raw meal pre-calcination under Bureau of Energy Efficiency efficiency benchmarks. Lower capital intensity and faster payback periods sustain demand despite limited revenue diversification.
- Electrical Energy Recovery:Heat-to-power conversion architectures generate grid-exportable electricity or offset captive power purchases. Japanese petrochemical complexes under METI subsidy programs prioritize these configurations for their dual carbon accounting benefits. Higher efficiency thresholds and complex grid synchronization requirements limit supplier field to established turbine-generator integrators.
- Hybrid Systems:Combined thermal and electrical recovery architectures optimize exergy capture across variable load conditions, gaining traction in oil and gas processing facilities.
- Process Integration:Deep system coupling with existing production workflows maximizes recovery efficiency but demands extended shutdown windows and specialized thermal engineering expertise.
Thermal Energy Recovery retains the largest installed base. Electrical Energy Recovery is climbing the fastest as carbon accounting tightens.
End User:
Capital availability and regulatory exposure determine technology selection across customer categories, with state-affiliated energy-intensive sectors leading integrated system adoption.
- Manufacturing:Steel, cement, and aluminum producers face binding emission intensity targets under China's dual carbon framework and India's PAT mechanism. Tangshan steel mills and Jiangsu cement clusters drive ORC and waste heat boiler procurement. Continuous production mandates complicate retrofit scheduling and extend project timelines.
- Chemical Plants:Process heat integration opportunities abound in fertilizer, petrochemical, and specialty chemical operations. Low-temperature exhaust streams from catalytic crackers and reformers suit ORC deployment. Site-specific safety protocols and hazardous area classifications constrain standardization.
- Power Generation:Combined cycle and cogeneration facilities pursue marginal efficiency gains through exhaust heat recovery from gas turbine and reciprocating engine exhaust.
- Oil & Gas:Upstream and midstream operations deploy flare gas recovery and compressor station heat recovery to meet emission reduction commitments and reduce fuel consumption.
Manufacturing channels the majority of current investment. Chemical Plants are gaining share fastest as low-temperature ORC economics improve.
Application:
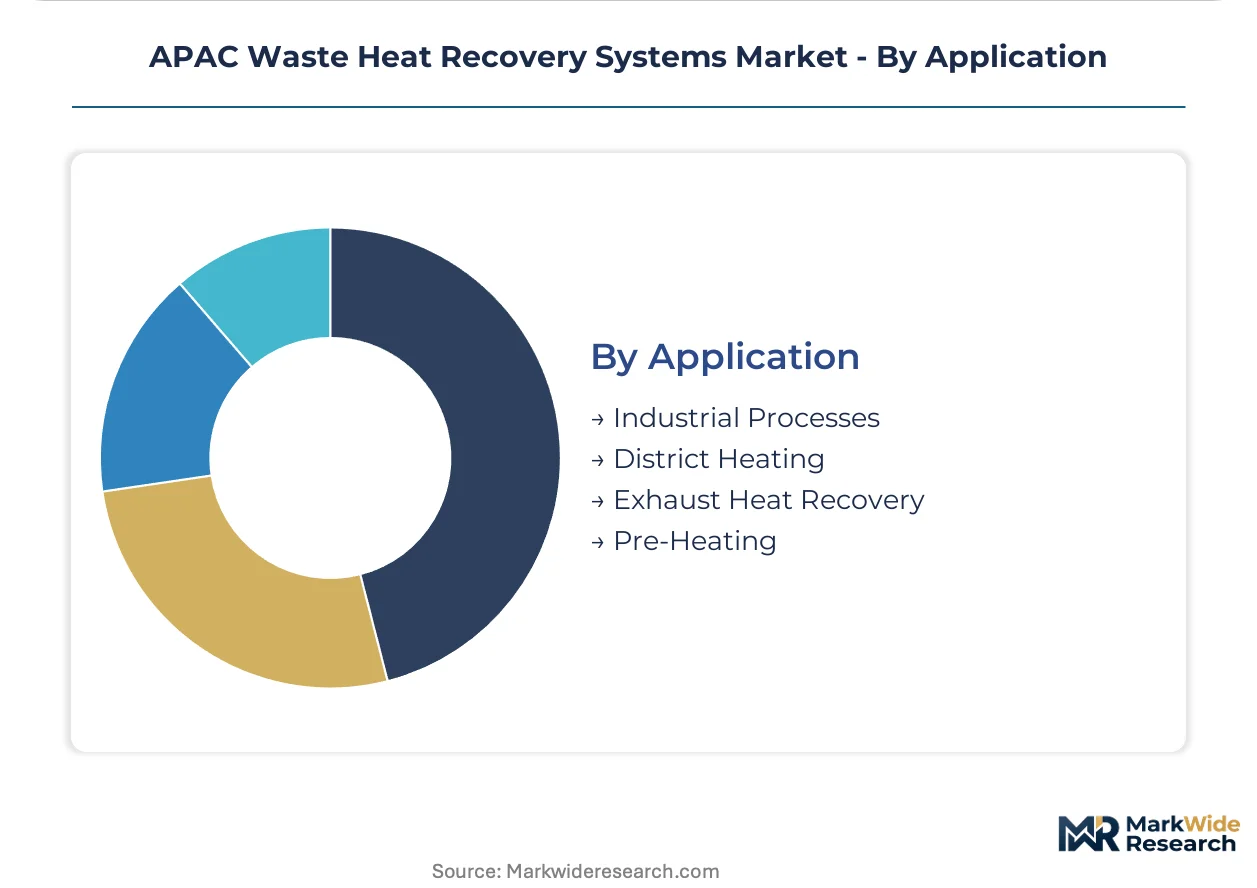
Industrial process integration offers the deepest efficiency gains but demands the most specialized engineering, while district heating applications leverage existing thermal distribution infrastructure.
- Industrial Processes:Direct integration with kilns, furnaces, and reactors captures thermal energy at the point of generation. Chinese cement producers in Shandong province embed waste heat boilers within clinker production lines to satisfy provincial environmental credit systems. Customized heat exchanger networks and control systems dominate project scope.
- District Heating:Urban and industrial park thermal networks absorb recovered heat for space heating and domestic hot water production. Northern Chinese municipalities integrate steel mill waste heat into municipal heating grids under carbon reduction mandates. Seasonal demand variability and long-distance transmission losses constrain economics.
- Exhaust Heat Recovery:Capture systems target flue gas, ventilation, and process exhaust streams across diverse industrial settings.
- Pre-Heating:Combustion air and feedstock pre-heating applications reduce primary fuel consumption through recovered thermal energy.
Industrial Processes account for the dominant share of deployment. District Heating is expanding most quickly as urban decarbonization accelerates in northern China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized thermal engineering talent concentrates in Japan's industrial corridors and select Chinese research institutes, constraining deployment velocity across Southeast Asian expansion zones.
China
Blast furnace gas recovery and cement kiln exhaust capture drive system procurement in Hebei and Shandong provinces. The Ministry of Ecology and Environment enforces dual carbon goals through provincial environmental credit systems that restrict expansion permits for non-compliant facilities. Tangshan steel mills accelerate ORC and waste heat boiler installation ahead of 2025 assessment deadlines.
India
Cement producers in Rajasthan and Gujarat favor ORC units for kiln exhaust recovery, while aluminum smelters pursue waste heat boilers for energy intensity compliance. The Bureau of Energy Efficiency administers Perform Achieve and Trade scheme compliance that links energy recovery performance to tradable certificates. Installation concentrates in industrial clusters across the western and northern manufacturing belts.
Japan
Petrochemical complexes and steel producers pilot supercritical CO2 power cycles for blast furnace gas recovery above 400°C. METI directs industrial decarbonization subsidies toward heat-to-power installations exceeding specified efficiency thresholds. Early demonstrations in Kansai and Chubu industrial zones show improved thermal efficiency and faster ramp rates.
Vietnam
Steel and cement capacity expansion in northern provinces lacks legacy heat recovery infrastructure, creating greenfield installation opportunities without retrofit complexity. Provincial industrial development authorities incentivize energy-efficient process integration for export-oriented manufacturing zones. Procurement activity concentrates in Hai Phong and Thai Nguyen industrial corridors.
South Korea
Refinery and petrochemical operators pursue marginal efficiency gains through exhaust heat recovery from catalytic crackers and reformers. National emission trading scheme compliance tightens carbon intensity benchmarks for energy-intensive sectors. Project development focuses on the Ulsan and Yeosu industrial complexes.
APAC Waste Heat Recovery Systems Market Competitive Environment
Top-tier vendors anchor integrated system supply for large-scale steel and cement projects, while mid-scale fabricators compete on heat exchanger retrofit compatibility and localized aftermarket services. The performance gap between premium turbine-generator architectures and commodity thermal recovery packages is widening. Two strategic archetypes dominate: full-system integrators with in-house turbine and generator manufacturing, and specialized heat transfer equipment suppliers with regional manufacturing footprints. Competitive moves concentrate on long-term performance contracting and technology licensing partnerships.
Within the full-system integrator tier, Mitsubishi Heavy Industries Ltd and Siemens Energy AG exemplify vendors assuming operational risk for heat recovery efficiency guarantees. Thermax Limited occupies a position among localized manufacturing specialists with channel control over Indian aftermarket services. These three anchors illustrate the market's bifurcation between premium integrated architectures and regionally embedded service networks.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| Siemens Energy AG |
| GE Aerospace |
| ABB Ltd |
| IHI Corp |
| Thermax Limited |
| Bosch Industriekessel GmbH |
| Ormat Technologies Inc |
| Wood |
| Others |
Value Chain & Pricing Dynamics
Steel billet price indices in Tangshan cascade through waste heat recovery system supply chains, compressing margins on commodity heat exchanger packages while reinforcing premium pricing for integrated turbine-generator architectures. Raw material volatility feeds directly into tiered equipment procurement decisions across Chinese and Indian industrial corridors.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across APAC waste heat recovery markets. Project-based contracting dominates large-scale steel and cement deployments, while equipment-only transactions prevail in mid-scale retrofit installations. Price differentiation rests on after-sales service bundling and efficiency guarantee terms rather than hardware specifications alone. Cost compression in standard heat exchanger tiers is intensifying because Chinese fabricators are absorbing steel price volatility to maintain volume. Mid-scale chemical processors exhibit highest price sensitivity, whereas Japanese petrochemical complexes under METI subsidy programs prioritize performance guarantees over first-cost minimization.
Supply Chain Analysis
Reverse logistics flows for turbine refurbishment and ORC working fluid reclamation anchor aftermarket service networks across Japan, China, and South Korea. Manufacturing concentration for precision turbine blades and generator windings centers on Japanese industrial corridors and select Chinese research institute partnerships. Raw material dependencies span high-grade steel alloys from Japanese specialty mills, rare-earth magnetic materials from Chinese processing facilities, and engineered polymers for ORC working fluids from South Korean chemical complexes. Single-source vulnerability in superalloy casting capacity constrains deployment velocity for high-temperature applications. Distribution runs through EPC contractors and industrial equipment distributors with established relationships across state-owned steel groups and cement majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waste heat recovery system margins expand as efficiency benchmarking tightens under China's dual carbon framework and India's PAT scheme, rewarding vendors who capture premium-tier procurement from compliance-driven heavy industry.
For Market Incumbents: Lock in multi-year performance contracting relationships with Chinese state-owned steel groups and Indian cement majors before 2025 assessment deadlines compress vendor selection windows. Defend against emerging ORC technology specialists by deepening backward integration into turbine blade manufacturing and captive service networks across Tangshan and Jiangsu industrial corridors. For New Entrants and Emerging Players: The price-point gap between premium integrated systems and commodity heat exchanger packages creates entry space for mid-tier ORC unit specialists targeting Vietnam's greenfield steel and cement expansions in Hai Phong and Thai Nguyen provinces. Pursue technology licensing partnerships with established Japanese turbine manufacturers to bypass thermal engineering specialization gaps while building operational track records. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid system integrators combining thermal storage dispatchability with ORC generation architectures. Long-term viability hinges on exposure to carbon border adjustment mechanism implementation across European export markets for APAC steel and cement. Monitor provincial environmental credit system enforcement intensity in Hebei and Shandong as inflection indicator for Chinese demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Performance Contracting | Transfers capex burden to vendors while locking in multi-year service relationships with state-owned steel groups. |
| Backward Integration into Turbine Manufacturing | Reduces dependency on Japanese specialty mills and captures margin from precision casting capacity constraints. |
| Technology Licensing Partnership | Enables new entrants to bypass thermal engineering gaps through METI-subsidized Japanese R&D collaborations. |
| Hybrid System Development | Addresses grid stability concerns that previously limited industrial self-generation in variable-load chemical processing. |
| Provincial Credit System Pre-Positioning | Secures expansion permit eligibility for Chinese cement and steel producers ahead of MEE assessment deadlines. |
Study Parameters
Bottom-up industrial end-use modeling reconciled against top-down equipment supply tracking forms the analytical core of this study. Primary interviews with plant engineers at Chinese steel mills and cement producers, procurement leads at Indian aluminum smelters, aftermarket service heads at Japanese turbine manufacturers, and EPC contractors across Southeast Asian industrial zones combined with secondary validation from MEE emission intensity filings, BEE PAT scheme compliance records, METI subsidy program disclosures, and customs data on heat exchanger and ORC unit trade flows. Triangulation between installation volume estimates and manufacturer shipment disclosures anchors market sizing integrity.
Input-output matrices map thermal source characteristics against conversion technology economics across temperature thresholds, exhaust stream compositions, and grid interconnection protocols. Segmentation dimensions span product type, recovery technology, end-user industry, and application integration depth. CAGRs derive from regression analysis of historical procurement patterns against regulatory enforcement timelines and raw material cost trajectories. Forecast inputs incorporate provincial environmental credit system rollout schedules and supercritical CO2 cycle demonstration outcomes from Kansai and Chubu industrial zones.
Caveats apply where steel price volatility, thermal engineering talent concentration constraints, or carbon border adjustment mechanism implementation delays could materially shift the outlook. Practitioners should monitor provincial environmental credit system enforcement intensity and supercritical CO2 pilot performance metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
Marine Incinerators Market
Waste to Energy Systems
Waste to Energy (WTE) Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
Europe Waste-To-Energy Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Nuclear Waste Management Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Japan Waste to Energy Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
Austria Waste to Energy Market
Waste to Energy Systems
Canada Waste-To-Energy Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Germany Waste-To-Energy Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
Drilling Waste Management Services Market