
 Cooling Tower Rental Market | 2026-2036
Cooling Tower Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Tower Rental Market Intelligence
Stainless steel is hardening as the dominant basin and casing material in premium rental fleets, displacing galvanized carbon steel units that corrode faster in chemically aggressive cooling loops. Aggreko leverages its modular fleet architecture to deploy skid-mounted stainless systems across petrochemical corridors. United Rentals anchors its position through dense depot networks in Gulf Coast industrial zones. SPX Cooling Technologies specializes in engineered polymer fill packs that extend thermal efficiency in high-cycling rental applications.
Cooling tower rental denotes temporary provision of heat-rejection equipment, typically field-erected or package units rated from 100 to 2,000+ tons of refrigeration, using evaporation across PVC or polypropylene fill media to transfer process heat to ambient air. Mechanical draft configurations dominate the rental fleet due to compact footprint and independent operation regardless of wind conditions. Project-based rental duration commands premium pricing during emergency outages and seasonal peak shaving for power plants. Data center end-user demand exhibits the fastest expansion trajectory as cloud providers defer capital expenditure on permanent infrastructure during facility ramp-up phases.
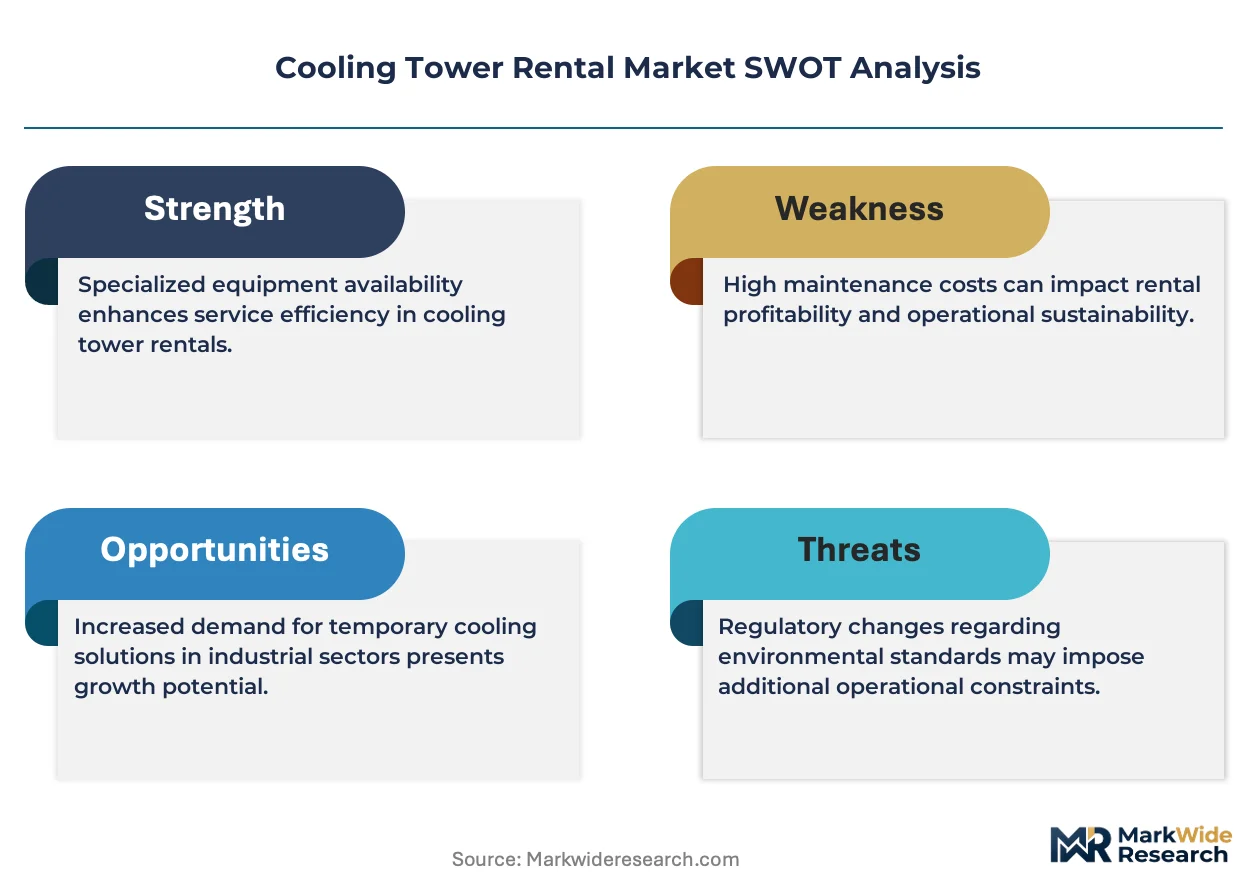
EPA NPDES permits govern thermal discharge limits from rental tower blowdown, while OSHA mandates legionella prevention protocols through routine biocide treatment documentation. ASME and CTI certification standards shape procurement specifications, with uncertified units increasingly excluded from utility and petrochemical bid pools. Stakeholders must monitor evolving state-level water-use restrictions that threaten open-loop evaporative cooling in drought-prone jurisdictions.
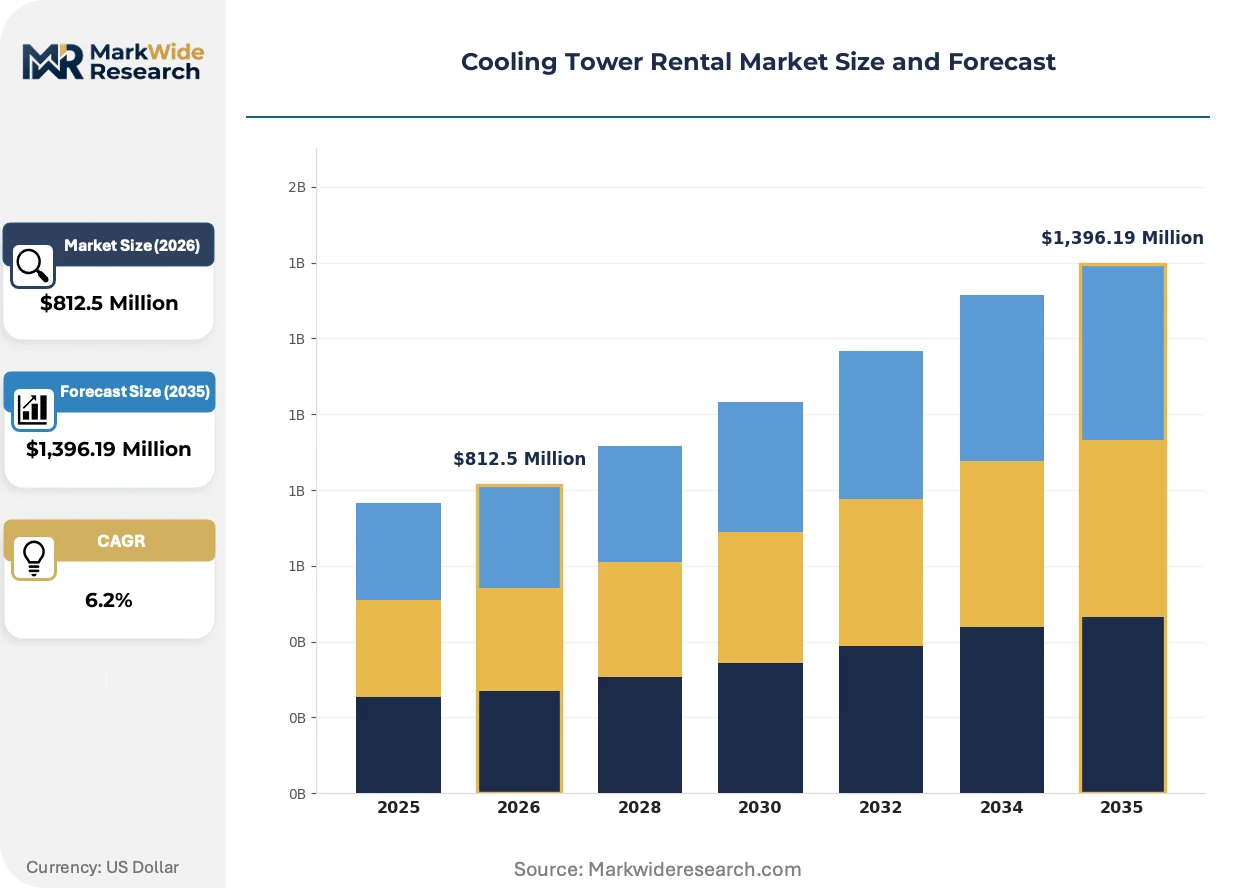
Market Dynamics
Data center construction timelines are compressing rental contract durations while demanding higher thermal capacity per footprint, forcing fleet operators to reconfigure modular architectures for hyperscale ramp-up phases.
Growth Catalysts
- EPA NPDES thermal discharge limits:Utilities facing emergency cooling failures must rent certified towers to maintain compliance during infrastructure repairs, creating mandatory demand spikes.
- Hyperscale facility construction clusters:Cloud providers in Texas, California, and Virginia defer permanent cooling capex during 18-36 month facility commissioning windows.
- Stainless steel basin technology:Chemically aggressive cooling loops in petrochemical corridors accelerate replacement cycles for galvanized carbon steel units.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials constitute 35-45% of unit manufacturing costs, compressing rental margins during commodity spikes.
- Regional fleet concentration:Gulf Coast depot density leaves Mountain West and Pacific Northwest markets underserved during seasonal demand surges.
- Evaporative cooling water intensity:Drought-prone jurisdictions in Arizona and Nevada impose escalating withdrawal fees that threaten open-loop economics.
Strategic Opportunities
- Modular hybrid cooling systems:Dry-fluid coolers paired with evaporative towers address water-scarce markets in Utah and Colorado.
- OSHA legionella documentation mandates:Biocide treatment verification services create recurring revenue streams beyond equipment rental.
- Edge data center distributed architectures:Smaller 100-500 ton units serve latency-sensitive compute nodes in secondary metros.
Industry Challenges
- CTI thermal performance certification timelines:Third-party testing bottlenecks delay fleet deployment during emergency response windows.
- Legacy control system integration:Rental units must interface with existing SCADA architectures without permanent infrastructure modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooling Tower Rental Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,396.19 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Tower Type: Natural Draft, Mechanical Draft, Induced Draft, Forced Draft End User Industry: Power Generation, Petrochemical Plants, Food Processing, Data Centers, Textile Manufacturing Rental Duration: Short Term, Medium Term, Long Term, Project Based Cooling Capacity: Below 500 TR, 500-1000 TR, 1000-2000 TR, Above 2000 TR |
| Companies Covered | Aggreko, United Rentals, Sunbelt Rentals, SPX Cooling Technologies, Caterpillar, Johnson Controls, Trane Technologies, Cooling Tower Depot, Midwest Cooling Tower Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Tower Rental Market Strategic Shifts & Innovations
Equipment architecture is fragmenting into containerized sub-assemblies that compress mobilization timelines and enable mixed-technology configurations for site-specific thermal loads.
Skid-mounted stainless steel cooling tower systems are modularizing field deployment by reducing foundation requirements and enabling crane-lift installation without permanent pad construction. Petrochemical operators in Louisiana and Texas adopt these configurations for 90-180 day turnaround maintenance. The technology is compressing project mobilization from weeks to days while expanding addressable rental occasions.
REACH chemical registration requirements are restricting biocide formulations available for European rental fleets, forcing operators to stock dual chemical inventories for cross-border deployments. Industrial users in Germany and the Netherlands face elevated compliance documentation burdens. The regulation is segmenting procurement specifications between certified and uncertified equipment pools.
Hyperscale buyers now specify outcome-based thermal rejection contracts rather than per-ton rental rates, transferring operational risk to fleet operators during facility commissioning. Cloud providers in Northern Virginia and Dallas-Fort Worth lead this shift. The model compresses supplier margins while extending contract durations and service bundling requirements.
Cooling Tower Rental Market Segmentation
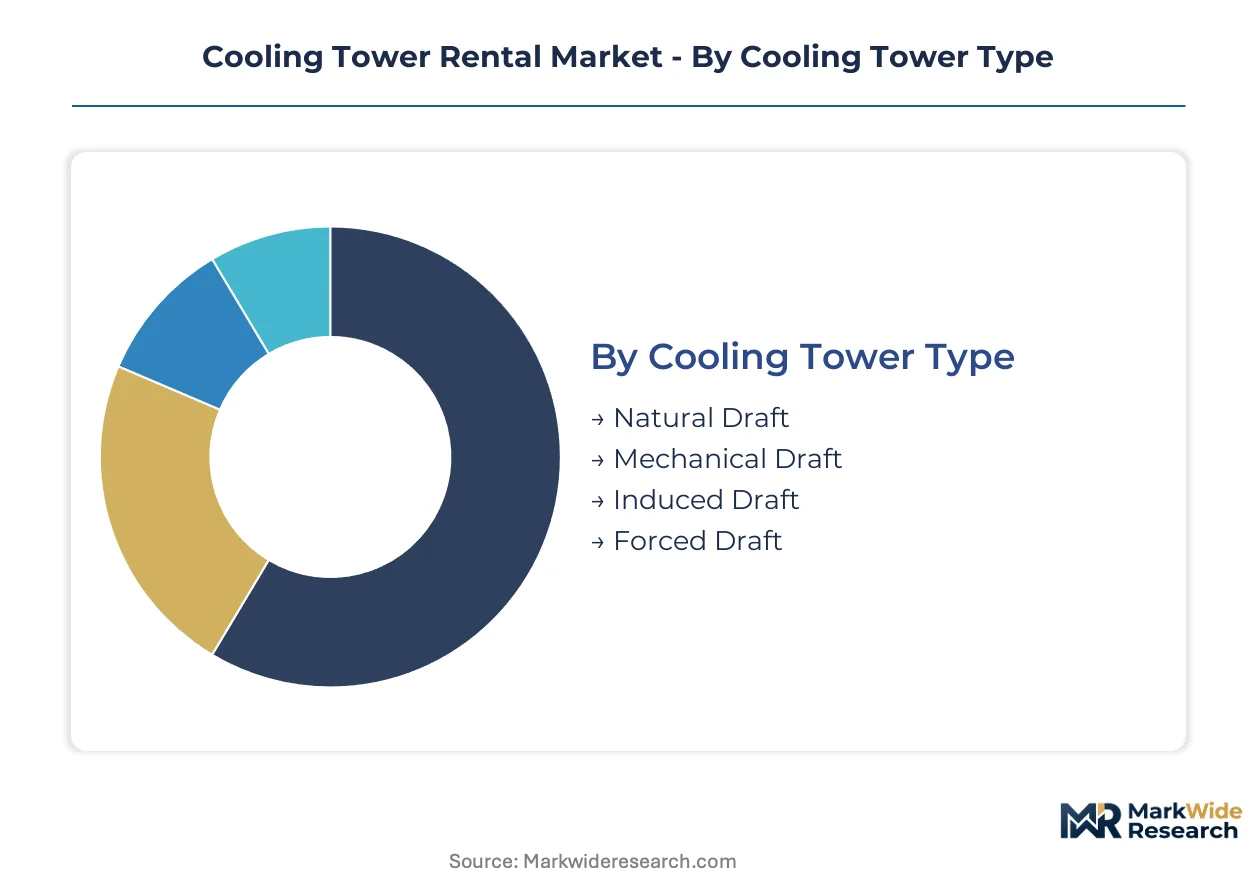
Cooling tower rental procurement hinges on matching thermal rejection specifications to operational timelines and site constraints. Segment boundaries shift as hyperscale data centers compress commissioning windows and petrochemical operators demand modular stainless configurations for aggressive chemical environments.
Cooling Tower Type:
Customization intensity varies sharply across this category, from fully engineered natural draft installations to standardized mechanical draft skids.
- Mechanical Draft:Centrifugal or axial fans force air through PVC fill media, enabling compact footprints independent of ambient wind conditions. Power plants in Texas and Louisiana specify these units for emergency outage coverage where space constraints preclude natural draft structures.
- Natural Draft:Hyperbolic concrete or steel structures exploit chimney effect for air movement, demanding substantial capital investment and extended mobilization timelines. These units serve permanent industrial installations in Germany and the Netherlands where REACH-compliant biocide protocols favor passive operation over chemical-intensive mechanical systems.
- Induced Draft:Fans mounted atop the tower pull air upward through the fill, reducing recirculation risk in humid climates. Food processors in California deploy these configurations for seasonal capacity augmentation.
- Forced Draft:Bottom-mounted fans push air through the fill, tolerating higher inlet air temperatures. Petrochemical corridors along the US Gulf Coast specify forced draft units for turnaround maintenance where ambient heat loads peak.
Leading the category by volume: Mechanical Draft. Growing fastest: Induced Draft.
End User Industry:
Margin profiles diverge across this category based on contract duration predictability and technical specification complexity.
- Data Centers:Hyperscale operators in Northern Virginia and Dallas-Fort Worth defer permanent cooling capex during 18-36 month facility ramp-up phases. Cloud providers now specify outcome-based thermal rejection contracts, transferring operational risk to fleet operators.
- Power Generation:Utilities facing EPA NPDES thermal discharge violations rent certified towers to maintain compliance during infrastructure repairs. Emergency response windows create mandatory demand spikes with premium pricing.
- Petrochemical Plants:Turnaround maintenance cycles in Louisiana and Texas drive 90-180 day rentals of skid-mounted stainless systems. Chemically aggressive cooling loops accelerate replacement cycles for galvanized carbon steel units.
- Food Processing:Seasonal harvest peaks in California's Central Valley create predictable short-term demand for medium-capacity mechanical draft towers.
- Textile Manufacturing:Dyehouse operations in North Carolina and South Carolina require consistent process water cooling, generating steady medium-term contract flow.
Dominating contract value: Data Centers. Expanding most quickly: Data Centers.
Rental Duration:
Customer type and cash flow timing determine duration selection, from spot-market emergency response to multi-year infrastructure deferral strategies.
- Project Based:Defined-scope engagements tied to specific construction milestones or maintenance turnarounds. Petrochemical operators in Texas specify these contracts with liquidated damages clauses for thermal performance shortfalls.
- Long Term:Multi-year agreements spanning full facility commissioning cycles. Hyperscale data centers in Virginia leverage these structures to defer permanent infrastructure investment.
- Medium Term:6-18 month contracts balancing flexibility with rate predictability. Food processors favor this structure for seasonal capacity planning.
- Short Term:Emergency response and spot-market deployments commanding 40-60% rate premiums. Power utilities activate these contracts during unplanned cooling system failures.
Generating highest margins: Project Based. Gaining share fastest: Long Term.
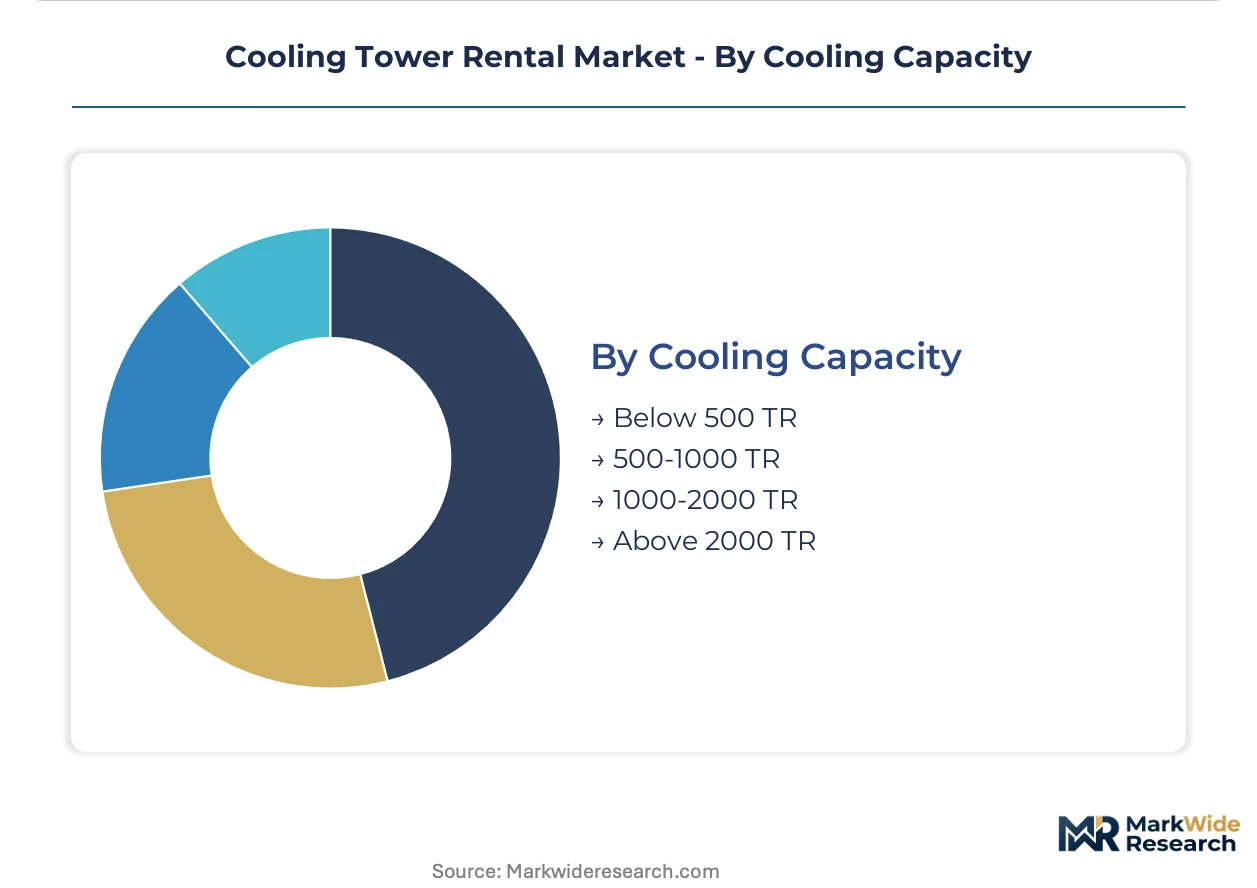
Cooling Capacity:
Volume concentration and specification complexity invert across this category, with smaller units serving distributed edge architectures and mega-tonnage systems anchoring utility and hyperscale deployments.
- Above 2000 TR:Field-erected or large package units serving utility-scale power generation and hyperscale data center campuses. These configurations demand CTI thermal performance certification and extended mobilization timelines.
- 1000-2000 TR:Modular skid-mounted systems enabling crane-lift installation without permanent pad construction. Petrochemical operators in Texas deploy these for turnaround maintenance with 90-180 day cycles.
- 500-1000 TR:Standardized package units dominating fleet inventory across Gulf Coast depot networks. These units balance mobilization speed with thermal output for mid-scale industrial applications.
- Below 500 TR:Containerized sub-assemblies serving edge data center distributed architectures in secondary metros. Smaller footprint enables rapid deployment for latency-sensitive compute nodes.
Commanding highest rental rates: Above 2000 TR. Climbing the fastest: Below 500 TR.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center construction concentrates rental demand in specific industrial corridors where thermal rejection infrastructure faces compressed commissioning timelines. Cloud providers defer permanent cooling capital expenditure across multiple jurisdictions, creating geographically dispersed but intense demand pockets.
United States
Texas, California, and Virginia host the densest clusters of hyperscale facility construction, driving 18-36 month rental cycles during data center ramp-up phases. EPA NPDES permits govern thermal discharge limits from rental tower blowdown, mandating certified equipment for utility compliance during emergency repairs. Dallas-Fort Worth and Northern Virginia data center corridors now specify outcome-based thermal rejection contracts rather than per-ton rates.
Germany
Industrial users in the Rhine-Ruhr and Bavarian chemical corridors deploy rental cooling for turnaround maintenance cycles. REACH chemical registration requirements restrict biocide formulations available for rental fleets, forcing operators to maintain dual chemical inventories for cross-border deployments. Frankfurt's data center hub generates sustained demand for medium-capacity mechanical draft configurations.
Netherlands
Amsterdam's digital infrastructure cluster and Rotterdam's petrochemical complex create dual demand streams for rental cooling. REACH-compliant biocide protocols favor passive operation over chemical-intensive mechanical systems in permanent installations. The country's national environmental regulator imposes strict thermal discharge documentation requirements on temporary cooling deployments.
China
Yangtze River Delta and Pearl River Delta manufacturing zones deploy rental cooling during seasonal peak loads and facility upgrades. MIIT industrial standards and GB technical regulations shape equipment certification requirements for temporary thermal infrastructure. Shanghai and Shenzhen data center operators increasingly specify modular skid-mounted systems for rapid deployment.
India
Maharashtra and Karnataka data center corridors in Mumbai and Bangalore drive emerging demand for 100-500 ton containerized units. CEA electrical safety standards and state-level pollution control board thermal discharge rules govern rental equipment specifications. Chennai's automotive and electronics manufacturing clusters generate secondary demand for process cooling rentals during capacity expansions.
Cooling Tower Rental Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with equipment owners commanding premium positioning in emergency response windows while regional fabricators compete on mobilization speed. The vendor base organizes into three tiers: multinational rental fleet operators with dense depot networks, specialized cooling tower manufacturers with rental divisions, and regional equipment lessors serving spot markets. Two dominant competitive moves are reshaping positioning: fleet operators are densifying stainless steel modular inventory in Gulf Coast and European chemical corridors, while technology licensors are partnering with regional lessors to extend certified equipment reach into underserved Mountain West and Pacific Northwest markets.
Within the multinational fleet operator tier, Aggreko and United Rentals exemplify divergent geographic anchoring strategies, with the former concentrating modular stainless systems in petrochemical corridors and the latter building depot density in Gulf Coast industrial zones. SPX Cooling Technologies occupies a position bridging equipment manufacturing and rental service provision, representing the specialized technology pathway. These three companies illustrate how competitive positioning depends on capital deployment choices between fleet scale, geographic coverage, and technical specialization.
| Leading Market Players |
|---|
| Aggreko |
| United Rentals |
| Sunbelt Rentals |
| SPX Cooling Technologies |
| Caterpillar |
| Johnson Controls |
| Trane Technologies |
| Cooling Tower Depot |
| Midwest Cooling Tower Services |
| Others |
Cost & Logistics Intelligence
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth now specify outcome-based thermal rejection contracts rather than per-ton rental rates, compressing supplier margins while extending contract durations and service bundling requirements. This buyer concentration transfers operational risk to fleet operators and restructures pricing power toward certified equipment pools with dense depot networks.
Pricing Analysis
Volume concentrates in standardized 500-1000 TR package units stocked across Gulf Coast depot networks, while margins concentrate in emergency short-term rentals and CTI-certified above-2000 TR field-erected systems. Price differentiation rests on certification grade and mobilization speed, with CTI thermal performance certification commanding substantial premiums over uncertified units. Cost compression in galvanized carbon steel basins is intensifying because stainless steel technology is displacing legacy materials in petrochemical corridors. Food processors and textile manufacturers exhibit highest price sensitivity due to seasonal demand predictability, while power utilities facing EPA NPDES violations show lowest sensitivity during mandatory compliance windows.
Supply Chain Analysis
Freight costs for oversized field-erected towers constrain economic delivery radius to 300-500 miles from fabrication points, anchoring supply concentration in Texas, Louisiana, and Ohio where industrial metalworking infrastructure supports stainless steel basin production. Manufacturing draws from copper and aluminum heat exchanger components, PVC and polypropylene fill media, and specialized axial fan assemblies. Single-source vulnerability in CTI-certified thermal testing capacity creates deployment bottlenecks during emergency response windows. Distribution runs through dense depot networks in Gulf Coast industrial zones, with regional lessors serving spot markets in underserved Mountain West corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet capacity for CTI-certified stainless steel modular systems runs substantially below hyperscale data center demand, propping pricing power for incumbent operators with deployed inventory. This supply constraint structures competitive dynamics across emergency response, seasonal peak shaving, and infrastructure deferral applications.
For Market Incumbents: Cement market position by accelerating stainless steel modular fleet deployment in Texas and Virginia hyperscale corridors while securing exclusive CTI testing partnerships to compress certification timelines. Aggreko and United Rentals face emerging pressure from technology licensors partnering with regional lessors to extend certified equipment reach; vertical integration into fill pack manufacturing insulates margin structures from polymer price volatility. For New Entrants and Emerging Players: Begin with edge data center distributed architectures in secondary metros where 100-500 TR containerized sub-assemblies serve latency-sensitive compute nodes with faster mobilization than incumbent depot networks. The Mountain West and Pacific Northwest markets remain structurally underserved during seasonal demand surges; a go-to-market angle pairing dry-fluid cooler hybrid configurations with Utah and Colorado water-scarce jurisdictions bypasses entrenched Gulf Coast supply chains. For Investors and Strategic Acquirers: The window for entry favors specialized cooling tower manufacturers with rental divisions and established CTI certification pathways over pure-play fleet operators facing commodity price exposure. Long-term viability hinges on outcome-based contract servicing capabilities and biocide treatment verification services creating recurring revenue streams. The signal to watch is state-level water-use restriction escalation in Arizona and Nevada threatening open-loop evaporative economics and accelerating hybrid cooling adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Stainless Steel Modular Fleet Expansion | Densifies premium inventory in Texas and Virginia hyperscale corridors where demand concentrates. |
| CTI Certification Partnership | Compresses third-party thermal testing bottlenecks that delay emergency deployment windows. |
| Hybrid Cooling System Development | Addresses water-scarce markets in Utah and Colorado through dry-fluid cooler pairings. |
| Biocide Treatment Verification Services | Creates recurring OSHA-compliant revenue streams beyond equipment rental transactions. |
| Regional Lessor Technology Licensing | Extends certified equipment reach into underserved Mountain West and Pacific Northwest markets. |
Research Approach
Independent corroboration across fleet operator deployment records, CTI certification databases, and hyperscale data center procurement documentation underwrites the qualitative findings in this study. Primary interviews with rental fleet operations directors, data center facility commissioning managers, petrochemical plant maintenance engineers, and EPA regional compliance officers combined with secondary validation from EIA power plant outage data, SEC equipment lessor filings, and state-level water withdrawal permit records. Bottom-up triangulation across rental contract volume estimates and top-down reconciliation against reported fleet capacity yields integrated market sizing.
Rate-of-change decomposition across the projection horizon isolates segment-specific growth drivers from macroeconomic baseline trends. Segmentation dimensions modeled include cooling tower type, end-user industry, rental duration, and cooling capacity tier, with additional granularity on REACH-compliant versus standard biocide protocol specifications. CAGRs derive from logistic adoption curve fitting for hyperscale data center demand and replacement cycle analysis for petrochemical turnaround maintenance. Industry-specific forecast inputs incorporate EPA NPDES enforcement intensity indices and state-level water-use restriction trajectories.
Underlying measurement precision varies by segment; data center end-user demand carries tighter precision than textile manufacturing due to disclosed hyperscale facility commissioning timelines. Forecasts reflect assumptions about regulatory enforcement continuity, stainless steel price stability, and CTI certification capacity expansion that could revise projections if EPA thermal discharge rules tighten or REACH chemical registrations restrict additional biocide formulations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Cold Trap Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Global Magnetic Refrigeration Market