
 Global Secondary Refrigerants Market | 2026-2036
Global Secondary Refrigerants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Secondary Refrigerants Market Intelligence
The market's historical reliance on bulk industrial buyers is unwinding in favor of specialized, performance-driven segments such as data center operators. This shift prioritizes thermal efficiency and system safety over lowest-cost inputs. Dow leverages its vast chemical production scale to supply foundational glycol-based fluids. Meanwhile, BASF SE differentiates with advanced formulations like potassium formate for demanding low-temperature industrial applications.
Secondary refrigerants are heat transfer fluids that move thermal energy from a cooled space to a primary refrigeration system. These liquids, which do not undergo a phase change, are selected for properties like low freezing points and high specific heat capacity. While ethylene and propylene glycol products form the market's core due to their cost-performance profile, the application segment dictates material choice. For instance, industrial process cooling increasingly specifies potassium formate for its superior performance at very low temperatures.
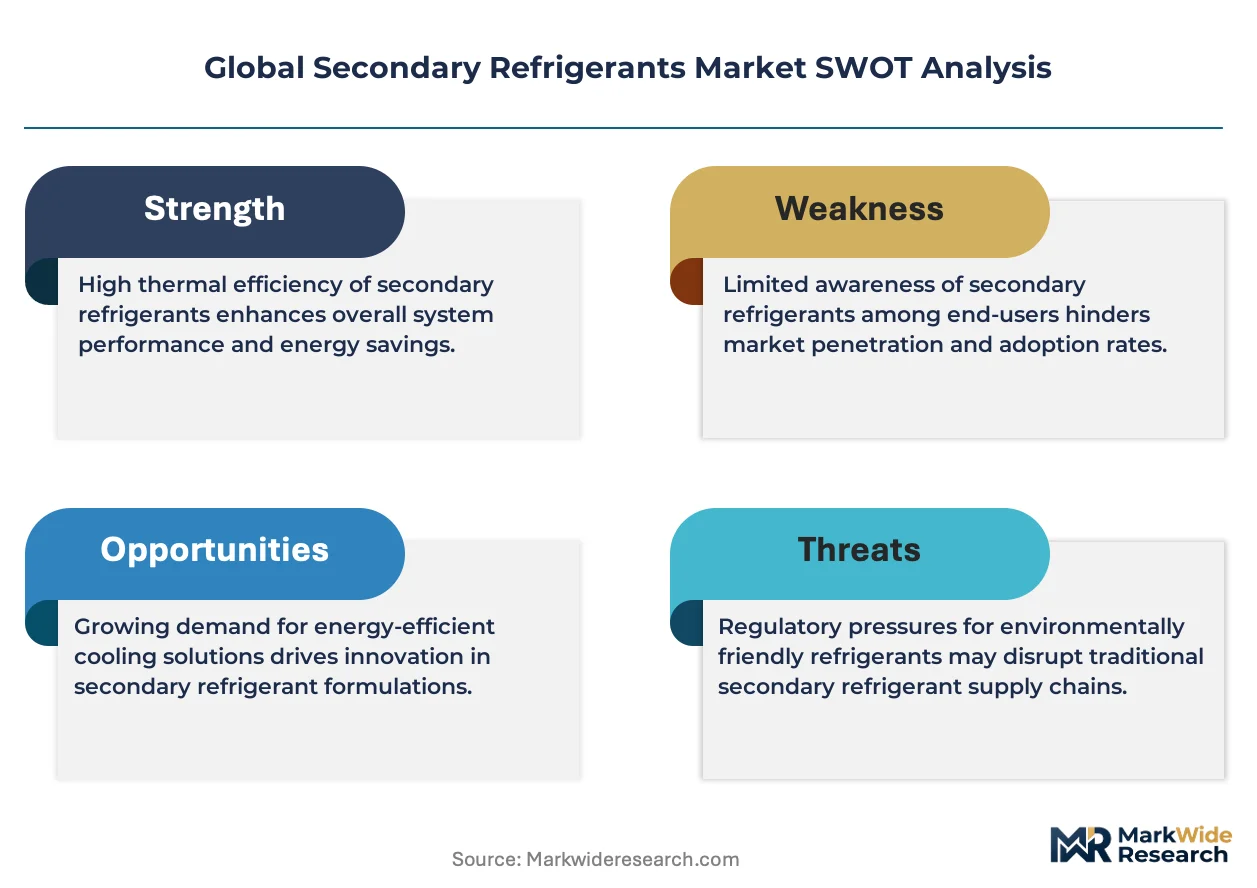
Regulations such as the European Union's F-Gas Regulation and the EPA's Significant New Alternatives Policy (SNAP) program in the United States are critical. These frameworks restrict high-GWP primary refrigerants, indirectly promoting secondary loop systems that require smaller primary refrigerant charges. Consequently, fluid selection for system designers now involves a complex trade-off between thermal efficiency, regulatory compliance, and total lifecycle cost.
Market Dynamics
The central structural force shaping the market is the regulatory-driven phase-down of high-GWP primary refrigerants. Mandates like the EU's F-Gas Regulation are compelling a shift to secondary loop systems, which use a smaller, contained primary charge, thereby elevating the importance of the heat transfer fluid's performance.
Growth Catalysts
- Data Center Cooling Demand:The expansion of hyperscale and edge data centers requires highly efficient and reliable cooling systems, driving adoption of secondary refrigerants to manage intense thermal loads.
- EU F-Gas Regulation:This framework's strict quotas on hydrofluorocarbons (HFCs) create a powerful incentive for system designers and end-users in Europe to adopt secondary loop architectures to minimize primary refrigerant use.
- Chinese Industrial Expansion:Rapid growth in China's food processing, pharmaceutical, and cold storage sectors is creating sustained demand for industrial-grade refrigeration, where secondary refrigerants are a core component.
Market Restraints
- High Initial Capital Outlay:Secondary loop systems often require a greater upfront investment in pumps, piping, and heat exchangers compared to simpler direct expansion (DX) systems, posing a barrier for cost-sensitive buyers.
- Performance Trade-Offs:Glycol-based fluids, the market's mainstay, exhibit increased viscosity at lower temperatures, which can reduce heat transfer efficiency and increase pumping energy requirements.
- Low-GWP Primary Refrigerant Advances:The development of new, safer, and more efficient low-GWP primary refrigerants for use in DX systems presents a substitution threat, potentially slowing the conversion to secondary loops.
Strategic Opportunities
- Bio-Based Fluid Development:Formulating secondary refrigerants from renewable, bio-based feedstocks offers a path to improve the sustainability profile of products and appeal to customers with corporate ESG mandates.
- Thermal Management for BESS:The battery energy storage system (BESS) market represents an emerging application, requiring precise and reliable liquid cooling to ensure battery safety and lifespan.
- Cold Chain in Southeast Asia:Underpenetrated markets in Southeast Asia present significant growth potential as their food production and pharmaceutical logistics infrastructure modernizes, requiring new cold chain solutions.
Industry Challenges
- Technician Skill Gaps:A shortage of HVAC-R technicians trained in the design, installation, and maintenance of more complex secondary loop systems can hinder adoption and lead to suboptimal system performance.
- Legacy System Integration:Retrofitting existing facilities with secondary refrigerant loops presents significant challenges, including integration with legacy primary refrigeration equipment and building automation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Secondary Refrigerants Market |
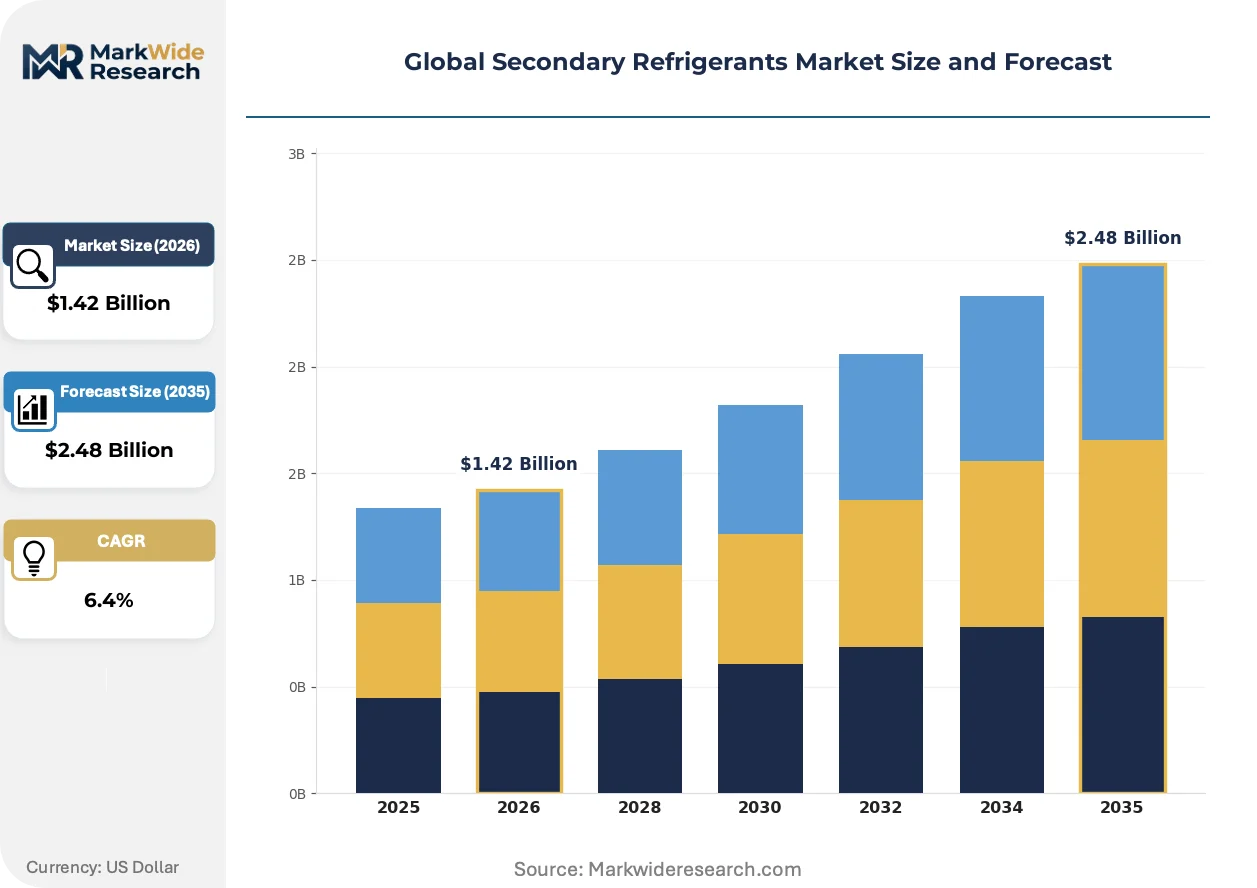
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene Glycol, Propylene Glycol, Calcium Chloride Brine, Magnesium Chloride Brine, Methanol, Potassium Formate Application: Commercial Cooling, Industrial Process Cooling, HVAC Systems, Food & Beverage Processing, Pharmaceutical Storage, Data Center Cooling End User Industry: Cold Storage Facilities, Chemical Manufacturers, Beverage Producers, Data Center Operators, Pharmaceutical Labs, Metal Fabrication Plants Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Industrial Suppliers, Regional Wholesalers, OEM Partnerships |
| Companies Covered | Evonik Industries, Clariant, Linde plc, A-Gas International, The Lubrizol Corporation, Dow, Eastman Chemical Company, Temper Technology Ab, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Secondary Refrigerants Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from basic heat transfer to a focus on total system efficiency and lifecycle sustainability. This shift is a direct response to the demands of data-intensive industries and tightening environmental regulations worldwide.
Nanofluids, which are base fluids like glycol seeded with thermally conductive nanoparticles, provide enhanced heat transfer properties. The high-performance computing and data center sectors are early adopters, seeking maximum heat dissipation from densely packed electronics. This technology is miniaturizing the required heat exchanger size and fluid volume for a given thermal load, enabling more compact and energy-efficient cooling system designs.
The United States EPA’s Significant New Alternatives Policy (SNAP) program continues to restrict the use of high-GWP refrigerants. This regulatory pressure forces commercial and industrial refrigeration operators to re-evaluate system design, often favoring secondary loops that use a minimal primary charge. The supermarket and cold storage warehouse segments are most impacted, accelerating their transition toward systems using ammonia or CO2 in the primary circuit.
End-users are increasingly adopting a Total Cost of Ownership (TCO) model when selecting heat transfer fluids. This evaluation moves the procurement decision beyond initial cost to encompass long-term factors like pumping energy, maintenance schedules, and regulatory compliance risk. This behavioral shift is most visible in the European food processing industry, where high energy costs and F-Gas compliance make TCO a critical decision metric.
Global Secondary Refrigerants Market Segmentation
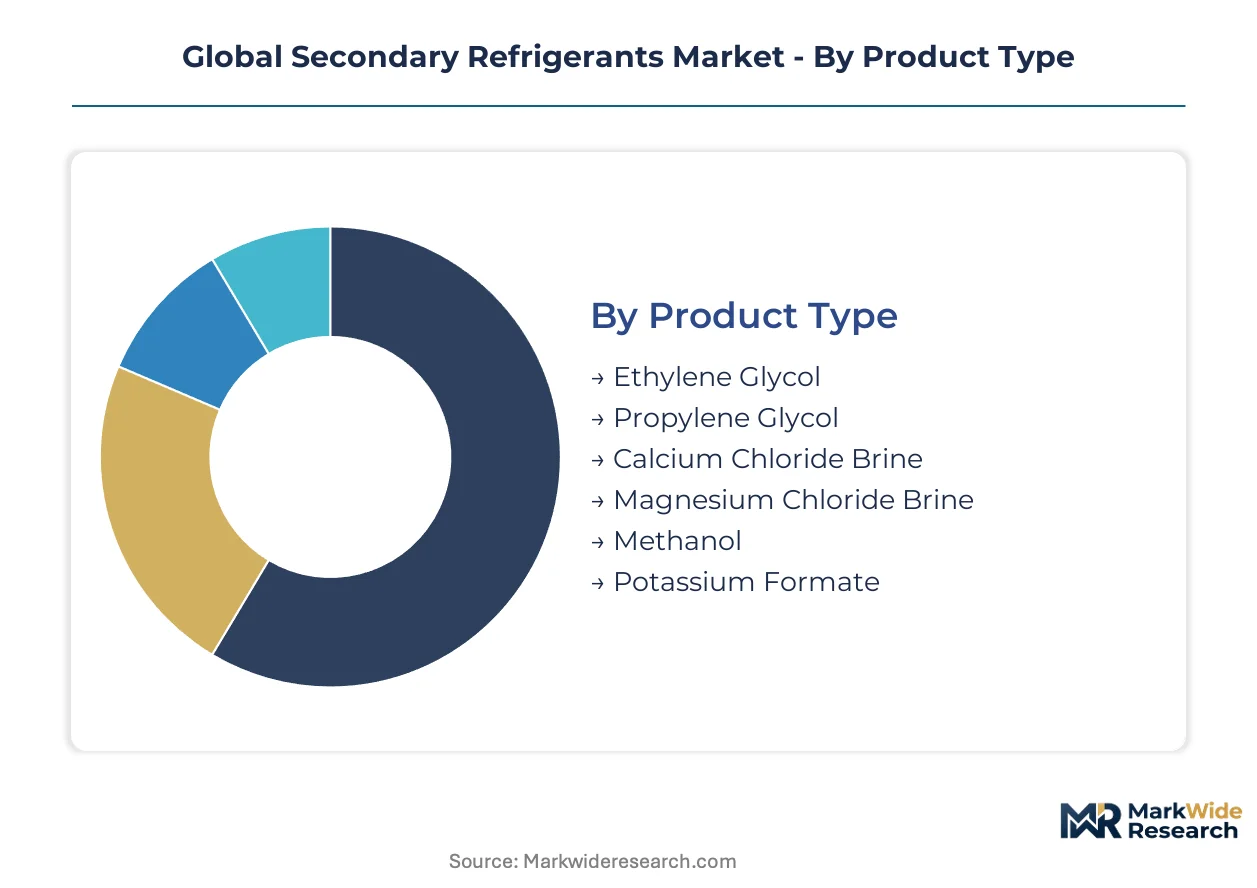
The Global Secondary Refrigerants Market segmentation reveals how specialized fluid properties and application demands shape distinct market sub-sectors. This granular view informs strategic planning for product development and market entry, identifying areas of concentrated demand.
Product Type:
Product type selection reflects regional regulatory landscapes and local feedstock availability. Formulations gain traction in specific industrial hubs due to established supply chains.
- Ethylene Glycol:This fluid provides robust freeze protection and efficient heat transfer. Demand concentrates in large industrial facilities across China and the United States, driven by cost-effectiveness.
- Propylene Glycol:With lower toxicity, this product is preferred where incidental contact with food is a concern. European food processing increasingly specifies propylene glycol.
- Calcium Chloride Brine:Economical option, offers good thermal properties for large-scale cold storage.
- Magnesium Chloride Brine:Alternative to calcium chloride, chosen for less corrosive nature in specific industrial setups.
- Methanol:Used in very low-temperature industrial applications, particularly chemical and petrochemical industries.
- Potassium Formate:Delivers superior low-temperature performance and reduced viscosity, suitable for demanding industrial process cooling.
Ethylene Glycol holds the largest share; momentum sits with Potassium Formate.
Application:
The application segment delineates operational environments and thermal management challenges. Each demands a unique balance of thermal efficiency and system compatibility.
- Industrial Process Cooling:Manages precise temperatures for manufacturing, requiring fluids operating across wide temperature ranges. Chemical production in Germany and the US prioritizes thermal stability.
- Data Center Cooling:Hyperscale data centers require highly efficient cooling for intense thermal loads. Demand for advanced fluids accelerates in facilities across Ireland and Singapore.
- Commercial Cooling:Encompasses retail and office cooling needs, often using glycol-based solutions.
- HVAC Systems:Secondary refrigerants provide comfort cooling and heating in large commercial buildings.
- Food & Beverage Processing:Demands non-toxic fluids for chilling and freezing, ensuring product safety.
- Pharmaceutical Storage:Requires precise temperature control for sensitive drugs, driving need for reliable refrigerants.
Data Center Cooling exhibits significant demand; Industrial Process Cooling remains a foundational segment.
End User Industry:
End-user industry classification highlights diverse operational requirements and regulatory pressures. Specialized industries demand fluids tailored to their unique production environments.
- Data Center Operators:Manage IT infrastructure requiring continuous, high-capacity cooling. Operators in Sweden and the Netherlands invest in advanced fluid solutions for energy efficiency.
- Cold Storage Facilities:Store perishable goods, demanding robust and energy-efficient refrigeration. Owners in China and India prioritize cost-effective fluids to minimize operational expenses.
- Chemical Manufacturers:Use refrigerants for precise temperature control in reactions and sensitive compound storage.
- Beverage Producers:Utilize fluids for chilling, fermentation control, and product storage in breweries.
- Pharmaceutical Labs:Rely on refrigerants for controlled environments and safe storage of biological samples.
- Metal Fabrication Plants:Employ refrigerants for cooling machinery and processes, managing heat during manufacturing.
Cold Storage Facilities represent a substantial market base; Data Center Operators are driving significant innovation.
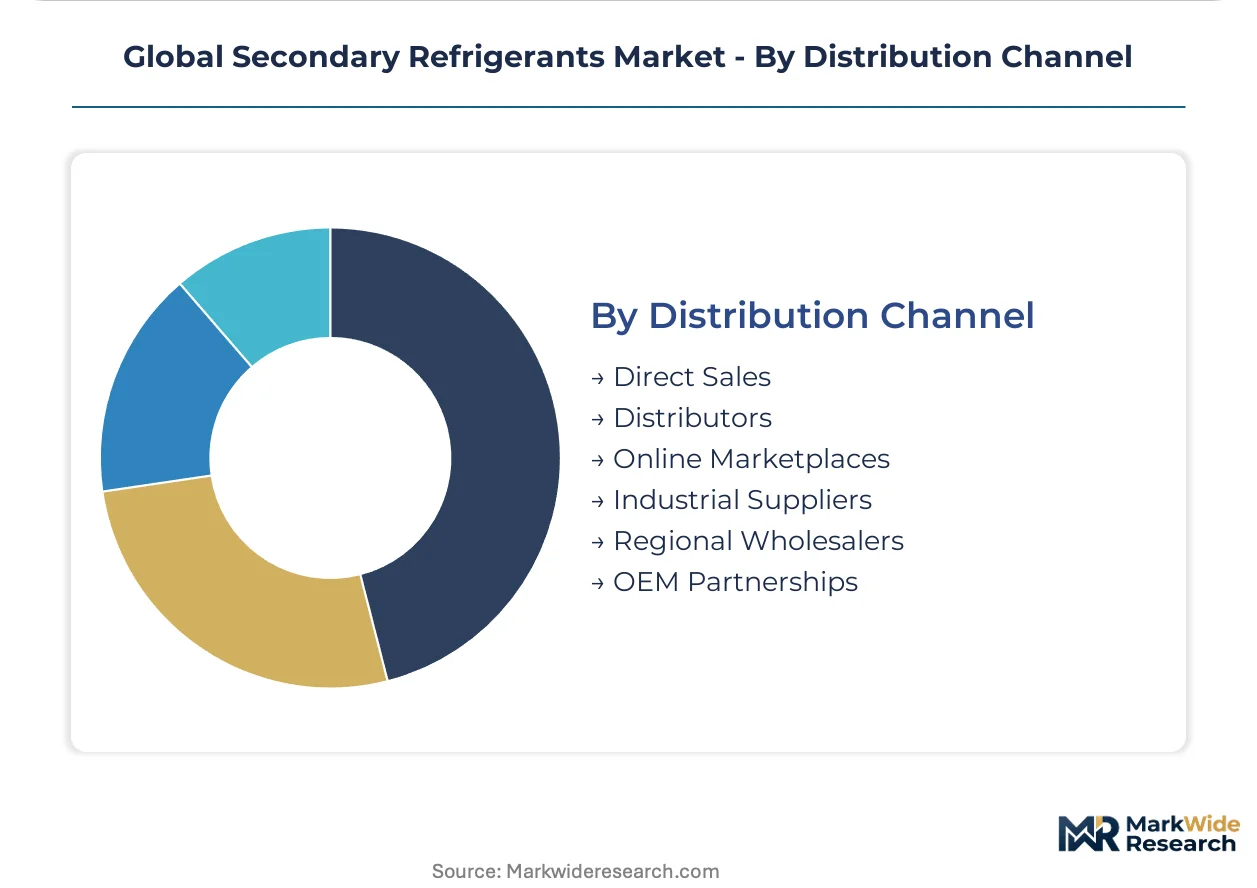
Distribution Channel:
This segment illustrates primary pathways for refrigerants, reflecting market maturity and customer requirements. Established channels cater to bulk buyers.
- Direct Sales:Large industrial consumers and OEMs procure directly from producers for consistent supply. Prevalent for high-volume orders in the US Gulf Coast.
- Distributors:Play a crucial role in reaching fragmented customer bases, providing localized inventory and technical support. Vital for SMEs across Europe and Australia.
- Online Marketplaces:Emerging channel for specialized or smaller volume orders, offering convenience and broad product selection.
- Industrial Suppliers:Cater to various industrial clients, offering a range of chemicals and related products.
- Regional Wholesalers:Serve specific geographic areas, providing bulk quantities to local businesses.
- OEM Partnerships:Collaborations integrate secondary refrigerants directly into new cooling systems and machinery.
Direct Sales accounts for a significant portion of volume; OEM Partnerships are expanding their market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical producers in Germany and the United States export advanced secondary refrigerant formulations to meet diverse industrial demands globally. This international trade facilitates the adoption of specialized fluids for critical thermal management applications. Regulatory frameworks in key regions further shape procurement patterns.
China
China's rapid industrial expansion and significant growth in cold storage infrastructure are primary drivers for secondary refrigerants. The country's dual carbon goals encourage more energy-efficient refrigeration technologies, impacting fluid selection. Major industrial hubs like the Yangtze River Delta and Pearl River Delta drive substantial demand for process cooling and cold chain solutions.
United States
The United States market is driven by robust demand from data center cooling and industrial process applications. The EPA's Significant New Alternatives Policy (SNAP) program encourages the shift away from high-GWP primary refrigerants, indirectly boosting secondary loop systems. Technology clusters in California and major data center corridors in Virginia represent significant consumption points for advanced cooling fluids.
Germany
Germany's sophisticated industrial base, particularly in chemical production, creates a strong demand for high-performance secondary refrigerants. The EU's F-Gas Regulation critically influences system design, pushing for smaller primary refrigerant charges and efficient secondary loops. Chemical manufacturing centers like Ludwigshafen consistently require advanced thermal management solutions for precise process control.
India
India's expanding food processing and pharmaceutical sectors are propelling demand for reliable cold chain and storage facilities. Government initiatives, such as the PLI scheme for food processing, support infrastructure development that requires efficient refrigeration. Major metropolitan areas and agricultural regions are developing new cold storage capacities, increasing fluid consumption.
Ireland
Ireland has become a major hub for hyperscale data centers, which require highly efficient and reliable cooling systems. The EU F-Gas Regulation directly impacts refrigerant choices for these facilities, favoring secondary loops to minimize environmental impact. Data center clusters around Dublin are at the forefront of adopting advanced thermal fluids for intense heat dissipation.
Global Secondary Refrigerants Market Key Industry Players
Listed leaders compete with private specialists across the secondary refrigerants market, influencing product innovation and distribution strategies. The market structure exhibits a blend of large-scale chemical producers and niche formulators catering to specific application needs. Strategic archetypes include global chemical conglomerates leveraging vast production capabilities, specialized thermal fluid providers focusing on performance, and regional solution integrators offering localized support. Companies pursue portfolio diversification and strategic partnerships to expand their application reach and integrate new technologies.
At the scale-driven end, Dow, a prominent American chemical manufacturer, represents a foundational supplier of glycol-based fluids, leveraging its extensive chemical production infrastructure. Similarly, German-based BASF SE exemplifies a leader in advanced formulations like potassium formate, catering to demanding low-temperature industrial applications with specialized products. These large entities often anchor the market with their broad portfolios. Linde plc, a global industrial gas and engineering firm, also occupies a position within the broader thermal management solutions segment, frequently integrating heat transfer fluids into larger system offerings for industrial clients.
| Leading Market Players |
|---|
| Evonik Industries |
| Clariant |
| Linde plc |
| A-Gas International |
| The Lubrizol Corporation |
| Dow |
| Eastman Chemical Company |
| Temper Technology Ab |
| BASF SE |
Cost & Logistics Intelligence
Typical lead times for specialized secondary refrigerants, particularly advanced formulations, directly influence their pricing power and market entry strategies. This reflects the complexity of chemical synthesis and the need for application-specific testing, shaping both supply chain configuration and customer willingness to pay a premium.
Pricing Analysis
A significant pricing gap separates foundational glycol-based fluids from advanced potassium formate formulations. The market primarily operates on a contract-based long-term offtake model for bulk industrial buyers, with per-unit transactional pricing common for smaller, specialized orders. Price differentiation stems from performance at low temperatures and regulatory compliance for non-toxic applications. Pricing pressure intensifies for standard glycol products due to competition from low-GWP primary refrigerants. Cold storage facilities often exhibit the highest price sensitivity, whereas data center operators prioritize thermal efficiency and reliability over initial cost.
Supply Chain Analysis
Just-in-time inventory models for specialized secondary refrigerants minimize holding costs for distributors and end-users. The supply chain for base chemicals heavily concentrates in Germany, the United States, and China. Manufacturers depend on key raw materials like ethylene, propylene, and potassium carbonate. A structural risk involves commodity price volatility for these base chemicals, impacting production costs. Distribution runs primarily through direct sales channels to large industrial consumers and OEMs, complemented by regional distributors serving fragmented customer bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The secondary refrigerants market is experiencing a platform-economics inflection driven by the integration of thermal management solutions into broader data center infrastructure ecosystems.
For Market Incumbents: Fortify core market positions by investing in next-generation bio-based fluid development. Develop strategic partnerships with HVAC-R system integrators to offer comprehensive thermal management solutions, mitigating the threat from low-GWP primary refrigerants. Leverage existing chemical production scale to achieve cost leadership in foundational glycol products. Prioritize channel control through expanded OEM partnerships to secure future demand within new system designs.
For New Entrants and Emerging Players: Anchor in emerging high-growth niches like battery energy storage systems (BESS) thermal management and cold chain expansion in Southeast Asia. The most penetrable segment remains smaller industrial facilities seeking sustainable cooling solutions. A performance-driven value proposition, emphasizing superior thermal efficiency and reduced energy consumption, offers a strong go-to-market angle against established, cost-focused offerings.
For Investors and Strategic Acquirers: Carve-out targets emerge from large chemical conglomerates looking to divest non-core specialty fluid divisions. The long-term viability of this market extends over the next decade, supported by regulatory tailwinds and increasing demand for efficient cooling. Niche formulators with proprietary low-viscosity, high-performance formulations represent attractive acquisition archetypes. The uptake rate of nanofluids in hyperscale data centers serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet rising demand from Chinese industrial expansion and cold storage development. |
| Green Manufacturing Transition | Align with EU F-Gas Regulation sustainability goals and corporate ESG mandates. |
| Long-term Supply Agreement | Secure key raw materials like potassium carbonate amidst potential supply chain disruptions. |
| Joint Venture | Develop integrated cooling solutions for data center operators and BESS manufacturers. |
| Technology Licensing | Accelerate adoption of advanced nanofluid formulations across diverse application segments. |
Research Approach
Two parallel data streams informed the analysis: in-depth primary interviews and extensive secondary research validation. Primary research engaged R&D directors at chemical manufacturers, procurement leads from data center operators, HVAC-R system integrators, and cold storage facility managers. Secondary data sources included EPA SNAP program documents, EU F-Gas Regulation texts, company annual reports, and industry association publications, all triangulated with bottom-up and top-down market sizing approaches.
Over the projection horizon, the analytical framework integrated a multi-dimensional segmentation approach across product type, application, end-user industry, and regional regulatory impact. Compound annual growth rates were derived from historical growth trends and projected future demand. Key industry-specific forecast inputs included data center build-out rates in key regions and the F-Gas quota phase-down schedules in Europe.
Material uncertainties — including unforeseen shifts in global energy prices or new primary refrigerant breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Annular Cooler Market
Cooling Systems
Offshore Air Handling Units Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Cryosystem Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Three Phase Cooling Fans Market