
 Heat Pump Dryer Market | 2026-2036
Heat Pump Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Pump Dryer Market Insights
EU Ecodesign regulations are rebalancing the cost-of-entry calculus for appliance manufacturers targeting European markets. Bosch Siemens Home Appliances Group leverages its captive compressor manufacturing to sustain margin control across premium residential lines. LG Electronics anchors its position through R&D intensity in dual-shaft heat pump architectures. Miele dominates the super-premium segment with specialized steel-drum engineering and extended warranty programs.
A heat pump dryer extracts moisture from textiles by circulating heated air through a closed-loop refrigeration cycle, typically achieving drying temperatures between 40°C and 65°C while consuming roughly half the energy of conventional resistive dryers. The apparatus serves residential and commercial laundries seeking to reduce operational expenditure and grid dependency. Vapor compression technology occupies the bulk of installed capacity due to its established supply chain and service infrastructure, though hybrid systems are gaining traction in commercial settings where duty cycles vary sharply. Residential end users represent the deepest demand pool, while modular configurations for industrial laundries command the widest per-unit margins.
CE marking requirements and the EU F-Gas Regulation constrain refrigerant selection and compressor efficiency thresholds for equipment sold across Europe. EPA Energy Star certification in the United States shapes procurement criteria for institutional buyers and utility rebate programs. Stakeholders must monitor refrigerant phase-down schedules and regional efficiency tier upgrades to align product roadmaps with compliance deadlines.
Market Dynamics
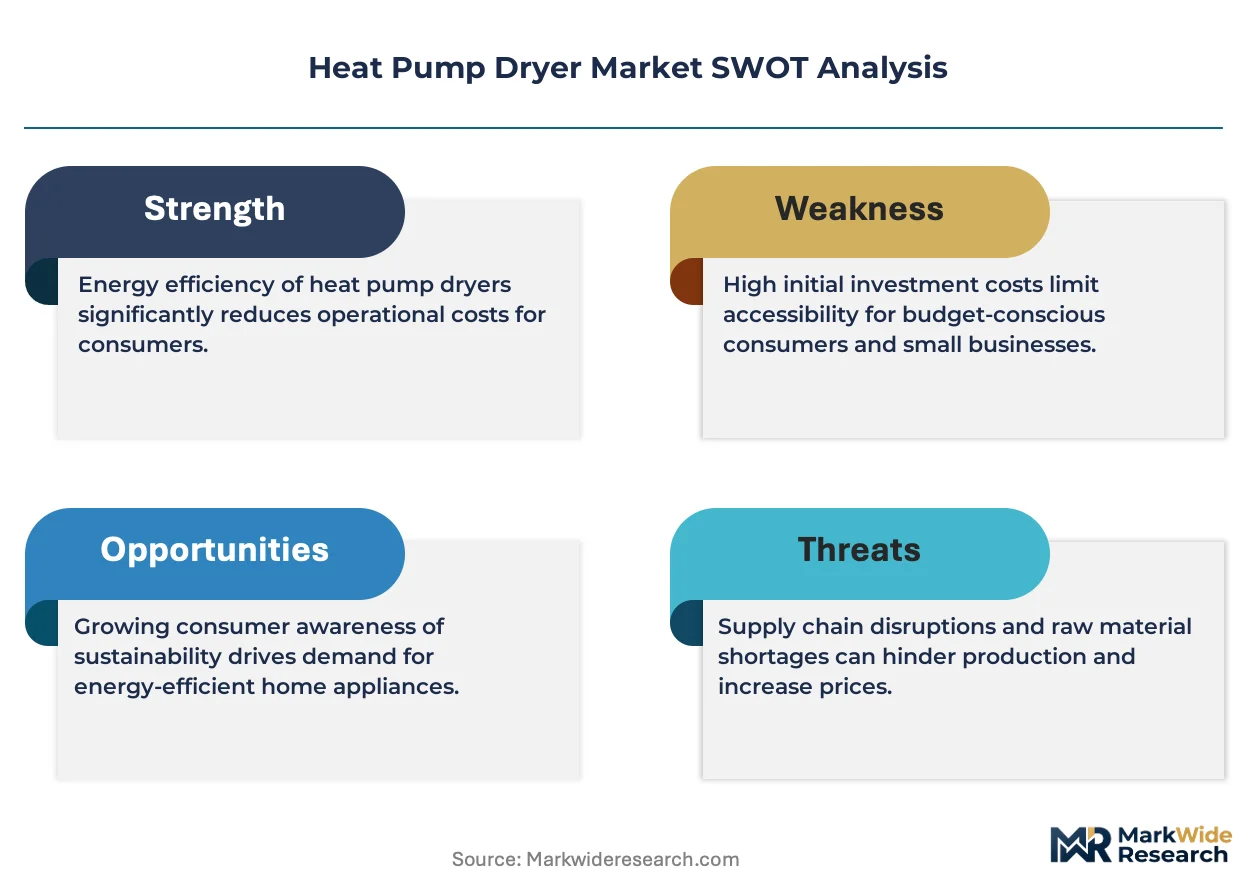
EU Ecodesign mandates are compressing replacement cycles across residential appliance stock, forcing manufacturers to reconfigure product portfolios around heat pump architectures ahead of 2027 efficiency tier upgrades. This regulatory compression is redistributing margin pressure upstream through compressor supply chains.
Growth Catalysts
- CE marking efficiency tiers:The EU F-Gas Regulation mandates refrigerant phase-downs that favor low-GWP heat pump systems over resistive alternatives in new residential construction.
- Utility rebate programs:EPA Energy Star certification unlocks institutional procurement pathways and consumer incentives across US municipal markets.
- Urban household density:Medium-capacity units serve space-constrained apartments in German and French metropolitan cores where vented dryers face installation barriers.
Market Restraints
- Copper and rare-earth input costs:Compressor manufacturing depends on concentrated Chilean copper supply and Chinese rare-earth processing, exposing margins to commodity volatility.
- Service infrastructure gaps:Vapor compression systems require specialized refrigerant handling certification that remains scarce outside major European urban centers.
- Resistive dryer substitution:Lower first-cost vented alternatives retain price-sensitive segments in markets without strict efficiency mandates.
Strategic Opportunities
- Hybrid system convergence:Dual-source heat pump-gas configurations address commercial laundries with variable duty cycles in German hospital and hotel sectors.
- Modular industrial configurations:Containerized drying units serve off-grid mining camps and remote hospitality operations seeking diesel displacement.
- Utility demand-response integration:Smart-grid-enabled dryers participating in frequency regulation programs create recurring revenue streams beyond equipment sales.
Industry Challenges
- Refrigerant technician certification:F-Gas licensing requirements constrain service network expansion, limiting aftermarket penetration in secondary European markets.
- Legacy electrical infrastructure:Residential panel upgrades required for heat pump dryer installation add friction to replacement sales in aging US housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Pump Dryer Market |
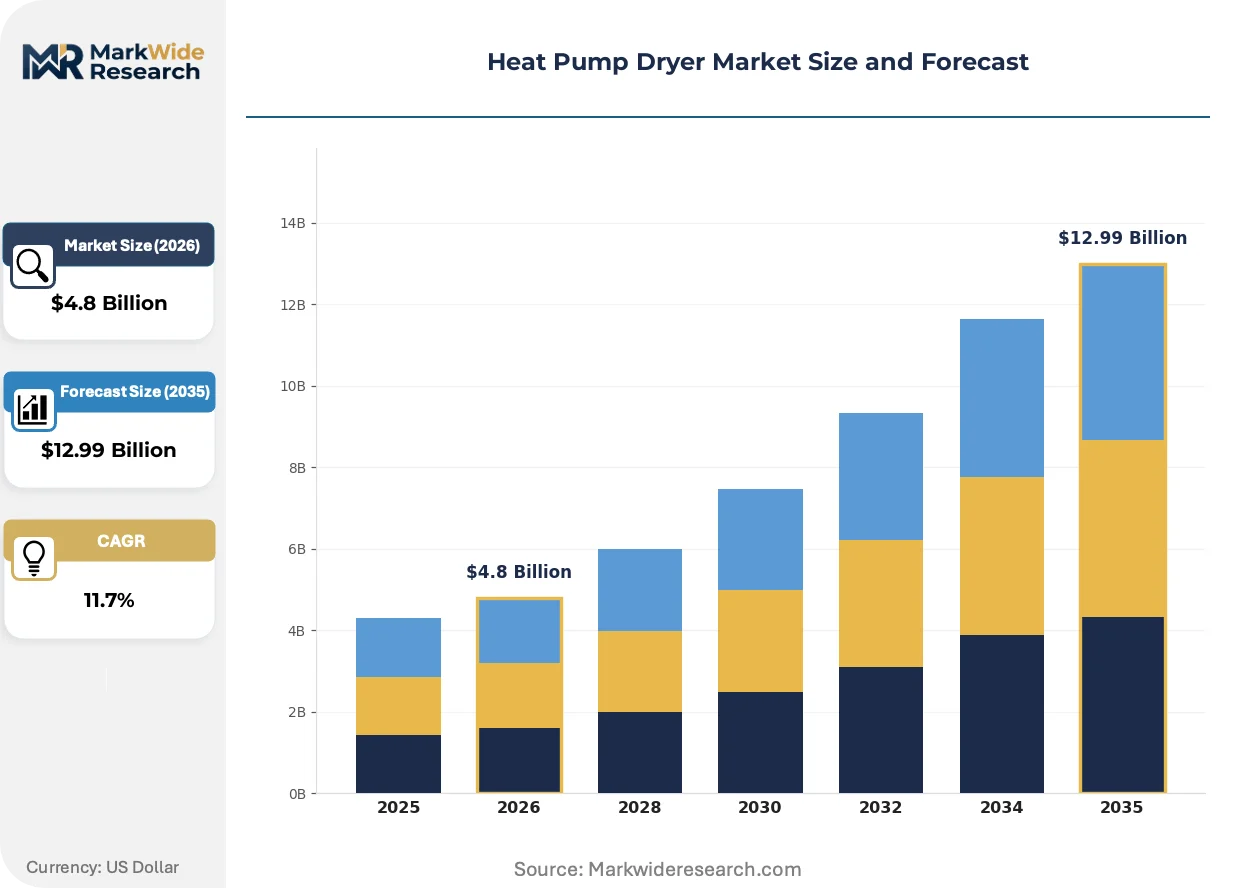
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Modular Technology: Vapor Compression, Thermoelectric, Dual-Shaft, Hybrid End User: Households, Laundries, Hotels, Manufacturing Facilities Capacity: Small, Medium, Large, Extra-Large |
| Companies Covered | Bosch Siemens Home Appliances Group, LG Electronics, Samsung Electronics, Whirlpool Corporation, Electrolux AB, Miele, Haier, Candy Hoover Group, Fisher & Paykel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Pump Dryer Market Trends and Innovations
Refrigeration cycle optimization and control system advances are compressing drying times while expanding the addressable market beyond efficiency-conscious early adopters. Equipment makers are embedding predictive maintenance and grid-interactive capabilities as standard features.
Variable-speed inverter compressors are automating load-matching across mixed fabric weights and ambient humidity conditions. Residential buyers in German and Benelux markets are specifying these systems for A+++ efficiency ratings. The technology is automating manual program selection and reducing energy overconsumption in heterogeneous laundry loads.
The EU F-Gas Regulation mandates refrigerant charge thresholds and leak detection requirements for systems above specified capacities. Manufacturers must redesign heat exchanger architectures and adopt microchannel coils to comply with volumetric limits. Commercial laundry operators in France and Italy are accelerating replacement timelines to avoid stranded asset risk from refrigerant availability constraints.
Building energy performance certificates now incorporate appliance efficiency ratings in German and Austrian residential transactions. Buyers are treating heat pump dryers as bundled assets in property valuations, shifting purchase timing from failure-driven to transaction-driven. This behavioral pivot concentrates demand spikes around peak real estate seasons in Central European urban markets.
Heat Pump Dryer Market Segmentation
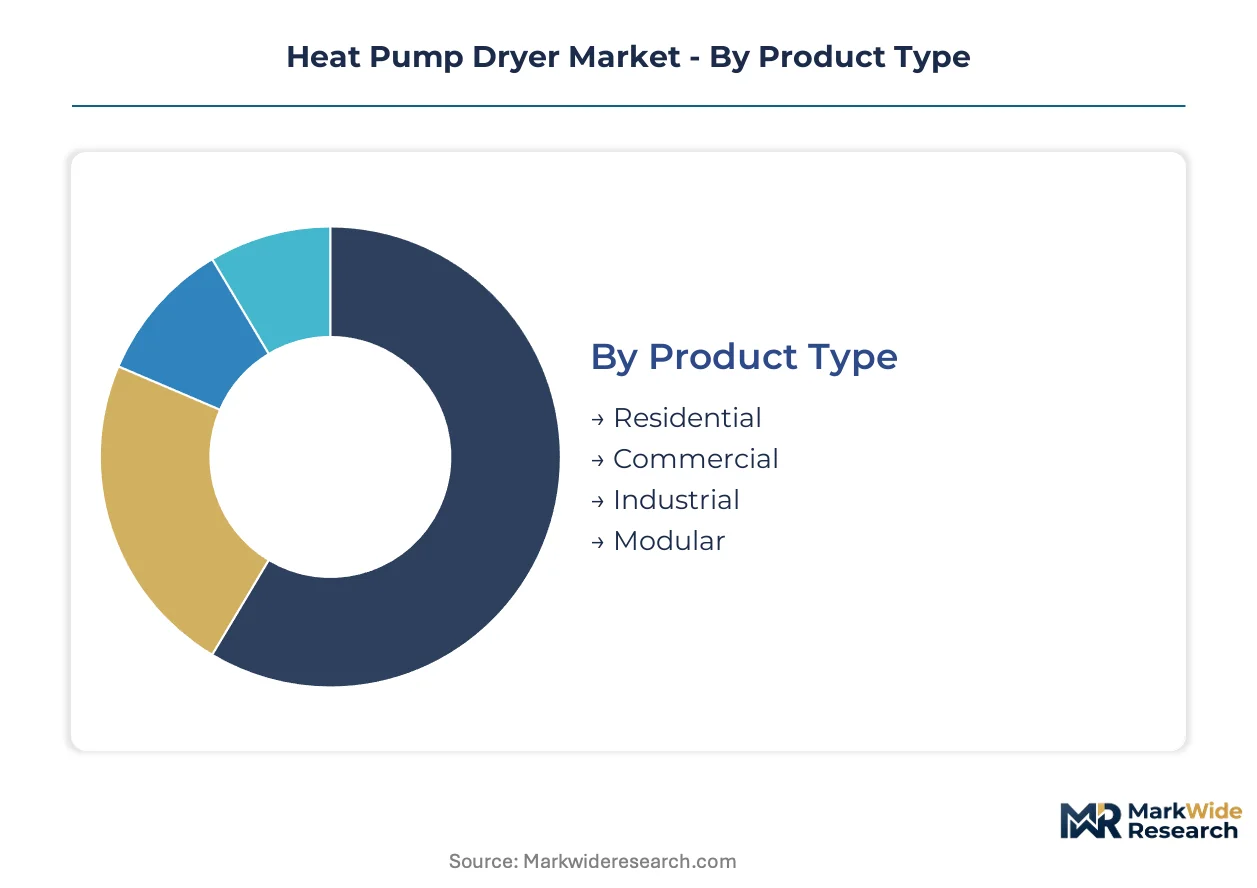
Heat pump dryer segmentation reveals distinct engineering and commercial logics across installation contexts. Product architecture, thermodynamic approach, and duty-cycle intensity each create separate margin profiles and regulatory exposure. Manufacturers configure portfolios across these dimensions to match regional efficiency mandates and end-user operational constraints.
Product Type:
Standalone units dominate residential replacement flows while embedded systems serve new construction and commercial retrofits.
- Residential:Self-contained cabinet designs integrate heat pump modules with drum assemblies for in-home installation. German households under Ecodesign mandates drive replacement demand in urban apartments where vented exhaust is impractical.
- Commercial:Rack-mounted or floor-standing configurations serve coin-laundry operators and multi-housing facilities with continuous duty cycles. French laundromat chains specify these for A+++ efficiency compliance and utility rebate capture.
- Industrial:Tunnel and batch systems process bulk textiles for hospitality linen services and healthcare sterilization operations.
- Modular:Containerized or skid-mounted units deploy to remote mining camps and temporary hospitality installations lacking grid connection.
Residential leads volumes today; modular configurations are gaining share fastest.
Technology:
Refrigeration cycle architecture determines efficiency ceiling, first cost, and service complexity across deployment scenarios.
- Vapor Compression:Standard compressor-evaporator-condenser loops achieve coefficient of performance ratios above three in steady-state operation. Established supply chains and technician certification networks support broad European penetration.
- Dual-Shaft:Separate compressor and fan motors enable independent speed control for mixed fabric loads. German and Benelux buyers specify these for precision drying of technical textiles and delicates.
- Thermoelectric:Solid-state Peltier modules eliminate refrigerant handling but sacrifice efficiency at scale.
- Hybrid:Gas-fired boost stages supplement heat pumps in high-throughput commercial settings with variable demand patterns.
Vapor compression anchors installed base; dual-shaft architectures are expanding most quickly in premium residential tiers.
End User:
Purchase criteria diverge sharply between consumption-driven households and throughput-optimized commercial operators.
- Households:Individual consumers prioritize program flexibility, noise levels, and energy label ratings over absolute drying speed. German and Austrian buyers bundle appliance efficiency into property transaction valuations.
- Hotels:On-premise laundry operations balance labor costs against linen availability targets. French and Italian hospitality chains accelerate replacement timelines to avoid F-Gas refrigerant availability constraints.
- Laundries:Independent and chain operators focus on throughput per square meter and utility demand-charge management.
- Manufacturing Facilities:Technical textile producers and automotive suppliers require contamination-controlled drying for process materials.
Households generate the deepest demand pool; hotel operators are driving the steepest efficiency upgrade cycle.
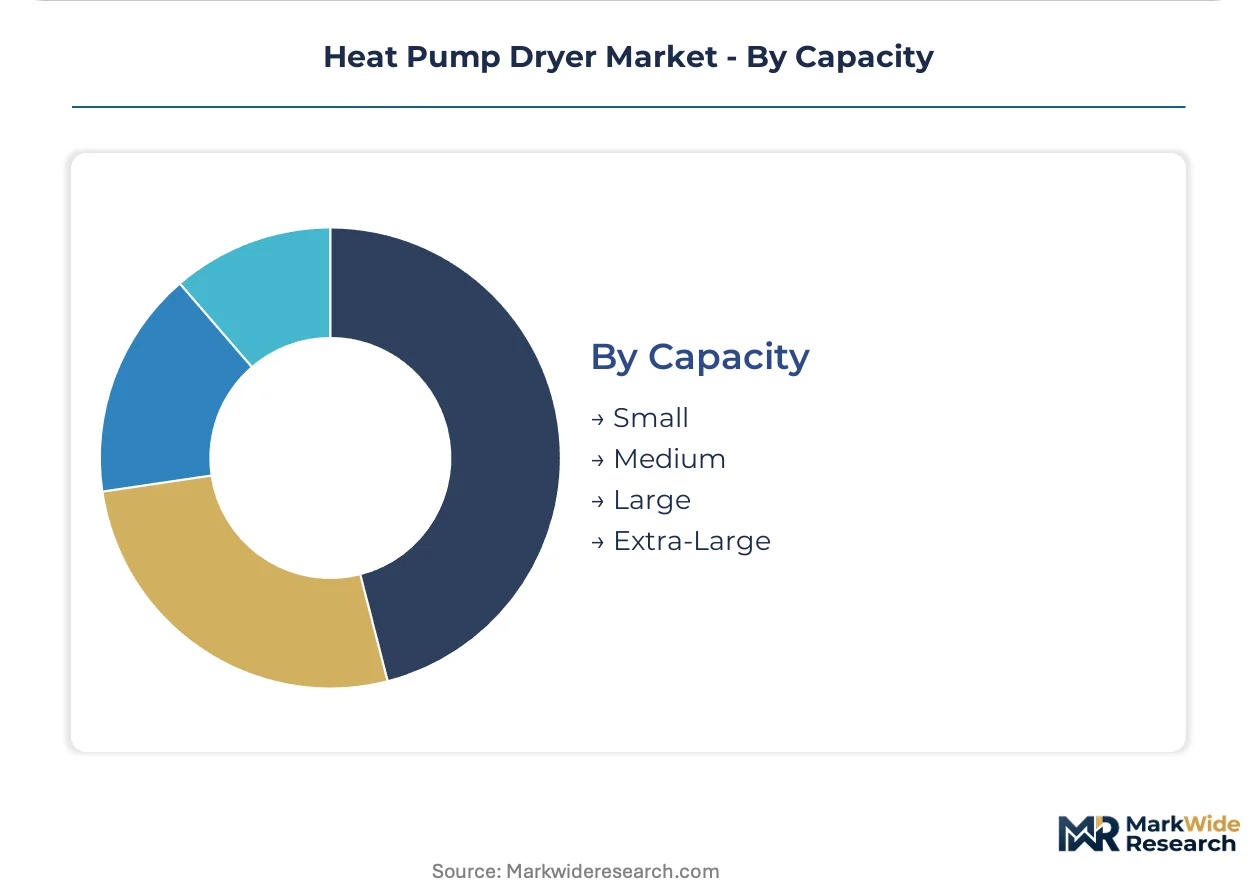
Capacity:
Drum volume and refrigerant charge scale determine installation requirements, panel capacity, and regulatory classification thresholds.
- Medium:Seven to nine kilogram drums serve space-constrained European apartments where vented alternatives face installation barriers. These units attract the strongest replacement demand in German and French metropolitan cores.
- Large:Ten to twelve kilogram configurations accommodate family-scale loads in detached and semi-detached housing. Buyers in suburban Benelux markets specify these for consolidated laundry cycles.
- Small:Compact under-counter designs target single-person households and secondary residences.
- Extra-Large:Industrial-scale drums exceed fifteen kilograms for commercial and institutional throughput requirements.
Medium capacity dominates unit shipments; large configurations are climbing the fastest in new construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled refrigeration technicians cluster in German industrial zones, anchoring Europe's densest service infrastructure for heat pump appliance deployment.
Germany
Bavarian and North Rhine-Westphalian households drive replacement cycles under Ecodesign mandates, with Munich and Cologne apartment blocks converting from vented systems. The F-Gas Regulation compresses refrigerant availability timelines. Stuttgart's manufacturing corridor hosts captive compressor production facilities supplying premium residential lines.
France
Paris and Lyon metropolitan cores exhibit concentrated demand for medium-capacity units in Haussmann-era buildings lacking exhaust infrastructure. The country's national energy regulator enforces building energy performance certificates that bundle appliance efficiency into property valuations. Lille's textile heritage corridor supports specialized commercial laundry engineering for hospitality chains.
United States
EPA Energy Star certification unlocks utility rebate pathways across California and New York municipal markets, with Los Angeles and Brooklyn apartment conversions accelerating. The Department of Energy maintains efficiency tier schedules that shape manufacturer product roadmaps. Chicago's electrical contractor networks face capacity constraints for residential panel upgrades required by heat pump dryer installations.
China
Yangtze River Delta and Pearl River Delta manufacturing basins concentrate compressor and heat exchanger component supply. The Ministry of Ecology and Environment enforces dual carbon goals that elevate heat pump architectures in domestic appliance standards. Qingdao's home appliance industrial park anchors export-oriented production for European efficiency-tier compliance.
Italy
Milan and Rome hospitality operators accelerate replacement timelines to avoid F-Gas refrigerant availability constraints in commercial laundry operations. The national energy agency administers appliance efficiency labeling that shapes procurement criteria for hotel chains. Bologna's packaging machinery corridor supplies auxiliary handling equipment for industrial-scale textile processing.
Heat Pump Dryer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The structure concentrates around three to five dominant appliance groups controlling premium and mass-market channels simultaneously. Strategic archetypes include captive-component manufacturers, brand-aggregating portfolio companies, and super-premium engineering specialists. Competitive moves center on backward integration into compressor supply and geographic licensing partnerships for regional efficiency compliance.
Within the captive-manufacturing archetype, Bosch Siemens Home Appliances Group and LG Electronics occupy positions that exemplify upstream control over refrigeration cycle components. Miele anchors the super-premium tier through specialized engineering positioning. These three entities represent distinct strategic postures: integrated supply chain command, dual-shaft architecture specialization, and steel-drum precision manufacturing respectively.
| Leading Market Players |
|---|
| Bosch Siemens Home Appliances Group |
| LG Electronics |
| Samsung Electronics |
| Whirlpool Corporation |
| Electrolux AB |
| Miele |
| Haier |
| Candy Hoover Group |
| Fisher & Paykel |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation phase-down schedules gate qualified refrigerant supply and premium-tier pricing access, forcing manufacturers to certify compressor architectures against tightening GWP thresholds before capturing A+++ efficiency premiums in German and Benelux residential markets.
Pricing Analysis
Bundled installation-and-warranty packages command 15-25% premiums over unbundled equipment-only transactions in European urban cores where F-Gas-certified technician scarcity inflates service costs. Price differentiation hinges on CE marking efficiency tiers and after-sales service bundling. Cost compression in standard-tier units is intensifying because Chinese compressor imports erode margin buffers. Price-sensitive mass-market buyers in Southern Europe resist premium positioning, while super-premium households in Munich and Vienna absorb extended-warranty markups without volume elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Bosch Siemens and LG captive manufacturing facilities, while specialized distributors serve aftermarket replacement flows. Component concentration centers on China's Yangtze River Delta for compressor motors and heat exchanger coils, Germany's Stuttgart corridor for precision steel drums, and Chile's copper belt for refrigerant tubing. Supply chain risk crystallizes around rare-earth magnet availability from Chinese processing nodes. Distribution runs through appliance retail chains in European urban centers and utility rebate program administrators in US municipal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Ecodesign 2027 efficiency tier upgrades lock in replacement demand acceleration across German residential stock.
For Market Incumbents: Deploy captive compressor manufacturing to defend margin position against low-cost Asian imports threatening standard-tier price floors. Bosch Siemens and LG Electronics should expand dual-shaft R&D pipelines to preempt Miele's super-premium steel-drum engineering advantages. Consolidate service certification networks before F-Gas technician scarcity constrains aftermarket penetration in secondary French and Italian markets.
For New Entrants and Emerging Players: Capture modular industrial configurations for off-grid mining camps and remote hospitality operations where diesel displacement economics override first-cost sensitivity. White-space concentration sits in US utility demand-response integration programs where smart-grid-enabled dryers create recurring revenue streams beyond equipment margins. Pursue licensing partnerships with established compressor suppliers rather than greenfield manufacturing investments.
For Investors and Strategic Acquirers: Roll-up economics work for regional service networks because F-Gas certification scarcity creates localized moats against national-scale competitors. Five-to-ten-year viability hinges on refrigerant phase-down compliance infrastructure rather than equipment manufacturing scale. Monitor EPA Energy Star tier upgrade announcements as inflection signals for US institutional procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Supply | Bosch Siemens and LG Electronics secure margin control against copper and rare-earth volatility through captive manufacturing. |
| Dual-Shaft Architecture R&D Investment | LG Electronics targets German precision-drying segments with independent motor speed control for technical textiles. |
| F-Gas Certification Network Expansion | Miele and Electrolux preempt service scarcity constraints in French and Italian secondary markets before 2027 deadlines. |
| Utility Demand-Response Partnership | Whirlpool and Haier capture recurring revenue streams through Los Angeles and Brooklyn municipal grid-interactive programs. |
| Modular Industrial Configuration Launch | Candy Hoover and Fisher & Paykel serve Australian mining camps and Saudi hospitality clusters lacking grid connection. |
Research Methodology
Coverage spans Germany, France, the United States, China, and Italy, with primary inputs from each market's stakeholder ecosystem. The research combines structured interviews with appliance R&D directors, compressor procurement leads at OEMs, F-Gas certification trainers, utility rebate program administrators, and commercial laundry operators with secondary validation through EU Ecodesign regulatory filings, EPA Energy Star certification databases, SEC 10-K appliance segment disclosures, and Chinese Ministry of Ecology and Environment domestic appliance standards. Bottom-up unit shipment modeling triangulates against top-down market value reconstruction.
Granularity-level modeling disaggregates volume and value across product type, refrigeration cycle architecture, end-user category, and drum capacity tier throughout the forecast period. CAGRs derive from segment-specific replacement cycle compression rates and efficiency mandate compliance deadlines. Industry-specific forecast inputs include Ecodesign tier adoption curves, F-Gas refrigerant availability constraints, and building energy performance certificate integration timelines in German residential transactions.
Underlying measurement precision varies by segment; residential replacement flows carry tighter precision than modular industrial configurations where project-based demand exhibits higher volatility. Forecasts reflect assumptions around regulatory enforcement consistency, copper price trajectory stability, and technician certification network expansion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Portable Chiller Market