
 Heat Pipe Market | 2026-2036
Heat Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Pipe Market Analysis
Copper is expanding its share in heat pipe construction as aluminum faces cost volatility and thermal performance limitations in high-density electronics. Boyd leverages vertical integration across thermal subsystem design to sustain pricing power in aerospace and defense contracts. Furukawa Electric anchors its position through captive smelting and precision extrusion capabilities in Japan. Fujikura competes via specialized vapor chamber geometries tailored to smartphone and server form factors.
A heat pipe is a passive heat transfer device that utilizes phase-change fluid dynamics within a sealed, evacuated envelope to transport thermal energy across temperature gradients with effective conductivities exceeding solid copper by orders of magnitude. The working fluid—typically water, ammonia, or specialized refrigerants—evaporates at the heated section and condenses at the cooler section, returning via capillary action through a wick structure. Electronics cooling applications dominate value capture given the power density escalation in GPUs and AI accelerators, while renewable energy installations represent the fastest-growing segment as concentrated solar and geothermal systems require reliable passive thermal management. Vapor chambers command premium positioning in consumer electronics where z-axis constraints prevent cylindrical geometries, and copper material grades differentiate performance tiers across telecommunications infrastructure deployments.
China's MIIT enforces GB standards on electronic product energy efficiency that directly mandate thermal management compliance testing, while the EU Ecodesign Directive and RoHS restrictions constrain material selections and end-of-life processing across European supply chains. Japan's METI promotes JIS-certified heat pipe integration in industrial equipment through efficiency rebate programs. Stakeholders must monitor regulatory divergence between Asian performance-based standards and European material restriction frameworks when configuring regional product portfolios.
Market Dynamics
Data center power densities from AI accelerators are forcing thermal management architectures toward vapor chamber and loop heat pipe configurations that traditional metal heatsinks cannot match.
Growth Catalysts
- MIIT GB Standards:China's energy efficiency mandates for electronic products require certified thermal management compliance testing, accelerating replacement of passive aluminum solutions with high-performance copper heat pipes.
- GPU Power Density Escalation:AI training clusters now exceed 700W per socket, creating immediate demand for two-phase cooling that maintains junction temperatures within thermal design power envelopes.
- East Asian Manufacturing Concentration:Precision extrusion and wick fabrication capabilities in Japan, South Korea, and Taiwan provide captive access to aerospace-grade copper tubing and sintered powder metallurgy.
Market Restraints
- Copper Price Volatility:London Metal Exchange copper futures expose heat pipe fabricators to input cost swings that compress margin on fixed-price telecommunications infrastructure contracts.
- Wick Structure Technical Limitations:Grooved and sintered wick designs face dry-out thresholds in high-g aerospace applications that limit deployment in satellite thermal control systems.
- REACH Material Restrictions:The EU ECHA's substance authorization requirements constrain working fluid selections and end-of-life processing for European-bound electronics cooling products.
Strategic Opportunities
- Concentrated Solar Power:Parabolic trough and tower installations in Spain and the Middle East require reliable passive thermal management for heat transfer fluid receivers.
- Geothermal Binary Cycle Plants:Organic Rankine cycle systems in Indonesia and Kenya utilize heat pipe heat exchangers for brine-to-working-fluid thermal coupling.
- METI Industrial Efficiency Rebates:Japan's rebate programs subsidize JIS-certified heat pipe integration in industrial furnaces and semiconductor manufacturing equipment.
Industry Challenges
- Two-Phase Flow Simulation Expertise:Computational fluid dynamics modeling of evaporator meniscus dynamics and condenser film condensation requires specialized talent scarce outside aerospace and nuclear engineering programs.
- Hermetic Seal Certification Timelines: Helium mass spectrometry leak testing and accelerated life validation for aerospace applications extend qualification cycles beyond commercial product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Pipe Market |
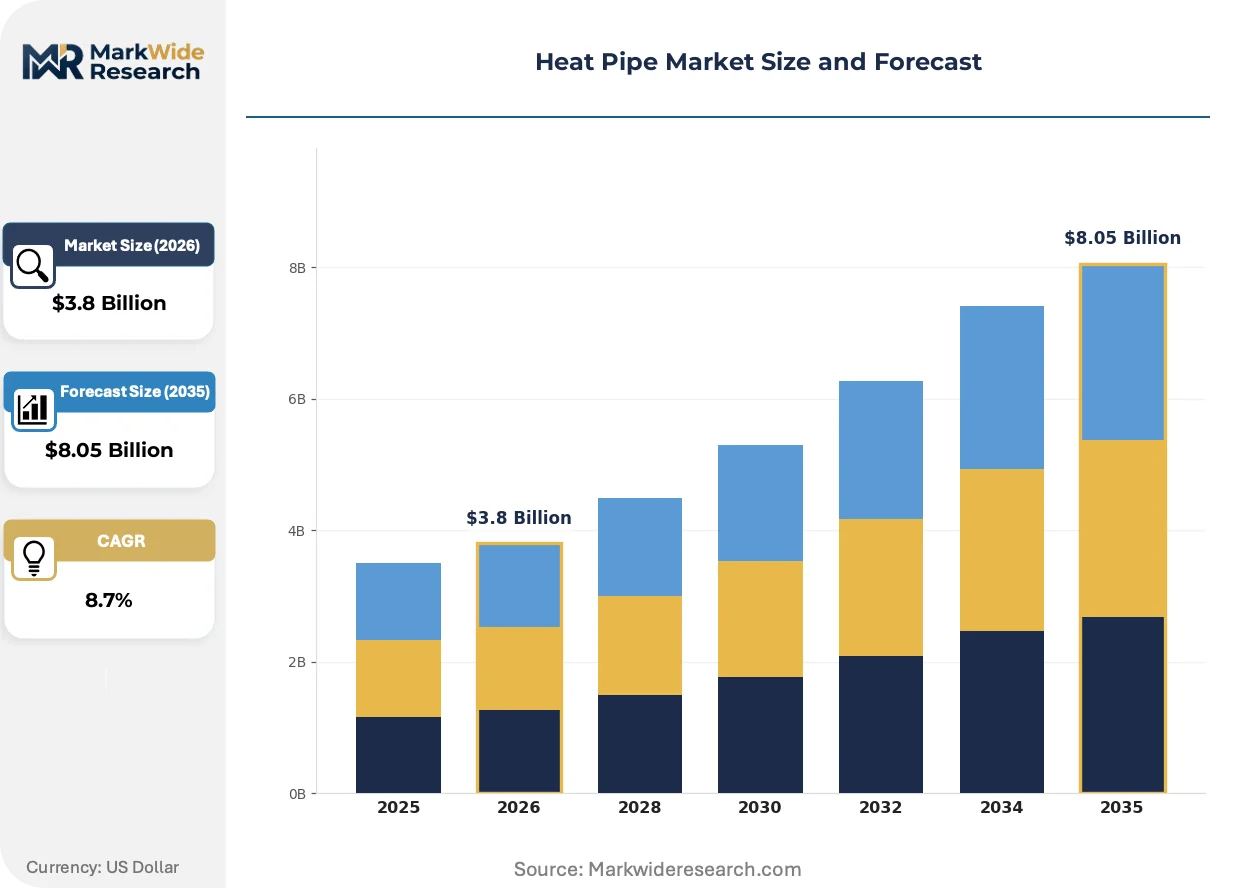
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vapor Chamber, Rectangular Heat Pipe, Flat Heat Pipe, Cylindrical Heat Pipe Application: Electronics Cooling, Aerospace, Renewable Energy, HVAC Systems End User: Telecommunications, Consumer Electronics, Automotive, Industrial Equipment Material: Copper, Aluminum, Stainless Steel, Composite Materials |
| Companies Covered | Furukawa Electric, Boyd, Wakefield Thermal, Inc., HEAT PIPE TECHNOLOGY, INC., Acrolab Ltd., Thermavant Technologies, LLC, Fujikura, TaiSol Electronics, ADVANCED COOLING TECHNOLOGIES, INC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Pipe Market Emerging Trajectories
Thermal management architectures are bifurcating between ultra-thin vapor chambers for consumer electronics and high-reliability loop heat pipes for satellite and defense applications.
Flat vapor chamber geometries with axial grooved wicks are electrifying thermal design options for foldable smartphones and ultrabook computers where z-height constraints preclude cylindrical heat pipes. Samsung and Apple suppliers now specify sub-2mm vapor chambers for flagship device thermal management. This form factor expansion is compressing the addressable market for traditional cylindrical heat pipes in premium consumer electronics.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants with high global warming potential, restricting working fluid selections for heat pipes deployed in European data centers and industrial equipment. Manufacturers are qualifying ammonia, propane, and hydrofluoroolefin alternatives with compatible envelope materials. Heat pipe suppliers serving European telecommunications infrastructure must requalify product lines or face market exclusion.
Hyperscale data center operators are consolidating thermal subsystem procurement under direct OEM relationships, bypassing traditional distributor channels for heat pipe and vapor chamber assemblies. Meta and Microsoft now specify thermal module performance envelopes directly to Taiwanese and Chinese fabricators. This channel compression is most visible in Singapore and Ireland colocation markets where operator concentration enables volume aggregation.
Heat Pipe Market Segmentation
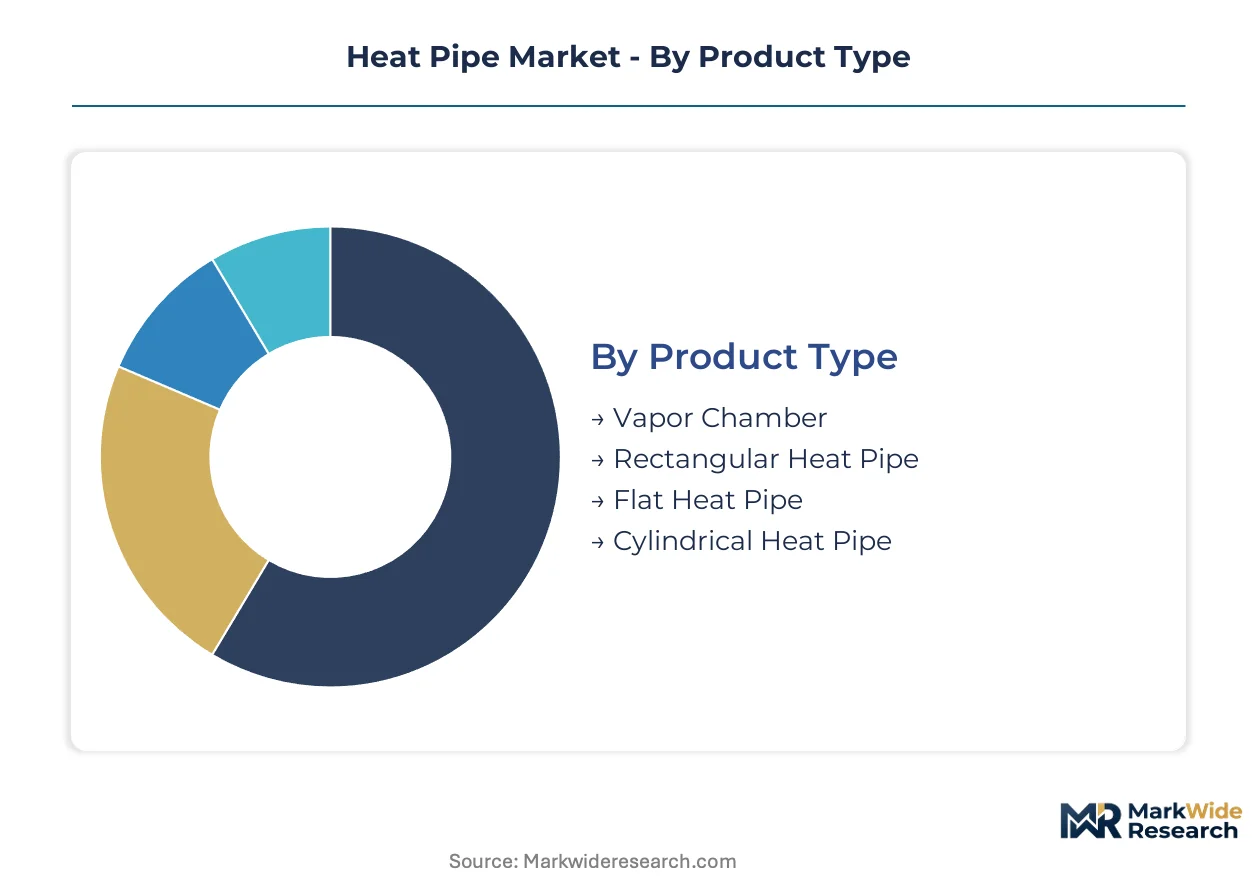
Heat pipe market segmentation reveals distinct performance tiers across form factors and material grades, with copper-based vapor chambers commanding premium positioning while aluminum alternatives serve cost-sensitive volume applications. Understanding these stratifications enables suppliers to align thermal conductivity specifications against end-use power density requirements and regional regulatory constraints.
Product Type:
Volume deployment favors established cylindrical geometries, while premium capture concentrates in ultra-thin vapor chambers where z-axis constraints dominate thermal design.
- Vapor Chamber:Flat, planar two-phase spreaders utilizing axial grooved or mesh wick structures to distribute heat across large surface areas in GPUs and smartphone chipsets. Demand concentrates in Taiwanese and Chinese manufacturing clusters serving Meta and Microsoft data center specifications, where sub-2mm profiles enable foldable device thermal management.
- Cylindrical Heat Pipe:Traditional sealed tubes with sintered copper powder wicks transporting heat along linear paths in telecommunications base stations and industrial equipment. Deployment remains anchored in Japanese and South Korean precision extrusion facilities supplying NTT and SK Telecom infrastructure rollouts.
- Rectangular Heat Pipe:Profiled extrusions conforming to tight geometric constraints in automotive battery packs and avionics enclosures. Aerospace contractors in France and Germany specify these for satellite thermal control systems.
- Flat Heat Pipe:Low-profile variants bridging the gap between cylindrical tubes and full vapor chambers in ultrabook computers and medical imaging equipment. German and US automotive Tier 1s integrate these for LED headlight thermal management.
Mature deployment sits with Cylindrical Heat Pipe. Newer deployment is concentrated in Vapor Chamber.
Application:
End-use diversification spans power electronics density escalation and passive thermal management requirements in harsh environments.
- Electronics Cooling:Dominant value capture segment addressing AI accelerator junction temperatures exceeding thermal design power envelopes in hyperscale data centers. NVIDIA and AMD reference designs now mandate two-phase cooling for training clusters surpassing 700W per socket.
- Renewable Energy:Concentrated solar power parabolic trough receivers and geothermal binary cycle plants in Spain, Saudi Arabia, and Kenya utilize heat pipe heat exchangers for reliable passive operation without pump maintenance.
- Aerospace:Loop heat pipe configurations and high-reliability grooved wick designs manage satellite payload thermal cycling under launch vibration and orbital microgravity conditions.
- HVAC Systems:Building heat recovery and dehumidification applications in Japanese commercial construction leverage METI efficiency rebate programs for JIS-certified installations.
Electronics Cooling anchors current revenue concentration. Renewable Energy is climbing the fastest as CSP and geothermal deployments scale.
End User:
Procurement authority is shifting from distributor networks toward direct OEM relationships with Taiwanese and Chinese fabricators.
- Telecommunications:5G base station deployments by Ericsson, Nokia, and Huawei suppliers require corrosion-resistant heat pipes for outdoor enclosures across varied climate zones.
- Consumer Electronics:Samsung and Apple supply chains specify vapor chamber performance envelopes directly, compressing traditional channel margins.
- Automotive:Battery thermal management and power electronics cooling in electric vehicle platforms from BYD, Tesla, and Volkswagen integrate flat heat pipe assemblies.
- Industrial Equipment:Semiconductor manufacturing furnaces and machine tool thermal stabilization in Japan qualify for METI rebate programs.
Procurement concentration sits with Consumer Electronics. Industrial Equipment is gaining share fastest through efficiency incentive programs.
Material:
Copper grade selection differentiates performance tiers, with oxygen-free high-conductivity variants reserved for aerospace and defense qualification.
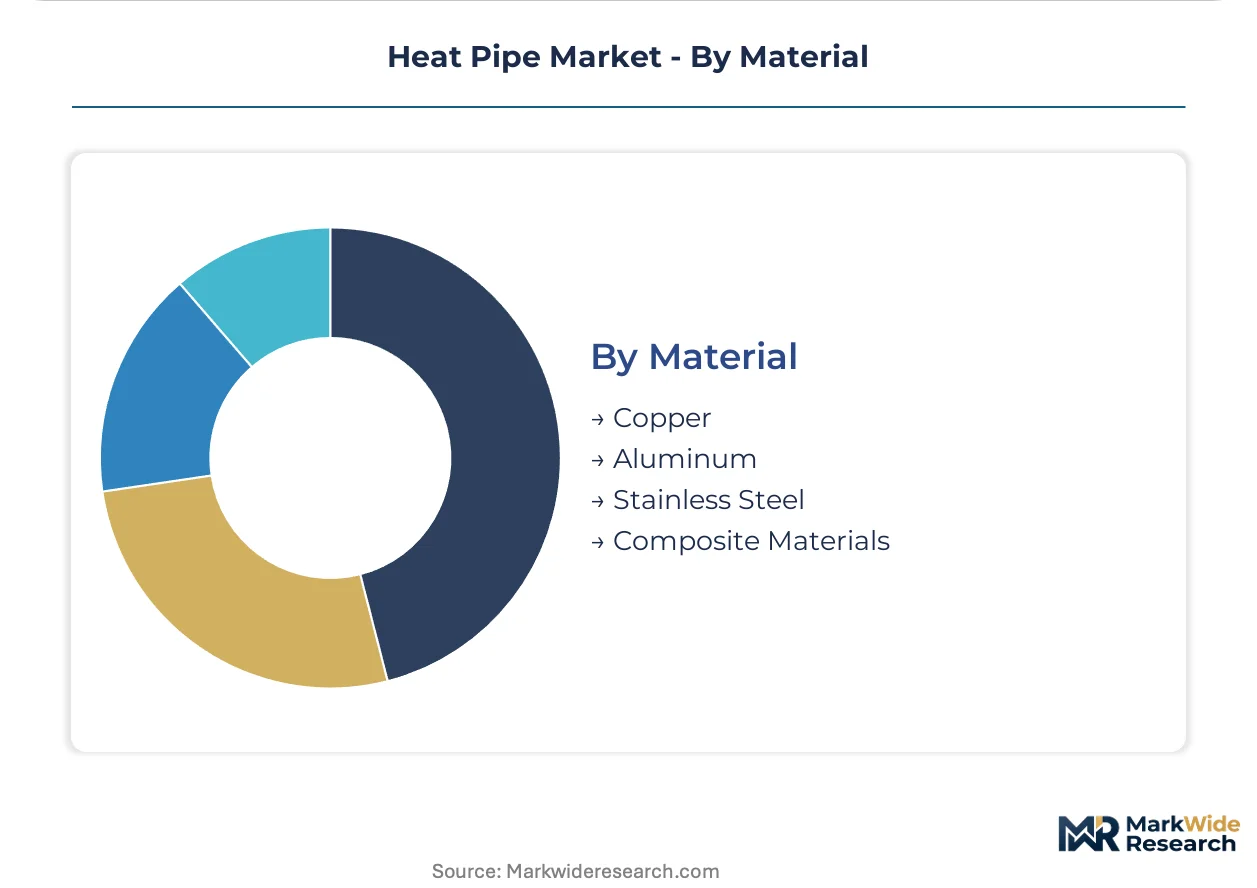
- Copper:Primary envelope material for high-performance applications, with C11000 and C10200 grades specified based on thermal conductivity requirements and hermetic seal reliability. China's MIIT GB standards mandate copper solutions for certified electronics cooling compliance.
- Aluminum:Lower-density alternative for weight-constrained automotive and portable electronics applications, though thermal performance limitations restrict deployment in power-dense AI accelerators.
- Stainless Steel:Corrosion-resistant envelopes for ammonia working fluids in geothermal and industrial process heat applications.
- Composite Materials:Titanium-copper bimetallic constructions and polymer-lined envelopes addressing specialized chemical compatibility requirements.
Volume concentration sits with Aluminum. Premium positioning is concentrating in Copper as efficiency mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian manufacturing clusters where precision copper extrusion and sintered powder metallurgy capabilities serve electronics cooling requirements. China's MIIT mandates and Japan's METI rebate programs accelerate high-performance thermal management adoption. Regulatory divergence between Asian efficiency standards and European material restrictions shapes regional product configurations.
China
Data center construction by Alibaba, Tencent, and ByteDance drives vapor chamber procurement for AI training infrastructure. MIIT GB standards mandate certified thermal management compliance testing for electronic products, displacing aluminum solutions with copper heat pipes. Shenzhen and Dongguan manufacturing clusters host precision wick fabrication facilities serving domestic hyperscale operators.
Japan
Semiconductor manufacturing equipment and industrial furnace sectors qualify for METI efficiency rebate programs subsidizing JIS-certified heat pipe integration. Furukawa Electric anchors captive smelting and precision extrusion capabilities in domestic facilities. Nagoya and Osaka industrial corridors concentrate aerospace-grade copper tubing production for regional electronics supply chains.
South Korea
Samsung Electronics and SK Hynix specify vapor chamber performance envelopes directly for smartphone and memory module thermal management. National industrial policy supports precision manufacturing clusters in Suwon and Pyeongtaek. Domestic fabricators supply 5G base station deployments by SK Telecom with corrosion-resistant cylindrical heat pipe assemblies.
United States
Hyperscale data center operators Meta and Microsoft consolidate thermal subsystem procurement under direct OEM relationships with Taiwanese fabricators. EPA energy efficiency guidelines and state-level data center sustainability mandates influence material selection criteria. Phoenix and Northern Virginia colocation markets exhibit operator concentration enabling volume aggregation for two-phase cooling modules.
Germany
Automotive battery thermal management and industrial heat recovery applications drive flat heat pipe integration in electric vehicle platforms from Volkswagen and BMW. ECHA REACH substance authorization requirements constrain working fluid selections for European-bound products. Bavarian and Baden-Württemberg manufacturing regions host aerospace contractors specifying rectangular heat pipes for satellite thermal control systems.
Heat Pipe Market Vendor Landscape
Capacity expansion dominates the current landscape as fabricators scale precision extrusion and wick metallurgy capabilities to match AI accelerator thermal requirements. The vendor base stratifies across three tiers: integrated thermal subsystem designers, specialized copper envelope manufacturers, and regional fabricators serving telecommunications infrastructure. Two strategic archetypes predominate: vertically integrated specialists controlling captive copper supply chains, and design-focused integrators bundling heat pipes into complete cooling modules. Geographic expansion and technology licensing represent the primary competitive vectors as suppliers establish qualification relationships with hyperscale data center operators.
Among Japanese precision manufacturers, Furukawa Electric and Fujikura exemplify distinct positioning archetypes within the premium tier. Furukawa Electric represents the captive supply chain model through integrated smelting and extrusion capabilities. Fujikura occupies a specialization position via vapor chamber geometries tailored to consumer electronics form factors. Boyd, a US-based thermal solutions integrator, anchors the subsystem design tier by bundling heat pipe assemblies into complete aerospace and defense cooling modules. These three companies illustrate how competitive positioning splits between material-grade control and thermal architecture integration.
| Leading Market Players |
|---|
| Furukawa Electric |
| Boyd |
| Wakefield Thermal, Inc. |
| HEAT PIPE TECHNOLOGY, INC. |
| Acrolab Ltd. |
| Thermavant Technologies, LLC |
| Fujikura |
| TaiSol Electronics |
| ADVANCED COOLING TECHNOLOGIES, INC. |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange copper futures cascade through heat pipe manufacturing economics, compressing margins on fixed-price telecommunications contracts while rewarding fabricators with captive smelting capabilities. The commodity volatility splits pricing power between integrated specialists controlling upstream copper supply and modular assemblers exposed to spot market swings.
Pricing Analysis
Volume deployment in aluminum cylindrical heat pipes runs on thin margins serving cost-sensitive telecommunications infrastructure, while copper vapor chambers for AI accelerators capture premium positioning through JIS certification and direct OEM relationships. Three-tier pricing structure separates aerospace-grade oxygen-free copper from commercial electronics grades and commodity aluminum alternatives. Pricing pressure stems from hyperscale data center procurement consolidation bypassing distributor markups. Telecommunications infrastructure buyers exhibit highest price sensitivity due to multi-year fixed contracts, whereas aerospace contractors accept elevated pricing for hermetic seal certification and accelerated life validation.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Nagoya, and Suwon operate hub-and-spoke patterns feeding precision wick fabrication to Taiwanese and Chinese module assemblers. Supply concentrates in Japan, South Korea, and Taiwan for aerospace-grade copper tubing and sintered powder metallurgy. Raw material dependencies center on LME copper cathodes, high-purity ammonia working fluids, and specialty nickel-alloy wick substrates. Single-source vulnerability looms in precision extrusion capabilities for sub-2mm vapor chamber profiles. Distribution runs through direct OEM relationships with Meta and Microsoft specifications bypassing traditional channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pipe supply chains face acute constraints in precision wick fabrication capacity, propping pricing power for qualified fabricators serving AI accelerator thermal requirements. Sintered powder metallurgy bottlenecks limit rapid scaling despite demand escalation from hyperscale data centers.
For Market Incumbents: Hedge copper price exposure through long-term offtake agreements with Japanese and Chilean smelters while accelerating JIS certification investments for METI rebate eligibility. Defensive consolidation should prioritize captive extrusion capabilities in Taiwan and South Korea to counter emerging Chinese competitors. Vertical integration into high-purity ammonia working fluid sourcing mitigates EU F-Gas Regulation compliance risks. For New Entrants and Emerging Players: Specialized loop heat pipe geometries for satellite thermal control offer a technology-first wedge into aerospace applications underserved by commercial electronics-focused incumbents. White-space targets include geothermal binary cycle installations in Indonesia and Kenya requiring corrosion-resistant stainless steel envelopes. Direct qualification relationships with concentrated solar power EPC contractors in Spain and Saudi Arabia provide channel access bypassing established data center procurement networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Japanese precision manufacturers with dormant aerospace certifications in Nagoya and Osaka industrial corridors. Long-term viability hinges on positioning for satellite constellation deployment and defense thermal management modernization. Monitor helium mass spectrometry leak testing backlog durations as inflection indicator for qualification bottleneck intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | Furukawa Electric's captive supply anchors pricing power against LME volatility. |
| JIS Certification Investment | METI rebate eligibility unlocks Japanese industrial furnace and semiconductor equipment demand. |
| Direct OEM Relationship Establishment | Meta and Microsoft procurement consolidation rewards qualified Taiwanese fabricators with volume commitments. |
| Alternative Working Fluid Qualification | Ammonia and hydrofluoroolefin compatibility ensures EU F-Gas Regulation compliance for European-bound products. |
| Precision Wick Fabrication Scale-Up | Sintered powder metallurgy capacity expansion addresses AI accelerator vapor chamber supply constraints. |
Methodological Framework
SEC 10-K filings, customs trade databases, and MIIT GB standard certification records formed the secondary backbone, supplemented by hyperscaler capex disclosures and ECHA REACH substance authorization tracking. Primary interviews engaged thermal subsystem design engineers at aerospace contractors, procurement leads at telecommunications OEMs, and plant managers at precision copper extrusion facilities across Japan, South Korea, and Taiwan. Bottom-up triangulation across fabricator capacity announcements and top-down validation against end-use equipment shipment data anchored volume estimates.
Historical trendline analysis of cylindrical heat pipe and vapor chamber deployment patterns informed segmentation-level growth trajectories across the projection horizon. The analytical framework modeled product type, application, material grade, and regional regulatory cluster dimensions. CAGRs derived from equipment power density escalation curves and efficiency mandate compliance timelines. Forecast inputs incorporated GPU thermal design power envelopes from NVIDIA and AMD reference designs and METI rebate program budget allocations.
Several conditions sit outside the modeled scope, including potential relaxation of China's dual carbon goals, breakthroughs in active liquid cooling substitution, and geopolitical disruption of Taiwanese manufacturing operations. Forecasts reflect documented assumptions regarding copper price stability and qualification timeline continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Solar Fan Market