
 Asia-Pacific Thermal Power Plant Market | 2026-2036
Asia-Pacific Thermal Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermal Power Plant Market Outlook
Ultra-supercritical steam cycles are reshaping turbine procurement specifications across the Asia-Pacific Thermal Power Plant Market. NTPC Limited leverages its integrated engineering division to design 660 MW and 800 MW units with operating temperatures above 600°C. China Huaneng Group sustains the region's largest ultra-supercritical fleet through continuous boiler tube metallurgy upgrades. Korea Electric Power Corporation anchors South Korean export competitiveness by supplying turbine islands to Vietnamese and Indonesian developers.
Thermal power plants convert fossil or biomass fuels into electricity through steam-driven turbine generators, with modern ultra-supercritical units achieving thermal efficiencies above 45% through steam pressures exceeding 300 bar and temperatures surpassing 600°C. Coal technology dominates installed capacity across the Asia-Pacific Thermal Power Plant Market while natural gas capacity expands fastest in Bangladesh, Myanmar, and Vietnam where LNG import terminals reduce supply uncertainty. The above 1000 MW capacity segment concentrates capital deployment and engineering margins, whereas the 101 MW to 500 MW band attracts independent power producers seeking faster permitting timelines.
China's MIIT enforces GB standard efficiency floors that decommission subcritical units below 300 MW, while India's CEA mandates flue-gas desulfurization retrofit deadlines that redirect capital toward pollution control equipment. Japan's METI governs thermal efficiency benchmarks through its Top Runner program, pressuring Chubu Electric and Tokyo Electric to accelerate turbine replacements. Stakeholders must monitor how carbon border adjustment mechanisms in export destination markets reshape the cost calculus for new coal-fired investment across the region.
Market Dynamics
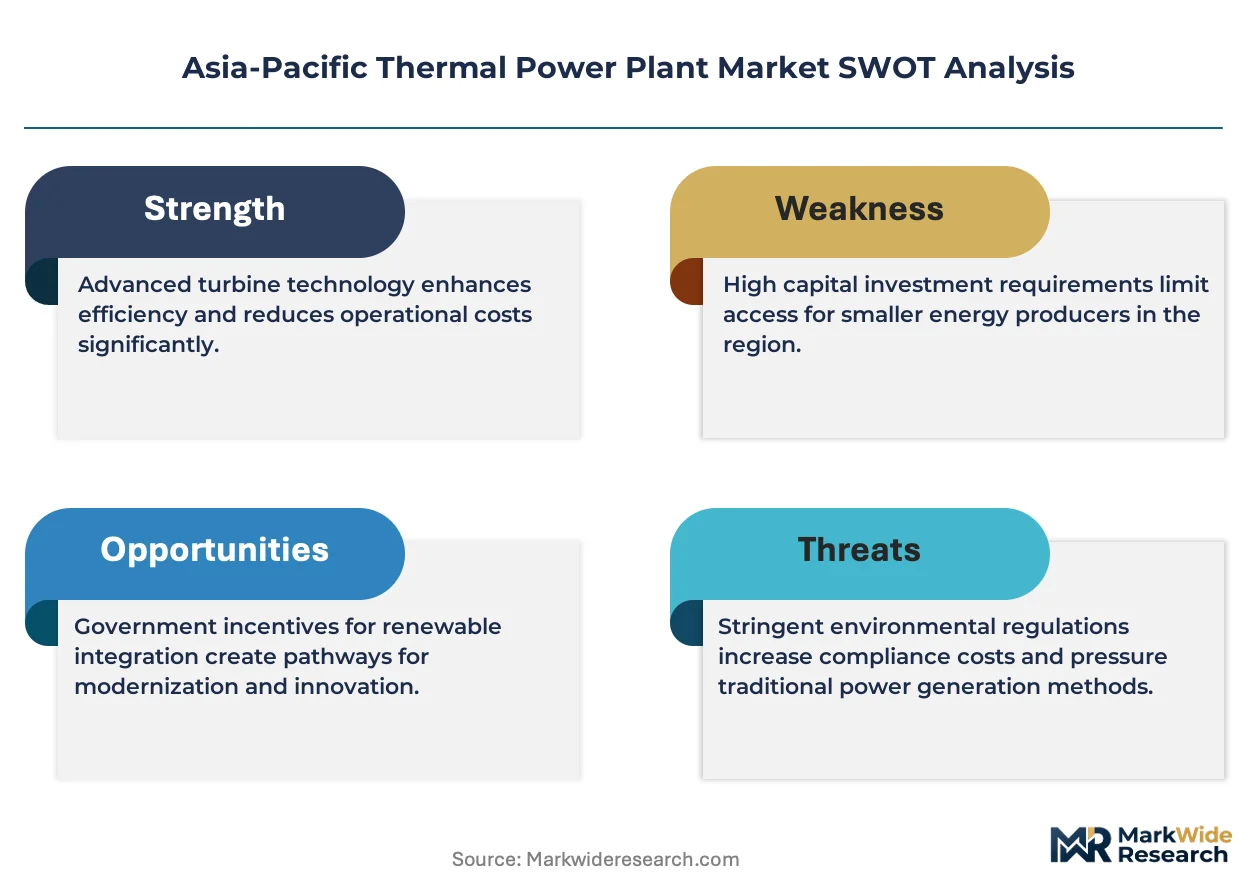
China's MIIT-mandated efficiency standards are forcing a wholesale turbine upgrade cycle across provincial coal fleets, while India's CEA pollution control deadlines redirect capital toward flue-gas desulfurization retrofits. These dual regulatory pressures are compressing procurement timelines and reshaping vendor qualification criteria across the region.
Growth Catalysts
- Ultra-supercritical turbine deployment:Steam temperatures exceeding 600°C and pressures above 300 bar are raising thermal efficiency floors. Provincial utilities in China must comply with MIIT decommissioning orders for subcritical units below 300 MW.
- LNG terminal infrastructure:Bangladesh, Myanmar, and Vietnam are reducing gas supply uncertainty through floating storage regasification units. Natural gas capacity additions accelerate where import terminals anchor fuel security.
- Grid electrification mandates:Southeast Asian utilities are expanding baseload procurement to serve industrial load growth. Maharashtra and Gujarat host India's largest pipeline of new thermal capacity.
Market Restraints
- Boiler tube metallurgy costs:Advanced nickel alloys required for 600°C+ steam conditions face supply concentration from specialized European and Japanese foundries. Input cost volatility constrains project economics.
- Carbon border adjustment exposure:Export destination markets in Europe are implementing embodied carbon tariffs. New coal-fired investment faces stranded asset risk from cross-border compliance costs.
- Flue-gas desulfurization retrofit backlog:India's CEA deadlines have created equipment procurement bottlenecks. Engineering resources concentrate on pollution control rather than greenfield generation.
Strategic Opportunities
- Indonesian IPP market liberalization:Independent power producers are securing faster permitting timelines in the 101 MW to 500 MW band. This segment attracts developers seeking compressed regulatory cycles.
- Biomass co-firing retrofits:Existing coal units are integrating agricultural waste and palm kernel shells to reduce carbon intensity. Feedstock supply chains in Malaysia and Thailand support this convergence.
- Korean turbine island exports:Korea Electric Power Corporation is supplying complete turbine-generator packages to Vietnamese and Indonesian developers. Engineering margins concentrate in above-1000 MW turnkey contracts.
Industry Challenges
- Ultra-supercritical welding certification:Specialized pressure vessel qualifications for advanced austenitic steels face limited inspector availability. Project timelines extend where certified welders are scarce.
- Legacy control system integration:Digital turbine governors must interface with analog legacy protection schemes. Commissioning delays accumulate where plant automation spans multiple technology generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermal Power Plant Market |
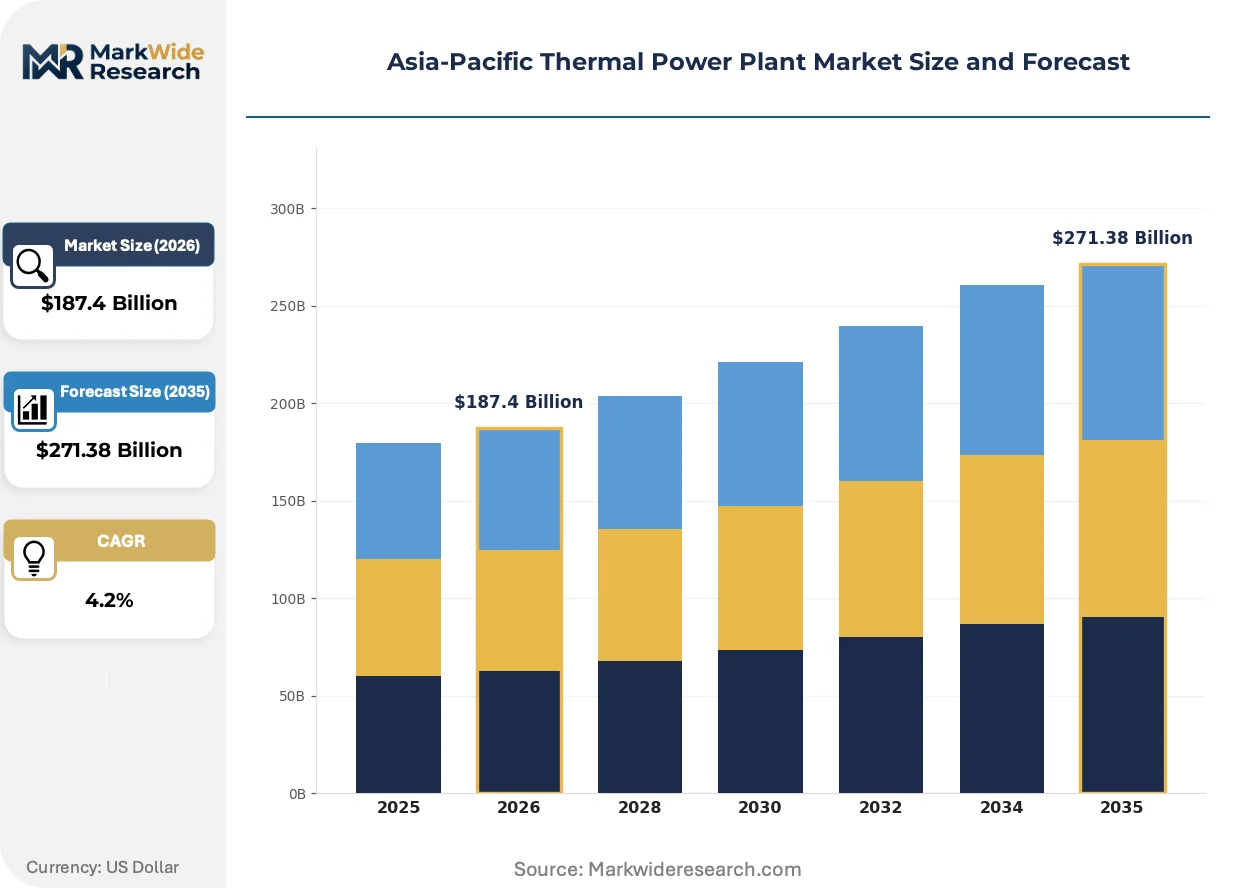
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Coal, Natural Gas, Biomass, Oil Capacity: Up to 100 MW, 101 MW to 500 MW, 501 MW to 1000 MW, Above 1000 MW Application: Base Load, Peak Load, Intermediate Load, Industrial Use End User: Utilities, Independent Power Producers, Government, Private Sector |
| Companies Covered | NTPC Limited, China Huaneng Group Co., Ltd., Datang International Power Generation Company Limited, China Energy Engineering Corporation, Tokyo Electric Power Company Holdings, Inc., Korea Electric Power Corporation, Tata Power Company Ltd, Chubu Electric Power Co., Inc., Tenaga Nasional Berhad, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermal Power Plant Market Strategic Shifts
Steam cycle technology is advancing through materials science breakthroughs and digital integration, while regulatory frameworks harden efficiency and emissions benchmarks. Procurement patterns are shifting toward performance-guaranteed turnkey contracts.
Advanced nickel-based superalloys are enabling steam temperatures approaching 620°C in next-generation ultra-supercritical designs. Chinese provincial utilities are specifying these materials for 660 MW and 800 MW greenfield units. Higher thermal efficiency is hybridizing with carbon capture readiness to extend coal asset viability under tightening emissions regimes.
Japan's METI Top Runner program governs thermal efficiency benchmarks through mandatory equipment replacement cycles. Chubu Electric and Tokyo Electric are accelerating turbine replacements to maintain compliance. The policy compresses capital deployment timelines for above-500 MW baseload units.
Performance-based procurement is displacing component-level tendering across Southeast Asian IPP markets. Developers are bundulating engineering-procurement-construction risk with long-term heat rate guarantees. Vietnam and Indonesia exhibit the strongest migration toward outcome-contracting for turbine islands.
Asia-Pacific Thermal Power Plant Market Segmentation
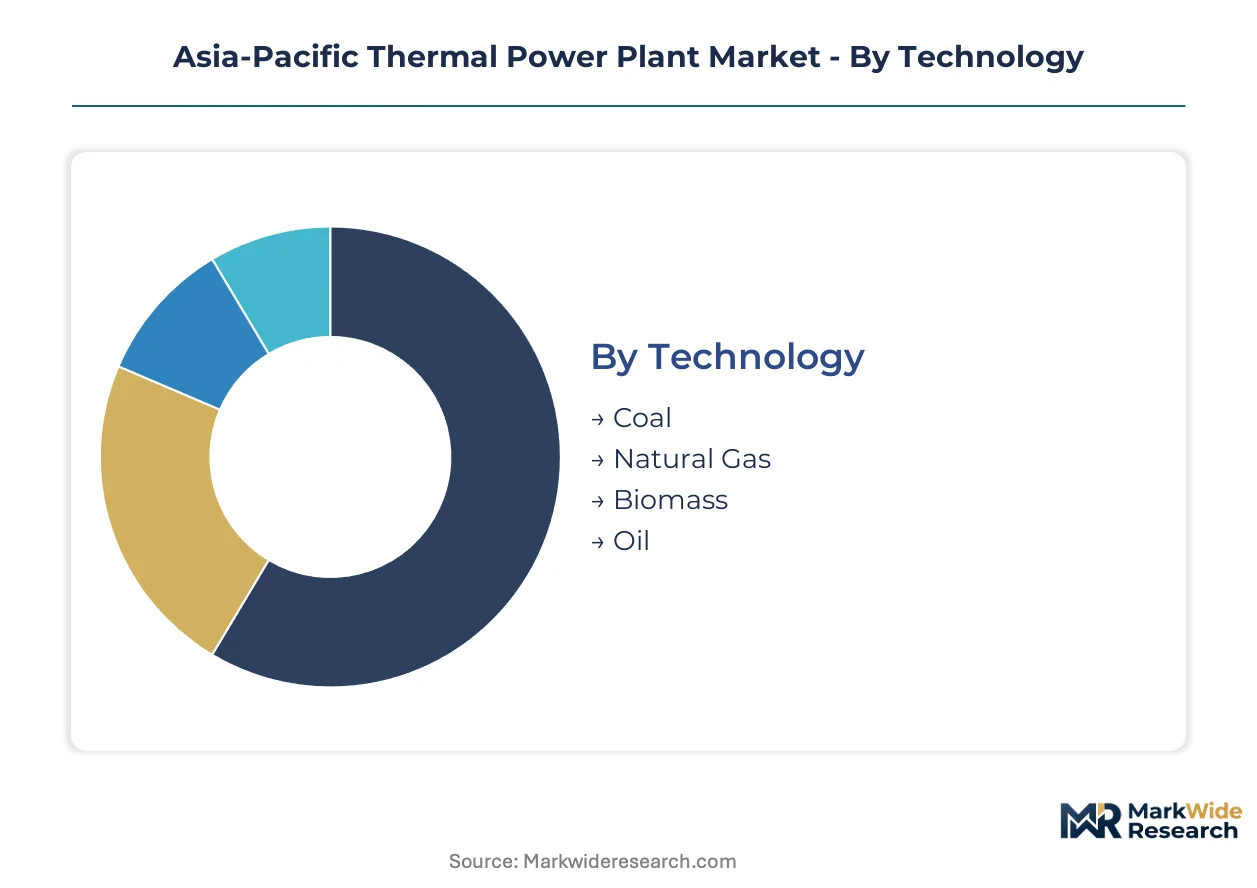
Technology choices and capacity sizing determine capital intensity, fuel procurement strategy, and regulatory exposure across the Asia-Pacific Thermal Power Plant Market. Procurement patterns diverge sharply between state-backed utilities seeking scale economies and independent developers prioritizing permitting velocity.
Technology:
Mature steam cycle designs coexist with emerging fuel-switching configurations as efficiency mandates harden across the region.
- Coal:Ultra-supercritical units dominate newbuild specifications with steam temperatures exceeding 600°C and pressures above 300 bar. China's MIIT mandates decommission subcritical units below 300 MW, compressing upgrade timelines across Shandong and Shanxi provincial fleets.
- Natural Gas:Combined-cycle configurations anchor capacity additions in Bangladesh, Myanmar, and Vietnam where floating storage regasification units reduce supply uncertainty. LNG terminal infrastructure determines project viability more than turbine technology selection.
- Biomass:Agricultural waste and palm kernel shell co-firing retrofits gain traction in Malaysia and Thailand. Feedstock supply chain reliability constrains dispatch factors below baseload thresholds.
- Oil:Diesel and fuel oil units persist in islanded grids and emergency peaking roles across Indonesia's eastern archipelago. High fuel cost volatility limits economics to reliability-critical applications.
Coal retains volume leadership through fleet scale in China and India; natural gas holds the steepest expansion curve where LNG infrastructure matures.
Capacity:
Engineering margins and permitting complexity stratify sharply across the megawatt spectrum, with scale thresholds determining developer type and financing structure.
- Up to 100 MW:Captive industrial plants and rural electrification projects concentrate in India's distributed generation schemes. Compressed regulatory cycles attract private capital despite higher per-kW capital costs.
- 101 MW to 500 MW:Independent power producers dominate this band across Indonesian market liberalization. Faster permitting timelines offset heat rate penalties versus larger units.
- 501 MW to 1000 MW:Provincial utilities in China's central provinces specify this scale for grid stability without ultra-supercritical metallurgy premiums. NTPC Limited deploys similar sizing for flexibility reserves.
- Above 1000 MW:Ultra-supercritical flagship projects concentrate engineering margins and long-term service contracts. Korea Electric Power Corporation anchors export competitiveness through turnkey turbine island supply.
Above 1000 MW units capture the dominant share of capital deployment; the 101 MW to 500 MW band is expanding most quickly as IPP market structures liberalize.
Application:
Grid role definitions shape equipment specification, with duty cycles determining maintenance intervals and fuel procurement contracting structures.
- Base Load:Continuous operation above 7000 annual hours demands ultra-supercritical efficiency and integrated pollution control. Maharashtra and Gujarat utilities specify this duty for new coal and gas units.
- Peak Load:Rapid start capability and cycling tolerance define competitive positioning. Open-cycle gas turbines serve this role where grid storage penetration remains limited.
- Intermediate Load:Daily cycling between 3000-5000 hours requires flexible boiler designs. Combined-cycle units with duct firing dominate this segment in Vietnam's evolving power market.
- Industrial Use:Captive power for cement, steel, and petrochemical complexes operates behind-the-meter. Cogeneration configurations improve project economics through steam offtake.
Base load applications command the largest installed capacity; industrial use is gaining share fastest as manufacturing electrification accelerates.
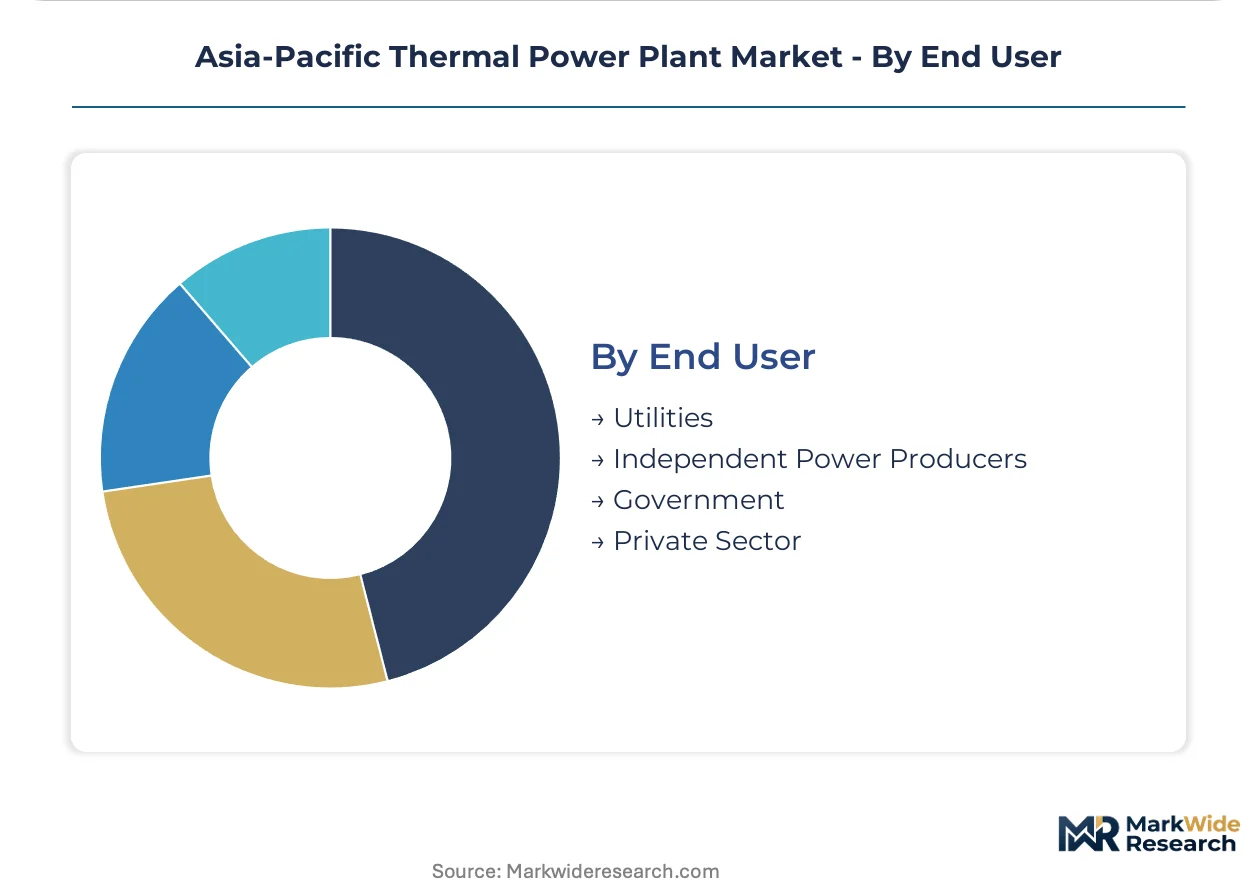
End User:
Ownership structure determines risk allocation, with public sector balance sheets absorbing construction risk that private capital avoids.
- Utilities:State-owned generators in China, India, and Vietnam deploy sovereign financing for above-500 MW projects. China's Big Five power groups and India's NTPC Limited anchor regional procurement volume.
- Independent Power Producers:Merchant and contracted developers exploit faster permitting in Indonesia's liberalized segments. Power purchase agreement tenor and offtaker credit quality determine bankability.
- Government:Direct state procurement persists for strategic reserves and rural electrification mandates. Ministries of Power specify technology and fuel type through central planning mechanisms.
- Private Sector:Industrial conglomerates and commercial real estate developers build captive capacity where grid reliability fails. Financing relies on corporate balance sheets rather than project structures.
Utilities retain volume leadership through fleet scale; independent power producers hold the steepest expansion curve as Southeast Asian markets liberalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean turbine island exports flow to Vietnamese and Indonesian developers, while Chinese ultra-supercritical technology anchors domestic fleet upgrades. Japan's METI efficiency mandates compress replacement cycles across utility portfolios. Australian grid operators source peaking capacity from open-cycle gas turbines as renewable penetration rises.
China
Provincial utilities in Shandong and Shanxi face MIIT-mandated decommissioning deadlines for subcritical units below 300 MW. The country's GB standard efficiency floors force wholesale turbine upgrade cycles across coal-dependent central provinces. Yangtze River Delta manufacturing clusters supply advanced nickel alloy boiler tubes for 660 MW and 800 MW ultra-supercritical specifications.
India
Maharashtra and Gujarat host the largest pipeline of new coal and gas-fired capacity additions serving industrial load growth. The CEA mandates flue-gas desulfurization retrofit deadlines that redirect capital toward pollution control equipment. Western state utilities anchor baseload procurement as grid electrification accelerates across rural distribution networks.
Japan
Chubu Electric and Tokyo Electric accelerate turbine replacements to maintain METI Top Runner program compliance. The country's thermal efficiency benchmarks govern mandatory equipment replacement cycles for above-500 MW baseload units. Kansai and Chubu regional utilities concentrate engineering procurement for combined-cycle upgrades.
Vietnam
LNG import terminals through floating storage regasification units reduce gas supply uncertainty for combined-cycle developers. Power purchase agreement structures migrate toward performance-guaranteed turnkey contracts with long-term heat rate guarantees. Southern industrial zones anchor capacity additions as manufacturing electrification accelerates.
South Korea
Korea Electric Power Corporation supplies complete turbine-generator packages to Vietnamese and Indonesian developers through export-oriented engineering divisions. The Seoul Capital Area concentrates engineering margins in above-1000 MW turnkey contracts. Domestic ultra-supercritical fleet maintenance sustains specialized welding certification capacity.
Asia-Pacific Thermal Power Plant Market Competitive Environment
On the supply side, the industry is consolidating around state-backed utilities with captive engineering divisions and specialized turbine island exporters. China's Big Five power groups and India's NTPC Limited anchor procurement volume through sovereign financing structures. Two strategic archetypes dominate: vertically integrated national champions with in-house design capabilities, and export-focused engineering conglomerates supplying turnkey packages. Competitive intensity centers on heat rate guarantees and long-term service contracting rather than component pricing alone.
Within the national champion tier, NTPC Limited and China Huaneng Group Co., Ltd. exemplify integrated engineering divisions designing proprietary ultra-supercritical specifications. Korea Electric Power Corporation occupies a distinct position as the region's largest turbine island exporter, supplying Vietnamese and Indonesian independent power producers. Tata Power Company Ltd. represents the independent utility archetype navigating India's pollution control retrofit cycle. Tokyo Electric Power Company Holdings, Inc. and Chubu Electric Power Co., Inc. anchor Japanese replacement demand under METI efficiency mandates. Datang International Power Generation Company Limited and China Energy Engineering Corporation sit within Chinese provincial upgrade procurement flows. Tenaga Nasional Berhad exemplifies Southeast Asian utility procurement liberalization.
| Leading Market Players |
|---|
| NTPC Limited |
| China Huaneng Group Co., Ltd. |
| Datang International Power Generation Company Limited |
| China Energy Engineering Corporation |
| Tokyo Electric Power Company Holdings, Inc. |
| Korea Electric Power Corporation |
| Tata Power Company Ltd |
| Chubu Electric Power Co., Inc. |
| Tenaga Nasional Berhad |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam container corridor carries advanced nickel alloy boiler tubes from Yangtze River Delta foundries to European turbine manufacturers, with freight cost volatility amplifying the pricing power of specialized metallurgy suppliers while compressing margins for engineering-procurement-construction contractors bidding fixed-price turnkey contracts.
Pricing Analysis
Subcritical-to-supercritical upgrade pricing spans three distinct technology tiers, with ultra-supercritical units commanding metallurgy premiums driven by advanced austenitic steel specifications. Price differentiation centers on heat rate guarantee thresholds and long-term service contract bundling, with state-backed utilities showing lowest price sensitivity due to sovereign financing access. Cost compression in the 101 MW to 500 MW band is intensifying as Indonesian IPP market liberalization attracts merchant developers seeking faster permitting timelines.
Supply Chain Analysis
Specialized foundry capacity concentrates in Germany, Japan, and select Chinese coastal provinces for advanced nickel-based superalloys required in 600°C+ steam conditions. Raw material procurement draws from Indonesian nickel ore, Australian coking coal, and Qatari LNG feedstocks. Single-source vulnerability in boiler tube metallurgy creates procurement bottlenecks where certified welding inspector availability constrains project timelines. Distribution runs through EPC-led turnkey contracting with heat rate performance guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital turbine governors must interoperate with legacy analog protection schemes, creating ecosystem lock-in for vendors controlling both control system architectures and long-term service protocols.
For Market Incumbents: Pre-empt emerging IPP entrants in Vietnam and Indonesia by securing exclusive turbine island service contracts before market liberalization accelerates. Anchor backward integration into boiler tube metallurgy supply to offset European and Japanese foundry pricing power. Prioritize welding certification capacity expansion where inspector scarcity extends commissioning timelines.
For New Entrants and Emerging Players: Myanmar's gas-fired capacity gap offers the most penetrable geographic entry point where LNG terminal infrastructure reduces fuel supply uncertainty for combined-cycle developers. Target the 101 MW to 500 MW permitting-fast-track segment with modular turbine-generator packages. Pursue joint-venture structures with Korean engineering firms to access Vietnamese power purchase agreement pipelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors engineering-procurement-construction contractors with captive ultra-supercritical design capabilities and established service contract backlogs. Long-term viability hinges on carbon capture readiness integration extending coal asset viability under tightening emissions regimes. Monitor carbon border adjustment mechanism implementation in European export destinations as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Supercritical Technology Licensing | Chinese provincial utilities leverage GB standard mandates to decommission subcritical units below 300 MW. |
| LNG Terminal Joint Development | Bangladesh and Vietnamese developers reduce gas supply uncertainty through floating storage regasification units. |
| Flue-Gas Desulfurization Retrofit Capacity | Indian CEA deadlines redirect capital toward pollution control equipment across western state fleets. |
| Biomass Co-Firing Feedstock Integration | Malaysian and Thai agricultural waste supply chains enable carbon intensity reduction in existing coal units. |
| Digital Turbine Governor Deployment | Chubu Electric and Tokyo Electric accelerate replacements under METI Top Runner efficiency benchmarks. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, grid operators, and fuel supply specialists. Secondary validation drew from EIA generation statistics, IEA power market reports, FERC infrastructure filings, and regional project development databases. Bottom-up capacity addition tracking was triangulated against top-down regulatory mandate analysis.
Calibration against historical deployment patterns and announced project pipelines anchored the analytical framework across the projection horizon. Segmentation modeling incorporated fuel source, generation capacity tier, project ownership structure, and regional grid stability requirements. CAGRs were derived from installed capacity trajectories and capital expenditure announcements, with fuel price sensitivity and emissions compliance cost curves as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese utilities to accelerate subcritical decommissioning would shift outcomes beyond modeled ranges. Quarterly review of MIIT efficiency standard enforcement intensity and CEA pollution control retrofit compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Solar Generator Market
Power Generation
South America Thermal Power Market
Power Generation
Gas Gensets Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Mexico Combined Heat and Power Market
Power Generation
Subsea Power Grid System Market
Power Generation
India Thermal Power Plant Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Thermal Power Market
Power Generation
Micro CHP Market
Power Generation
Temporary Power Generation & Power Rental Market
Power Generation
Global Black Start Generator Market
Power Generation
Air Cooled Turbo Generators Market
Power Generation
Gas Fired Power Plant Market
Power Generation
Stirling Engine Market
Power Generation
Marine Power Plant Market