
 Thawing System Market | 2026-2036
Thawing System Market Size, Share, and Industry Trends Forecast 2026-2036
Thawing System Market Outlook
Automated controlled-rate thawing is reorganizing competitive dynamics across the thawing system landscape. Thermo Fisher Scientific leverages its life sciences platform breadth to sustain instrument-service bundling in North American hospital networks. Sartorius AG anchors European bioprocessing demand with specialized thawing solutions calibrated to cell therapy manufacturing standards. Cardinal Health competes through distribution density, occupying procurement channels that prioritize supply reliability over feature differentiation.
A thawing system is a thermally controlled device engineered to raise frozen biological materials from cryogenic or sub-zero storage temperatures to usable states without compromising cellular viability, typically maintaining rate precision within ±0.5°C per minute through resistive, microwave, or convection heating modalities. These systems serve critical functions in preserving protein structures, membrane integrity, and therapeutic potency across clinical and research workflows. Rapid thawing devices command expanding share in cell therapy applications where speed-to-dose directly impacts patient treatment windows, while water bath systems retain installed-base dominance in blood banks governed by established SOP compliance. Microwave heating technology differentiates through energy efficiency advantages, though resistive heating maintains broader regulatory acceptance across jurisdictions.
FDA 21 CFR Part 11 electronic records requirements and EMA Good Distribution Practice guidelines shape validation documentation burdens for thawing system manufacturers seeking multi-regional market access. ISO 13485 quality management standards and EU Medical Device Regulation conformity pathways filter participant eligibility, concentrating commercial traction among firms with established notified body relationships. Stakeholders must weigh thermal uniformity certification against total cost of ownership when specifying equipment for validated manufacturing environments.
Market Dynamics
Automated controlled-rate thawing is compressing traditional water bath workflows as cell therapy manufacturing scales demand precise thermal profiles that manual methods cannot replicate. Biopharmaceutical producers now specify equipment capable of maintaining ±0.5°C per minute uniformity across validated batch records, forcing equipment vendors to reengineer heating architectures around resistive and microwave modalities.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for blood component traceability are compelling blood banks to replace non-validated thawing equipment with compliant automated systems.
- Cell therapy manufacturing:Autologous and allogeneic cell production workflows require rapid thawing devices that preserve membrane integrity during dose preparation.
- Japan's PMDA cell therapy acceleration pathway:Expedited review timelines for regenerative medicines are expanding installed base demand for GMP-grade thawing infrastructure.
Market Restraints
- Stainless steel and electronic component costs:Input price volatility for precision temperature sensors and medical-grade alloys compresses margin structures for mid-tier equipment manufacturers.
- Notified body capacity constraints in Europe:EU MDR conformity assessment backlogs are extending time-to-market for novel thawing device introductions by 12-18 months.
- Water bath substitution threat:Established blood bank SOPs and lower capital requirements sustain incumbent technology preference despite performance limitations.
Strategic Opportunities
- India's CDSCO biologics manufacturing push:PLI scheme incentives for local cell therapy production are creating first-mover advantage for thawing system vendors establishing service networks.
- Convergence of RFID tracking and thermal logging:Integration of cold-chain monitoring with thawing device data streams enables end-to-end chain of custody documentation.
- Direct-to-biotech distribution:Bypassing traditional hospital procurement committees through specialized life sciences distributors accelerates cell therapy segment penetration.
Industry Challenges
- ISO 13485 quality management certification:Small and mid-sized equipment manufacturers face resource intensity in maintaining notified body relationships across multiple jurisdictions.
- Legacy LIMS integration complexity:Biopharmaceutical manufacturers require seamless data handoff from thawing devices to existing manufacturing execution systems, demanding custom protocol development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thawing System Market |
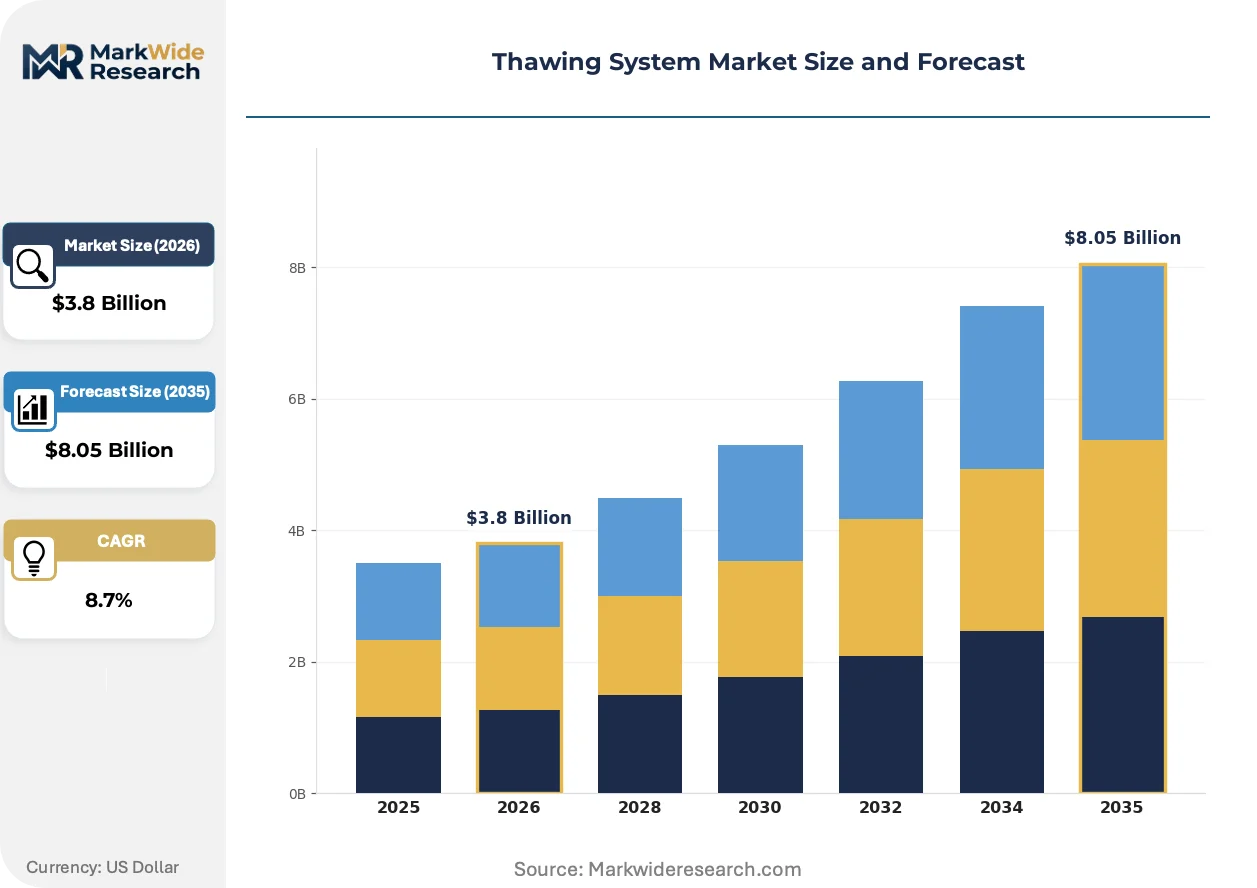
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Bath, Microwaves, Chamber Thawers, Rapid Thawing Devices Technology: Resistive Heating, Microwave Heating, Convection Heating, Ultrasonic Thawing End User: Hospitals, Blood Banks, Research Laboratories, Biopharmaceutical Companies Application: Cell Therapy, Organ Transplantation, Blood Component Thawing, Vaccine Preparation |
| Companies Covered | Helmer Scientific, Sartorius AG, Boekel Scientific, Cardinal Health, Thermo Fisher Scientific, Sarstedt AG & Co. KG, Barkey, BioCision, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thawing System Market Strategic Shifts
Microwave heating architectures are gaining engineering investment as energy efficiency advantages challenge resistive heating's regulatory acceptance dominance. Equipment designers are optimizing electromagnetic field distribution to achieve thermal uniformity without the thermal mass penalties of conventional heating elements.
Resistive heating technology is fragmenting across application-specific implementations. Blood banking workflows retain cartridge-based resistive systems for established SOP compatibility. Cell therapy manufacturers adopt precision resistive platforms with programmable ramp rates. Biobanking operations specify high-capacity resistive chambers for bulk specimen processing. Each segment's divergent performance requirements are preventing technology consolidation.
EMA Good Distribution Practice cold-chain integrity guidelines are tightening validation documentation for cross-border biological shipments. Logistics providers must now demonstrate thermal excursion prevention across thawing handoff points. European cell therapy distributors are investing in qualified thawing stations at regional hub facilities to maintain chain of custody compliance.
Service contract unbundling is reshaping buyer-supplier relationships in North American hospital networks. Procurement departments are separating equipment acquisition from maintenance agreements to optimize capital expenditure timing. Biopharmaceutical manufacturers increasingly negotiate performance-based service tiers tied to uptime guarantees rather than fixed preventive maintenance schedules. This shift is most pronounced in United States academic medical centers managing diverse research and clinical thawing workloads.
Thawing System Market Segmentation
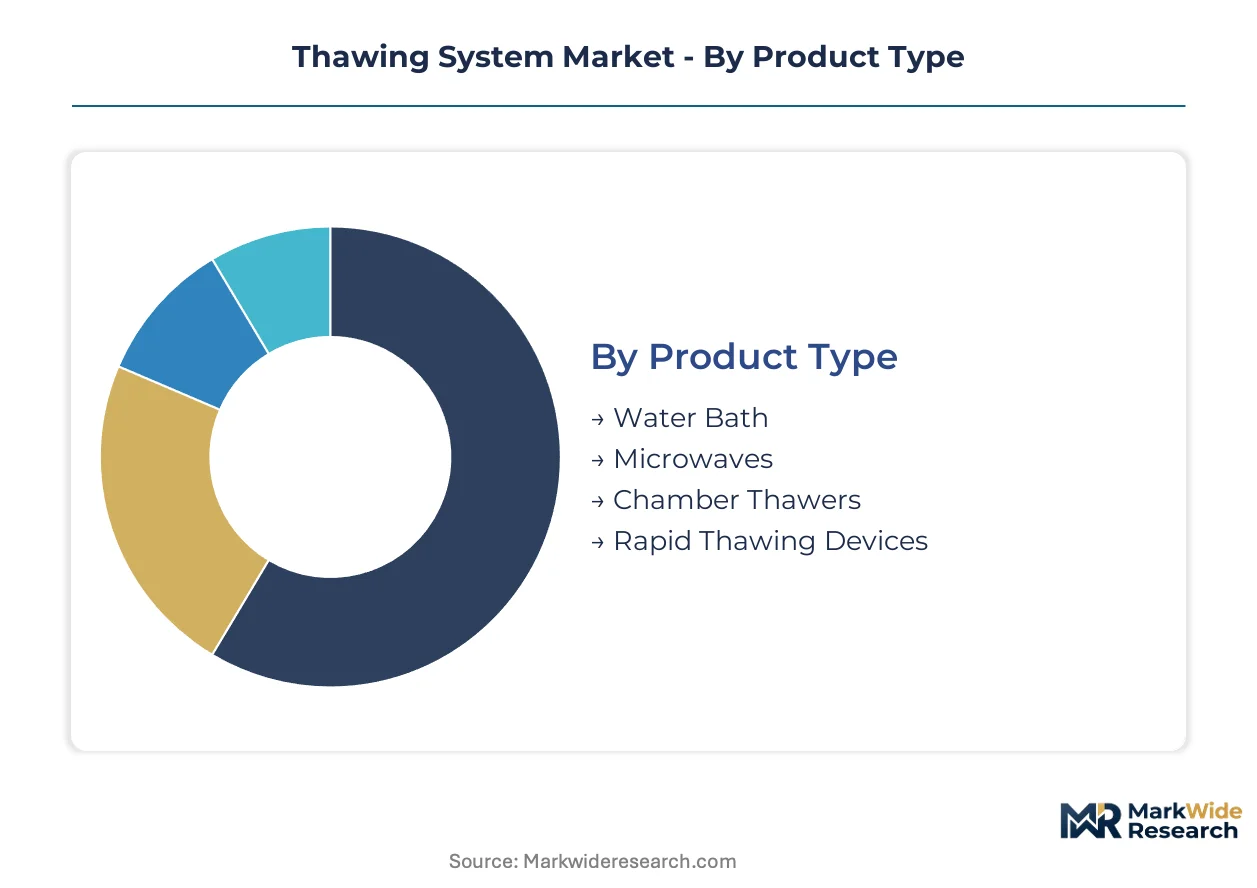
Thawing system procurement diverges sharply across clinical versus manufacturing environments, with regulatory validation requirements and throughput demands driving fundamentally different equipment specifications. Understanding segment-level substitution pressures and technology trade-offs enables vendors to align R&D investment with pockets of highest willingness-to-pay.
Product Type:
Water bath systems face the most acute substitution threat from automated alternatives as blood banks confront FDA electronic records mandates and cell therapy manufacturers reject manual temperature monitoring.
- Rapid Thawing Devices:These systems deploy forced convection or microwave energy to achieve thaw rates exceeding 10°C per minute while maintaining viability-critical thermal uniformity. Cell therapy manufacturers in the United States and Germany are specifying these for autologous dose preparation where treatment windows compress patient access. FDA 21 CFR Part 11 compliance and integrated data logging justify premium positioning against conventional alternatives.
- Water Bath:Submersion-based thawing in temperature-controlled reservoirs retains dominance in blood banking workflows governed by established SOPs and lower capital procurement thresholds. Blood banks in Japan continue specifying these for plasma and cryoprecipitate processing where validation documentation for alternative technologies remains incomplete.
- Microwaves:Electromagnetic field-based systems deliver energy efficiency advantages but face uneven regulatory acceptance across jurisdictions.
- Chamber Thawers:Enclosed cabinet designs with programmable temperature profiles serve biobanking operations requiring batch processing of multiple specimens.
Water bath retains volume leadership; rapid thawing devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium precision platforms from commodity heating elements, with resistive systems commanding price premiums for programmable ramp rate capabilities.
- Resistive Heating:Cartridge-based or chamber-integrated heating elements deliver precise temperature ramp control within ±0.5°C per minute through direct thermal conduction. Biopharmaceutical companies in Germany and Japan specify these for GMP manufacturing environments where batch record validation demands reproducible thermal profiles. ISO 13485 certification and notified body relationships filter supplier eligibility.
- Microwave Heating:Electromagnetic energy deposition enables rapid volumetric heating without thermal mass penalties, though field uniformity engineering remains critical for cell viability preservation. Equipment designers are optimizing cavity geometries to compete with resistive systems on thermal consistency metrics.
- Convection Heating:Forced air circulation provides moderate thaw rates suitable for blood component processing with lower energy consumption.
- Ultrasonic Thawing:Acoustic energy transmission accelerates phase change through cavitation effects, emerging in research laboratory settings.
Resistive heating dominates validated manufacturing; microwave architectures are gaining share fastest in energy-sensitive installations.
End User:
Customer type determines procurement authority structure, with biopharmaceutical direct purchasing bypassing hospital committee delays that slow equipment refresh cycles.
- Biopharmaceutical Companies:Cell therapy manufacturers and CDMOs specify GMP-grade equipment with integrated manufacturing execution system connectivity and comprehensive IQ/OQ/PQ documentation. These buyers negotiate performance-based service contracts tied to uptime guarantees rather than fixed maintenance schedules.
- Blood Banks:Transfusion service departments prioritize SOP compliance and supply reliability over feature differentiation, sustaining incumbent water bath preferences despite performance limitations.
- Hospitals:Academic medical centers manage diverse research and clinical workloads, driving demand for flexible platforms with multiple thawing protocols.
- Research Laboratories:Preclinical and discovery settings prioritize experimental flexibility and lower capital barriers over validation documentation.
Blood banks retain installed base dominance; biopharmaceutical companies are expanding procurement fastest.
Application:
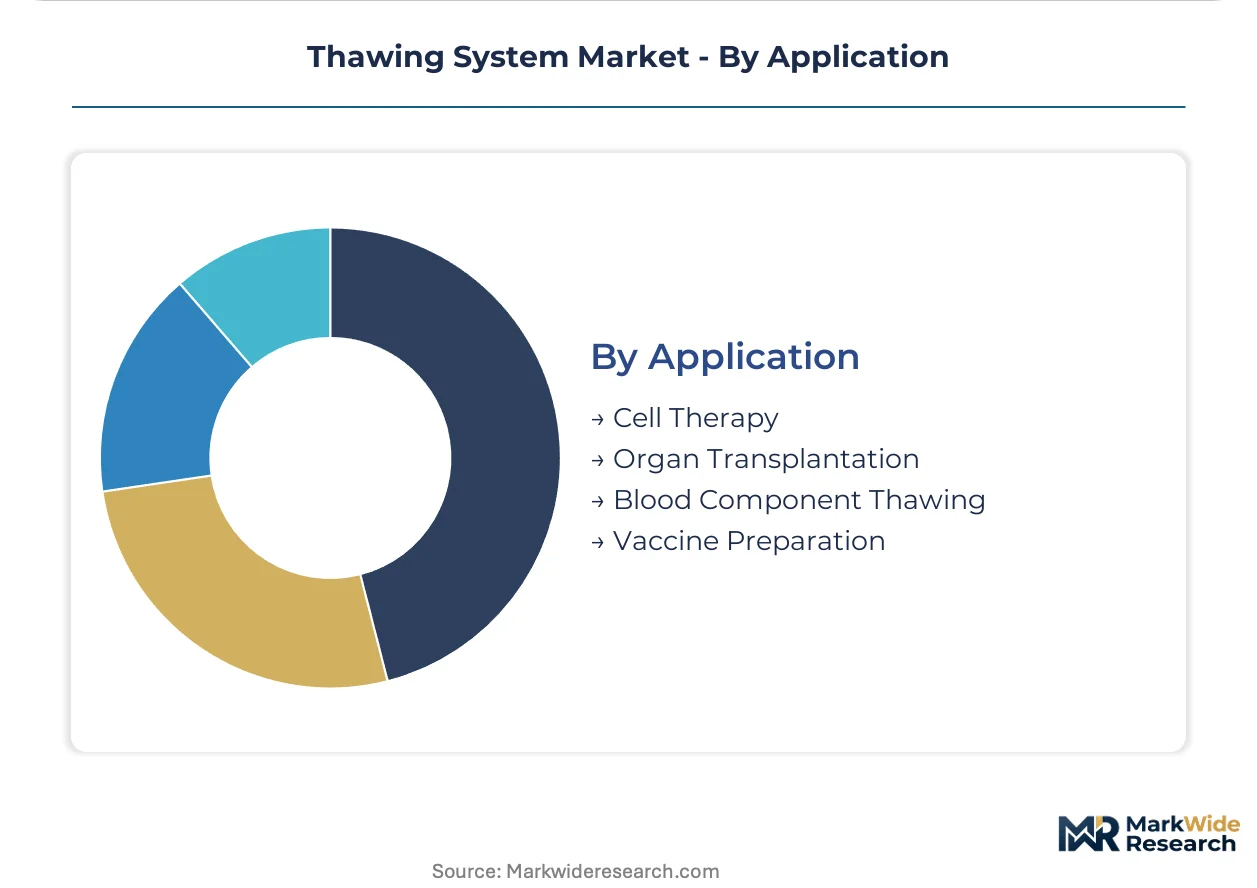
Volume concentration in blood component processing contrasts with margin concentration in cell therapy, where speed-to-dose directly impacts commercial therapy availability.
- Cell Therapy:Autologous and allogeneic cell production requires rapid thawing with membrane integrity preservation during dose preparation and infusion workflows. Japan's PMDA cell therapy acceleration pathway is expanding demand for qualified thawing infrastructure at manufacturing and clinical sites.
- Blood Component Thawing:Plasma, cryoprecipitate, and stem cell products for transfusion represent high-volume, established workflows with entrenched equipment preferences and regulatory familiarity.
- Organ Transplantation:Perfusion and preservation protocols for solid organ transport require specialized thawing coordination with cold ischemia time management.
- Vaccine Preparation:Cold-chain distribution handoffs for temperature-sensitive immunological products demand validated thawing stations at regional hub facilities.
Blood component thawing retains volume leadership; cell therapy holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German thawing system manufacturers export precision equipment to United States biopharmaceutical clusters, while Japanese vendors supply regional cell therapy networks across East Asia. This trade corridor reflects divergent regulatory validation requirements and manufacturing standards across major demand centers.
United States
FDA 21 CFR Part 11 mandates are compelling blood banks in Texas and California to replace legacy water baths with validated automated systems. Academic medical centers in Greater Boston and the Research Triangle are specifying GMP-grade thawing infrastructure for autologous cell therapy manufacturing. Thermo Fisher Scientific leverages its North American distribution platform to sustain instrument-service bundling across hospital procurement networks.
Germany
EMA Good Distribution Practice cold-chain integrity guidelines are tightening validation documentation for cross-border biological shipments. Sartorius AG anchors European bioprocessing demand with specialized thawing solutions calibrated to cell therapy manufacturing standards. The Baden-Württemberg and Bavaria industrial clusters concentrate precision equipment fabrication serving CDMOs across the EU.
Japan
PMDA cell therapy acceleration pathway timelines are expanding installed base demand for qualified thawing infrastructure at manufacturing and clinical sites. METI industrial policy supports domestic production of GMP-grade thermal processing equipment. The Kanto region surrounding Tokyo hosts the highest concentration of regenerative medicine production facilities requiring validated thawing protocols.
India
CDSCO biologics manufacturing push under the PLI scheme is creating first-mover advantage for vendors establishing service networks. Maharashtra and Telangana state governments are incentivizing cell therapy production infrastructure through dedicated biotechnology parks. Domestic thawing equipment demand concentrates in Hyderabad and Pune manufacturing clusters serving export-oriented CDMOs.
United Kingdom
MHRA post-Brexit regulatory alignment with EMA standards maintains conformity assessment requirements for thawing device market access. The Golden Triangle biotech cluster spanning London, Cambridge, and Oxford drives specification of precision thermal processing equipment. NHS blood and transplant services are evaluating automated alternatives to manual water bath workflows for component processing.
Thawing System Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The vendor base stratifies between diversified life sciences conglomerates with full-platform portfolios and focused equipment specialists with single-technology depth. Three archetypes dominate: integrated platform providers bundling instruments with service contracts, precision thermal engineering specialists serving GMP manufacturing, and distribution-heavy incumbents optimizing supply reliability. Competitive moves concentrate on strategic partnerships for manufacturing execution system integration and geographic expansion through specialized life sciences distributors.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and GE Healthcare represent the integrated platform archetype with broad instrument portfolios spanning sample preparation through analytical workflows. Sartorius AG exemplifies the precision thermal engineering specialist positioned for bioprocessing applications. Cardinal Health occupies a distinct position anchored in distribution density and supply chain reliability rather than feature differentiation. These three companies illustrate how competitive positioning diverges across technology depth, service integration, and procurement channel access.
| Leading Market Players |
|---|
| Helmer Scientific |
| Sartorius AG |
| Boekel Scientific |
| Cardinal Health |
| Thermo Fisher Scientific |
| Sarstedt AG & Co. KG |
| Barkey |
| BioCision |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Microwave heating technology displacing resistive systems in energy-sensitive cell therapy facilities is redrawing procurement geography toward East Asian component suppliers while compressing price premiums for legacy thermal architectures. This substitution dynamic simultaneously elevates inbound logistics costs for precision sensors and fragments pricing power across certification tiers.
Pricing Analysis
Next-generation microwave architectures command 15-25% premiums over incumbent resistive platforms, while water bath systems occupy a collapsing economy tier. Three-tier pricing structure across GMP-certified, clinical-grade, and research-use equipment reflects ISO 13485 validation burdens and FDA 21 CFR Part 11 compliance documentation. Cost compression in the mid-tier intensifies because stainless steel and electronic component input volatility squeezes manufacturer margins. Blood banks exhibit highest price sensitivity due to capital procurement committee constraints, while biopharmaceutical companies prioritize thermal uniformity certification over unit economics.
Supply Chain Analysis
Port congestion on transpacific lanes elevates landed costs for precision temperature sensors sourced from Japanese and German component fabricators. Final assembly concentrates in Germany, the United States, and Japan, with medical-grade alloy feedstock drawing from specialty steel producers in Austria and Sweden. Single-source vulnerability around cryogenic-compatible sensor arrays creates exposure to semiconductor foundry allocation shifts. Distribution runs through specialized life sciences distributors serving hospital procurement networks and direct-to-biotech channels bypassing traditional committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among biopharmaceutical consolidators and integrated hospital networks, compressing vendor margins and elevating specification authority for GMP-grade equipment.
For Market Incumbents: Shield installed-base revenue by embedding predictive maintenance algorithms that raise switching costs for blood bank customers confronting FDA electronic records mandates. Deepen backward integration into precision sensor calibration capabilities to offset component cost volatility from Japanese suppliers. Prioritize notified body relationship expansion across EU MDR and Japan PMDA pathways before backlog extensions worsen. For New Entrants and Emerging Players: Anchor in India's CDSCO biologics manufacturing push under PLI scheme incentives, where domestic cell therapy production infrastructure remains underdeveloped and service network gaps persist. Target research laboratory segments with lower capital barriers and reduced validation documentation requirements. Pursue direct-to-biotech distribution partnerships that bypass hospital procurement committee delays. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision thermal engineering specialists holding ISO 13485 certifications but limited geographic footprint. Long-term viability hinges on manufacturing execution system integration capabilities and cell therapy segment exposure. Monitor PMDA cell therapy acceleration pathway approval velocity as inflection indicator for GMP-grade infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Execution System Integration | Enables seamless data handoff from thawing devices to biopharmaceutical batch records for FDA compliance. |
| RFID-Enabled Cold Chain Convergence | Links thermal logging with thawing device data streams for end-to-end custody documentation under EMA guidelines. |
| Service Contract Unbundling | Separates equipment acquisition from maintenance agreements to optimize capital expenditure timing for US academic medical centers. |
| Microwave Cavity Geometry Optimization | Improves electromagnetic field distribution to challenge resistive heating thermal uniformity benchmarks. |
| Regional Hub Qualification Investment | Positions European cell therapy distributors to maintain chain of custody compliance at thawing handoff points. |
Study Parameters
Cross-validation between primary interviews with biopharmaceutical manufacturing executives, blood bank operations directors, and hospital biomedical engineers and secondary sources anchors the qualitative findings. FDA 510(k) filings, EMA medical device registration databases, ISO 13485 certification registries, and GPO procurement contract repositories provide validation triangulation. Bottom-up equipment shipment analysis and top-down healthcare infrastructure spending estimates converge on segment-level demand quantification.
Sensitivity analysis across resistive versus microwave technology adoption curves, cell therapy manufacturing capacity expansion scenarios, and blood bank capital refresh cycles shapes the analytical framework. Segmentation dimensions include product type, heating modality, end-user archetype, and application workflow. CAGRs derive from installed base replacement dynamics and greenfield bioprocessing facility buildouts. Forecast inputs incorporate PMDA cell therapy acceleration pathway throughput assumptions and EU MDR conformity assessment timeline projections.
Material uncertainties — regulatory approval delays, semiconductor supply allocation shocks, and cell therapy clinical trial failure rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution velocity and certification pathway efficiency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Global Magnetic Refrigeration Market