
 Adiabatic Cooler Market | 2026-2036
Adiabatic Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Adiabatic Cooler Market Intelligence
A transition toward multi-source procurement for core cooling components is hardening vendor selection criteria. SPX Cooling Technologies, Inc. leverages its extensive service network to secure large-scale industrial contracts. GEA Group Aktiengesellschaft differentiates through its focus on hygienic designs for food processing and pharmaceutical applications. Baltimore Aircoil Company competes on modular system designs optimized for rapid deployment in data center projects.
An adiabatic cooler lowers air temperature by evaporating water across a wetted media pad before the air reaches a dry heat exchanger. This process delivers energy-efficient cooling for industrial processes without adding humidity to the conditioned air stream. Data centers constitute a primary demand driver among applications due to their intense cooling needs. Hybrid product types are gaining share by offering operational flexibility that adapts to diverse climate conditions.
The EU's F-Gas Regulation and refrigerant phase-down mandates from the US EPA create significant tailwinds for technologies that reduce reliance on high-GWP refrigerants. Concurrently, ISO 50001 standards for energy management systems encourage facilities to adopt more efficient cooling solutions like adiabatic systems. Future system design will need to balance superior energy efficiency against increasing scrutiny over water consumption in arid regions.
Market Dynamics
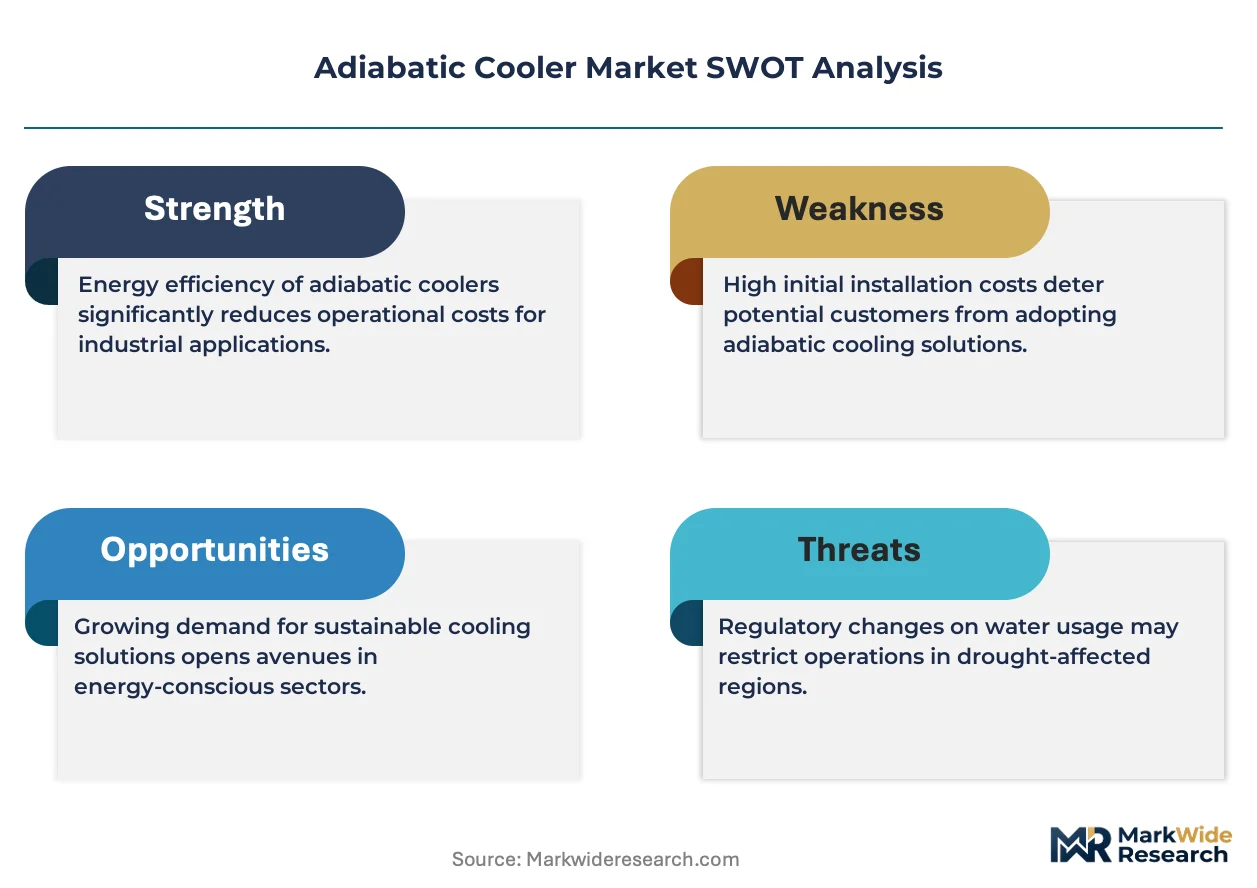
The central tension shaping the adiabatic cooler market is the conflict between the drive for superior energy efficiency, mandated by regulations, and the increasing scrutiny over water consumption, particularly in water-stressed industrial and data center hubs.
Growth Catalysts
- Energy Efficiency Standards:The adoption of frameworks like ISO 50001 encourages industrial facilities to invest in energy management systems, directly favoring the deployment of efficient technologies such as adiabatic coolers over conventional HVAC.
- Data Center Cooling Demand:Hyperscale and colocation data centers require massive, continuous cooling, making them primary adopters of adiabatic systems to manage intense thermal loads while reducing overall power usage effectiveness (PUE) metrics.
- Refrigerant Phase-Downs:Mandates including the EU's F-Gas Regulation and parallel actions by the US EPA are accelerating the transition away from high-GWP refrigerants, creating a strong regulatory incentive for alternative cooling technologies.
Market Restraints
- Water Consumption Scrutiny:High water usage in arid regions, such as the Southwestern United States or parts of Australia, invites regulatory oversight and increases operational costs, limiting viability for certain large-scale deployments.
- High Initial Capital Outlay:The upfront investment for an adiabatic cooling system can exceed that of traditional air-cooled chillers, presenting a significant adoption barrier for businesses with constrained capital expenditure budgets.
- Performance in High Humidity:System efficiency degrades substantially in climates with high ambient humidity, like those found in Southeast Asia, which restricts the addressable market for standard product configurations.
Strategic Opportunities
- Hybrid System Development:Integrating adiabatic pre-cooling with conventional DX or chilled water systems creates flexible solutions that can penetrate markets with highly variable climate conditions, such as Southern Europe.
- Edge Computing Applications:The growth of distributed edge data centers creates a distinct opportunity for smaller, modular adiabatic coolers that are optimized for rapid and scalable deployment in non-traditional IT environments.
- Industrial Retrofit Programs:Upgrading aging cooling infrastructure within established manufacturing clusters in Germany and the US Midwest presents a substantial market for retrofit-focused adiabatic solutions tailored to existing facilities.
Industry Challenges
- Legionella Risk Mitigation:Preventing the growth of Legionella bacteria requires strict adherence to water treatment and maintenance protocols, such as those outlined in ASHRAE Standard 188, adding operational complexity and cost.
- Controls Integration Expertise:Successfully connecting adiabatic units with sophisticated building management systems (BMS) demands specialized controls engineering talent, which remains a notable skills gap in the HVAC industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adiabatic Cooler Market |
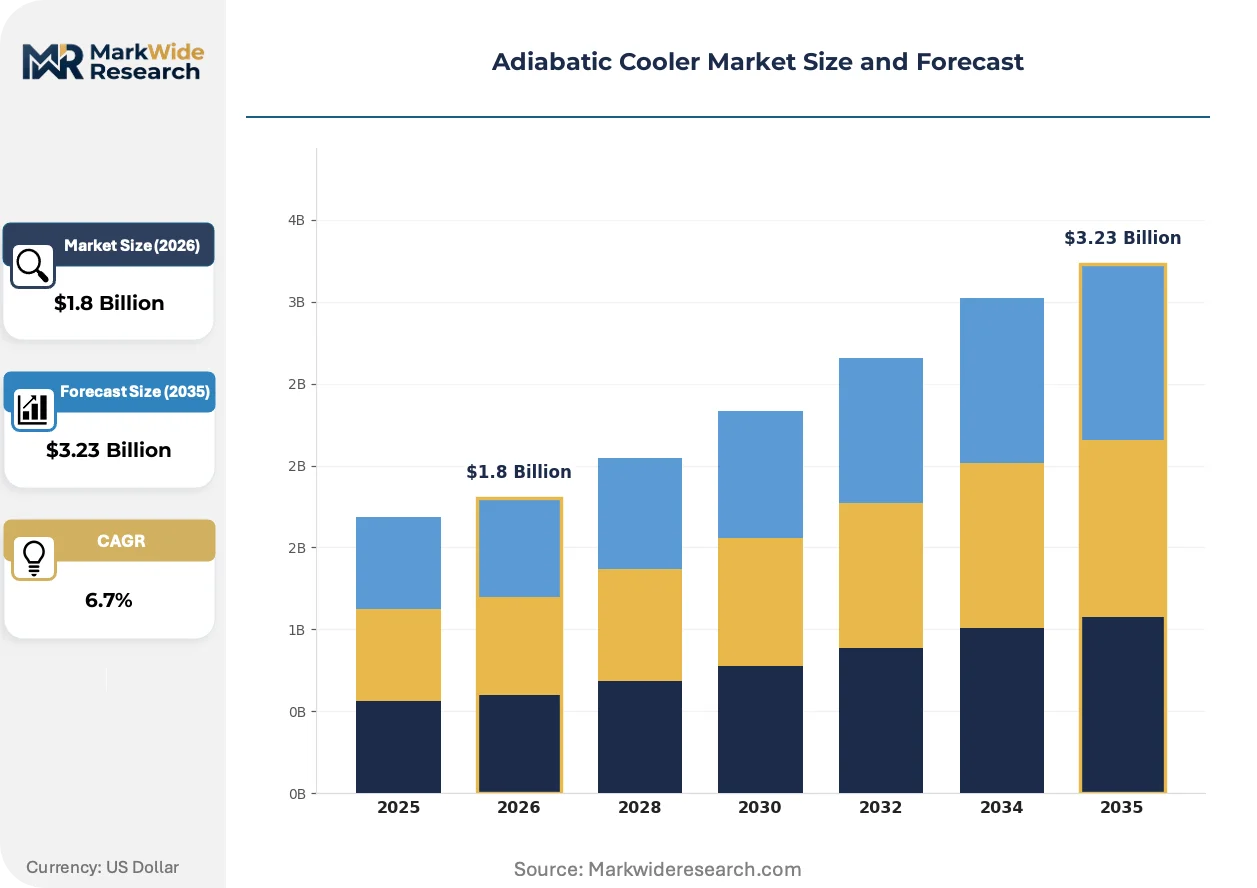
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-flow, Counter-flow, Hybrid, Modular Technology: Indirect, Direct, Combined, Recirculation Application: Data Centers, Power Generation, Food Processing, HVAC Systems End User: Manufacturing Facilities, Commercial Buildings, Chemical Plants, Pharmaceutical Units |
| Companies Covered | Hamon Group NV, Kelvion Holding GmbH, SPX Cooling Technologies, Inc., MITA Cooling Technologies, Thermax Limited, EVAPCO, Inc., GEA Group Aktiengesellschaft, Zanotti, Baltimore Aircoil Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adiabatic Cooler Market Strategic Shifts & Innovations
System design is increasingly governed by a dual mandate for extreme energy efficiency and minimized water consumption. This pushes innovation toward intelligent controls and hybrid configurations that adapt to real-time environmental and operational conditions.
Smart controls that leverage IoT sensors and predictive analytics optimize water use and fan speed based on real-time weather forecasts and facility heat loads. Data center operators and large-scale industrial facilities are the primary adopters of these advanced systems. This logic is integrating water conservation strategies directly into the core operational programming, creating self-adjusting systems that balance cooling performance with resource stewardship.
The EU's Corporate Sustainability Reporting Directive (CSRD) compels large companies to provide detailed disclosures on environmental impacts, including water and energy usage. This regulatory pressure forces facility owners to quantify the resource efficiency of their cooling infrastructure, building a strong business case for systems with verifiable performance data. Enterprises in water-stressed EU countries like Spain and Italy are therefore prioritizing cooling technologies that offer transparent, reportable efficiency metrics.
A shift from component-based purchasing toward pre-engineered, modular cooling solutions is compressing project deployment timelines. This trend challenges the traditional model of on-site assembly by HVAC contractors, favoring factory-assembled, skid-mounted systems that are tested before delivery. This model is most prominent in the fast-paced data center construction sector, particularly in North America and Northern Europe, where speed-to-market is a critical competitive advantage.
Adiabatic Cooler Market Segmentation
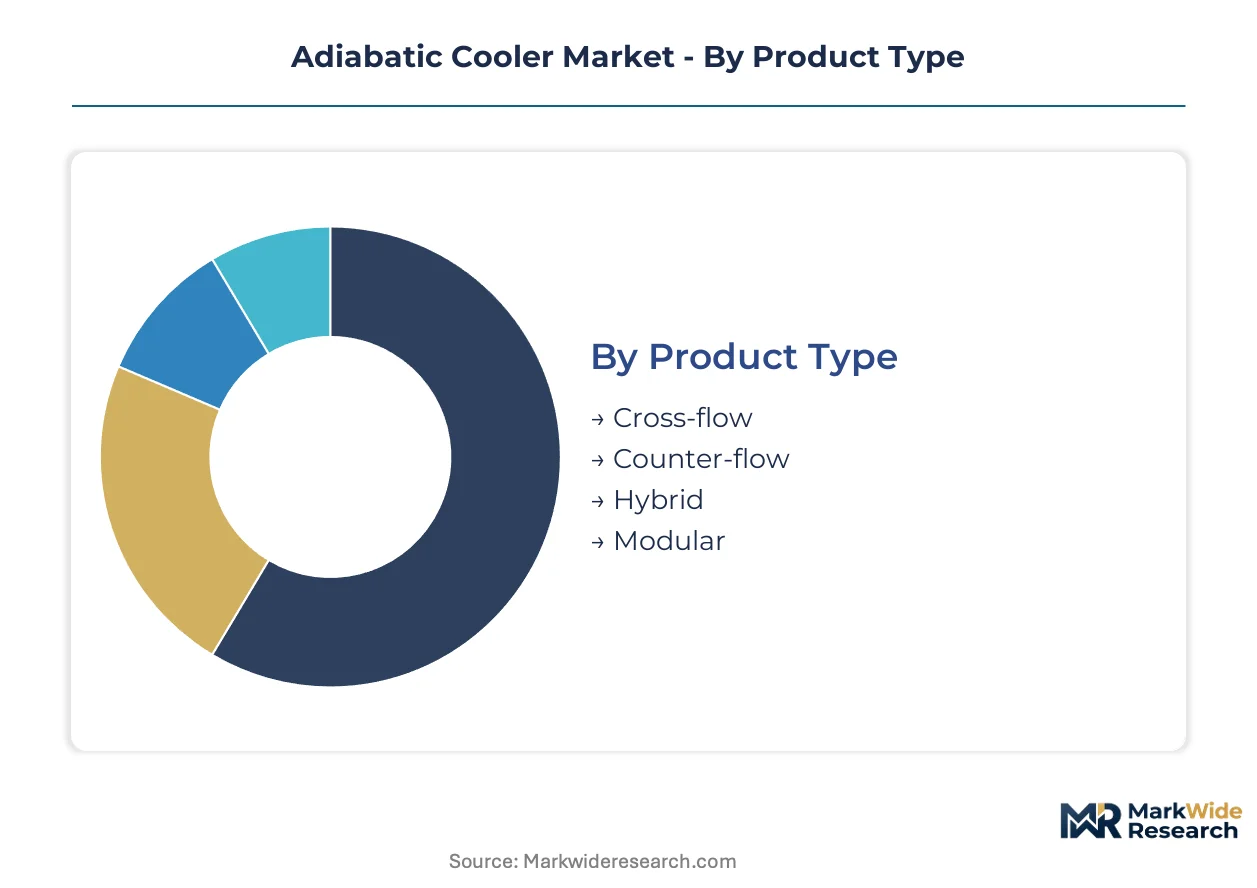
The adiabatic cooler market segments across diverse product types, technologies, applications, and end-user industries. Understanding these distinctions helps businesses tailor solutions for specific operational demands and regional climate conditions. Each segment reflects unique requirements for efficiency, system integration, and regulatory compliance, influencing market penetration strategies.
Product Type:
The market's product type segmentation highlights the volume versus premium split within cooling solutions. Hybrid and modular designs command higher price points due to their advanced features and flexibility.
- Hybrid:These systems integrate both adiabatic pre-cooling and conventional refrigeration, offering operational flexibility that adapts to varying climate conditions. Demand for hybrid units is concentrating in regions with highly variable temperatures, such as Southern Europe, where energy efficiency during peak loads is critical.
- Modular:Composed of standardized, pre-engineered units, modular adiabatic coolers facilitate rapid deployment and scalability for projects. Data center construction in North America and Northern Europe drives significant demand for modular solutions, prioritizing speed-to-market and simplified installation.
- Cross-flow:Air flows perpendicular to the water spray in cross-flow designs, offering a compact footprint for specific industrial applications.
- Counter-flow:Counter-flow systems feature air moving opposite to the water flow, enhancing heat exchange efficiency for larger cooling capacities.
Mature deployment sits with Cross-flow systems. Newer deployment is concentrated in Modular solutions.
Technology:
Technology segmentation reveals the different approaches to heat transfer and water management within adiabatic systems, impacting efficiency and application suitability.
- Indirect:Indirect adiabatic coolers separate the process air from the wetted media, preventing humidification of the conditioned air stream. This technology sees strong adoption in data centers and industrial processes where maintaining dry air is critical for equipment longevity.
- Combined:Combined systems integrate indirect adiabatic cooling with an additional heat rejection method, offering enhanced performance during peak thermal loads. Facilities in water-stressed regions of the United States are increasingly using combined technologies to optimize both water and energy consumption.
- Direct:Direct adiabatic cooling involves passing air directly through a wetted medium, adding humidity to the airstream.
- Recirculation:Recirculation systems reuse water within the cooling process, minimizing fresh water intake for sustained operation.
Demand for Direct technology remains steady. Combined technology is gaining share fastest.
Application:
Application analysis delineates where adiabatic cooling solutions provide the most significant operational benefits, often driven by intense cooling needs and energy efficiency mandates.
- Data Centers:Hyperscale and colocation data centers require massive, continuous cooling to manage intense thermal loads and reduce Power Usage Effectiveness (PUE) metrics. These facilities in Germany and the United States are primary adopters of adiabatic systems to meet stringent energy efficiency targets.
- Food Processing:The food processing industry demands hygienic cooling solutions that maintain precise temperatures without compromising product quality or safety. GEA Group Aktiengesellschaft focuses on hygienic designs for these applications, particularly in Europe, to meet strict regulatory standards.
- Power Generation:Adiabatic coolers support power generation plants by cooling auxiliary equipment and optimizing turbine inlet air temperatures.
- HVAC Systems:Commercial and industrial HVAC systems utilize adiabatic cooling to enhance efficiency, especially in large-scale building climate control.
Power Generation represents a stable application segment. Data Centers show the most significant expansion.
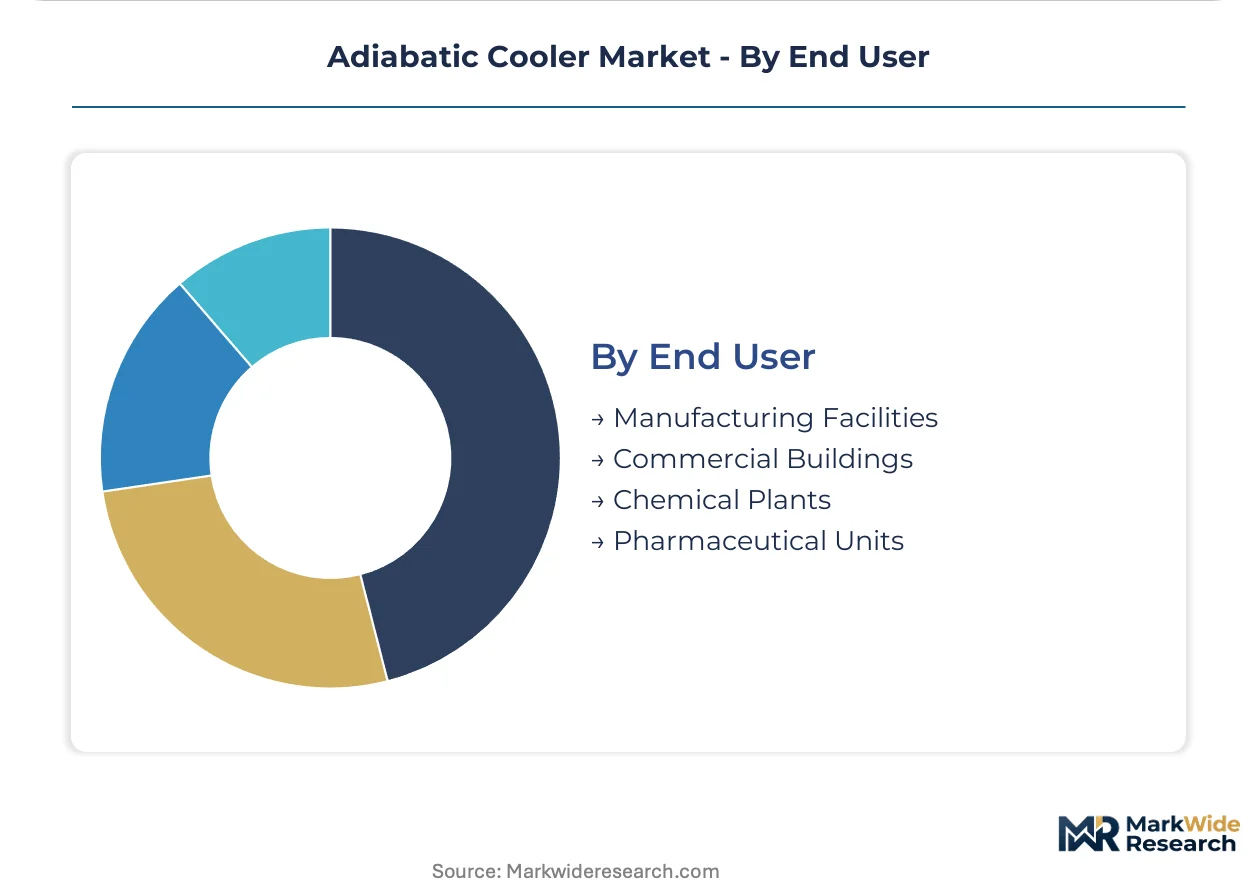
End User:
The end-user segmentation highlights the diverse industrial and commercial sectors benefiting from adiabatic cooling, each with distinct operational requirements and investment profiles.
- Manufacturing Facilities:Industrial clusters in Germany and the US Midwest use adiabatic coolers for process cooling, maintaining stable temperatures for machinery and production lines. These facilities prioritize robust systems with extensive service networks to ensure continuous operation.
- Pharmaceutical Units:Pharmaceutical manufacturing requires precise temperature control and hygienic environments to comply with strict regulatory guidelines. Facilities in Europe adopt adiabatic cooling to manage cleanroom environments and sensitive chemical processes without contamination risks.
- Commercial Buildings:Large commercial structures, including office complexes and retail centers, deploy adiabatic systems to reduce energy costs for climate control.
- Chemical Plants:Chemical processing facilities use adiabatic coolers for exothermic reaction control and equipment cooling, handling corrosive environments.
Established demand exists within Commercial Buildings. Pharmaceutical Units are experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial clusters in Germany anchor significant demand for adiabatic cooling solutions, driven by stringent energy efficiency mandates and a focus on sustainable manufacturing. Water scarcity in regions like the Southwestern United States also influences technology adoption, pushing for water-optimized hybrid systems. This global market shows varied adoption rates based on regional climate, energy costs, and regulatory pressures.
United States
Hyperscale data centers and manufacturing facilities in the Southwestern United States drive demand for adiabatic cooling. The US EPA’s refrigerant phase-down mandates accelerate the shift to alternative cooling technologies. Industrial hubs in Texas and Arizona increasingly deploy combined adiabatic systems to balance energy efficiency with water conservation.
Germany
German manufacturing facilities and data centers prioritize energy-efficient cooling to comply with ISO 50001 standards. The EU's F-Gas Regulation provides a strong incentive for adopting adiabatic systems over traditional refrigeration. Industrial clusters in Bavaria and North Rhine-Westphalia are key deployment sites for industrial retrofit programs.
China
Large-scale industrial expansion and data center construction in China are increasing the need for efficient cooling solutions. The country's dual carbon goals and energy efficiency policies encourage the adoption of advanced cooling technologies. Manufacturing zones in the Yangtze River Delta and Pearl River Delta are seeing rising interest in adiabatic systems.
India
India's rapidly expanding data center market and industrial sector require robust and energy-efficient cooling infrastructure. Government initiatives promoting sustainable industrial practices support the deployment of adiabatic coolers. Major IT hubs like Bengaluru and Hyderabad are key areas for new adiabatic system installations.
Spain
Southern European countries like Spain face variable climate conditions, driving demand for flexible hybrid adiabatic systems. The EU's Corporate Sustainability Reporting Directive compels companies to disclose water and energy usage, favoring efficient cooling. Facilities in Catalonia and Andalusia are adopting hybrid solutions to manage peak cooling loads efficiently.
Adiabatic Cooler Market Key Industry Players
Global majors compete with regional champions across technology specialization and service network reach within the adiabatic cooler market. The market structure is moderately consolidated among top-tier providers, with a fragmented base of regional specialists. Strategic archetypes include large-scale industrial solution providers, specialized hygienic design manufacturers, and modular data center cooling experts. Dominant competitive moves involve strategic partnerships for market access and continuous product innovation focused on efficiency.
Specialized hygienic designs for food processing and pharmaceutical applications exemplify the differentiation strategy of GEA Group Aktiengesellschaft. SPX Cooling Technologies, Inc. represents a global leader leveraging an extensive service network for large industrial contracts. Baltimore Aircoil Company occupies a position among providers focused on modular system designs optimized for rapid data center deployment.
| Leading Market Players |
|---|
| Hamon Group NV |
| Kelvion Holding GmbH |
| SPX Cooling Technologies, Inc. |
| MITA Cooling Technologies |
| Thermax Limited |
| EVAPCO, Inc. |
| GEA Group Aktiengesellschaft |
| Zanotti |
| Baltimore Aircoil Company |
| Others |
Cost & Logistics Intelligence
Specialized controls engineering talent in Germany connects directly to premium pricing for integrated adiabatic cooling systems, reflecting higher labor costs across advanced manufacturing hubs. This cost structure differentiates solutions based on complexity and regional expertise.
Pricing Analysis
Warranty and service-bundling angles define the perceived value of adiabatic cooling systems. Project-based pricing dominates for large industrial and data center deployments, reflecting custom engineering requirements. Price differentiation stems from customization levels and extensive after-sales service networks. Pricing softness affects standard cross-flow systems due to component commoditization. Data centers and pharmaceutical units exhibit lower price sensitivity, prioritizing reliability and regulatory compliance over initial capital outlay.
Supply Chain Analysis
The EU's F-Gas Regulation in Europe reshapes sourcing patterns for cooling components, emphasizing alternatives to traditional refrigerants. Geographic supply concentration for key components like heat exchangers and fan motors centers on Germany and China. Raw material dependencies include specialized metals for coils and advanced polymers for wetted media pads. Single-source vulnerability for intelligent control systems presents a structural risk. Distribution primarily runs through specialized HVAC contractors and direct sales channels to large enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adiabatic cooler market is a vertical-integration race, with players pursuing in-house development of intelligent control systems to optimize system performance and water usage.
For Market Incumbents: To counter increasing scrutiny over water consumption, incumbents must invest in R&D for advanced water conservation technologies. Expanding service networks in emerging industrial clusters, particularly in India and China, secures long-term maintenance contracts. Strategic partnerships with controls integration specialists enhance system intelligence and operational efficiency for complex installations. Leveraging existing customer relationships for retrofit programs in the US Midwest offers a stable revenue stream.
For New Entrants and Emerging Players: The EU's F-Gas Regulation in Europe opens a window for specialized manufacturers focusing on non-refrigerant cooling. Targeting distributed edge data centers with smaller, modular adiabatic units represents a penetrable segment. A go-to-market angle focused on rapid deployment and simplified installation appeals to speed-conscious IT infrastructure developers. Offering comprehensive controls integration services helps bridge the existing skills gap in the HVAC industry.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with strong intellectual property in water management. Long-term viability hinges on the continued global push for energy efficiency and reduced carbon footprints. Acquisition targets should include firms developing IoT-enabled predictive maintenance and water optimization software. The signal to watch is the widespread adoption of real-time water consumption reporting in large industrial and data center facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Development | Creates flexible solutions adapting to diverse climate conditions, expanding addressable markets in Southern Europe. |
| Controls Integration Expertise Acquisition | Addresses the HVAC industry's skills gap, enabling seamless connection with building management systems. |
| Modular Design Expansion | Compresses project deployment timelines, meeting rapid construction demands in North American data centers. |
| Service Network Enhancement | Secures large-scale industrial contracts by providing robust post-installation support in Germany. |
| Water Conservation Technology R&D | Mitigates regulatory risks and operational costs associated with water usage in arid regions like the Southwestern United States. |
Research Approach
Independent corroboration across industry association reports, government energy efficiency databases, and company financial disclosures underwrites the qualitative findings. This approach combines primary interviews with data center facility managers, industrial plant engineers, and HVAC contractors. Secondary validation draws from technical journals and regulatory filings to ensure comprehensive data coverage, employing both bottom-up and top-down triangulation.
The forecast framework anchored the projection horizon to historical reference periods for market sizing and growth rate derivation. Segmentation dimensions modeled include product type, technology, application, end-user, and geographic region. CAGRs were derived using a compound growth formula applied to segmented market values over the modeling period. Industry-specific forecast inputs included Power Usage Effectiveness (PUE) metrics and F-Gas phase-down schedules.
The model assumes a particular technology adoption path; alternative pathways for hybrid adiabatic systems would alter the outlook. Forecasts reflect assumptions documented regarding regulatory enforcement and technological advancements. Unexpected shifts in water availability regulations or economic downturns impacting industrial capital expenditure represent specific risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Global Chiller Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Thawing System Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Absorption Chillers Market