
 Fluid Coolers Market | 2026-2036
Fluid Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Coolers Market Analytics
Data center operators is bifurcating demand away from traditional industrial buyers as AI compute density reshapes thermal management procurement. Carrier sustains technology leadership in adiabatic and hybrid cooling systems for hyperscale facilities. Kelvion Holding GmbH dominates European industrial applications with specialized heat exchanger integration. Thermax anchors emerging market deployment through localized manufacturing and aftermarket service networks.
Fluid coolers are heat rejection devices that transfer thermal energy from process fluids to ambient air or water, typically operating across temperature differentials of 5°F to 15°F approach to wet-bulb conditions, and serve primarily to stabilize industrial processes, power generation cycles, and commercial building HVAC systems. Air-cooled configurations lead in water-scarce regions and applications where plume abatement matters, while hybrid systems represent the fastest-expanding category as operators seek to optimize water and energy tradeoffs under tightening environmental constraints. Adiabatic technology segments command premium positioning where local water restrictions intensify, whereas evaporative cooling retains volume dominance in cost-sensitive industrial installations.
The EPA enforces refrigerant phaseout timelines under the AIM Act that directly shape fluid cooler specification and retrofit demand across United States industrial and commercial installations. OSHA process safety management standards and ASHRAE thermal guidelines further constrain equipment selection, particularly in chemical processing and power generation end uses. Stakeholders must monitor regulatory acceleration in refrigerant transition timelines and assess equipment replacement cycles against emerging low-global-warming-potential fluid compatibility requirements.
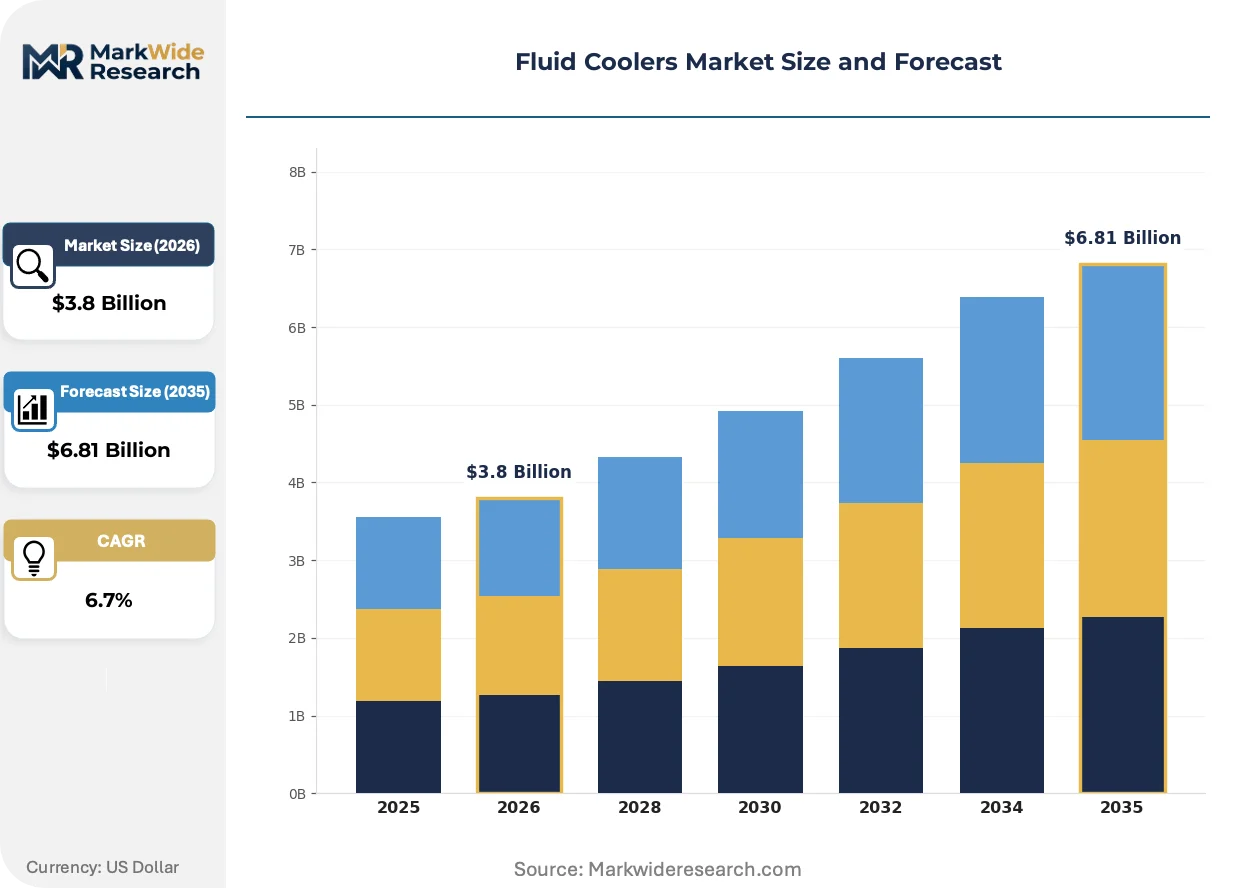
Market Dynamics
AI-driven server density in hyperscale data centers is compressing thermal management procurement cycles and bifurcating demand away from traditional industrial buyers toward specialized fluid cooler architectures.
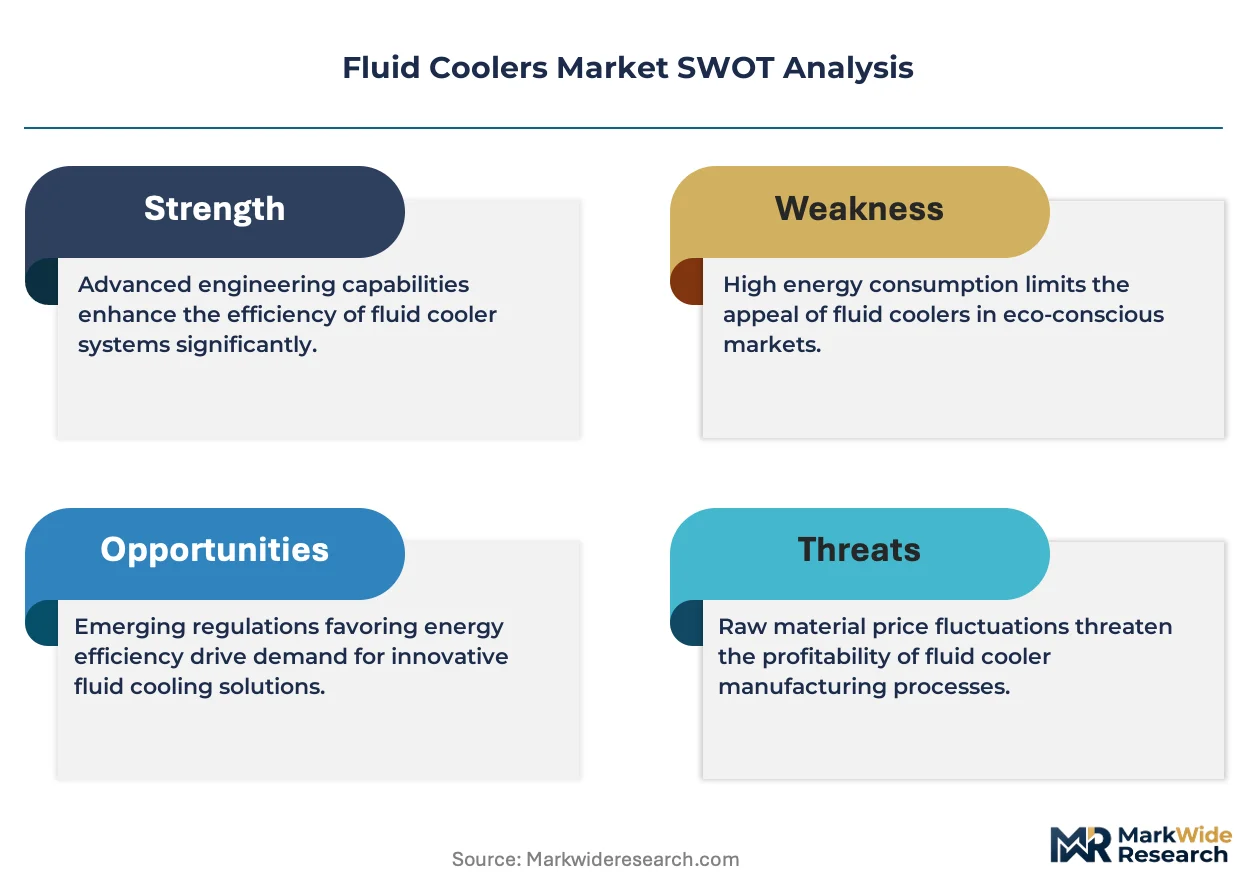
Growth Catalysts
- EPA AIM Act Refrigerant Phasedown:The United States regulatory timeline is accelerating retrofit demand across existing industrial and commercial installations as operators seek alternative cooling architectures compatible with low-global-warming-potential fluids.
- Hyperscale Data Center Expansion:Concentrated deployment across Texas, Arizona, and Northern Virginia clusters is pulling specialized adiabatic and hybrid cooling systems into volume procurement.
- Adiabatic Technology Maturation:Water-scarce regions are specifying advanced adiabatic fluid coolers where plume abatement and conservation mandates intersect with process cooling reliability requirements.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchanger manufacturing faces margin compression from base metal price swings that transfer unevenly through equipment pricing.
- Regional Supply Concentration:European heat exchanger component sourcing creates vulnerability for North American fluid cooler assembly when logistics disruptions affect specialized manufacturing nodes.
- Evaporative Cooling Substitution Ceiling:Cost-sensitive industrial installations retain incumbent evaporative systems where water access remains unrestricted, limiting premium technology penetration.
Strategic Opportunities
- India Industrial Cooling Infrastructure:Localized manufacturing and aftermarket service networks can capture process cooling demand from pharmaceutical and chemical processing expansion under BIS efficiency mandates.
- Hybrid System Technology Convergence:Integration of dry cooling with adiabatic assist modules creates white space for equipment that optimizes water-energy tradeoffs without full evaporative commitment.
- EU F-Gas Regulation Tailwind:The European regulatory framework is mandating transition timelines that accelerate specification of alternative cooling architectures in industrial refrigeration and process applications.
Industry Challenges
- Thermal-Fluid Engineering Talent Scarcity:The specialized skill set bridging HVAC design with process engineering constrains equipment customization for non-standard industrial applications.
- Legacy Control System Integration:Fluid cooler deployment in brownfield facilities requires protocol translation between modern variable-speed drives and existing building automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Coolers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Hybrid, Oil-Cooled Technology: Direct Expansion, Adiabatic, Indirect Cooling, Evaporative Cooling End User: Power Generation, Chemical Processing, Food & Beverage, HVAC Application: Industrial, Commercial, Residential, Agricultural |
| Companies Covered | Valvoline Global Operations, Thermax, Shell plc, Piovan S.p.A., Carrier, The Chemours Company, Exxon Mobil Corporation, Kelvion Holding GmbH, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Coolers Market Evolving Landscape
Equipment architecture is compressing physical footprints while expanding thermal rejection capacity, driven by site constraints in dense urban data centers and modular industrial deployment models.
Microchannel heat exchanger technology is miniaturizing fluid cooler footprints without sacrificing thermal rejection rates. Hyperscale operators in Northern Virginia and Singapore are specifying these configurations where rooftop load limits or lease space constraints restrict traditional coil arrangements. The technology is miniaturizing equipment footprints to below 40% of conventional shell-and-tube equivalents while maintaining approach temperatures within specification.
The EPA's phasedown schedule under the AIM Act is forcing refrigerant transition timelines that reshape fluid cooler specification across United States process industries. Chemical processing and cold chain logistics facilities face compressed replacement cycles as hydrofluorocarbon availability contracts. ASHRAE thermal guidelines are tightening in parallel, pushing operators toward equipment architectures that accommodate emerging low-global-warming-potential heat transfer fluids without full system replacement.
Buyer concentration among hyperscale operators is consolidating procurement leverage and compressing vendor qualification timelines. Traditional distribution through mechanical contractors is giving way to direct specification relationships where data center developers embed thermal management vendors into design-build contracts. This channel shift is most visible in Texas and Arizona markets where multi-hundred-megawatt facilities negotiate multi-year equipment supply agreements outside conventional bidding processes.
Fluid Coolers Market Segmentation
Fluid cooler procurement varies sharply across cooling architectures and thermal loads, with specification decisions driven by water availability, energy costs, and regulatory compliance rather than unit economics alone. Understanding segment boundaries reveals where technology substitution creates margin compression or expansion for equipment suppliers.
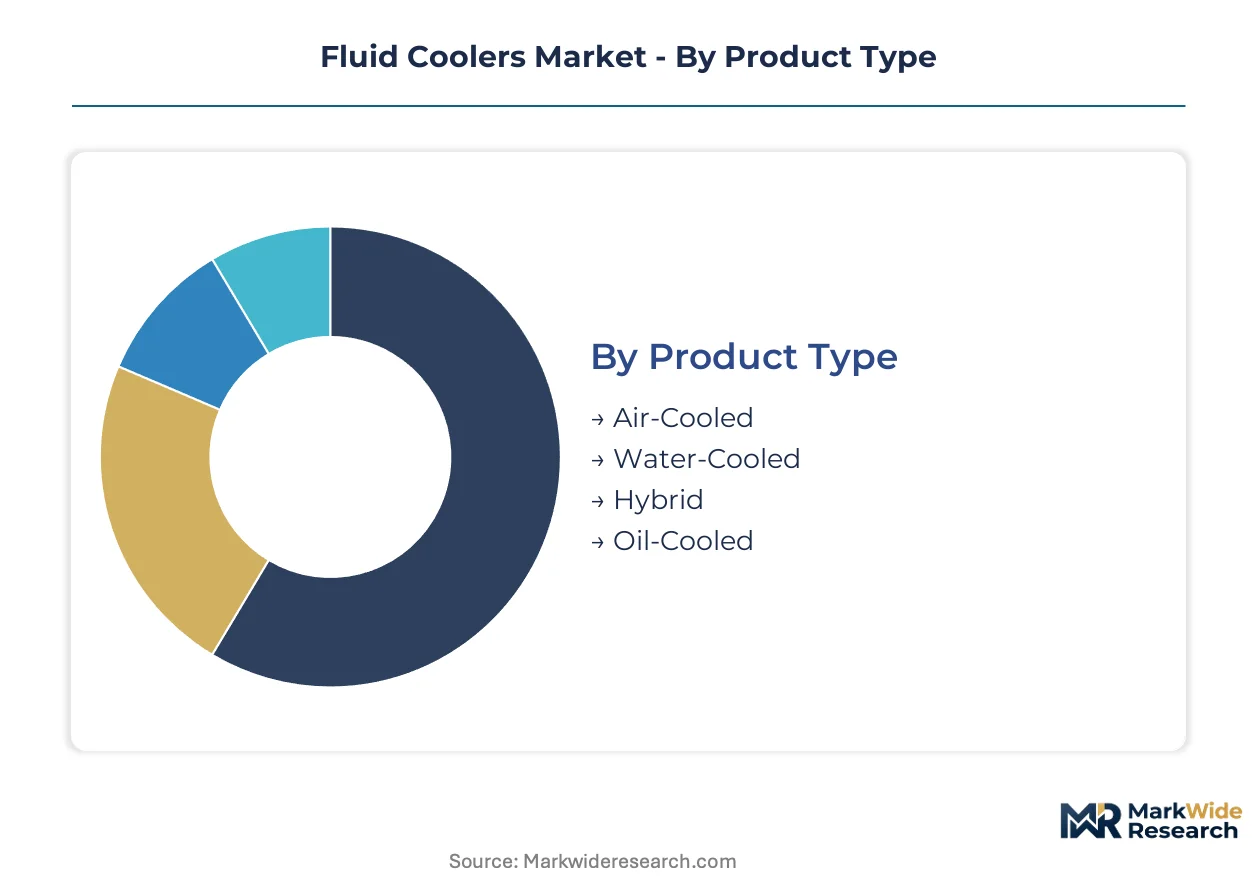
Product Type:
Premium positioning concentrates in configurations that resolve water-energy tradeoffs, while commoditized segments compete on replacement cycle timing and aftermarket service attach rates.
- Air-Cooled:These systems reject heat directly to ambient air through finned coil arrangements, eliminating water consumption entirely. Demand clusters in Arizona and Texas data center corridors where aquifer depletion triggers municipal withdrawal restrictions, with hyperscale operators specifying dry cooling to secure permitting.
- Hybrid:Dual-mode architectures switch between dry and evaporative operation based on ambient wet-bulb temperature, optimizing water use without sacrificing peak-load capacity. Northern Virginia facilities are deploying these configurations where seasonal humidity swings demand operational flexibility.
- Water-Cooled:Shell-and-tube or plate heat exchanger designs leveraging cooling tower circuits dominate legacy industrial installations.
- Oil-Cooled:Specialized dielectric fluid configurations serve transformer and high-voltage equipment cooling in utility substations.
The dominant share belongs to Air-Cooled, while Hybrid is closing the gap fastest.
Technology:
Adoption velocity splits between mature evaporative methods and emerging adiabatic systems that promise water savings without dry cooling energy penalties.
- Adiabatic:Pre-cooling modules humidify incoming air upstream of dry coils, extending free-cooling hours and trimming peak power draw. Singapore data centers mandate these systems under tropical efficiency codes, with equipment suppliers embedding humidity sensors for automated mode switching.
- Evaporative Cooling:Direct or indirect wet-surface heat rejection remains the baseline for cost-sensitive chemical processing and food manufacturing, though water scarcity is narrowing its addressable market.
- Direct Expansion:Refrigerant-based cooling circuits serve smaller commercial loads and retrofit applications where infrastructure constraints block fluid loop installation.
- Indirect Cooling:Decoupled heat exchanger arrangements separate process fluids from ambient air via intermediate glycol or water-glycol loops, protecting sensitive equipment from contamination.
Evaporative Cooling retains volume leadership, yet Adiabatic is expanding most quickly as water stress intensifies across industrial clusters.
End User:
Procurement sophistication varies widely, with power utilities and hyperscale operators driving specification standardization while fragmented food manufacturing accepts distributor-led equipment selection.
- HVAC:Building thermal management applications span commercial offices, healthcare facilities, and educational institutions, with specification influenced by ASHRAE standards and local energy codes. Carrier and Trane dominate this channel through contractor relationships.
- Power Generation:Combined-cycle gas turbine plants and thermal solar facilities require massive heat rejection capacity with guaranteed availability, favoring engineered-to-order systems with long-term service contracts.
- Chemical Processing:Corrosion-resistant materials and hazardous area certifications constrain supplier pools for refinery and petrochemical applications.
- Food & Beverage:Cold chain and brewing operations prioritize rapid defrost cycles and hygienic design over thermal efficiency optimization.
HVAC commands the largest equipment volume, though Power Generation delivers the highest project margins.
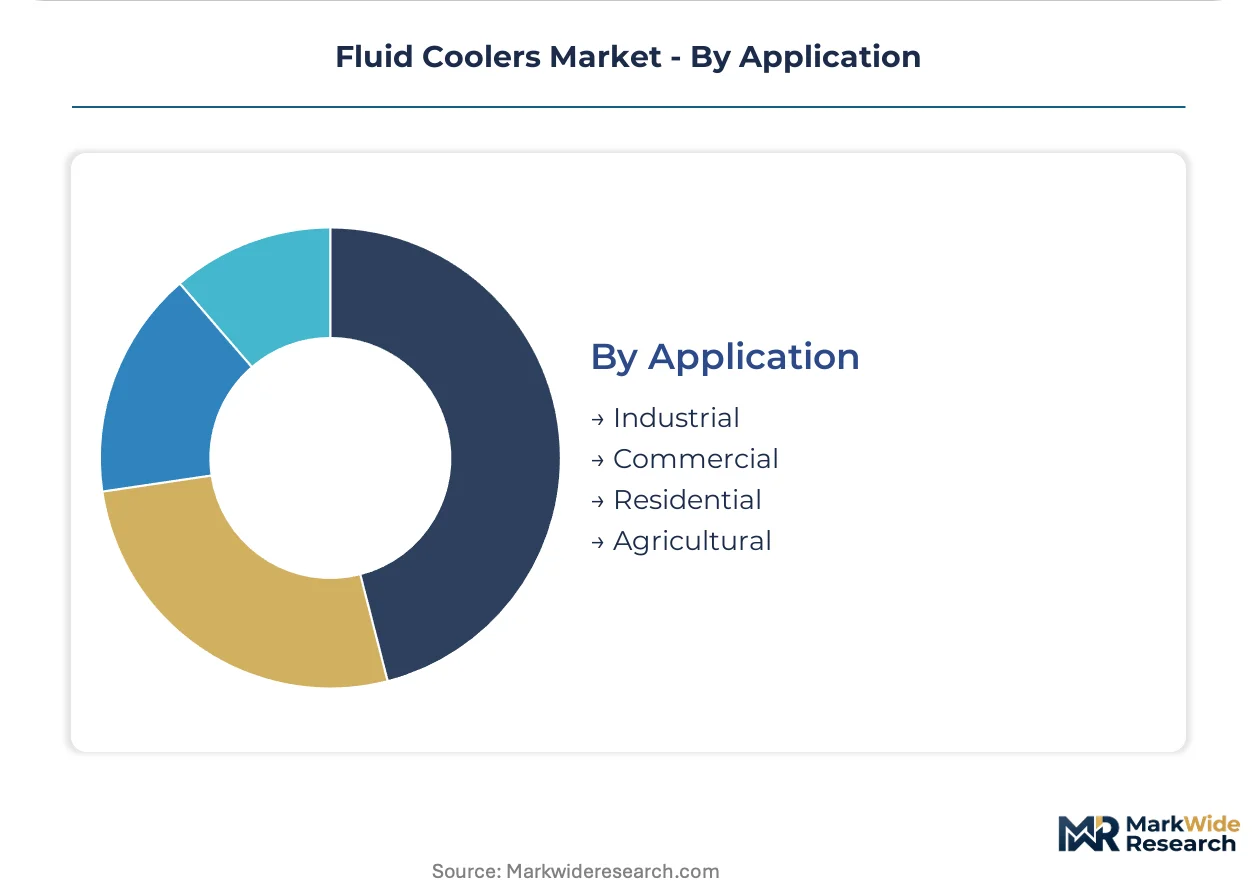
Application:
Site constraints and ownership structures shape equipment lifecycle economics, with industrial buyers accepting higher capital outlays for durability while commercial landlords prioritize lease-compatible footprints.
- Industrial:Continuous-duty process cooling demands redundant capacity and predictive maintenance protocols, with buyers negotiating total-cost-of-ownership contracts spanning 15-20 year horizons.
- Commercial:Retail, office, and hospitality installations favor modular units with rapid commissioning timelines to minimize revenue disruption during tenant improvements.
- Residential:Distributed cooling for multi-family housing and luxury estates represents a niche segment with limited supplier participation.
- Agricultural:Greenhouse climate control and livestock facility ventilation applications stress corrosion resistance and debris tolerance over thermal precision.
Industrial applications anchor supplier revenue, while Commercial is gaining share fastest through data center co-location and build-to-suit development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German heat exchanger specialists export precision-engineered components to United States data center developers, establishing a transatlantic supply corridor that channels European manufacturing expertise into North American hyperscale deployment.
United States
Texas and Arizona hyperscale clusters drive procurement of adiabatic and hybrid cooling systems as municipal water restrictions tighten. The EPA's AIM Act refrigerant phasedown accelerates retrofit cycles across existing industrial installations. Northern Virginia data center corridors negotiate direct supply agreements with thermal management vendors outside conventional bidding channels.
Germany
Industrial refrigeration demand from chemical processing and automotive manufacturing sustains engineered-to-order fluid cooler production. The EU F-Gas Regulation mandates transition timelines that accelerate specification of alternative cooling architectures. The Ruhr industrial basin and Bavarian manufacturing zones concentrate heat exchanger component fabrication for export markets.
China
Data center construction in the Yangtze River Delta and Pearl River Delta regions absorbs modular cooling systems for cloud computing expansion. National dual carbon goals under MEE oversight push operators toward water-efficient thermal rejection technologies. Beijing-Tianjin-Hebei corridor facilities face intensifying efficiency mandates under GB standards compliance.
India
Pharmaceutical and chemical processing expansion in Maharashtra and Gujarat generates process cooling demand under BIS efficiency mandates. The PLI scheme for manufacturing incentivizes localized production of industrial thermal equipment. Telangana and Karnataka data center clusters emerge as specification drivers for adiabatic cooling in water-stressed southern states.
Singapore
Tropical data center efficiency codes mandate adiabatic pre-cooling modules with automated humidity sensing for free-cooling optimization. The country's national environmental regulator enforces strict water conservation standards on industrial thermal rejection systems. The Jurong and Changi industrial zones concentrate deployment of compact-footprint fluid coolers where land scarcity constrains equipment sizing.
Fluid Coolers Market Competitive Landscape
Listed leaders compete with private specialists across capital access and customization agility. The vendor base spans multinational HVAC conglomerates, European heat exchanger fabricators, and regional industrial cooling contractors. Three archetypes dominate: technology-integrated system houses, component-specialized fabricators, and emerging market service-network operators. Consolidation pressure favors M&A activity among mid-scale regional players, while capacity expansion concentrates in India and Southeast Asian manufacturing nodes.
Within the technology-integrated tier, Carrier represents system-house consolidation across adiabatic and hybrid architectures for hyperscale facilities. Kelvion Holding GmbH anchors German precision engineering in heat exchanger specialization for industrial process applications. Thermax occupies a position exemplifying emerging market service-network operators that combine localized manufacturing with predictive maintenance contracts. These three entities illustrate divergent strategic paths: direct specification relationships with data center developers, engineered-to-order industrial project execution, and aftermarket service attach-rate maximization in price-sensitive geographies.
| Leading Market Players |
|---|
| Valvoline Global Operations |
| Thermax |
| Shell plc |
| Piovan S.p.A. |
| Carrier |
| The Chemours Company |
| Exxon Mobil Corporation |
| Kelvion Holding GmbH |
| Dow Inc. |
| Others |
Value Network & Pricing Analysis
Aluminum fin-stock substitution for copper tubing in microchannel coil assemblies simultaneously shifts procurement geography toward Chinese rolling mills and compresses heat exchanger pricing premiums across North American fluid cooler assembly. This materials transition concentrates supply risk in single-source metallurgical processing while eroding the cost advantage that incumbent coil fabricators previously extracted from proprietary forming techniques.
Pricing Analysis
Next-generation adiabatic modules command 35-50% premiums over conventional evaporative baselines, while prior-generation dry cooling systems face accelerated price erosion as hyperscale procurement consolidates. Three-tier pricing structure across premium adiabatic, standard hybrid, and economy evaporative levels stratifies by water-efficiency certification tier and peak-load thermal guarantee. Cost compression in the evaporative tier intensifies because municipal water restrictions disqualify these systems from an expanding share of permitting applications. Chemical processing buyers exhibit highest price sensitivity due to commoditized process cooling requirements, whereas data center developers prioritize thermal reliability over unit economics.
Supply Chain Analysis
Strategic stockpiling of copper tube and aluminum fin-stock dominates procurement behavior among North American fluid cooler OEMs confronting rolling mill allocation constraints and ocean freight volatility. Heat exchanger manufacturing draws from Chinese aluminum rolling capacity, German precision tube forming, and domestic coil fabrication in Texas and Ohio. Single-source vulnerability concentrates in specialized adiabatic pad media sourced from Japanese ceramic fiber producers. Distribution runs through direct specification relationships with hyperscale developers, bypassing traditional mechanical contractor channels in Arizona, Texas, and Northern Virginia data center corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale data center procurement consolidation into direct vendor relationships has shifted bargaining power decisively toward buyers, compressing qualification timelines and squeezing margin capture across equipment tiers.
For Market Incumbents: Compound technology leadership in adiabatic and hybrid architectures by embedding humidity-sensor automation and mode-switching intelligence that emerging competitors cannot replicate without thermal-fluid engineering depth. Defend against Chinese OEM encroachment through captive supply of microchannel coil fabrication in domestic manufacturing nodes. Prioritize backward integration into aluminum fin-stock forming to insulate margins from Shanghai Futures Exchange volatility.
For New Entrants and Emerging Players: Anchor in India pharmaceutical and chemical processing demand under BIS efficiency mandates where localized aftermarket service networks create stickier relationships than equipment-only competition. Target Telangana and Karnataka data center clusters for adiabatic specification where water stress exceeds incumbent service coverage. Pursue joint development agreements with European heat exchanger fabricators to shortcut thermal engineering capability gaps.
For Investors and Strategic Acquirers: The market sits at a refrigerant-transition phase that favors component-specialized fabricators with proven low-global-warming-potential fluid compatibility over system-integrators locked into legacy architectures. Long-term viability centers on heat exchanger technology IP rather than assembly scale. Acquisition candidates should demonstrate predictive maintenance contract attach rates above 40% in industrial process cooling. Watch EPA AIM Act enforcement acceleration as the inflection signal that compresses replacement cycles and expands addressable retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Adiabatic Technology Licensing | Carrier's patent portfolio in pre-cooling modules enables royalty streams from Asian OEMs seeking EPA-compliant architectures. |
| Backward Integration into Aluminum Fin-Stock | Kelvion's captive rolling mill investment in Ruhr basin insulates margin from LME price swings and Chinese export quotas. |
| Localized Manufacturing in India | Thermax's Maharashtra assembly expansion captures PLI scheme incentives while shortening lead times for Gujarat chemical processors. |
| Predictive Maintenance Platform Development | Sensor-embedded fluid coolers generate recurring revenue streams through thermal performance monitoring contracts with power utilities. |
| EU F-Gas Regulatory Compliance Certification | CE marking for low-global-warming-potential compatibility unlocks specification in German automotive and chemical cooling procurement. |
Research Methodology
Operator-level perspectives from data center thermal engineers, chemical plant maintenance directors, power utility cooling system procurement leads, and HVAC contractor estimators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA AIM Act rulemaking dockets, ASHRAE technical guideline publications, SEC 10-K filings from listed HVAC conglomerates, and customs data on heat exchanger component trade flows. Bottom-up equipment shipment triangulation against top-down infrastructure capex disclosures from hyperscale operators ensured dimensional consistency across modeling approaches.
Sensitivity analysis tested forecast robustness against aluminum price volatility scenarios, EPA refrigerant phasedown acceleration cases, and data center deployment timing variations across the projection horizon. Segmentation modeling spanned cooling architecture type, technology generation, end-use industry vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, greenfield capacity absorption rates, and technology substitution elasticity parameters. Thermal load density projections from AI server deployment informed hyperscale segment sizing.
Material uncertainties — EPA enforcement intensity, copper-aluminum substitution velocity, and hyperscale procurement channel consolidation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding refrigerant transition timelines and municipal water restriction diffusion patterns. Revision becomes warranted when EPA AIM Act rulemaking accelerates hydrofluorocarbon availability contraction beyond baseline scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Thawing System Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Cold Trap Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
North America Evaporative Cooling Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Global Condensing Unit Market