
 Evaporative Cooling Tower Market | 2026-2036
Evaporative Cooling Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Evaporative Cooling Tower Market Intelligence
The United States EPA's stringent water discharge and consumption regulations are consolidating the market toward closed-loop and hybrid systems with higher upfront costs. SPX Cooling Technologies leverages its extensive portfolio of water-conserving designs to meet these new performance benchmarks. Baltimore Aircoil Company specializes in hybrid cooler technology, gaining share in water-scarce regions. Meanwhile, Thermax sustains a strong position in developing economies through its focus on cost-effective, locally manufactured units for industrial clients.
An evaporative cooling tower is a specialized heat rejection device that extracts waste heat to the atmosphere through the cooling of a water stream to a lower temperature. The process relies on the principle of evaporative cooling, where a small portion of the water evaporates, lowering the temperature of the remaining circulating water. HVAC systems and industrial processes represent the largest application segments, demanding consistent and reliable performance. Within product types, counterflow designs offer higher efficiency and a smaller footprint, while hybrid towers are gaining traction for their water-saving capabilities.
Regulatory frameworks such as the EU's REACH directive for chemical substances in water treatment and China's national GB standards for energy efficiency govern product specifications. These regulations directly influence material selection, particularly for corrosion resistance and legionella control, and set minimum performance levels for market entry. Stakeholders must now decide between investing in higher-cost, water-efficient hybrid technologies or optimizing traditional designs for specific regional compliance.
Market Dynamics
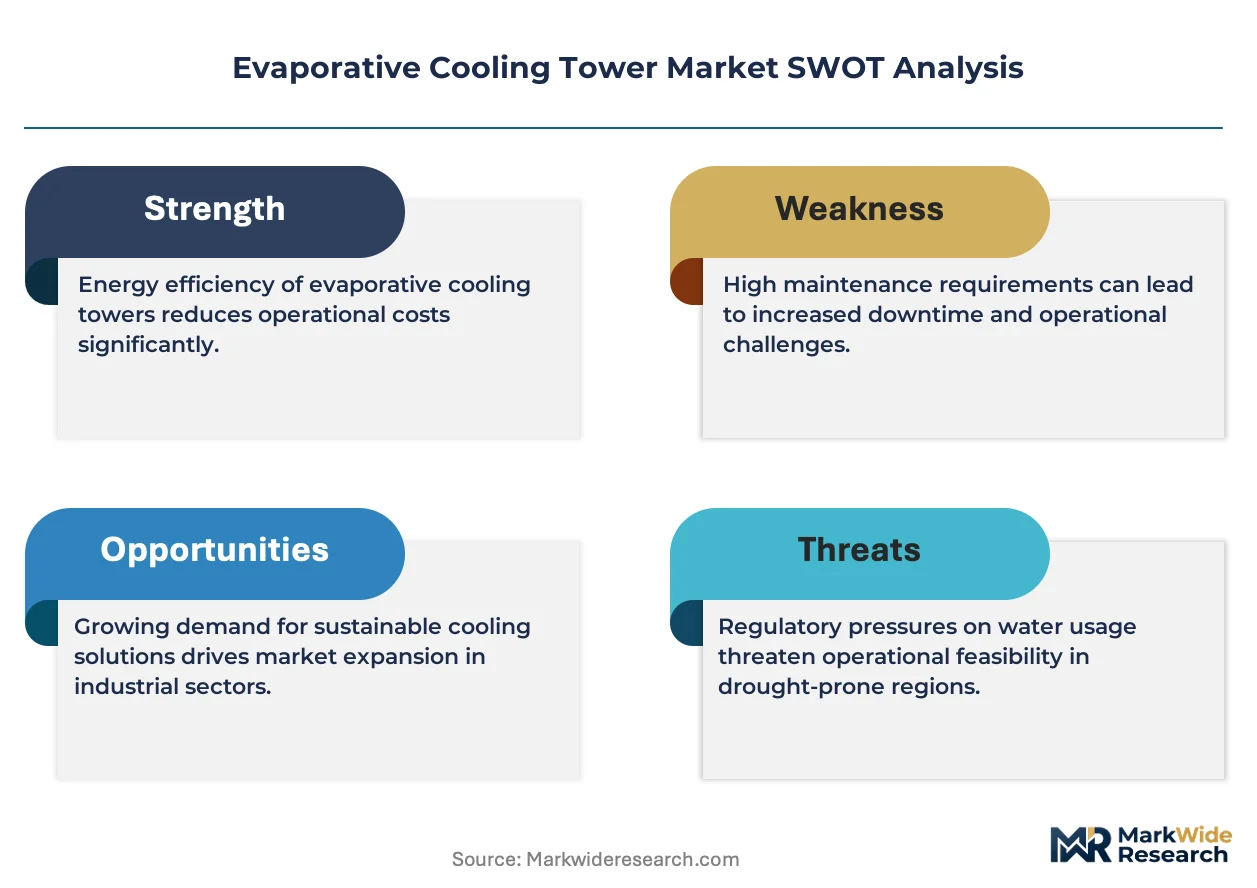
The convergence of stringent water conservation mandates and rising energy costs in developed economies is the central force shaping the evaporative cooling tower market. This pressure compels a technological pivot towards higher-efficiency closed-loop and hybrid systems, altering the competitive landscape.
Growth Catalysts
- Power Sector Expansion:Sustained investment in thermal and geothermal power generation, particularly in Asia-Pacific, requires high-capacity cooling towers to manage significant waste heat loads, directly stimulating new unit installations.
- Industrialization in Developing Economies:Rapid industrial growth in countries like India creates consistent demand for cost-effective, open-loop cooling towers for manufacturing, chemical processing, and food production facilities.
- Water Treatment Regulations:The EU's REACH directive governing chemical use in water treatment incentivizes the adoption of towers constructed with corrosion-resistant materials that require less aggressive chemical maintenance programs.
Market Restraints
- High Upfront Capital Costs:The initial investment for water-efficient hybrid and closed-loop cooling towers is substantially higher than for traditional open-loop designs, acting as a barrier for budget-constrained industrial operators.
- Performance in Arid Climates:The efficiency of evaporative cooling fundamentally diminishes in regions with high ambient humidity or severe water scarcity, limiting its applicability and favoring alternative dry cooling technologies.
- Complex Regulatory Compliance:Navigating disparate national standards, such as China's GB standards for energy efficiency and the US EPA's water discharge rules, increases design, testing, and compliance costs for manufacturers.
Strategic Opportunities
- Retrofit and Modernization:A large installed base of aging cooling towers in North America and Europe presents a significant opportunity for retrofitting with high-efficiency fills, drift eliminators, and variable speed drives to meet new performance standards.
- Hybrid Technology for Data Centers:The need for precise, year-round temperature control in data centers creates a prime opportunity for advanced hybrid towers that can switch between evaporative and dry cooling modes to optimize water and energy use.
- Geographic Expansion in Southeast Asia:Growing industrial and power generation investments in nations like Vietnam and Indonesia represent an underpenetrated market for both standard and high-efficiency cooling tower installations.
Industry Challenges
- Legionella Risk Management:The persistent risk of Legionella bacteria growth requires rigorous and costly maintenance, water treatment, and monitoring protocols, posing a continuous operational and liability challenge for facility owners.
- Skilled Technician Scarcity:Servicing and optimizing modern, digitally controlled hybrid cooling systems requires technicians with specialized HVAC, electrical, and water chemistry expertise, a skill set currently in short supply.
- Integration with Legacy Systems:Integrating advanced, automated cooling towers with older, analog-based plant control infrastructure presents significant technical challenges and can require expensive control system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evaporative Cooling Tower Market |
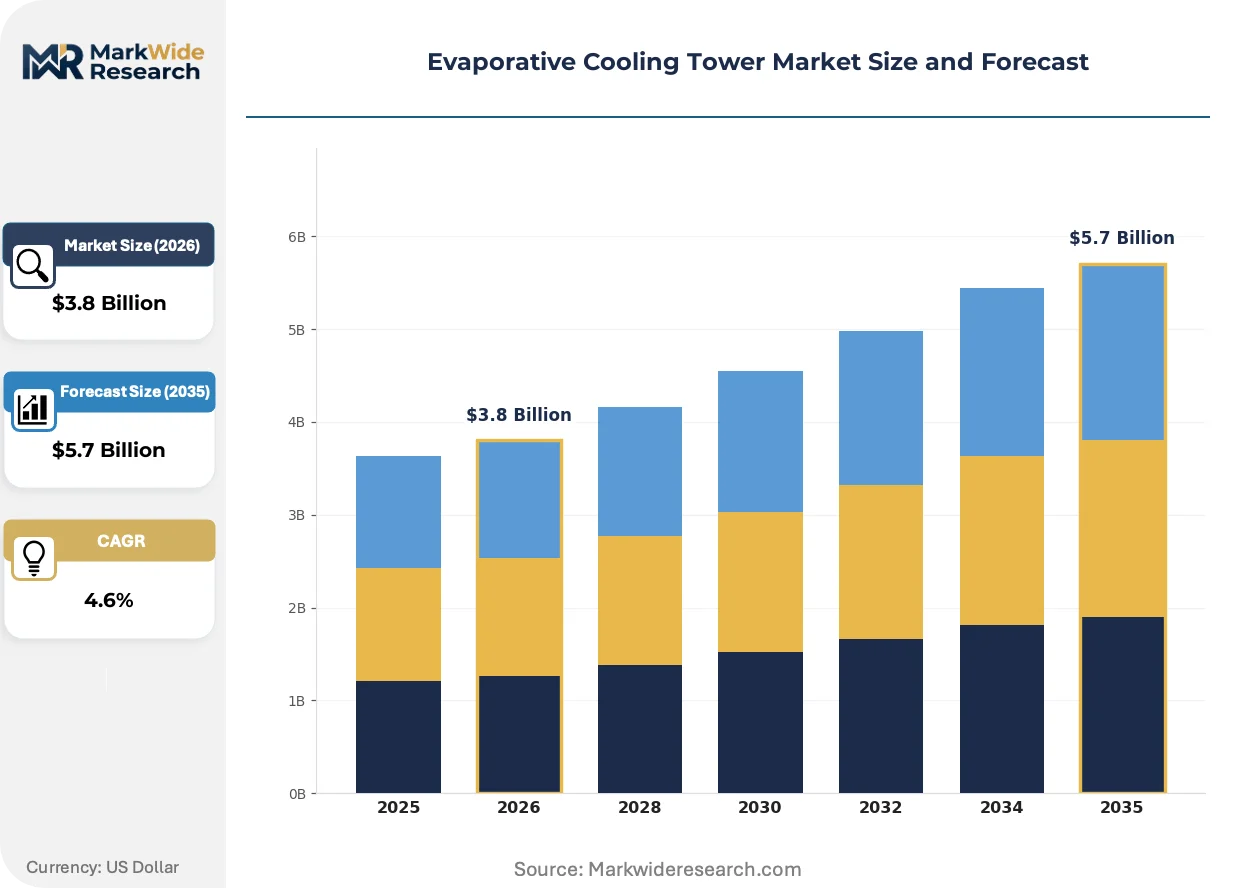
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crossflow, Counterflow, Hybrid, Natural Draft Application: Industrial Processes, HVAC Systems, Power Generation, Food Processing End User: Manufacturing, Oil & Gas, Chemical, Pharmaceutical Material: Fiberglass, Steel, Concrete, Aluminum |
| Companies Covered | Johnson Controls, ENGIE, SPX Cooling Technologies, Enexio, John Cockerill, Baltimore Aircoil Company, Thermax, Paharpur Cooling Towers, EVAPCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evaporative Cooling Tower Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of intelligent controls and advanced materials to solve the core conflict between thermal performance and resource conservation. This shift prioritizes lifecycle operational costs over upfront capital expenditure, favoring more sophisticated system designs.
Advanced non-metallic materials, such as polypropylene and pultruded fiberglass reinforced plastic (FRP), are increasingly used for key components like fill, drift eliminators, and even structural elements. Industrial facilities in corrosive environments, including chemical plants and coastal power stations, are the primary adopters. The use of these inert materials is rewriting the traditional maintenance and replacement cycle, significantly extending asset life and reducing long-term operational costs compared to galvanized steel units.
European Union regulations, specifically the F-Gas Regulation aimed at phasing down hydrofluorocarbons, indirectly influence cooling tower selection. This policy forces facilities to evaluate their entire thermal management system, often increasing the appeal of efficient evaporative or hybrid cooling solutions as an alternative to refrigerant-intensive chillers. The commercial HVAC sector in Europe is most affected, driving innovation in integrated systems that balance chiller and tower operation for maximum efficiency and regulatory compliance.
A notable demand-side shift involves the adoption of performance-based service contracts focused on guaranteed water and energy efficiency. This model disrupts the traditional transactional sale of equipment, replacing it with long-term partnerships that bundle monitoring, maintenance, and optimization services. This trend is most prominent for large-scale cooling requirements in data centers and healthcare campuses across North America, where predictable operational expenditure is critical.
Evaporative Cooling Tower Market Segmentation
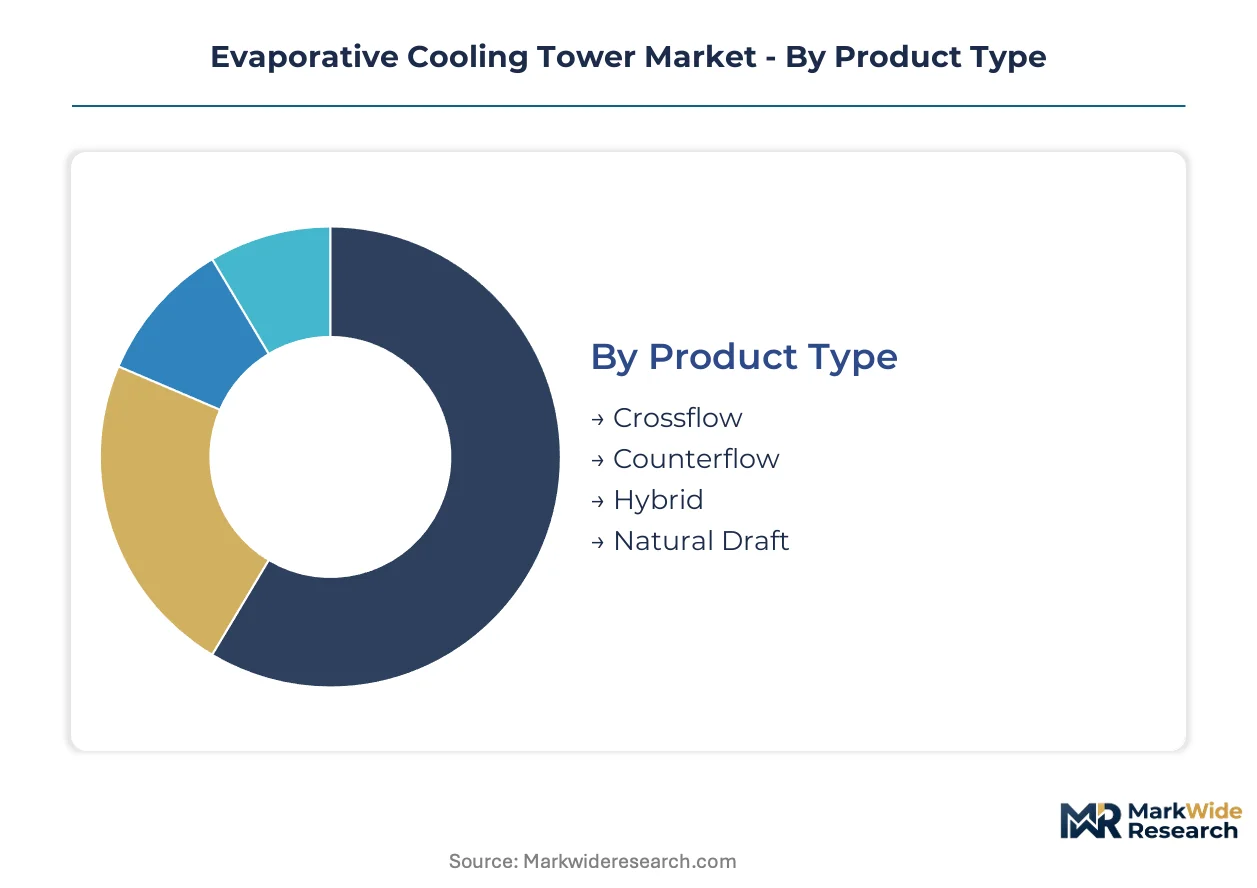
The evaporative cooling tower market's segmentation reveals diverse product designs and end-use requirements. Understanding these categories is crucial for manufacturers to tailor solutions and for operators to optimize thermal management strategies. This analysis highlights key differentiators influencing market dynamics.
Product Type:
Supply concentration in product type reflects specialized manufacturing capabilities and design patents.
- Hybrid:These systems integrate both evaporative and dry cooling coils, allowing for water conservation during cooler ambient conditions. Demand from data centers in North America is rising, driven by the need for precise temperature control and water efficiency mandates.
- Counterflow:Characterized by air flowing upward opposite to the downward water spray, counterflow designs achieve higher thermal efficiency and require a smaller footprint. Industrial facilities in Germany increasingly adopt these for space-constrained environments and energy optimization.
- Crossflow:Air flows horizontally across the falling water, offering easier maintenance access and lower static pressure.
- Natural Draft:These large, hyperboloid structures use natural convection for cooling, primarily in large-scale power generation.
Today's leader: Counterflow. Tomorrow's challenger: Hybrid.
Application:
Applications for evaporative cooling towers span critical sectors, each with distinct operational demands.
- Power Generation:This segment requires high-capacity cooling solutions to dissipate significant waste heat from thermal and geothermal power plants. Asia-Pacific countries, particularly India, are seeing substantial installations due to sustained energy infrastructure investment.
- HVAC Systems:Evaporative cooling towers provide efficient heat rejection for large commercial and institutional buildings, maintaining comfortable indoor climates. European commercial real estate developers prioritize these for energy efficiency and compliance with regional sustainability standards.
- Industrial Processes:Cooling towers support various manufacturing operations, including chemical processing and metal fabrication.
- Food Processing:This sector uses cooling towers for temperature control in production and refrigeration systems, ensuring product quality.
Power Generation represents the fastest-growing trajectory, while HVAC Systems maintain consistent demand.
End User:
End-user segments reflect specialized cooling requirements and regulatory compliance needs across diverse industries.
- Manufacturing:This broad segment encompasses various industrial facilities requiring process cooling for machinery and production lines. Cost-effective, open-loop towers are prevalent in developing economies like Vietnam to support rapid industrial expansion.
- Chemical:Chemical plants utilize cooling towers for exothermic reaction control and condensation processes, often demanding corrosion-resistant materials due to aggressive operating environments. The US chemical industry focuses on closed-loop systems to meet stringent water discharge regulations.
- Oil & Gas:Cooling towers are essential for gas compression, refining, and petrochemical processes in upstream and downstream operations.
- Pharmaceutical:This sector uses precise cooling for drug manufacturing and laboratory environments, prioritizing reliability and sterility.
The Manufacturing sector drives significant volume, with the Chemical industry demonstrating a shift towards specialized solutions.
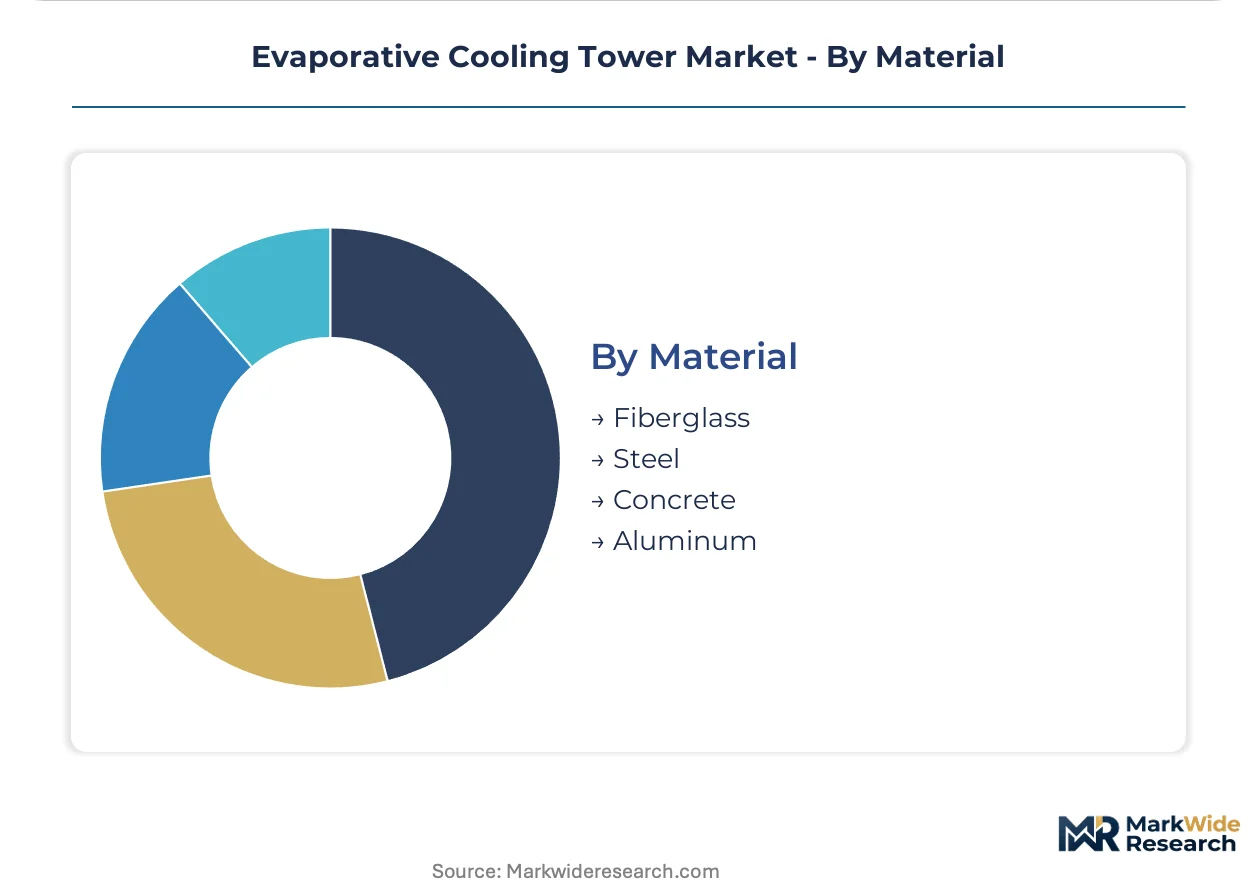
Material:
Material selection for cooling towers depends on operational environment, lifespan expectations, and upfront cost considerations.
- Fiberglass:Pultruded fiberglass reinforced plastic (FRP) offers excellent corrosion resistance and lightweight properties, extending asset life in aggressive industrial settings. Coastal power stations in Southeast Asia increasingly adopt FRP for durability against saline environments.
- Steel:Galvanized and stainless steel are traditional materials, valued for their structural strength and cost-effectiveness in many applications. North American HVAC installations frequently employ steel towers, balancing performance with initial investment.
- Concrete:Concrete towers are durable and suitable for very large, long-life installations, common in large power generation facilities.
- Aluminum:Lightweight aluminum components are used in specific designs, offering good corrosion resistance in certain environments.
Fiberglass is gaining share fastest due to its corrosion resistance, while Steel remains a foundational material choice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled engineering talent in key industrial hubs anchors demand for advanced evaporative cooling solutions across diverse global markets. These regions lead in adopting energy-efficient and water-conserving technologies for critical infrastructure. Regulatory pressures and industrial expansion drive localized market growth.
United States
The United States' substantial data center expansion and robust power generation sector drive demand for high-efficiency cooling towers. EPA's stringent water discharge and consumption regulations compel adoption of closed-loop and hybrid systems. California's tech industry invests in advanced hybrid technologies for optimized water and energy use.
Germany
Germany's advanced manufacturing base and energy-efficient commercial HVAC sector require precise thermal management. The EU's F-Gas Regulation indirectly influences cooling tower selection, favoring efficient evaporative alternatives. Industrial facilities across Bavaria adopt high-efficiency counterflow designs to meet strict energy optimization targets.
India
India's significant investment in thermal power generation and rapid industrialization create substantial demand for new cooling tower installations. Government initiatives like the PLI scheme support manufacturing growth, driving the need for cost-effective systems. Industrial clusters in Maharashtra represent a strong market for locally manufactured units.
China
China's vast power generation capacity and expanding industrial base consistently require high-capacity evaporative cooling solutions. The nation's GB standards for energy efficiency directly influence product specifications, promoting higher performance levels. Manufacturers in the Yangtze River Delta region focus on developing towers complying with these rigorous national benchmarks.
Vietnam
Vietnam's robust industrial expansion and growing power generation investments create significant opportunities for cooling tower installations. National industrial development policies support manufacturing, increasing demand for both standard and high-efficiency systems. Manufacturing zones near Ho Chi Minh City are experiencing substantial installations for new production facilities.
Evaporative Cooling Tower Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the evaporative cooling tower market. The market exhibits a tiered structure, with global players offering comprehensive solutions alongside regional manufacturers specializing in cost-effective units. Strategic archetypes include integrated thermal management providers, niche water-conservation innovators, and volume-driven industrial suppliers. Companies prioritize portfolio diversification and strategic partnerships to enhance market reach and technological capabilities.
Within the specialized equipment segment, SPX Cooling Technologies exemplifies a global provider leveraging an extensive portfolio of water-conserving designs. Baltimore Aircoil Company occupies a strong position as a hybrid cooler technology specialist, gaining share in water-scarce regions. Thermax, an India-based firm, represents a key player in developing economies through its focus on cost-effective, locally manufactured units for industrial clients. These companies anchor different market segments, from high-performance applications to budget-conscious industrial installations, shaping the competitive dynamics.
| Leading Market Players |
|---|
| Johnson Controls |
| ENGIE |
| SPX Cooling Technologies |
| Enexio |
| John Cockerill |
| Baltimore Aircoil Company |
| Thermax |
| Paharpur Cooling Towers |
| EVAPCO |
| Others |
Cost & Logistics Intelligence
Vertical integration by large cooling tower manufacturers anchors their supply position and grants significant pricing power, particularly for complex, high-capacity systems required by global power generation projects.
Pricing Analysis
Bundled service contracts, integrating equipment, monitoring, and maintenance, define pricing for advanced cooling tower systems in North America. Project-based pricing dominates for large industrial installations, with differentiation based on specific energy efficiency certifications and material corrosion resistance. Pricing softness stems from intense competition among manufacturers for cost-effective units in developing economies like India. Industrial buyers in manufacturing sectors exhibit higher price sensitivity compared to data center operators prioritizing uptime and water efficiency.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks for large-scale cooling tower projects. Supply concentration for specialized fiberglass and steel components centers on manufacturers in China, India, and Germany. The industry sources advanced controls and pumps from global electronics and fluid dynamics specialists. Commodity price volatility for steel and plastics presents a structural supply chain risk. Distribution runs through a network of regional engineering firms and authorized equipment dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The evaporative cooling tower market offers margin expansion opportunities driven by the premium-tier shift towards advanced hybrid and closed-loop systems. These high-efficiency solutions command better pricing due to their water and energy saving capabilities.
For Market Incumbents: To counter the threat of niche innovators specializing in hybrid technology, established players must invest heavily in R&D for next-generation water-efficient designs. Expanding capacity in Southeast Asian manufacturing hubs provides a strategic defensive move against regional cost-competitive suppliers. Deepening vertical integration into advanced material production, like pultruded FRP, enhances quality control and reduces input costs.
For New Entrants and Emerging Players: Advanced sensor integration and AI-driven predictive maintenance platforms create a technology-first wedge into the data center cooling market. Targeting the retrofit and modernization segment in North America, which has an aging installed base, represents a penetrable white space. A go-to-market angle focused on guaranteed water and energy savings, leveraging real-time data, will resonate with facility owners.
For Investors and Strategic Acquirers: Roll-up economics work for specialized cooling tower service providers because of market fragmentation in maintenance and optimization. Long-term viability for the sector remains strong over the next decade, driven by industrialization and climate regulations. Acquisition targets should be niche players with proprietary hybrid technologies or strong regional service networks in Europe. The signal to watch is the increasing adoption rate of performance-based contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Advanced Hybrid Materials | Develops lighter, more corrosion-resistant components, reducing operational costs for chemical plants. |
| Expansion into Southeast Asian Manufacturing | Captures growing demand from industrialization in Vietnam and Indonesia for cost-effective units. |
| Acquisition of Digital Control Specialists | Integrates smart monitoring and optimization capabilities, enhancing system efficiency for data centers. |
| Retrofit Program for Aging Infrastructure | Addresses compliance needs for older cooling towers in North America with modern water-saving technologies. |
| Performance-Based Service Contract Offering | Shifts revenue model towards long-term partnerships, ensuring predictable operational expenditure for healthcare campuses. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary research involved discussions with plant engineers, procurement managers, HVAC system integrators, and regulatory compliance officers. Secondary data sources included industry association reports, government energy statistics, and company financial filings. A bottom-up and top-down triangulation approach ensured data consistency.
Segment-weighting approaches were applied to project market evolution across the analysis window, considering product type, application, end-user, and material. CAGRs were derived by analyzing historical trends and projected growth drivers. Key industry-specific forecast inputs included power generation capacity additions and water efficiency mandate timelines. The analytical framework integrated macroeconomic indicators with technological adoption rates.
The model holds under current regulatory and economic conditions; deviation in global industrial investment or water policy stringency would shift projections. Forecasts reflect assumptions documented regarding technological advancements and raw material availability. Deviation in these factors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Chilled Water Storage System Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Industrial Radiators Market