
 Cryogenic Systems Market | 2026-2036
Cryogenic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Systems Market Outlook
China is tilting toward large-scale industrial gas production capacity. Chart Industries leverages backward integration into cryogenic tank manufacturing to control cost structures. Linde plc anchors European healthcare demand through specialized medical imaging infrastructure. Air Liquide competes on liquefaction technology leadership across energy and aerospace segments.
Cryogenic systems encompass engineered equipment that maintains temperatures below minus 150 degrees Celsius through controlled refrigeration cycles, thermal insulation, and specialized fluid handling. These systems liquefy industrial gases, preserve biological specimens, and enable superconducting applications across scientific and commercial domains. Cryogenic tanks capture the dominant margin pool due to capital intensity and certification barriers in pressure vessel fabrication. Magnetic refrigeration represents the fastest-expanding technology segment as efficiency standards tighten and helium scarcity intensifies. Space exploration applications attract concentrated R&D investment from government procurement programs and private launch ventures.
The EPA regulates refrigerant emissions under Section 608 of the Clean Air Act, compelling manufacturers toward closed-loop designs and lower-global-warming-potential alternatives. FDA oversight of cryogenic freezers in biologics storage shapes validation protocols and equipment qualification requirements for healthcare end users. ISO 20485 establishes international tightness standards for cryogenic vessels, creating compliance thresholds that filter regional competitors from export markets. Stakeholders must weigh helium supply diversification against magnetic refrigeration capital commitments as regulatory timelines compress.
Market Dynamics
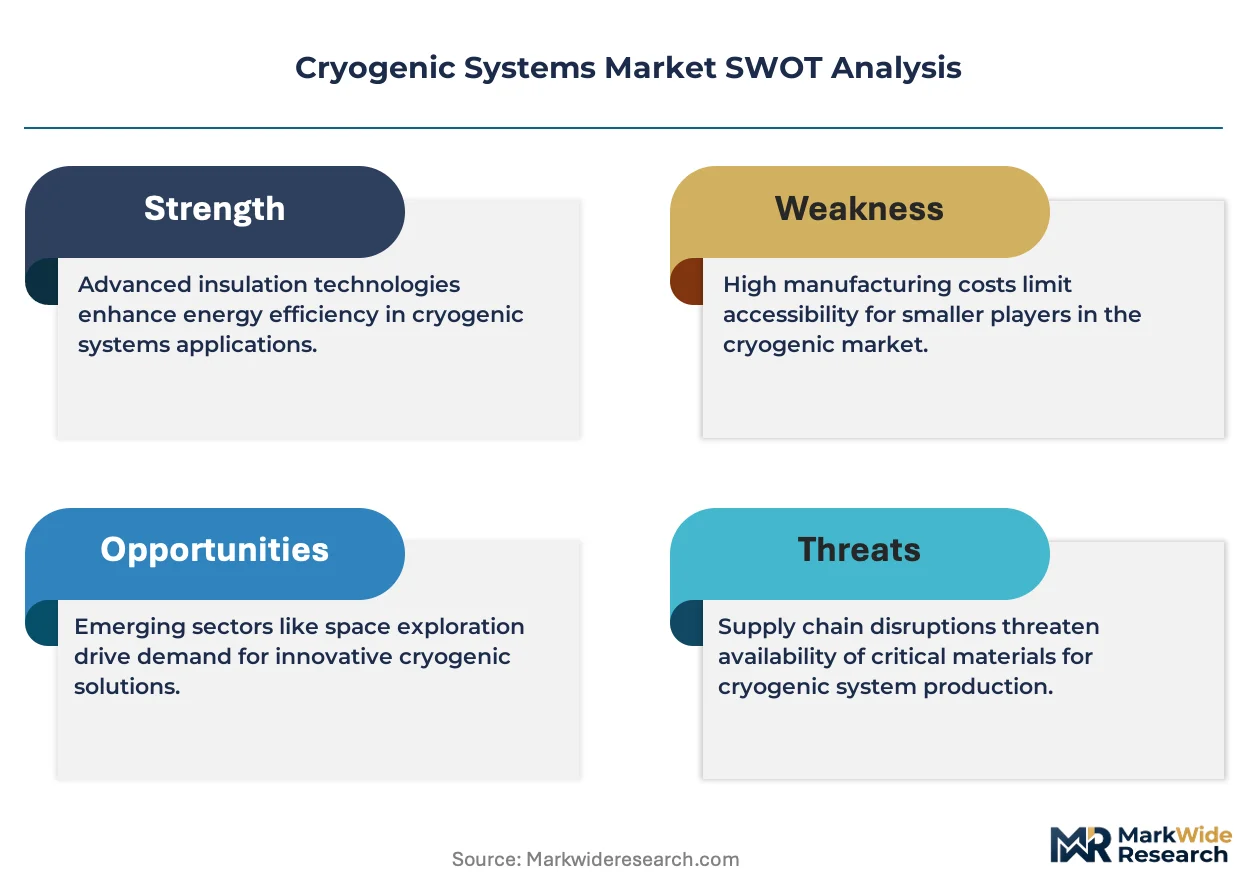
Helium scarcity is compressing supply chains and forcing buyers toward alternative cooling architectures. Magnetic refrigeration gains traction as conventional vapor-compression systems face input cost volatility and regulatory phase-down schedules.
Growth Catalysts
- EU Medical Device Regulation:Germany's healthcare providers are expanding MRI infrastructure under stricter conformity assessment procedures, driving demand for superconducting magnet systems and associated cryogenic cooling equipment.
- Magnetic refrigeration:Japan's METI efficiency mandates are accelerating adoption of magnetocaloric cooling systems in industrial gas liquefaction, displacing conventional helium-based cycles in select applications.
- Pharmaceutical cold chain:India's CDSCO has strengthened distribution guidelines for temperature-sensitive biologics, compelling logistics operators to deploy certified cryogenic transport vessels and storage infrastructure.
Market Restraints
- Helium supply concentration:Qatar and the United States control over three-quarters of global helium production, exposing buyers to export quota volatility and price spikes.
- Pressure vessel certification:ISO 20485 tightness standards and ASME Section VIII compliance create 18-24 month qualification timelines for cryogenic tank manufacturers, filtering regional competitors from export markets.
- Capital intensity:Magnetic refrigeration systems require rare-earth magnet arrays and precision mechanical drives, pushing installed costs above conventional systems by multiples that deter mid-scale adopters.
Strategic Opportunities
- Space exploration:Government procurement programs and private launch ventures in the United States are funding concentrated R&D into propellant densification and in-orbit cryogenic fluid management systems.
- Carbon capture and storage:The EU Green Deal's funding mechanisms for industrial decarbonization are creating demand for cryogenic CO2 separation and liquefaction equipment at emission-intensive facilities.
- Biobanking infrastructure:China's dual carbon goals and biomedical investment priorities are accelerating construction of large-scale specimen preservation facilities using automated cryogenic storage robotics.
Industry Challenges
- Cryogenic engineering talent:The specialized knowledge required for two-phase flow modeling and superinsulation design concentrates in aging workforce cohorts, constraining expansion at equipment manufacturers.
- System integration complexity:Legacy MRI and semiconductor fabrication facilities face extended downtime and validation costs when retrofitting next-generation closed-loop helium recovery architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Systems Market |
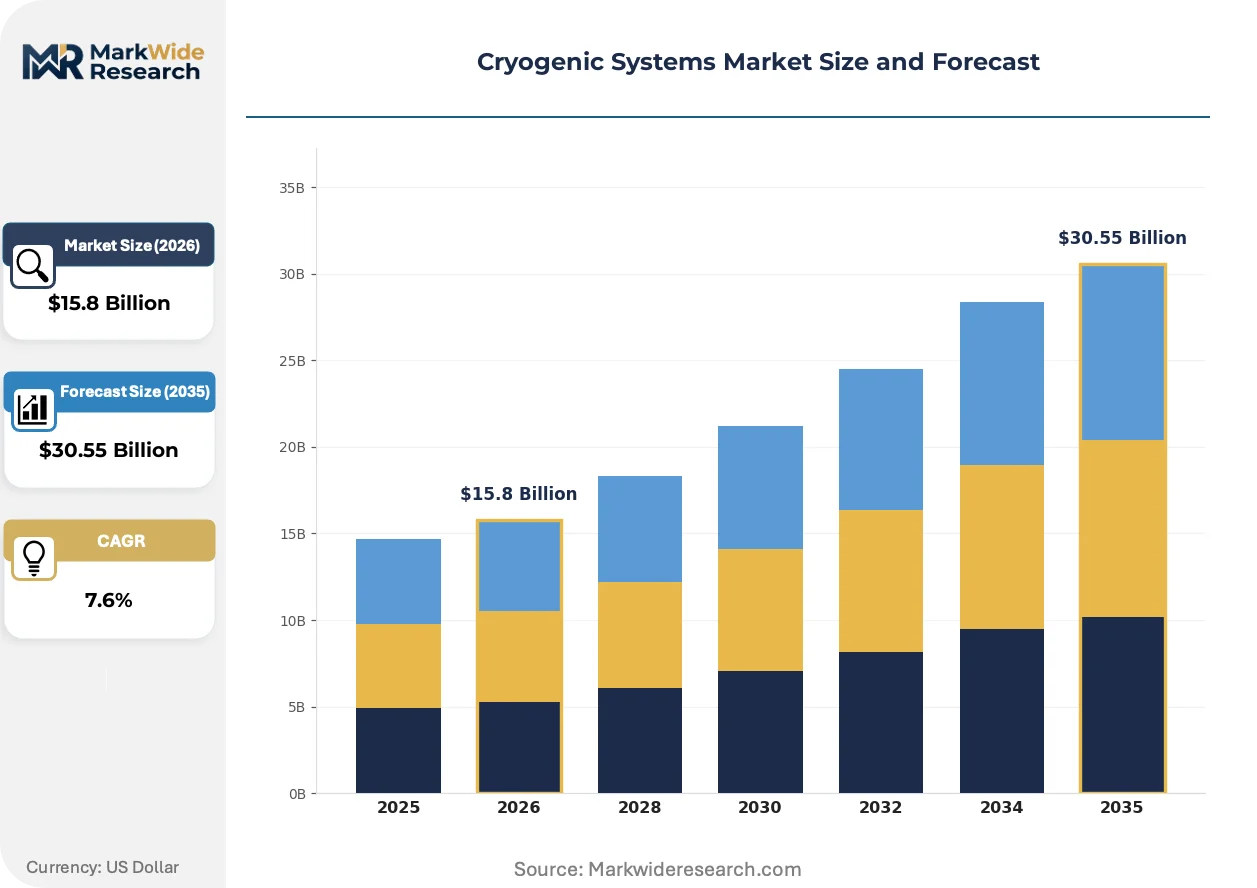
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $30.55 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryogenic Refrigerators, Cryogenic Freezers, Cryogenic Tanks, Cryogenic Valves Technology: Magnetic Refrigeration, Gases Liquefaction, Joule-Thomson Effect, Stirling Cycle Application: Space Exploration, Medical Imaging, Food Processing, Industrial Gas Production End User: Aerospace, Healthcare, Food & Beverage, Energy |
| Companies Covered | Air Products and Chemicals, Flowserve Corporation, Chart Industries, INOX India Limited, Emerson Electric, Linde plc, Nikkiso Co. Ltd., Wessington Cryogenics, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Systems Market Strategic Shifts
Digital twin architectures are virtualizing thermal performance prediction across the equipment lifecycle. This shift compresses design iteration cycles and enables remote diagnostics that reduce field service deployment.
Magnetic refrigeration is virtualizing the role of mechanical compressors in ultra-low-temperature applications. Research consortia in Japan and the Netherlands are piloting magnetocaloric systems for hydrogen liquefaction at 20 Kelvin. The technology is virtualizing capital deployment patterns by enabling modular capacity expansion without helium inventory exposure.
The EPA's Section 608 refrigerant management regulations are tightening leak detection and repair mandates for industrial cooling systems. Equipment manufacturers must redesign service access points and integrate continuous monitoring sensors. Healthcare and aerospace end users in the United States are prioritizing suppliers with closed-loop certification and documented lifecycle refrigerant accounting.
After-sales service contracts are unbundling from equipment sales as buyers demand performance-based thermal uptime guarantees. Independent service organizations are capturing maintenance revenue from original equipment manufacturers by specializing in multi-brand helium recovery system optimization. This shift is most visible in the United States and Germany, where hospital procurement teams are separating capital and operating budgets for MRI infrastructure.
Cryogenic Systems Market Segmentation
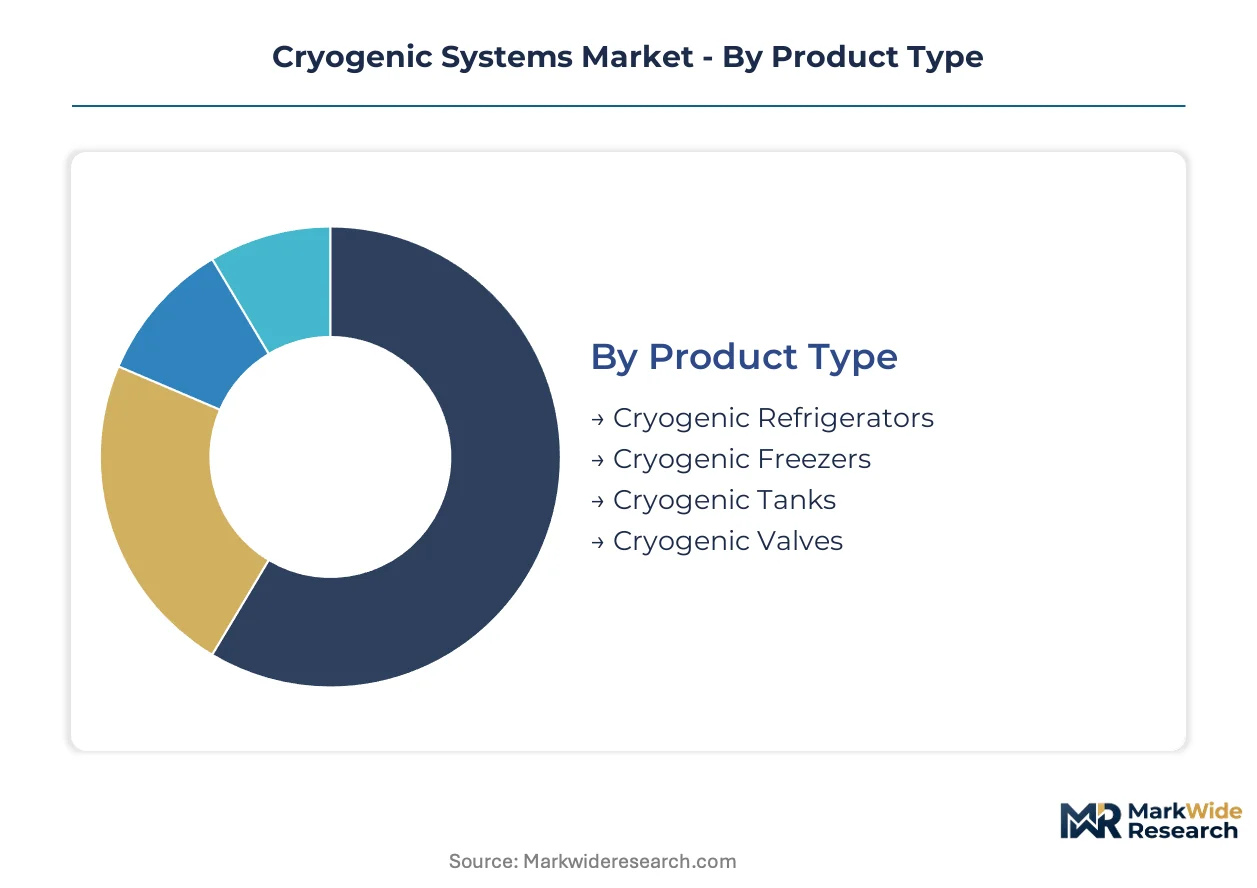
Cryogenic systems serve fundamentally different cycle demands across equipment types, cooling technologies, and end-use verticals. Segmentation reveals where capital intensity concentrates versus where replacement frequency creates recurring revenue pools.
Product Type:
Replacement cycles stretch from 5 years for precision mechanical components to 25 years for certified pressure vessels, creating divergent aftermarket strategies.
- Cryogenic Tanks:Vacuum-insulated pressure vessels store liquefied gases at temperatures below minus 150 degrees Celsius with multi-layer superinsulation. Demand concentrates in Germany's expanding MRI infrastructure under EU Medical Device Regulation helium storage requirements. These assets turn over slowest due to ASME Section VIII certification timelines.
- Cryogenic Refrigerators:Closed-loop systems maintain ultra-low temperatures for biological specimen preservation through vapor-compression or emerging magnetocaloric cycles. India's pharmaceutical cold chain under CDSCO guidelines is driving deployment of transportable units with validated temperature logging.
- Cryogenic Freezers:Upright and chest configurations preserve biologics at minus 80 to minus 196 degrees Celsius with liquid nitrogen or mechanical cooling.
- Cryogenic Valves:Specialized sealing systems manage two-phase flow in transfer lines and storage vessels with extended bonnet designs.
Cryogenic tanks dominate installed base. Cryogenic refrigerators are where expansion concentrates.
Technology:
Capital deployment intensity separates mature thermodynamic cycles from emerging magnetocaloric architectures still scaling manufacturing.
- Magnetic Refrigeration:Magnetocaloric materials generate cooling through cyclic magnetization-demagnetization without helium refrigerants. Japan's METI efficiency mandates are accelerating pilot deployments in industrial gas liquefaction as helium scarcity intensifies.
- Gases Liquefaction:Large-scale systems compress and cool air, natural gas, or hydrogen to liquid states through Claude or Linde-Hampson cycles. China's industrial gas production capacity expansion is absorbing multi-train liquefaction trains with integrated cold box architectures.
- Joule-Thomson Effect:Expansion cooling through throttling valves enables compact cryocoolers for infrared sensors and missile guidance.
- Stirling Cycle:Reciprocating displacer systems achieve cryogenic temperatures with high thermodynamic efficiency in closed regenerative loops.
Gases liquefaction dominates installed base. Magnetic refrigeration is climbing the fastest.
Application:
Project duration and procurement authority differ sharply between government-funded exploration programs and commercial healthcare infrastructure.
- Medical Imaging:Superconducting MRI magnets require continuous liquid helium cooling or closed-loop cryocooler systems. Germany's healthcare providers are expanding infrastructure under stricter EU Medical Device Regulation conformity assessments.
- Space Exploration:Propellant densification and in-orbit fluid management demand cryogenic storage with zero-boiloff architectures. United States government procurement programs and private launch ventures are funding concentrated R&D investment.
- Industrial Gas Production:Air separation units and hydrogen liquefaction plants operate continuous liquefaction cycles at scale.
- Food Processing:Cryogenic freezing and chilling systems use liquid nitrogen or carbon dioxide for rapid temperature reduction in protein processing.
Industrial gas production dominates installed base. Space exploration is gaining share fastest.
End User:
Specification authority and lifecycle cost accountability vary between regulated healthcare procurement and performance-driven aerospace programs.
- Healthcare:Hospitals and biobanks operate FDA-validated cryogenic freezers for biologics storage with documented temperature qualification protocols. FDA oversight shapes equipment validation requirements and service contract structures.
- Aerospace:Launch vehicle manufacturers and satellite operators require cryogenic propellant management with extreme reliability margins. United States private launch ventures are driving specifications for in-orbit refueling demonstrations.
- Energy:Carbon capture and hydrogen economy projects deploy cryogenic separation and liquefaction equipment.
- Food & Beverage:Protein processors and cold chain logistics operators deploy cryogenic freezing for quality preservation.
Healthcare dominates installed base. Aerospace is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium supply chains concentrate in Qatar and the United States, forcing end users across Asia-Pacific and Europe toward alternative cooling architectures. Germany's healthcare infrastructure expansion and Japan's efficiency mandates exemplify how regional regulatory frameworks accelerate technology transitions. China's industrial gas capacity buildout and India's pharmaceutical logistics upgrades complete the geographic demand map.
United States
Space exploration programs and private launch ventures drive concentrated R&D into propellant densification systems. EPA Section 608 refrigerant management regulations tighten leak detection mandates for industrial cooling equipment. Houston and Cape Canaveral anchor propellant testing infrastructure for in-orbit cryogenic fluid management demonstrations.
Germany
Healthcare providers are expanding MRI infrastructure under stricter EU Medical Device Regulation conformity assessments. The F-Gas Regulation accelerates phase-down schedules for high-global-warming-potential refrigerants in medical equipment. Bavaria's medical technology cluster around Munich concentrates superconducting magnet system deployment and helium recovery infrastructure.
Japan
METI efficiency mandates accelerate magnetocaloric cooling adoption in industrial gas liquefaction applications. JIS standards for cryogenic equipment create compliance thresholds that filter import competition. The Chubu region around Nagoya hosts pilot deployments of hydrogen liquefaction systems using magnetic refrigeration cycles.
China
Industrial gas production capacity expansion absorbs multi-train liquefaction trains with integrated cold box architectures. Dual carbon goals under MEE oversight accelerate construction of large-scale biobanking facilities. The Yangtze River Delta concentrates air separation unit deployment and automated cryogenic storage robotics manufacturing.
India
Pharmaceutical cold chain logistics operators deploy certified cryogenic transport vessels under strengthened CDSCO distribution guidelines. PLI scheme incentives support domestic manufacturing of pressure vessels and refrigeration equipment. Maharashtra's pharmaceutical manufacturing corridor around Mumbai and Pune anchors temperature-sensitive biologics storage infrastructure deployment.
Cryogenic Systems Market Competitive Environment
Industrial gas majors and specialized equipment fabricators split the market along capital intensity and certification capability lines. Consolidation concentrates among liquefaction technology providers with integrated cold box offerings, while fragmentation persists in tank manufacturing where regional certification barriers filter competition. Three archetypes dominate: backward-integrated industrial gas conglomerates, pressure vessel specialists with ASME certification depth, and emerging magnetic refrigeration technology developers. Competitive moves center on helium supply diversification partnerships and rare-earth magnet sourcing arrangements for next-generation cooling systems.
Within the industrial gas tier, Linde plc and Air Liquide occupy positions anchored by liquefaction technology leadership across energy and aerospace segments. Chart Industries exemplifies the backward-integrated equipment archetype through captive cryogenic tank manufacturing. INOX India Limited represents regional pressure vessel specialists expanding certification scope for export market access.
| Leading Market Players |
|---|
| Air Products and Chemicals |
| Flowserve Corporation |
| Chart Industries |
| INOX India Limited |
| Emerson Electric |
| Linde plc |
| Nikkiso Co. Ltd. |
| Wessington Cryogenics |
| Air Liquide |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Houston LNG shipping corridor anchors freight cost dynamics for cryogenic equipment, compressing margins on European-bound tanks while enabling price differentiation between ASME-certified and ISO-only product tiers. Helium scarcity concentrates supply-side leverage with Qatar and United States producers, forcing buyers toward longer-term contract structures that lock in capacity premiums.
Pricing Analysis
EPA Section 608 refrigerant management regulations dictate the pricing tier structure across the United States market, separating closed-loop certified systems from conventional equipment. Three-tier pricing structure across premium, standard, and economy levels reflects ASME Section VIII certification depth, helium recovery integration, and after-sales service bundling. Cost compression in mid-scale magnetic refrigeration units is intensifying because rare-earth magnet arrays remain supply-constrained. Hospital procurement teams in Germany exhibit lowest price sensitivity due to EU Medical Device Regulation compliance mandates, while Indian pharmaceutical logistics operators face acute budget constraints under CDSCO guideline implementation.
Supply Chain Analysis
Extended payment terms from 90 to 180 days have become standard for cryogenic tank procurement, with supply-chain finance facilities emerging as competitive differentiators for European fabricators. Manufacturing concentrates in China, Germany, and the United States, drawing from rare-earth magnet deposits, nickel-alloy steel plate, and multi-layer superinsulation materials. Single-source vulnerability runs through helium feedstock, where Qatar and United States export quotas expose buyers to allocation risk. Distribution runs through industrial gas majors with captive equipment divisions and specialized pressure vessel distributors holding regional certification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic refrigeration adoption sits at early-cycle expansion, with Japan's METI efficiency mandates accelerating pilot deployments beyond demonstration phase into commercial gas liquefaction.
For Market Incumbents: Pre-empt helium supply diversification partnerships before Qatar export quota volatility hardens into structural shortage. Lock in rare-earth magnet offtake agreements with Australian and Canadian miners to secure input cost stability for next-generation cooling systems. Vertical integration into cryogenic tank manufacturing, as demonstrated by Chart Industries, defends margin position against regional pressure vessel specialists expanding ASME certification scope. For New Entrants and Emerging Players: Mid-scale pharmaceutical cold chain operators in India represent the most penetrable entry point, where CDSCO guideline enforcement has outpaced domestic manufacturing capacity. Target modular magnetic refrigeration units for hydrogen liquefaction pilots in Japan's Chubu region, where METI funding de-risks technology adoption. Lead with performance-based thermal uptime guarantees rather than capital equipment sales to bypass incumbent service contract lock-in. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial gas conglomerates divesting non-core equipment fabrication units to streamline balance sheets. Position holdings for five-to-ten year window as helium scarcity structuralizes and magnetic refrigeration achieves manufacturing scale. Signal to watch: Japan pilot deployment data showing magnetocaloric system efficiency parity with Claude cycles at 20 Kelvin.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Secures neodymium-dysprosium feedstock for magnetic refrigeration scaling under Japan METI mandates. |
| ASME Section VIII Certification Expansion | Opens United States and German healthcare procurement channels for regional pressure vessel fabricators. |
| Helium Recovery System Integration | Addresses EPA Section 608 compliance while reducing lifecycle operating costs for hospital MRI infrastructure. |
| Modular Hydrogen Liquefaction Pilot | Validates magnetocaloric technology at 20 Kelvin for Japan's Chubu region hydrogen economy deployment. |
| Biobank Automation Partnership | Captures China dual carbon goals funding for large-scale specimen preservation facility construction. |
Study Parameters
Initial hypotheses were tested against primary input from cryogenic equipment procurement managers, biomedical engineering directors, industrial gas supply chain leads, and pressure vessel certification specialists and refined through secondary validation. Sources included EPA Section 608 enforcement databases, FDA biologics storage validation guidelines, EU Medical Device Regulation conformity assessment records, and Japan METI efficiency standard filings. Bottom-up equipment shipment analysis triangulated against top-down industrial gas capacity expansion tracking.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling cryogenic tank, refrigerator, and freezer segments alongside magnetic refrigeration, gas liquefaction, and Stirling cycle technologies. End-use dimensions spanned medical imaging, space exploration, industrial gas production, and biobanking applications. CAGRs derived from equipment replacement cycle analysis, regulatory timeline compression effects, and helium price elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in industrial gas demand, rare-earth commodity pricing, or export quota policy would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Cold Trap Market
Cooling Systems
Transformer Oil Coolers Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Global Air Cooled Condenser Market