
 Europe Cooling Systems Market | 2026-2036
Europe Cooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cooling Systems Market Foresight
Data center operators is rotating toward liquid-cooled and hybrid architectures as AI compute density strains legacy HVAC infrastructure. Johnson Controls International plc leverages its building automation portfolio to capture retrofit cycles across Frankfurt and Amsterdam server clusters. Schneider Electric SE anchors its position through integrated microgrid-cooling packages for edge facilities. Carrier Global Corporation competes on refrigerant transition readiness as F-Gas phase-down deadlines approach.
Europe cooling systems encompass engineered thermal management equipment that rejects waste heat through vapor compression, absorption, or evaporative cycles, typically operating between -40°C and 50°C setpoints depending on application. These systems protect industrial processes, preserve perishables, and maintain uptime for critical infrastructure across the continent's climate zones. Chillers dominate value capture in the product mix, while refrigerant-based technology faces structural pressure from natural coolant substitution. Data center application segments outpace industrial process cooling in incremental growth as hyperscalers expand Nordic and Central European footprints.
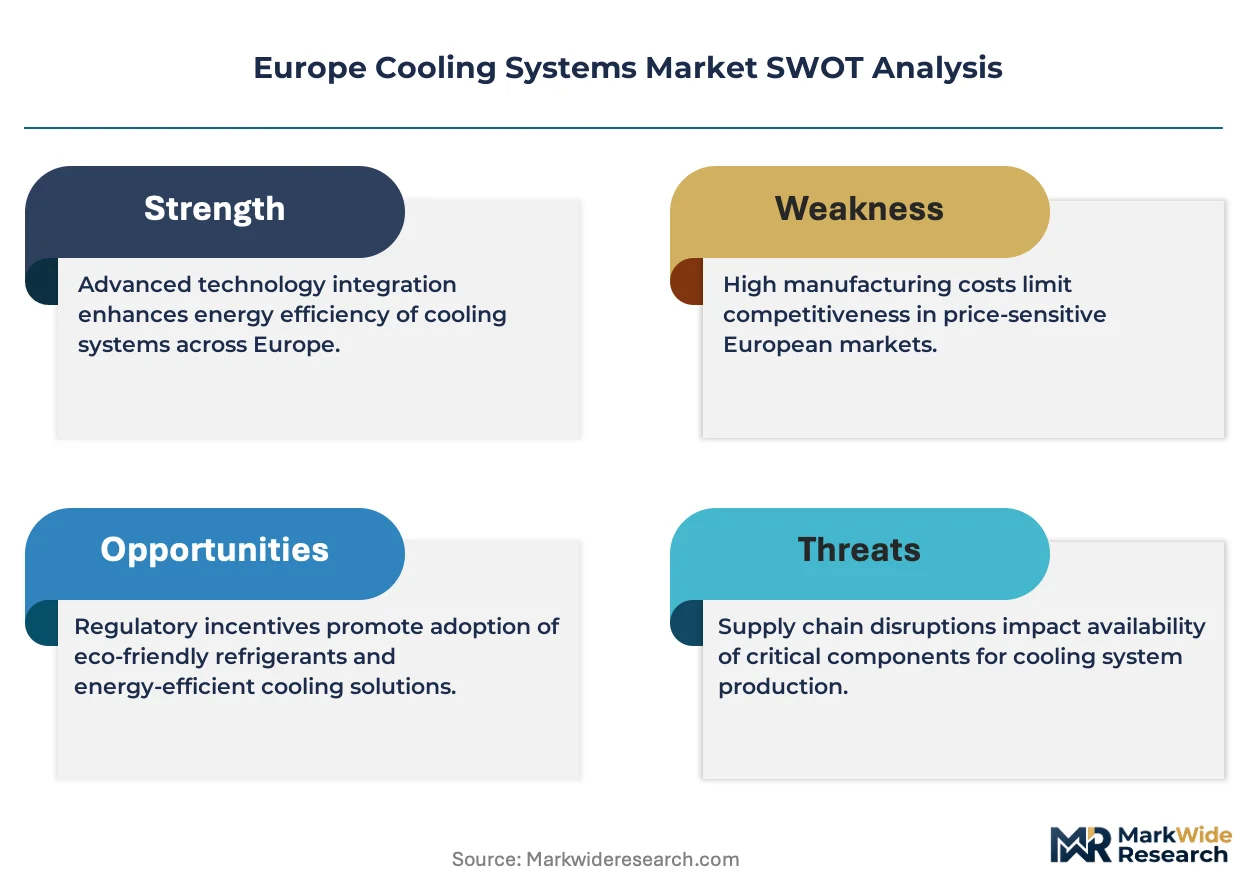
The EU F-Gas Regulation and Ecodesign directives shape product roadmaps by mandating lower-GWP refrigerants and minimum seasonal efficiency thresholds. REACH compliance adds material disclosure burdens for heat exchanger coatings and insulation chemistries. EMA and national health regulators indirectly influence demand through pharmaceutical cold chain integrity requirements. Stakeholders must monitor refrigerant quota allocation mechanics and carbon border adjustment implementation timelines to calibrate sourcing and pricing strategies.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant supply chains while hyperscale data centers in Frankfurt and Amsterdam strain legacy thermal infrastructure beyond design limits.
Growth Catalysts
- AI Compute Density:Hyperscalers across Germany and France are retrofitting server halls with liquid-cooled architectures as GPU clusters exceed 50kW per rack.
- REACH Compliance:Chemical disclosure mandates for heat exchanger coatings are accelerating substitution toward natural refrigerant loops in Nordic industrial zones.
- Automotive Electrification:Battery gigafactories in Hungary and Poland are procuring process chillers for electrode coating lines and cell formation chambers.
Market Restraints
- Copper-Alloy Supply Concentration:Heat exchanger tubing depends on German and Spanish semi-finished metal suppliers facing energy cost volatility.
- Quota Allocation Mechanics:The EU F-Gas Regulation's phasedown schedule creates refrigerant scarcity pricing that disturbs chiller OEM production planning.
- Absorption Chiller Efficiency Limits:Industrial waste-heat recovery systems cannot achieve sub-10°C setpoints required by pharmaceutical cold chains.
Strategic Opportunities
- Nordic Edge Expansion:Norway and Sweden offer free-air cooling advantages for AI training clusters seeking PUE ratios below 1.15.
- Refrigerant-as-a-Service:Chemical leasing models for natural coolant management are penetrating Dutch and Belgian food processing plants.
- Microgrid-Cooling Integration:On-site solar-thermal absorption paired with electric compression is capturing industrial parks in Portugal and Spain.
Industry Challenges
- Fluorinated Gas Handling Certification:Technician licensing bottlenecks in France and Italy are extending installation lead times for retrofit projects.
- Legacy HVAC Integration:Hybrid liquid-air systems must interface with 20-year-old building automation protocols in Frankfurt's financial district.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cooling Systems Market |
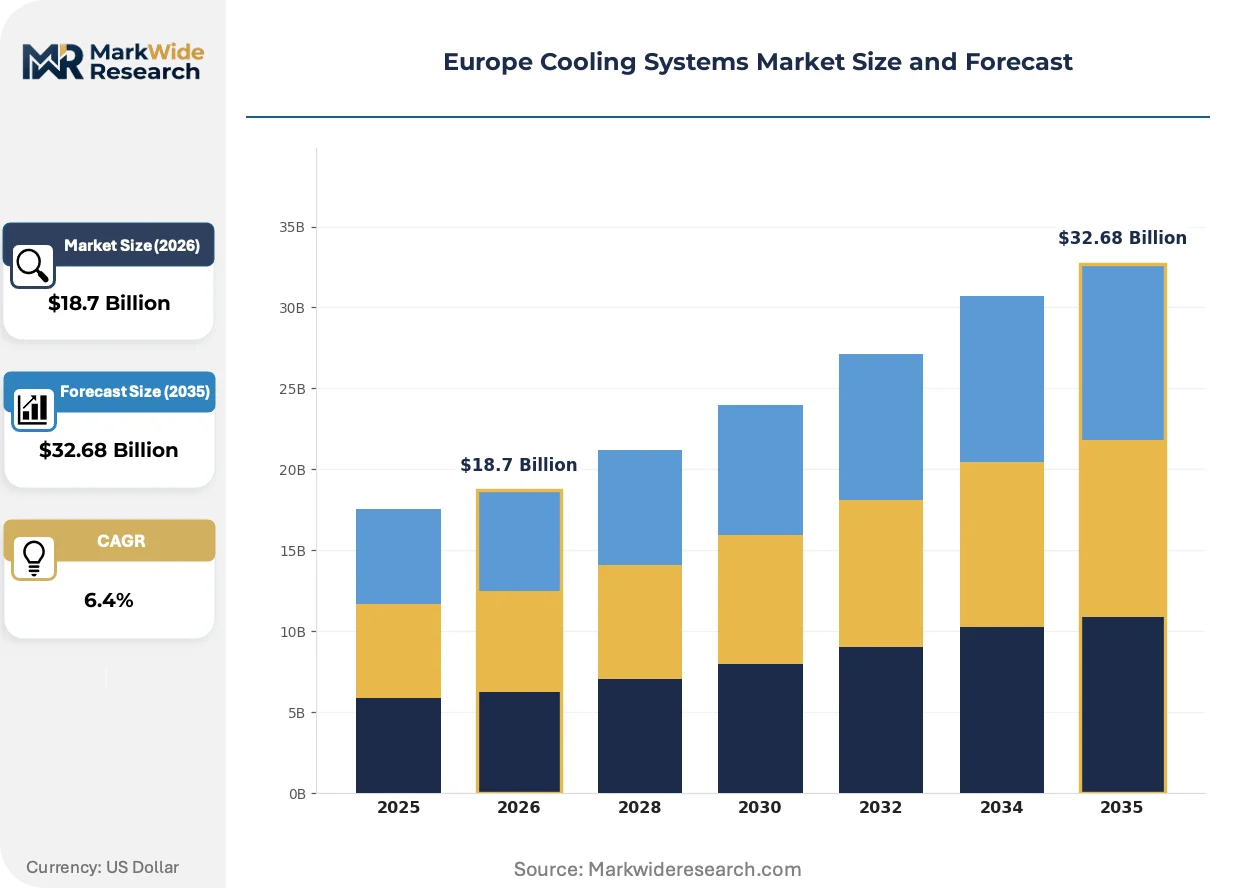
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Condensers, Evaporators, Cooling Towers Technology: Air-Cooled, Water-Cooled, Hybrid, Refrigerant-Based End User: Residential, Commercial, Industrial, Automotive Application: HVAC, Refrigeration, Data Centers, Process Cooling |
| Companies Covered | Stulz GmbH, Johnson Controls International plc, Schneider Electric SE, Trane Technologies Company, LLC, Carrier Global Corporation, Alfa Laval AB, Rittal GmbH & Co KG, Daikin Industries, Ltd., Vertiv Group Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cooling Systems Market Shifts & Advancements
Refrigerant chemistry, control architectures, and procurement models are simultaneously transforming as efficiency mandates tighten and compute loads intensify across European industrial and digital infrastructure.
Micro-channel heat exchangers are replacing traditional fin-and-tube coils in compact chiller packages. Data center operators in the Netherlands and Ireland are specifying these units for rooftop installations where footprint constraints dominate. The technology is miniaturizing thermal rejection capacity into volumes that legacy equipment cannot match.
The EU F-Gas Regulation's 2027 quota step-down is forcing refrigerant portfolio transitions toward propane and ammonia variants. Chiller manufacturers are redesigning safety systems and pressure vessels to accommodate flammable working fluids. Industrial process cooling in Germany's chemical corridor faces the steepest compliance timeline and is accelerating equipment replacement cycles.
Performance-based cooling contracts are displacing capital purchase models for large industrial sites. Energy service companies in France and Italy now guarantee thermal output per euro spent, transferring operational risk from plant owners to equipment vendors. Food processing multinationals with pan-European footprints are piloting these arrangements at their Iberian facilities.
Europe Cooling Systems Market Segmentation
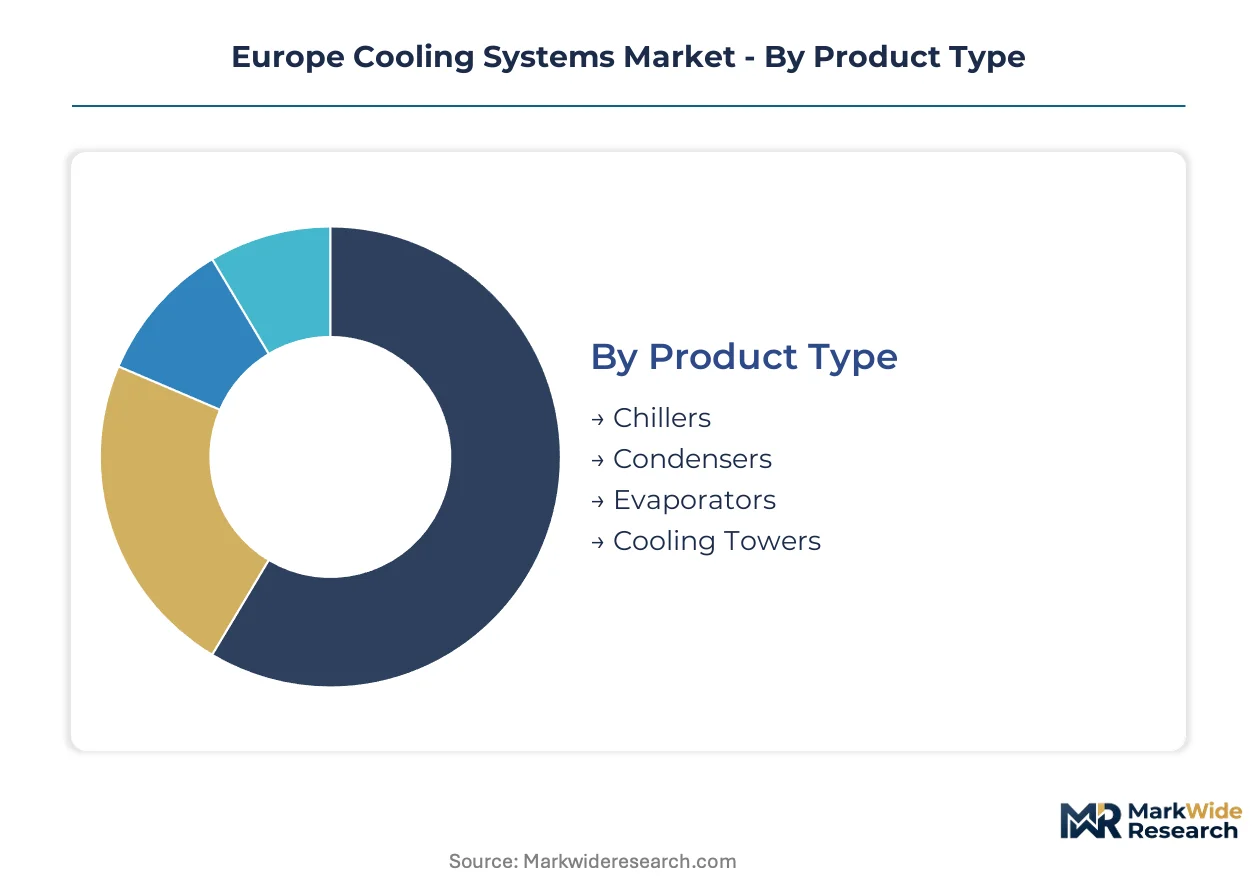
Segmentation reveals where capital deployment concentrates across Europe's cooling infrastructure upgrade cycle. Equipment buyers prioritize thermal performance specifications that align with F-Gas compliance timelines and AI compute density requirements.
Product Type:
Margin pools concentrate in engineered compression equipment where refrigerant transitions drive replacement demand.
- Chillers:Vapor compression and absorption systems ranging from 10kW to 30MW cooling capacity. Germany's automotive and chemical corridors are retrofitting process chillers as electrode coating lines and cell formation chambers multiply. The EU F-Gas Regulation's phasedown schedule compresses equipment replacement cycles.
- Condensers:Heat rejection coils and shell-and-tube exchangers that liquefy refrigerant vapor. Data center operators in Frankfurt and Amsterdam specify these for hybrid liquid-air architectures as GPU rack densities exceed 50kW. Micro-channel designs are displacing traditional fin-and-tube configurations.
- Evaporators:Direct-expansion and flooded units for cold storage and process cooling.
- Cooling Towers:Open-circuit and closed-circuit evaporative heat rejection systems for industrial parks.
The dominant share belongs to Chillers, while Condensers is closing the gap fastest.
Technology:
Application requirements dictate thermal rejection architecture selection across climate zones and regulatory environments.
- Air-Cooled:Refrigerant-to-air heat exchangers eliminating water consumption. Nordic edge facilities in Norway and Sweden deploy these for free-air cooling advantages targeting PUE ratios below 1.15. Rooftop installations in the Netherlands and Ireland favor compact footprints.
- Water-Cooled:Shell-and-tube or plate heat exchangers using cooling water loops. Central European data centers and industrial process plants rely on these for higher efficiency in temperate climates. Water scarcity constraints in Southern Europe limit deployment.
- Hybrid:Combined air-water systems switching modes by ambient conditions.
- Refrigerant-Based:Direct-expansion cooling using synthetic or natural working fluids.
Water-Cooled retains the installed base majority, though Hybrid is expanding most quickly in hyperscale facilities.
End User:
Customer scale determines procurement complexity and service contract structures.
- Residential:Unitary air conditioning and heat pump systems for single-family and multi-family dwellings.
- Commercial:Packaged rooftop units and split systems for offices, retail, and hospitality. Building automation integration requirements in Frankfurt's financial district drive specification complexity.
- Industrial:Custom-engineered process cooling for manufacturing and chemical production. Battery gigafactories in Hungary and Poland are procuring electrode coating line chillers.
- Automotive:Thermal management for battery electric vehicle production and charging infrastructure.
Industrial commands the value pool, while Automotive is climbing the fastest on electrification capex.
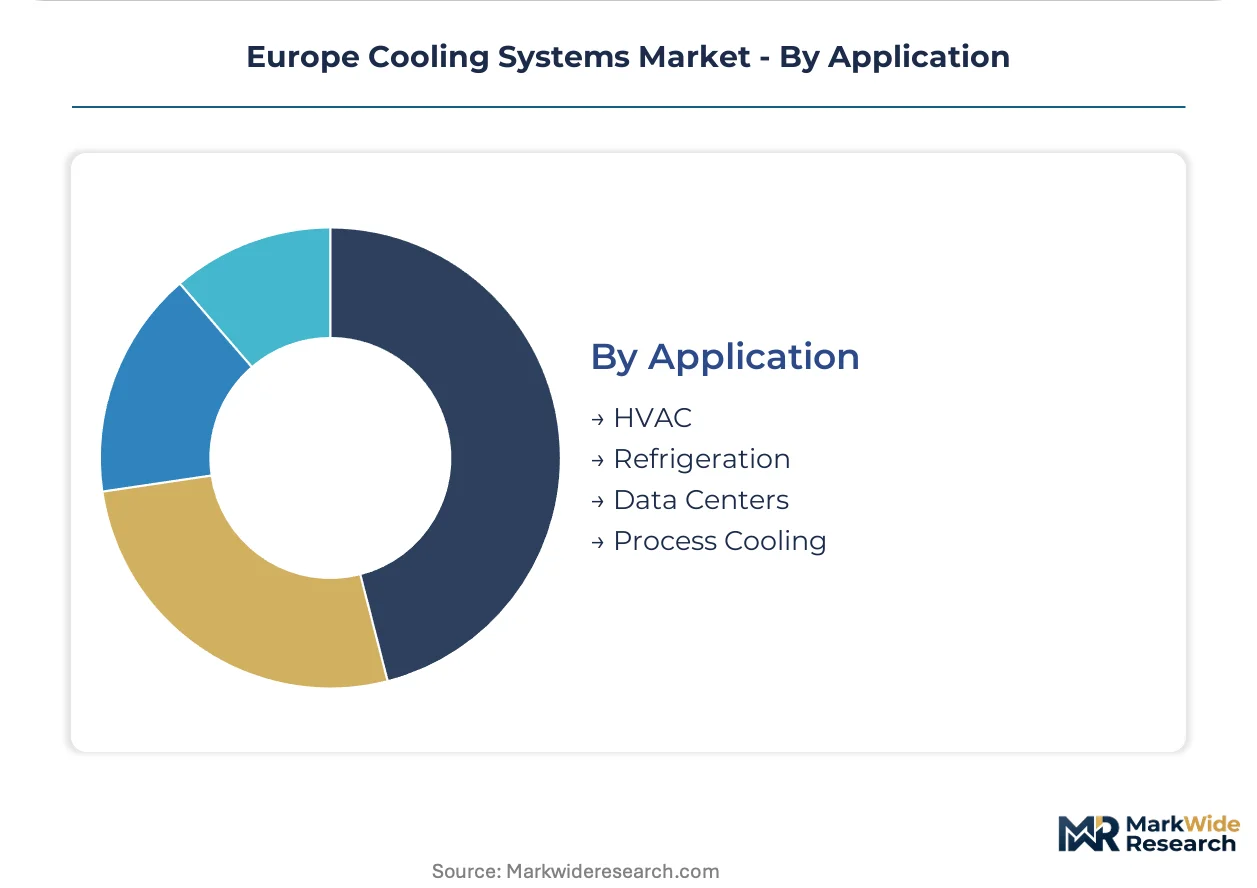
Application:
Operational uptime requirements separate mission-critical from comfort cooling specifications.
- HVAC:Building climate control for occupant comfort and air quality. The EU Green Deal tightens energy efficiency mandates for commercial building retrofits across Germany and France.
- Refrigeration:Cold chain preservation for food, pharmaceuticals, and chemicals. EMA and national health regulators enforce pharmaceutical cold chain integrity requirements.
- Data Centers:Precision cooling for server and storage infrastructure. Hyperscalers across Germany and France are rotating toward liquid-cooled and hybrid architectures as AI compute density strains legacy infrastructure.
- Process Cooling:Industrial temperature control for manufacturing operations.
Data Centers is gaining share fastest, though HVAC maintains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway and North Sea-Baltic rail corridor position Central Europe as the continent's thermal management hub. Frankfurt's data center cluster and Rotterdam's port cooling infrastructure anchor cross-border equipment flows.
Germany
Automotive electrification and chemical process cooling drive equipment procurement across the Rhine-Ruhr and Bavarian industrial belts. The EU F-Gas Regulation's 2027 quota step-down accelerates chiller replacement cycles in Ludwigshafen's chemical corridor. Battery gigafactories in Thuringia and Saxony-Anhalt are installing electrode coating line chillers.
France
Pharmaceutical cold chain expansion and nuclear fleet thermal management sustain demand for precision cooling systems. EMA cold chain integrity requirements tighten specifications for Lyon and Strasbourg distribution hubs. The Paris-Saclay research cluster is retrofitting laboratory HVAC with low-GWP refrigerant architectures.
Netherlands
Hyperscale data center concentration and greenhouse horticulture cooling dominate equipment specifications. Amsterdam's server hall density strains district cooling networks beyond design capacity. The Port of Rotterdam's petrochemical complex is transitioning process chillers to ammonia-based systems.
Sweden
Free-air cooling advantages and renewable energy surplus attract AI training cluster investments targeting sub-1.15 PUE ratios. The Nordic Green Taxonomy incentivizes natural refrigerant adoption in Malmö food processing plants. Luleå's server farms leverage Arctic ambient conditions for evaporative cooling.
Poland
Battery manufacturing capacity expansion and automotive supplier migration from Western Europe concentrate demand in Lower Silesia and Greater Poland. The EU Just Transition Mechanism funds industrial cooling retrofits in former coal regions. Wrocław's emerging semiconductor cluster is procuring cleanroom precision chillers.
Europe Cooling Systems Market Competitive Landscape
Listed leaders compete with private specialists across refrigerant transition readiness and building automation integration. The vendor base spans three tiers: diversified industrial conglomerates with full HVAC portfolios, focused thermal management specialists, and regional fabrication houses serving retrofit cycles. Strategic differentiation concentrates on F-Gas compliance timing, microgrid-cooling integration capabilities, and performance-based service contracting. Capacity expansion and technology licensing dominate competitive moves as quota scarcity compresses production planning horizons.
Within the diversified conglomerate tier, Johnson Controls International plc and Schneider Electric SE exemplify building automation integration strategies, while Carrier Global Corporation anchors refrigerant transition positioning. Stulz GmbH represents the specialist archetype focused on mission-critical cooling. These players occupy distinct competitive spaces based on scale scope and service model depth.
| Leading Market Players |
|---|
| Stulz GmbH |
| Johnson Controls International plc |
| Schneider Electric SE |
| Trane Technologies Company, LLC |
| Carrier Global Corporation |
| Alfa Laval AB |
| Rittal GmbH & Co KG |
| Daikin Industries, Ltd. |
| Vertiv Group Corp |
| Others |
Supply & Pricing Matrix
Long-term refrigerant offtake contracts between chiller OEMs and chemical suppliers lock in quota access under the EU F-Gas Regulation while capping price volatility for natural coolant transitions. These arrangements bind German and French equipment manufacturers to Belgian and Dutch refrigerant distributors, embedding supply security into project finance structures.
Pricing Analysis
Volume-discount tiering structures separate premium-certified chillers for pharmaceutical cold chains from standard industrial units and economy-grade HVAC retrofit packages. Price differentiation hinges on CE marking tier and after-sales service bundling, with certified pharmaceutical-grade systems commanding substantial premiums over commodity comfort cooling. Cost compression in the economy tier is intensifying because copper-alloy supply volatility feeds into heat exchanger fabrication. Data center operators demonstrate the lowest price sensitivity due to uptime guarantees, while municipal building retrofits in Southern Europe face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes are elevating landed costs for micro-channel heat exchanger assemblies. Component manufacturing concentrates in Germany, Spain, and Italy, with German semi-finished metal suppliers anchoring copper-alloy tubing production. Raw material dependencies span copper cathodes, aluminum billets, and synthetic refrigerant precursors. Single-source vulnerability around German copper-alloy suppliers exposes the network to energy cost shocks. Distribution runs through regional fabrication houses serving retrofit cycles across the Rhine-Ruhr and Bavarian industrial belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale data center operators consolidating procurement across Frankfurt and Amsterdam clusters, fragmenting the vendor base into price-takers versus specification-setters.
For Market Incumbents: Fortify refrigerant transition readiness by accelerating ammonia and propane safety system certifications ahead of the EU F-Gas Regulation's quota step-down. Deepen backward integration into heat exchanger fabrication by acquiring Spanish semi-finished metal capabilities, insulating margin structures from copper-alloy supply volatility. This defensive posture counters emerging Polish and Hungarian battery gigafactory entrants procuring direct from Asian component suppliers. For New Entrants and Emerging Players: Differentiate on microgrid-cooling integration capabilities targeting Portuguese and Spanish industrial parks seeking solar-thermal absorption paired with electric compression. White-space concentration sits with Nordic edge facilities in Norway and Sweden pursuing sub-1.15 PUE ratios, where free-air cooling advantages remain underexploited by incumbent building automation portfolios. A performance-based contracting go-to-market model transfers operational risk from plant owners and accelerates reference customer acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward specialist thermal management firms with natural refrigerant safety system expertise and established EMA cold chain certification pathways. Long-term viability over the next decade rests on F-Gas compliance timing and microgrid integration capabilities rather than scale economies alone. The signal to watch is refrigerant quota allocation mechanics tightening faster than equipment replacement cycles, compressing production planning horizons for unprepared OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Safety System Certification | EMA and national health regulators enforce pharmaceutical cold chain integrity requirements that demand certified low-GWP architectures. |
| Backward Integration into Heat Exchanger Fabrication | Spanish and German semi-finished metal suppliers face energy cost volatility that threatens copper-alloy tubing availability. |
| Performance-Based Cooling Contracts | Energy service companies in France and Italy now guarantee thermal output per euro spent, transferring operational risk. |
| Microgrid-Cooling Integration | On-site solar-thermal absorption paired with electric compression captures industrial parks in Portugal and Spain. |
| Nordic Edge Facility Expansion | Norway and Sweden offer free-air cooling advantages for AI training clusters seeking PUE ratios below 1.15. |
Research Methodology
Operator-level perspectives from data center infrastructure directors, pharmaceutical cold chain managers, automotive plant engineers, and chemical process cooling specialists anchored the qualitative base. These primary insights combined with secondary validation from EU F-Gas Regulation quota allocation reports, EMA cold chain guidance documents, SEC filings of listed HVAC conglomerates, and customs data on copper-alloy trade flows. Bottom-up equipment procurement tracking and top-down macroeconomic scenario triangulation calibrated market size estimates.
Sensitivity analysis tested demand elasticity across the projection horizon under varying AI compute density assumptions and refrigerant phasedown acceleration scenarios. The analytical framework modeled segmentation dimensions spanning product type, cooling technology, end-user scale, and application criticality, with regional regulatory cluster as an overlay. CAGRs derived from equipment replacement cycle compression rates and hyperscaler capex disclosure patterns, incorporating battery gigafactory buildout timelines and automotive electrification capex curves as industry-specific demand drivers.
Decision-makers should treat outputs as directional under base assumptions of F-Gas quota adherence and AI rack density progression; material deviation would warrant model refresh. Specific risk factors include refrigerant scarcity pricing distorting chiller OEM production planning and copper-alloy supply concentration extending installation lead times. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Global Air Cooled Condenser Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Turbine Inlet Cooling Systems Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Seawater Condensers Market
Cooling Systems
Thermosiphon Cooling System Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Temporary Power and Cooling Solutions Market