
 Dry Cooler Market | 2026-2036
Dry Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cooler Market Analytics
Refrigeration technician shortages across Europe are redrawing competitive boundaries in the dry cooler sector. Kelvion leverages its German engineering base to sustain premium positioning in industrial process applications. Carrier anchors North American demand through extensive service networks and chiller-dry cooler hybrid integration. Guntner dominates the food processing segment with specialized aluminum coil designs that navigate strict hygiene standards.
A dry cooler is a heat rejection device that uses ambient air to cool a process fluid—typically water or glycol—circulated through finned-tube heat exchangers without evaporative water loss, operating across temperature differentials of 5°C to 15°C depending on ambient conditions and coil configuration. Its primary industrial purpose is to dissipate waste heat from compressors, engines, or process loops in locations where water conservation or plume elimination matters. Air-cooled configurations lead the product type landscape due to simplicity and minimal maintenance, while hybrid designs are capturing the fastest growth as facilities seek peak-load efficiency without year-round water consumption. Among end users, data centers represent the most concentrated margin pool as hyperscalers prioritize modular, non-evaporative technology to eliminate water risk in drought-prone locations.
The EU F-Gas Regulation and REACH framework restrict high-GWP refrigerants, redirecting investment toward dry coolers in commercial and industrial HVAC retrofits. EPA SNAP rules in the United States similarly constrain refrigerant choices, expanding addressable demand for air-cooled heat rejection equipment. ISO 5149 and EN 378 safety standards govern pressure equipment and refrigerant system design, creating compliance barriers that favor established manufacturers with certified testing protocols. Stakeholders must monitor evolving carbon border adjustments and local water-use restrictions to determine where dry cooler substitution outperforms cooling tower retention on a total-cost basis.
Market Dynamics
EU F-Gas Regulation enforcement is systematically dismantling refrigerant-dependent cooling architectures across European industrial zones, redirecting capital toward air-cooled heat rejection systems that eliminate synthetic working fluids entirely.
Growth Catalysts
- REACH chemical restrictions:The ECHA framework classifies high-GWP refrigerants as substances of very high concern, compelling facility operators to retrofit process cooling loops with dry cooler alternatives that bypass chemical registration burdens.
- Data center water risk:Hyperscale computing clusters in drought-prone regions of Spain and Italy now specify non-evaporative thermal management to secure operating permits and mitigate supply interruptions.
- Aluminum coil advances:Enhanced fin geometries and microchannel tubing designs extend dry cooler applicability into sub-zero ambients previously dominated by evaporative systems.
Market Restraints
- Copper and aluminum price volatility:Coil manufacturing consumes substantial non-ferrous metal volumes, exposing producers to London Metal Exchange commodity swings that compress fabrication margins.
- Refrigeration technician scarcity:European vocational pipelines produce insufficient certified service personnel to support accelerated retrofit timelines, extending project completion windows.
- Evaporative cooling cost advantage:Cooling towers retain lower first-cost positioning in water-abundant geographies, limiting dry cooler penetration in price-sensitive industrial segments.
Strategic Opportunities
- Polish industrial corridor:Manufacturing investment in Lower Silesia and Masovia creates concentrated demand for process cooling without mature evaporative infrastructure to displace.
- Chiller-dry cooler hybrid architectures:Integration of free-cooling coils with mechanical compression systems captures partial-load efficiency gains in variable climate zones.
- EU Green Deal capital access:Recovery and Resilience Facility disbursements prioritize industrial decarbonization projects, subsidizing heat pump and dry cooler combinations in facility upgrades.
Industry Challenges
- Pressure equipment certification:EN 378 and ISO 5149 compliance testing creates six-to-nine month validation timelines that delay product launches and contract awards.
- Legacy control system integration:Brownfield installations require protocol bridging between dry cooler PLCs and existing building management systems, inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cooler Market |
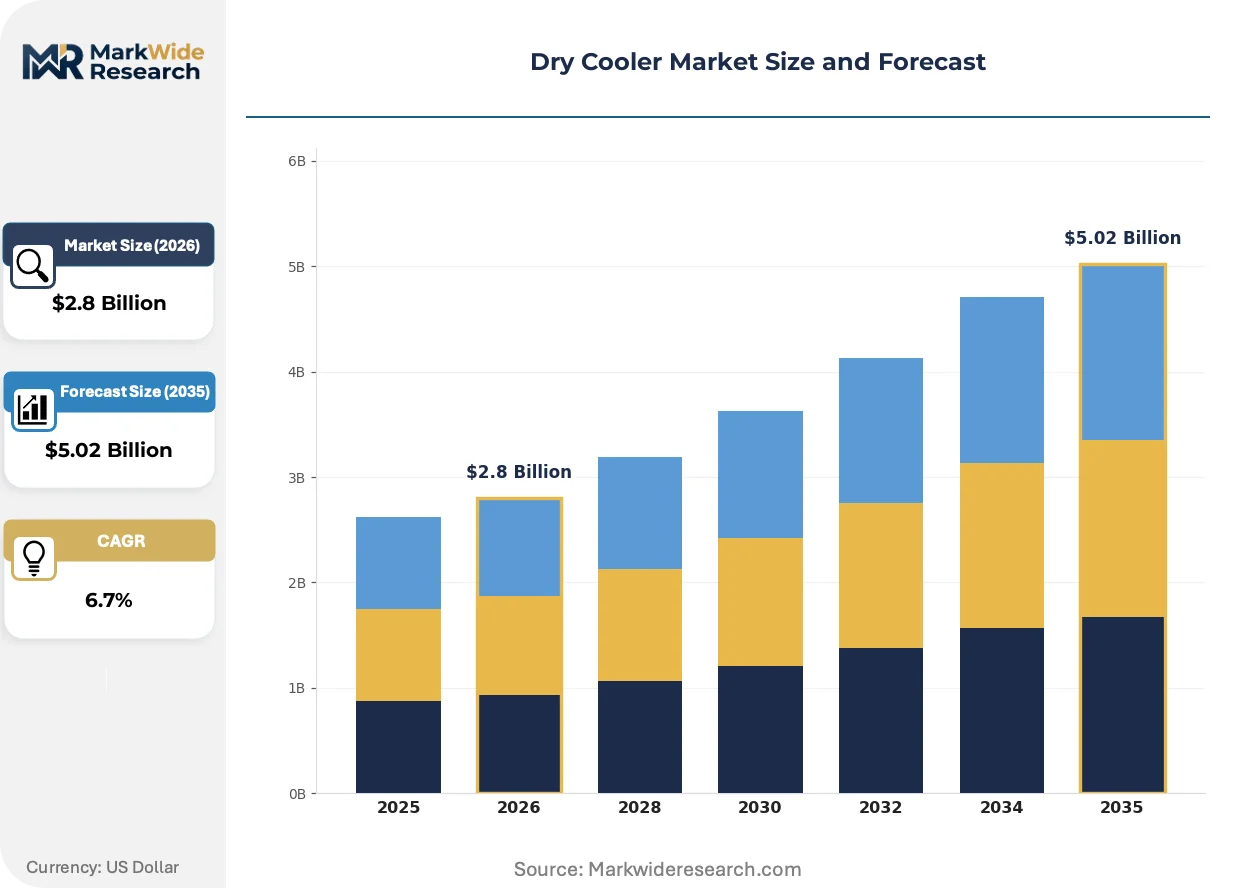
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Hybrid, Telescopic Application: Industrial Process, HVAC, Power Generation, Refrigeration End User: Manufacturing, Data Centers, Food Processing, Commercial Buildings Technology: Direct Expansion, Evaporative, Non-Evaporative, Modular |
| Companies Covered | EVAPCO, Kelvion, Carrier, Kaltra, ThermoKey, Thermax, Guntner, Hexonic, Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cooler Market Evolving Landscape
Equipment architecture is fragmenting into modular, software-defined thermal nodes that separate heat rejection capacity from central plant design, enabling demand-responsive scaling without redundant infrastructure.
Microchannel aluminum coil technology is decomposing traditional copper-tube-and-fin construction across commercial HVAC specifications. Data center operators in Frankfurt and Amsterdam clusters specify all-aluminum dry coolers for weight reduction and corrosion resistance. The technology is decomposing established supplier relationships as coil fabricators without legacy copper supply chains capture specification authority.
EPA SNAP Rule 23 finalization in the United States restricts HFC refrigerants in new chillers and direct expansion equipment, accelerating dry cooler specification in process cooling retrofits. Industrial facilities in Texas and Arizona face compliance deadlines that compress procurement cycles. Food processing plants with existing ammonia infrastructure are most affected, expanding dry cooler deployment as secondary heat rejection for compressor intercooling loops.
Specification authority is migrating from mechanical contractors to sustainability officers with explicit carbon accounting mandates. Large manufacturing groups in Germany and France now require embodied carbon disclosures for heat rejection equipment, favoring suppliers with verified Environmental Product Declarations. This pattern is most visible in automotive battery gigafactory projects where Scope 3 emissions targets override first-cost considerations in vendor selection.
Dry Cooler Market Segmentation
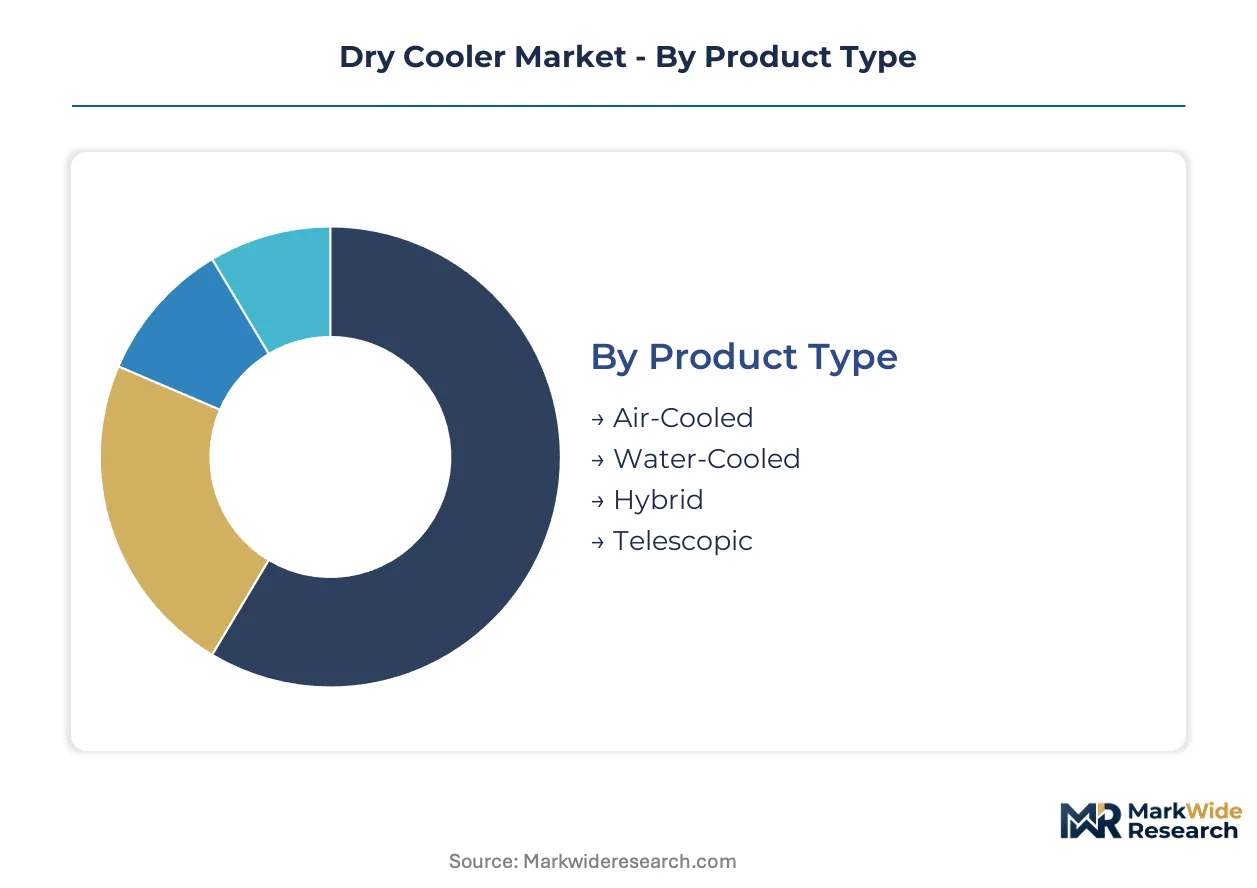
Dry cooler procurement patterns diverge sharply across regulatory jurisdictions, with EU F-Gas enforcement favoring non-evaporative architectures while water-scarce US states prioritize hybrid designs. Specification authority now sits with sustainability officers who weight embodied carbon disclosures alongside thermal performance metrics.
Product Type:
EU F-Gas Regulation and EPA SNAP rules differentiate compliance pathways, with refrigerant-dependent systems facing accelerated phase-out timelines that reshape equipment substitution curves.
- Air-Cooled:Finned-tube heat exchangers circulate water or glycol through aluminum or copper coils without evaporative water loss, operating across 5°C to 15°C temperature differentials. German automotive battery gigafactories specify these systems to eliminate water risk and secure operating permits under strict environmental compliance. Air-cooled configurations handle the majority of throughput; hybrid designs are the fastest mover on share.
- Hybrid:Integrated free-cooling coils with mechanical compression capture partial-load efficiency in variable climate zones. Data center clusters in Frankfurt and Amsterdam deploy hybrid architectures to navigate peak-load demands without year-round water consumption.
- Water-Cooled:Closed-loop configurations retain applicability in water-abundant geographies where first-cost sensitivity dominates procurement decisions.
- Telescopic:Compact footprint designs address space-constrained urban installations and rooftop mechanical plant retrofits.
Air-cooled systems dominate installed base volume; hybrid configurations are expanding most quickly as facilities seek regulatory compliance with operational flexibility.
Application:
Cost tier differentiation separates mission-critical process cooling from comfort HVAC, with industrial applications commanding premium pricing for certified pressure equipment and control system integration.
- Industrial Process:Heat rejection for compressor intercooling, engine cooling, and manufacturing process loops where thermal stability affects production yields. Polish manufacturing corridors in Lower Silesia and Masovia generate concentrated demand as greenfield facilities bypass legacy evaporative infrastructure.
- HVAC:Commercial building retrofits across Spain and Italy specify dry coolers to meet EU Green Deal capital access requirements and decarbonization subsidies.
- Power Generation:Secondary cooling for turbine auxiliary systems and transformer heat rejection in electrical utility applications.
- Refrigeration:Secondary heat rejection for ammonia-based food processing plants in Texas and Arizona facing EPA SNAP Rule 23 compliance deadlines.
Industrial Process captures the highest margin pool; HVAC retrofits are climbing the fastest as regulatory deadlines compress procurement cycles.
End User:
Customer type determines specification complexity, with hyperscale data center operators driving standardization while food processors demand specialized hygiene-certified coil designs.
- Data Centers:Hyperscale computing clusters in drought-prone regions specify modular, non-evaporative thermal management to secure operating permits and mitigate supply interruptions. Sustainability officers with explicit carbon accounting mandates now control vendor selection for Frankfurt and Amsterdam clusters.
- Food Processing:Aluminum coil designs with specialized fin geometries navigate strict hygiene standards and corrosion resistance requirements in continuous washdown environments.
- Manufacturing:Automotive battery production facilities in Germany and France require embodied carbon disclosures and verified Environmental Product Declarations.
- Commercial Buildings:Brownfield installations face legacy control system integration challenges that inflate commissioning costs and extend project timelines.
Data Centers concentrate the highest value demand; Manufacturing is gaining share fastest as battery gigafactory investment accelerates.
Technology:
Maturity curves separate established direct expansion architectures from emerging modular nodes that enable demand-responsive scaling without redundant central plant infrastructure.
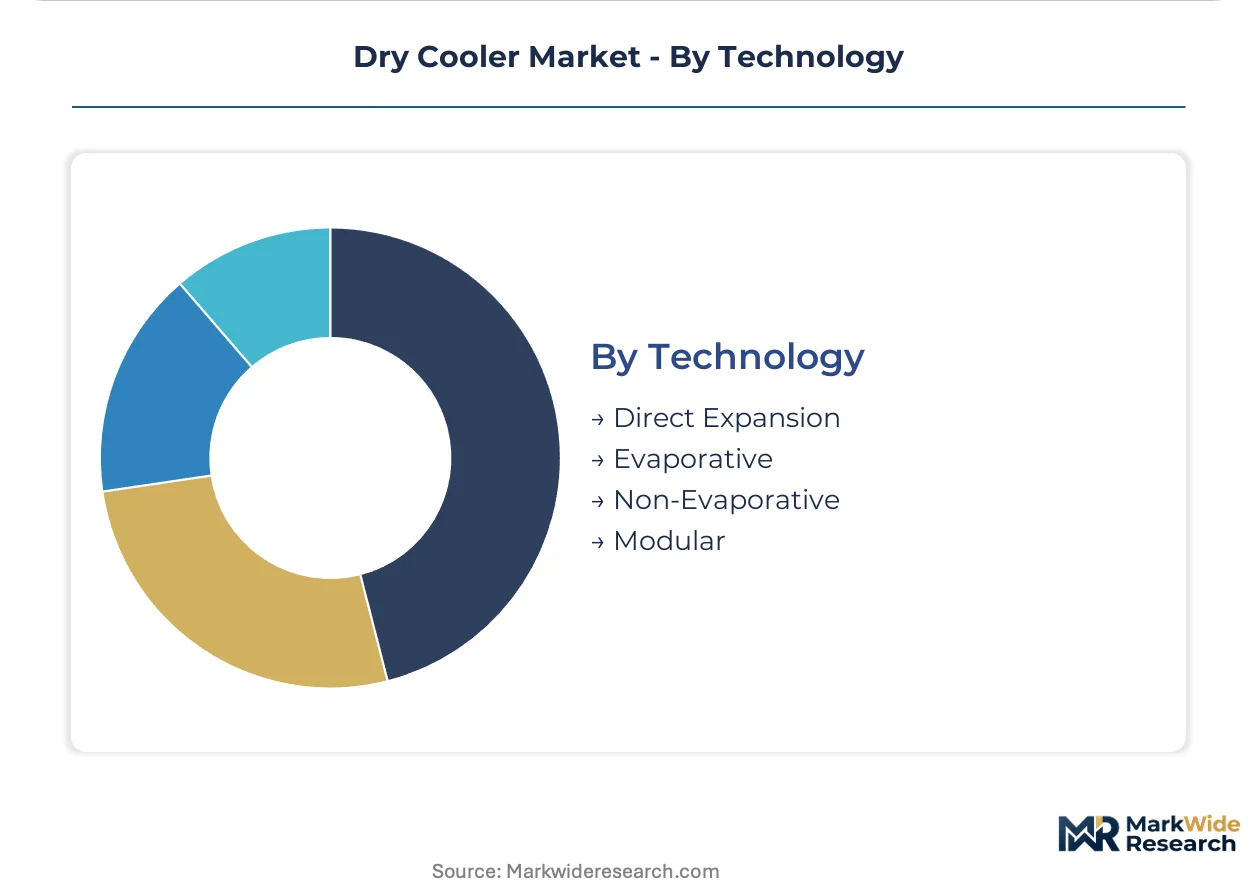
- Non-Evaporative:Air-cooled heat rejection eliminates synthetic working fluids entirely, satisfying ECHA classifications of high-GWP refrigerants as substances of very high concern. REACH chemical restrictions compel facility operators to retrofit process cooling loops with dry cooler alternatives.
- Modular:Software-defined thermal nodes separate heat rejection capacity from central plant design, enabling demand-responsive scaling. Equipment architecture fragmentation favors coil fabricators without legacy copper supply chains.
- Direct Expansion:Refrigerant-based systems face accelerated phase-out under EU F-Gas Regulation and EPA SNAP constraints.
- Evaporative:Cooling towers retain lower first-cost positioning in water-abundant geographies, limiting penetration in price-sensitive segments.
Non-Evaporative systems anchor current deployment; Modular technology shows the steepest expansion trajectory as facilities prioritize scalable infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial facilities deploy dry coolers primarily for process cooling compliance, while US data center operators prioritize water-risk mitigation through non-evaporative architectures. This consumption-mix differential shapes divergent specification priorities across major demand centers.
United States
Hyperscale data center clusters in Texas and Arizona specify modular dry coolers to eliminate water consumption and secure operating permits in drought-prone jurisdictions. EPA SNAP Rule 23 restricts HFC refrigerants in new chillers, accelerating retrofit demand for air-cooled heat rejection equipment. Food processing plants with ammonia infrastructure in the Southwest deploy dry coolers as secondary heat rejection for compressor intercooling loops.
Germany
Automotive battery gigafactories in Bavaria and Baden-Württemberg require embodied carbon disclosures and verified Environmental Product Declarations for heat rejection equipment. EU F-Gas Regulation enforcement dismantles refrigerant-dependent cooling architectures, redirecting capital toward air-cooled systems. Industrial process cooling demand concentrates in the Ruhr region and Lower Saxony, where strict environmental compliance converges with manufacturing investment.
China
Data center operators in the Yangtze River Delta and Pearl River Delta specify non-evaporative thermal management to navigate water-use restrictions and secure energy efficiency certifications. The country's dual carbon goals prioritize industrial decarbonization projects, subsidizing heat pump and dry cooler combinations in facility upgrades. Manufacturing corridors in Shandong and Sichuan generate concentrated demand for process cooling without mature evaporative infrastructure.
India
Commercial building retrofits in Maharashtra and Gujarat specify dry coolers to meet cooling load demands without municipal water dependence. The Bureau of Indian Standards pressure equipment certification creates compliance timelines that favor established manufacturers with testing protocols. Industrial parks in Tamil Nadu and Karnataka deploy air-cooled heat rejection for semiconductor and electronics manufacturing process loops.
Poland
Manufacturing investment in Lower Silesia and Masovia creates concentrated demand for process cooling without legacy evaporative infrastructure to displace. EU Green Deal capital access through Recovery and Resilience Facility disbursements prioritizes industrial decarbonization projects. Automotive and electronics production facilities in the Warsaw metropolitan area specify modular thermal nodes for demand-responsive scaling.
Dry Cooler Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the dry cooler market structure. The upper tier commands specification authority through certified pressure equipment testing protocols and established service networks. Specialist fabricators compete on coil geometry innovation and rapid customization for hygiene-sensitive applications. Dominant competitive moves include geographic expansion into emerging industrial corridors and portfolio diversification toward chiller-dry cooler hybrid architectures.
Among European-based engineering groups, Kelvion and Guntner exemplify divergent specialization archetypes within the premium tier. Carrier anchors North American demand through extensive service infrastructure. Alfa Laval occupies a position bridging industrial process and HVAC specification channels. These three names represent distinct competitive positioning vectors—German engineering depth, North American service scale, and Nordic heat transfer technology heritage—rather than interchangeable market presence.
| Leading Market Players |
|---|
| EVAPCO |
| Kelvion |
| Carrier |
| Kaltra |
| ThermoKey |
| Thermax |
| Guntner |
| Hexonic |
| Alfa Laval |
| Others |
Value Network & Pricing Analysis
Capacity utilization at European coil fabrication facilities shapes both supply concentration and price floors, as aluminum microchannel technology redraws competitive boundaries and compresses margins for legacy copper-tube producers. German engineering groups leverage scale economies in certified pressure equipment testing to sustain premium positioning, while Polish and Chinese fabricators compete on volume throughput for standardized HVAC specifications.
Pricing Analysis
Project-based contracting dominates industrial process cooling procurement, with long-term offtake agreements anchoring data center deployments and spot purchasing limited to maintenance spares. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EN 378 and ISO 5149 compliance commands substantial premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because aluminum coil substitution erodes copper-tube cost advantages. Food processing and automotive battery gigafactory segments exhibit the least price sensitivity due to carbon accounting mandates, while commercial HVAC retrofits in water-abundant geographies remain highly price-sensitive.
Supply Chain Analysis
Strategic stockpiling of aluminum and copper coil inventory prevails among Tier 1 fabricators, mitigating London Metal Exchange volatility exposure that just-in-time procurement cannot absorb. Manufacturing concentration rests on Germany, China, and Poland, with German facilities specializing in certified pressure equipment and Chinese producers dominating microchannel aluminum coil volume. Raw material dependencies draw from aluminum ingot, copper tube, and specialized fin stock. Single-source vulnerability in microchannel tubing technology creates supply chain risk as patent-protected geometries limit qualified suppliers. Distribution runs through OEM direct sales for large industrial projects and specialized HVAC distributors for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified refrigeration technician scarcity constrains retrofit velocity across European industrial zones, creating a bottleneck that rewards suppliers with in-house commissioning capabilities and established service networks.
For Market Incumbents: Fortify specification authority through backward integration into microchannel coil production, capturing margin that currently flows to specialized fabricators. Expand certified service headcount in Poland and Lower Silesia to exploit manufacturing corridor demand before evaporative infrastructure matures. Prioritize EN 378 testing protocol investment as regulatory compliance timelines extend competitive moats against uncertified entrants. For New Entrants and Emerging Players: Lead with modular software-defined thermal nodes targeting data center clusters in Frankfurt and Amsterdam, where sustainability officers with carbon accounting mandates have displaced mechanical contractors in vendor selection. Penetrate the Polish industrial corridor through rapid customization capabilities for automotive and electronics production facilities lacking legacy cooling infrastructure. Pursue a design-build-operate go-to-market angle that bundles equipment with commissioning expertise, addressing technician scarcity directly. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coil fabricators with aluminum microchannel expertise and established automotive battery gigafactory relationships over legacy copper-tube producers facing substitution pressure. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch EPA SNAP Rule 23 enforcement intensity in Texas and Arizona food processing corridors as an inflection indicator for North American retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microchannel Coil Production | Captures margin from specialized fabricators and secures supply chain control for automotive battery gigafactory contracts. |
| Certified Service Network Expansion | Addresses refrigeration technician scarcity in Polish manufacturing corridors and accelerates project completion timelines. |
| EN 378 Testing Protocol Investment | Creates six-to-nine month validation barriers that favor established manufacturers in EU F-Gas Regulation compliance markets. |
| Modular Software-Defined Thermal Node Development | Aligns with hyperscale data center procurement patterns in Frankfurt and Amsterdam clusters driven by sustainability officers. |
| Design-Build-Operate Contracting Model | Bundles equipment with commissioning expertise to overcome technician scarcity and differentiate from component suppliers. |
Research Methodology
Cross-validation between primary interviews with industrial facility engineers, HVAC procurement managers, data center sustainability officers, and refrigeration service technicians anchors the qualitative findings. Secondary validation draws from EU F-Gas Regulation enforcement documentation, EPA SNAP rule filings, EN 378 and ISO 5149 certification registries, and London Metal Exchange commodity data. Bottom-up triangulation across installation project databases and top-down reconciliation against industrial cooling equipment trade flows ensures dimensional consistency.
Sensitivity analysis across aluminum and copper price scenarios, regulatory enforcement intensity variations, and technician availability constraints shapes the analytical framework. Segmentation dimensions modeled include product type architecture, application intensity tier, end-user procurement complexity, and regional regulatory cluster. CAGRs derive from installed base evolution curves and replacement cycle compression effects. Forecast inputs incorporate EU Green Deal capital disbursement schedules and data center water-use restriction expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement or accelerated EPA SNAP compliance timelines would require recalibration. Forecasts reflect assumptions regarding aluminum microchannel technology adoption rates and certified technician pipeline recovery. Revision becomes warranted when commodity price volatility crosses thresholds that fundamentally alter coil fabrication economics or when carbon border adjustments introduce unmodeled trade friction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Air-Cooled Gas Coolers Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Adiabatic Cooler Market