
 Plastic Jar Packaging Market | 2026-2036
Plastic Jar Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Jar Packaging Market Intelligence
The performance gap between premium, post-consumer recycled (PCR) content jars and commodity, virgin polypropylene containers is expanding. This divergence creates distinct market tiers for different end-use requirements. Amcor Plc leverages its global manufacturing footprint to supply multinational food and beverage clients. Berry Global Inc. specializes in high-volume, cost-effective jar solutions for the household chemicals sector. Gerresheimer AG differentiates itself by producing high-purity, sterile plastic jars for pharmaceutical and nutraceutical applications.
Plastic jar packaging refers to rigid, wide-mouthed containers manufactured through injection molding or blow molding processes. These containers are typically made from materials like Polyethylene Terephthalate (PET), prized for its clarity and barrier properties against oxygen and moisture. Their primary function is to provide durable, lightweight, and shatter-resistant containment for a wide array of products. Polyethylene Terephthalate dominates the material type segment, while the food & beverage industry remains the largest end-use consumer by volume. Specialized closure types, such as pump dispensers and flip tops, are seeing increased use in the personal care segment.
Regulatory frameworks are critical in shaping material choices and product design. In the United States, the FDA enforces strict guidelines for materials intended for food contact, impacting resin selection. In Europe, regulations like REACH and specific directives on single-use plastics influence polymer composition and end-of-life considerations. These standards compel manufacturers to verify material safety and substantiate any recyclability claims. Consequently, navigating divergent regional mandates on recycled content and chemical safety is a central strategic challenge for producers.
Market Dynamics
The central dynamic in the plastic jar packaging market is the tension between sustainability mandates and material performance. Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) are forcing a shift towards post-consumer recycled content, creating a widening performance and cost gap between premium recycled materials and commodity virgin polymers.
Growth Catalysts
- Personal Care Sector Demand:The personal care industry's need for differentiated packaging, including jars with specialized pump dispensers and flip-top closures for creams and lotions, stimulates design innovation and value-added feature integration.
- Material Superiority in Food:Polyethylene Terephthalate (PET) continues to be specified in the food and beverage industry due to its exceptional clarity, shatter resistance, and effective barrier properties against oxygen and moisture, protecting product integrity.
- Recycled Content Mandates:Government regulations in regions like Europe mandating minimum post-consumer recycled (PCR) content in plastic packaging are compelling brand owners and converters to increase their use of recycled resins.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of crude oil and natural gas directly impact the cost of virgin resins like PET and polypropylene, creating pricing instability and margin pressure for manufacturers.
- Divergent Regulatory Standards:Conflicting regulations between major markets, such as the FDA's food-contact material guidelines in the U.S. and REACH in Europe, complicate global product launches and increase compliance costs.
- Threat of Substitution:Glass jars in the premium food segment and flexible pouches in household chemicals present significant substitution threats, challenging plastic's market position on grounds of perceived quality or environmental impact.
Strategic Opportunities
- Pharmaceutical and Nutraceutical Expansion:The growing demand for high-purity, sterile, and tamper-evident plastic jars for vitamins, supplements, and over-the-counter pharmaceuticals presents a high-margin growth avenue for specialized producers.
- Monolayer PET Innovations:Developing advanced single-layer PET jars that offer the barrier properties of multilayer containers without the associated recycling challenges provides a path to meet both performance and sustainability goals.
- Smart Packaging Integration:Incorporating QR codes or NFC tags directly onto jars enables brands to enhance consumer engagement, provide detailed product provenance, and improve supply chain traceability for high-value goods.
Industry Challenges
- Recycled Feedstock Quality:Securing a consistent supply of high-quality post-consumer recycled resin that is free from contaminants and suitable for food-contact applications remains a significant operational hurdle for converters.
- Compliance and Certification Delays:The lengthy and resource-intensive process of achieving food-contact approvals from bodies like the EFSA or FDA for new PCR material formulations can slow down the introduction of innovative sustainable packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Jar Packaging Market |
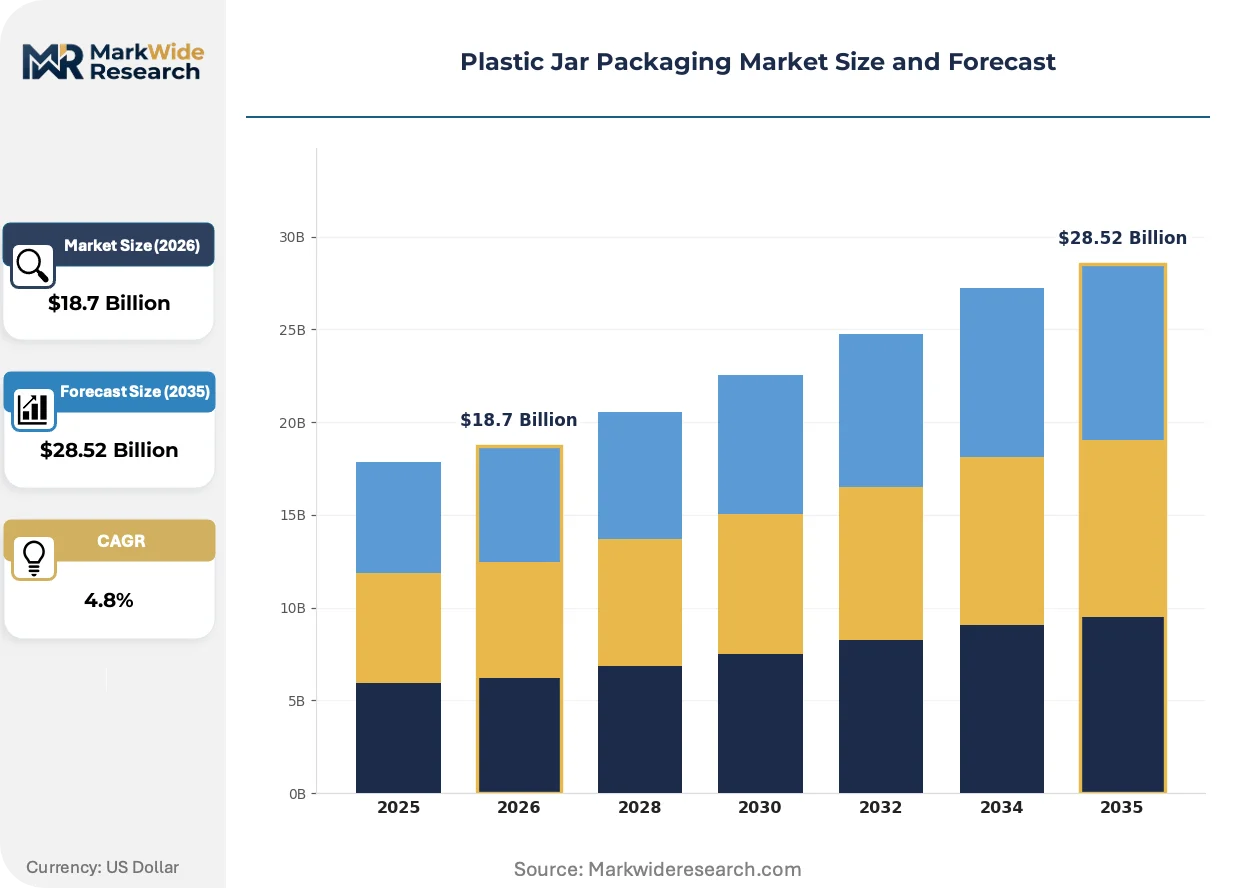
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Closure Type: Screw Cap, Flip Top, Snap-On, Pump Dispenser, Collar Cap End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Household Chemicals, Pet Care Jar Capacity: 50ml, 100ml, 250ml, 500ml, 1000ml |
| Companies Covered | Alpha Packaging, Pretium Packaging, Amcor Plc, All American Containers, RPC M&H Plastics, Berry Global Inc., Silgan Holdings Inc., Tim Plastics Inc., Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Jar Packaging Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of material circularity and manufacturing efficiency. These parallel objectives are driving innovations in sorting technology, material science, and digital integration to meet both regulatory demands and consumer expectations for transparency.
Advanced sorting technology using digital watermarks and spectral analysis improves the purity of post-consumer recycled resin streams. Packaging converters in the food and beverage sector are increasingly adopting these systems to meet stringent recycled-content mandates. This technology is automating the quality control process for incoming feedstocks, enabling the consistent production of higher-grade, food-contact-safe PCR jars.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant policy shift influencing material selection. It compels large companies to provide audited disclosures on their packaging's environmental footprint, including material sourcing and recyclability. The personal care and cosmetics segments are most impacted, now prioritizing suppliers who can deliver validated data to fulfill these stringent transparency obligations.
A consumer-led preference for product transparency is altering packaging design choices. This is causing a move away from simple adhesive labels toward jars with molded-in QR codes that link to detailed sourcing, ingredient, and sustainability information. This demand for on-pack digital access is most prominent within the organic food and premium nutraceutical categories in North America and Europe.
Plastic Jar Packaging Market Segmentation
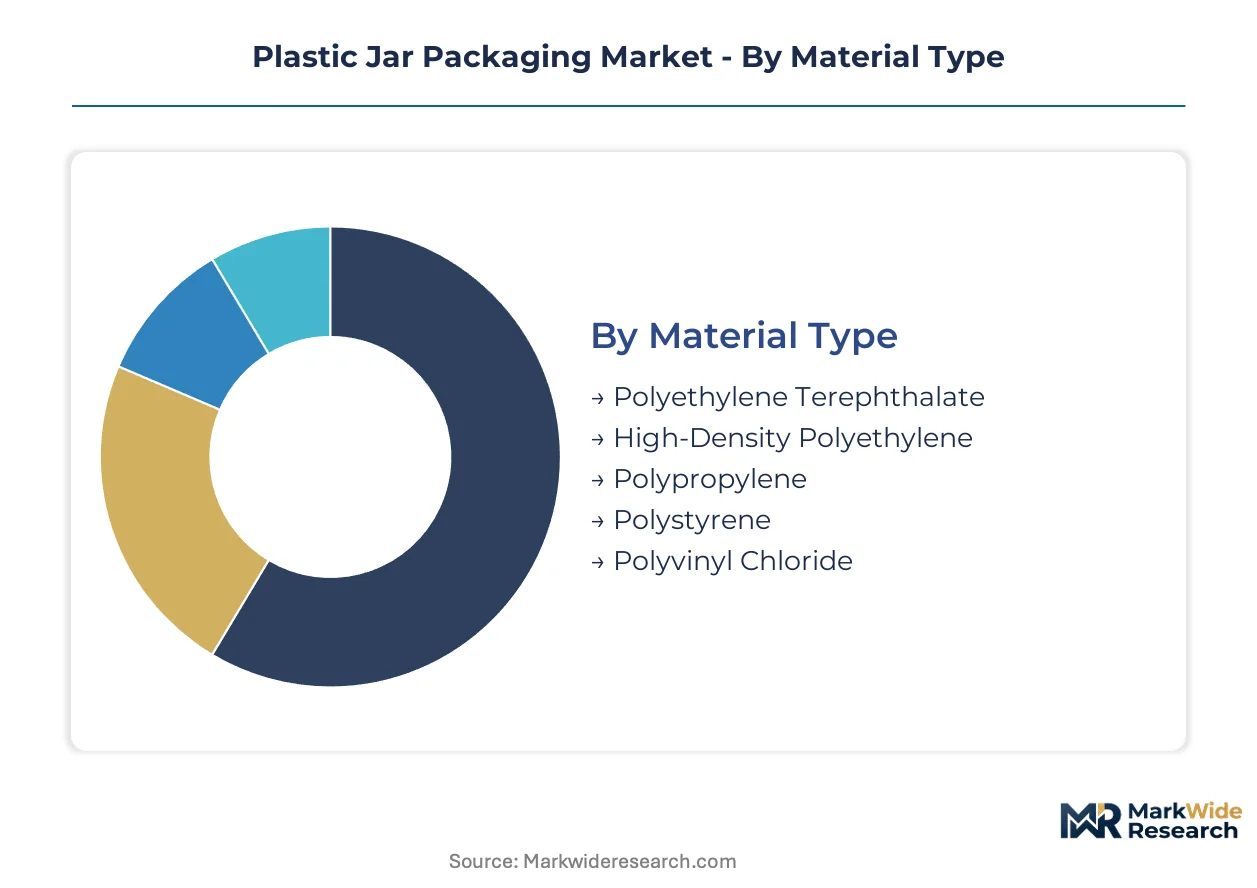
The plastic jar packaging market is segmented to reveal the diverse material preferences, functional requirements, and end-user applications that shape demand. Understanding these distinct segments assists manufacturers in tailoring product offerings and navigating regulatory complexities across various industries.
Material Type:
The material type segmentation highlights the spectrum from highly standardized, cost-effective polymers to specialized resins offering enhanced performance characteristics for specific applications.
- Polyethylene Terephthalate (PET):This material is valued for its exceptional clarity, lightweight nature, and strong barrier properties against oxygen and moisture, crucial for product preservation. Demand concentrates in the food and beverage industry, particularly for items requiring visual appeal and extended shelf life in regions like the United States and Europe.
- Polypropylene (PP):Offering good chemical resistance and a high melting point, polypropylene is a versatile and cost-effective polymer often used for commodity packaging. Its application is widespread in household chemicals and personal care products, where durability and affordability are key drivers for manufacturers in China and Southeast Asia.
- High-Density Polyethylene (HDPE):Known for its impact resistance and chemical inertness, HDPE is a robust choice for various industrial and consumer goods.
- Polystyrene (PS):Polystyrene provides rigidity and transparency, making it suitable for certain dry food items and cosmetic applications where a glass-like appearance is desired.
- Polyvinyl Chloride (PVC):While its use has declined in some regions due to environmental concerns, PVC offers excellent clarity and barrier properties for specific non-food packaging needs.
Leading the category by volume: Polyethylene Terephthalate. Growing fastest: Polypropylene.
Closure Type:
Product functionality and consumer convenience drive the differentiation within closure types, addressing specific dispensing and security needs across diverse product formulations.
- Screw Cap:This traditional closure provides a secure, re-sealable seal, essential for product integrity and preventing leakage. It remains a staple across food, pharmaceutical, and personal care segments due to its reliability and cost-effectiveness.
- Pump Dispenser:Offering controlled and hygienic product dispensing, pump dispensers are increasingly specified for lotions, creams, and gels. The personal care industry in North America and Europe drives significant innovation and demand for these specialized closures.
- Flip Top:Providing easy one-handed access, flip-top closures are popular for personal care items and condiments where quick application is valued.
- Snap-On:Snap-on closures offer a simple, secure, and often tamper-evident seal, frequently used for dry goods and some cosmetic products.
- Collar Cap:Collar caps provide an aesthetic finish and can integrate tamper-evident features, enhancing product presentation in premium segments.
Screw caps maintain broad utility, while pump dispensers are gaining market share in premium personal care applications.
End Use Industry:
The end-use industry segmentation reflects the diverse product categories that rely on plastic jar packaging, each with unique material and design requirements.
- Food & Beverage:This sector is the largest consumer of plastic jars, utilizing them for everything from sauces and spreads to snacks and dairy products. Clarity, barrier properties, and food-contact safety standards (e.g., FDA in the U.S., EFSA in Europe) are paramount for packaging integrity.
- Personal Care:The personal care industry demands aesthetically pleasing and functional jars for creams, lotions, and cosmetics, often integrating specialized closures and sustainable materials. Innovation in PCR content and design for recyclability is particularly important for brands targeting environmentally conscious consumers in Western markets.
- Pharmaceuticals:Plastic jars for pharmaceuticals require high purity, tamper-evidence, and strict compliance with regulations from bodies like the EMA and NMPA.
- Household Chemicals:This segment utilizes plastic jars for cleaning agents and detergents, prioritizing chemical resistance and robust construction.
- Pet Care:Plastic jars offer durable and convenient packaging for pet food, treats, and supplements, with an emphasis on freshness and ease of use.
The food and beverage industry accounts for the largest volume, while the personal care segment exhibits significant design innovation.
Jar Capacity:
Jar capacity influences packaging material choice, manufacturing processes, and target consumer segments, ranging from single-use portions to bulk industrial containers.
- 50ml:Small capacity jars cater to travel-size personal care products, premium samples, and specialized nutraceuticals. These often command higher per-unit margins due to their niche application and design requirements in markets like France and Germany.
- 250ml:This mid-range capacity is a versatile option for a wide array of products, including creams, sauces, and dry goods, balancing portability with sufficient product volume. It finds broad application across Europe and Asia, particularly in fast-moving consumer goods.
- 100ml:Widely used for cosmetics and small food portions, 100ml jars balance convenience with product quantity.
- 500ml:Larger 500ml jars are common for household chemicals, bulk food items, and some personal care products, offering economy of scale.
- 1000ml:These large capacity jars are typically employed for industrial supplies, bulk food ingredients, and institutional use, prioritizing durability and volume.
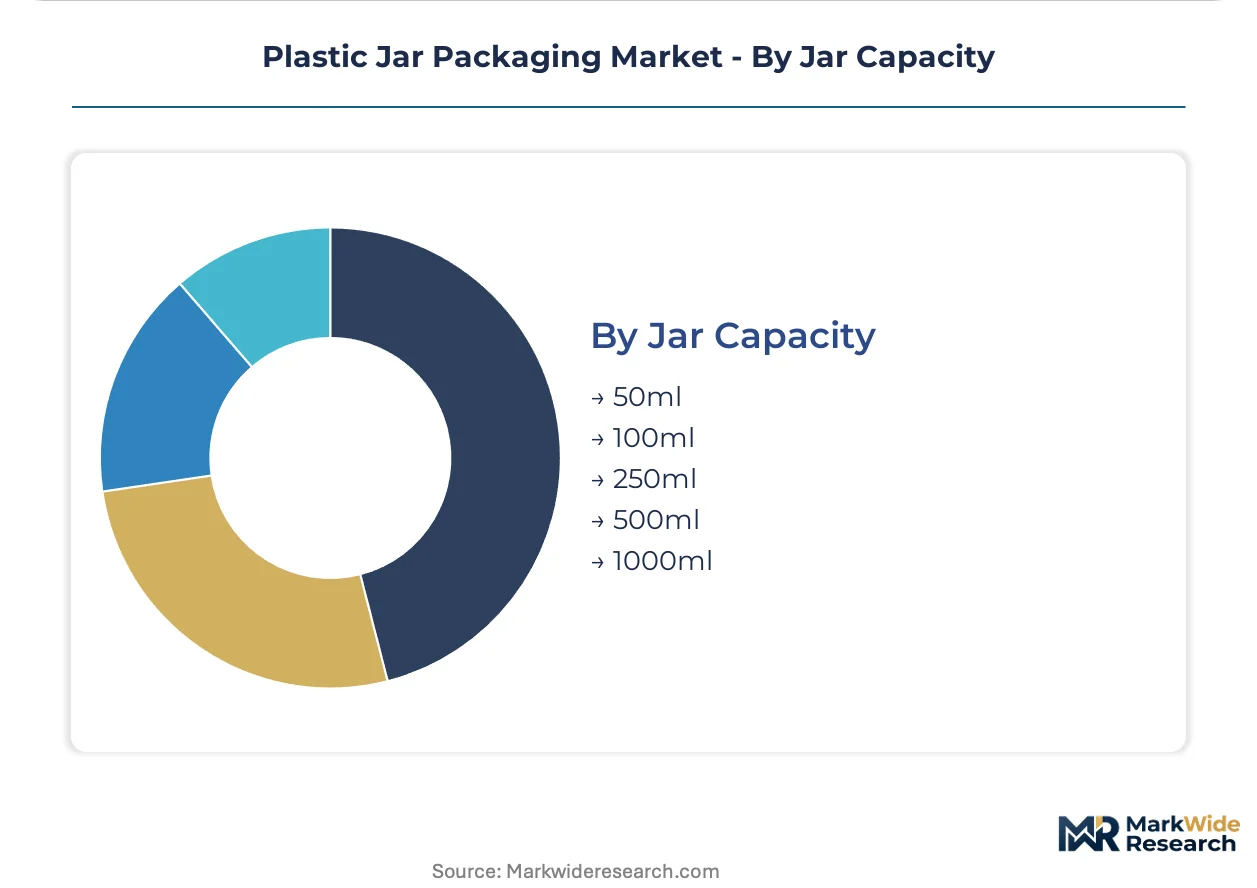
Smaller capacities such as 50ml cater to premium segments, while larger formats like 1000ml serve bulk consumer needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's robust manufacturing base drives significant plastic jar packaging demand, particularly for consumer goods destined for domestic and export markets. This concentration reflects the city's role as a major economic hub with extensive supply chain infrastructure. Regional regulatory frameworks increasingly influence material choices and product design across diverse industries.
China
Massive domestic consumption and a large consumer goods manufacturing sector propel demand for cost-effective plastic jars. The Chinese government's dual carbon goals encourage manufacturers to explore more sustainable packaging solutions, including recycled content. Industrial clusters in the Pearl River Delta region actively integrate advanced injection molding technologies for high-volume production.
United States
The vast food and beverage industry, alongside a thriving personal care sector, sustains high demand for plastic jar packaging. The FDA's stringent guidelines for food-contact materials directly impact resin selection, favoring PET for safety and clarity. Major packaging manufacturers in the Midwest supply a diverse range of industries, from agricultural products to household chemicals.
Germany
Europe's largest economy demonstrates strong demand for premium plastic jars, especially for pharmaceutical and high-end personal care products. Regulations like REACH and the EU's Corporate Sustainability Reporting Directive (CSRD) mandate material transparency and recyclability. The Rhine-Ruhr area hosts specialized chemical and packaging companies innovating in advanced polymer formulations.
India
Rapid urbanization and a growing middle class fuel the consumption of packaged food and personal care items, driving plastic jar market expansion. BIS standards for packaging materials ensure product quality and safety across various applications. Manufacturing hubs around Mumbai and Delhi are expanding capacity to meet the rising demand for affordable and durable containers.
Plastic Jar Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across material innovation and specialized application capabilities. This tiered structure reflects varying investment levels in R&D and regulatory compliance. Key strategic archetypes include large-scale commodity producers, specialized pharmaceutical packaging providers, and integrated consumer packaging solutions companies. Dominant competitive moves involve strategic partnerships with brand owners and continuous investment in advanced manufacturing technologies.
Within the scale-driven end of the market, Amcor Plc exemplifies global reach, leveraging its manufacturing footprint to serve multinational food and beverage clients. Berry Global Inc. anchors its position through high-volume, cost-effective jar solutions for the household chemicals sector. Gerresheimer AG represents a premium archetype, specializing in high-purity, sterile plastic jars for pharmaceutical and nutraceutical applications, meeting stringent regulatory requirements.
| Leading Market Players |
|---|
| Alpha Packaging |
| Pretium Packaging |
| Amcor Plc |
| All American Containers |
| RPC M&H Plastics |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Tim Plastics Inc. |
| Gerresheimer AG |
| Others |
Cost & Logistics Intelligence
Skilled labor concentrations in advanced injection molding across Germany and specialized polymer processing in the United States influence pricing-tier spreads for high-purity plastic jars. These regional cost differentials impact the final price points for both commodity and premium packaging solutions.
Pricing Analysis
Price points for plastic jars anchor to certified material purity and performance characteristics. The dominant pricing structure is per-unit transactional for commodity volumes, shifting to contract-based long-term agreements for specialized applications. Price differentiation stems from certification levels, such as FDA food-contact approval, and the volume scale of the order. Pricing softness runs through the commodity polypropylene segment due to volatile crude oil prices and intense competition. Pharmaceutical and nutraceutical buyers exhibit the least price sensitivity, prioritizing material integrity over cost.
Supply Chain Analysis
Single-source vulnerability for high-purity, food-contact PCR resin sits with a limited number of specialized recyclers. Geographic supply concentration for plastic jar manufacturing centers on China for high-volume commodity production, the United States for diverse industrial applications, and Germany for specialized pharmaceutical packaging. Raw material dependencies include Polyethylene Terephthalate (PET), Polypropylene (PP), and crude oil derivatives. A structural supply chain risk is the inconsistent quality of recycled feedstock. Distribution primarily occurs directly to large brand owners and through regional distributors for smaller consumer goods manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic jar packaging market is undergoing a technology-transition phase, with advanced sorting technology replacing traditional mechanical recycling methods for higher-grade PCR content.
For Market Incumbents:Deploy advanced manufacturing automation to enhance efficiency and reduce production costs, particularly for high-volume PET and PP jars. Invest in R&D for monolayer PET innovations to offer competitive barrier properties without recycling challenges, addressing the threat of substitution from glass. Expand global manufacturing footprints strategically to leverage regional cost advantages and serve multinational clients more effectively. Pursue certifications for food-contact recycled content to meet evolving regulatory mandates.
For New Entrants and Emerging Players:Enter via specialized niche markets, such as high-purity sterile jars for nutraceuticals or premium personal care products with integrated smart packaging features. The most penetrable segment for new entrants is smaller, environmentally conscious brands seeking validated sustainable packaging solutions. A strong go-to-market angle involves offering fully traceable, certified recycled content jars with transparent environmental footprint data to meet stringent EU CSRD requirements.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized packaging converters possessing strong intellectual property in advanced material science or recycling technologies, given the increasing regulatory pressure for circularity. Focus on companies that can provide high-purity, food-contact PCR solutions or develop innovative barrier technologies for single-layer plastics. Acquisition targets should include firms with established relationships in pharmaceutical or premium personal care segments. The signal to watch is the successful commercialization of food-contact-approved monolayer PET jars.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in PCR Processing | Increases the availability of high-quality recycled feedstock for brand owners. |
| Green Manufacturing Transition | Reduces operational environmental footprint, aligning with sustainability mandates for packaging. |
| Product Launch: Monolayer PET Jars | Addresses performance and recyclability challenges in a single packaging solution. |
| Strategic Partnership with Recyclers | Secures consistent supply of high-quality post-consumer recycled resin. |
| Certification Investment for Food-Contact Materials | Ensures compliance with FDA and EFSA regulations for sensitive applications. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic studies underwrites the qualitative findings and quantitative projections within this analysis. The research combined primary interviews with packaging manufacturers, brand owners, resin suppliers, and recycling facility operators. Secondary data sources included EU CSRD documents, FDA guidelines for food contact materials, and company annual reports, triangulated through bottom-up and top-down approaches.
Comparable-period analysis anchored the forecast window to historical reference periods, ensuring data consistency. The analytical framework integrated quantitative modeling and statistical analysis to project market trends across the analysis window. Segmentation dimensions modeled included material type, closure type, end-use industry, jar capacity, and regional regulatory clusters. Compound Annual Growth Rates were derived from regression analysis and market growth projections, incorporating polymer price indices and consumer spending on personal care as key inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unforeseen geopolitical events or rapid material science breakthroughs. The projections reflect assumptions about economic stability and consistent regulatory enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
PET Preforms Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Plastic Caulk Tube Market