
 Vertical Injection Molding Machine Market | 2026-2036
Vertical Injection Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Injection Molding Machine Market Intelligence
Multi-source procurement for servo-motor drives and control systems is broadening as Tier-1 suppliers reduce dependency on single Japanese component vendors. Nissei Plastic Industrial leverages in-house spindle manufacturing to sustain lead times for medical-grade machines. ENGEL competes through integrated automation cells that combine vertical presses with robotic handling. Sumitomo (SHI) Demag Plastics Machinery anchors European demand with localized assembly in Germany.
A vertical injection molding machine positions the clamping unit below the injection unit, enabling gravity-assisted insert placement and overmolding with clamp forces typically ranging from 20 to 500 tons. The configuration suits multi-component assembly where operators or automation load metal inserts, electronic substrates, or filter membranes before each cycle. Fully automatic electric systems command premium positioning in medical and electronics applications where repeatability below 0.01 mm and clean-room compatibility justify capital intensity. Hydraulic technology retains cost advantages in automotive component runs where shot weights exceed two kilograms and cycle consistency tolerances widen.
FDA enforces 21 CFR Part 820 quality system regulations that mandate process validation for medical device injection molding, directly elevating demand for machines with full parameter traceability and IQ/OQ/PQ documentation packages. CE marking under the EU Machinery Directive and ISO 20430 safety standards for injection molding machinery shape product design requirements for European market access. Stakeholders must weigh electric-hybrid technology transitions against residual hydraulic installed bases when planning capacity additions for multi-material automotive interiors.
Market Dynamics
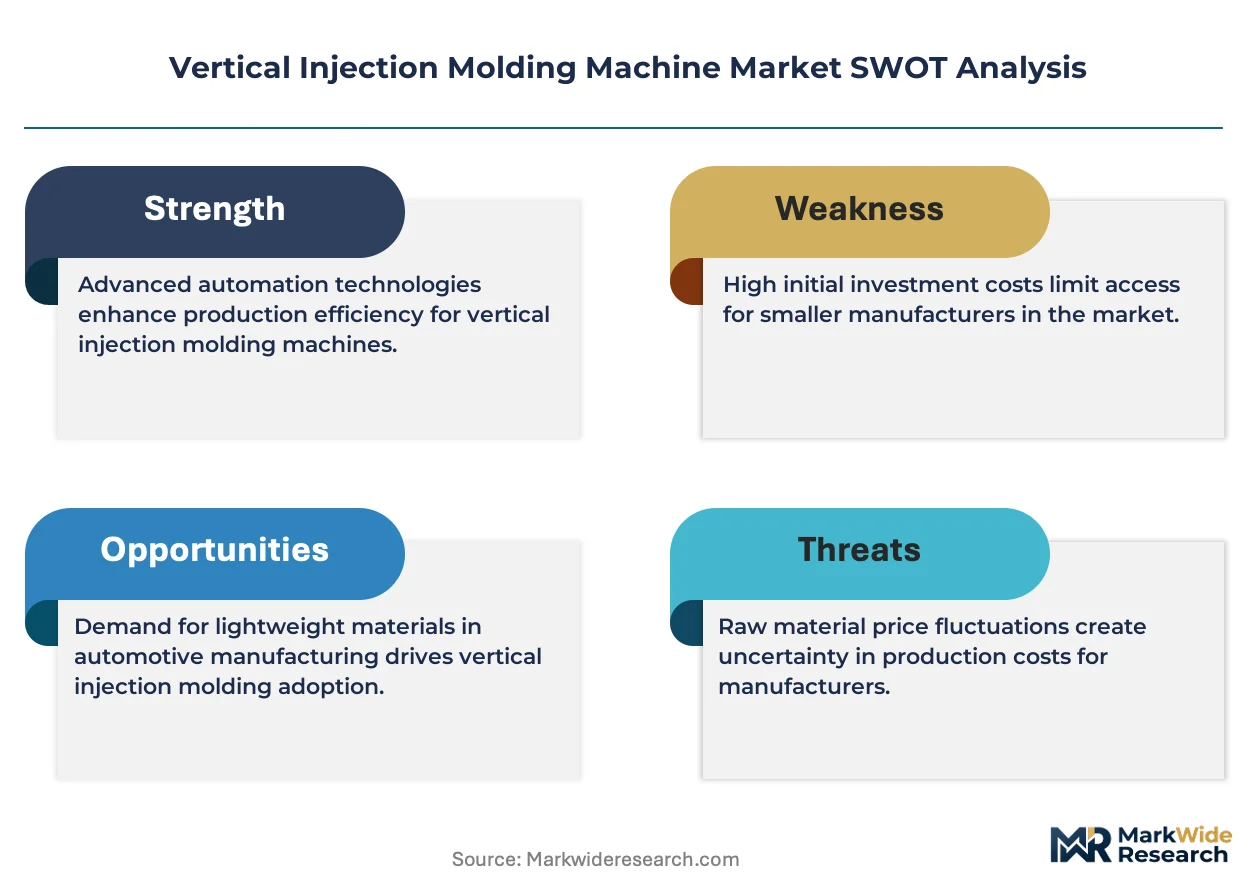
Electric-hybrid vertical presses are compressing cycle times for medical insert molding as FDA traceability mandates harden documentation requirements for implantable device manufacturers. This technology shift is redrawing competitive boundaries between hydraulic legacy installed bases and fully electric systems.
Growth Catalysts
- FDA 21 CFR Part 820:Process validation mandates for medical device injection molding elevate demand for machines with full parameter traceability and IQ/OQ/PQ documentation packages.
- Automotive multi-material interiors:Overmolding of soft-touch surfaces onto structural substrates requires gravity-assisted insert placement that vertical configurations optimize.
- German precision molding clusters:Concentrated demand from pharmaceutical packaging tiers and automotive OEMs sustains specialized vertical press procurement.
Market Restraints
- Servo-motor supply concentration:Dependency on Japanese spindle and drive component vendors creates lead time vulnerability for electric system manufacturers.
- Residual hydraulic installed base:Automotive component producers with shot weights exceeding two kilograms face switching costs that delay electric-hybrid transitions.
- CE marking compliance friction:EU Machinery Directive and ISO 20430 safety standards impose design certification timelines that extend product launch cycles.
Strategic Opportunities
- Clean-room automation convergence:Integration of vertical presses with robotic handling cells opens medical electronics and diagnostic cartridge production.
- India medical device manufacturing:CDSCO regulatory alignment with international standards creates procurement openings for traceability-compliant electric systems.
- Filter membrane overmolding:Bioprocessing and water treatment applications represent underpenetrated demand for insert-molding vertical configurations.
Industry Challenges
- Validation engineering talent scarcity:FDA IQ/OQ/PQ documentation expertise sits concentrated with specialized service providers, constraining manufacturer scale-up.
- Legacy system integration complexity:Electric press retrofits into existing hydraulic production lines require custom control architecture and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Injection Molding Machine Market |
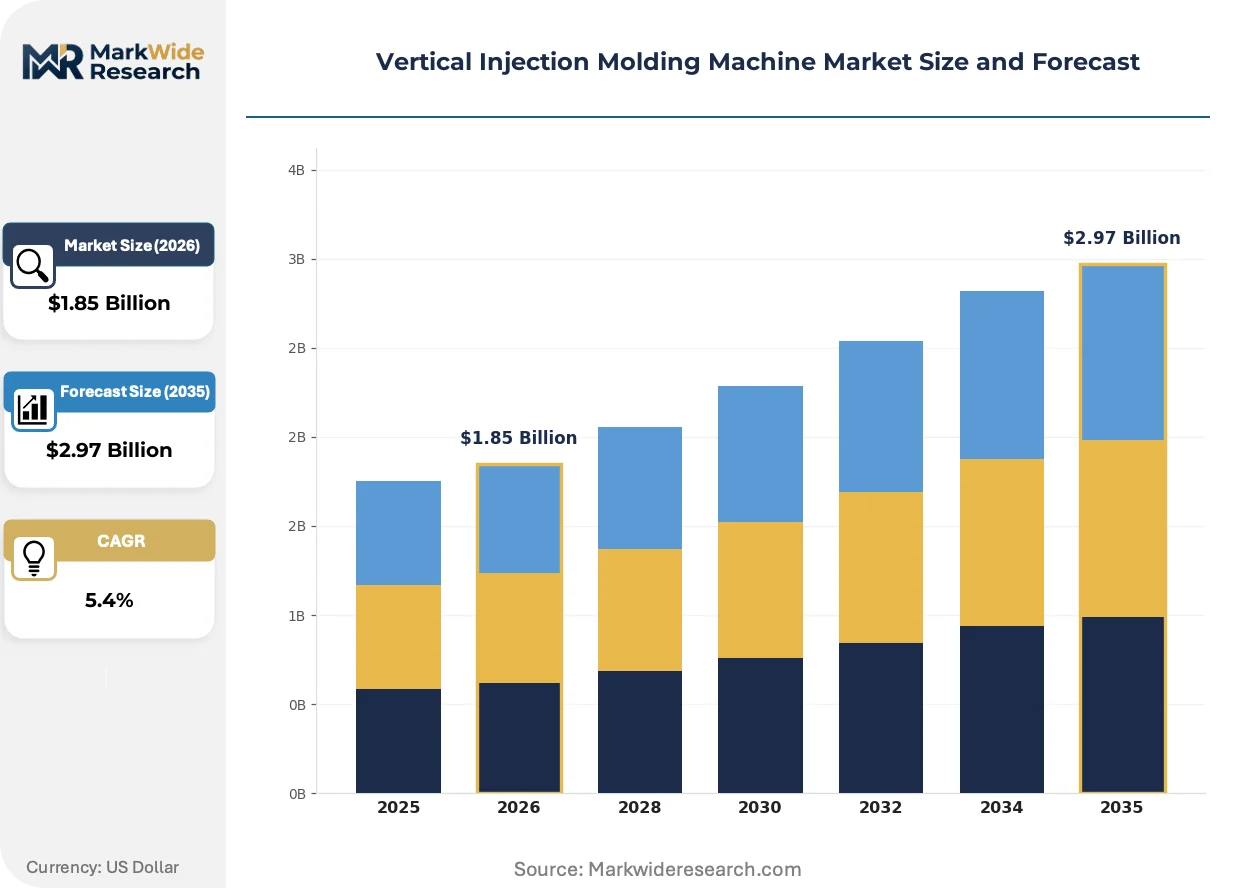
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Manual, Hybrid Application: Automotive Components, Medical Devices, Consumer Goods, Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Contract Manufacturers Technology: Electric, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Nissei Plastic Industrial, Wittmann Battenfeld, Sumitomo (SHI) Demag Plastics Machinery, Sodick, ENGEL, Fanuc Corporation, Toyo Machinery & Metal, Arburg, Japan Steel Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Injection Molding Machine Market Strategic Shifts & Innovations
Control system architectures are fragmenting as machine builders reduce dependency on single-source automation vendors. This supplier diversification is accelerating feature differentiation and compressing development cycles.
All-electric clamp and injection units is overtaking hydraulic systems in medical and electronics applications where repeatability below 0.01 mm justifies capital intensity. Implantable device manufacturers are specifying electric systems for traceability compliance. This displacement is compressing hydraulic technology to automotive runs with wider tolerance bands.
REACH substance restrictions and EU Green Deal carbon accounting requirements are reshaping material qualification protocols for European market access. Machine builders must document energy consumption and lubricant chemistry for CE marking packages. Medical packaging tiers in Germany are prioritizing electric systems for compliance visibility.
Buyer concentration among Tier-1 automotive and medical OEMs is consolidating procurement leverage and extending payment terms. Distributor networks are unbundling after-sales service contracts from hardware sales. This restructuring is most visible in German supply chains serving pharmaceutical packaging clusters.
Vertical Injection Molding Machine Market Segmentation
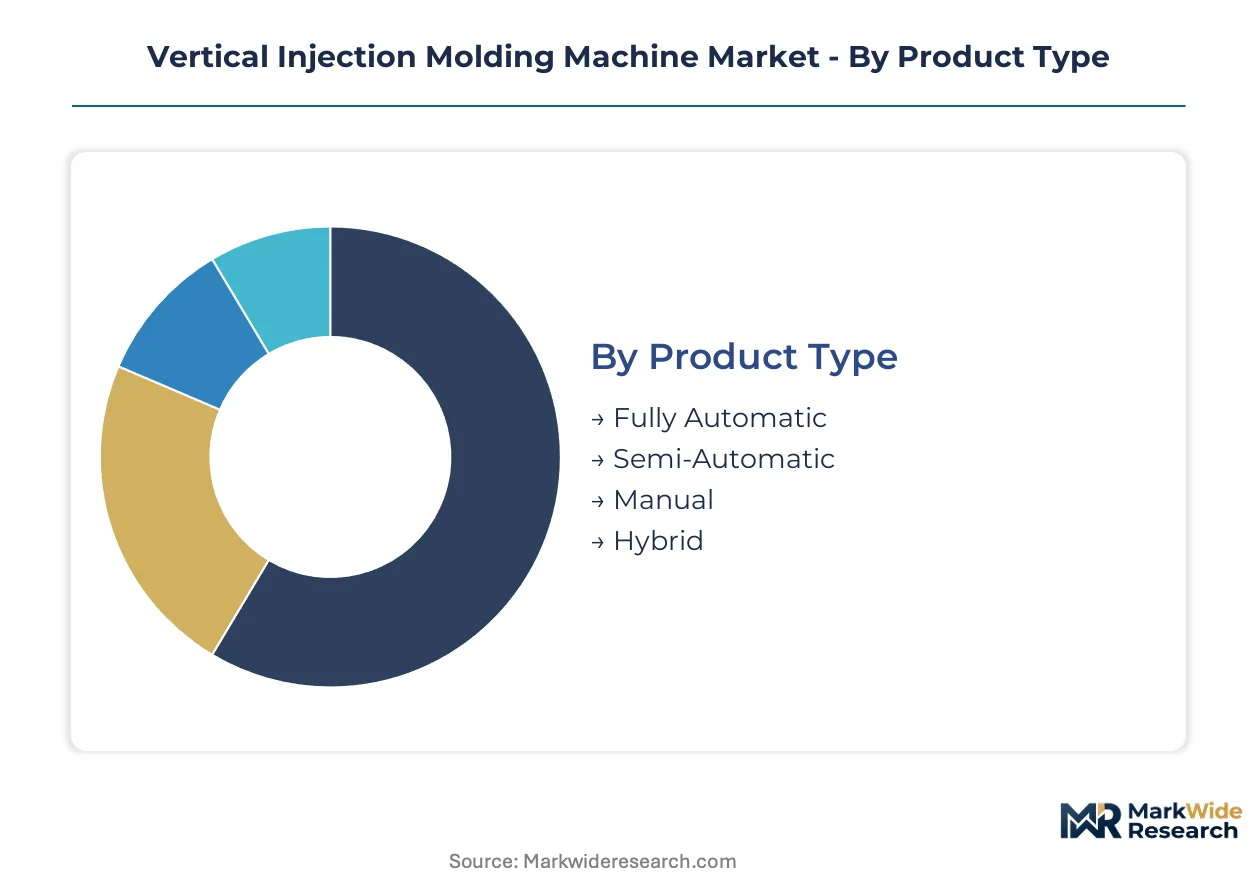
Vertical injection molding machine procurement splits across automation grades, end-use applications, and technology architectures that determine capital allocation cycles. Upgrade decisions hinge on regulatory compliance requirements, insert-molding complexity, and energy accounting mandates.
Product Type:
Replacement cycles accelerate as FDA traceability mandates and EU energy disclosure rules render older manual and semi-automatic systems non-compliant.
- Fully Automatic:Servo-driven clamp and injection units deliver repeatability below 0.01 mm with closed-loop parameter logging for IQ/OQ/PQ validation. Medical device OEMs in Germany and the United States specify these systems for implantable component production where FDA 21 CFR Part 820 demands full process traceability.
- Hybrid:Electric injection combined with hydraulic clamping balances precision against capital cost for automotive soft-touch overmolding runs. Tier-1 suppliers in Stuttgart and Wolfsburg procurement clusters favor hybrid configurations for multi-material interior components with shot weights between 500 grams and two kilograms.
- Semi-Automatic:Operator-assisted insert placement suits low-volume medical device prototyping and filter membrane overmolding where automation ROI remains unfavorable.
- Manual:Hand-loaded configurations persist in emerging market contract manufacturing for simple consumer goods with minimal regulatory burden.
Fully automatic systems sit at the top of the volume ranking, with hybrid configurations climbing the fastest as automotive producers split the difference between precision and capital efficiency.
Application:
Margin profiles diverge sharply across end-use segments, with medical and electronics applications commanding premium positioning against commodity automotive runs.
- Medical Devices:Implantable components, diagnostic cartridges, and drug delivery systems require clean-room-compatible electric systems with validated parameter traceability. FDA enforcement of 21 CFR Part 820 quality system regulations and EU MDR technical documentation requirements concentrate procurement among validated machine builders.
- Automotive Components:Multi-material interior overmolding of soft-touch surfaces onto structural substrates exploits gravity-assisted insert placement unique to vertical configurations. German OEMs anchor demand through specialized supply chains in Baden-Württemberg and Bavaria.
- Electronics:Connector overmolding and sensor encapsulation demand sub-0.01 mm repeatability for miniaturized components in consumer and industrial devices.
- Consumer Goods:Cost-sensitive production of handles, grips, and housings tolerates wider tolerance bands and longer cycle times.
Medical devices command the highest average selling prices, with electronics applications expanding most quickly on diagnostic and wearable device demand.
End User:
Procurement authority concentrates differently across the value chain, with OEMs dictating specifications that cascade to supplier tiers.
- OEMs:Medical device and automotive original equipment manufacturers specify machine platforms and validate processes directly, often mandating electric systems with full automation integration.
- Tier-1 Suppliers:Automotive interior and pharmaceutical packaging specialists operate captive molding capacity under OEM qualification programs.
- Contract Manufacturers:Electronics assembly services and medical device CMOs invest in flexible machine configurations to serve multiple customer validation requirements.
- Aftermarket Providers:Spare part and repair component producers utilize older hydraulic and semi-automatic systems with minimal compliance exposure.
OEMs sit at the top of the volume ranking, with contract manufacturers climbing the fastest as outsourcing trends deepen across medical and electronics verticals.
Technology:
Energy accounting requirements and precision mandates are compressing the addressable market for legacy hydraulic and mechanical systems.
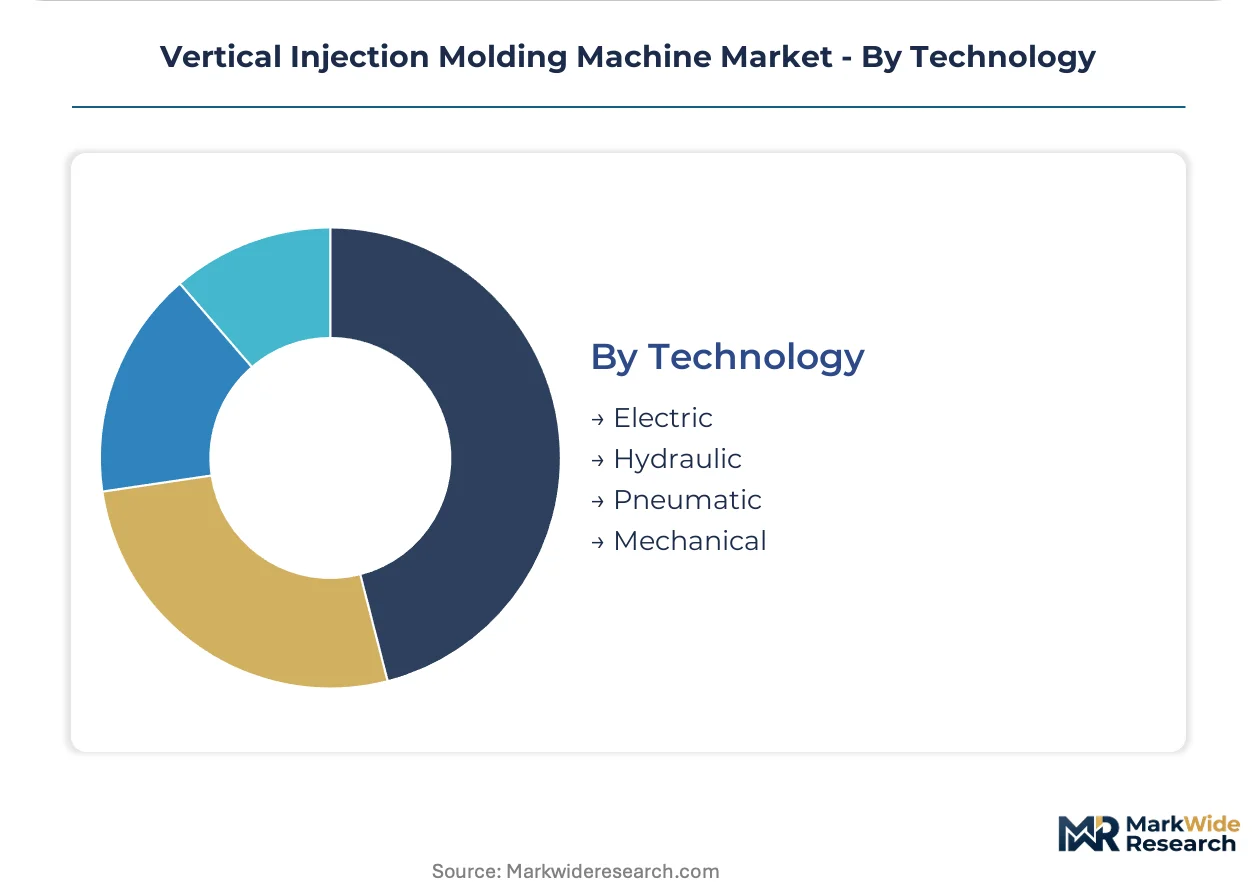
- Electric:All-electric clamp and injection units eliminate hydraulic fluid contamination risk while delivering positional repeatability below 0.01 mm. EU Green Deal carbon accounting and REACH substance restrictions favor electric systems for European market access.
- Hydraulic:High-tonnage clamping force and lower capital cost retain relevance for automotive structural components with shot weights exceeding two kilograms and tolerance bands above 0.05 mm.
- Pneumatic:Limited to low-force applications in specialized consumer goods and laboratory equipment with minimal precision requirements.
- Mechanical:Obsolescent technology confined to legacy installed bases and emerging market aftermarket production.
Electric systems sit at the top of the volume ranking, with hydraulic technology retaining position in heavy-shot automotive applications despite share erosion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement geography as medical device manufacturers migrate production toward jurisdictions with streamlined compliance pathways and concentrated precision-molding infrastructure. Cost-of-compliance gaps between FDA-enforced traceability mandates and emerging-market regulatory alignment programs are redirecting capital flows across three continents.
Germany
Automotive OEMs and pharmaceutical packaging tiers sustain specialized vertical press demand through precision-molding clusters in Baden-Württemberg and Bavaria. EU Machinery Directive CE marking requirements and ISO 20430 safety standards shape machine design specifications for European market access. Stuttgart and Wolfsburg procurement networks anchor multi-material interior overmolding capacity for Tier-1 suppliers.
United States
Implantable device manufacturers drive electric system procurement as FDA 21 CFR Part 820 quality system regulations harden process validation requirements. The agency's enforcement of IQ/OQ/PQ documentation packages elevates demand for machines with full parameter traceability. Medical device production concentrates in Minnesota and Massachusetts corridors serving diagnostic and surgical instrument OEMs.
China
Domestic medical device manufacturing expansion and export-oriented electronics assembly sustain hybrid and electric system demand. NMPA regulatory alignment with international standards accelerates traceability-compliant machine adoption. Yangtze River Delta and Pearl River Delta industrial zones concentrate contract manufacturing capacity for multinational device companies.
India
CDSCO regulatory harmonization with FDA and EU MDR standards creates procurement openings for validation-ready electric vertical presses. Government PLI scheme incentives for medical device manufacturing attract molding capacity investment. Maharashtra and Gujarat industrial corridors host emerging contract manufacturing operations serving export markets.
Japan
PMDA quality system requirements and METI industrial policy support precision machinery exports to medical and electronics end-users. Domestic machine builders leverage in-house component manufacturing to sustain lead times for medical-grade systems. Nagoya and Osaka industrial zones anchor servo-motor and control system supply chains.
Vertical Injection Molding Machine Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue clean-room automation convergence and regional assembly localization. Market structure consolidates around precision-molding specialists with validated documentation capabilities and diversified component sourcing. Three archetypes dominate: integrated automation cell providers, in-house spindle manufacturers, and localized assembly operators. Competitive moves center on supplier diversification for servo-motor drives and strategic partnerships for validation engineering services.
Among German precision-molding specialists, Wittmann Battenfeld and ENGEL occupy positions exemplifying integrated automation and medical-grade system architecture. Japanese machinery builders Nissei Plastic Industrial represent the in-house manufacturing archetype through captive spindle production capabilities. Sumitomo (SHI) Demag Plastics Machinery anchors European demand through localized assembly operations in Germany.
| Leading Market Players |
|---|
| Nissei Plastic Industrial |
| Wittmann Battenfeld |
| Sumitomo (SHI) Demag Plastics Machinery |
| Sodick |
| ENGEL |
| Fanuc Corporation |
| Toyo Machinery & Metal |
| Arburg |
| Japan Steel Works |
| Others |
Cost & Logistics Intelligence
Captive in-house spindle manufacturing at Nissei Plastic Industrial and Fanuc Corporation anchors supply security for medical-grade electric systems while compressing procurement leverage for competitors dependent on outsourced Japanese servo-motor components. This backward integration into precision drive systems simultaneously insulates lead times and supports premium pricing for FDA-validated machine platforms serving implantable device manufacturers.
Pricing Analysis
Distributor margin compression runs through German pharmaceutical packaging supply chains as OEMs consolidate procurement authority and extend payment terms to Tier-1 suppliers. Three-tier pricing structure across premium, standard, and economy levels separates fully electric medical systems with IQ/OQ/PQ documentation packages from hybrid automotive configurations and legacy hydraulic units for aftermarket production. Cost compression in standard-tier hybrid systems is intensifying because automotive OEMs are splitting volume between precision requirements and capital efficiency targets. Contract manufacturers exhibit the highest price sensitivity due to multi-customer validation requirements, while medical device OEMs accept premium positioning for traceability compliance.
Supply Chain Analysis
Servo-motor and precision spindle supply rests on Japanese specialty machinery producers in Nagoya and Osaka industrial zones, with secondary sourcing emerging from German automation component specialists in Baden-Württemberg. Critical inputs include high-torque AC servo drives, linear motion guides, and medical-grade control system architectures. Single-source vulnerability concentrates in rare-earth magnet supply for permanent-motor assemblies, creating exposure to export restriction dynamics. Distribution runs through manufacturer-direct sales teams for large OEM accounts and specialized industrial machinery distributors serving contract manufacturing segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertical injection molding machine market functions as a regulatory compounder where FDA 21 CFR Part 820 traceability mandates and EU MDR technical documentation requirements continuously elevate compliance barriers and sustain premium pricing for validated electric systems.
For Market Incumbents: To counter servo-motor supply concentration risk, machine builders should diversify spindle sourcing toward German and South Korean component vendors while investing in captive validation engineering capabilities to reduce dependency on scarce third-party IQ/OQ/PQ documentation specialists. Capacity expansion in India leverages CDSCO regulatory harmonization and PLI scheme incentives to capture emerging medical device manufacturing investment. For New Entrants and Emerging Players: Launch via clean-room automation integration partnerships targeting diagnostic cartridge and medical electronics contract manufacturers in China's Yangtze River Delta. Filter membrane overmolding for bioprocessing applications represents the most penetrable white-space segment, with go-to-market positioning centered on validated parameter traceability for single-use bioreactor component production. For Investors and Strategic Acquirers: Roll-up economics work for regional validation engineering service providers because FDA documentation expertise sits concentrated with specialized firms that medical device OEMs mandate for machine qualification. Long-term viability favors platforms with diversified component sourcing and automation integration capabilities. The inflection signal to monitor is CDSCO regulatory enforcement intensity in Maharashtra and Gujarat industrial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Manufacturing | Nissei's captive production model insulates lead times against Japanese component supply volatility. |
| Clean-Room Automation Convergence | ENGEL's integrated cells capture diagnostic cartridge demand from Roche and Abbott supply chains. |
| Regional Assembly Localization | Sumitomo's German operations reduce CE marking compliance friction for European medical device OEMs. |
| Validation Engineering Service Acquisition | IQ/OQ/PQ documentation scarcity constrains manufacturer scale-up and creates specialist rollup opportunities. |
| India Manufacturing Footprint Expansion | PLI scheme incentives attract molding capacity investment for export-oriented medical device production. |
Research Approach
Bottom-up medical device and automotive component modeling reconciled against top-down machinery production tracking forms the analytical core of this study. Primary interviews with plant engineers at Tier-1 automotive suppliers, biomedical engineers at implantable device manufacturers, GPO contracts managers at hospital systems, and aftermarket service heads at distributor networks combined with secondary validation from FDA 510(k) filings, CE marking databases, EU MDR technical documentation registries, and customs trade data for injection molding machinery. This dual-approach triangulation ensures demand-side consumption patterns align with supply-side production capacity disclosures.
Historical trendline analysis of electric-hybrid technology transitions and regulatory compliance investment cycles established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include automation grade, end-use application, technology architecture, and regional regulatory cluster. CAGRs derived from fitted trend analysis incorporate medical device outsourcing intensity, automotive multi-material interior content expansion, and energy accounting mandate adoption as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA enforcement escalation or sudden servo-motor supply disruption scenarios. Forecasts reflect documented assumptions regarding regulatory alignment timelines and technology substitution elasticities. A small set of triggers—including CDSCO enforcement intensity, EU Green Deal carbon accounting implementation pace, and Japanese spindle export policy shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Pre-Made Pouch Packaging Machines Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Global Blow Fill Seal Equipment Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Pulp Molding Machines Market
Packaging Machinery
Capsule Filling Machines Market