
 South Africa Plastic Bottles Market | 2026-2036
South Africa Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Plastic Bottles Market Insights
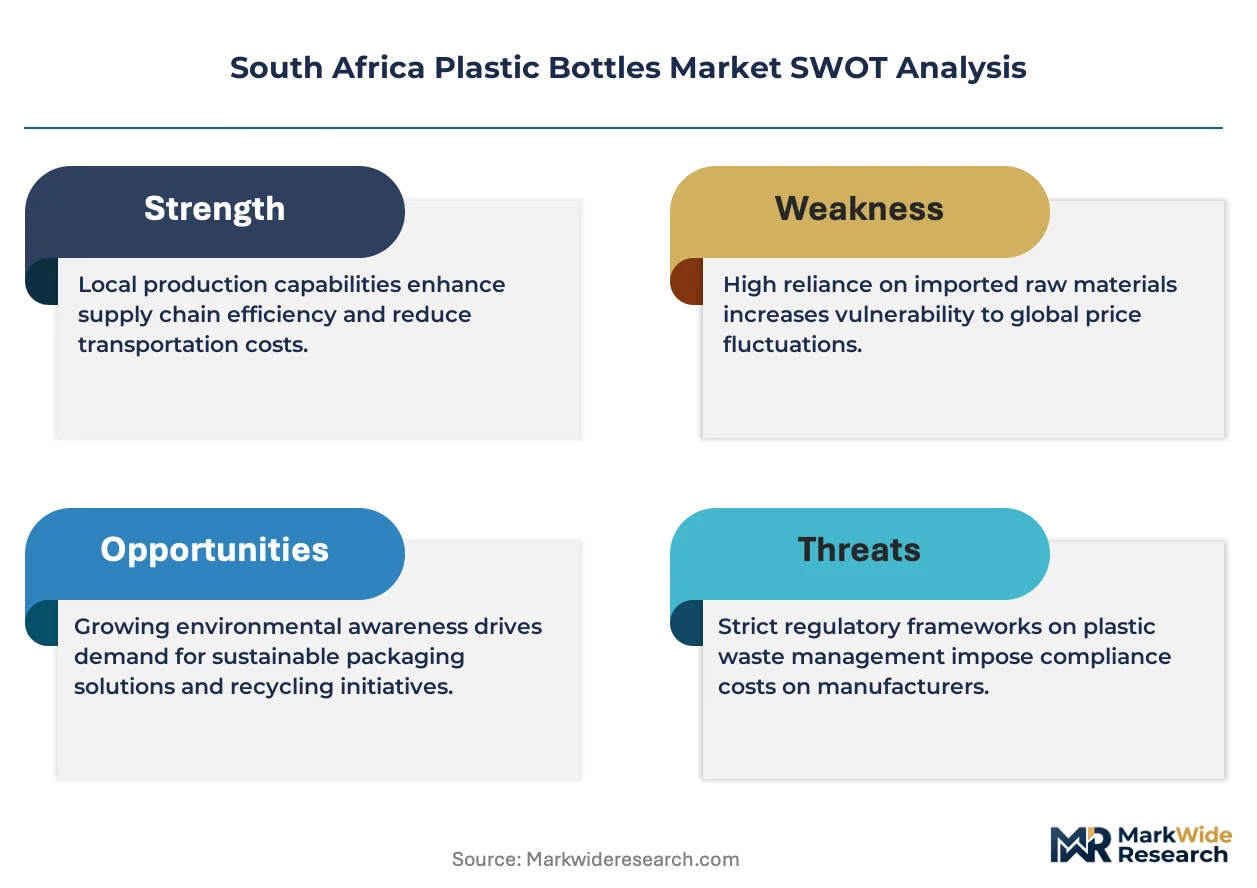
The price-performance gap between premium barrier-enhanced bottles and commodity-grade containers is hardening in South Africa. Mpact Group leverages integrated recycling and blow-molding assets to control cost positions in standard PET. Alpla Group anchors technical bottle supply for carbonated soft drinks through its Johannesburg operations. Berry Global Inc. differentiates via multilayer and hot-fill technologies aimed at shelf-stable beverages and personal care applications.
Plastic bottles are hollow thermoplastic containers produced through extrusion blow molding, injection stretch blow molding, or reheat stretch blow molding, with wall thickness, neck finish precision, and barrier properties engineered to contents. PET dominates South African volume due to clarity, recyclability, and compatibility with existing beverage filling lines. HDPE competes in household and pharmaceutical segments where chemical resistance and squeezability command premium placement. The 500ml and 2L size brackets carry the heaviest throughput, though 5L containers for household chemicals and bulk water are expanding fastest as retail formats shift toward value sizing.
The National Environmental Management Waste Act and South Africa's extended producer responsibility regulations mandate minimum recycled content thresholds and collection targets, forcing converters to certify rPET sourcing or face market exclusion. Bureau of Standards South Africa (SABS) testing protocols and FDA-equivalent food-contact compliance requirements shape import substitution dynamics, as European and Asian suppliers must validate material safety for local dairy and juice bottlers. Stakeholders must track EPR fee escalations and rPET feedstock availability, since domestic flake supply remains constrained against aggressive brand-owner sustainability commitments.
Market Dynamics
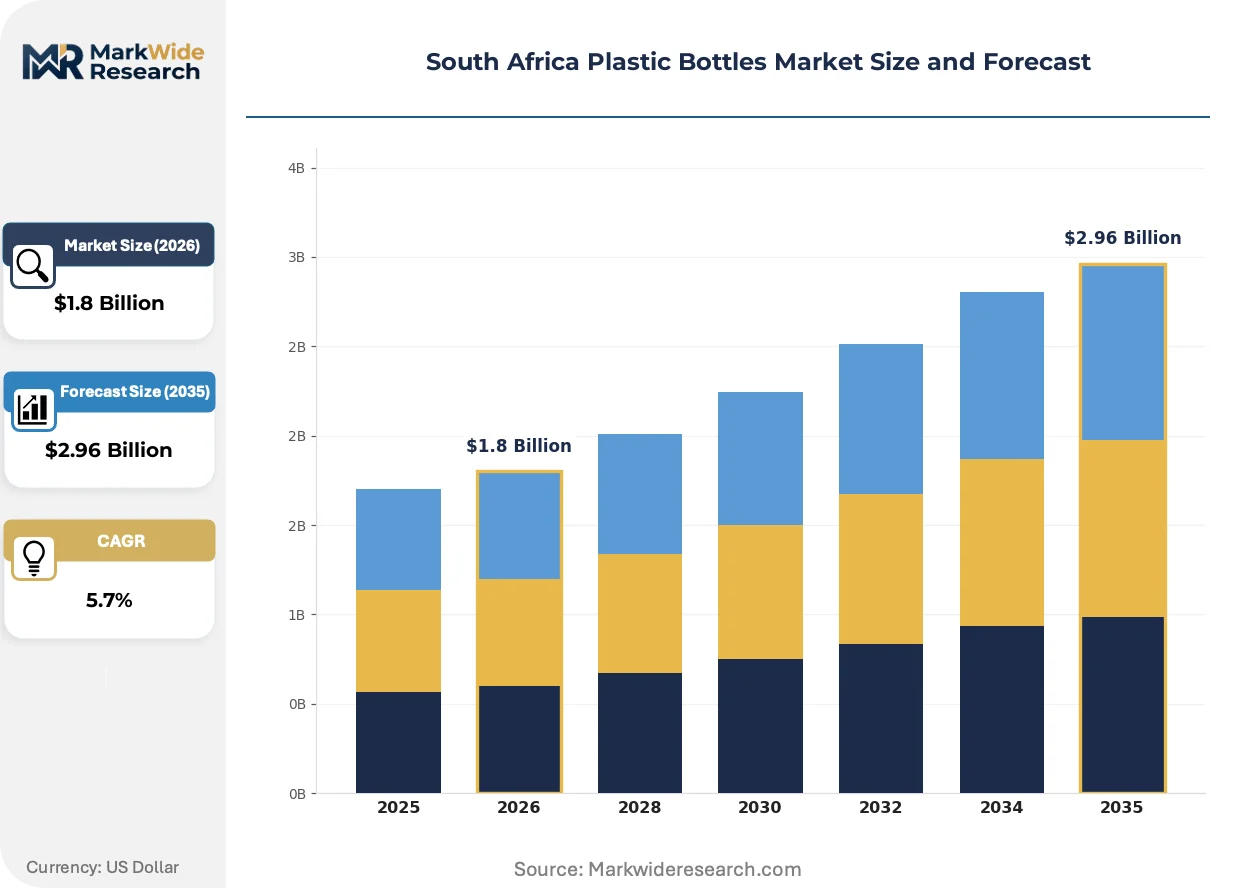
Extended producer responsibility regulations under South Africa's National Environmental Management Waste Act are forcing converters to reengineer supply chains around certified rPET sourcing and lightweighting investments, compressing margins for non-compliant suppliers while rewarding integrated recyclers.
Growth Catalysts
- EPR Mandates:South Africa's extended producer responsibility regulations mandate minimum recycled content thresholds, compelling beverage bottlers to certify rPET sourcing and locking in demand for domestic recycling capacity.
- Beverage Line Expansion:Coca-Cola Beverages South Africa and other majors are expanding PET bottling capacity in Gauteng and the Western Cape, driving converter investment in blow-molding assets near Johannesburg-Pretoria and Cape Town industrial zones.
- Lightweighting Technologies:Advanced preform design and material distribution software are enabling gram-weight reductions in standard PET bottles, cutting resin costs while maintaining burst-pressure performance for carbonated applications.
Market Restraints
- rPET Feedstock Scarcity:Domestic PET flake supply remains constrained against aggressive brand-owner sustainability commitments, forcing converters to import recycled material at premium landed costs or face volume shortfalls.
- Input Cost Volatility:Virgin PET resin prices track naphtha and paraxylene feedstock swings, exposing blow-molders to margin compression when oil markets spike without corresponding pricing power with retail customers.
- Technical Barrier Limitations:Standard monolayer PET lacks oxygen and CO2 retention for extended shelf-life applications, restricting penetration into premium juice and functional beverage segments without costly multilayer or coating investments.
Strategic Opportunities
- Underpenetrated Bulk Formats:The 5L household chemical and bulk water container segment is expanding fastest as South African retail formats shift toward value sizing, creating white space beyond the saturated 500ml and 2L brackets.
- Hot-Fill Technology Convergence:Integration of heat-set PET with aseptic filling lines is opening shelf-stable beverage applications previously reserved for glass or multilayer structures, targeting dairy and juice bottlers in KwaZulu-Natal.
- SABS Certification Arbitrage:Bureau of Standards South Africa testing protocols create import substitution dynamics, as local converters with validated material safety credentials capture share from European and Asian suppliers facing compliance delays.
Industry Challenges
- rPET Quality Certification Timeline:FDA-equivalent food-contact compliance and SABS validation for recycled content requires 12-18 month testing cycles, delaying converter qualification for brand-owner supply agreements.
- Legacy Equipment Retrofit Costs:Existing injection stretch blow molding lines require capital-intensive modifications to process high percentages of rPET without yellowing or IV degradation, straining mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Plastic Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Beverages, Household, Personal Care, Pharmaceuticals Size: 500ml, 1L, 2L, 5L Shape: Round, Square, Rectangular, Specialty |
| Companies Covered | Berry Global Inc., Alpla Group, Mpact Group, Bericap Holding GmbH, Nioro Plastics Pty Ltd., Nampak Bevcan, Polyoak Packaging Group, Alpla Packaging SA, RN Plastics Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Plastic Bottles Market Trends and Innovations
Converter investment patterns in South Africa are pivoting from capacity expansion toward material circularity and process efficiency, with technology choices increasingly dictated by EPR compliance timelines rather than pure unit economics.
Reheat stretch blow molding with advanced preform heating profiles is overtaking conventional extrusion blow molding for carbonated soft drink bottles. Beverage bottlers in Gauteng are adopting these lines at replacement-cycle pace to achieve lighter gram weights without sacrificing top-load strength. The technology is overtaking older equipment in the Johannesburg-Pretoria corridor, compressing demand for legacy extrusion assets and rewarding converters with in-house preform injection capability.
South Africa's National Environmental Management Waste Act amendments are tightening EPR fee structures and collection targets for plastic packaging producers. The industrial consequence is forced backward integration into recycling infrastructure or long-term offtake agreements with certified flake suppliers. Personal care and dairy bottlers are most affected, with many redirecting capex from greenfield blow-molding plants to rPET washing and pelletizing joint ventures.
Brand-owner procurement teams are consolidating supplier panels around certified circularity credentials rather than unit pricing alone. The shift is compressing the viable vendor base for Coca-Cola Beverages South Africa and other majors, with SABS-validated converters displacing uncertified competitors in Western Cape supply agreements. This pattern is most visible in Cape Town industrial zones, where converter clusters with integrated recycling assets are capturing disproportionate share of new volume awards.
South Africa Plastic Bottles Market Segmentation
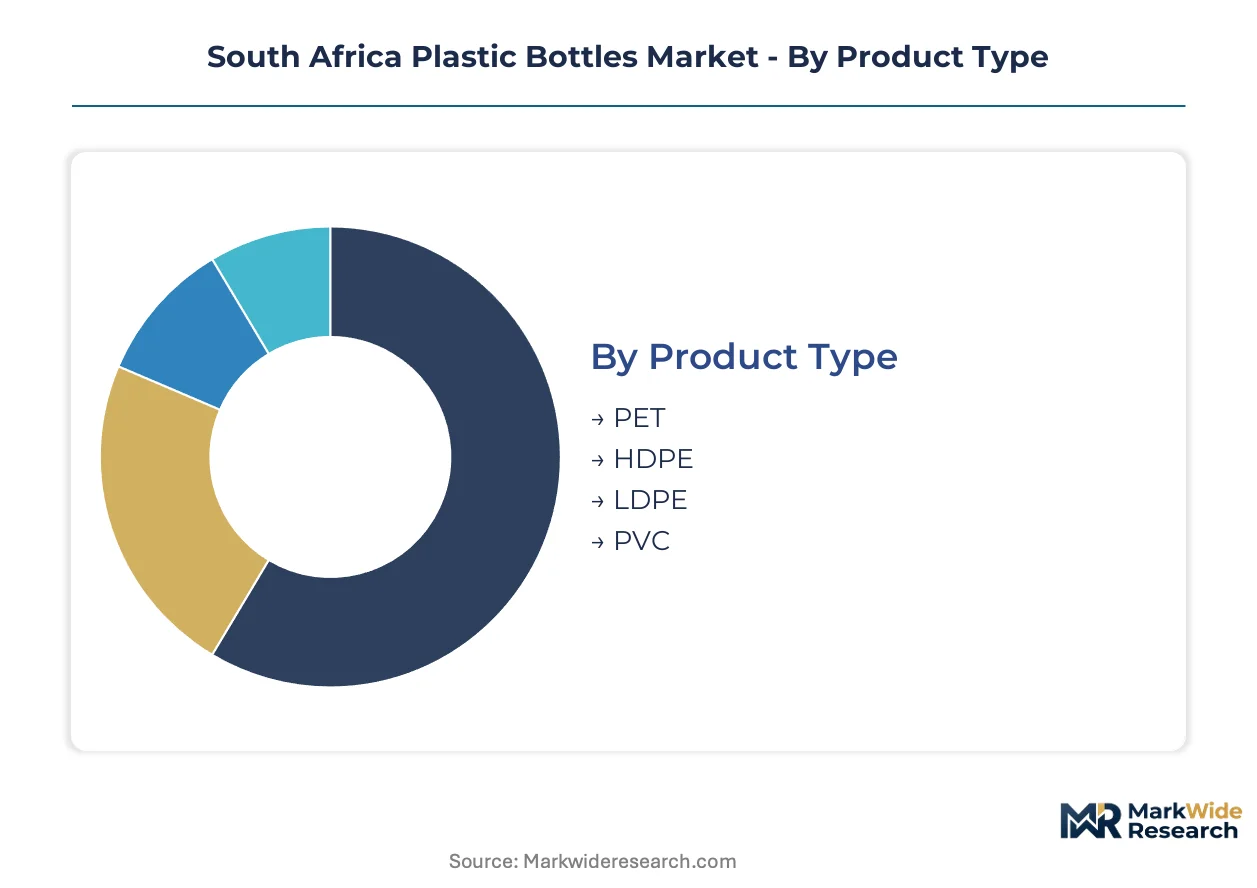
Segmentation in South Africa's plastic bottles market reveals how capital deployment and regulatory pressure concentrate across material grades and end-use applications. Understanding these divides exposes where converters must invest to maintain supply relationships with major beverage and personal care bottlers.
Product Type:
PET commands the heaviest upfront capital burden due to injection stretch blow molding lines and preform tooling requirements, while commodity polyolefins run on lower-cost extrusion equipment.
- PET:Injection stretch blow molding produces crystal-clear containers with precise neck finishes calibrated to Coca-Cola Beverages South Africa filling lines. Demand concentrates in Gauteng and Western Cape beverage corridors where EPR mandates now require certified rPET sourcing. The National Environmental Management Waste Act thresholds are forcing converters to validate food-contact compliance through SABS protocols before securing volume contracts.
- HDPE:Extrusion blow molding yields chemical-resistant, squeezable containers favored by household and pharmaceutical bottlers. Mpact Group leverages integrated recycling assets to control resin costs in this segment, capturing share from import-dependent competitors when oil price spikes compress margins.
- LDPE:Soft, flexible extrusion outputs serve squeeze tubes and dispensers where low stiffness permits one-handed dispensing.
- PVC:Rigid calendered and blow-molded forms persist in pharmaceutical blister and bottle applications demanding barrier stability.
PET absorbs the bulk of installed capacity; 5L bulk formats in HDPE are expanding most quickly as retail shifts toward value sizing.
End User:
Application-driven margin structures separate beverage bottlers, who negotiate on scale, from pharmaceutical customers who pay premiums for batch traceability and SABS validation.
- Beverages:Carbonated soft drinks, juices, and bottled water drive the highest volume throughput, with Coca-Cola Beverages South Africa and other majors consolidating supplier panels around certified circularity credentials. The 500ml and 2L brackets dominate, though hot-fill PET technology is opening shelf-stable dairy and juice applications previously reserved for glass.
- Household:Cleaning chemicals and bulk water containers in 5L formats are climbing fastest as supermarket chains expand value-size shelf space. Berry Global Inc. targets this segment with multilayer structures for aggressive chemical compatibility.
- Personal Care:Shampoos, lotions, and cosmetics demand aesthetic surface finishes and precise dispensing features that command 15-25% resin premiums over commodity grades.
- Pharmaceuticals:Child-resistant closures, light-blocking pigments, and batch-level traceability requirements limit the viable supplier base to converters with validated cleanroom capabilities.
Beverage applications dominate converter revenue; household chemical containers are gaining share fastest as retail formats evolve.
Size:
Equipment utilization rates diverge sharply between high-throughput 500ml lines and lower-volume 5L formats requiring specialized blow-pin configurations.
- 500ml:Standard beverage single-serve format running at maximum line speeds on reheat stretch blow molding equipment. Alpla Group anchors supply for this bracket through Johannesburg operations serving Gauteng bottlers.
- 1L:Mid-size juice and functional beverage niche with growing penetration in convenience retail channels.
- 2L:Family-size carbonated soft drink standard, with lightweighting investments focused here to maintain burst pressure while cutting resin grams.
- 5L:Bulk water and household chemical expansion segment where converter clusters in Cape Town industrial zones are adding dedicated large-format blow-molding capacity.
The 500ml and 2L brackets carry the heaviest installed base; 5L containers are climbing fastest as value sizing penetrates South African retail.
Shape:
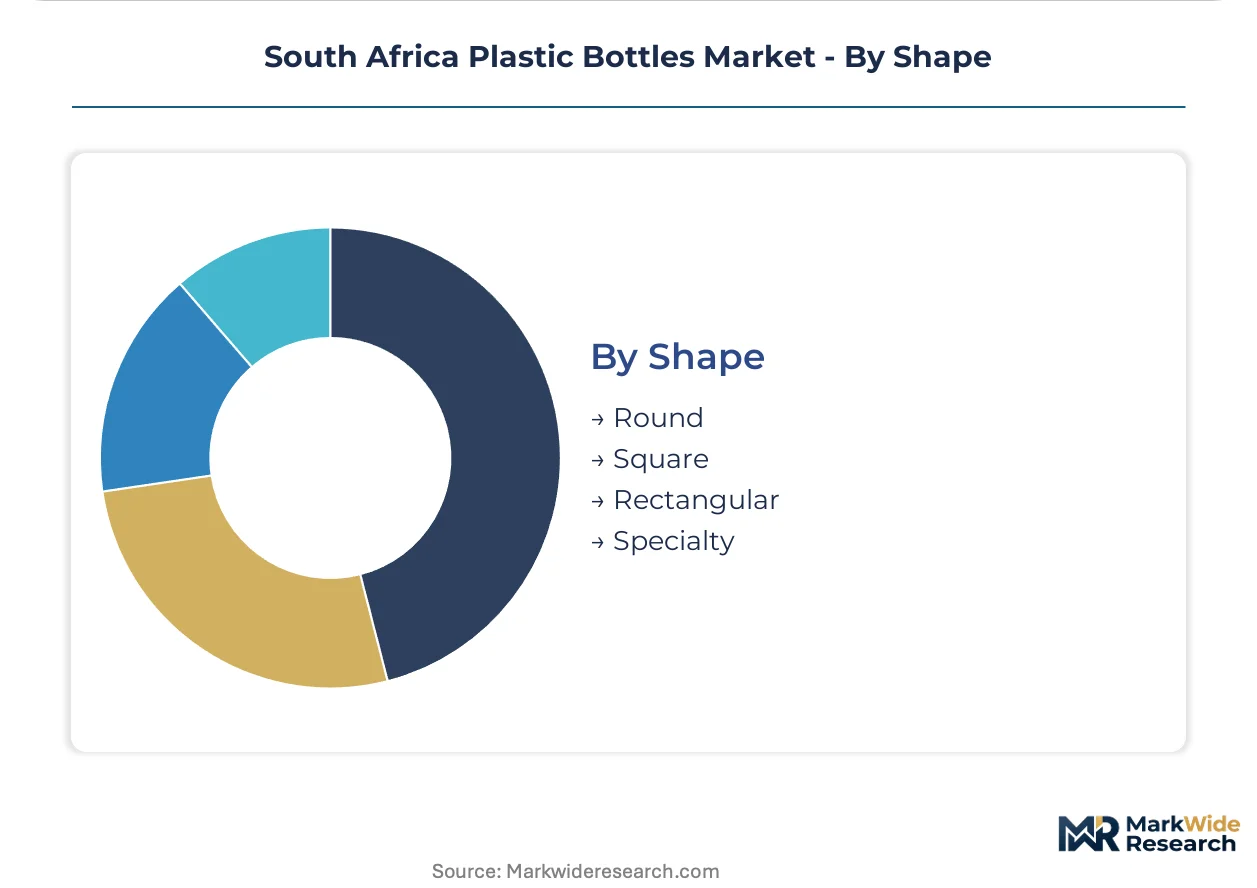
Tooling amortization schedules favor round geometries with standardized cavity counts, while custom shapes demand dedicated mold investments that smaller converters cannot justify.
- Round:Universal beverage and chemical container geometry maximizing volume-to-surface efficiency and minimizing wall thickness variation during blow molding.
- Square:Space-efficient palletization for household chemicals and bulk water, with flat panels enabling label adhesion without curvature distortion.
- Rectangular:Personal care and pharmaceutical preference for shelf presence and dispensing ergonomics in bathroom and kitchen storage.
- Specialty:Custom ergonomic grips, asymmetric shoulders, and brand-differentiated silhouettes requiring proprietary mold investments and longer lead times.
Round geometries absorb the majority of blow-molding machine hours; square formats are expanding most quickly in bulk chemical and water applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Johannesburg-Pretoria corridor anchors South African plastic bottle demand, with converter clusters in Gauteng and the Western Cape serving beverage bottlers and personal care manufacturers under tightening EPR regulations.
Gauteng
Coca-Cola Beverages South Africa and other beverage majors operate filling lines across the Johannesburg-Pretoria corridor, driving converter investment in reheat stretch blow molding capacity. The National Environmental Management Waste Act mandates minimum recycled content thresholds, forcing local suppliers to certify rPET sourcing through SABS protocols. Alpla Group anchors technical bottle supply from its Johannesburg operations, capturing share as brand-owner procurement panels consolidate around circularity credentials.
Western Cape
Cape Town industrial zones host converter clusters positioned close to wine, juice, and dairy bottling facilities requiring shelf-stable packaging formats. Extended producer responsibility regulations under South Africa's waste act redirect capex toward rPET washing and pelletizing joint ventures rather than greenfield blow-molding plants. Berry Global Inc. targets this region with multilayer and hot-fill technologies for premium beverage applications previously reserved for glass.
KwaZulu-Natal
Durban-Pietermaritzburg manufacturing corridors concentrate personal care and household chemical bottlers seeking 5L bulk formats as retail shifts toward value sizing. The Bureau of Standards South Africa testing protocols create import substitution opportunities for local converters with validated material safety credentials. Converter investment here focuses on extrusion blow molding lines for HDPE containers serving aggressive chemical compatibility requirements.
Eastern Cape
Port Elizabeth-Gqeberha industrial zones support automotive-linked packaging demand alongside emerging beverage bottling operations. Domestic PET flake supply constraints force converters in this region to import recycled material at premium landed costs or pursue long-term offtake agreements with certified suppliers. Mid-tier converters face balance sheet strain from capital-intensive equipment retrofits needed to process high rPET percentages without quality degradation.
South Africa Plastic Bottles Market Competitive Landscape
Capital-heavy producers with integrated recycling assets compete with specialized blow-molding converters lacking upstream resin control. The vendor base separates into three tiers: multinational packaging conglomerates with global technology licenses, mid-cap domestic groups with captive recycling operations, and regional specialists focused on single formats or end-use segments. Dominant competitive moves include backward integration into flake supply and strategic partnerships with brand owners to secure long-term volume commitments under EPR compliance timelines.
Among multinational packaging groups, Berry Global Inc. and Alpla Group occupy positions as technology anchors for barrier-enhanced and carbonated beverage applications respectively. Mpact Group exemplifies the integrated domestic archetype, leveraging in-house recycling and blow-molding assets to control cost positions in standard PET and HDPE segments. These three company structures represent the competitive spectrum: global technology licensing versus regional supply chain control.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Alpla Group |
| Mpact Group |
| Bericap Holding GmbH |
| Nioro Plastics Pty Ltd. |
| Nampak Bevcan |
| Polyoak Packaging Group |
| Alpla Packaging SA |
| RN Plastics Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Paraxylene price volatility cascades through South Africa's PET bottle supply chain, compressing margins for converters lacking long-term resin contracts while amplifying pricing power for integrated recyclers with captive rPET supply. The National Environmental Management Waste Act's EPR mandates further stratify the market, locking brand-owner procurement panels around certified circularity credentials that command resin premiums over commodity-grade alternatives.
Pricing Analysis
Throughput-based contract pricing anchors South African converter revenue, with Coca-Cola Beverages South Africa and other majors negotiating multi-year offtake agreements tied to filling line uptime guarantees. Price differentiation separates SABS-validated rPET suppliers from uncertified competitors, while volume scale and lightweighting performance determine tier placement. Pricing pressure stems from virgin PET resin cost spikes that blow-molders cannot fully pass through to retail customers. Mid-tier converters without backward integration into recycling face the steepest margin compression.
Supply Chain Analysis
Virgin PET resin supply rests on naphtha and paraxylene feedstock imports from Saudi Arabia, South Korea, and Singapore, exposing South African converters to currency and oil price volatility. Domestic rPET flake production draws from post-consumer collection networks concentrated in Gauteng and Western Cape urban corridors. Single-source vulnerability sits with European specialty additive suppliers for barrier-enhanced multilayer structures. Distribution runs through converter clusters in Johannesburg-Pretoria and Cape Town industrial zones positioned adjacent to beverage bottling facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's plastic bottles market is consolidating around EPR compliance capabilities, with the National Environmental Management Waste Act forcing non-integrated converters toward acquisition or exit. Brand-owner procurement panels are shrinking, rewarding suppliers with validated circularity credentials and punishing those dependent on virgin resin spot markets.
For Market Incumbents: Anchor market position through backward integration into rPET washing and pelletizing assets, securing flake supply before domestic scarcity intensifies. Mpact Group's integrated model demonstrates how captive recycling controls cost positions when oil spikes compress import-dependent competitors. Prioritize SABS certification timelines to maintain supply relationships with Coca-Cola Beverages South Africa and other majors consolidating vendor panels.
For New Entrants and Emerging Players: Hot-fill PET technology convergence offers a technology-first wedge into shelf-stable dairy and juice applications previously reserved for glass or multilayer structures. Target KwaZulu-Natal's underpenetrated bulk format segment, where 5L household chemical containers are expanding fastest as retail shifts toward value sizing. Lead with SABS validation and rPET sourcing guarantees rather than price competition.
For Investors and Strategic Acquirers: The window for entry favors integrated recyclers with validated food-contact credentials and established brand-owner relationships. Mid-tier converters with legacy extrusion assets but no rPET capability represent distressed acquisition targets. Watch EPR fee escalations and rPET import parity pricing as inflection indicators for consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Recycling | Captive flake supply insulates margins from virgin resin volatility under National Environmental Management Waste Act mandates. |
| SABS Certification Investment | FDA-equivalent food-contact validation locks in supply agreements with Coca-Cola Beverages South Africa procurement panels. |
| Hot-Fill Technology Deployment | Heat-set PET opens shelf-stable dairy and juice segments previously reserved for glass in KwaZulu-Natal. |
| Lightweighting Preform Redesign | Gram-weight reductions cut resin costs while maintaining burst-pressure performance for carbonated applications. |
| 5L Bulk Format Capacity Addition | Value-sizing retail shift in household chemicals and water drives fastest-growing segment in Cape Town industrial zones. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at Gauteng and Western Cape converter facilities, procurement leads at Coca-Cola Beverages South Africa and other beverage majors, distribution channel partners in Johannesburg-Pretoria corridors, and technical R&D directors at integrated recycling operations. Secondary sources included National Environmental Management Waste Act regulatory documents, Bureau of Standards South Africa testing protocols, SABS certification databases, and PET resin import customs declarations. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from beverage bottling line expansions.
Data-stream reconciliation across virgin resin import volumes, rPET flake production capacity, and brand-owner sustainability commitments shaped the analytical framework. Segmentation dimensions modeled encompassed material grade, end-use application, size format, and regional production cluster. CAGRs derived from trend extrapolation of converter capex cycles, EPR compliance timelines, and retail format evolution across the analysis window. Industry-specific forecast inputs incorporated lightweighting technology adoption curves and hot-fill line conversion rates.
Several conditions sit outside the modeled scope, including abrupt oil price shocks beyond historical volatility bands, regulatory delays in EPR enforcement, and breakthrough barrier technologies displacing multilayer PET structures. Forecasts reflect documented assumptions about rPET feedstock availability and brand-owner circularity commitment durability. A small set of named triggers warrants ongoing watch: EPR fee escalation schedules, SABS certification backlog durations, and import parity shifts for virgin versus recycled resin.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market