
 Plastic Aerosol Packaging Market | 2026-2036
Plastic Aerosol Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Aerosol Packaging Market Analytics
Personal care applications are decoupling from traditional aluminum aerosol dominance as brands seek lighter, more customizable packaging formats. Graham Packaging leverages its blow-molding expertise to supply polyethylene aerosol cans with barrier technologies. Berry Global Inc. anchors North American supply through multi-site manufacturing of personal care aerosol containers. Plastipak Holdings Inc. differentiates via in-house resin processing and thin-wall injection molding capabilities for household spray products.
Plastic aerosol packaging comprises pressurized containers fabricated from thermoplastic resins such as polyethylene and polypropylene, incorporating multilayer barrier constructions to prevent propellant permeation and maintain product integrity. These containers serve industrial and consumer markets requiring controlled, metered dispensing of liquids, foams, or powders under pressure. Aerosol cans occupy the largest value share due to their established compatibility with hydrocarbon and compressed gas propellants across personal care and household segments. Polyethylene leads material selection for its chemical resistance and compatibility with existing blow-molding infrastructure, though polypropylene is gaining traction in hot-fill and high-temperature industrial applications. The household products application segment generates stable recurring volume, while food and beverage aerosol formats remain nascent with concentrated development in dairy and cooking spray categories.
EPA regulates volatile organic compound emissions from aerosol consumer products under the National Emission Standards for Hazardous Air Pollutants, directly constraining formulation and propellant choices available to packaging converters. REACH mandates disclosure of substances of very high concern in plastic aerosol components sold into the European Union, compelling resin suppliers and molders to reformulate or certify material streams. FDA maintains oversight of food-contact aerosol packaging through 21 CFR compliance requirements for indirect food additives. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple jurisdictions, as these programs will increasingly assign end-of-life collection and recycling costs to original packaging producers rather than downstream waste handlers.
Market Dynamics
REACH and EU F-Gas Regulation are compressing formulation freedom for propellants and mandating recyclability disclosures, forcing converters to revalidate barrier material stacks and propellant chemistries across their European product lines.
Growth Catalysts
- Lightweighting mandates in personal care:Brands are converting aluminum aerosol lines to polyethylene formats to cut transport costs and enable asymmetric bottle geometries. Germany leads this conversion among European personal care manufacturers.
- REACH SVHC disclosure requirements:The regulation compels resin suppliers to certify material streams, accelerating qualified supply partnerships between converters and compounders with verified compliance documentation.
- Compressed gas propellant compatibility:Advances in multilayer blow-molding enable hydrocarbon-free pressurization, opening segments previously blocked by VOC restrictions under EPA NESHAP standards.
Market Restraints
- Resin price volatility:Polyethylene feedstock costs fluctuate with naphtha and natural gas liquid markets, squeezing converter margins on fixed-price household product contracts.
- Recycling infrastructure gaps:Multi-layer barrier constructions complicate mechanical recycling streams, limiting post-consumer resin offtake in jurisdictions without advanced sorting capabilities.
- Aluminum can substitution resistance:Premium personal care segments retain metal preference for tactile perception and shelf differentiation, capping plastic penetration in high-margin categories.
Strategic Opportunities
- Food-contact aerosol expansion:Dairy and cooking spray applications remain underdeveloped, with FDA 21 CFR compliance frameworks now stabilizing for indirect food additive barriers in polyethylene constructions.
- Extended producer responsibility tailwinds:EU member states are assigning end-of-life collection costs to original producers, rewarding converters with established take-back partnerships and certified recyclable designs.
- Hot-fill polypropylene development:Industrial solvent applications requiring elevated temperature resistance present white space beyond polyethylene's thermal limits, with polypropylene barrier coextrusion advancing rapidly.
Industry Challenges
- Barrier coextrusion technician scarcity:The specialized skill set for multilayer blow-molding process control is concentrated among aging workforces in Germany and the US Midwest, constraining capacity expansion timelines.
- Propellant permeation testing bottlenecks:Validating new barrier constructions against compressed gas and hydrocarbon chemistries requires extended accelerated aging protocols, delaying product qualification cycles.
- Legacy aluminum line retooling costs:Personal care brands face capital intensity in converting filling equipment and supply chain logistics from metal to plastic handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Aerosol Packaging Market |
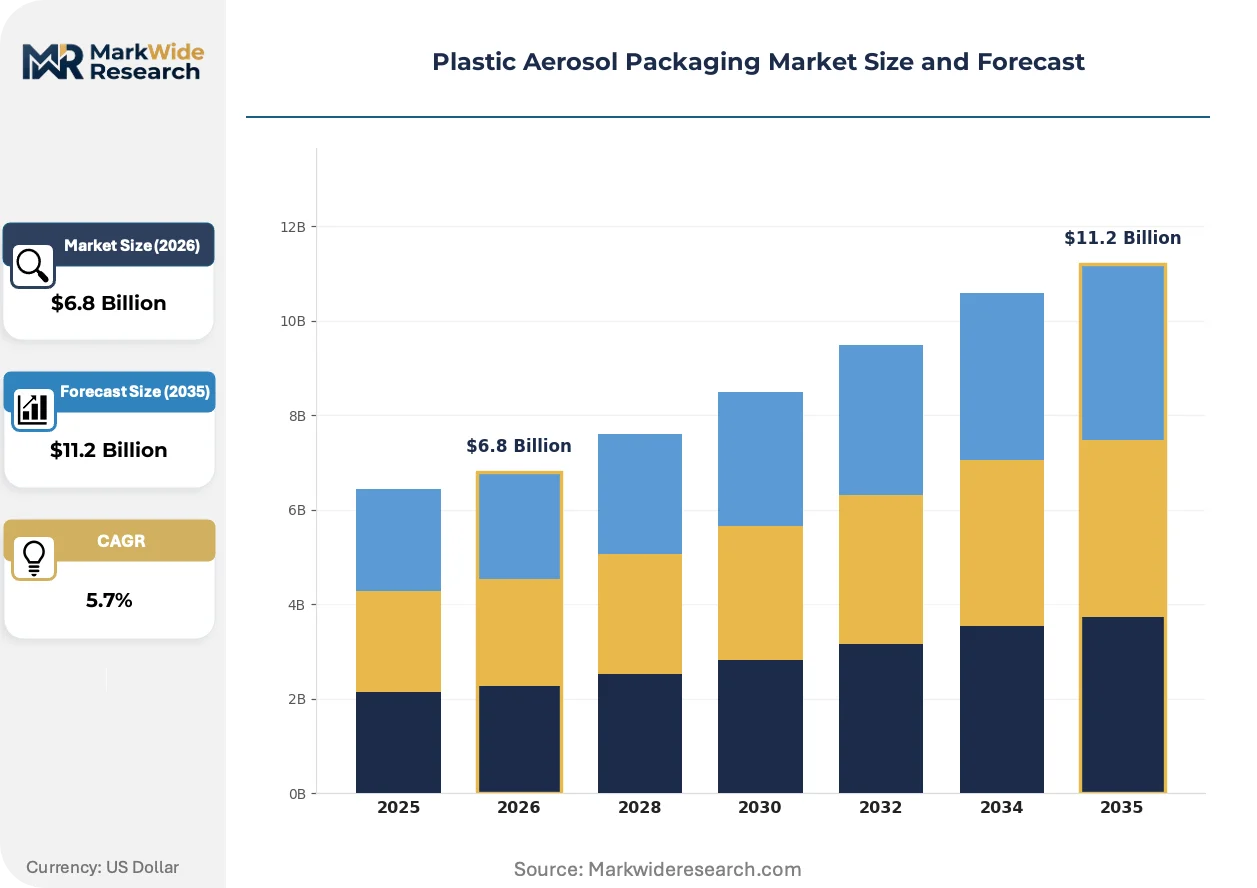
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Cans, Pump Sprays, Foam Aerosol, Trigger Sprays Material: Polyethylene, Polypropylene, PVC, Polystyrene Application: Personal Care, Household Products, Food & Beverage, Industrial Solutions End User: Manufacturers, Retailers, Distributors, Consumer Goods Companies |
| Companies Covered | Graham Packaging, Plastipak Holdings Inc., Berry Global Inc., AptarGroup Inc., Crown Holdings Inc., Montebello Packaging Inc., Ball Corporation, CCL Industries Inc., Precise Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Aerosol Packaging Market Evolving Landscape
Barrier coextrusion technologies are redefining performance thresholds for plastic aerosol containers, while regulatory frameworks on both sides of the Atlantic reshape acceptable material chemistries and end-of-life accountability.
Multilayer polyethylene constructions with ethylene vinyl alcohol or polyamide barrier layers are overtaking monolayer formats in personal care applications. Deodorant and hair spray brands in Germany are specifying these constructions for 18-month shelf life guarantees against propellant loss. The shift is compressing demand for simpler single-layer cans and rewarding converters with in-house coextrusion capabilities.
EU F-Gas Regulation is phasing down hydrofluorocarbon propellants with high global warming potential, forcing reformulation toward hydrocarbon or compressed gas alternatives. This regulatory pressure cascades into material specifications, as new propellant chemistries interact differently with polyethylene stress-cracking resistance. Household insecticide and industrial solvent segments are most affected, with converters running parallel qualification programs for compliant barrier stacks.
Brand procurement teams are consolidating supplier panels around converters with integrated resin processing and certified recycling partnerships. Personal care multinationals are awarding multi-year contracts contingent on demonstrated post-consumer resin incorporation and take-back program participation. This consolidation is most visible in North American supply chains, where Berry Global and Graham Packaging have anchored volume through captive recycling infrastructure and multi-site manufacturing networks.
Plastic Aerosol Packaging Market Segmentation
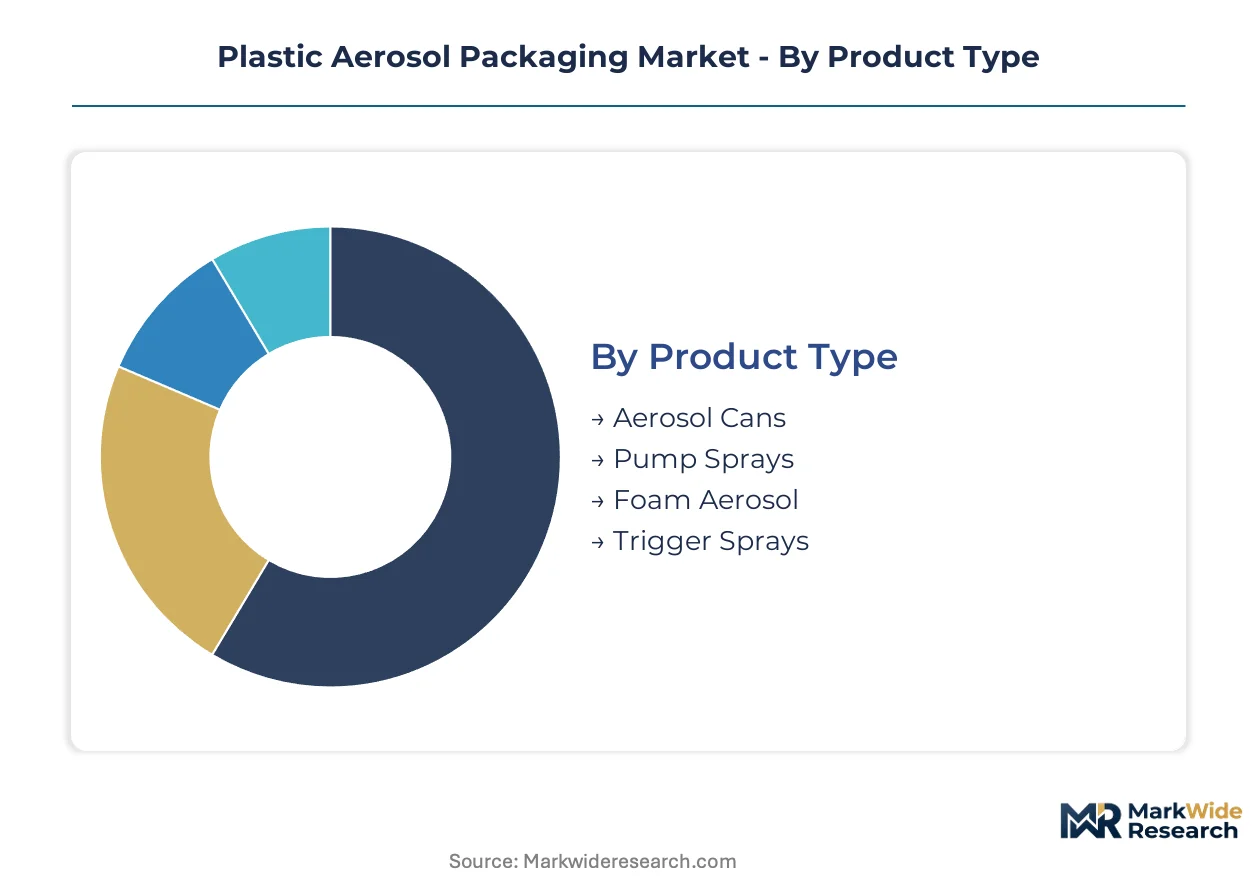
Plastic aerosol packaging segments diverge sharply between standardized commodity formats and engineered barrier constructions. Material selection and barrier complexity determine which converters capture volume versus margin across personal care, household, and emerging food-contact applications.
Product Type:
Standardized pump mechanisms dominate high-volume household segments, while proprietary barrier technologies command premium positioning in personal care and industrial solvent applications.
- Aerosol Cans:Pressurized cylindrical containers fabricated through multilayer blow-molding with ethylene vinyl alcohol or polyamide barrier layers to prevent hydrocarbon permeation. Demand concentrates in Germany where personal care brands convert aluminum lines to polyethylene formats for weight reduction and asymmetric design flexibility.
- Pump Sprays:Non-pressurized finger-actuated dispensers relying on mechanical displacement rather than propellant pressure. Household insecticide and surface cleaner manufacturers in North America specify these for EPA NESHAP compliance without volatile organic compound emissions.
- Foam Aerosol:Specialized valves and actuator designs delivering product as expanded foam rather than fine mist. Personal care applications include shaving foams and hair styling mousses.
- Trigger Sprays:Hand-held pistol-grip dispensers with adjustable nozzles for stream or spray patterns. Industrial solvent and automotive cleaning product lines favor these for controlled dosing and reduced propellant dependency.
Leading the category by volume: Aerosol Cans. Expanding most quickly: Foam Aerosol formats in personal care specialty applications.
Material:
Resin selection maps directly to thermal performance requirements and barrier sophistication, with commodity grades serving household volume and engineered copolymers capturing industrial and food-contact premiums.
- Polyethylene:Dominant resin selection leveraging existing blow-molding infrastructure and proven chemical resistance to hydrocarbon propellants. Personal care deodorant and hair spray brands specify high-density polyethylene with multilayer EVOH barriers for 18-month shelf life guarantees.
- Polypropylene:Superior thermal resistance enabling hot-fill applications and elevated-temperature industrial solvent packaging. Hot-fill polypropylene barrier coextrusion is advancing rapidly for segments beyond polyethylene's thermal limits.
- PVC:Cost-positioned resin with established compatibility for certain household cleaner chemistries. Regulatory pressure from REACH SVHC disclosure requirements is compressing deployment in European markets.
- Polystyrene:Rigid amorphous polymer limited to non-pressurized decorative and display applications. Fragility under stress-cracking conditions excludes this material from pressurized aerosol constructions.
Polyethylene commands the volume lead. Polypropylene posts the steepest expansion trajectory as hot-fill industrial applications multiply.
Application:
Application segmentation tracks regulatory intensity, with personal care facing REACH and EPA constraints while food-contact segments navigate FDA 21 CFR compliance frameworks.
- Personal Care:Deodorants, hair sprays, and body mists driving conversion from aluminum to plastic formats. German manufacturers lead this shift for transport cost reduction and design geometry freedom.
- Household Products:Insecticides, air fresheners, and surface cleaners generating stable recurring volume. EU F-Gas Regulation is forcing reformulation toward hydrocarbon or compressed gas propellants with cascading effects on material specifications.
- Food & Beverage:Cooking sprays and dairy-based whipped toppings in early commercialization. FDA 21 CFR compliance frameworks are stabilizing for indirect food additive barriers in polyethylene constructions.
- Industrial Solutions:Solvents, lubricants, and coatings requiring elevated temperature resistance and chemical compatibility. Compressed gas propellant compatibility is opening segments previously blocked by VOC restrictions.
Household Products anchors volume. Food & Beverage gains share fastest as barrier technologies mature for dairy and cooking spray categories.
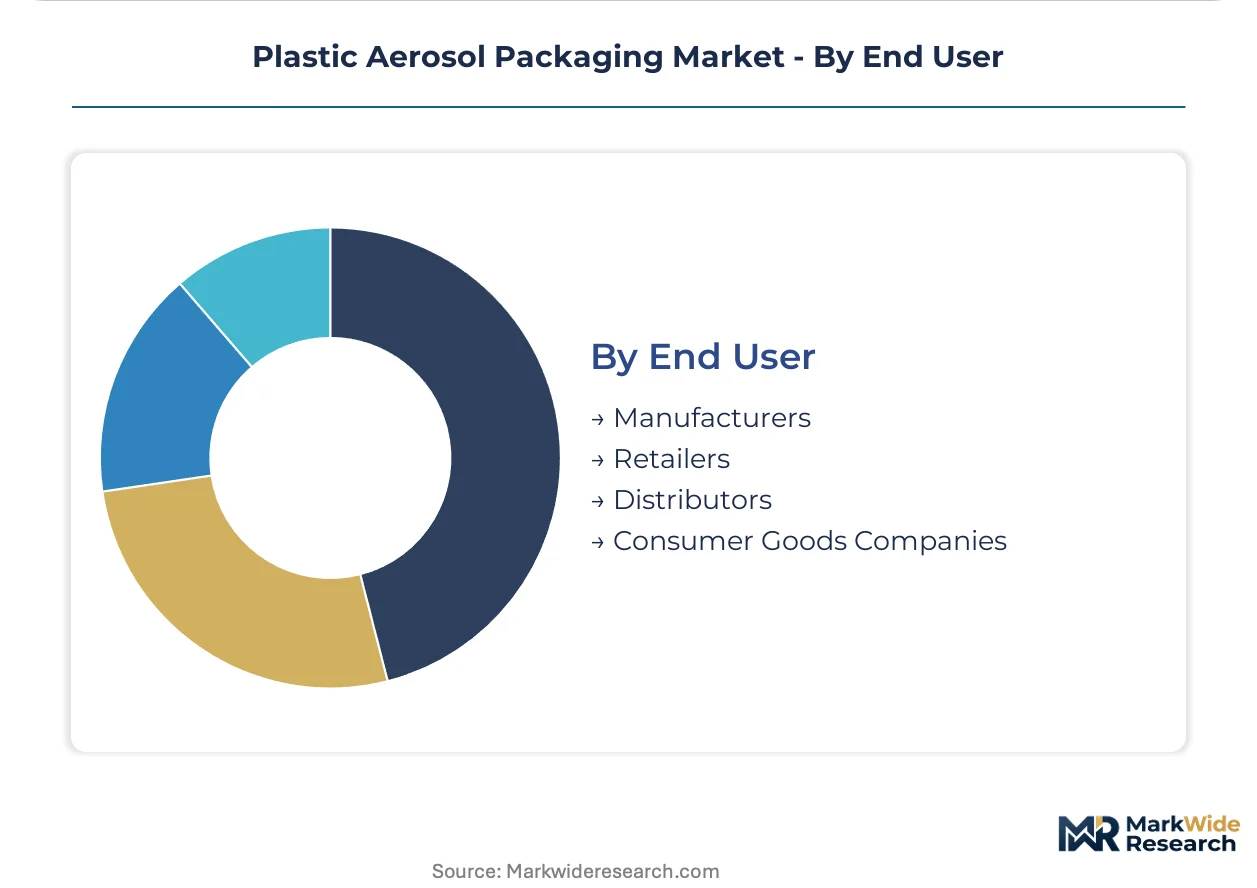
End User:
End user segmentation reveals procurement consolidation patterns, with consumer goods multinationals driving supplier panel rationalization around integrated resin processing and certified recycling partnerships.
- Manufacturers:Brand owners and contract fillers operating pressurized packaging lines. Extended producer responsibility frameworks in EU member states are assigning end-of-life collection costs to these original producers.
- Retailers:Private label program operators and store-brand developers. Shelf differentiation requirements sustain aluminum preference in premium personal care segments.
- Distributors:Industrial and institutional supply channel intermediaries. Inventory risk from resin price volatility squeezes margins on fixed-price household product contracts.
- Consumer Goods Companies:Multinational brand portfolios with consolidated procurement functions. Multi-year contract awards now contingent on demonstrated post-consumer resin incorporation and take-back program participation.
Manufacturers represent the largest addressable base. Consumer Goods Companies are consolidating supplier relationships fastest around certified recyclable designs and captive recycling infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Hamburg and Rotterdam concentrate European aerosol packaging logistics, while tax-advantaged manufacturing corridors in Mexico and Southeast Asia draw capacity investment from multinational converters seeking duty-efficient supply chains.
Germany
Personal care brands in Hamburg and Cologne are converting aluminum aerosol lines to polyethylene formats for transport cost reduction and asymmetric design flexibility. REACH SVHC disclosure requirements compel resin suppliers to certify material streams, accelerating qualified supply partnerships. The North Rhine-Westphalia chemical corridor hosts barrier coextrusion specialists serving deodorant and hair spray manufacturers with 18-month shelf life guarantees.
United States
EPA NESHAP standards constrain volatile organic compound emissions from aerosol consumer products, directly shaping formulation and propellant choices available to packaging converters. Household insecticide and surface cleaner manufacturers specify pump spray formats for compliance without hydrocarbon propellants. The Midwest blow-molding belt—centered on Ohio and Illinois—hosts multilayer coextrusion capacity for personal care and industrial solvent applications.
China
GB standards and MIIT industrial policy guide material specifications for pressurized plastic containers in domestic and export markets. The Yangtze River Delta manufacturing cluster—spanning Shanghai, Jiangsu, and Zhejiang—concentrates blow-molding capacity serving global personal care contract fillers. Local converters are advancing thin-wall injection molding capabilities for household spray products targeting Southeast Asian export markets.
Mexico
IMMEX maquiladora program incentives attract North American brand owners seeking tariff-advantaged production for US consumer goods markets. The Bajío Region—Querétaro and Guanajuato—hosts automotive and industrial aerosol packaging operations leveraging compressed gas propellant compatibility for solvent applications. Proximity to Texas petrochemical feedstock supplies supports polyethylene resin integration for regional household product manufacturers.
India
BIS certification requirements and FSSAI food-contact standards shape barrier material specifications for domestic and export aerosol packaging. Maharashtra's industrial corridor—Mumbai-Pune—concentrates personal care manufacturing driving deodorant and body mist format conversion from metal to plastic. The Gujarat chemical belt supplies engineered resins for multilayer constructions meeting global brand owner compliance documentation requirements.
Plastic Aerosol Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with personal care procurement teams consolidating supplier panels around integrated resin processing and certified recycling partnerships. The vendor base organizes into three tiers: multinational converters with captive recycling infrastructure, regional blow-molding specialists with coextrusion capabilities, and commodity injection molders serving standardized household formats. Dominant competitive moves include geographic expansion through multi-site manufacturing networks and backward integration into resin compounding to secure qualified material streams.
Within the multinational converter tier, Graham Packaging and Berry Global Inc. exemplify integrated supply chain positioning through multi-site manufacturing networks and captive recycling infrastructure. Plastipak Holdings Inc. occupies a position among specialists with in-house resin processing capabilities. These three anchors represent distinct archetypes: blow-molding expertise with barrier technologies, North American volume leadership through distributed production, and thin-wall injection molding differentiation for household applications.
| Leading Market Players |
|---|
| Graham Packaging |
| Plastipak Holdings Inc. |
| Berry Global Inc. |
| AptarGroup Inc. |
| Crown Holdings Inc. |
| Montebello Packaging Inc. |
| Ball Corporation |
| CCL Industries Inc. |
| Precise Packaging |
| Others |
Value Network & Pricing Analysis
Naphtha price index movements cascade directly through polyethylene feedstock costs into converter margin compression, forcing tiered pricing responses that separate REACH-certified barrier constructions from commodity monolayer formats. Buyers with multi-year offtake agreements secure resin price hedges, while spot purchasers absorb volatility surges that widen spreads between qualified and unqualified supply tiers.
Pricing Analysis
Short lead-time premiums command substantial markups in the personal care segment, where German deodorant manufacturers pay elevated rates for 18-month shelf life guarantees against propellant loss. Pricing stratifies across premium certified barrier tiers, standard multilayer constructions, and economy monolayer alternatives, with REACH SVHC documentation and EVOH barrier sophistication as primary differentiation drivers. Cost compression in household product contracts is intensifying because fixed-price agreements expose converters to naphtha volatility without pass-through mechanisms. Distributors serving industrial solvent applications exhibit highest price sensitivity due to inventory risk, while consumer goods multinationals with captive recycling partnerships demonstrate lowest sensitivity through volume-scale leverage.
Supply Chain Analysis
REACH and FDA 21 CFR compliance certifications gate supplier qualification, extending onboarding cycles and concentrating qualified supply among converters with demonstrated barrier coextrusion capabilities. Manufacturing gravity centers on Germany, the United States, and China, with the North Rhine-Westphalia chemical corridor, Ohio-Illinois blow-molding belt, and Yangtze River Delta cluster anchoring regional supply. Raw material flows draw from Texas petrochemical feedstock, Saudi naphtha exports, and regional polyethylene resin compounding operations. Single-source vulnerability concentrates in ethylene vinyl alcohol barrier layer supply, where Asian specialty chemical producers dominate global capacity. Distribution runs through Hamburg and Rotterdam free trade zones for European personal care brands, with cross-border maquiladora flows serving North American household product markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH SVHC disclosure requirements and EU F-Gas Regulation phase-down mandates erect barrier-to-entry moats favoring incumbents with certified material streams and validated barrier constructions.
For Market Incumbents: Lock in qualified resin supply partnerships through backward integration into compounding operations or captive offtake agreements with certified suppliers, insulating margin structures from naphtha volatility while denying feedstock access to emerging competitors. Extend coextrusion technician training pipelines through apprenticeship partnerships with German technical institutes, addressing workforce scarcity that constrains capacity expansion timelines and preserves pricing power in barrier construction segments. For New Entrants and Emerging Players: Contract fillers represent the most penetrable channel partner type, as personal care brands retool aluminum lines and seek qualified plastic alternatives without incumbent converter relationships. Target food-contact aerosol applications for dairy and cooking spray categories, where FDA 21 CFR compliance frameworks are stabilizing and barrier technology requirements remain less sophisticated than personal care shelf life guarantees. Pursue geographic entry through Mexico's IMMEX maquiladora program, leveraging tariff-advantaged production proximity to Texas petrochemical supplies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with stranded barrier coextrusion capacity in Germany and the US Midwest, where aging workforces and capital intensity pressures create acquisition opportunities at compressed multiples. Long-term viability hinges on demonstrated post-consumer resin incorporation capabilities and established take-back partnerships under extended producer responsibility frameworks. Monitor EU member state implementation timelines for end-of-life cost assignment as the critical inflection signal, with early-mover jurisdictions accelerating supplier consolidation around certified recyclable designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive EVOH barrier layer supply secures REACH certification continuity against Asian specialty chemical concentration. |
| Multi-Site Manufacturing Network Expansion | Ohio-Illinois and Querétaro-Guanajuato proximity reduces logistics exposure to Rotterdam-Hamburg chokepoints. |
| Post-Consumer Recycling Partnership Development | Take-back program participation satisfies EU extended producer responsibility preconditions for multi-year contract awards. |
| Hot-Fill Polypropylene Barrier Coextrusion Investment | Thermal performance beyond polyethylene limits opens industrial solvent segments with compressed gas propellant compatibility. |
| Food-Contact Compliance Certification Acceleration | FDA 21 CFR validation for dairy and cooking spray barriers captures fastest-expanding application segment. |
Research Methodology
Trade association filings, customs and import-export databases, and SEC 10-K disclosures from packaging converters formed the secondary backbone, cross-referenced against primary interviews with blow-molding plant managers, personal care brand procurement directors, resin supplier technical R&D leads, and regulatory affairs specialists at REACH compliance consultancies. Bottom-up volume modeling triangulated against top-down market sizing from industry association statistics and petrochemical feedstock consumption patterns.
Historical trendline analysis established baseline growth trajectories across material, product type, and application dimensions, with segmentation modeling incorporating polyethylene versus polypropylene thermal performance tiers, multilayer barrier complexity levels, and regional regulatory framework clusters. CAGRs derived from fitted trend extrapolation adjusted for propellant chemistry transitions under EPA NESHAP and EU F-Gas constraints, with converter capacity utilization and resin price volatility as primary forecast sensitivity inputs.
Caveats apply where REACH SVHC list expansions, EPA NESHAP formulation revisions, or breakthrough monolayer barrier technologies could materially shift the outlook for multilayer construction demand. A model refresh is warranted upon material change in extended producer responsibility implementation timelines across EU member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
PET Clamshell Market