
 North America Blow Molded Plastics Market | 2026-2036
North America Blow Molded Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Blow Molded Plastics Market Intelligence
Market Context with Strategic Players
The US Midwest is tilting toward expanded blow molding capacity to serve reshoring packaging and automotive programs. Berry Global, Inc. sustains broad geographic coverage through multi-site manufacturing across the United States and Canada. Comar, LLC specializes in healthcare and consumer packaging applications with FDA-compliant cleanroom operations. Dow, Inc. anchors upstream material supply with polyethylene resin production integrated into converter networks.
Technical Definition and Structural Segments
Blow molded plastics are thermoplastic hollow forms created by inflating a heated parison inside a mold cavity, typically achieving wall thicknesses of 0.5 to 5 millimeters depending on application stress requirements. These components serve as lightweight, chemically resistant enclosures for liquids, gases, and structural parts across industrial and consumer supply chains. Bottles and containers within the packaging application dominate volume throughput due to food and beverage industry procurement scale, while automotive tanks and industrial components command higher per-unit margins through engineering-grade polypropylene and polyethylene specifications. Medical end users represent a concentrated premium segment where ISO 13485 compliance and lot traceability requirements limit supplier pools.
Regulatory Frame and Forward-Looking Close
The EPA administers recycled content standards under the IRA that directly affect polyethylene and PET sourcing obligations for packaging producers. FDA food-contact regulations and OSHA workplace exposure limits govern plant operations and product clearance pathways across US-based facilities. Health Canada and PMRA maintain parallel chemical safety frameworks that shape cross-border product qualifications for Ontario and Quebec converters. Stakeholders must monitor state-level extended producer responsibility legislation advancing in California, Oregon, and Maine for compliance cost redistribution.
Market Dynamics
Automotive lightweighting mandates and EPA recycled content requirements under the IRA are compressing material specifications while forcing converter investments in post-consumer resin processing capabilities.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's recycled content incentives are pulling post-consumer polyethylene into automotive fuel tanks and HVAC ducting applications.
- Great Lakes Manufacturing Corridor:Michigan, Ohio, and Ontario are concentrating blow molding capacity to serve reshoring packaging and Tier 1 automotive programs.
- Extrusion Blow Molding Advancements:Co-extrusion barrier technologies are expanding shelf-life performance for dairy and edible oil containers.
Market Restraints
- Resin Price Volatility:Ethane feedstock fluctuations tied to Gulf Coast petrochemical capacity constrain margin predictability for converters.
- Post-Consumer Feedstock Scarcity:Collection infrastructure gaps in the US Midwest limit rHDPE availability for food-contact applications.
- Dimensional Tolerance Limits:Blow molding's ±2% wall thickness variation restricts adoption in precision medical device housings.
Strategic Opportunities
- Quebec EPR Expansion:Extended producer responsibility frameworks advancing in Canada are creating structured demand for recycled content packaging.
- 3D Printing Convergence:Hybrid manufacturing combining blow molding with fused deposition modeling is enabling low-volume custom automotive ducts.
- Closed-Loop Pooling Systems:Reusable intermediate bulk containers are displacing single-use drums in chemical distribution.
Industry Challenges
- Multi-Material Separation:Barrier-layer adhesives complicate mechanical recycling streams and contaminate rPET batches.
- ISO 13485 Certification Timelines:Medical device qualification cycles stretch 18-24 months, freezing out mid-cap converters from premium segments.
- Legacy Equipment Retrofit Costs:All-electric machine conversions require $2-4 million per line, straining family-owned Midwest shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Blow Molded Plastics Market |
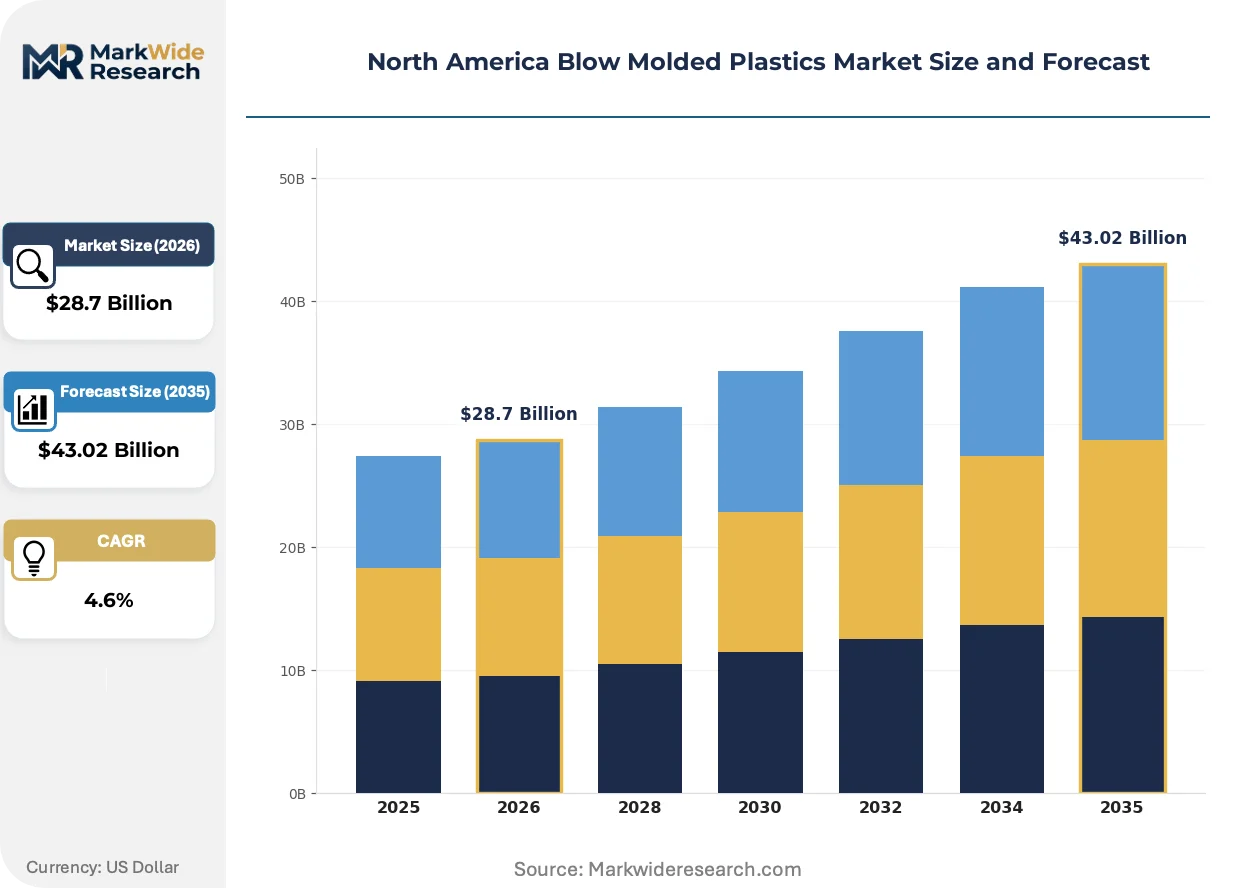
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Tanks, Jugs End User: Food & Beverage, Consumer Goods, Automotive, Medical Material: Polyethylene, Polypropylene, PVC, PET Application: Packaging, Automotive Parts, Industrial Components, Household Articles |
| Companies Covered | Comar, LLC, Pet All Manufacturing, Inc., Berry Global, Inc., Agri-Industrial Plastics, Garrtech Inc., Magna International, Inc., The Plastic Forming Company, Inc., Apex Plastics, Dow, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Blow Molded Plastics Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory pressure on circularity are compressing traditional processing windows while opening new performance tiers for structural applications.
All-electric blow molding machinery with servo-driven parison programming is rendering obsolete hydraulic systems in thin-wall packaging operations. Food and beverage converters in Wisconsin and Illinois are adopting these platforms for 15% cycle time gains. The technology is rendering obsolete legacy toggle-clamp architectures below 500-ton clamp force.
The EPA's recycled content mandates under the IRA are forcing polyethylene sourcing audits across packaging supply chains. Converters must document 30% post-consumer content thresholds for federal procurement eligibility. Automotive fuel tank producers face the steepest compliance curves due to virgin resin legacy specifications.
Brand-led packaging reduction targets are compressing bottle weights below 20 grams for 500ml formats. Retailers including Walmart and Target are enforcing these thresholds through supplier scorecards. California and Oregon markets exhibit the fastest adoption curves due to state-level plastic reduction statutes.
North America Blow Molded Plastics Market Segmentation
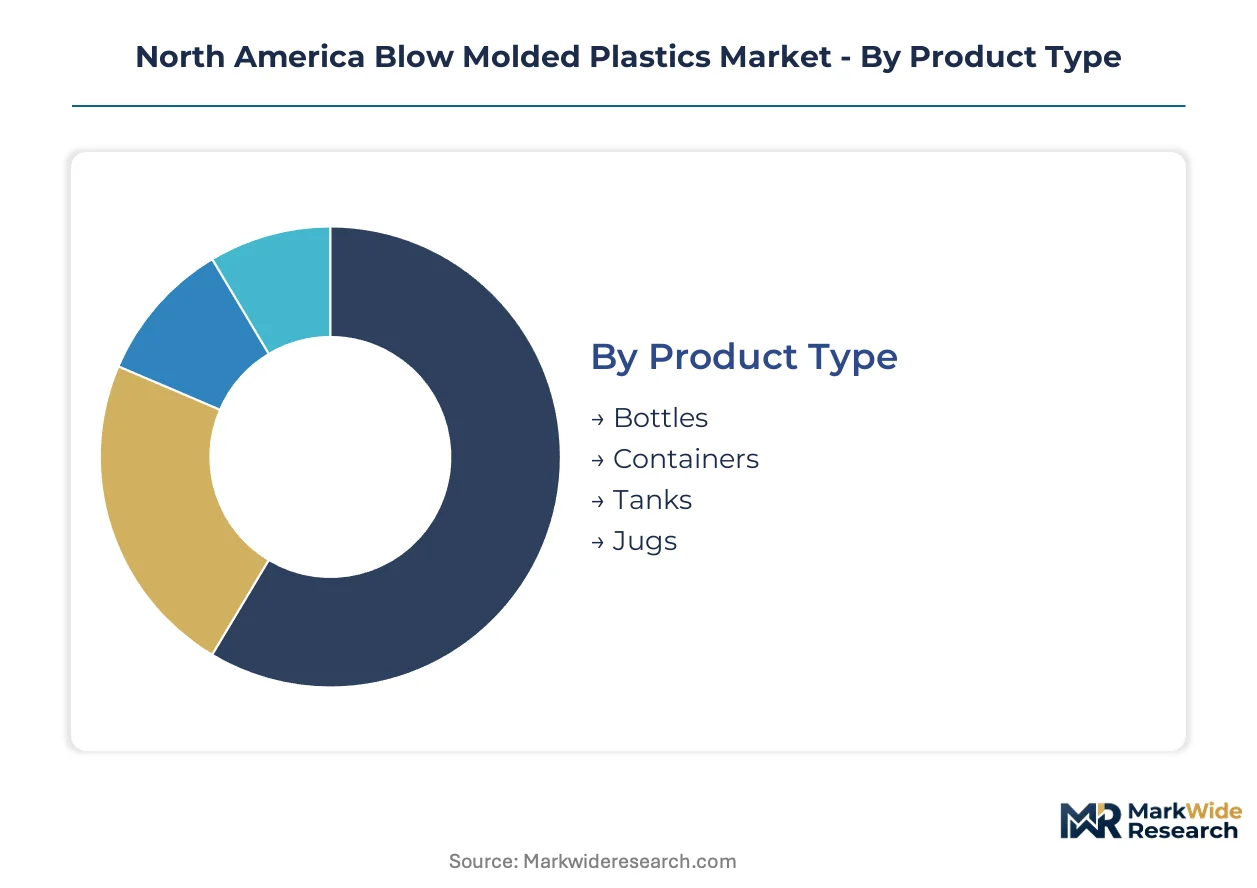
Segmentation in blow molded plastics reveals how processing economics and regulatory compliance requirements fragment converter capabilities across distinct performance tiers. Material specifications and end-use qualification barriers create natural market boundaries that resist easy crossover.
Product Type:
Volume throughput and margin structure vary dramatically across hollow form geometries, with cycle time economics and tooling complexity driving converter specialization.
- Bottles:Thin-wall polyethylene and PET formats dominate dairy, water, and edible oil packaging with sub-20 gram weight targets now standard for 500ml formats. Walmart and Target supplier scorecards enforce these thresholds, compressing converter margins while demanding capital upgrades to all-electric servo systems.
- Containers:Intermediate bulk formats and industrial pails command premium pricing through UN certification requirements for chemical transport. The Great Lakes corridor concentrates capacity here to serve Ohio and Michigan manufacturing reshoring programs.
- Tanks:Automotive fuel systems and agricultural cisterns utilize co-extrusion barrier technologies to meet evaporative emission standards. EPA recycled content mandates under the IRA are forcing post-consumer polyethylene integration into these legacy virgin specifications.
- Jugs:Household bleach and cleaning product formats face intense private-label competition with limited differentiation beyond handle ergonomics and label adhesion properties.
Bottles holds installed capacity. Containers is rotating up the share rankings.
End User:
Customer qualification requirements and compliance burdens stratify the converter base into distinct service tiers with minimal overlap.
- Food & Beverage:FDA food-contact regulations and lot traceability mandates govern polyethylene and PET sourcing for dairy, juice, and edible oil packaging. Wisconsin and Illinois converters are consolidating to capture scale efficiencies in this procurement-intensive segment.
- Automotive:SAE specifications and OEM PPAP validation cycles stretch 12-18 months for fuel tank and HVAC ducting programs. Michigan Tier 1 suppliers are reshoring blow molding capacity to reduce logistics exposure on just-in-sequence delivery.
- Consumer Goods:Personal care and household chemical formats compete on shelf presence and e-commerce durability with lower regulatory barriers than food-contact applications.
- Medical:ISO 13485 certification and cleanroom operations limit supplier pools to specialists like Comar with FDA-registered facilities. Eighteen-to-twenty-four month qualification timelines freeze out mid-cap converters from this premium segment.
Food & Beverage holds installed capacity. Automotive is rotating up the share rankings.
Material:
Resin selection dictates processing window, recyclability pathway, and regulatory compliance burden across converter operations.
- Polyethylene:HDPE and LDPE grades dominate packaging volume through superior chemical resistance and established mechanical recycling infrastructure. The IRA's 30% post-consumer content thresholds for federal procurement are pulling rHDPE into automotive fuel tank applications previously reserved for virgin resin.
- Polypropylene:Engineering-grade specifications command automotive and industrial margins with higher heat deflection temperatures than polyethylene. Michigan and Ontario converters are expanding PP capacity for lightweighting programs.
- PVC:Construction and agricultural applications persist despite environmental scrutiny, with limited recycling infrastructure constraining growth in sustainable packaging mandates.
- PET:Beverage bottle clarity and barrier performance sustain demand despite collection infrastructure gaps in the US Midwest that limit food-grade rPET availability.
Polyethylene holds installed capacity. Polypropylene is rotating up the share rankings.
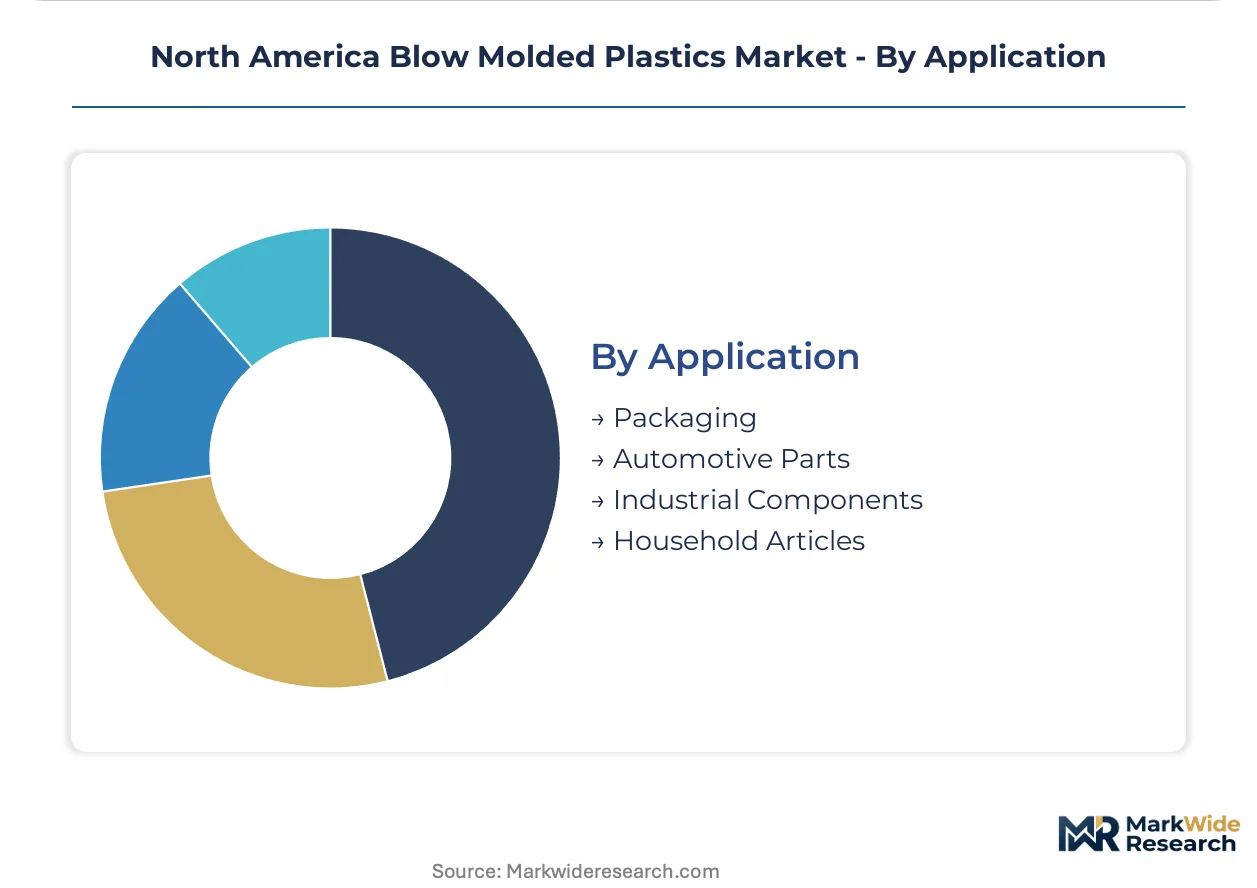
Application:
Functional performance requirements and certification standards segment converter capabilities into non-overlapping operational footprints.
- Packaging:Food, beverage, and consumer goods formats absorb the majority of extrusion blow molding throughput with thin-wall technology driving 15% cycle time gains. California and Oregon plastic reduction statutes are compressing bottle weights fastest in this segment.
- Automotive Parts:Structural ducting and reservoir systems utilize sequential co-extrusion to meet NVH and fluid compatibility specifications. The Great Lakes manufacturing corridor is concentrating capacity to serve reshoring programs.
- Industrial Components:Chemical drums and intermediate bulk containers face reusable format displacement from closed-loop pooling systems in distribution networks.
- Household Articles:Toys, furniture, and garden products compete with injection molding alternatives on tooling cost and design flexibility with lower entry barriers.
Packaging holds installed capacity. Automotive Parts is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor concentrates North American blow molding capacity, with resin supply chains and automotive demand anchoring facility location decisions across the Midwest and Ontario.
United States
Michigan and Ohio host the densest concentration of automotive blow molding operations serving Tier 1 fuel tank and HVAC ducting programs. The EPA's recycled content mandates under the IRA are forcing converters in these states to retool for post-consumer polyethylene integration. Wisconsin and Illinois food packaging clusters are consolidating to capture scale efficiencies in dairy and edible oil container production.
Canada
Ontario converters leverage proximity to Detroit's automotive assembly plants for just-in-sequence delivery of structural blow molded components. Health Canada and PMRA chemical safety frameworks govern cross-border product qualifications for packaging serving US markets. Quebec's advancing extended producer responsibility regulations are creating structured demand pull for recycled content packaging investments.
Mexico
Nuevo León and the Bajío Region are attracting blow molding capacity to serve nearshored automotive and appliance manufacturing. Mexican converters supply hollow components for US-bound vehicle assembly with lower logistics exposure than Asian alternatives. The country's automotive OEM presence is accelerating demand for engineering-grade polypropylene structural tanks and reservoirs.
North America Blow Molded Plastics Market Key Industry Players
Multi-site packaging conglomerates and specialized automotive suppliers split the market into distinct service tiers with limited capability overlap. The structure tilts toward consolidation in food-contact packaging and fragmentation in industrial and medical segments. Three archetypes dominate: resin-integrated majors with captive polyethylene supply, regional converters serving single end-use verticals, and FDA-registered medical specialists with cleanroom infrastructure. Capacity expansion in the Great Lakes corridor and strategic partnerships for post-consumer resin sourcing represent the dominant competitive moves.
Among resin-integrated majors, Dow, Inc. anchors upstream material supply with polyethylene production feeding converter networks across the region. Berry Global, Inc. exemplifies the multi-site packaging archetype with broad geographic coverage spanning US and Canadian facilities. Comar, LLC occupies the medical specialist tier, representing FDA-compliant cleanroom operations that limit supplier pools through ISO 13485 certification requirements.
| Leading Market Players |
|---|
| Comar, LLC |
| Pet All Manufacturing, Inc. |
| Berry Global, Inc. |
| Agri-Industrial Plastics |
| Garrtech Inc. |
| Magna International, Inc. |
| The Plastic Forming Company, Inc. |
| Apex Plastics |
| Dow, Inc. |
| Others |
Cost & Logistics Intelligence
The I-75 freight corridor connecting Detroit to Cincinnati transmits resin cost volatility directly into converter pricing power, with automotive fuel tank producers absorbing upstream polyethylene fluctuations while food packaging buyers exploit thin-margin competition among Wisconsin and Illinois suppliers.
Pricing Analysis
The EPA's recycled content mandates under the IRA dictate the pricing tier structure across federal procurement eligibility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical specialists from FDA food-contact converters and commodity industrial pail producers. Cost compression in thin-wall packaging is intensifying because Walmart and Target supplier scorecards enforce sub-20 gram bottle weight thresholds. Food and beverage converters exhibit highest price sensitivity due to private-label competition, while automotive Tier 1 suppliers accept premium pricing for SAE-specified co-extrusion barrier technologies.
Supply Chain Analysis
Ethane feedstock from Gulf Coast petrochemical complexes anchors North American polyethylene supply, with Dow's integrated production tethered to converter networks across Michigan, Ohio, and Ontario. Automotive blow molded components draw from engineering-grade polypropylene specifications, while medical packaging rests on FDA-registered cleanroom resin batches. Single-source vulnerability concentrates in rHDPE collection infrastructure gaps across the US Midwest. Distribution runs through just-in-sequence delivery protocols serving Detroit automotive assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America blow molded plastics market approaches a platform-economics inflection as closed-loop pooling systems for intermediate bulk containers create interoperability standards that reshape chemical distribution networks.
For Market Incumbents: Pre-empt post-consumer resin scarcity by securing long-term rHDPE offtake agreements with Great Lakes materials recovery facilities before automotive fuel tank mandates tighten. Consolidate Wisconsin and Illinois food packaging capacity to capture scale efficiencies against private-label margin erosion. Defensive backward integration into captive polyethylene recycling protects against IRA compliance cost spikes. For New Entrants and Emerging Players: Quebec's advancing extended producer responsibility frameworks represent the most penetrable entry point for recycled-content packaging specialists. Mid-cap converters frozen out of ISO 13485 medical certification cycles can capture automotive HVAC ducting reshoring programs in the Great Lakes corridor. A go-to-market angle anchored to 3D printing convergence for low-volume custom automotive ducts bypasses legacy equipment capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Midwest shops facing all-electric machine conversion costs. Long-term viability favors converters with demonstrated post-consumer resin processing capabilities and federal procurement eligibility. Watch EPA recycled content threshold adjustments as the primary inflection signal for valuation repricing across packaging tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Processing Scale-Up | IRA compliance eligibility secures federal automotive and packaging procurement contracts. |
| All-Electric Machinery Conversion | Servo-driven parison programming delivers 15% cycle time gains for thin-wall food containers. |
| ISO 13485 Certification Investment | Cleanroom operations unlock premium medical device packaging margins above commodity tiers. |
| Closed-Loop Pooling System Partnership | Reusable intermediate bulk containers displace single-use drums in Ohio chemical distribution. |
| Quebec EPR Regulatory Alignment | Extended producer responsibility frameworks create structured demand pull for recycled content. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with automotive Tier 1 procurement managers, FDA-registered medical packaging specialists, polyethylene plant managers, and Great Lakes distribution channel partners. Secondary validation drew from EPA recycled content filings, Health Canada chemical safety frameworks, SEC 10-K disclosures from resin-integrated majors, and American Chemistry Council trade data. Bottom-up capacity assessments across Michigan, Ohio, and Ontario facilities were triangulated against top-down demand modeling from automotive production schedules and food packaging procurement volumes.
Calibration against historical capacity utilization rates and resin price elasticity informed projections across the analysis window. Segmentation dimensions modeled include product type, end-user industry vertical, material grade specification, and geographic production cluster within the Great Lakes corridor. CAGRs were derived from regression analysis of installed capacity expansion announcements and regulatory compliance cost trajectories. Key inputs encompassed IRA tax credit eligibility thresholds and state-level extended producer responsibility adoption curves.
Practitioners should monitor EPA recycled content mandate enforcement intensity and rHDPE collection infrastructure buildout for early signals of forecast revision. Cross-checking against American Chemistry Council resin production and inventory data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
Middle East and Africa Single-Use Plastic Packaging Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market