
 United Kingdom Rigid Plastic Packaging Market | 2026-2036
United Kingdom Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Rigid Plastic Packaging Market Insights
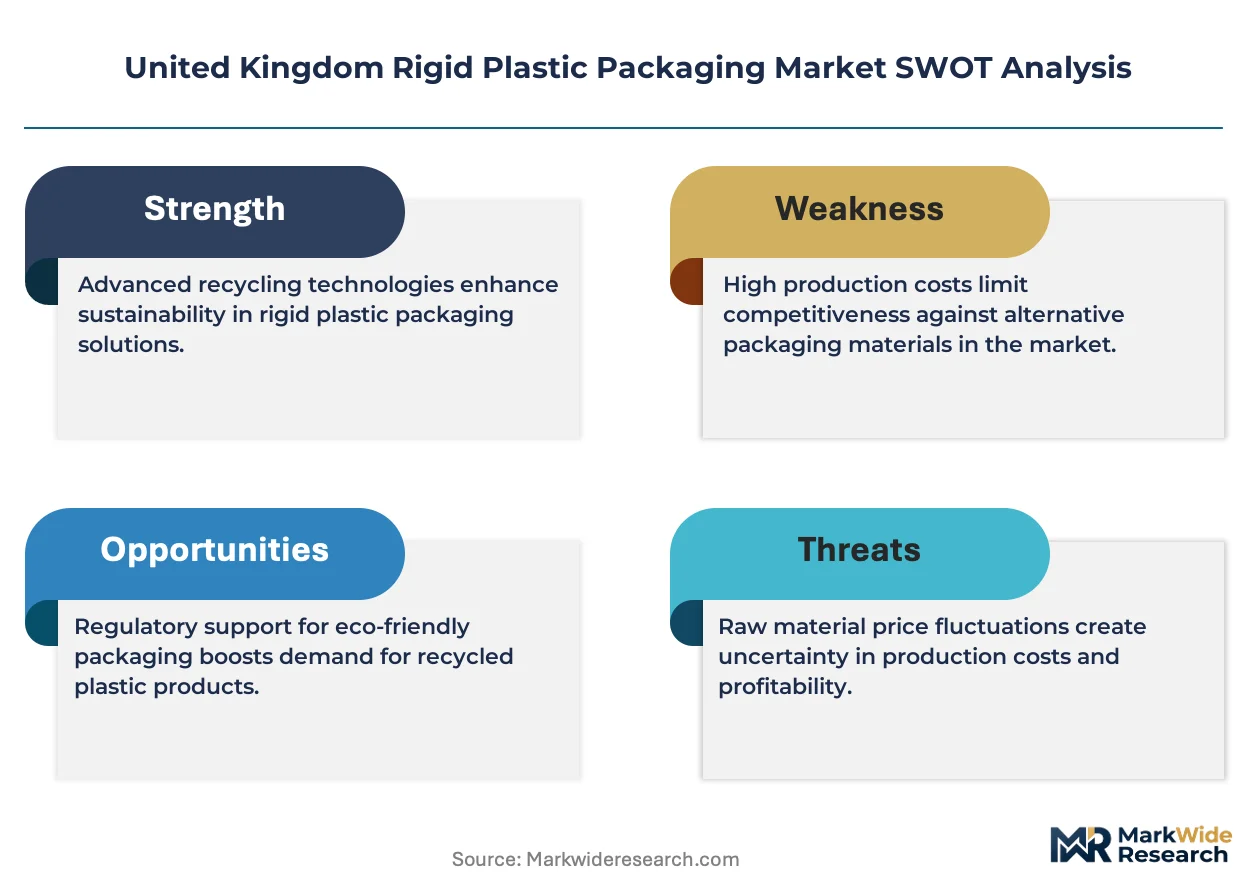
Pharmaceutical demand is recalibrating the United Kingdom Rigid Plastic Packaging Market as sterile barrier requirements and patient compliance features reshape procurement criteria. Berry Global Inc. dominates blow-molded prescription bottle supply through its healthcare-specialized operations. Amcor Group GmbH leverages multilayer barrier technology to sustain shelf-life extension contracts with branded drug makers. Robinson plc differentiates through custom tooling capabilities that serve mid-tier generic pharmaceutical clients.
United Kingdom Rigid Plastic Packaging comprises thermoformed or injection-molded polymer structures—typically polyethylene, polypropylene, PVC, or polystyrene—with wall thicknesses exceeding 0.25 millimetres, engineered to protect contents from moisture, oxygen ingress, and mechanical damage during distribution. Bottles and containers lead the product type landscape, reflecting entrenched demand from beverage and household chemical sectors where HDPE and PET formats prevail. Polypropylene is displacing polystyrene across food tub applications as microwave-safe requirements and recycling stream compatibility tighten material specifications.
The UK's Plastic Packaging Tax, enforced by HMRC, mandates minimum recycled content thresholds and directly alters material cost structures for converters serving domestic food and personal care brands. BSI standards and Environment Agency guidance on Extended Producer Responsibility shape design-for-recycling obligations that influence polymer selection and label adhesive specifications. Stakeholders must monitor post-collection sorting infrastructure investments and chemical recycling scale-up timelines to align capacity decisions with evolving compliance thresholds and offtake agreements.
Market Dynamics
Extended Producer Responsibility obligations and HMRC's Plastic Packaging Tax are forcing converters to redesign material specifications and renegotiate supplier contracts across England's polymer processing corridors.
Growth Catalysts
- Pharmaceutical compliance mandates:UK drug manufacturers are expanding procurement of child-resistant and senior-friendly rigid formats to meet MHRA safety requirements. Sterile barrier specifications now dominate tender evaluations for prescription packaging.
- Mechanical recycling infrastructure:Post-collection sorting investments in the Midlands are unlocking consistent PCR supply streams for food-contact applications. Local authorities are expanding kerbside collection of rigid PP and HDPE containers.
- Lightweighting engineering:Advanced injection molding and blow molding process controls are enabling wall-thickness reduction without structural compromise. Beverage and household chemical brands are specifying gram-weight reductions in supply agreements.
Market Restraints
- Recycled resin cost volatility:rPET and rPP pricing fluctuates with oil-indexed virgin polymer and collection yield variability. Converters cannot fully pass through material cost swings to FMCG clients locked in annual contracts.
- Single-source tooling dependency:Custom blow molds for pharmaceutical bottles often originate from specialized German or Italian equipment suppliers. Lead times exceeding 20 weeks constrain rapid format pivots.
- Design-for-recycling complexity:BSI standards on label adhesives and closure compatibility create formulation constraints that conflict with shelf-life performance requirements. Multilayer barrier structures face downstream sorting rejection.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization projects in Teesside and Humberside promise food-grade recycled content beyond mechanical stream limitations. Early offtake agreements with petrochemical platforms are securing preferential supply.
- Healthcare serialization integration:EU Falsified Medicines Directive compliance requirements are expanding demand for rigid containers with embedded tamper-evidence and track-and-trace features. Contract packagers are retrofitting lines for aggregation-ready formats.
- Reusable rigid pool systems:Closed-loop container pooling for industrial chemicals and food ingredients is gaining traction with mid-sized manufacturers. Logistics providers are establishing wash-and-return hubs in Manchester and Birmingham corridors.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for compatibilizing recycled content with virgin resin streams is concentrated among retiring specialists. Technical universities are not graduating sufficient materials scientists for packaging R&D functions.
- Validation timeline compression:Pharmaceutical packaging qualification protocols require 12-18 month stability studies that conflict with brand owners' compressed NPD cycles. Accelerated aging protocols face MHRA scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Rigid Plastic Packaging Market |
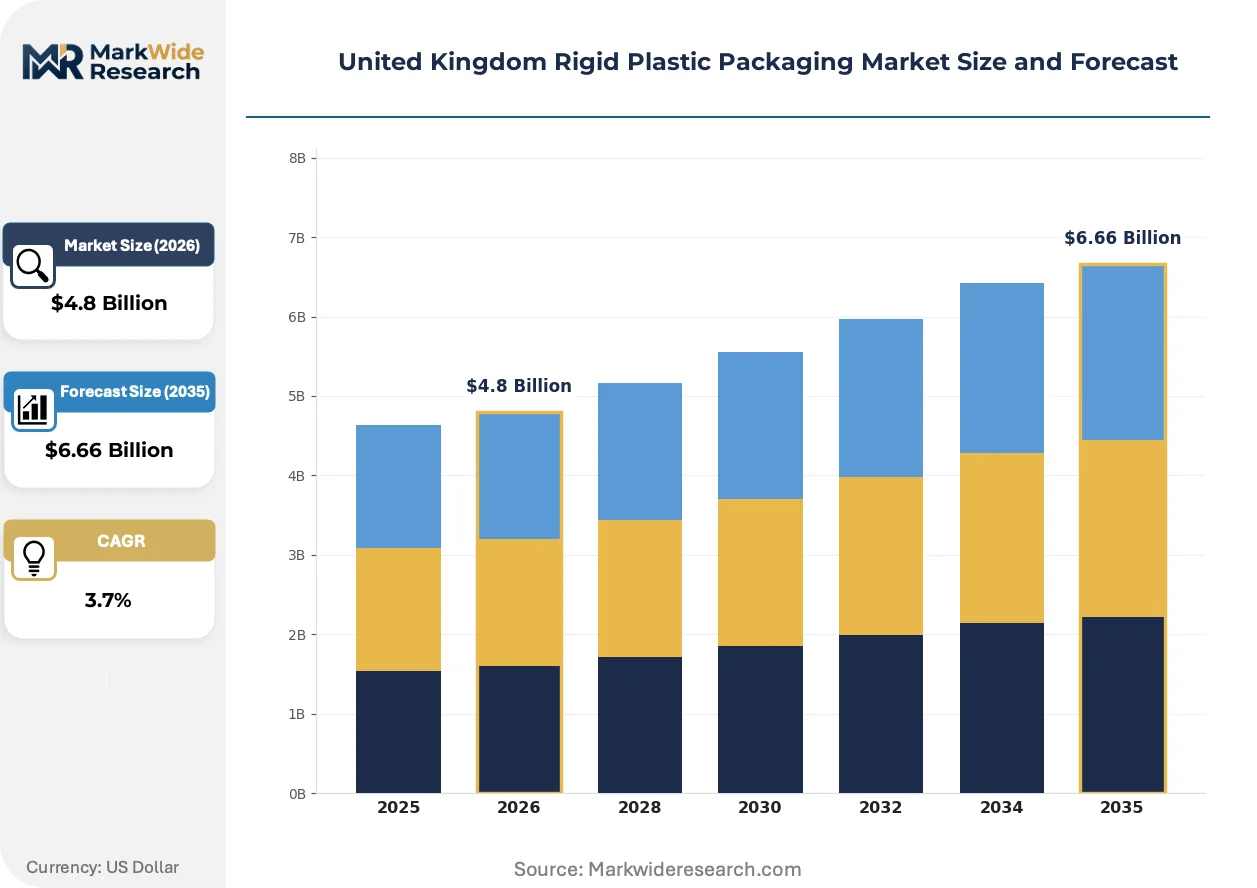
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Tubs End User: Food, Beverage, Personal Care, Pharmaceuticals Material: Polyethylene, Polypropylene, PVC, Polystyrene Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Aptar Group Inc., Coda Plastics Ltd., Berlin Packaging UK, P. Wilkinson Containers Ltd, Robinson plc, Esterform Packaging, Cambrian Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Rigid Plastic Packaging Market Trends and Innovations
Digital manufacturing controls and regulatory compliance automation are converging to reshape how UK converters specify, produce, and validate rigid plastic packaging across fragmented end-use requirements.
Digital twin simulation of injection molding processes is rewriting how toolmakers optimize cooling channel design and cycle times. Medical device and pharmaceutical contract manufacturers are adopting virtual commissioning to reduce physical prototype iterations. The technology is compressing time-to-market for complex multi-cavity molds while reducing scrap rates during startup phases.
HMRC's Plastic Packaging Tax enforcement is tightening recycled content verification requirements for converters serving domestic food and personal care brands. Third-party certification schemes such as RecyClass and EUCertPlast are becoming mandatory tender preconditions. Mid-sized converters in the North West are investing in mass-balance accounting systems to document post-consumer resin provenance.
Direct sourcing relationships between supermarket private-label teams and rigid packaging converters are displacing traditional distributor intermediaries. Retailers are specifying format standardization and shelf-ready merchandising features in direct negotiations. This pattern is most visible in England's fresh produce and dairy categories where own-brand penetration exceeds sixty percent.
United Kingdom Rigid Plastic Packaging Market Segmentation
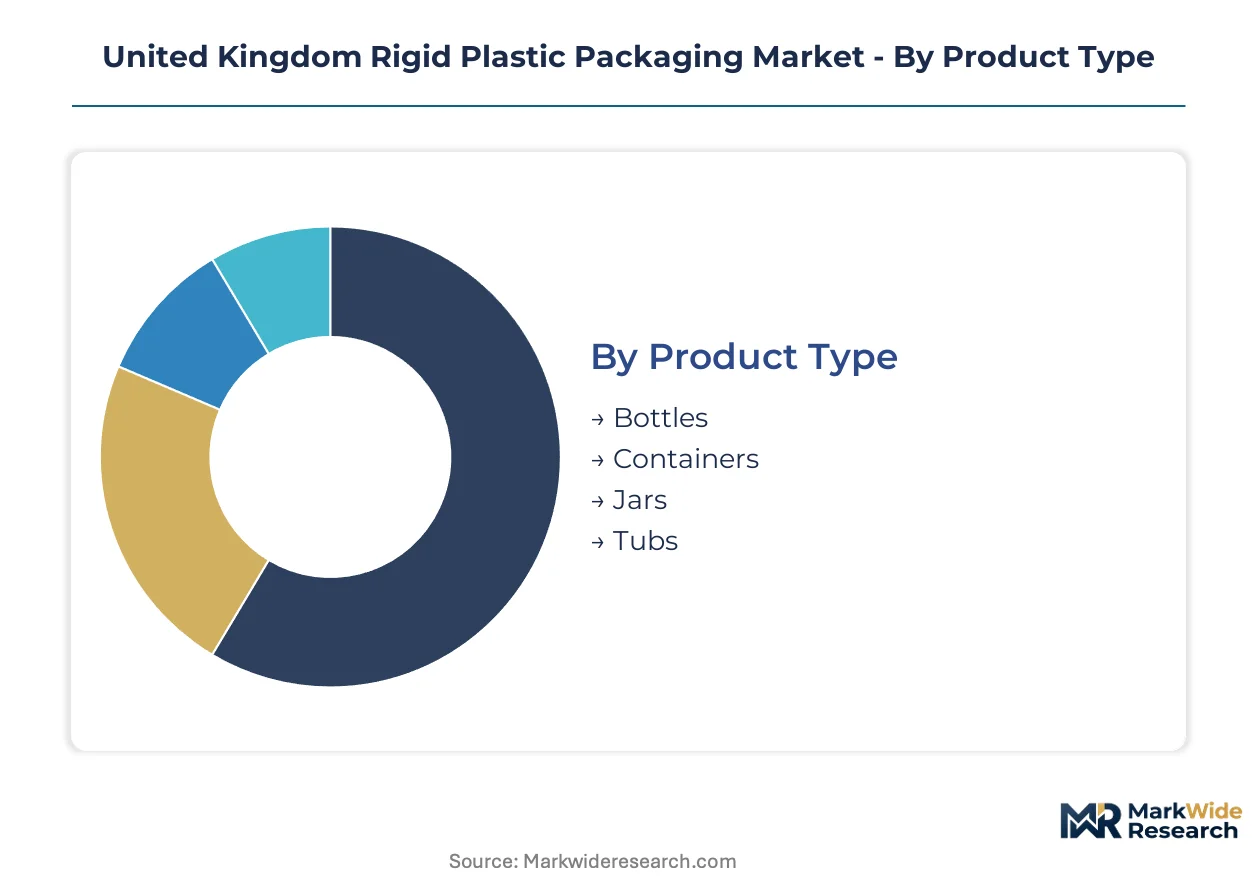
Segmentation reveals how material specifications, end-use compliance requirements, and channel economics fragment procurement patterns across England's polymer processing corridors. Each axis carries distinct margin profiles and regulatory exposure that shape converter specialization.
Product Type:
Wall thickness, closure complexity, and barrier layering requirements differentiate manufacturing economics across rigid formats.
- Bottles:Blow-molded HDPE and PET structures dominate prescription pharmaceutical and beverage applications. MHRA child-resistant closure mandates and HMRC recycled content thresholds are reshaping specification sheets for converters serving Boots and Tesco private-label contracts.
- Containers:Injection-molded rectangular formats with integrated handles serve household chemical and industrial lubricant sectors. Demand concentrates in West Midlands automotive supply corridors where chemical-resistant polypropylene formulations are specified.
- Jars:Wide-mouth thermoformed or injection-molded formats accommodate viscous personal care and food spreads. Tamper-evident banding requirements add secondary assembly costs that compress margins for mid-tier converters.
- Tubs:Thin-wall polypropylene formats serve ready-meal and dairy applications where microwave-safe specifications and kerbside recyclability determine retail listing approval.
Bottles lead on scale; containers lead on momentum.
End User:
Regulatory intensity and specification stability vary sharply across buyer categories, dictating converter qualification timelines and contract structures.
- Food:FSSAI-aligned safety specifications and retailer-driven design-for-recycling mandates dominate procurement. Extended Producer Responsibility obligations are forcing reformulation of multilayer barrier structures that previously optimized shelf life.
- Beverage:Lightweighting targets and rPET content mandates from supermarket private-label teams are accelerating investment in advanced blow molding controls. Carbonated and still water segments specify different barrier grades.
- Personal Care:Premium aesthetic requirements including metallic finishes and soft-touch overmolding conflict with sorting compatibility for mechanical recycling streams.
- Pharmaceuticals:MHRA sterile barrier and child-resistant closure mandates dominate tender evaluation. Validation protocols requiring 12-18 month stability studies create entry barriers for non-specialized converters.
Food commands volume concentration; pharmaceuticals commands margin concentration.
Material:
Polymer selection balances mechanical performance, regulatory compliance, and post-consumer recyclability within evolving collection infrastructure.
- Polyethylene:HDPE and LDPE grades serve blow-molded bottles and injection-molded caps across beverage and chemical applications. Midlands mechanical recycling investments are stabilizing rHDPE supply for food-contact formats.
- Polypropylene:Displacing polystyrene across microwaveable food tubs and pharmaceutical containers. Random copolymer grades offer clarity and impact resistance that meet healthcare serialization visibility requirements.
- PVC:Retained in pharmaceutical blister packs and specific chemical resistance applications despite environmental pressure. Medical device packaging exemptions sustain niche demand.
- Polystyrene:General purpose and high-impact grades retreat to low-cost disposable applications as recycling stream incompatibility triggers retailer delisting. Dairy and fresh produce trays face accelerated substitution.
Polyethylene leads on installed capacity; polypropylene leads on substitution momentum.
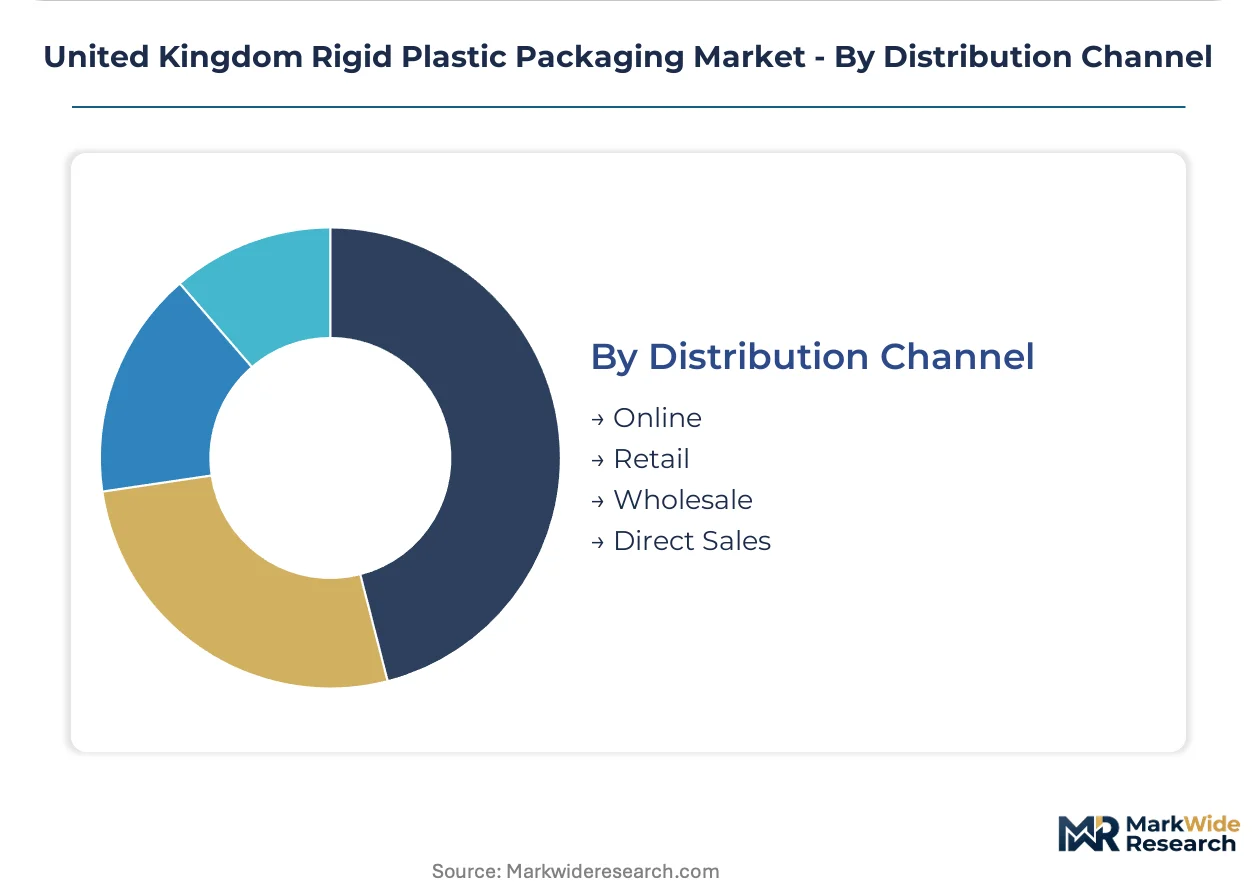
Distribution Channel:
Channel selection determines specification control, volume predictability, and working capital requirements for converters.
- Online:E-commerce direct-to-manufacturer platforms serve small-batch custom tooling for startup cosmetic and specialty food brands. Lead time compression and MOQ flexibility offset premium pricing.
- Retail:Supermarket private-label teams negotiate directly with converters, bypassing traditional distributors. Shelf-ready packaging specifications and format standardization dominate tender terms.
- Wholesale:Distributor intermediaries retain relevance for fragmented SME food and chemical processors requiring consolidated logistics and credit terms.
- Direct Sales:Long-term supply agreements with multinational FMCG and pharmaceutical manufacturers lock in dedicated capacity and co-development relationships.
Direct sales anchor revenue stability; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters are migrating capacity toward sub-regions with favorable Extended Producer Responsibility cost structures and established polymer processing infrastructure. The Midlands and North West corridors attract investment due to mechanical recycling proximity and HMRC compliance cost advantages over peripheral areas.
Midlands
Automotive chemical packaging and household product containers drive polymer demand across Birmingham and Coventry manufacturing zones. Environment Agency permitting for industrial emissions shapes converter siting decisions near existing petrochemical distribution nodes. West Midlands polymer clusters supply rigid HDPE formats to lubricant and cleaning product manufacturers with dedicated rail-served warehousing.
North West
Pharmaceutical contract packaging and food-grade rPET processing concentrate around Manchester and Liverpool logistics corridors. HMRC Plastic Packaging Tax administration operates through Liverpool-based customs facilities that service Irish Sea trade routes. Teesside chemical recycling projects promise future pyrolysis-derived feedstock for converters seeking food-contact compliant recycled content.
South East
Personal care and premium cosmetic packaging procurement clusters near London distribution hubs serving Heathrow air freight and Channel port access. MHRA pharmaceutical licensing proximity influences sterile barrier converter qualification timelines. Thames Valley logistics parks host co-packing operations that aggregate rigid formats for supermarket private-label distribution.
Scotland
Whisky and beverage bottling rigid formats sustain blow-molding demand across Glasgow and Edinburgh production facilities. Scottish Environment Protection Agency waste regulations diverge from England on certain producer responsibility thresholds. Grangemouth petrochemical infrastructure provides captive polyethylene supply to converters serving local drinks manufacturers.
Wales
Food processing and dairy packaging applications concentrate in South Wales valleys with historic polymer molding heritage. Natural Resources Wales permitting timelines for recycling facility expansion lag England's Environment Agency processing speeds. Cardiff and Newport corridors attract lightweighting-focused converters serving retailer sustainability scorecard requirements.
United Kingdom Rigid Plastic Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical and food-grade applications favoring dedicated healthcare converters while commodity formats sustain fragmented toll-manufacturing relationships. The vendor base organizes into three tiers: multinational integrated packaging groups with captive resin sourcing, mid-cap regional specialists with custom tooling capabilities, and niche contract manufacturers serving single-category buyers. Market structure rewards backward integration into recycling feedstock and forward integration into design-for-recycling services. Consolidation pressure concentrates among mid-tier players lacking mass-balance accounting systems for Plastic Packaging Tax compliance documentation.
Within the multinational integrated tier, Amcor Group GmbH and Berry Global Inc. anchor premium barrier technology and pharmaceutical serialization capabilities. Robinson plc occupies a position among mid-cap specialists with custom tooling heritage serving generic drug manufacturers. These three exemplify the strategic archetypes: global platform scale, healthcare regulatory depth, and agile format customization respectively.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Aptar Group Inc. |
| Coda Plastics Ltd. |
| Berlin Packaging UK |
| P. Wilkinson Containers Ltd |
| Robinson plc |
| Esterform Packaging |
| Cambrian Packaging |
| Others |
Pricing and Supply Chain Analysis
Captive resin sourcing through backward integration into mechanical recycling infrastructure anchors both supply security and pricing power for converters serving HMRC Plastic Packaging Tax compliance requirements. This integration choice separates mass-balance accounting capability from commodity toll-manufacturing relationships across England's polymer processing corridors.
Pricing Analysis
Retailer markup compression in supermarket private-label negotiations is reshaping margin structures for mid-tier converters lacking dedicated healthcare contracts. Three-tier pricing structure across premium barrier technology, standard food-grade formats, and economy commodity containers reflects certification grade and volume scale differentiation. Cost compression in standard-grade segments is intensifying because rPET and rPP supply volatility constrains pass-through pricing to annual-contract FMCG buyers. Pharmaceutical and healthcare packaging buyers exhibit lowest price sensitivity due to MHRA validation timeline requirements that lock in supplier relationships.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical and multinational FMCG demand through long-term supply agreements with dedicated capacity allocation. Raw material sourcing draws from Belgium and the Netherlands for virgin polymer feedstock, while post-consumer resin supply rests on Midlands mechanical recycling investments and emerging Teesside chemical recycling projects. Single-source tooling dependency on German and Italian mold suppliers creates structural vulnerability for format pivots exceeding twenty-week lead times. Distribution runs through England's Midlands and North West manufacturing corridors with rail-served warehousing proximity to polymer processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through lightweighting engineering adoption that reduces gram-weight specifications without structural compromise, alongside premium-tier shift toward pharmaceutical serialization-integrated formats commanding validation-timeline premiums.
For Market Incumbents: Acquire mechanical recycling feedstock assets to secure mass-balance accounting systems for HMRC compliance documentation. Consolidate custom tooling capabilities serving mid-tier generic pharmaceutical clients before chemical recycling scale-up disrupts PCR supply economics. Threat of polymer chemist scarcity in formulation expertise for recycled content compatibilization demands immediate technical university partnership investment. Capacity addition in Teesside corridor positions early offtake agreements with pyrolysis-derived feedstock projects. For New Entrants and Emerging Players: HMRC's Plastic Packaging Tax enforcement opens a window for digital mass-balance accounting platform providers serving mid-sized converters lacking compliance infrastructure. White-space targets include reusable rigid pool systems for industrial chemicals in Manchester and Birmingham logistics corridors, plus e-commerce direct-to-manufacturer channels for startup cosmetic brands requiring MOQ flexibility. Most penetrable segment is online small-batch custom tooling where lead time compression offsets premium pricing. Go-to-market angle centers on shelf-ready packaging specification expertise for supermarket private-label teams bypassing traditional distributors. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap regional specialists with custom tooling capabilities because consolidation pressure concentrates among players lacking Plastic Packaging Tax compliance documentation systems. Long-term viability framing favors acquisition targets with healthcare regulatory depth and pharmaceutical serialization integration expertise. Signal to watch is chemical recycling project commissioning timelines in Teesside and Humberside as inflection indicator for food-grade recycled content supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Feedstock | Secures mass-balance accounting capability for HMRC Plastic Packaging Tax compliance verification. |
| Healthcare Serialization Integration | Captures EU Falsified Medicines Directive contract packager retrofit demand for track-and-trace features. |
| Lightweighting Engineering Investment | Enables gram-weight reduction specifications that meet beverage brand sustainability scorecard requirements. |
| Chemical Recycling Offtake Agreements | Positions converters for food-contact compliant recycled content beyond mechanical stream limitations. |
| Direct Retailer Negotiation Capability | Bypasses distributor intermediaries for supermarket private-label shelf-ready packaging specifications. |
Research Methodology
Coverage spans England's Midlands, North West, South East, Scotland, and Wales corridors, with primary inputs from each region's polymer processing clusters. Primary interviews with converter operations directors, pharmaceutical packaging procurement managers, supermarket private-label category buyers, polymer chemists at technical universities, and Environment Agency permitting officers combined with secondary validation from HMRC Plastic Packaging Tax guidance documents, BSI standards publications, MHRA regulatory filings, and local authority kerbside collection infrastructure disclosures. Bottom-up and top-down triangulation cross-validated regional capacity estimates against national compliance threshold projections.
Granularity-level modeling operated at product type, end user, material, and distribution channel dimensions with regional production hub overlay. Volume and value outputs across the analysis window reflect segment-specific CAGRs derived from polymer processing capacity expansion timelines and regulatory compliance cost curve assumptions. Industry-specific forecast inputs incorporated chemical recycling project development databases and pharmaceutical validation protocol duration benchmarks.
Revisions become necessary when chemical recycling commissioning delays, mechanical recycling yield variability, or MHRA regulatory interpretation shifts materialize. Forecasts reflect assumptions on Extended Producer Responsibility cost pass-through rates and supermarket private-label penetration trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market