
 PET Preforms Market | 2026-2036
PET Preforms Market Size, Share, and Industry Trends Forecast 2026-2036
PET Preforms Market Analysis
China's manufacturing belt is reshaping PET preform supply dynamics through injection-stretch blow molding capacity additions. Indorama Ventures leverages backward integration into purified terephthalic acid to sustain margin control across Southeast Asian markets. Plastipak Holdings anchors North American beverage supply through captive bottle production networks. RETAL Industries specializes in high-cavitation mold technologies that differentiate its European output.
PET preforms are injection-molded tubular blanks of polyethylene terephthalate, typically ranging from 10 to 150 grams, designed for stretch blow molding into bottles and containers with burst pressures exceeding 15 bar. The material delivers gas barrier performance below 0.03 cc-mil per 100 square inches per day, making it indispensable for carbonated soft drinks and oxygen-sensitive foods. Standard preforms dominate volume throughput across beverage lines, while lightweight preforms capture fastest growth as Coca-Cola and PepsiCo systems pursue gram-per-bottle reduction targets. Recycled PET grade preforms command premium positioning where EFSA and FDA letter-of-no-objection certifications unlock food-contact applications.
The EU's Packaging and Packaging Waste Regulation alongside FDA food-contact notification requirements shape material compliance pathways for cross-border preform trade. China's GB 4806.6 standard for food-contact plastics and India's BIS certification for PET resin constrain market access for uncertified imports. REACH registration thresholds for antimony catalyst residues influence virgin PET sourcing decisions among European converters. Stakeholders must monitor evolving extended producer responsibility fee structures and recycled content mandates to calibrate capacity investments between virgin and rPET feedstock lines.
Market Dynamics
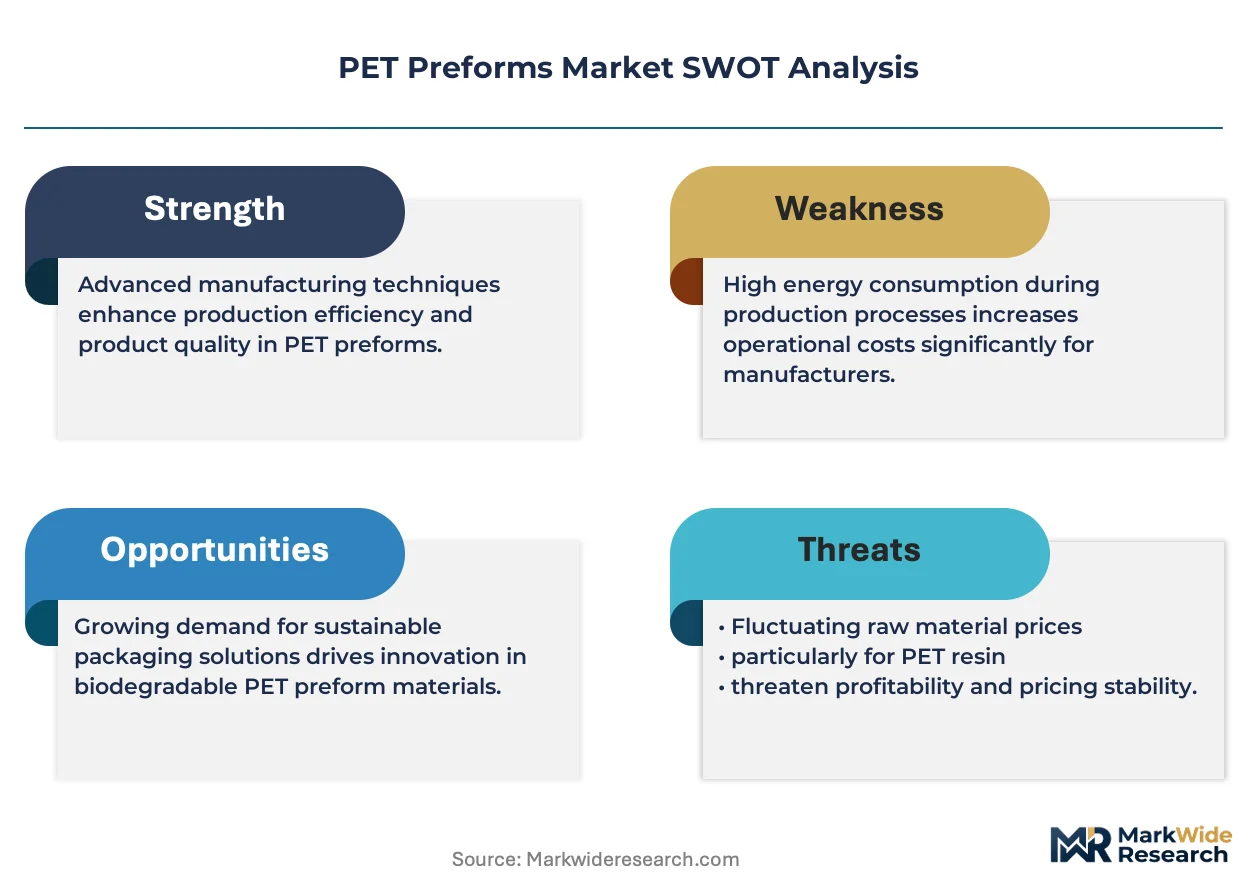
Lightweighting mandates from beverage brand owners are compressing gram weights per preform while maintaining burst pressure thresholds, forcing converters to recalibrate injection molding parameters and cavity designs.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content floors for PET bottles are pulling rPET-grade preforms into food-contact applications across European bottling lines.
- India's dairy sector conversion:Edible oil and milk brands are abandoning rigid containers for PET formats, expanding addressable demand beyond carbonated beverages.
- High-cavitation molding:144-cavity and 192-cavity tool technologies are slashing unit production costs for standard-weight preforms in high-volume beverage runs.
Market Restraints
- Purified terephthalic acid price volatility:Crude-linked paraxylene feedstock swings transmit directly to preform converter margins, compressing EBITDA at non-integrated facilities.
- Antimony catalyst residue thresholds:REACH registration requirements for virgin PET resin are constraining European sourcing flexibility and elevating compliance documentation burdens.
- Glass bottle persistence in premium spirits:Super-premium alcohol categories resist PET conversion due to tactile and perception barriers, capping penetration in high-margin packaging segments.
Strategic Opportunities
- EFSA letter-of-no-objection certification:Food-contact clearance for rPET preforms unlocks closed-loop supply contracts with major bottlers seeking circular packaging claims.
- Pharmaceutical blow-fill-seal integration:Sterile PET preforms for intravenous and ophthalmic applications represent an underpenetrated high-specification segment with pricing power.
- Extended producer responsibility fee differentials:Jurisdictions with lower EPR levies on recycled-content packaging are attracting rPET preform capacity investments.
Industry Challenges
- Hot-runner mold maintenance specialization:High-cavitation tooling requires technicians with polymer rheology expertise that command premium wages and limited labor pool availability.
- Dual certification timelines:Simultaneous FDA food-contact notification and EFSA safety assessments for novel rPET sources extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Preforms Market |
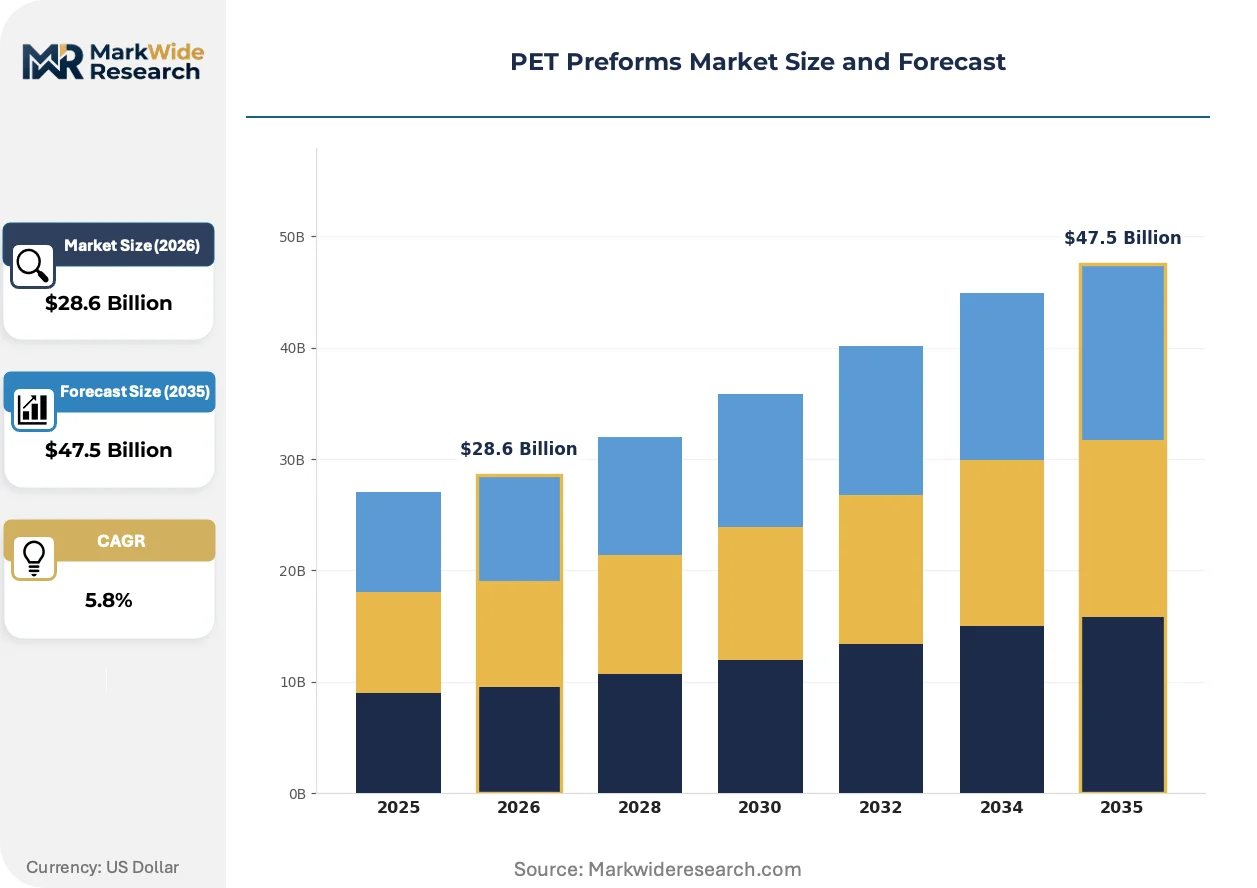
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Preforms, Custom Preforms, Lightweight Preforms, Multi-layer Preforms End Use Industry: Beverage, Food Packaging, Personal Care, Household Products Material Grade: Recycled PET, Virgin PET, High-Barrier PET, Biodegradable PET Packaging Type: Plastic Bottles, Jars, Containers, Closures |
| Companies Covered | Retal Industries Ltd., Taiwan Hon Chuan Enterprise Co., Ltd, Plastipak Holdings Inc., KOKSAN Pet Packaging Industry Co., Zhuhai Zhongfu Enterprise Co. Limited, ALPLA Werke Alwin Lehner GmbH & Co KG, RESILUX NV, Société Générale des Techniques, Indorama Ventures Public Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Preforms Market Emerging Trajectories
Preform manufacturing is pivoting toward closed-loop material flows and precision lightweighting as brand owners harden sustainability commitments and cost targets simultaneously.
Mono-material barrier coatings are migrating from experimental pilot lines to commercial beverage production. Silica-based plasma deposition technologies deposit sub-micron gas barrier layers directly onto preform interiors. Coca-Cola and PepsiCo bottling systems are qualifying these treatments for oxygen-sensitive juices and teas. The technology is migrating from niche premium applications toward mainstream carbonated soft drink volumes as coating deposition speeds approach 50,000 preforms per hour.
China's GB 4806.6 food-contact plastics standard is tightening migration limits for heavy metals and primary aromatic amines in virgin and recycled PET resins. The regulation forces preform importers to demonstrate supply chain traceability through resin batch testing. Southeast Asian converters serving Chinese beverage brands are accelerating in-house laboratory capacity to maintain market access.
Direct-to-bottler preform supply contracts are displacing merchant market spot purchases among top-20 global beverage companies. Procurement teams are consolidating supplier panels to three-to-five approved converters per region, extracting volume commitments in exchange for technical collaboration on lightweighting roadmaps. This concentration is most visible in North American and Western European markets where bottler procurement functions have centralized category management authority.
PET Preforms Market Segmentation
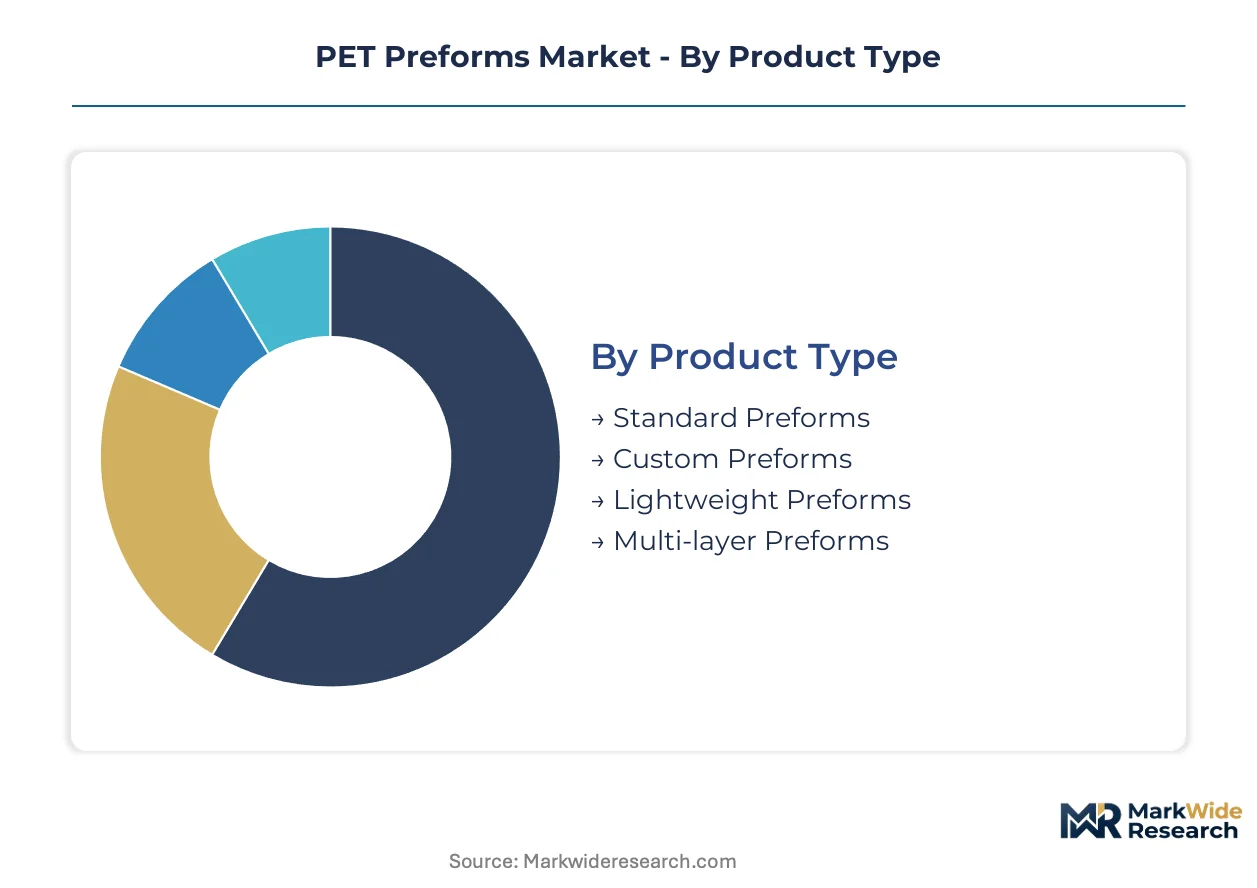
PET preform segmentation reveals divergent service intensity requirements across product tiers. Technical support demands escalate with specification complexity, reshaping converter-bottler contractual relationships and margin structures throughout the value chain.
Product Type:
After-sales service intensity varies sharply across preform categories, with high-cavitation tooling and lightweight designs demanding specialized mold maintenance programs that extend far beyond standard warranty periods.
- Standard Preforms:Injection-molded tubular blanks ranging from 10 to 150 grams with conventional single-layer PET construction. Demand concentrates in carbonated soft drink bottling lines across India and China, where beverage brand owners prioritize supply security over specification differentiation. High-cavitation production lines for standard preforms require dedicated hot-runner maintenance contracts to sustain cavity-to-cavity consistency.
- Lightweight Preforms:Engineered with reduced gram weights per bottle while maintaining burst pressure thresholds above 15 bar through optimized wall thickness distribution. Coca-Cola and PepsiCo systems in North America and Western Europe are driving adoption as gram-per-bottle reduction targets harden. These designs demand tighter process control and more frequent mold servicing than standard alternatives.
- Custom Preforms:Application-specific geometries developed for unique bottle shapes or functional requirements. Specialty dairy and edible oil formats in India utilize custom neck finishes and body profiles.
- Multi-layer Preforms:Co-extruded structures incorporating oxygen-scavenging or carbon dioxide barrier layers. Premium juice and beer applications in Europe deploy these for extended shelf-life requirements.
By volume, Standard Preforms leads. By growth pace, Lightweight Preforms is ahead.
End Use Industry:
Application-driven cost tier differentiation separates commodity beverage supply from specialized food-contact and personal care segments with divergent certification burdens.
- Beverage:Carbonated soft drinks, bottled water, juices, and functional beverages represent the dominant consumption category. Asia-Pacific bottlers in China, India, and Vietnam drive volume throughput. EFSA and FDA food-contact notification requirements constrain rPET integration timelines, extending commercialization cycles for recycled-content variants.
- Food Packaging:Edible oils, dairy products, sauces, and condiments are converting from rigid containers to PET formats. India's dairy sector expansion is accelerating demand for oxygen-barrier preform designs with specialized closure compatibility.
- Personal Care:Shampoos, conditioners, and lotions utilize PET for clarity and chemical resistance. Premium positioning in this segment resists lightweighting pressures seen in beverage applications.
- Household Products:Cleaners, detergents, and automotive fluids employ PET for chemical containment and retail shelf presence. Lower regulatory scrutiny permits faster material innovation cycles than food-contact segments.
By revenue scale, Beverage dominates. By margin expansion potential, Food Packaging is climbing the fastest.
Material Grade:
Supply concentration dynamics around purified terephthalic acid sourcing and recycling infrastructure create divergent margin profiles across material tiers.
- Recycled PET:Post-consumer flake processed to food-contact purity standards with EFSA letter-of-no-objection or FDA notification clearance. European converters face REACH registration thresholds for antimony catalyst residues that constrain sourcing flexibility. The EU's Packaging and Packaging Waste Regulation is mandating recycled content floors that pull rPET-grade preforms into mainstream beverage applications.
- Virgin PET:Polymerized from purified terephthalic acid and monoethylene glycol with consistent intrinsic viscosity and color specifications. Crude-linked paraxylene feedstock price volatility transmits directly to converter margins.
- High-Barrier PET:Modified resin systems or additive packages enhancing gas barrier performance for oxygen-sensitive applications. Specialty beer and juice segments in Japan and South Korea utilize these formulations.
- Biodegradable PET:Experimental grades incorporating bio-based monomers or degradation accelerants. Limited commercial penetration due to performance gaps and regulatory uncertainty around composting infrastructure.
By installed capacity, Virgin PET leads. By investment flow, Recycled PET is gaining share fastest.
Packaging Type:
Customer type segmentation separates high-volume bottler direct contracts from merchant market spot purchases with divergent pricing mechanisms and technical collaboration depth.
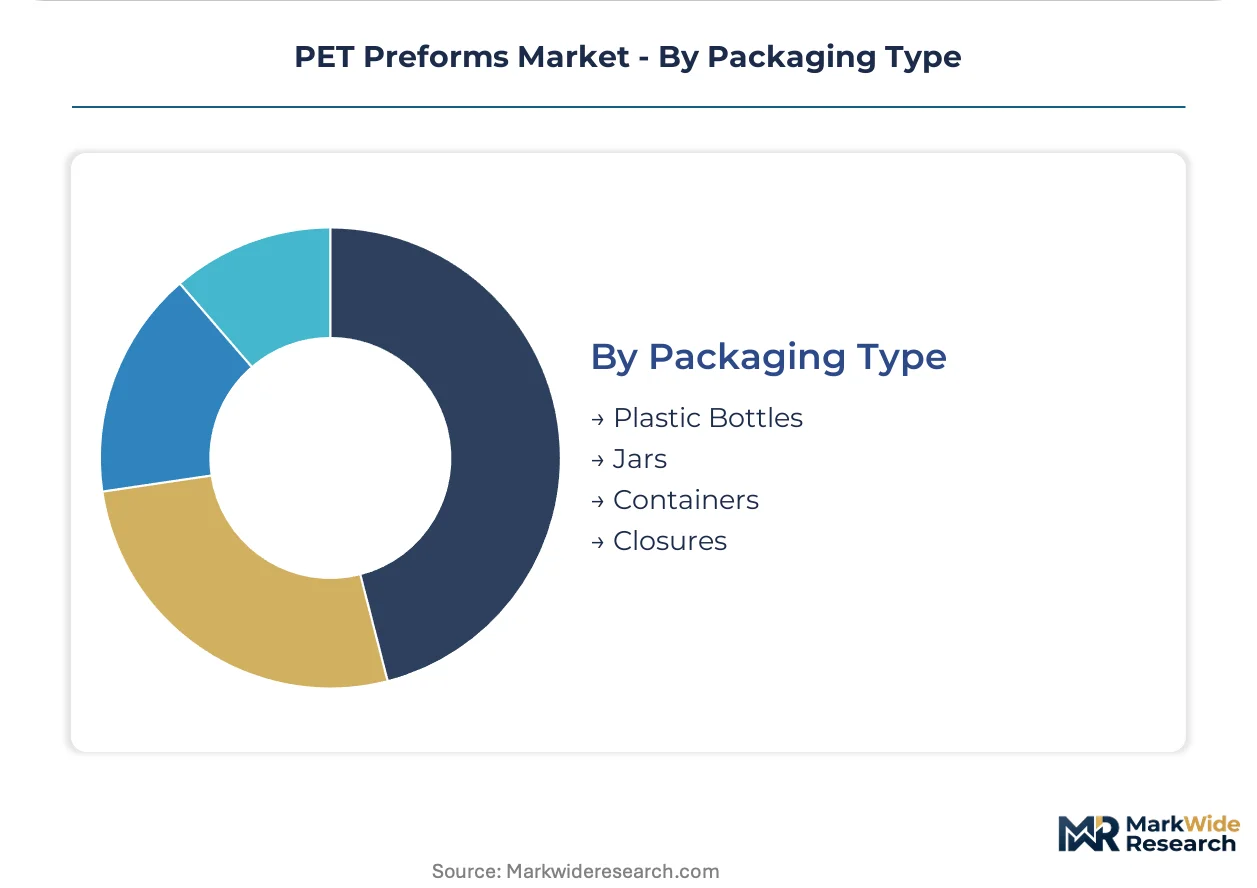
- Plastic Bottles:Stretch blow-molded containers for beverages, foods, and personal care products. North American and Western European bottlers are consolidating supplier panels to three-to-five approved converters per region, extracting volume commitments in exchange for lightweighting roadmap collaboration.
- Jars:Wide-mouth containers for food spreads, condiments, and personal care creams. India's edible oil brands are driving format conversion from metal and glass.
- Containers:General-purpose rigid packaging for industrial and household applications. Lower specification tolerance permits broader supplier qualification.
- Closures:Threaded caps and dispensing systems requiring precise dimensional match with preform neck finishes. Closure-preform compatibility testing extends qualification timelines for new converter entry.
By shipment volume, Plastic Bottles leads. By specification complexity growth, Jars is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB 4806.6 food-contact plastics standard anchors Asia-Pacific compliance frameworks, forcing preform importers to demonstrate resin batch traceability. The EU's Packaging and Packaging Waste Regulation alongside India's BIS certification requirements create divergent certification burdens across major demand centers.
China
Beverage bottlers in the Yangtze River Delta drive injection-stretch blow molding capacity additions for carbonated soft drink lines. GB 4806.6 tightening on heavy metal migration limits forces Southeast Asian converters serving Chinese brands to accelerate in-house laboratory investment. Zhuhai-based fabricators anchor Pearl River Delta supply clusters for lightweight preform export.
India
Dairy and edible oil brands in Maharashtra and Gujarat abandon rigid containers for PET formats, expanding addressable demand beyond beverages. BIS certification for PET resin constrains market access for uncertified imports from Southeast Asia. Ahmedabad and Mumbai industrial corridors concentrate blow molding conversion capacity for domestic edible oil packaging.
Germany
REACH registration thresholds for antimony catalyst residues influence virgin PET sourcing decisions among European converters. The EU Single-Use Plastics Directive mandates recycled content floors that pull rPET-grade preforms into mainstream beverage applications. Bavarian and North Rhine-Westphalian packaging clusters specialize in high-cavitation mold technologies for standard preform export.
United States
FDA food-contact notification requirements shape material compliance pathways for cross-border preform trade from Canadian and Mexican suppliers. Bottler procurement teams consolidate supplier panels to three-to-five approved converters per region, extracting volume commitments for lightweighting collaboration. Michigan and Ohio industrial bases anchor North American injection molding capacity for captive bottle production networks.
Brazil
ANVISA pharmaceutical packaging regulations create compliance pathways for sterile PET preforms in intravenous and ophthalmic applications. Extended producer responsibility fee structures in São Paulo state incentivize rPET preform investments over virgin alternatives. São Paulo and Minas Gerais concentrate blow-fill-seal integration capacity for high-specification medical packaging.
PET Preforms Market Vendor Landscape
Capability concentration sits with specialists commanding hot-runner mold maintenance expertise; scale advantage sits with integrated resin-to-preform operators. The vendor base organizes around three strategic tiers: backward-integrated petrochemical conglomerates, captive bottler-owned converters, and independent merchant suppliers. Dominant competitive moves include capacity expansion in high-cavitation tooling and strategic partnerships for rPET feedstock security.
Within the integrated tier, Indorama Ventures Public Company Limited exemplifies upstream control through purified terephthalic acid sourcing. Among European specialists, RETAL Industries and ALPLA Werke Alwin Lehner GmbH & Co KG occupy positions defined by mold technology differentiation and regional bottler relationships. Plastipak Holdings anchors North American beverage supply through captive production networks that bypass merchant market spot purchasing.
| Leading Market Players |
|---|
| Retal Industries Ltd. |
| Taiwan Hon Chuan Enterprise Co., Ltd |
| Plastipak Holdings Inc. |
| KOKSAN Pet Packaging Industry Co. |
| Zhuhai Zhongfu Enterprise Co. Limited |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| RESILUX NV |
| Société Générale des Techniques |
| Indorama Ventures Public Company Limited |
| Others |
Supply Flow & Price Mechanics
Zhuhai's injection-molding clusters anchor Asia-Pacific capacity expansion, translating manufacturing scale into pricing leverage over European and North American bottler procurement teams. The Pearl River Delta's backward integration into purified terephthalic acid feedstock insulates Chinese converters from paraxylene volatility that compresses margins at non-integrated facilities elsewhere.
Pricing Analysis
Geographic price spreads between Asian export hubs and European domestic production run 15-25 percent for standard-weight preforms, reflecting labor cost differentials and energy pricing gaps. Three-tier pricing structure across food-contact certified, industrial-grade, and uncertified import tiers separates EFSA-cleared rPET preforms from virgin alternatives. Pricing pressure stems from high-cavitation tooling investments in China and India that flood merchant markets with commoditized volume. Small-scale dairy converters in Maharashtra exhibit highest price sensitivity, while Coca-Cola and PepsiCo systems prioritize supply security over unit cost in direct-to-bottler contracts.
Supply Chain Analysis
Export-control regimes on high-cavitation mold technologies limit tool flows from German and Austrian specialists to Southeast Asian fabricators, constraining capacity replication speed. Supply concentrates in China, India, and Germany, with China's Yangtze River Delta and India's Gujarat corridor hosting the densest converter clusters. Raw material dependencies center on purified terephthalic acid from integrated petrochemical complexes, monoethylene glycol from ethylene crackers, and food-contact-grade rPET flake from European mechanical recycling lines. Single-source vulnerability runs through antimony catalyst suppliers for virgin PET resin facing REACH registration thresholds. Distribution runs through direct-to-bottler long-term contracts displacing spot purchases among top-20 global beverage companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage brand owner procurement consolidation to three-to-five approved converters per region has shifted bargaining power decisively toward buyers, squeezing merchant market pricing and forcing technical collaboration concessions from suppliers.
For Market Incumbents: Insulate margin position through captive rPET flake sourcing agreements with European mechanical recyclers holding EFSA letters-of-no-objection, while accelerating high-cavitation capacity additions in India to defend volume share against Zhuhai-based exporters. The threat of lightweighting mandates compressing gram weights per preform demands tighter process control investments that smaller merchant converters cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in India's dairy and edible oil packaging conversion, where BIS certification requirements constrain import competition and local blow molding capacity lags preform demand growth. Target pharmaceutical blow-fill-seal applications in Brazil under ANVISA regulations, where sterile PET preform specifications create pricing power unavailable in commodity beverage supply. Lead with technical service intensity rather than unit cost to bypass scale disadvantages against integrated incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a circular packaging infrastructure play because regulatory mandates for recycled content floors are structurally permanent rather than cyclical. Acquisition targets should emphasize converters with in-house rPET decontamination capabilities and established EFSA safety assessments, not virgin PET scale. The signal to watch is dual certification timeline compression—faster FDA and EFSA parallel review pathways would unlock premium positioning for early movers in food-contact rPET supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Sourcing | Secures feedstock for EU Packaging and Packaging Waste Regulation compliance at beverage bottler direct contracts. |
| High-Cavitation Mold Technology Deployment | 144-cavity and 192-cavity tools slash unit costs for standard preforms in India and China volume runs. |
| EFSA Letter-of-No-Objection Certification | Unlocks closed-loop supply contracts with European bottlers pursuing circular packaging claims under Single-Use Plastics Directive. |
| Pharmaceutical Blow-Fill-Seal Integration | ANVISA compliance for sterile PET preforms opens intravenous and ophthalmic segments with pricing power. |
| Direct-to-Bottler Contract Consolidation | Three-to-five converter panels extract volume commitments in exchange for lightweighting roadmap collaboration. |
Methodological Framework
Desk research of customs trade databases, SEC and exchange filings from listed petrochemical conglomerates, and EU regulatory notification precedents preceded structured interviews with PET preform plant managers, beverage bottler procurement directors, hot-runner mold technology specialists, and mechanical recycling facility operators. Primary fieldwork covered converter operations in China's Pearl River Delta, India's Gujarat industrial corridor, and Germany's North Rhine-Westphalia packaging cluster. Secondary validation drew from BIS certification records, EFSA safety assessment publications, and FDA food-contact notification databases. Bottom-up capacity and utilization estimates were triangulated against top-down demand modeling from beverage brand owner volume disclosures.
Forecast assumptions held fixed the EU's recycled content mandate trajectories, China's GB 4806.6 enforcement intensity, and crude-linked paraxylene pricing correlation patterns, while varying lightweighting adoption speed and rPET food-contact certification timeline compression. Segmentation modeling spanned product type, end-use industry, material grade, and packaging format dimensions. CAGRs were derived from fitted growth curves against historical volume trajectories, with cross-checks against injection-stretch blow molding capacity expansion announcements and bottler procurement consolidation patterns.
Stress conditions across purified terephthalic acid price volatility bands, REACH antimony threshold revisions, and Indian dairy sector conversion speed were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory timeline delays, feedstock supply disruptions, and technology substitution in premium spirits packaging. Material shifts in EU extended producer responsibility fee structures or FDA-EFSA mutual recognition pathways would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate-Glycol (PETG) Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Blow Moulded Plastic Packaging Market