
 FFS Rigid Films Market | 2026-2036
FFS Rigid Films Market Size, Share, and Industry Trends Forecast 2026-2036
FFS Rigid Films Market Foresight
Co-extrusion barrier technology is narrowing the performance gap between mono-material and multi-layer FFS rigid films. Mondi Group leverages in-house polymer compounding to sustain film clarity at reduced caliper. Berry Global Inc. anchors North American supply through blown film lines optimized for high-speed form-fill-seal equipment. Amcor plc differentiates via integrated design-to-recycling services that navigate emerging extended-producer-responsibility frameworks.
FFS rigid films are thermoformed or extruded polymer sheets engineered for automated form-fill-seal packaging lines, typically ranging from 150 to 800 microns in thickness and specified for dimensional stability under vacuum or pressure forming. These films seal to themselves or lidding substrates to create hermetic packages for moisture-sensitive or oxygen-critical contents. Polypropylene formulations lead volume due to cost-positioning and heat-seal latitude, while multi-layer co-extruded structures capture margin pools in pharmaceutical and fresh-protein applications where ethylene-vinyl-alcohol or polyamide barrier layers extend shelf life. Metallized and laminated forms occupy niche positions in electronic device packaging where electrostatic discharge protection commands price premiums over standard mono-layer offerings.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are reshaping material selection, with ECHA evaluations of phthalate alternatives directly influencing PVC substitution rates in food-contact films. FDA food-contact notifications and ISO 15378 GMP standards for medicinal packaging govern export-oriented production from European converters. Stakeholders must monitor polymer recycling infrastructure buildout and mechanical-recycling yield rates, as these determine whether mono-material claims translate into actual circular-economy compliance without sacrificing barrier performance.
Market Dynamics
Co-extrusion barrier technology is compressing the performance premium historically commanded by multi-layer structures, forcing converters to recalibrate capital allocation between legacy blown film assets and next-generation cast line investments.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recycled-content mandates for rigid plastic formats are accelerating capital deployment into mono-material compatible extrusion lines across German and French packaging corridors.
- Fresh-protein packaging:Retailers in the Cologne-Düsseldorf industrial zone are specifying ethylene-vinyl-alcohol barrier layers to extend shelf life and reduce food waste penalties.
- Thin-gauge conversion:Downgauging to sub-200-micron films preserves material throughput while satisfying ECHA evaluations of phthalate alternatives driving PVC substitution.
Market Restraints
- Polypropylene resin volatility:Propylene feedstock exposure ties margin stability to naphtha-cracker economics and regional refinery utilization rates.
- Mechanical-recycling yield gaps:Actual circular-economy compliance remains constrained by contamination rates in post-industrial film waste streams.
- Barrier-layer incompatibility:Polyamide and EVOH fractions in multi-layer structures complicate mono-material claims under emerging extended-producer-responsibility frameworks.
Strategic Opportunities
- Pharmaceutical serialization:ISO 15378 GMP certification requirements for medicinal packaging create margin pools for converters with validated clean-room extrusion capacity.
- Electronic device packaging:Metallized FFS films with electrostatic discharge protection command price premiums in semiconductor logistics chains.
- Design-to-recycling services:Integrated consulting models that navigate REACH chemical compliance and recycling infrastructure buildout differentiate full-service suppliers.
Industry Challenges
- Multi-layer delamination control:Co-extrusion die design expertise is scarce, constraining yield rates at reduced caliper targets.
- Legacy equipment retrofit costs:Food packaging lines require substantial modification to handle thinner-gauge films without sacrificing forming consistency.
- Extended-producer-responsibility reporting:Fragmented national implementations of packaging waste regulations complicate pan-European compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FFS Rigid Films Market |
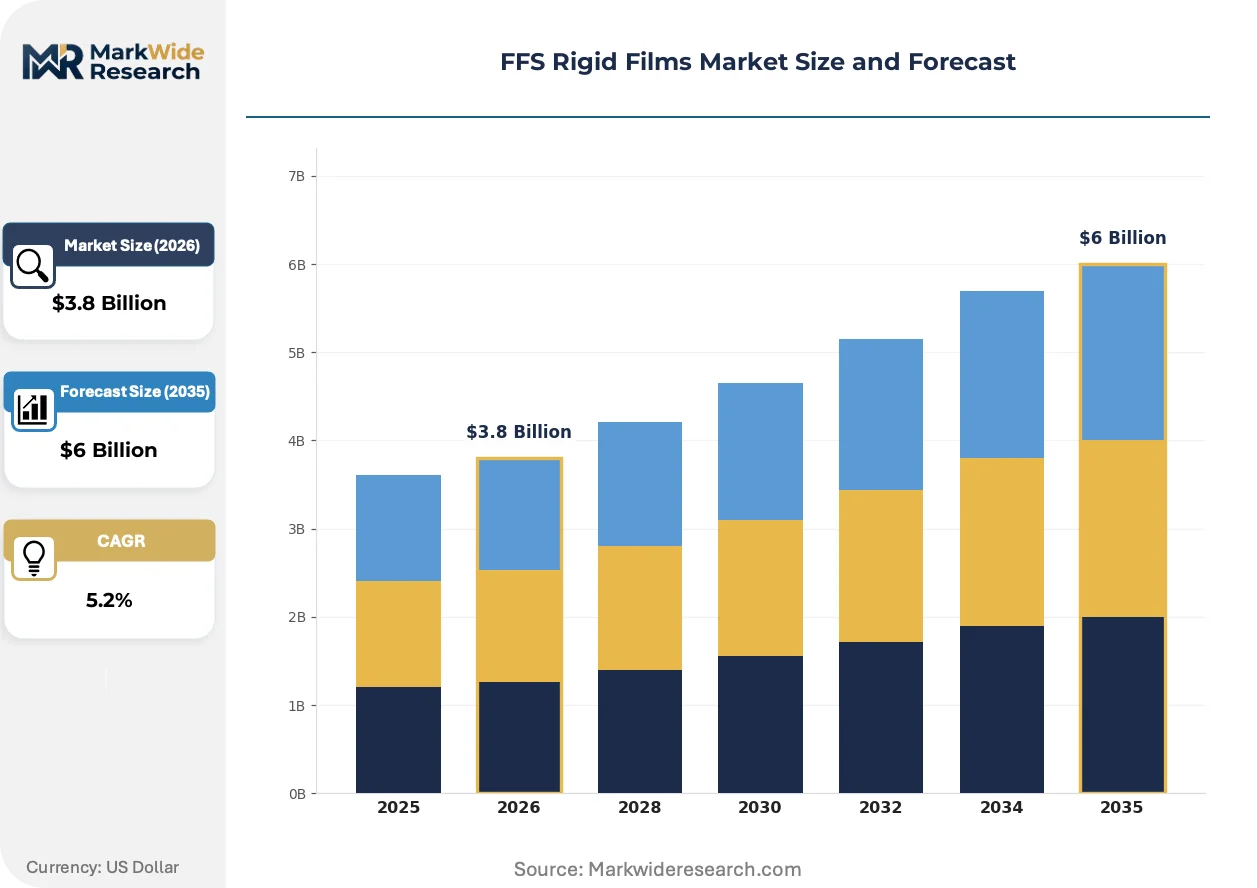
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polyvinyl Chloride, Polypropylene, Polystyrene, Cellulose Acetate Form: Mono-layer, Multi-layer, Co-extruded, Laminated, Metallized Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Containers, Industrial Wrapping, Electronic Device Packaging End User: Plastic Converters, Packaging Manufacturers, Contract Packaging, Branding Agencies |
| Companies Covered | Mondi Group, Constantia Flexibles Group, Amcor plc, Fucine Film Solutions, Avi Global Plast, Berry Global Inc., Coveris Holdings S.A., Living Fresh Packaging, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FFS Rigid Films Market Shifts & Advancements
Active migration from commodity polypropylene toward engineered co-extruded structures is redefining technical specifications and procurement criteria across European form-fill-seal operations.
Co-extrusion barrier technology is migrating from pharmaceutical and fresh-protein niches into broader food-contact applications. Mid-tier converters in Germany and France are adopting five-layer cast film lines to access barrier performance without full metallization. This technology is migrating from premium segments into standard dairy and ready-meal packaging, compressing price premiums for conventional laminated structures.
REACH chemical compliance frameworks are reshaping material selection through ECHA evaluations of phthalate alternatives. Industrial consequence includes accelerated PVC substitution in food-contact films and heightened scrutiny of additive packages in polypropylene formulations. Fresh-protein and dairy segments are responding with proactive reformulation programs to secure advance food-contact notifications.
Buyer concentration among German retail cooperatives is consolidating procurement leverage and compressing supplier margins. Direct specification of recycled-content thresholds is replacing reliance on converter certifications. This pattern is most visible in the Rhine-Ruhr packaging cluster, where centralized buying desks now mandate thin-gauge compatibility and mechanical-recyclability documentation as standard tender requirements.
FFS Rigid Films Market Segmentation
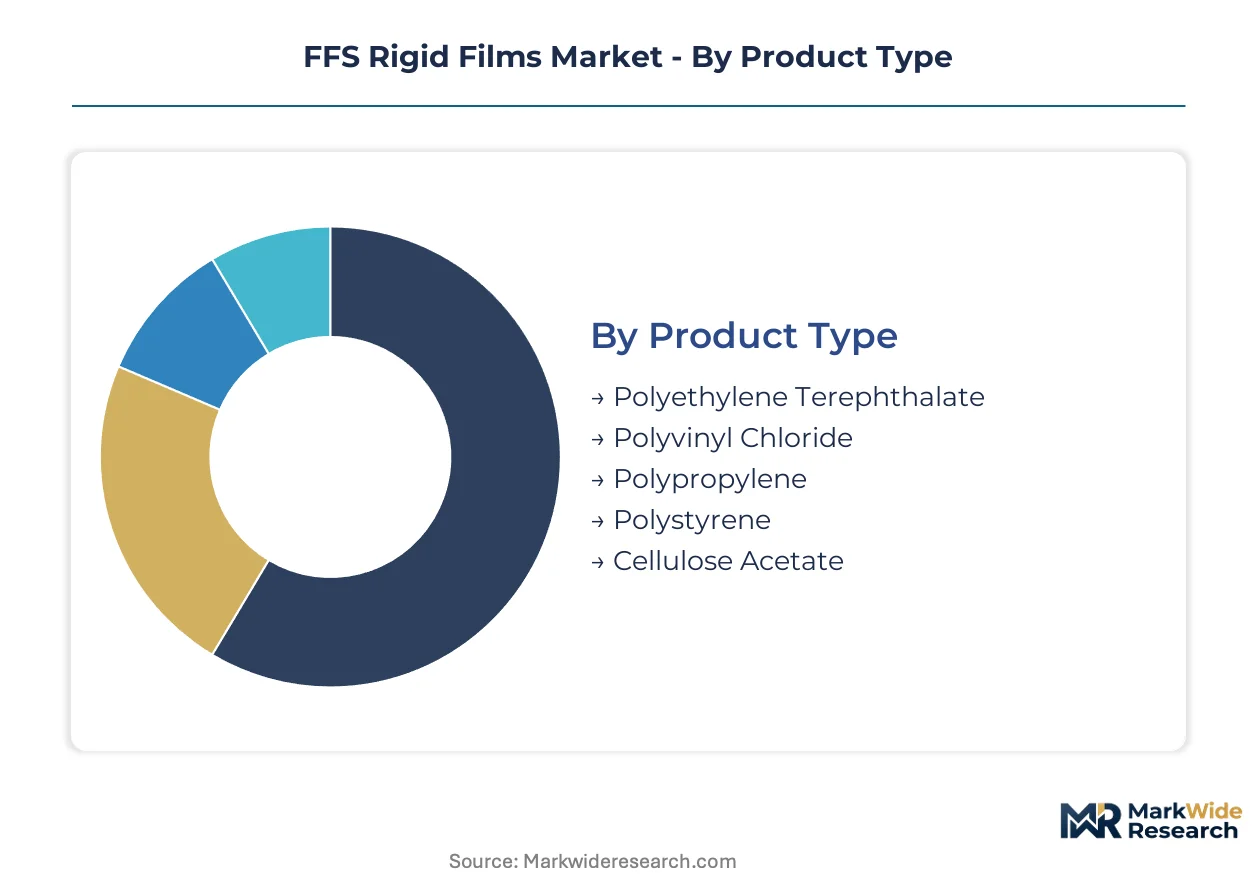
FFS rigid films segment across polymer chemistry, structural architecture, and downstream application requirements. Procurement criteria diverge sharply between commodity food-contact specifications and validated pharmaceutical formats where ISO 15378 GMP compliance commands price premiums.
Product Type:
Polymer selection traces a cost-performance arc from commodity polyolefins to engineered barrier formulations.
- Polypropylene:Semi-crystalline thermoplastic dominates European volume due to heat-seal latitude and caliper reduction compatibility. German retail cooperatives in the Cologne-Düsseldorf corridor specify biaxially oriented grades for downgauged fresh-protein trays.
- Polyethylene Terephthalate:Amorphous-to-crystalline transition behavior delivers dimensional stability for thermoformed pharmaceutical blisters. REACH chemical compliance scrutiny of additive packages is accelerating migration toward glycol-modified copolyesters in high-clarity applications.
- Polyvinyl Chloride:ECHA evaluations of phthalate alternatives are compressing food-contact adoption; residual demand concentrates in industrial blister packs where legacy tooling amortization delays conversion.
- Polystyrene:Crystal and high-impact grades retain position in cosmetic containers and disposable cutlery formats; brittleness constraints exclude oxygen-critical applications.
- Cellulose Acetate:Bio-based feedstock positioning captures premium cosmetic and specialty food niches; moisture sensitivity limits barrier-critical deployments.
Established volume favors Polypropylene; emerging adoption favors Polyethylene Terephthalate.
Form:
Structural complexity determines recyclability claims and equipment compatibility.
- Multi-layer:Co-extruded barrier constructions incorporating EVOH or polyamide fractions capture pharmaceutical and fresh-protein margin pools. EPR framework fragmentation complicates post-consumer sorting infrastructure for these formats.
- Co-extruded:Five-layer cast film lines narrow the performance gap against fully laminated structures while preserving mono-material recyclability credentials. Mid-tier converters in France are retrofitting blown film assets to access this technology.
- Mono-layer:Homogeneous polypropylene or PET sheets satisfy EU Packaging and Packaging Waste Regulation recycled-content mandates with minimal sorting complexity.
- Laminated:Adhesive-bonded combinations of dissimilar polymers deliver peak barrier performance; delamination risk and incompatible recycling streams constrain growth trajectories.
- Metallized:Vacuum-deposited aluminum layers provide electrostatic discharge protection for semiconductor logistics; niche positioning commands substantial price premiums over standard offerings.
Multi-layer constructions dominate current pharmaceutical specification; co-extruded formats are climbing the fastest as converters balance barrier performance against circular-economy compliance.
Application:
End-use requirements fragment across oxygen sensitivity, mechanical load, and regulatory validation tiers.
- Food Packaging:Thermoformed trays and lidding films for modified-atmosphere packaging represent the volume anchor. Retailer mandates for thin-gauge compatibility and mechanical-recyclability documentation are reshaping converter procurement in Germany.
- Pharmaceutical Packaging:Blister packs and cold-form foils demand ISO 15378 GMP certification and validated clean-room extrusion capacity. Serialization requirements are tightening specification control.
- Cosmetic Containers:Aesthetic clarity and decoration compatibility drive material selection; cellulose acetate and PET-G copolyesters occupy premium positioning.
- Industrial Wrapping:Pallet stabilization and corrosion-inhibiting formats prioritize tensile strength over barrier precision; commodity polypropylene satisfies most specifications.
- Electronic Device Packaging:Metallized and conductive grades protect sensitive components during logistics; semiconductor supply chain reshoring is expanding addressable demand.
Food packaging anchors installed capacity; pharmaceutical and electronic applications deliver steepest margin expansion.
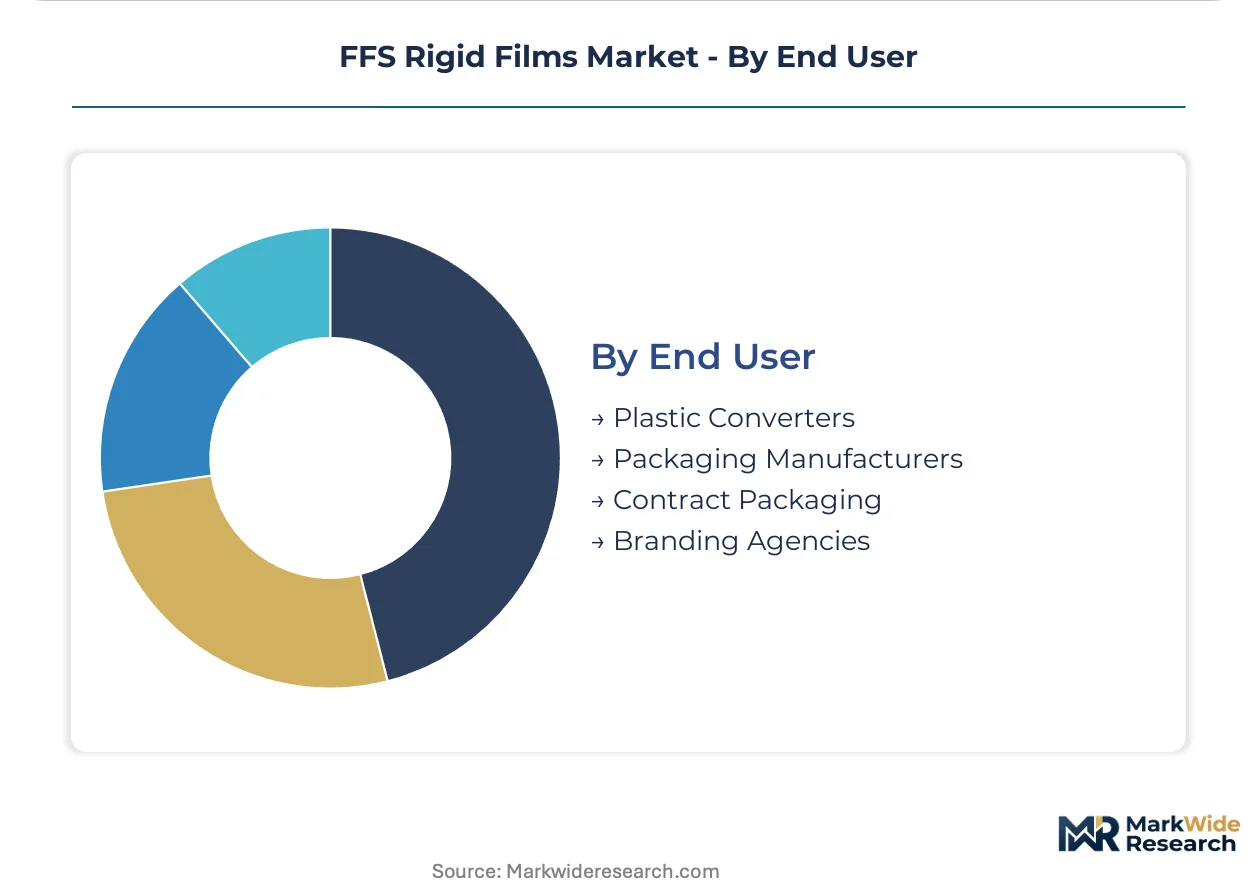
End User:
Customer type determines specification authority and contract structure.
- Packaging Manufacturers:Integrated form-fill-seal operations in the Rhine-Ruhr cluster wield direct specification power over film caliper, barrier construction, and recycled-content thresholds.
- Plastic Converters:Toll extrusion and thermoforming specialists respond to downstream customer mandates; equipment retrofit costs for thin-gauge handling compress operating margins.
- Contract Packaging:Third-party logistics providers prioritize equipment flexibility and rapid format changeover; standardization pressures favor mono-material specifications.
- Branding Agencies:Design-to-recycling consulting services are emerging as a distinct procurement channel; integrated material-selection and compliance-navigation offerings differentiate full-service suppliers.
Packaging manufacturers concentrate volume authority; branding agencies represent the fastest-expanding influence channel as EPR reporting obligations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German retail cooperatives and French dairy processors anchor procurement authority across the European FFS rigid films landscape, with specification power concentrating in industrial corridors rather than dispersed national markets.
Germany
The Cologne-Düsseldorf industrial corridor drives thin-gauge conversion demand as packaging lines retrofit for sub-200-micron films. ECHA evaluations of phthalate alternatives accelerate PVC substitution in food-contact applications. North Rhine-Westphalia hosts the densest concentration of form-fill-seal equipment operators, with centralized buying desks now mandating mechanical-recyclability documentation as standard tender requirements.
France
Fresh-protein retailers specify ethylene-vinyl-alcohol barrier layers to extend shelf life and reduce food waste penalties. REACH chemical compliance frameworks prompt proactive reformulation programs in dairy and ready-meal segments. The Rhône-Alpes packaging cluster sees mid-tier converters retrofitting blown film assets to access five-layer co-extrusion technology.
Italy
Pharmaceutical blister pack demand from Lombardy-based drug manufacturers tightens ISO 15378 GMP certification requirements. The national pharmaceutical regulator enforces serialization standards that ripple upstream to film converters. Emilia-Romagna thermoforming specialists expand clean-room extrusion capacity to capture medicinal packaging margin pools.
United States
FDA food-contact notification requirements govern export-oriented production from European converters serving American pharmaceutical and food brands. Berry Global Inc. anchors North American supply through blown film lines optimized for high-speed equipment. The Midwest industrial belt concentrates thermoforming operations serving retail and healthcare end-uses.
China
Dual carbon goals and GB standards for packaging recyclability reshape material selection for converters serving export markets. Yangtze River Delta electronics manufacturers drive metallized film demand for semiconductor logistics protection. NMPA pharmaceutical regulations tighten specification control for blister pack films destined for domestic drug distribution.
FFS Rigid Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base organizes around three strategic archetypes: integrated packaging conglomerates with in-house polymer compounding, mid-scale converters with regional equipment footprints, and specialty metallization houses serving electronics logistics. Dominant competitive moves include portfolio diversification into design-to-recycling services and geographic expansion through toll extrusion partnerships.
Within the integrated conglomerate tier, Mondi Group and Amcor plc exemplify channel-controlling positions. Mondi leverages in-house polymer compounding capabilities to sustain film clarity at reduced caliper. Amcor occupies a position differentiated through integrated design-to-recycling services that navigate extended-producer-responsibility frameworks. Berry Global Inc. anchors North American supply as a scale-driven specialist in high-speed form-fill-seal compatibility.
| Leading Market Players |
|---|
| Mondi Group |
| Constantia Flexibles Group |
| Amcor plc |
| Fucine Film Solutions |
| Avi Global Plast |
| Berry Global Inc. |
| Coveris Holdings S.A. |
| Living Fresh Packaging |
| Sealed Air Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity signals from North Rhine-Westphalia's blown film corridor are compressing converter margins and forcing recalibration of pricing discipline across European supply contracts. German packaging cooperatives exploit this utilization slack to extract mechanical-recyclability documentation without price premiums, while resin volatility in propylene feedstock chains amplifies margin instability for non-integrated players.
Pricing Analysis
Cost-plus contracts indexed to ICIS propylene assessments dominate procurement structures across the Cologne-Düsseldorf industrial zone. Price differentiation separates ISO 15378 GMP-certified pharmaceutical grades from commodity food-contact specifications, with certification tier commanding substantial premia over standard polypropylene offerings. Cost compression in fresh-protein barrier films is intensifying as five-layer co-extrusion technology democratizes EVOH performance without full metallization. Branding agencies and design-to-recycling consultants exhibit lowest price sensitivity due to compliance-navigation value capture, while mid-tier plastic converters face acute margin pressure from thin-gauge retrofit requirements.
Supply Chain Analysis
Export-control regimes limiting advanced co-extrusion die technology flows from Germany and Austria constrain capacity expansion in emerging converter markets. Geographic supply concentration centers on Germany, France, and Italy, with the Rhine-Ruhr cluster hosting densest form-fill-seal equipment density. Raw material dependencies draw from naphtha-cracker propylene, EVOH barrier resin, and polyamide feedstocks. Single-source vulnerability in specialized five-layer cast line equipment amplifies supply chain risk. Distribution runs through integrated packaging manufacturers with direct specification authority, bypassing traditional converter intermediaries in consolidated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FFS rigid films market is positioned for cyclical recovery as EU Packaging and Packaging Waste Regulation enforcement tightens recycled-content mandates and accelerates equipment replacement cycles. Polypropylene resin volatility and mechanical-recycling yield gaps create temporary margin compression that favors integrated players with captive compounding capabilities.
For Market Incumbents: Harden barrier-layer delamination control through proprietary co-extrusion die design expertise, defending against mid-tier converters retrofitting to five-layer technology. Deepen upstream control over polymer compounding to offset propylene feedstock volatility and sustain clarity performance at sub-200-micron calipers. Prioritize ISO 15378 GMP certification investment to capture pharmaceutical serialization margin pools as Lombardy-based drug manufacturers tighten specification control.
For New Entrants and Emerging Players: Establish a beachhead in metallized electronic device packaging for Yangtze River Delta semiconductor logistics, where electrostatic discharge protection commands substantial price premiums and incumbent presence remains thin. Target design-to-recycling consulting services for German retail cooperatives navigating fragmented extended-producer-responsibility reporting requirements. Go-to-market leverage rests on integrated compliance-navigation offerings that bundle REACH chemical expertise with mechanical-recyclability documentation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with validated clean-room extrusion capacity serving pharmaceutical blister pack demand, as serialization requirements tighten specification lock-in and extend contract durations. Long-term viability favors integrated conglomerates with in-house polymer compounding and established EPR framework navigation capabilities. The signal to watch is mechanical-recycling yield rate improvements in post-industrial film waste streams, which would validate mono-material claims and trigger accelerated capital deployment into compatible extrusion lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Mondi Group's captive resin production sustains film clarity at reduced caliper amid propylene volatility. |
| Five-Layer Co-Extrusion Capacity Expansion | Mid-tier French converters retrofit blown film assets to access barrier performance without full metallization. |
| ISO 15378 GMP Certification Investment | Emilia-Romagna thermoforming specialists capture medicinal packaging margin pools from Lombardy drug manufacturers. |
| Design-to-Recycling Service Launch | Amcor's integrated consulting navigates REACH compliance and EPR reporting for German retail cooperatives. |
| Metallized Film Production Scale-Up | Yangtze River Delta electronics manufacturers drive semiconductor logistics protection demand with price premiums. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across published sources. Primary interviews captured perspectives from extrusion line operators, procurement leads at German retail cooperatives, technical R&D directors at polymer compounders, and regulatory affairs specialists navigating ECHA evaluations. Secondary sources included EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance evaluation dossiers, ICIS resin pricing assessments, and SEC filings from listed packaging conglomerates. Bottom-up capacity estimates across the Cologne-Düsseldorf corridor were triangulated against top-down demand projections from food packaging and pharmaceutical end-uses.
Forecast inputs considered polymer chemistry segments, structural architecture tiers, and application requirements across the analysis window. Segmentation dimensions modeled included product type, form complexity, end-use regulatory validation tier, and geographic production cluster. CAGRs were derived from slope analysis of annual progression curves adjusted for regulatory inflection points. Industry-specific inputs incorporated mechanical-recycling yield rate trajectories and EVOH barrier layer adoption curves in fresh-protein packaging.
Stress conditions across propylene feedstock volatility, EPR framework fragmentation, and co-extrusion technology diffusion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding recycled-content mandate enforcement timelines and resin recycling infrastructure buildout. Cross-checking against ICIS resin price benchmarks and EU regulatory implementation trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Polyethylene Terephthalate (PET) Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Vacuum Forming Plastic Market