
 Asia Pacific Plastic Packaging Market | 2026-2036
Asia Pacific Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Plastic Packaging Market Outlook
Polyethylene terephthalate is realigning rigid container economics as converters substitute virgin grades with food-safe recycled flake. Amcor plc leverages integrated recycling infrastructure across Australia and Thailand to secure flake supply. Mondi plc anchors its kraft-plastic hybrid portfolio in industrial bagging applications where paper barrier limitations persist. UFlex Limited dominates flexible film exports from India to African and Middle Eastern markets.
Asia Pacific plastic packaging comprises thermoformed, extruded, and molded polymer structures engineered for containment, preservation, and unitization of consumer and industrial goods, with typical film gauges ranging from twelve to two hundred microns depending on barrier requirements. Films leads material throughput due to snack and fresh-produce wrapping volumes, while PET bottles capture premium beverage accounts demanding clarity and carbonation retention. Food and Beverage applications command the largest value pool, though Healthcare blister packs carry superior margin profiles owing to validation and cleanroom requirements.
China's SAMR enforces GB standards for food-contact plastics, while India's BIS mandates ISI certification for polyethylene carry bags under environmental quality orders. Japan's METI circular economy guidelines pressure brand owners to verify recycled content claims through mass-balance documentation. Stakeholders must track how extended producer responsibility schemes in Indonesia and Vietnam alter collection economics before committing to domestic compounding investments.
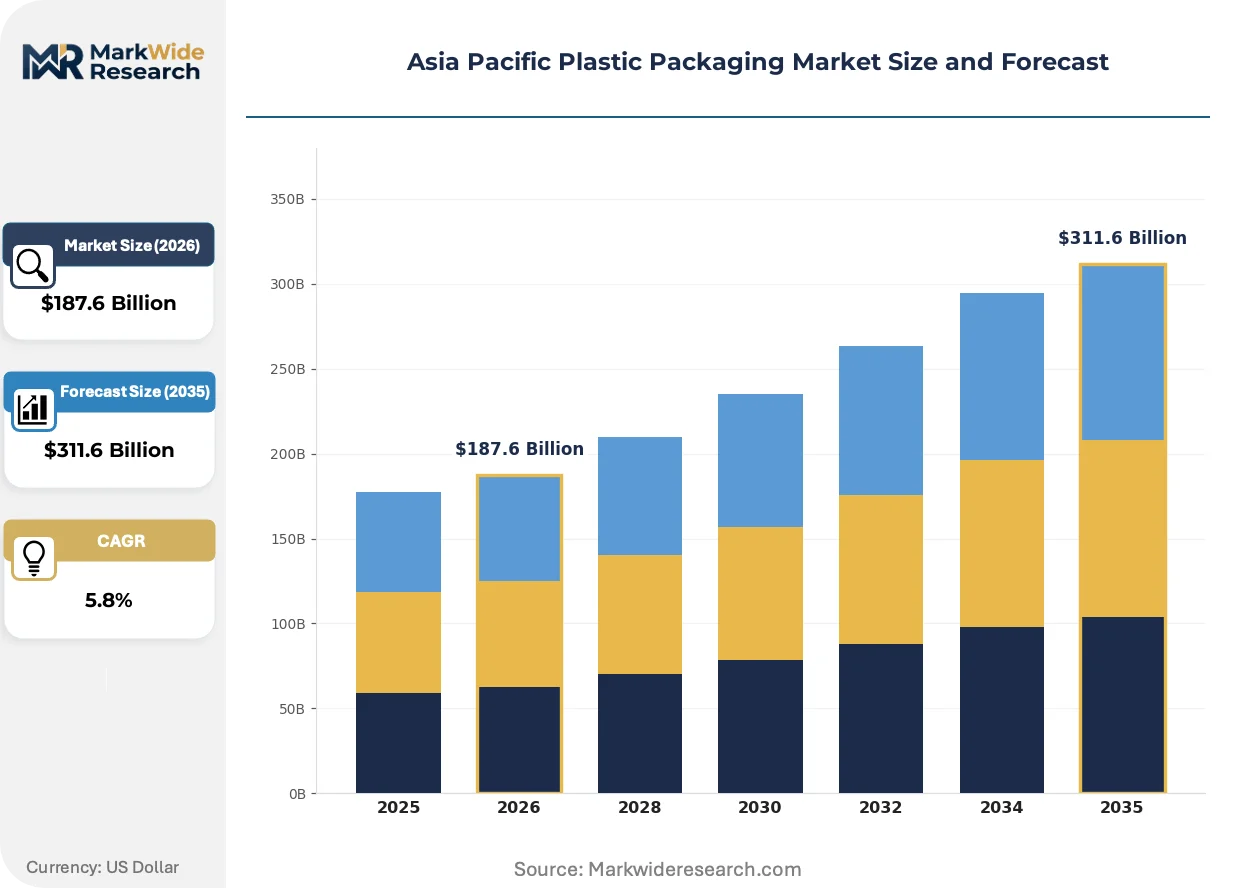
Market Dynamics
China's dual carbon goals and India's Plastic Waste Management Rules are forcing converters to re-engineer resin formulations around recycled flake availability, compressing virgin polyethylene margins across Southeast Asian supply chains.
Growth Catalysts
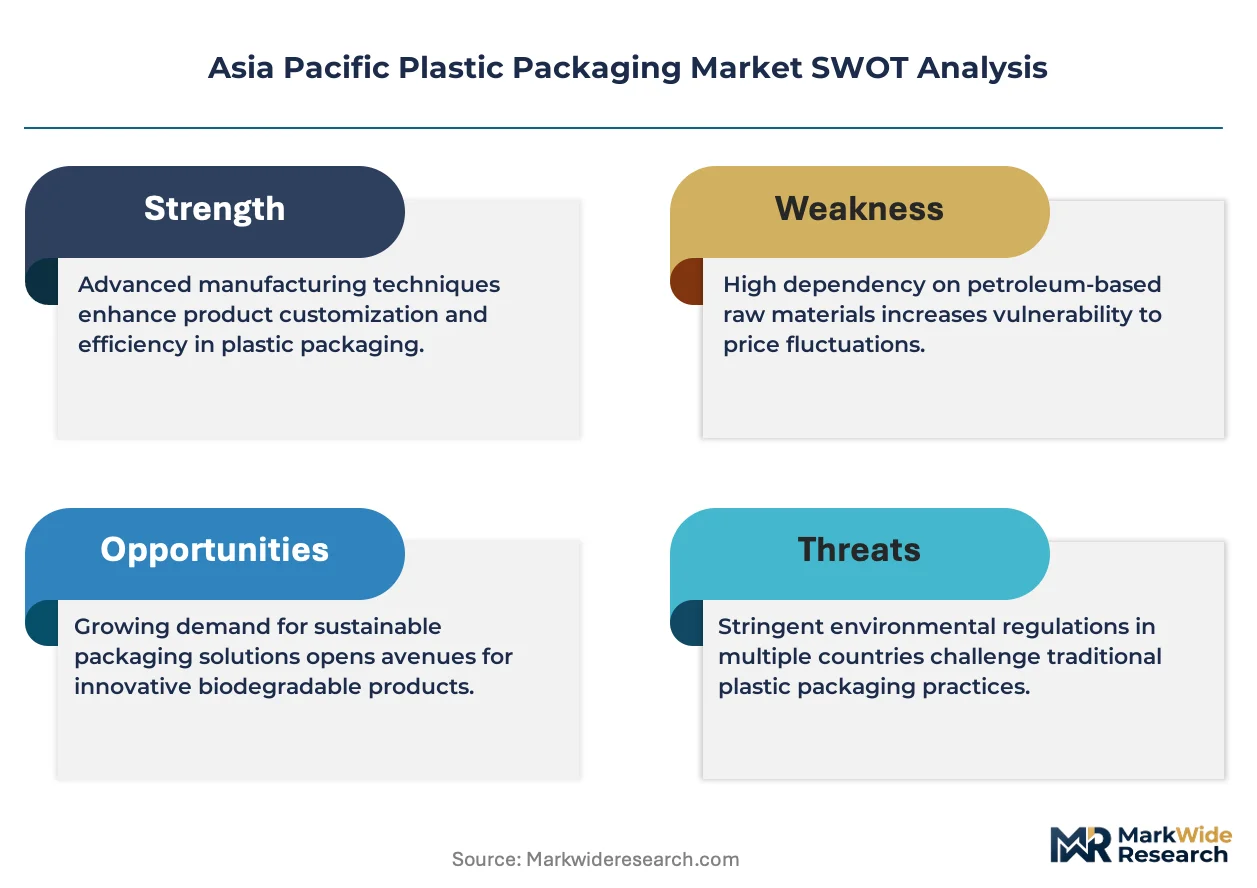
- Extended Producer Responsibility mandates:Indonesia's EPR schemes for plastic packaging are mobilizing brand-anchored collection networks that secure post-consumer feedstock for domestic reprocessors.
- Food-grade rPET flake qualification:Thailand's FDA-equivalent food-contact approvals for mechanically recycled polyethylene terephthalate are unlocking rigid container substitution in ASEAN beverage bottling.
- Jakarta corridor demand concentration:Indonesia's fast-moving consumer goods processors are expanding polyethylene film purchases for shelf-stable snack and fresh-produce wrapping.
Market Restraints
- Recycled resin price volatility:Post-consumer bale supply fragmentation across Indonesian islands creates input cost instability for domestic compounders.
- Food-contact certification timelines:China's SAMR GB standard migration testing for recycled-content plastics extends qualification cycles by eight to fourteen months.
- Biodegradable polymer substitution:PLA and PHA pilot deployments in Japanese retail bagging threaten commodity polyethylene volumes in single-use applications.
Strategic Opportunities
- Vietnam's underpenetrated central provinces:Da Nang and Hue industrial zones lack integrated flexographic printing and slitting capacity for regional snack distributors.
- Healthcare blister pack validation services:India's CDSCO medical device packaging regulations create margin-rich demand for cleanroom-certified thermoforming.
- Digital watermark-sorting infrastructure:Convergence of near-infrared detection and blockchain traceability is expanding into Japanese brand-owner compliance verification.
Industry Challenges
- Mass-balance accounting skill scarcity:Japan's METI circular economy guidelines require auditors capable of verifying recycled content claims across multi-tier supply chains.
- Legacy extrusion line retrofit costs:Converting cast film equipment for high-percentage recycled polyethylene blends demands capital outlays that mid-tier Thai processors cannot self-finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Plastic Packaging Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Containers, Films Application: Food & Beverage, Healthcare, Personal Care, Household Material: Polyethylene, Polypropylene, PET, PVC End User: Retail, Wholesale, E-commerce, Manufacturing |
| Companies Covered | Amcor plc, Mondi plc, Sonoco Products Company, Berry Global Group Inc, Sealed Air Corporation, DS Smith PLC, UFlex Limited, SCG Packaging, Huhtamaki India Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Plastic Packaging Market Strategic Shifts
Active and intelligent packaging technologies are penetrating Asia Pacific food chains, while regulatory pressure on virgin resin intensifies converter investment in chemical recycling and mono-material design.
Mono-material polyethylene pouches with enhanced ethylene-vinyl alcohol barrier layers are expanding into Japanese retort seafood and ready-meal segments. Major trading houses in Tokyo and Osaka are specifying these structures for private-label shelf-stable lines. The technology is expanding into premium applications previously dominated by multilayer aluminum-laminate formats that lack mechanical recyclability.
China's SAMR enforcement of GB 4806.7-2016 food-contact plastic standards is compelling converters to document additive migration limits through third-party laboratory certification. Industrial consequence includes disqualification of legacy antioxidant packages in high-temperature filling applications. Malaysian and Thai exporters to mainland China are restructuring compound procurement to secure pre-certified masterbatch supply.
Brand-owner procurement teams in Australia's supermarket sector are consolidating flexible film purchasing through direct mill relationships, bypassing traditional distributor networks. This channel compression concentrates volume with converters capable of ISO 22000 food safety certification and real-time production data sharing. The pattern is most visible in Sydney and Melbourne metropolitan supply chains serving private-label snack and bakery accounts.
Asia Pacific Plastic Packaging Market Segmentation
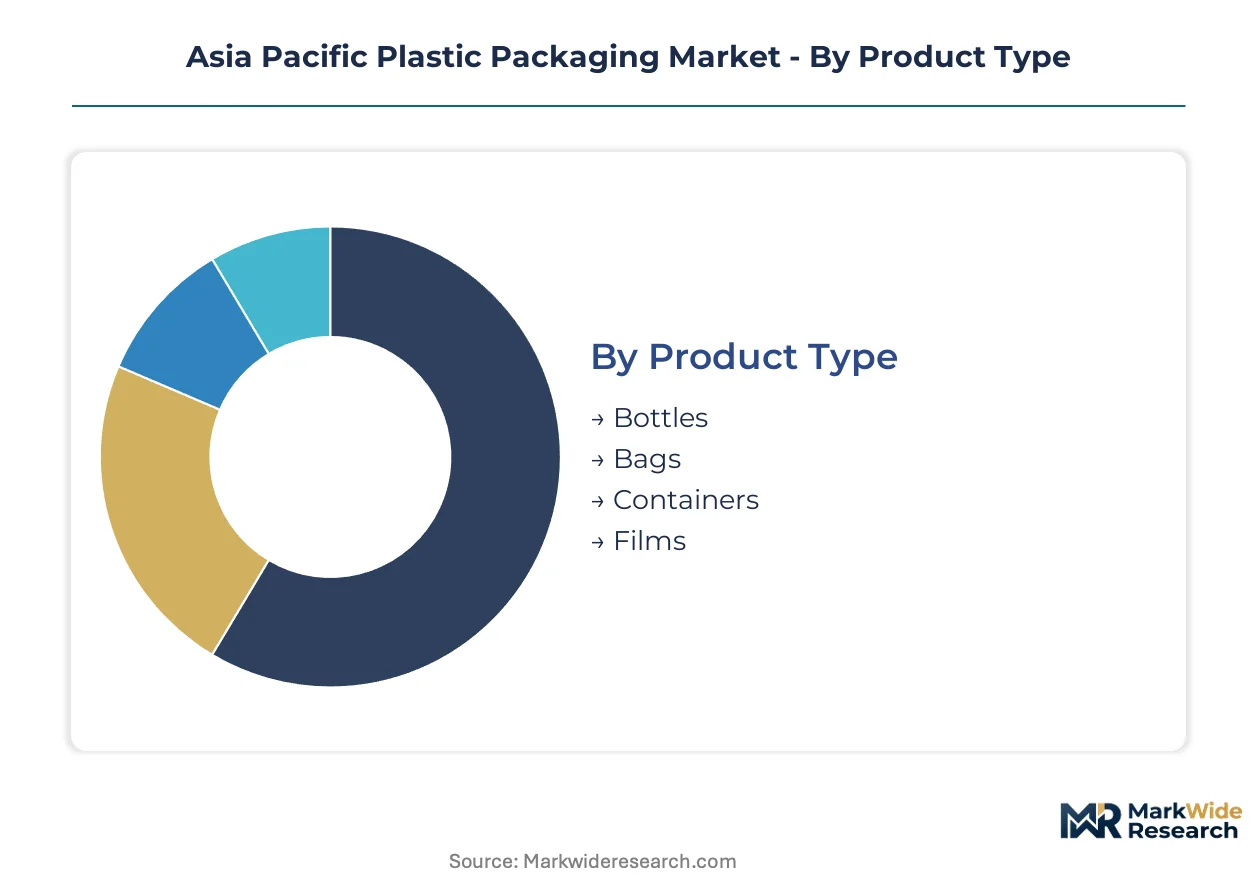
Asia Pacific plastic packaging segments diverge sharply by resin specification and barrier engineering. Food-grade recycled flake qualification timelines and dual carbon compliance are forcing converters to align product portfolios with material availability rather than virgin resin economics alone.
Product Type:
Structural design determines processing method and recyclability pathway across converter operations.
- Films:Extruded polyethylene and polypropylene sheets ranging from twelve to two hundred microns serve snack wrapping and fresh-produce preservation. Indonesia's FMCG corridor around Jakarta drives volume concentration as processors expand shelf-stable packaging purchases.
- Bottles:Stretch blow-molded PET structures with carbonation retention specifications capture premium beverage accounts. Thailand's FDA-equivalent food-contact approvals for mechanically recycled flake are unlocking rigid container substitution across ASEAN bottling lines.
- Bags:Heat-sealed polyethylene carry structures face India's BIS-mandated ISI certification requirements under environmental quality orders.
- Containers:Thermoformed polypropylene and polyethylene tubs serve dairy and ready-meal segments with retort compatibility specifications.
Mature deployment sits with Films. Newer deployment is concentrated in Bottles as rPET flake qualification expands.
Application:
End-use validation requirements create margin stratification across segment economics.
- Food & Beverage:Barrier-engineered structures for shelf-stable and fresh-produce wrapping command the largest throughput volume. China's SAMR enforces GB 4806.7-2016 migration testing that extends qualification cycles by eight to fourteen months for recycled-content plastics.
- Healthcare:Blister packs and vial systems demand cleanroom-certified thermoforming with CDSCO validation in India. Validation and documentation requirements carry superior margin profiles compared to commodity segments.
- Personal Care:Pump dispensers and tubes utilize polypropylene and polyethylene with aesthetic clarity specifications.
- Household:Industrial bagging applications persist where paper barrier limitations drive kraft-plastic hybrid adoption.
Food & Beverage anchors volume concentration. Healthcare represents the fastest-growing margin expansion trajectory.
Material:
Resin selection determines recycling pathway compatibility and regulatory exposure under extended producer responsibility schemes.
- Polyethylene:Linear low-density and high-density grades dominate flexible film extrusion for snack and produce wrapping. Post-consumer bale supply fragmentation across Indonesian islands creates input cost instability for domestic compounders.
- PET:Food-grade recycled flake substitution is realigning rigid container economics as converters migrate from virgin grades. Japan's METI circular economy guidelines pressure brand owners to verify recycled content claims through mass-balance documentation.
- Polypropylene:Oriented and cast film structures serve retort and microwaveable applications with temperature resistance specifications.
- PVC:Blister packaging and medical applications persist despite regulatory pressure on chlorine-containing resins in certain jurisdictions.
Polyethylene holds mature volume concentration. PET is gaining share fastest as food-contact flake qualification expands regionally.
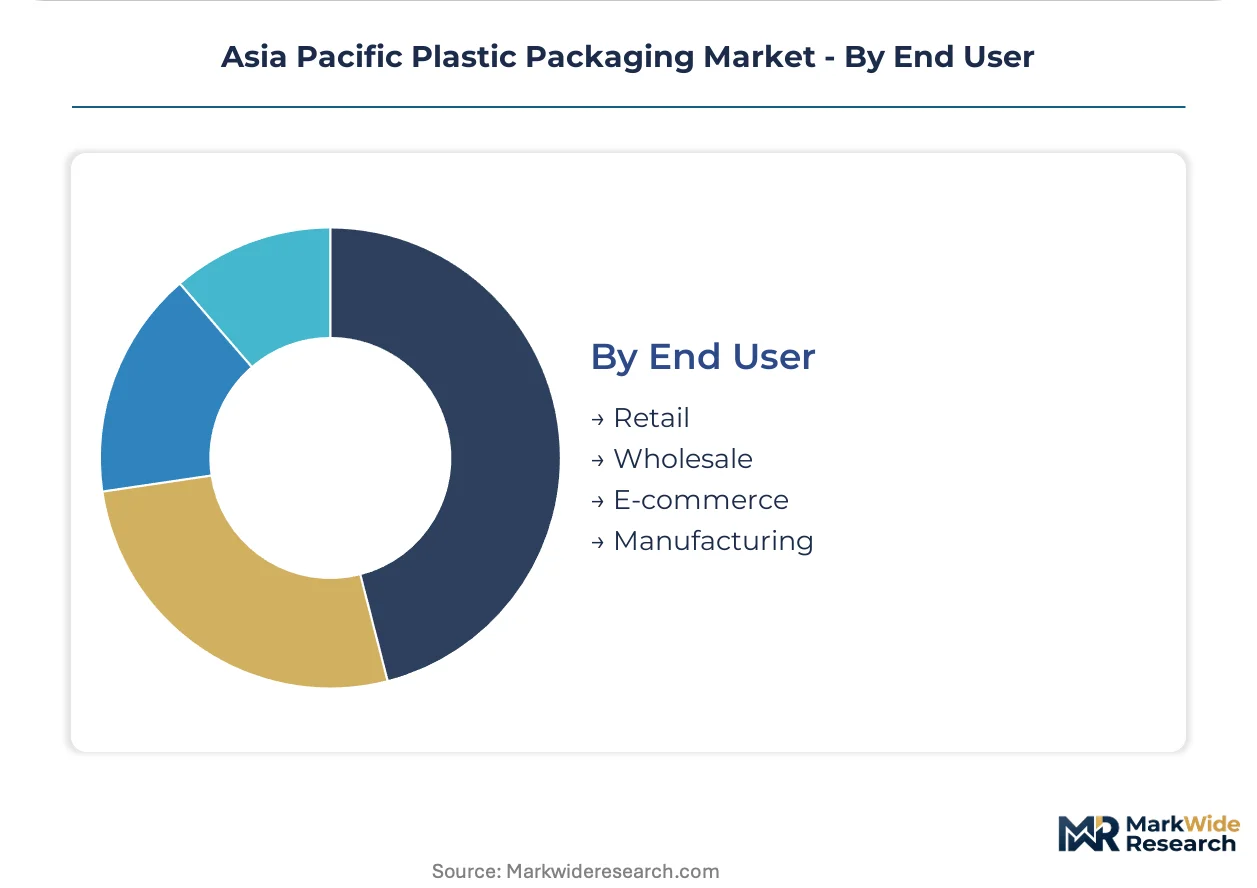
End User:
Channel structure determines certification requirements and data-sharing obligations in procurement relationships.
- Retail:Australia's supermarket sector is consolidating flexible film purchasing through direct mill relationships, bypassing traditional distributor networks. ISO 22000 food safety certification and real-time production data sharing are mandatory for volume concentration.
- E-commerce:Protective mailer and void-fill demand is expanding with fulfillment center density across Southeast Asian urban corridors.
- Wholesale:Industrial bagging and bulk container specifications prioritize unitization efficiency over aesthetic properties.
- Manufacturing:Component packaging for automotive and electronics supply chains demands static-control and precision-fit specifications.
Retail commands mature procurement consolidation. E-commerce shows the steepest expansion trajectory with fulfillment infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's fast-moving consumer goods corridor around Jakarta concentrates polyethylene film demand as processors expand shelf-stable packaging purchases for snack and fresh-produce applications.
China
SAMR enforces GB 4806.7-2016 migration testing standards that extend qualification cycles for recycled-content plastics by eight to fourteen months. The dual carbon goals pressure converters to document additive limits through third-party laboratory certification. Yangtze River Delta converters are restructuring compound procurement to secure pre-certified masterbatch supply for mainland market access.
India
BIS mandates ISI certification for polyethylene carry bags under environmental quality orders while CDSCO regulations create margin-rich demand for cleanroom-certified thermoforming in medical device packaging. Maharashtra and Gujarat host the dominant flexible film export infrastructure serving African and Middle Eastern markets. Domestic compounders face input cost instability from post-consumer bale supply fragmentation.
Japan
METI circular economy guidelines pressure brand owners to verify recycled content claims through mass-balance documentation. Mono-material polyethylene pouches with enhanced barrier layers are expanding into retort seafood and ready-meal segments previously dominated by aluminum-laminate formats. Kanto region trading houses specify these structures for private-label shelf-stable lines.
Thailand
FDA-equivalent food-contact approvals for mechanically recycled polyethylene terephthalate are unlocking rigid container substitution across ASEAN beverage bottling operations. Bangkok-based processors leverage integrated recycling infrastructure to secure flake supply for brand-owner procurement teams. Legacy extrusion line retrofit costs for high-percentage recycled blends challenge mid-tier operators seeking capital.
Vietnam
Extended producer responsibility schemes are altering collection economics for domestic reprocessors considering compounding investments. Da Nang and Hue industrial zones lack integrated flexographic printing and slitting capacity for regional snack distributors. Central province underpenetration creates strategic whitespace for converters with ISO 22000 food safety certification.
Asia Pacific Plastic Packaging Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding premium beverage and healthcare accounts while regional compounders serve commodity flexible film demand. The vendor base organizes around three archetypes: integrated recycling-converter hybrids, pure-play flexible film exporters, and rigid container specialists with flake qualification capabilities. Competitive moves concentrate on backward integration into recycling infrastructure and geographic expansion into underpenetrated ASEAN provinces.
Within the integrated recycling tier, Amcor plc and Mondi plc occupy positions that exemplify the converter-archetype with captive flake supply chains. UFlex Limited anchors the flexible film export specialist category. These three entities represent distinct strategic postures: Australian-Thai integrated infrastructure, European kraft-plastic hybrid industrial positioning, and Indian-African-Middle Eastern trade corridor dominance respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi plc |
| Sonoco Products Company |
| Berry Global Group Inc |
| Sealed Air Corporation |
| DS Smith PLC |
| UFlex Limited |
| SCG Packaging |
| Huhtamaki India Ltd |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate both qualified recycled flake supply and premium-tier pricing access for converters seeking mainland market entry, compressing virgin polyethylene margins while rewarding mass-balance-certified producers with procurement preference from Japanese trading houses.
Pricing Analysis
Volume concentrates in commodity polyethylene films serving Jakarta's FMCG corridor, while margin expansion sits with healthcare blister packs and food-grade rPET rigid containers. Pricing stratifies across premium, standard, and economy tiers based on ISO 22000 certification status and real-time production data-sharing capability. Cost compression in standard-grade flexible film is intensifying because Australia's supermarket sector bypasses distributors for direct mill relationships. Brand-owner procurement teams show lowest price sensitivity in healthcare validation services, while snack distributors in Vietnam's central provinces remain most price-sensitive.
Supply Chain Analysis
Post-consumer bale supply rests on fragmented collection networks across Indonesian islands, Thai FDA-equivalent approved reprocessors, and Australian integrated recycling infrastructure. Virgin resin draws from Middle Eastern petrochemical feedstock, Southeast Asian naphtha crackers, and Indian domestic polymer production. Single-source vulnerability concentrates in mechanically recycled flake qualification capabilities. Distribution runs through brand-anchored collection networks mobilized under Indonesia's EPR schemes and direct mill relationships consolidated by Australian retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where converters pursue backward control over recycling infrastructure to secure flake supply and mass-balance certification capability.
For Market Incumbents: Deploy captive recycling infrastructure across Thailand and Australia to lock in post-consumer feedstock before EPR schemes alter collection economics. Amcor plc's integrated model demonstrates how flake supply security defends against virgin resin price volatility. Accelerate ISO 22000 certification and real-time data-sharing protocols to meet Australian supermarket direct procurement requirements. For New Entrants and Emerging Players: Enter via Vietnam's Da Nang and Hue industrial zones where flexographic printing and slitting capacity gaps persist for regional snack distributors. Target healthcare blister pack validation services in India where CDSCO regulations create margin-rich demand exceeding commodity film economics. Pursue joint ventures with established compounders to bypass legacy extrusion line retrofit capital barriers. For Investors and Strategic Acquirers: Thailand's FDA-equivalent food-contact approvals for mechanically recycled PET is the leading indicator that rigid container substitution will accelerate across ASEAN bottling lines. Five-to-ten-year viability favors converters with integrated recycling-converter hybrid architectures over pure-play flexible film exporters. Watch for mass-balance accounting skill scarcity as Japan's METI guidelines tighten verification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Secures post-consumer flake supply under Indonesia's EPR collection networks. |
| Food-Grade rPET Flake Qualification | Unlocks rigid container substitution in ASEAN beverage bottling per Thai FDA-equivalent approvals. |
| ISO 22000 Certification Investment | Enables direct mill relationships with Australia's supermarket procurement consolidation. |
| Healthcare Validation Service Expansion | Captures margin-rich demand under India's CDSCO medical device packaging regulations. |
| Digital Watermark-Sorting Infrastructure | Supports Japanese brand-owner compliance verification through near-infrared detection and blockchain traceability. |
Study Parameters
Document review covered customs and trade data, BIS environmental quality orders, SAMR GB standard filings, and METI circular economy guidelines, complemented by interviews with plant managers at Thai and Indonesian converters, procurement leads at Australian supermarket chains, regulatory affairs specialists navigating China's migration testing protocols, and technical R&D directors at flexible film exporters. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the Asia Pacific region.
Historical shipment data cross-referenced against expert panel input on EPR scheme implementation timelines and food-contact qualification trajectories. Segmentation dimensions included product type, application, material specification, and end-user channel structure. CAGRs derived from regression analysis of resin throughput trends and substitution elasticity estimates for recycled-content adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPR enforcement acceleration or biodegradable polymer substitution breakthroughs in Japanese retail applications. A small set of named triggers—including Thailand's flake approval expansion, Vietnam's central province industrial policy, and Australia's distributor bypass momentum—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Cast Films Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
HDPE Jug Market