
 PLA Cup Market | 2026-2036
PLA Cup Market Size, Share, and Industry Trends Forecast 2026-2036
PLA Cup Market Analytics
Food-grade compostable certification is unwinding price resistance among institutional buyers. Eco-Products, Inc. leverages its captive distribution through broadline foodservice channels to sustain volume leadership in North America. Novolex anchors its position through backward integration into resin sourcing, while Biopac Ltd competes on European private-label partnerships with quick-service restaurant chains.
Polylactic acid cups are thermoformed or injection-molded vessels derived from fermented plant starch, typically corn or sugarcane, designed to degrade under industrial composting conditions within 90 to 180 days. Disposable cups dominate current production volumes, though compostable variants command premium placement in regulated municipalities where ASTM D6400 or EN 13432 certification gates market access. Food service leads end-user consumption, while leak-proof feature specifications are concentrating margin pools among specialty converters serving drive-through and mobile beverage formats.
The FDA regulates food-contact substances for PLA cups in the United States, while the EU's Packaging and Packaging Waste Regulation alongside EN 13432 compostability standards shapes product design and disposal labeling across European markets. California's SB 54 extended producer responsibility framework and New York's foam ban enforcement are tightening compliance thresholds for non-certified alternatives. Stakeholders must monitor composting infrastructure buildout timelines against certification requirements to avoid stranded inventory in jurisdictions where industrial composting remains unavailable.
Market Dynamics
Single-use plastic bans across North America and Europe are forcing food service chains into rapid material substitution, creating a structural pull for certified compostable alternatives that outpaces available industrial composting infrastructure.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates material transition across member states, creating guaranteed demand pools for certified alternatives in quick-service restaurant chains.
- Municipal composting infrastructure:Cities in California, New York, and Washington are building industrial composting facilities that validate PLA cup disposal pathways.
- Corporate sustainability pledges:Food service operators are embedding compostable packaging into net-zero commitments ahead of regulatory deadlines.
Market Restraints
- Corn starch price volatility:Fermentation feedstock costs fluctuate with agricultural commodity cycles, squeezing converter margins during drought periods.
- Industrial composting availability:Limited facility coverage in the American Midwest and Southern states creates geographic demand ceilings.
- Polypropylene substitution:Conventional plastic cups retain cost advantages in unregulated jurisdictions, slowing uniform adoption.
Strategic Opportunities
- Extended producer responsibility frameworks:California's SB 54 creates compliance-driven procurement pools for certified suppliers.
- Drive-through beverage formats:Leak-proof PLA cup specifications are opening premium margin tiers among specialty converters.
- Sugarcane feedstock expansion:Thai and Brazilian agricultural processors are developing dedicated PLA resin supply chains.
Industry Challenges
- ASTM D6400 certification timelines:Third-party testing and validation cycles extend product launch windows by six to nine months.
- Composting facility integration:Mismatches between cup certification standards and local composting operational parameters create stranded inventory risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PLA Cup Market |
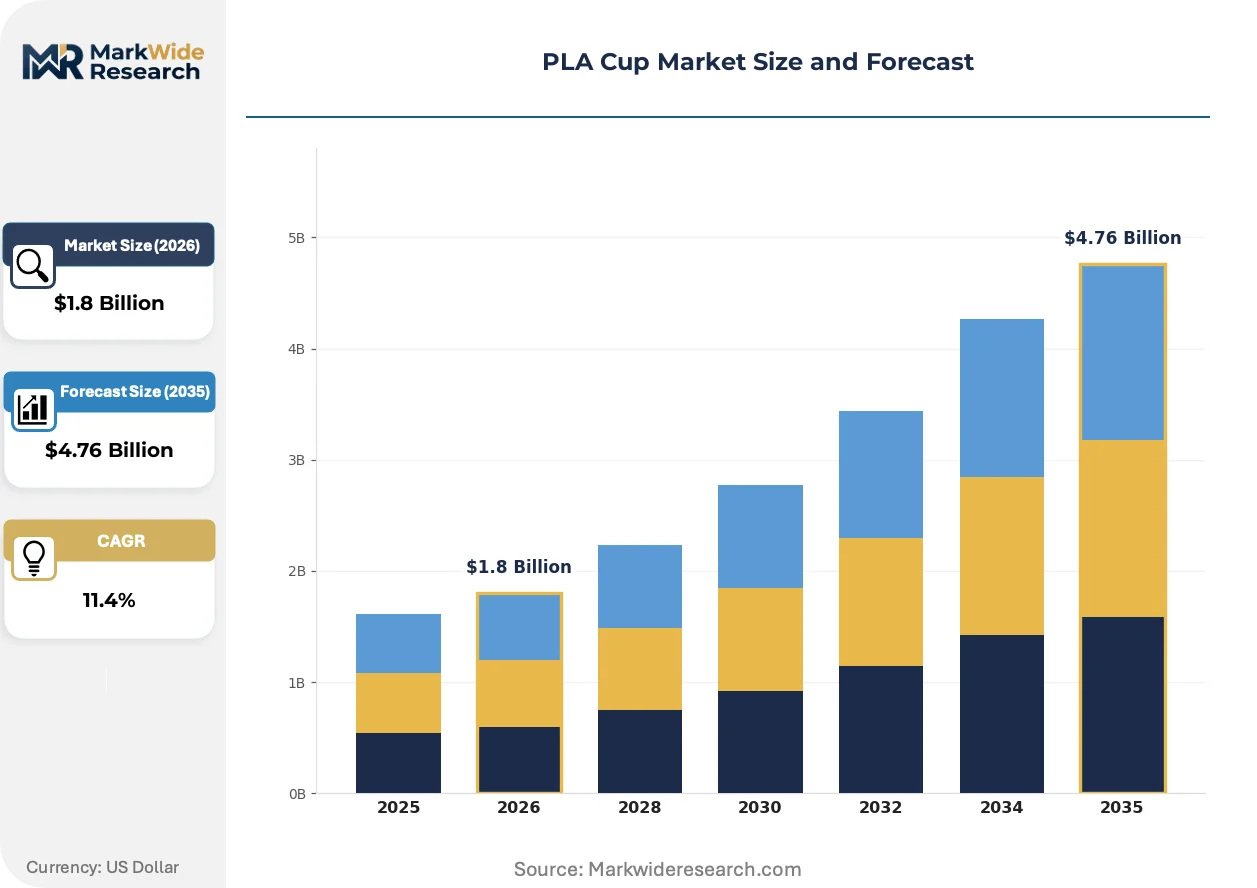
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Cups, Reusable Cups, Biodegradable Cups, Compostable Cups End User: Food Service, Retail, Event Management, Bulk Purchasing Size: Small, Medium, Large, Extra Large Feature: Leak-Proof, Insulated, Printed Designs, Customizable |
| Companies Covered | Biopac Ltd, Eco-Products, Inc., Green Paper Products, Avani Eco Hub, Dart Container Corporation, Pactiv LLC, Novolex, Celebration Paper & Plastics Ltd., Betterearth Llc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PLA Cup Market Evolving Landscape
Material science advances and regulatory precision are compressing the gap between bioplastic performance and conventional plastic economics, reshaping how converters design for both compliance and functionality.
High-heat PLA formulations are decomposing the temperature limitations that previously restricted hot beverage applications. Coffee chains in the Pacific Northwest are piloting these variants for espresso-based drinks. This thermal performance expansion is decomposing the cold-beverage-only market boundary that has constrained PLA cup penetration.
California's SB 54 extended producer responsibility framework is mandating source reduction and recyclability targets that PLA cups satisfy through industrial composting pathways. Brand owners are redesigning packaging portfolios to meet these thresholds. Quick-service restaurant procurement teams in Los Angeles and San Francisco are prioritizing ASTM D6400-certified suppliers to ensure compliance.
Direct procurement from resin converters is consolidating buyer power among large food service chains. Broadline distributors are losing volume share as institutional buyers establish captive supply relationships. This disintermediation is most visible in the United States, where Aramark and Compass Group are building dedicated bioplastic supply chains.
PLA Cup Market Segmentation
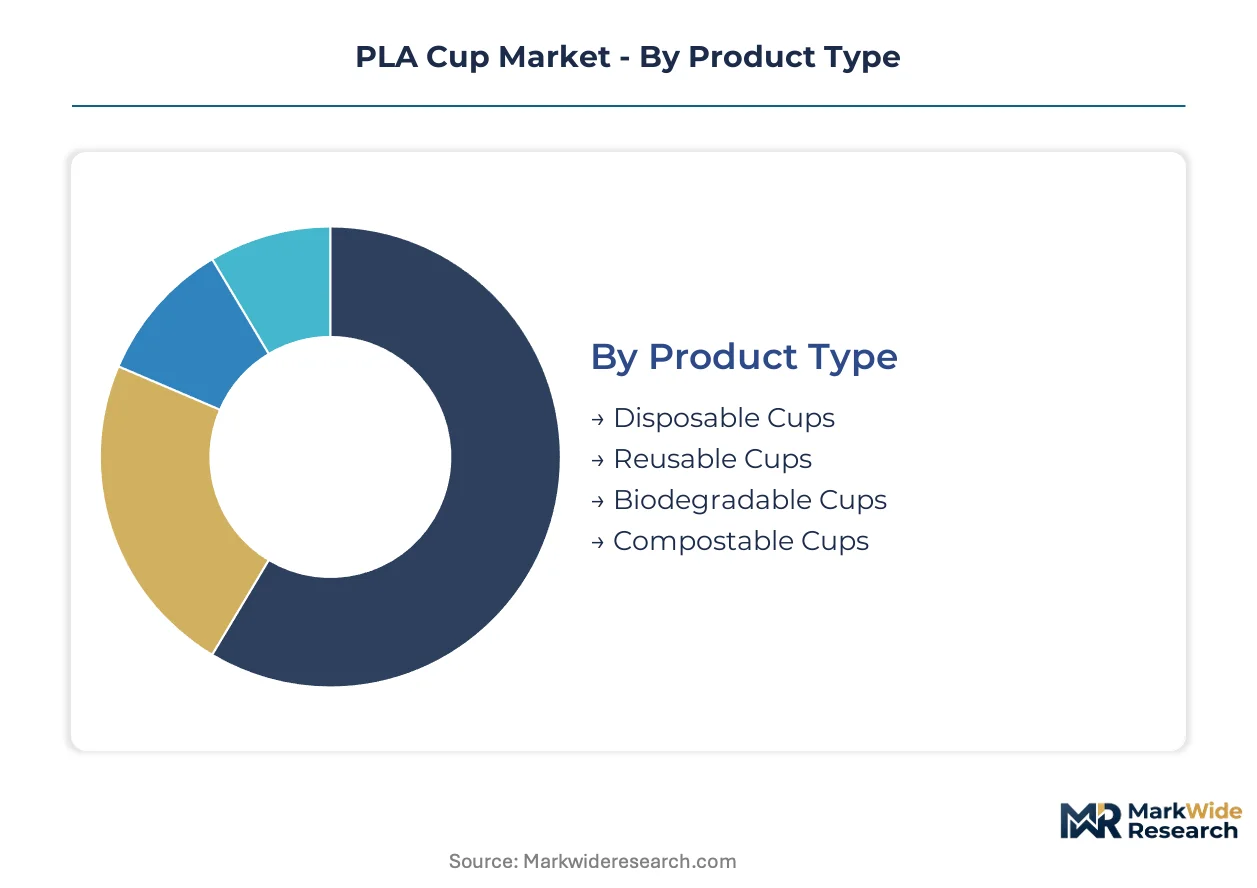
PLA cup segmentation reveals how certification tiers, end-use specifications, and format requirements partition margin pools across converter portfolios. Product certification levels and feature complexity determine pricing power, while end-user scale concentrates volume leverage among institutional buyers.
Product Type:
Margin pools concentrate in certified compostable grades where ASTM D6400 and EN 13432 compliance gates access to regulated municipal markets and corporate sustainability procurement.
- Disposable Cups:Thermoformed single-use vessels dominate current production volumes, with demand clustering in quick-service restaurant chains across California and New York where single-use plastic bans mandate material substitution. Corn starch price volatility squeezes converter margins during agricultural commodity cycles.
- Compostable Cups:Certified variants meeting industrial composting standards command premium placement in jurisdictions with operational facilities. Food-grade compostable certification is unwinding price resistance among institutional buyers in Seattle, San Francisco, and Portland.
- Reusable Cups:Durable PLA formulations target closed-loop beverage programs in corporate campuses and university dining services.
- Biodegradable Cups:Uncertified variants compete in price-sensitive segments where composting infrastructure remains undeveloped.
Disposable cups hold installed capacity. Compostable cups are rotating up the share rankings.
End User:
Volume concentration follows procurement scale, with food service operators leveraging sustainability commitments to consolidate supplier relationships.
- Food Service:Quick-service restaurants, cafeterias, and catering operations generate the dominant share of demand, with leak-proof specifications opening premium margin tiers among specialty converters serving drive-through formats. Municipal composting infrastructure buildout in California and Washington validates disposal pathways.
- Bulk Purchasing:Institutional buyers including Aramark and Compass Group are establishing captive bioplastic supply chains, disintermediating broadline distributors. Direct procurement from resin converters is consolidating buyer power among large food service chains.
- Retail:Grocery and convenience store channels stock PLA cups for consumer resale in regulated municipalities.
- Event Management:Stadiums, festivals, and convention centers adopt compostable formats to meet temporary venue sustainability mandates.
Food service commands volume leadership. Bulk purchasing is climbing the fastest.
Size:
Format segmentation tracks beverage category standardization, with medium and large sizes capturing coffee and fountain drink specifications.
- Medium:12-16 ounce formats align with specialty coffee serving standards, concentrating demand in Pacific Northwest espresso chains piloting high-heat PLA formulations.
- Large:20-24 ounce vessels match fountain beverage specifications at quick-service restaurants, with insulated variants addressing iced drink applications.
- Small:8-10 ounce formats serve espresso shots and children's portions in regulated school districts.
- Extra Large:32+ ounce vessels target convenience store fountain programs and movie theater concessions.
Medium holds format standardization. Large is expanding most quickly.
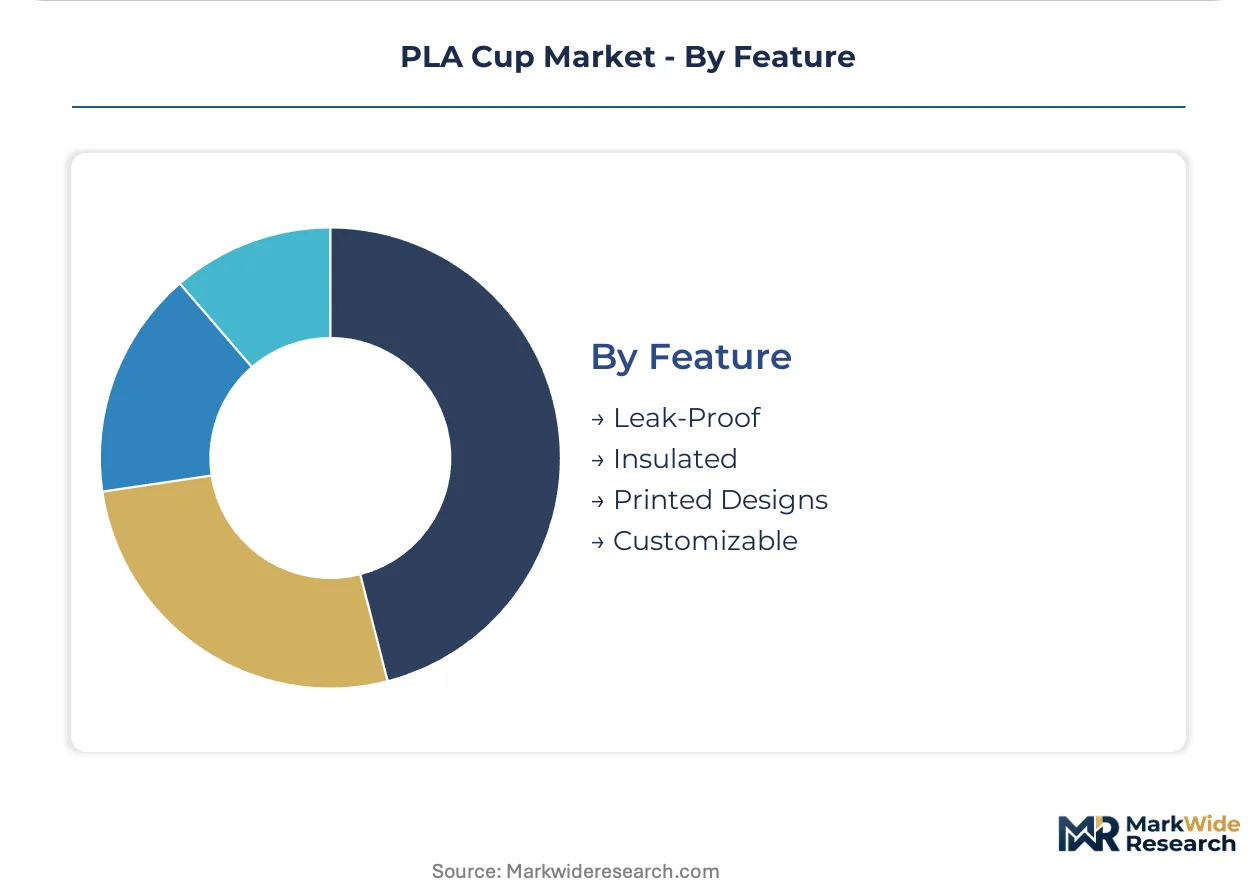
Feature:
Performance specifications differentiate commodity converters from specialty suppliers, with leak-proof engineering capturing drive-through application premiums.
- Leak-Proof:Engineered rim and base seals prevent beverage seepage during vehicle transport, opening margin pools among converters serving mobile beverage formats. Quick-service restaurant procurement teams specify these variants for drive-through and delivery applications.
- Insulated:Double-wall or foam-core constructions address temperature retention for hot and iced beverages, with demand concentrating in coffee chain portfolios.
- Printed Designs:Brand-customized graphics support marketing requirements for limited-time beverage promotions.
- Customizable:Blank stock formats enable end-user labeling and regional co-branding programs.
Leak-proof holds performance premium positioning. Insulated is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai agricultural processors export PLA resin to converters across the United States and Germany, establishing a critical feedstock corridor that feeds manufacturing clusters in California and Bavaria. This trade flow anchors the material supply base for food service chains navigating single-use plastic bans.
United States
California and New York municipal composting buildouts validate disposal pathways for certified cups. The FDA regulates food-contact substances while state-level mandates like California's SB 54 tighten compliance thresholds. Seattle and San Francisco procurement teams prioritize ASTM D6400-certified suppliers for institutional food service contracts.
Germany
Quick-service restaurant chains source EN 13432-certified alternatives to satisfy EU Single-Use Plastics Directive mandates. The country's national packaging regulator enforces strict labeling requirements for compostability claims. Bavarian converters supply private-label programs for Central European beverage chains.
Thailand
Sugarcane processors develop dedicated fermentation feedstock supply chains for PLA resin export markets. The country's agricultural ministry supports bioplastic feedstock cultivation through dedicated crop programs. Bangkok-area processors ship resin to converters in California and Germany.
France
Café chains in Paris and Lyon pilot high-heat PLA formulations for espresso-based drinks. The national environmental agency enforces extended producer responsibility frameworks for food service packaging. Île-de-France procurement clusters concentrate demand among institutional buyers.
United Kingdom
Quick-service operators replace conventional plastic ahead of national single-use plastic restrictions. The Environment Agency coordinates composting infrastructure standards with local waste authorities. London metropolitan area food service chains consolidate supplier relationships around certified converters.
PLA Cup Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and distribution channels, producing a bifurcated structure where scale-driven converters battle regional fabricators for municipal procurement contracts. The vendor base segments into three archetypes: broadline distributors with captive food service relationships, resin-integrated converters controlling upstream feedstock, and private-label specialists serving quick-service restaurant chains. Capacity expansion and backward integration into resin sourcing represent the dominant competitive moves as converters seek margin protection against agricultural commodity volatility.
Among North American distributors, Eco-Products, Inc. and Novolex occupy positions exemplifying the scale-driven archetype, while Biopac Ltd represents European private-label specialization for quick-service chains. These three anchors illustrate how geographic concentration and certification depth separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Biopac Ltd |
| Eco-Products, Inc. |
| Green Paper Products |
| Avani Eco Hub |
| Dart Container Corporation |
| Pactiv LLC |
| Novolex |
| Celebration Paper & Plastics Ltd. |
| Betterearth Llc |
| Others |
Value Network & Pricing Analysis
Corn starch displacement by sugarcane feedstock is redrawing procurement geography and compressing resin cost differentials between Thai processors and Midwest agricultural suppliers. This feedstock migration simultaneously weakens price anchoring to US commodity futures and exposes converters to Brazilian Real volatility.
Pricing Analysis
Standard-grade PLA resin pricing diverges sharply from next-generation high-heat formulations and prior-generation uncertified bioplastics. Three-tier pricing structure across ASTM D6400-certified premium, food-grade standard, and uncertified economy levels reflects certification investment recovery timelines. Pricing pressure stems from polypropylene substitution in unregulated jurisdictions where conventional plastic retains cost advantages. Quick-service restaurant chains exhibit lowest price sensitivity due to compliance mandates, while independent cafeterias face acute margin compression.
Supply Chain Analysis
Inventory cycles extending to twelve weeks signal resin converter capacity constraints ahead of seasonal food service procurement surges. Supply concentrates in Thailand, the United States, and Germany, with Bangkok-area processors feeding California thermoforming clusters. Raw material dependencies center on fermented plant starch, fermentation catalysts, and colorant masterbatches. Single-source vulnerability runs through Thai sugarcane processors controlling dedicated PLA resin export channels. Distribution runs through broadline foodservice distributors, though direct procurement from resin converters is accelerating among institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from agricultural commodity cyclicality as drought-induced corn price spikes moderate and sugarcane feedstock alternatives mature. The cyclical driver is normalized fermentation input costs restoring converter margins.
For Market Incumbents: Compound certification depth by securing EN 13432 and ASTM D6400 dual compliance ahead of EU Packaging and Packaging Waste Regulation enforcement waves. Extend backward integration into Thai or Brazilian resin sourcing to neutralize agricultural commodity volatility. Channel control through captive broadline distributor relationships defends against disintermediation by institutional buyers building direct supply chains. For New Entrants and Emerging Players: Geographic service-layer gaps in the American Midwest and Southern states where industrial composting infrastructure remains underdeveloped present white-space opportunities. Target municipal procurement contracts in secondary California markets and emerging Washington state jurisdictions where certification requirements are tightening but supplier competition remains sparse. A go-to-market angle anchored to ASTM D6400 pre-certification and rapid custom tooling turnaround penetrates quick-service restaurant pilot programs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed foodservice packaging roll-ups that acquired regional converters during prior commodity downturns. The five-to-ten year viability window hinges on industrial composting infrastructure buildout pacing against single-use plastic ban expansion. Acquisition target archetypes include European private-label specialists with EN 13432 certification depth and captive quick-service relationships. The signal to watch is California SB 54 extended producer responsibility enforcement thresholds tightening procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive Thai sugarcane supply chains insulate margins from agricultural commodity volatility. |
| Dual Certification Investment | ASTM D6400 and EN 13432 compliance gates access to California and EU municipal procurement pools. |
| High-Heat Formulation Development | Thermal performance expansion unlocks espresso-based beverage applications in Pacific Northwest coffee chains. |
| Direct Procurement Relationships | Bypassing broadline distributors captures volume share from Aramark and Compass Group captive supply chains. |
| Leak-Proof Engineering Specialization | Drive-through and delivery format specifications open premium margin tiers among mobile beverage converters. |
Research Methodology
A standing panel of foodservice procurement directors, PLA resin converter plant managers, municipal composting facility operators, and quick-service restaurant sustainability leads provided ongoing calibration throughout the study. Primary interview intelligence combined with secondary validation against FDA food-contact substance filings, EU Packaging and Packaging Waste Regulation implementation guidance, and California SB 54 compliance documentation. Customs data tracking Thai resin export flows and SEC filings from listed packaging converters anchored supply-side quantification. Bottom-up volume builds across certification tiers, end-user segments, and geographic markets triangulated against top-down spending estimates from institutional foodservice operators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type segmentation by certification grade, end-user concentration by procurement scale, size standardization by beverage category, and feature complexity by performance specification. CAGRs derived from segment-level growth rate reconciliation against macro drivers including regulatory enforcement timelines, composting infrastructure buildout schedules, and corporate sustainability pledge implementation. Industry-specific forecast inputs incorporated agricultural commodity price cycle assumptions and municipal procurement contract award patterns.
Forecasts assume regulatory continuity in EU Single-Use Plastics Directive implementation, California SB 54 enforcement, and New York foam ban expansion; material policy shifts would require re-modeling demand trajectories. Agricultural commodity volatility, industrial composting facility commissioning delays, and polypropylene cost compression represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Europe Plastic Packaging Films Market
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Poland Plastic Packaging Tubes Market