
 North America Paper Cups Market | 2026-2036
North America Paper Cups Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paper Cups Market Intelligence
Buyer concentration among quick-service chains is broadening as regional coffee cooperatives and ghost kitchen operators enter procurement pools alongside legacy fast-food giants. Huhtamaki North America leverages its integrated converting network to secure multi-year supply agreements with top-tier beverage retailers. Dart Container Corporation anchors the institutional segment through manufacturing scale that spans thermoformed and fiber-based formats. Pactiv Evergreen differentiates via refrigerated and hot-fill cup technologies that address temperature-specific performance demands.
North America paper cups are cylindrical liquid containers manufactured from bleached or unbleached Kraft pulp, typically laminated with polyethylene or bio-based barrier coatings to prevent leakage across temperature ranges from iced to near-boiling contents. The primary commercial purpose centers on sanitary, single-use beverage service in high-throughput foodservice environments where washing infrastructure is absent or cost-prohibitive. Double wall and insulated variants command premium placement in specialty café channels where hand-comfort and heat retention determine repeat purchase behavior. Biodegradable material grades are gaining fastest traction among municipal composting programs in Seattle, San Francisco, and Vancouver that reject conventional polyethylene-lined stock.
The FDA regulates food-contact substances under 21 CFR, while EPA scrutiny of per- and polyfluoroalkyl substances intensifies compliance burdens for conventional barrier coatings across U.S. manufacturing. Health Canada and PMRA coordinate parallel chemical safety assessments that influence cross-border product formulations and labeling requirements. State-level extended producer responsibility frameworks in California and Maine are forcing cup producers to internalize end-of-life collection costs. Stakeholders must monitor how municipal composting certification standards diverge between U.S. and Canadian jurisdictions before committing capital to next-generation barrier material platforms.
Market Dynamics
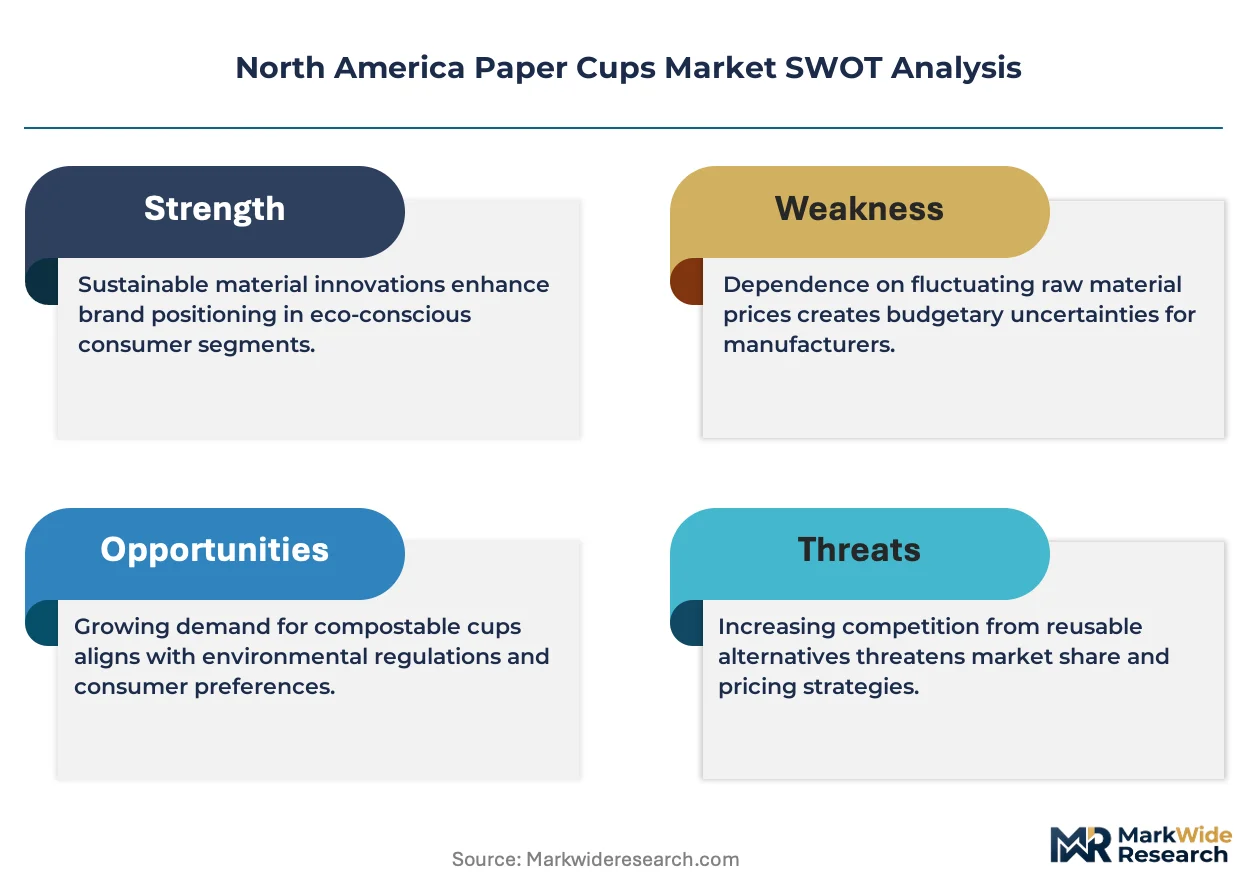
State-level PFAS bans in California and New York are forcing cup manufacturers to abandon conventional fluorinated barrier coatings faster than bio-based alternatives can achieve cost parity, compressing margin structures across the converting base.
Growth Catalysts
- Quick-service beverage expansion:Chains across the United States and Canada are scaling to-go programs, pulling container volume through dedicated supply agreements.
- Composting infrastructure maturation:Municipal programs in Seattle, San Francisco, and Vancouver now accept certified fiber cups, creating compliant end-of-life pathways that validate premium material investments.
- Polyethylene replacement mandates:Extended producer responsibility frameworks in Maine and California internalize collection costs, accelerating demand for certified biodegradable grades.
Market Restraints
- Pulp cost volatility:Kraft pulp prices fluctuate with energy and freight inputs, squeezing converter margins when long-term supply agreements lock in fixed cup pricing.
- Barrier coating performance gaps:Bio-based alternatives still fail hot-fill durability tests above 85°C, limiting deployment in specialty coffee and tea applications.
- Converter concentration in Upper Midwest:Three integrated manufacturers control the majority of North American thermoformed and fiber cup capacity, creating supply vulnerability during weather or labor disruptions.
Strategic Opportunities
- Ghost kitchen beverage programs:Delivery-only operators in Toronto, Chicago, and Austin lack established cup supply relationships, opening procurement channels outside legacy quick-service networks.
- Refrigerated cup technology convergence:Integration of moisture-resistant barriers with chilled dairy and juice applications addresses an underserved segment between hot-fill and ambient formats.
- Canadian federal single-use plastics prohibition:Health Canada enforcement creates immediate substitution demand for fiber alternatives in provinces lagging municipal composting adoption.
Industry Challenges
- Composting certification timeline compression:Biodegradable Products Institute and Cedar Grove approval cycles now exceed 18 months, delaying product launches past seasonal menu windows.
- Barrier chemistry skill scarcity:Formulation expertise in plant-based polymers and aqueous coatings concentrates among a handful of material scientists, inflating R&D compensation costs.
- Legacy polyethylene line retrofit complexity:Converting equipment designed for extrusion-coated stock requires six-figure capital outlays to handle water-based barrier coatings without throughput degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paper Cups Market |
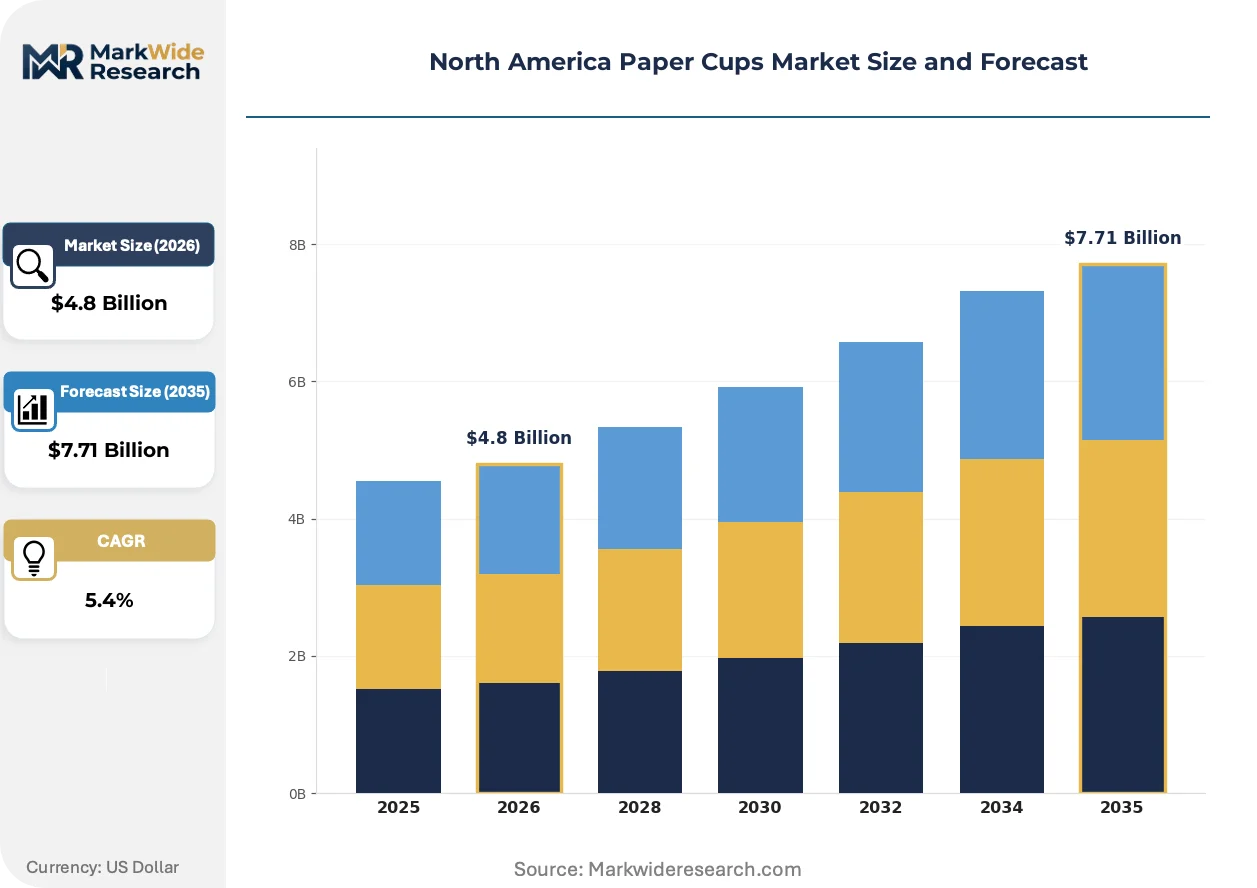
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Insulated, Biodegradable End User: Cafés, Restaurants, Fast Food Chains, Catering Services Material: Recycled Paper, New Fiber, Coated Paper, Plant-based Material Capacity: 8 oz, 12 oz, 16 oz, 20 oz |
| Companies Covered | Huhtamaki North America, WestRock Company, Dart Container Corporation, Eco-Products, Pactiv Evergreen, International Paper Company, Graphic Packaging, Karat by Lollicup, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paper Cups Market Strategic Shifts & Innovations
Barrier material chemistry and end-of-life certification standards are diverging faster than supply chains can consolidate, fragmenting procurement specifications across state and provincial boundaries.
Aqueous barrier coatings derived from polysaccharide and protein matrices are expanding into hot-fill cup applications previously reserved for polyethylene-laminated stock. Specialty café chains in Portland and Montreal are piloting these formats for espresso and black tea service. The technology is expanding into temperature performance tiers that bio-based materials had not previously penetrated, compressing the addressable market for conventional laminated constructions.
EPA scrutiny of per- and polyfluoroalkyl substances intensifies compliance burdens for manufacturers still using fluorinated grease barriers. Industrial consequence includes accelerated reformulation timelines and inventory write-downs of non-compliant stock. California quick-service operators are responding by requiring certified PFAS-free documentation in all new supply agreements, effectively pre-qualifying converters before formal procurement begins.
Regional coffee cooperatives and independent roasters are consolidating purchasing through group procurement platforms, displacing individual store-level ordering that dominated specialty channels. These platforms aggregate volume across fifty to two hundred locations, extracting tiered pricing concessions previously reserved for national chains. The shift concentrates most visibly in the U.S. Northeast corridor, where urban café density enables platform operators to achieve minimum viable scale within single metropolitan areas.
North America Paper Cups Market Segmentation
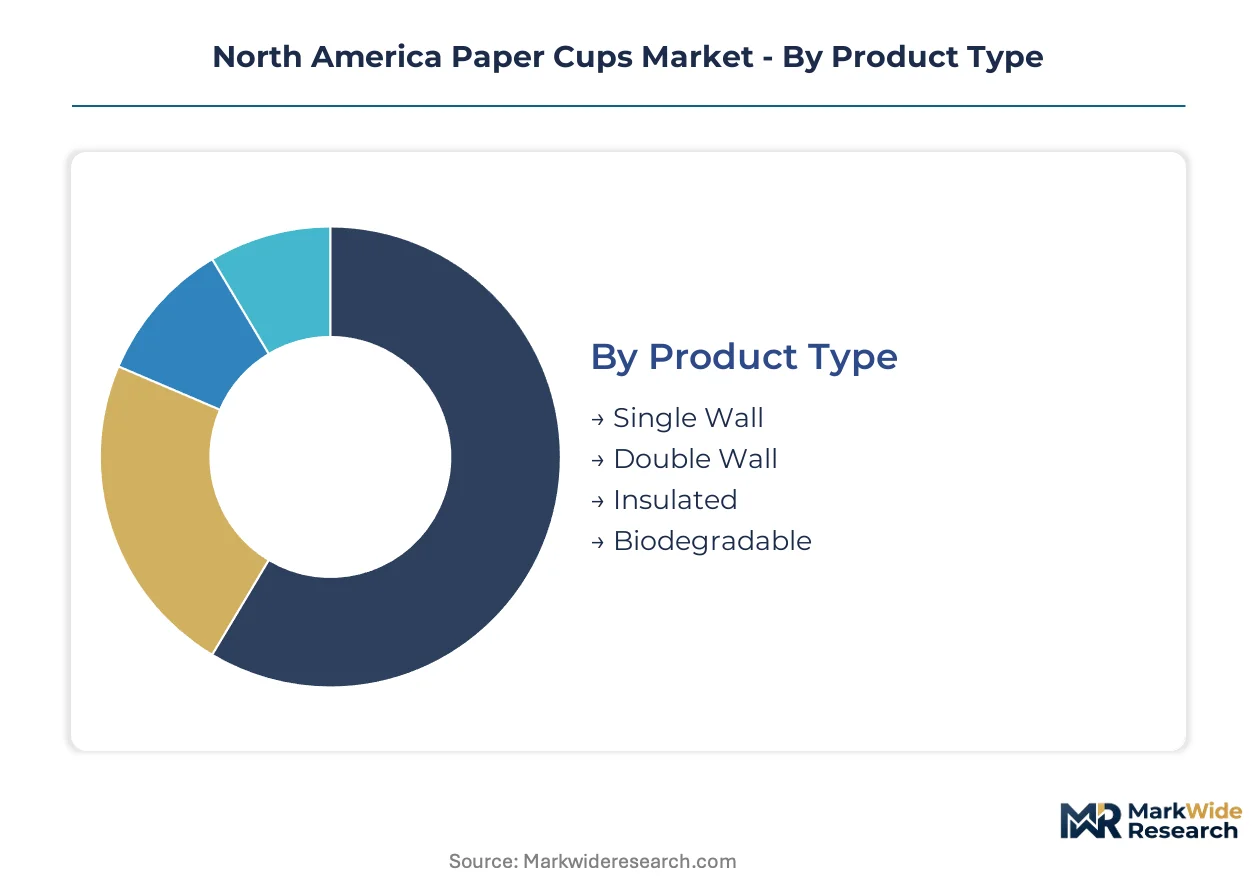
Segmentation in the North American paper cups market reveals how material choices and structural designs map directly onto regulatory compliance requirements and end-use temperature demands. Understanding these splits enables procurement alignment with municipal composting certifications and state-level PFAS restrictions.
Product Type:
Volume throughput concentrates in single-wall formats, while premium positioning and thermal performance drive double-wall and insulated adoption.
- Single Wall:Lightweight Kraft pulp construction with polyethylene or bio-based barrier coating serves ambient and cold beverages across high-throughput quick-service environments. Demand clusters in California and Texas drive-through operations where cost-per-unit sensitivity outweighs hand-comfort considerations. FDA food-contact substance compliance remains straightforward given established extrusion-coating supply chains.
- Double Wall:Dual-layer construction creates trapped air insulation that eliminates the need for separate sleeves in hot beverage service. Specialty café density in the U.S. Northeast corridor—Boston, New York, Philadelphia—pulls volume as consumers prioritize heat retention and tactile comfort during extended consumption periods.
- Insulated:Foamed or textured interlayers deliver maximum thermal performance for near-boiling contents in premium coffee and tea applications. Seattle and Portland roasters specify these formats for single-origin espresso service where temperature stability affects perceived quality.
- Biodegradable:Plant-based barrier coatings and certified compostable substrates align with municipal programs in San Francisco, Vancouver, and Seattle that reject conventional polyethylene-lined stock. Extended producer responsibility frameworks in Maine and California validate material premiums through internalized end-of-life cost structures.
Mature deployment sits with Single Wall formats across legacy quick-service networks. Newer deployment is concentrated in Biodegradable variants as state-level mandates accelerate.
End User:
Procurement scale and specification complexity separate institutional buyers from fragmented independent operators.
- Cafés:Independent and chain coffeehouses prioritize branded cup exteriors, double-wall hand comfort, and compostable certification for consumer-facing sustainability claims. Urban density in Montreal and Chicago enables group purchasing platforms that aggregate volume across fifty to two hundred locations.
- Restaurants:Full-service establishments balance cost control with beverage program differentiation, often mixing single-wall formats for water service with insulated variants for specialty coffee. Toronto's ghost kitchen operators represent emerging demand outside traditional procurement relationships.
- Fast Food Chains:National quick-service networks drive the largest container volumes through multi-year supply agreements with integrated converters. FDA compliance documentation and PFAS-free certification requirements now pre-qualify suppliers before formal procurement begins.
- Catering Services:Event-based demand concentrates in 8 oz and 12 oz single-wall formats for conference and banquet beverage service. Seasonal volume spikes around holidays and wedding seasons strain converter capacity planning.
Established procurement relationships anchor Fast Food Chains. Expanding most quickly are Catering Services as corporate event volumes recover and outdoor gathering formats persist.
Material:
Fiber sourcing and barrier chemistry determine compliance trajectories across diverging U.S. and Canadian regulatory frameworks.
- Recycled Paper:Post-consumer fiber content satisfies extended producer responsibility mandates in Maine and California while reducing Kraft pulp exposure to price volatility. FDA food-contact substance notifications require careful contaminant screening for prior-use residues.
- New Fiber:Virgin bleached or unbleached Kraft pulp delivers consistent mechanical properties and barrier coating adhesion for high-speed converting lines. Upper Midwest pulp mills supply the majority of North American cupstock production.
- Coated Paper:Polyethylene extrusion or aqueous barrier coatings prevent leakage across temperature ranges from iced to near-boiling contents. EPA scrutiny of PFAS chemistry accelerates reformulation timelines for grease-resistant variants.
- Plant-based Material:Polysaccharide and protein matrix barriers expand into hot-fill applications previously reserved for petroleum-based coatings. Portland and Montreal specialty cafés pilot these formats for espresso service above 85°C.
Conventional supply concentrates in New Fiber and Coated Paper combinations. Steepest expansion trajectory belongs to Plant-based Material as bio-based alternatives achieve hot-fill durability breakthroughs.
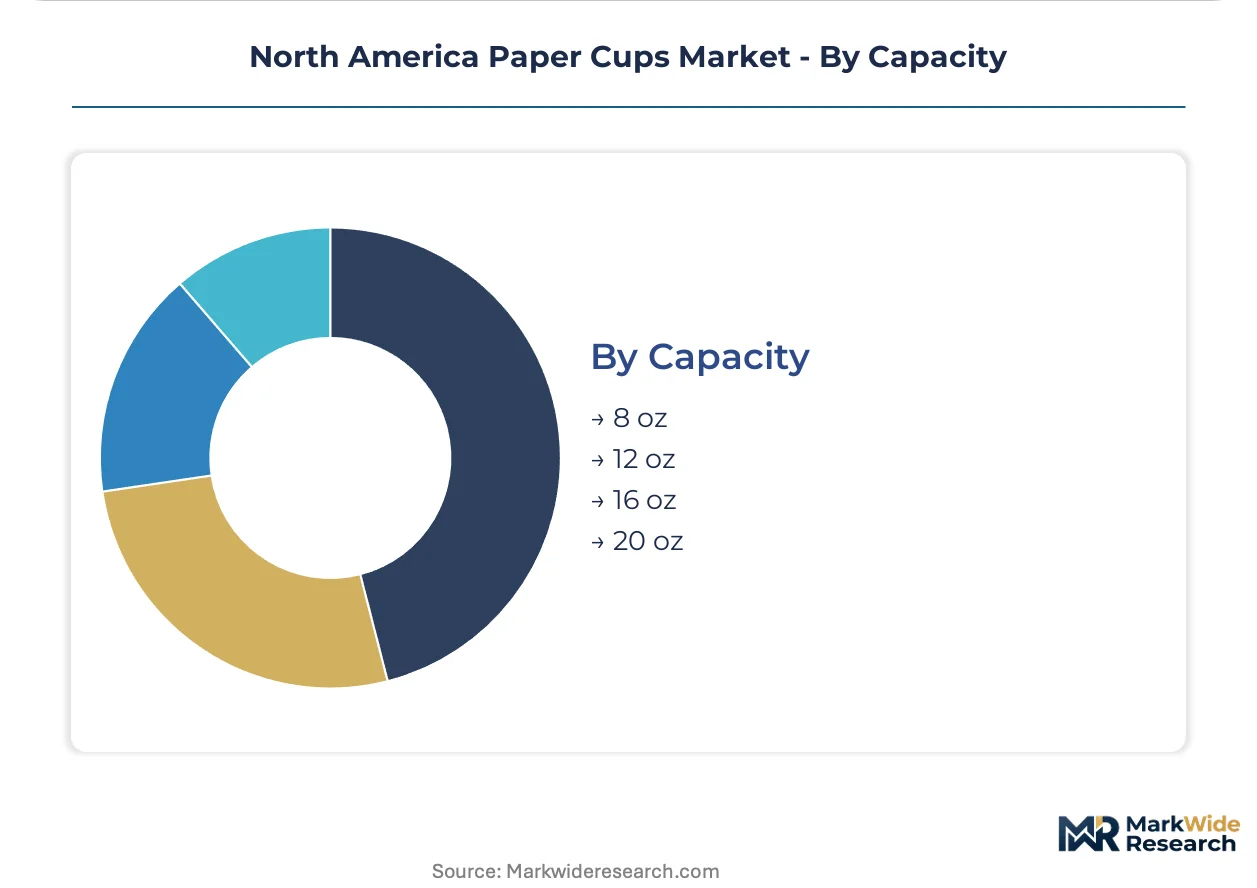
Capacity:
Format sizing maps directly onto beverage category conventions and consumption occasion patterns.
- 8 oz:Standard espresso, cortado, and children's beverage format dominates European-style café service. Smallest volume in absolute terms but highest per-unit margin given specialty positioning.
- 12 oz:Default small coffee and standard tea size across U.S. quick-service chains. Balances material cost with perceived value in value-menu beverage programs.
- 16 oz:Medium format anchors drive-through coffee and fountain soda service. Texas and Florida operations show highest per-capita consumption given climate and commute patterns.
- 20 oz:Large format for extended consumption periods and iced beverage applications where ice displacement reduces effective liquid volume. Energy drink and cold brew positioning drives premium placement.
Volume leadership sits with 16 oz across national quick-service networks. Gaining share fastest is 20 oz as iced beverage programs expand and cold brew penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service beverage programs concentrate procurement volume in the United States, while Canadian federal mandates accelerate fiber substitution. Municipal composting infrastructure and state-level chemical restrictions fragment compliance requirements across sub-regional boundaries.
United States
Drive-through coffee chains and ghost kitchen operators pull container volume through dedicated supply agreements. FDA food-contact substance regulations under 21 CFR intersect with EPA scrutiny of per- and polyfluoroalkyl substances, forcing accelerated reformulation timelines. The U.S. Northeast corridor—Boston, New York, Philadelphia—hosts the densest specialty café clustering where double-wall formats command premium placement.
Canada
Federal single-use plastics prohibition creates immediate substitution demand for fiber alternatives across provinces lagging municipal composting adoption. Health Canada and PMRA coordinate chemical safety assessments that influence cross-border product formulations. Vancouver's municipal composting program accepts certified fiber cups, validating material investments in British Columbia's Lower Mainland.
Mexico
Quick-service expansion in Mexico City and Monterrey metro areas drives container throughput for international beverage chains. Federal environmental standards under SEMARNIT establish baseline compliance frameworks without state-level fragmentation. Manufacturing clusters in Nuevo León and Jalisco supply converting capacity for regional quick-service networks.
North America Paper Cups Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and aqueous barrier technologies. Three integrated manufacturers control the majority of thermoformed and fiber cup capacity, creating tiered supply dynamics. Strategic archetypes include integrated converters with captive pulp supply, specialty material innovators, and regional distributors with group purchasing platforms. Dominant competitive moves center on multi-year supply agreement lock-ins and equipment retrofit partnerships for water-based coating compatibility.
Within the integrated converter tier, Huhtamaki North America and Dart Container Corporation exemplify scale-driven positioning across quick-service procurement channels. Pactiv Evergreen occupies a specialization anchor in temperature-specific formats. Eco-Products represents the certification-forward archetype, aligning product development with municipal composting program requirements in Seattle, San Francisco, and Vancouver.
| Leading Market Players |
|---|
| Huhtamaki North America |
| WestRock Company |
| Dart Container Corporation |
| Eco-Products |
| Pactiv Evergreen |
| International Paper Company |
| Graphic Packaging |
| Karat by Lollicup |
| Georgia-Pacific LLC |
| Others |
Cost & Logistics Intelligence
State-mandated PFAS phaseouts in California and New York are compressing converter margins as bio-based barrier coatings command material premiums before achieving cost parity with conventional fluorinated alternatives. This specification shift forces supply chains to absorb reformulation costs while locked-in quick-service contracts limit price pass-through flexibility.
Pricing Analysis
Volume leadership sits with single-wall polyethylene-lined formats at economy pricing tiers, while insulated and biodegradable variants capture premium positioning through compostable certification and thermal performance differentiation. Price differentiation hinges on BPI certification status and barrier coating chemistry grade, with FDA food-contact tier documentation adding further cost layering. Pricing pressure stems from pulp cost volatility and extended producer responsibility cost internalization in Maine and California. Fast food chains exhibit highest price sensitivity due to billion-unit procurement scale, whereas specialty cafés in Portland and Montreal absorb premiums for hand-comfort and sustainability positioning.
Supply Chain Analysis
Regional distribution centers in Wisconsin, Michigan, and Ohio anchor hub-and-spoke patterns that feed quick-service networks across the United States and Canada. Manufacturing concentrates in the Upper Midwest where integrated converters control thermoformed and fiber cup capacity. Raw material flows draw from bleached Kraft pulp mills in Wisconsin and Minnesota, polyethylene resin networks, and emerging polysaccharide barrier feedstocks. Supply chain risk centers on single-source vulnerability during Upper Midwest weather disruptions. Distribution runs through dedicated logistics partnerships with national quick-service chains and group purchasing platforms serving Northeast corridor café density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where state-level chemical mandates and composting certification barriers are forcing sub-scale converters toward exit or acquisition.
For Market Incumbents: Hedge against bio-based coating performance gaps by securing multi-year pulp supply agreements before volatility intensifies. Lock in group purchasing platform partnerships across Northeast corridor café cooperatives to defend volume share against emerging aqueous barrier specialists. Prioritize equipment retrofit partnerships for water-based coating compatibility to maintain throughput parity with legacy polyethylene lines. For New Entrants and Emerging Players: Ghost kitchen operators in Toronto, Chicago, and Austin represent an underserved buyer archetype lacking established cup supply relationships and willing to trial certified PFAS-free formats. Refrigerated cup technology convergence between hot-fill and ambient formats offers white-space positioning against incumbent temperature-specialization strategies. Lead with municipal composting certification as the go-to-market differentiator to pre-qualify for Seattle, San Francisco, and Vancouver procurement channels. For Investors and Strategic Acquirers: The window for entry favors aqueous barrier technology specialists with demonstrated hot-fill durability above 85°C and active BPI certification pipelines. Long-term viability rests on capturing share during the 5-10 year polyethylene replacement transition before incumbent retrofit investments mature. Watch for composting certification timeline compression as the inflection signal—approval cycles exceeding 18 months will strand capital in pre-revenue formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment Retrofit Partnership | Converting lines handling water-based coatings require six-figure capital outlays that incumbent converters must deploy to maintain throughput. |
| BPI Certification Acceleration | Biodegradable Products Institute approval validates municipal composting acceptance in Seattle, San Francisco, and Vancouver procurement specifications. |
| Pulp Supply Backward Integration | Captive Kraft pulp sourcing from Upper Midwest mills insulates margin structures against energy and freight input volatility. |
| Ghost Kitchen Supply Agreement | Toronto, Chicago, and Austin delivery-only operators lack legacy procurement relationships and trial PFAS-free formats. |
| Aqueous Barrier R&D Collaboration | Polysaccharide and protein matrix formulations expanding into 85°C hot-fill applications compress conventional polyethylene addressable markets. |
Research Approach
Independent corroboration across FDA food-contact substance filings, EPA PFAS regulatory dockets, and municipal composting program specifications underwrites the qualitative findings in this study. Primary interviews with quick-service procurement directors, converting plant managers, and specialty café group purchasing platform operators combined with secondary validation from Health Canada chemical safety assessments and state-level extended producer responsibility framework documents. Bottom-up volume modeling triangulates against top-down pulp consumption and converting capacity estimates.
Rate-of-change decomposition across product type, end user, material chemistry, and capacity format dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by polyethylene replacement mandate timelines and municipal composting infrastructure maturation curves. Forecast inputs incorporate barrier coating technology readiness levels and state-level PFAS restriction phaseout schedules.
Revisions become necessary when bio-based barrier coatings achieve hot-fill durability breakthroughs above 85°C at cost parity, or when municipal composting certification standards diverge between U.S. and Canadian jurisdictions. Forecasts reflect documented assumptions regarding pulp price volatility bands and quick-service contract renewal cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Global Folding Boxboards Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Paperboard Clamshell Boxes Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Corrugated Fish Box Market
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market