
 Latin America Metal Caps and Closures Market | 2026-2036
Latin America Metal Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Metal Caps and Closures Market Insights
Lightweight aluminum alloy formulations is tilting production economics toward thinner-gauge closures without sacrificing torque retention. Crown Holdings, Inc. leverages its integrated beverage-can closure platform to anchor supply contracts with major Latin American bottlers. Silgan White Cap Brasil dominates regional pharmaceutical and food closures through specialized lining-compounding capabilities. Guala Closures S.p.A. differentiates via tamper-evident and premium spirits closure designs that command positioning in Mexico's tequila and Brazil's cachaça export channels.
Metal caps and closures are precision-formed aluminum, steel, tinplate, or stainless steel sealing devices, typically manufactured through deep drawing, roll-forming, or thread-rolling processes with internal elastomeric liners, designed to create hermetic seals on rigid containers across beverage, food, pharmaceutical, and personal care applications. Aluminum closures lead volume due to recyclability alignment with Latin American extended producer responsibility frameworks, while tinplate retains share in retort-stable food applications where oxygen barrier performance is non-negotiable. Pharmaceutical-grade seals represent a concentrated margin pool as ANVISA and COFEPRIS tighten child-resistance and tamper-evidence mandates across Brazil and Mexico.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce pharmaceutical and food-contact material standards that dictate liner composition, migration limits, and closure torque specifications, effectively raising technical barriers for non-compliant imports. Brazil's National Solid Waste Policy (PNRS) and emerging state-level return schemes in São Paulo are accelerating demand for mono-material aluminum closures that simplify post-consumer sorting and recycling streams. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks, as misaligned packaging standards threaten to fragment procurement and inventory strategies across the region's two largest economic blocs.
Market Dynamics
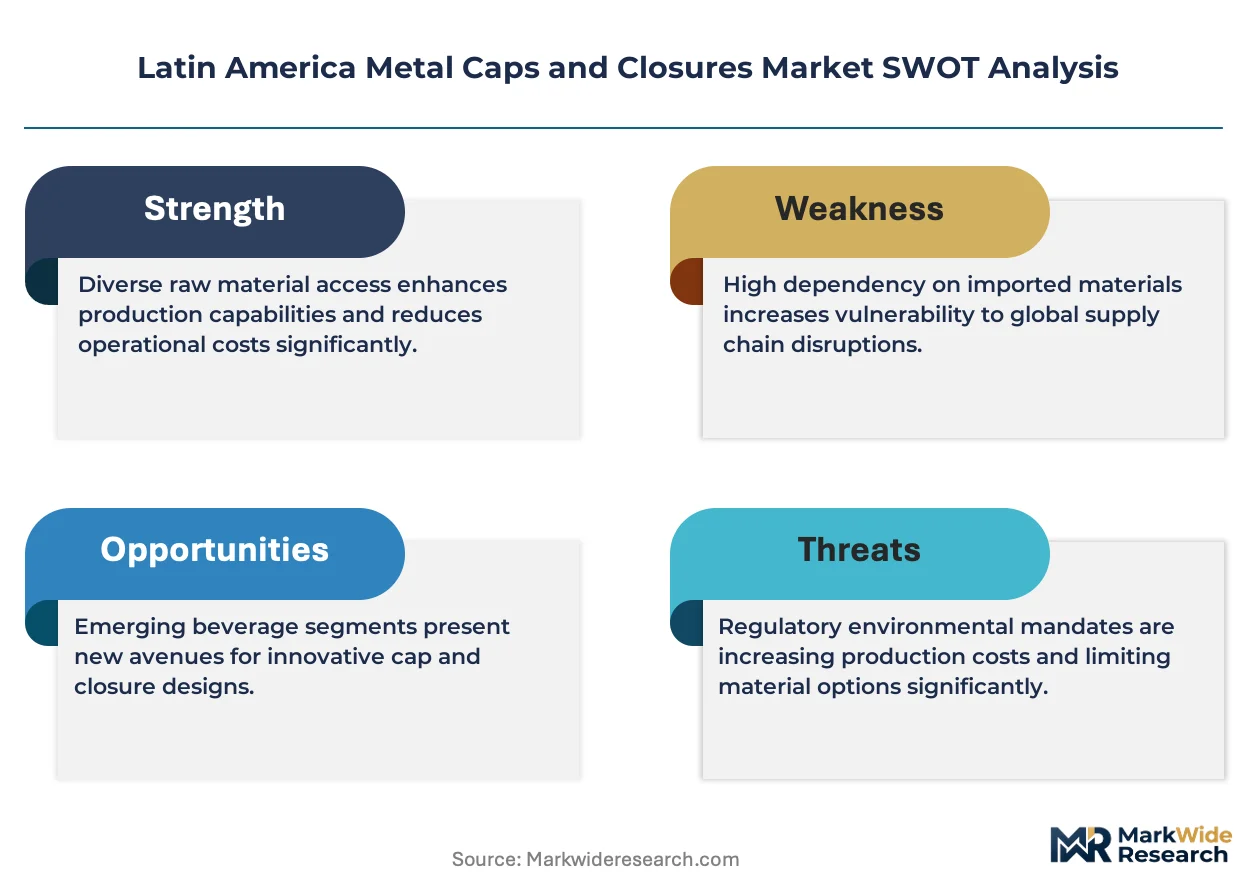
Aluminum lightweighting mandates from Brazil's beverage bottlers are compressing gauge thicknesses while ANVISA tightens pharmaceutical torque specifications, creating a technical squeeze between material efficiency and regulatory compliance.
Growth Catalysts
- ANVISA Pharmaceutical Standards:Brazil's child-resistance and tamper-evidence mandates for pharmaceutical closures are forcing upgrade cycles across domestic packaging lines.
- Aluminum Recyclability:Extended producer responsibility frameworks in São Paulo and Minas Gerais states favor mono-material aluminum closures that streamline post-consumer sorting.
- Beverage Export Channels:Premium spirits bottlers in Mexico's tequila and Brazil's cachaça segments demand differentiated closure aesthetics for North American and European markets.
Market Restraints
- Aluminum Alloy Input Volatility:Thin-gauge closure production depends on specialized aluminum-magnesium alloys subject to LME price swings and regional smelter capacity constraints.
- Retort-Grade Tinplate Concentration:Oxygen-barrier tinplate for sterilized food applications sources predominantly from Asian integrated steel mills, creating import dependency.
- Mercosur-Pacific Alliance Divergence:Misaligned packaging standards between Brazil's Mercosur bloc and Mexico's Pacific Alliance membership fragment procurement strategies.
Strategic Opportunities
- Colombia INVIMA Alignment:Harmonization of pharmaceutical closure standards with Brazilian ANVISA protocols opens cross-border supplier qualification efficiencies.
- Digital Printing Convergence:Direct-to-metal decoration technology enables short-run customization for craft beverage segments without tooling changeover costs.
- Reverse Logistics Integration:São Paulo's emerging state-level return schemes create closed-loop aluminum recovery partnerships with major bottlers.
Industry Challenges
- Liner Compounding Expertise Gap:Pharmaceutical-grade elastomeric liner formulation requires polymer chemistry capabilities scarce in regional compounders.
- Dual Certification Timelines:Simultaneous ANVISA and COFEPRIS approvals for cross-border pharmaceutical suppliers extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Metal Caps and Closures Market |
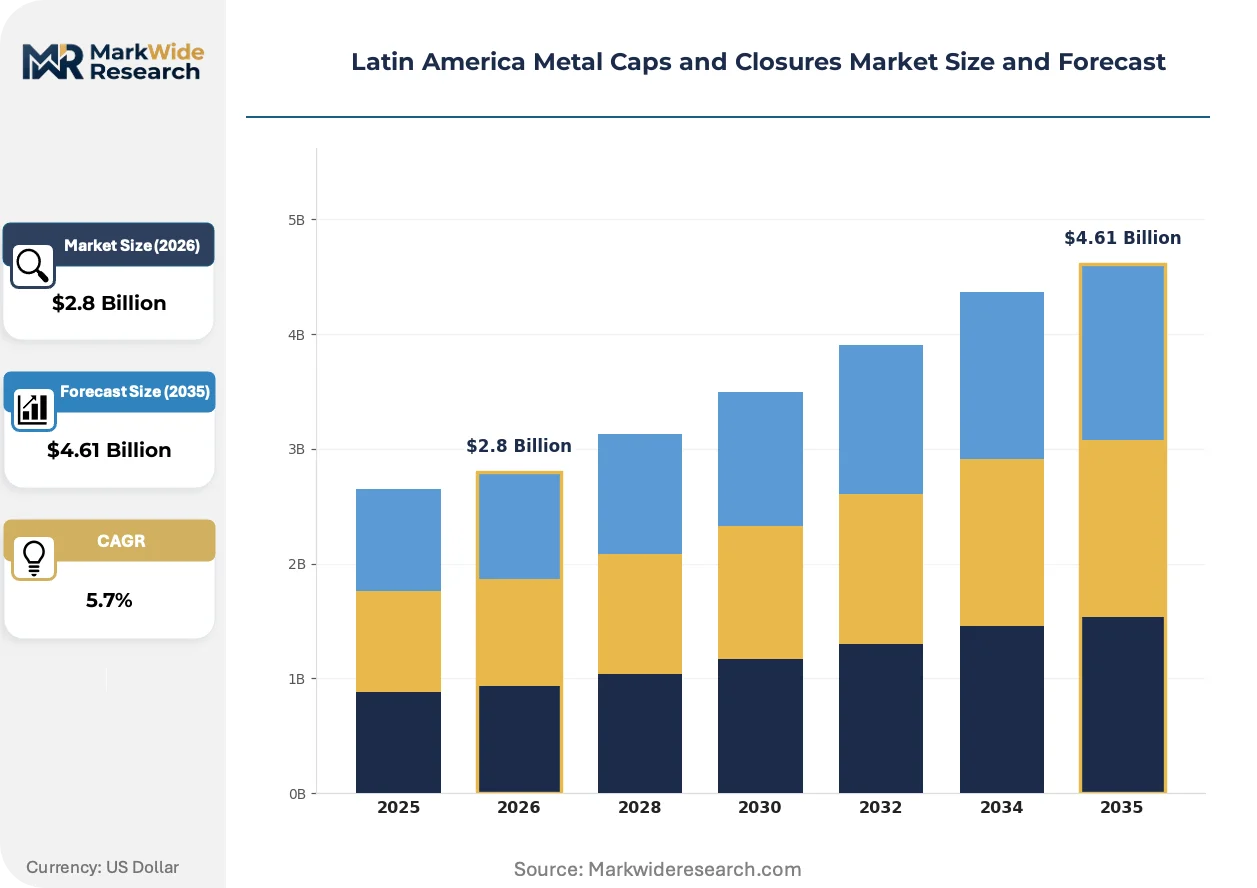
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caps, Lids, Closures, Seals Material: Aluminum, Steel, Tinplate, Stainless Steel Application: Beverages, Food, Pharmaceuticals, Personal Care End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Crown Holdings, Inc., Guala Closures S.p.A, Sonoco Products Company, Can-Pack S.A., Silgan White Cap Brasil, Amcor PLC, O. Berk Company, Trivium Packaging, ACTEGA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Metal Caps and Closures Market Trends and Innovations
Closure manufacturing is bifurcating between ultra-thin aluminum beverage formats and high-integrity pharmaceutical seals, with digital integration and regulatory harmonization as cross-cutting themes.
Thread-forming technology is hybridizing with precision deep-drawing processes to produce aluminum closures below 0.20mm gauge while maintaining torque retention specifications. Brazilian beverage bottlers are piloting these hybrid-formed closures at scale for carbonated soft drink lines. The hybridizing production method is compressing capital equipment requirements and enabling faster die changeovers for SKU proliferation.
COFEPRIS in Mexico is enforcing migration limit testing for liner compositions that contact acidic food matrices, extending pharmaceutical-grade material traceability into food-contact applications. Industrial consequence includes mandatory batch-level documentation from resin suppliers through finished closure. Acidic sauce and pickled vegetable packers in Jalisco and Puebla states are accelerating supplier audits to preempt enforcement actions.
Beverage bottlers are consolidating closure procurement under direct contracts with integrated aluminum suppliers, bypassing traditional distributor intermediaries. Mexican tequila exporters and Brazilian beer multinationals are leading this disintermediation to secure volume commitments and technical collaboration on lightweighting. The concentration is most visible in São Paulo's manufacturing corridor where three bottlers represent over sixty percent of regional aluminum closure offtake.
Latin America Metal Caps and Closures Market Segmentation
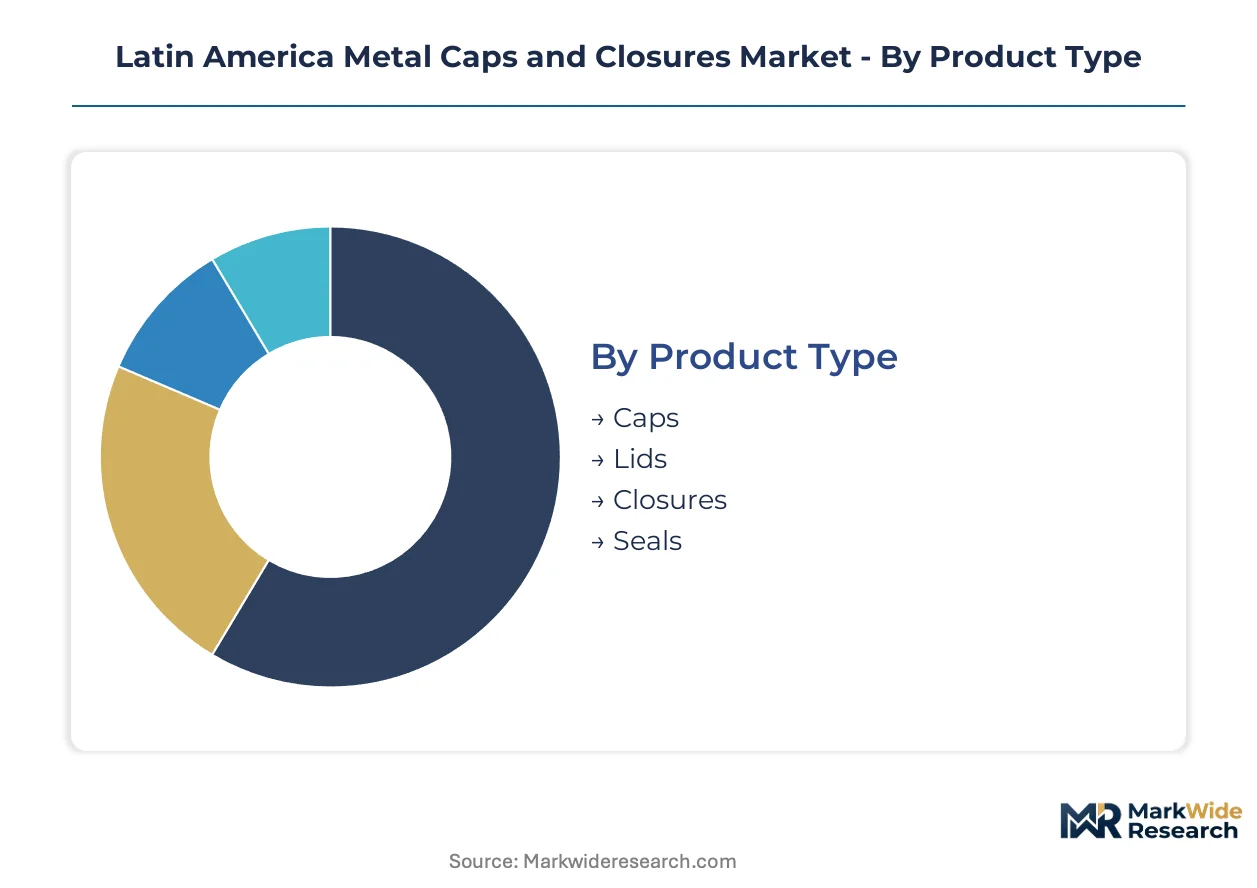
Metal caps and closures serve divergent technical requirements across Latin America's beverage, pharmaceutical, and food packaging sectors. Segmentation reveals how material specifications and regulatory mandates fragment procurement strategies across Brazil, Mexico, and Colombia.
Product Type:
Demand concentrates in hermetic sealing solutions spanning carbonated beverage bottling lines to sterile pharmaceutical vials.
- Caps:Threaded aluminum and steel caps dominate carbonated soft drink and beer bottling across São Paulo's manufacturing corridor. Crown Holdings secures multi-year supply agreements with Brazilian beverage multinationals by integrating roll-on pilfer-proof (ROPP) technology with lightweight gauge specifications.
- Lids:Flat metal lids with compound-sealed edges serve retort-stable food applications where oxygen barrier performance resists thermal processing cycles. Jalisco and Puebla food processors specify tinplate lids for acidic sauce matrices under COFEPRIS migration limit enforcement.
- Closures:Integrated sealing devices with elastomeric liners span pharmaceutical vials to premium spirits bottles. ANVISA child-resistance mandates force Brazilian pharmaceutical packers toward specialized closure designs with torque-verified opening forces.
- Seals:Tamper-evident aluminum seals protect injectable drug integrity across Colombia's INVIMA-regulated distribution channels. Bogotá pharmaceutical contract manufacturers qualify seal suppliers through batch-level material traceability documentation.
Established volume favors caps; emerging adoption favors seals.
Material:
Recyclability mandates and barrier requirements drive material selection across Latin American regulatory frameworks.
- Aluminum:Mono-material aluminum closures streamline post-consumer sorting under Brazil's National Solid Waste Policy. São Paulo state return schemes incentivize bottlers to specify aluminum ROPP closures for carbonated beverage lines.
- Steel:Tin-free steel retains cost-sensitive food packaging applications where moderate barrier performance suffices. Mexican vegetable canners specify chrome-coated steel for non-acidic product matrices.
- Tinplate:Oxygen-impermeable tinplate dominates sterilized food and infant formula applications requiring absolute shelf stability. Asian integrated steel mills supply retort-grade tinplate to Brazilian food processors facing import dependency.
- Stainless Steel:Corrosion-resistant grades serve pharmaceutical and high-acid food contact where liner migration risks demand inert substrates. ANVISA pharmaceutical audits prioritize stainless steel closures for parenteral drug packaging.
Aluminum captures volume leadership; stainless steel commands premium positioning.
Application:
Regulatory stringency varies sharply across end-use sectors, fragmenting supplier qualification requirements.
- Beverages:Aluminum ROPP closures for carbonated soft drinks and beer represent the highest-volume application. Brazilian bottlers compress gauge thicknesses below 0.20mm while maintaining torque retention through hybrid thread-forming technology.
- Food:Tinplate and steel closures preserve shelf stability for retorted vegetables, sauces, and infant nutrition. COFEPRIS migration testing for acidic matrices accelerates supplier audits among Jalisco packers.
- Pharmaceuticals:Child-resistant and tamper-evident closures command concentrated margins under ANVISA and INVIMA enforcement. Dual certification timelines for Brazil-Colombia cross-border suppliers extend product launches.
- Personal Care:Decorative metal closures differentiate premium cosmetics and fragrance positioning. Direct-to-metal digital printing enables short-run customization for craft beauty brands.
Beverages anchor volume scale; pharmaceuticals drive margin expansion.
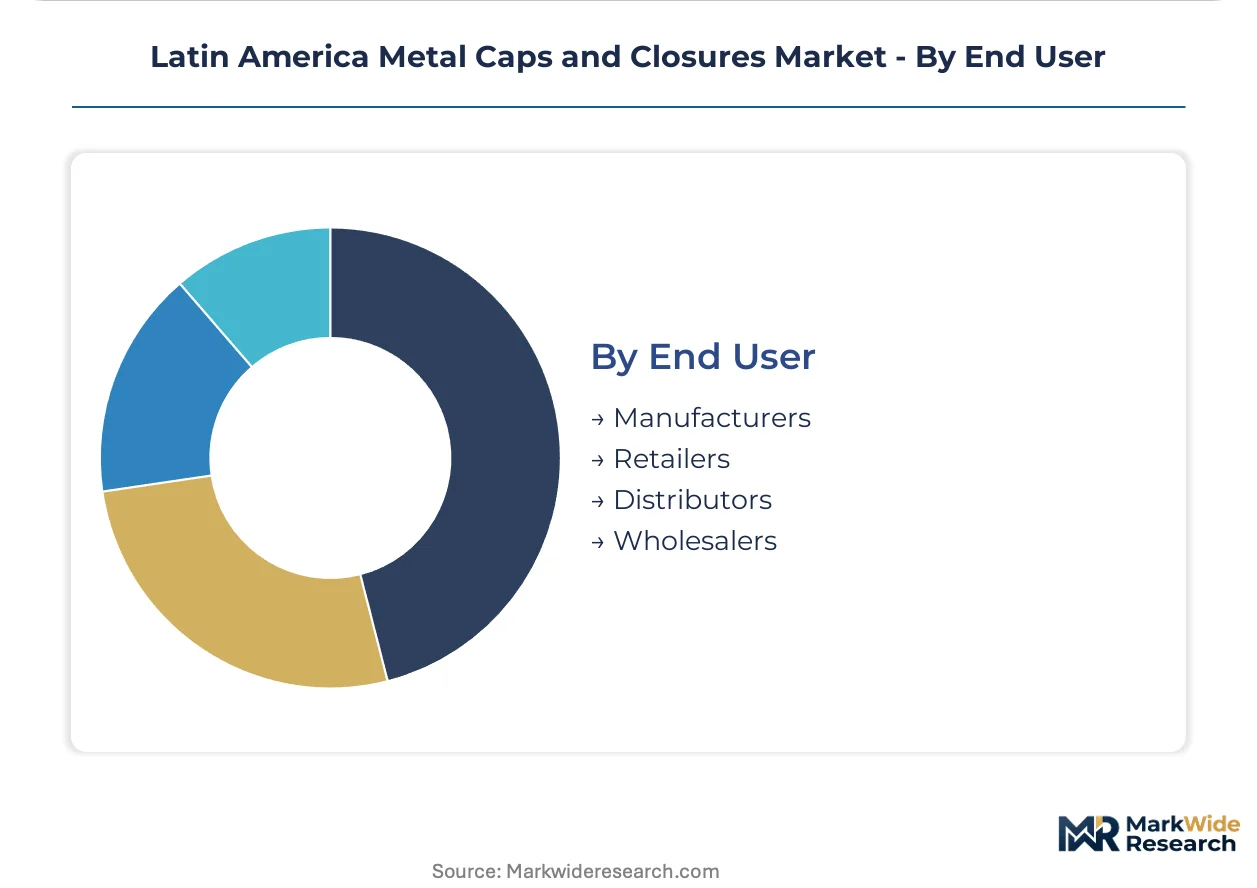
End User:
Procurement concentration is shifting from distributor intermediaries toward direct manufacturer relationships.
- Manufacturers:Beverage and pharmaceutical packaging lines source closures through integrated supply contracts with aluminum suppliers. Three São Paulo bottlers consolidate over sixty percent of regional aluminum closure offtake.
- Retailers:Private-label food and personal care brands specify closure aesthetics through direct supplier negotiations. Mexican retail chains audit tinplate lid suppliers for COFEPRIS compliance documentation.
- Distributors:Traditional intermediaries face disintermediation as major bottlers consolidate procurement under technical collaboration agreements. Remaining distributors serve fragmented craft beverage segments.
- Wholesalers:Bulk pharmaceutical closure supply to regional drug repackagers requires ANVISA batch traceability. Wholesalers maintain inventory buffers against dual certification delays.
Manufacturer direct procurement expands fastest; distributor relevance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southeastern manufacturing corridor exports aluminum closures to Mercosur partners while Mexican tequila bottlers supply North American premium spirits channels. Trade flows concentrate through São Paulo's industrial belt and Jalisco's agave-processing cluster.
Brazil
São Paulo and Minas Gerais states host beverage bottlers compressing aluminum gauge thicknesses below 0.20mm. ANVISA enforces child-resistance and tamper-evidence mandates for pharmaceutical closures. The ABC Paulista industrial zone anchors Crown Holdings' integrated beverage-can closure platform serving carbonated soft drink multinationals.
Mexico
Tequila and mezcal exporters in Jalisco demand differentiated closure aesthetics for US and European markets. COFEPRIS enforces migration limit testing for liner compositions contacting acidic food matrices. Guadalajara's packaging cluster concentrates Guala Closures' premium spirits designs and direct-to-metal digital printing capabilities.
Colombia
Bogotá pharmaceutical contract manufacturers qualify seal suppliers through INVIMA-regulated batch traceability documentation. INVIMA alignment with Brazilian ANVISA protocols opens cross-border supplier qualification efficiencies. The Sabana de Bogotá industrial corridor concentrates sterile injectable packaging for Andean distribution networks.
Argentina
Wine bottlers in Mendoza specify aluminum ROPP closures for export-oriented malbec lines. The national pharmaceutical regulator tightens material traceability rules for parenteral drug packaging. Buenos Aires province food processors source tinplate lids through Mercosur tariff-aligned supply chains.
Chile
Copper mining supply chains in Antofagasta drive demand for corrosion-resistant stainless steel closures in chemical processing applications. The national food safety authority enforces liner migration limits for acidic preserved foods. Santiago's packaging distributors consolidate procurement for northern mining camps and southern salmon processing facilities.
Latin America Metal Caps and Closures Market Competitive Landscape
On the supply side, the industry is consolidating around integrated aluminum suppliers and specialized lining compounders. Beverage bottlers disintermediate traditional distributors through direct technical collaboration agreements. Three archetypes dominate: integrated metal packaging conglomerates, pharmaceutical-grade closure specialists, and premium spirits design houses. Capacity expansion and backward integration into aluminum alloy supply represent the dominant competitive moves.
Within the integrated conglomerate tier, Crown Holdings, Inc. and Silgan White Cap Brasil occupy positions spanning beverage and pharmaceutical applications. Guala Closures S.p.A. exemplifies the premium spirits specialization archetype through its tamper-evident design capabilities for tequila and cachaça export channels.
| Leading Market Players |
|---|
| Crown Holdings, Inc. |
| Guala Closures S.p.A |
| Sonoco Products Company |
| Can-Pack S.A. |
| Silgan White Cap Brasil |
| Amcor PLC |
| O. Berk Company |
| Trivium Packaging |
| ACTEGA |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in São Paulo's aluminum closure manufacturing belt is compressing margins while forcing suppliers toward technical differentiation. Brazilian beverage bottlers exploit this utilization gap to extract gauge-thinning concessions from Crown Holdings and Silgan White Cap Brasil.
Pricing Analysis
Hybrid thread-forming technology commands premium positioning against conventional deep-drawn closures, while legacy tinplate formats face price erosion from Asian import competition. Three-tier pricing structure across premium, standard, and economy levels reflects torque specification tiers under ANVISA pharmaceutical mandates. Cost compression in standard-grade aluminum ROPP closures is intensifying because Brazilian bottlers consolidate procurement under direct contracts. Craft beverage segments show highest price sensitivity; pharmaceutical packers accept premium positioning for child-resistant certification.
Supply Chain Analysis
Tariff exposure between Brazil and Asian integrated steel mills dominates retort-grade tinplate sourcing strategies for regional food processors. Supply concentrates in São Paulo's manufacturing corridor, Jalisco's packaging cluster, and Bogotá's pharmaceutical belt. Raw material flows draw from LME-linked aluminum-magnesium alloy suppliers, elastomeric liner compounders in Argentina, and chrome-coated steel mills in East Asia. Single-source vulnerability pervades pharmaceutical-grade liner formulation where regional polymer chemistry capabilities remain scarce. Distribution runs through direct manufacturer-bottler contracts that disintermediate traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American metal caps and closures represent a high-growth disruption as ANVISA and COFEPRIS pharmaceutical mandates force upgrade cycles across domestic packaging lines. Regulatory tightening creates structural demand for certified closures that command margin premiums.
For Market Incumbents: Harden supply security through backward integration into aluminum alloy supply and captive liner compounding capabilities. Crown Holdings and Silgan White Cap Brasil must defend against emerging regional compounders by locking multi-year technical collaboration agreements with São Paulo bottlers. Certification investment in simultaneous ANVISA-COFEPRIS dual approval pathways protects against cross-border supplier encroachment.
For New Entrants and Emerging Players: Build out digital printing capabilities for craft beverage short-run customization in Mexico's tequila and mezcal export channels. Colombia's INVIMA alignment with Brazilian protocols creates the most penetrable regulatory entry point for pharmaceutical seal suppliers. Direct-to-brand go-to-market positioning bypasses distributor disintermediation already advanced in Brazil.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade closure manufacturing as batch-level traceability systems become mandatory. Long-term viability centers on suppliers with polymer chemistry capabilities and regulatory certification infrastructure. Acquisition target archetype: regional lining compounders with ANVISA-qualified formulations. The signal to watch is INVIMA-COFEPRIS harmonization momentum as cross-border supplier qualification efficiency indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Alloy Supply | Crown Holdings secures captive supply against LME volatility for São Paulo bottler contracts. |
| Dual Certification Investment | Simultaneous ANVISA and COFEPRIS approvals compress product launch cycles for cross-border pharmaceutical suppliers. |
| Digital Printing Capability Buildout | Direct-to-metal decoration enables short-run craft beverage customization without tooling changeover costs in Jalisco. |
| Reverse Logistics Partnership | São Paulo state return schemes create closed-loop aluminum recovery with major beverage bottlers. |
| Liner Compounding Acquisition | Polymer chemistry capabilities address pharmaceutical-grade elastomeric formulation scarcity in regional supply base. |
Research Methodology
A standing panel of beverage packaging procurement directors, pharmaceutical regulatory affairs leads, aluminum alloy plant managers, and liner compounding technical directors provided ongoing calibration. Primary interviews across these stakeholder roles combined with secondary validation from ANVISA regulatory filings, COFEPRIS migration limit documentation, Brazilian National Solid Waste Policy implementation records, and Latin American customs trade data. Bottom-up closure volume estimates triangulated against top-down beverage production statistics across the analysis window.
Scenario-bracketing framed demand projections across optimistic, baseline, and constrained regulatory enforcement pathways. Segmentation dimensions modeled include product type, material grade, application sector, and end-user procurement channel throughout the forecast period. CAGRs derived from volume trajectory analysis incorporating aluminum lightweighting adoption curves and pharmaceutical mandate implementation timelines. Industry-specific inputs captured hybrid thread-forming technology penetration and digital printing adoption rates.
Stress conditions across LME aluminum price volatility, ANVISA certification timeline delays, and Mercosur-Pacific Alliance regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization momentum and lightweighting technology adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
France Plastic Caps and Closures Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Screw Closure Market
Caps and Closures
Bar Top Corks Market
Caps and Closures
Aluminium ROPP Closures Market
Caps and Closures
Cuvette Caps Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
China Plastic Caps and Closures Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Asia Pacific Metal Caps and Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Resealable Closures and Spouts Packaging Market
Caps and Closures
Bag Closures and Seals Market
Caps and Closures
Brush Caps Market
Caps and Closures
Foam End Caps Market