
 United Arab Emirates Plastic Bottles Market | 2026-2036
United Arab Emirates Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Plastic Bottles Market Insights
Lightweighting-as-a-service is repositioning how converters monetize bottle production, shifting revenue from unit sales to material-efficiency guarantees and ongoing technical support. Emirates Plastic Industry UAE leverages backward integration into preform injection to sustain margin control across the Gulf Cooperation Council corridor. Al Amana Plastics anchors its position through dedicated pharmaceutical blow-molding lines serving MOHAP-registered facilities. Precision Group competes on rapid mold-change capabilities that reduce downtime for beverage contract packers.
Plastic bottles are hollow thermoplastic containers formed through extrusion blow molding, injection blow molding, or stretch blow molding, typically ranging from 0.5 to 2.0 millimeters in wall thickness depending on resin grade and internal pressure requirements. These vessels store, protect, and dispense liquid and semi-liquid products across consumer and industrial supply chains. PET dominates beverage applications due to its clarity, gas barrier properties, and compatibility with high-speed filling lines, while HDPE leads in personal care and pharmaceutical segments where chemical resistance and moisture protection command premium positioning. The 500ml size category captures the highest volume throughput as on-the-go consumption patterns normalize across UAE retail and foodservice channels.
MOHAP enforces food-contact safety standards that mandate migration testing for all plastic bottles intended for consumable goods, while the Emirates Authority for Standardization and Metrology administers UAE-specific labeling and recyclability marking rules that affect market access timelines. Dubai Municipality's sustainable packaging guidelines are pushing converters toward rPET incorporation thresholds that reshape raw material procurement and capital equipment planning. Stakeholders must monitor how MOHAP updates its technical regulations to align with evolving Gulf Standardization Organization harmonization efforts, as compliance divergence between emirates could fragment distribution logistics and testing costs.
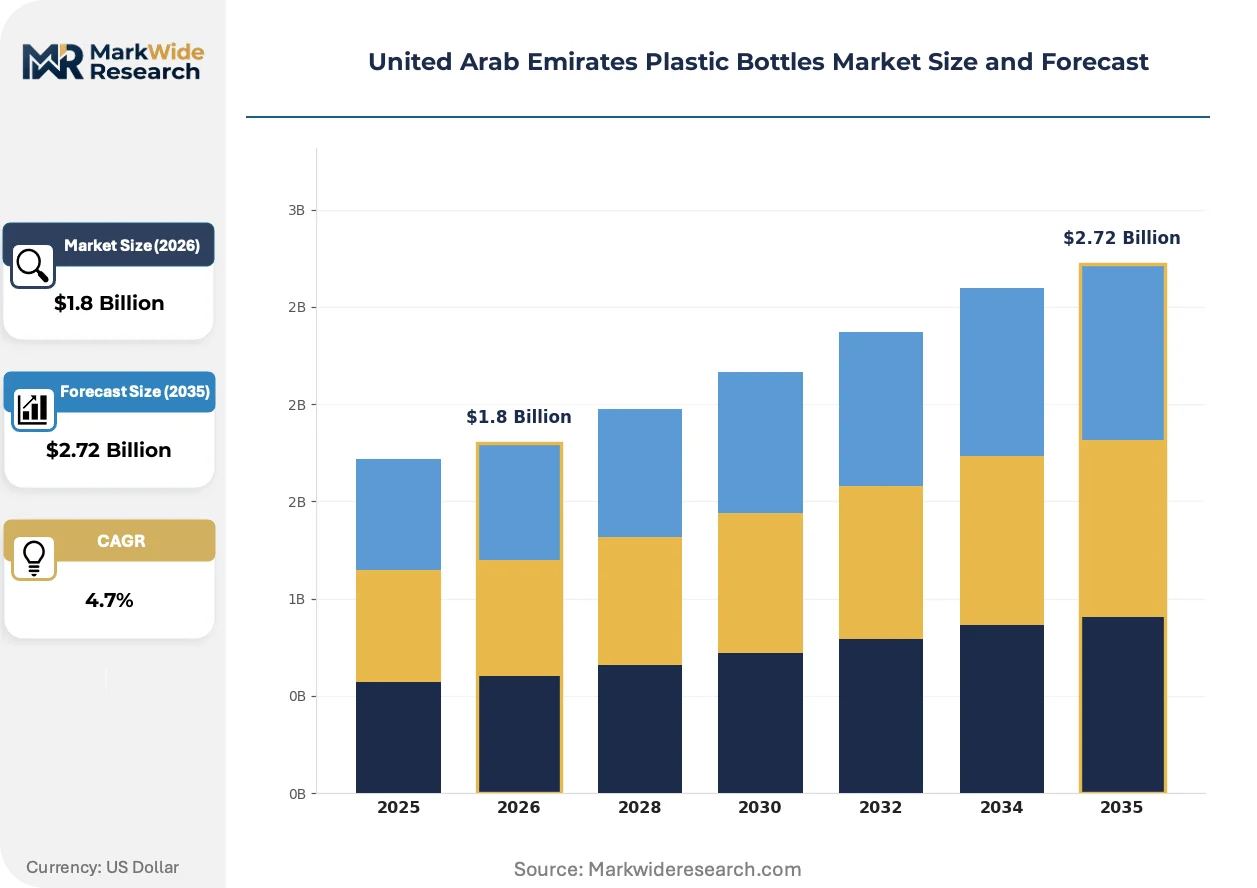
Market Dynamics
MOHAP's tightening food-contact migration testing protocols and Dubai Municipality's emerging rPET incorporation mandates are compressing converter compliance timelines while reshaping raw material procurement across the Emirates packaging corridor.
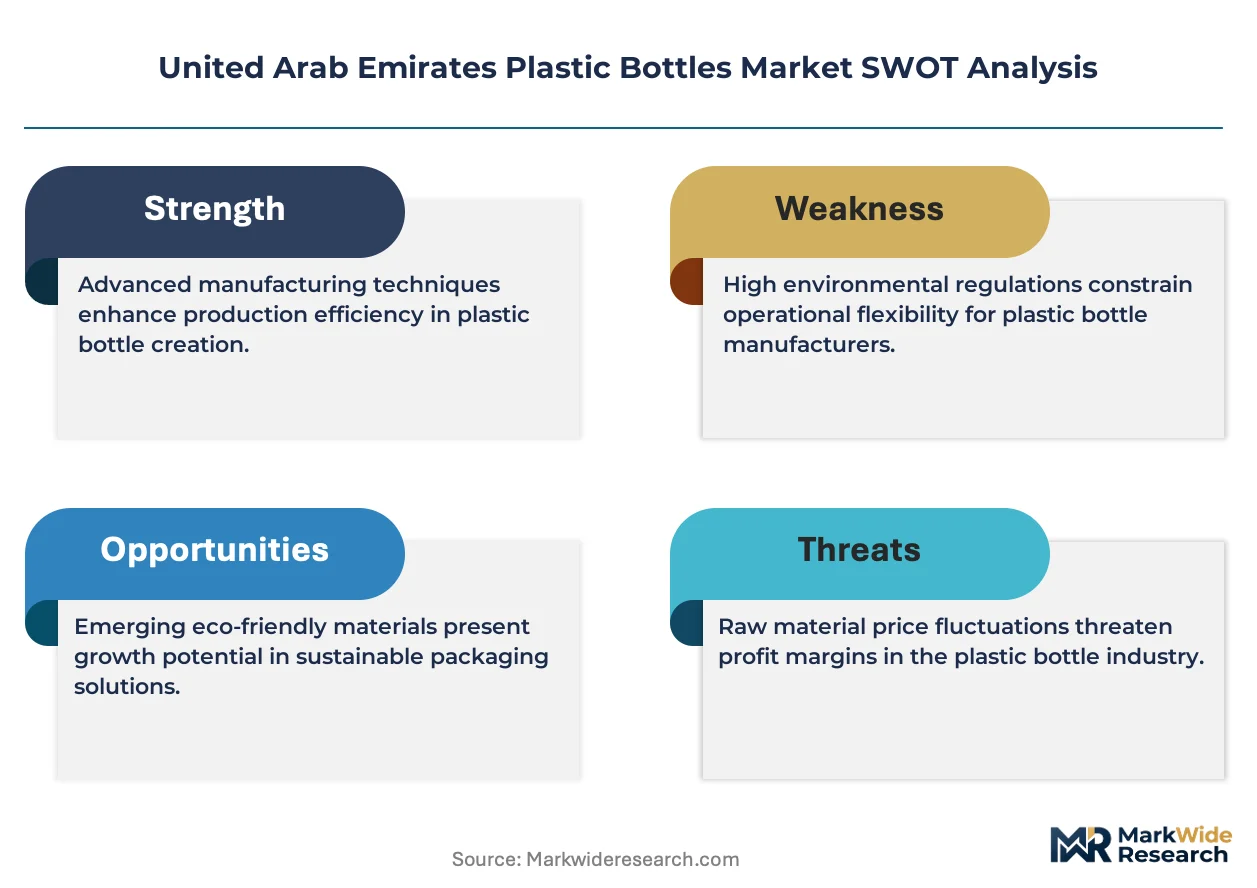
Growth Catalysts
- Pharmaceutical cold-chain expansion:UAE healthcare logistics networks are deepening temperature-controlled pharmaceutical distribution, driving demand for HDPE bottles with enhanced moisture barrier properties.
- rPET blending mandates:Dubai Municipality's sustainable packaging guidelines are creating procurement pull for post-consumer recycled content integration among beverage contract packers.
- High-speed filling line upgrades:PET clarity and gas barrier compatibility are accelerating adoption across soft drink bottling facilities in Dubai and Abu Dhabi packaging corridors.
Market Restraints
- Virgin PET resin price volatility:Feedstock cost fluctuations tied to naphtha and paraxylene markets squeeze converter margin structures without backward integration into preform production.
- Emirate-level regulatory divergence:Potential misalignment between MOHAP technical regulations and Gulf Standardization Organization harmonization efforts fragments testing costs and distribution logistics.
- Glass and aluminum substitution:Premium beverage brands are piloting alternative packaging formats in hospitality channels, pressuring PET volume retention in high-margin segments.
Strategic Opportunities
- Pharmaceutical-grade HDPE specialization:MOHAP-registered blow-molding capacity remains undersupplied relative to biologics distribution growth in Abu Dhabi and Dubai free zones.
- Lightweighting-as-a-service models:Technical consulting and material-efficiency guarantees offer recurring revenue streams beyond unit-based bottle sales to beverage contract packers.
- Rapid mold-change capabilities:Downtime reduction for SKU-dense beverage portfolios creates differentiation among converters serving fragmented retail and foodservice channels.
Industry Challenges
- Migration testing capacity bottlenecks:MOHAP-accredited laboratories face queue compression as food-contact compliance deadlines tighten, extending product launch timelines.
- rPET feedstock quality inconsistency:Post-consumer flake contamination variability complicates blow-molding process stability and optical grade achievement for clear bottle applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Plastic Bottles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End Use: Beverage, Personal Care, Household, Pharmaceuticals Size: 250ml, 500ml, 1L, 2L Closure Type: Screw Cap, Snap Fit, Flip Top, Diaphragm |
| Companies Covered | Emirates Plastic Industry UAE, Al Amana Plastics, Precision Group, Alpla Group, Bericap Holding GmbH, Integrated Plastic Packaging, Polycos Plastic Industries, Falconpack Industries LLC, Duplas Al Sharq, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Plastic Bottles Market Trends and Innovations
Digitalization of quality assurance and material traceability is compressing compliance verification cycles while enabling real-time specification management across converter-buyer interfaces.
Advanced preform injection systems with integrated vision inspection are unifying dimensional control and defect detection within single production cells. Beverage bottlers in Dubai packaging corridors are adopting these platforms at accelerated replacement cycles. This technology convergence is compressing quality assurance headcount requirements while elevating specification consistency for high-volume PET applications.
MOHAP's alignment with Gulf Standardization Organization harmonization protocols is tightening migration testing documentation requirements for all food-contact plastic bottles. Industrial consequence includes mandatory third-party certification renewal compression from biennial to annual cycles. Pharmaceutical and bottled water segments are responding by embedding compliance documentation within supplier scorecard mechanisms.
Buyer consolidation among UAE retail chains is compressing procurement decision cycles and elevating technical specification bargaining leverage. National supermarket operators are unbundling bottle supply from filling contracts, creating direct converter relationships that disintermediate traditional beverage brand procurement channels. This channel restructuring is most visible in Dubai and Abu Dhabi retail corridors where private-label beverage volume is accelerating.
United Arab Emirates Plastic Bottles Market Segmentation
Segmentation in the UAE plastic bottles market reveals how resin selection, end-use requirements, and packaging specifications create distinct procurement corridors. Converters align production capabilities against MOHAP compliance tiers and Dubai Municipality sustainability mandates to capture differentiated value pools.
Product Type:
Purchasing decisions in this category hinge on barrier performance requirements and regulatory compliance intensity across food-contact and pharmaceutical applications.
- PET:Amorphous polyester delivers optical clarity and carbonation retention for carbonated soft drinks and bottled water. Dubai and Abu Dhabi beverage corridors drive procurement volume as high-speed filling line upgrades accelerate specification standardization.
- HDPE:Semi-crystalline polyethylene offers chemical resistance and moisture protection for pharmaceutical and personal care formulations. MOHAP-registered facilities in Abu Dhabi free zones are expanding cold-chain biologics distribution, tightening demand for pharmaceutical-grade blow-molding capacity.
- LDPE:Lower-density variant provides flexibility and squeeze-ability for household cleaning trigger bottles and personal care dispensers where deformation recovery matters.
- PVC:Chlorinated polymer retains niche position in chemical-resistant industrial containers where cost sensitivity overrides sustainability positioning.
PET leads volumes today; HDPE is gaining share fastest as pharmaceutical logistics networks deepen across the Emirates.
End Use:
Application-specific compliance thresholds and filling line compatibility reshape converter-customer matching across the value chain.
- Beverage:Carbonated soft drinks, bottled water, and juice segments demand clarity, gas barrier, and high-speed line compatibility. Dubai Municipality's rPET incorporation mandates are restructuring raw material procurement for contract packers serving retail and foodservice channels.
- Pharmaceuticals:Biologics, generics, and over-the-counter medications require USP-grade HDPE with validated moisture barrier performance. MOHAP migration testing protocols and temperature-controlled distribution requirements elevate technical entry barriers for domestic converters.
- Personal Care:Shampoos, lotions, and cosmetic formulations prioritize chemical resistance and aesthetic differentiation through color matching and surface finish options.
- Household:Cleaning products and disinfectants balance cost efficiency with chemical compatibility, often specifying HDPE or LDPE depending on trigger mechanism integration.
Beverage dominates current throughput; pharmaceuticals is expanding most quickly as healthcare infrastructure investment accelerates.
Size:
Volume-to-surface optimization and consumption occasion patterns determine size selection across retail, foodservice, and institutional channels.
- 500ml:Standard single-serve format captures highest throughput as on-the-go consumption normalizes across UAE retail and foodservice. Convenience store and petrol station distribution networks standardize around this specification.
- 250ml:Compact format serves hospitality mini-bar, airline catering, and premium sampling applications where portion control commands price premiums.
- 1L:Multi-serve household format gains traction in supermarket private-label water and soft drink segments as buyer consolidation elevates volume-scale procurement leverage.
- 2L:Family-size format concentrates in hypermarket and wholesale club channels, with lightweighting initiatives reducing resin content per unit to defend margin structures.
500ml leads volumes today; 1L is climbing the fastest as private-label beverage expansion restructures retail procurement.
Closure Type:
Dispensing functionality and child-resistance requirements create specification divergence across end-use segments and regulatory exposure levels.
- Screw Cap:Threaded closure dominates beverage and pharmaceutical applications where resealability and tamper-evidence are mandatory. Standard 28mm and 38mm neck finishes enable equipment compatibility across Dubai and Abu Dhabi filling facilities.
- Flip Top:Hinged dispensing closure serves personal care and household segments where one-handed operation differentiates user experience. Molded-in living hinge designs reduce component count and assembly cost.
- Snap Fit:Press-on closure retains position in low-cost water and beverage applications where single-use consumption patterns eliminate resealability requirements.
- Diaphragm:Pierced membrane closure serves pharmaceutical oral liquid and unit-dose applications where contamination control and dosing accuracy override convenience considerations.
Screw cap leads volumes today; flip top is gaining share fastest as personal care and household segments expand formulation diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi command disproportionate procurement volumes compared to Sharjah and the Northern Emirates, reflecting divergent industrial infrastructure density across the federation. The seven emirates present distinct regulatory microclimates and end-use demand profiles that reshape converter location decisions and distribution network design.
Dubai
Dubai's retail and foodservice corridors drive PET bottle procurement for beverage contract packers serving convenience stores and petrol station networks. Dubai Municipality's sustainable packaging guidelines mandate rPET incorporation thresholds that compress converter compliance timelines. Jebel Ali industrial zone concentrates blow-molding capacity serving export-oriented beverage brands with high-speed filling line compatibility.
Abu Dhabi
Abu Dhabi's healthcare logistics expansion generates pharmaceutical-grade HDPE demand for cold-chain biologics distribution through Khalifa Port free zones. MOHAP food-contact migration testing protocols tighten entry barriers for converters serving MOHAP-registered pharmaceutical facilities. Musaffah industrial area anchors dedicated pharmaceutical blow-molding lines with validated moisture barrier performance.
Sharjah
Sharjah's cost-sensitive manufacturing base supplies household and personal care segments with LDPE trigger bottles and squeeze dispensers. The emirate's central location between Dubai and Northern Emirates enables distribution network optimization for regional retail chains. Hamriyah Free Zone concentrates mid-scale converters serving private-label detergent and cleaning product brands.
Northern Emirates
Ras Al Khaimah and Fujairah host emerging converter capacity targeting price-competitive water and beverage segments with simplified specification requirements. Federal infrastructure investment in these emirates lags Dubai and Abu Dhabi, extending lead times for MOHAP-accredited laboratory access. Local converters prioritize screw-cap beverage bottles for domestic wholesale and hospitality mini-bar channels.
United Arab Emirates Plastic Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with beverage bottlers consolidating procurement around preform-integrated suppliers while pharmaceutical buyers fragment orders across MOHAP-certified specialists. The market exhibits moderate concentration at the top tier, where backward-integrated players control margin structures through captive preform production. Three archetypes dominate: resin-integrated converters, compliance-specialist blow-molders, and rapid-turnaround contract packers. Capacity expansion and lightweighting technology licensing represent the dominant competitive moves reshaping positioning.
Among UAE-based converters, Emirates Plastic Industry UAE exemplifies the resin-integrated archetype through its preform injection capabilities. Al Amana Plastics occupies a position within the compliance-specialist tier, serving pharmaceutical-grade requirements. Precision Group anchors the rapid-turnaround segment with mold-change efficiency positioning. These three entities represent distinct strategic vectors without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Emirates Plastic Industry UAE |
| Al Amana Plastics |
| Precision Group |
| Alpla Group |
| Bericap Holding GmbH |
| Integrated Plastic Packaging |
| Polycos Plastic Industries |
| Falconpack Industries LLC |
| Duplas Al Sharq |
| Others |
Pricing and Supply Chain Analysis
Dubai Municipality's rPET incorporation mandates for beverage packaging are forcing converters to restructure raw material procurement toward post-consumer recycled flake, compressing margin structures and elevating price premiums for compliant supply tiers.
Pricing Analysis
Capacity additions in Sharjah and Ras Al Khaimah are reshaping price floors for standard-grade PET bottles as new entrants compete on unit economics. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and economy beverage tiers separates MOHAP-registered converters from commodity suppliers. Pricing pressure stems from virgin PET resin volatility tied to naphtha feedstock markets, squeezing non-integrated players. Beverage contract packers exhibit highest price sensitivity, while pharmaceutical buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Freight costs from Jebel Ali and Khalifa Port industrial zones anchor distribution economics for converters serving Dubai and Abu Dhabi corridors. Raw material sourcing draws from Saudi Arabia, Qatar, and India for virgin resin, with post-consumer flake increasingly sourced from European recycling networks. Single-source vulnerability concentrates in preform injection capacity controlled by backward-integrated players. Distribution runs through beverage bottler consolidation centers and pharmaceutical cold-chain logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through lightweighting technology licensing and pharmaceutical-grade certification premiums that offset commodity beverage pricing compression.
For Market Incumbents: To counter virgin resin price volatility and new entrant capacity in Northern Emirates, Emirates Plastic Industry UAE and Al Amana Plastics should deepen backward integration into preform injection and expand MOHAP-registered pharmaceutical blow-molding lines. Captive resin conversion and validated moisture barrier capacity defend pricing power in premium tiers.
For New Entrants and Emerging Players: Rapid mold-change automation technology offers entry leverage into SKU-dense beverage contract packing segments underserved by incumbent downtime constraints. Target Sharjah-based household and personal care converters with simplified specification requirements. Lead with technical consulting partnerships rather than unit-based volume competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-specialist blow-molders holding MOHAP pharmaceutical registrations as healthcare logistics networks deepen across Abu Dhabi free zones. Five-to-ten year viability favors converters with rPET processing capabilities aligned to Dubai Municipality sustainability mandates. Monitor MOHAP-Gulf Standardization Organization harmonization progress as regulatory divergence risk indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Injection | Captive resin conversion shields Emirates Plastic Industry UAE from virgin PET volatility. |
| MOHAP Pharmaceutical Registration Investment | Validates Al Amana Plastics for cold-chain biologics distribution in Abu Dhabi free zones. |
| Rapid Mold-Change Capability Deployment | Reduces Precision Group downtime for beverage contract packers with fragmented SKU portfolios. |
| rPET Processing Line Installation | Aligns converter capacity with Dubai Municipality sustainable packaging incorporation thresholds. |
| Lightweighting-as-a-Service Model Launch | Shifts converter revenue from unit sales to material-efficiency guarantees for beverage bottlers. |
Research Methodology
Direct dialogue with blow-molding plant managers, beverage procurement leads at contract packers, pharmaceutical supply chain directors, and MOHAP regulatory affairs specialists grounded qualitative findings. Secondary validation drew from UAE customs trade data, Emirates Authority for Standardization and Metrology filings, Dubai Municipality sustainable packaging guidelines, and SEC disclosures from resin suppliers. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Bottom-up segment analysis projected PET, HDPE, LDPE, and PVC resin demand across beverage, pharmaceutical, personal care, and household end uses over the projection horizon. Modeled dimensions included size category, closure type, and emirate-level regulatory cluster. CAGRs derived from historical volume trajectories, capacity expansion announcements, and end-use consumption elasticity. Forecast inputs incorporated MOHAP migration testing protocol updates and rPET blending mandate implementation timelines.
The model holds under stable UAE-Asia resin trade flows and Dubai Municipality guideline adherence; deviation in Gulf Standardization Organization harmonization progress or post-consumer flake import restrictions would shift converter compliance costs and launch timelines. Stakeholders should weight assumptions against their own operating context and laboratory accreditation status.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Brazil Plastic Packaging Market