
 PE Blow Molded Products Market | 2026-2036
PE Blow Molded Products Market Size, Share, and Industry Trends Forecast 2026-2036
PE Blow Molded Products Market Outlook
Polypropylene is repositioning select container applications as converters seek clarity and heat resistance beyond standard PE grades. LyondellBasell Industries Holdings B.V. leverages its polyolefin catalyst technology to sustain differentiated HDPE supply for large-part blow molding. Berry Global Inc. anchors North American food packaging demand through multi-site extrusion blow molding networks. Dow Inc. competes on metallocene PE innovation that extends downgauging possibilities in pharmaceutical bottles.
PE blow molded products are hollow thermoplastic articles formed by extruding molten polyethylene into a parison and inflating it within a cooled mold cavity, typically achieving wall thicknesses of 0.5–5 mm depending on structural requirements. These parts serve primarily as lightweight, chemically resistant enclosures for liquids, powders, and semi-solids across industrial and consumer supply chains. Bottles and containers command the largest volume share within product type segmentation, though drums for chemical logistics carry disproportionate margin contributions due to UN certification requirements. The automotive application segment is gaining structural importance as OEMs specify blow molded PE reservoirs and ducts to meet weight reduction targets without sacrificing impact resistance.
FDA food contact regulations and EPA container design standards govern material selection and permeation thresholds in the United States, while REACH and the EU Packaging and Packaging Waste Directive establish substance restrictions and recyclability mandates across European markets. China's GB standards and SAMR technical specifications further fragment compliance requirements for exporters serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content thresholds that will determine qualified resin sourcing strategies and mold design investments.
Market Dynamics
Automotive lightweighting mandates and virgin-grade resin certification requirements are forcing converters to requalify supply chains and retool for higher-performance polyethylene grades.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving SVHC candidate list is redirecting European compounders toward certified recycled PE streams for pharmaceutical and agrochemical packaging.
- Extrusion blow molding technology:Advances in parison programming and wall-thickness control are enabling complex automotive duct geometries previously requiring injection molding.
- Indonesia and Vietnam:Appliance and agrochemical export manufacturing clusters are expanding dedicated blow molding capacity to serve ASEAN and Australian distribution networks.
Market Restraints
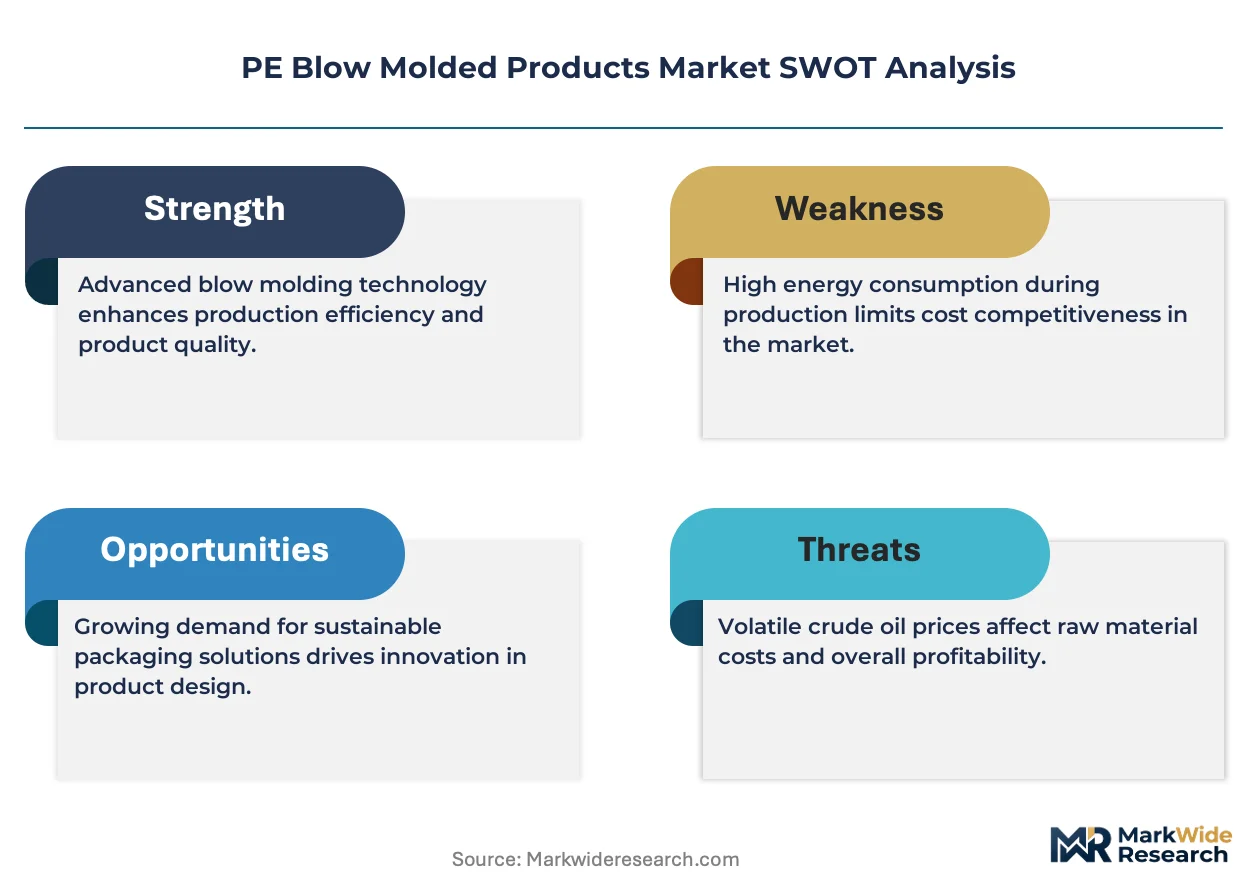
- Ethylene feedstock volatility:Naphtha and ethane price swings compress margin predictability for integrated and non-integrated resin producers alike.
- Single-site supply concentration:Critical HDPE grades for large-part blow molding originate from a narrow Gulf Coast production corridor vulnerable to hurricane disruptions.
- Polypropylene substitution:PP's superior clarity and heat resistance is capturing premium cosmetic and hot-fill food container segments.
Strategic Opportunities
- India's FSSAI packaging mandates:Stricter food contact compliance is creating qualified-supplier gaps that certified PE converters can fill for domestic edible oil and dairy markets.
- Metallocene PE downgauging:Convergence of catalyst innovation and pharmaceutical bottle specifications enables material reduction without permeation compromise.
- Direct-to-filler channel expansion:Bypassing traditional distributor networks for agrochemical and lubricant customers reduces working capital cycles and improves formulation collaboration.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and NMPA compliance for pharmaceutical bottles extends qualification cycles and strains technical resources.
- Coextrusion equipment capex:Barrier-layer blow molding lines for fuel tanks and chemical drums require capital commitments that mid-scale converters struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PE Blow Molded Products Market |
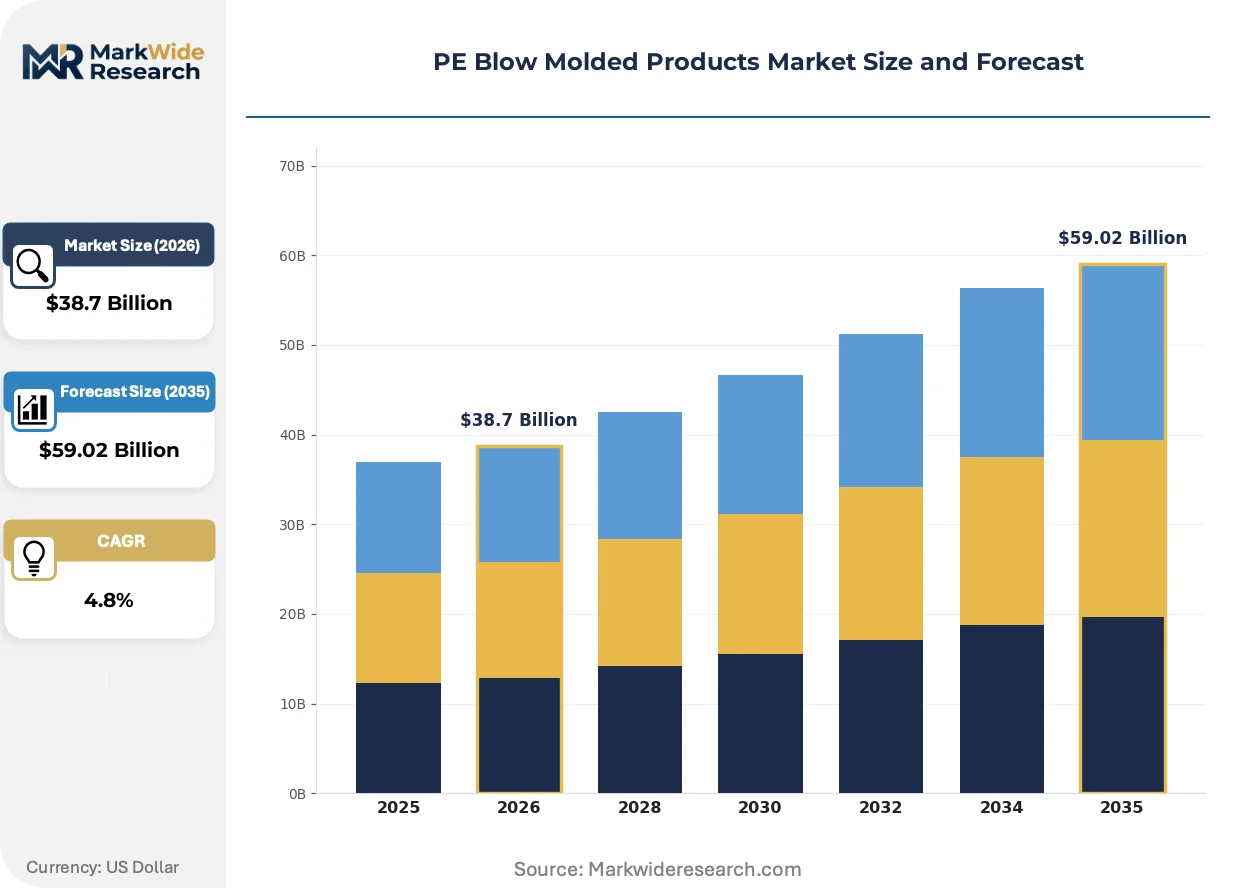
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jugs, Drums Industry Vertical: Food & Beverage, Pharmaceuticals, Consumer Goods, Automotive End User: Retailers, Wholesalers, Manufacturers, Distributors Application: Packaging, Storage, Transportation, Waste Management |
| Companies Covered | LyondellBasell Industries Holdings B.V., Berry Global Inc., INEOS Group, Magna International Inc., Dow Inc., Comar LLC, Inpress Plastics Ltd., Graham Packaging Company, Amcor Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PE Blow Molded Products Market Strategic Shifts
Digital mold simulation and real-time parison control are compressing development cycles for complex hollow parts while regulatory pressure on recyclability is reshaping material formulation roadmaps.
Multilayer coextrusion with ethylene vinyl alcohol barrier layers is absorbing demand from fluorinated and post-treatment alternatives for fuel tank and agrochemical drum applications. Tier 1 automotive suppliers in Germany and the United States are qualifying these structures for 15-year permeation warranties. The technology is absorbing share from conventional single-layer HDPE in UN-certified packaging segments.
China's GB standards for food contact plastics are tightening migration limits and testing protocols for polyethylene articles. Domestic converters face reformulation costs or virgin resin sourcing premiums to maintain compliance. The pharmaceutical and edible oil packaging segments are responding with accelerated adoption of certified resin tracking systems and third-party audit programs.
Consolidated procurement by multinational agrochemical and lubricant formulators is displacing fragmented regional buying patterns. Direct sourcing agreements now specify resin grade, recycled content thresholds, and mold ownership terms previously negotiated through distributors. This concentration is most visible in the North American and Western European agricultural chemical supply chains where three formulators control majority volume allocation.
PE Blow Molded Products Market Segmentation
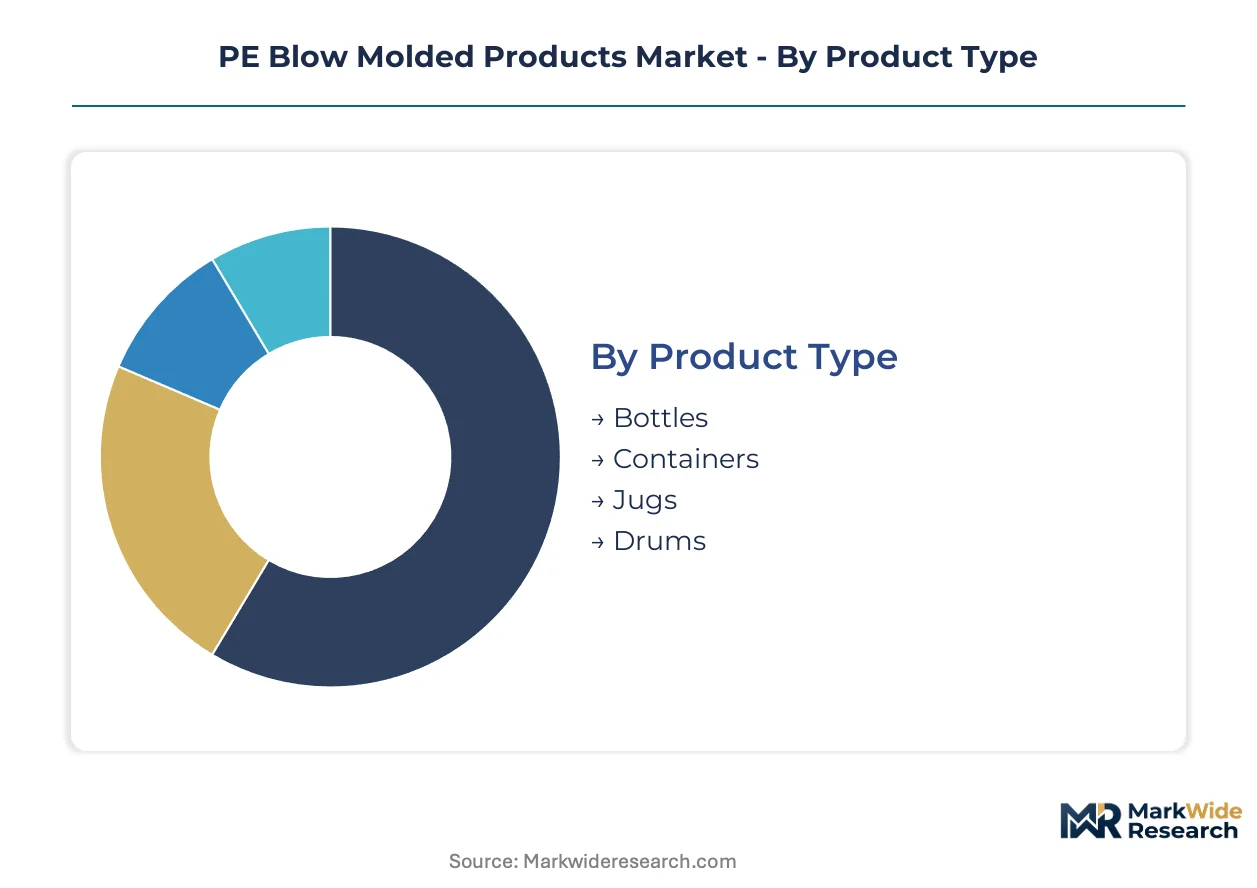
Segmentation in PE blow molding reveals how certification burdens, resin specifications, and end-use performance requirements fragment manufacturing strategies across converter tiers. Each dimension carries distinct margin structures and qualification barriers.
Product Type:
FDA food contact rules govern bottles and containers, while UN certification mandates shape drum specifications for chemical logistics.
- Bottles:Narrow-neck hollow forms extruded from HDPE or metallocene grades achieve wall thicknesses of 0.3–1.2 mm for pharmaceutical and edible oil applications. Pharmaceutical bottle demand concentrates in North American and European markets where FDA and EMA permeation standards require virgin-grade resin documentation and barrier-layer validation.
- Containers:Wide-mouth designs accommodate scoops and dispensing closures for dry goods and semi-solids. Food & beverage container procurement in Germany and the United States favors converters with documented REACH and FDA compliance histories, particularly for hot-fill and retort applications where heat resistance specifications exceed standard PE capabilities.
- Jugs:Intermediate-volume vessels serve institutional food service and chemical concentrate dilution markets.
- Drums:200-liter capacity UN-certified designs for agrochemical and lubricant logistics command premium pricing tied to drop-test and stack-load certification protocols.
Bottles sit at the top of the volume ranking, with containers climbing the fastest.
Industry Vertical:
Margin concentration varies sharply across verticals, with automotive and pharmaceutical applications requiring capital-intensive coextrusion capabilities.
- Food & Beverage:Edible oil, dairy, and condiment packaging drives high-throughput extrusion blow molding with FSSAI, FDA, and GB standard compliance. Indian and Chinese domestic markets are expanding certified converter capacity to meet tightening migration limit enforcement.
- Pharmaceuticals:Prescription and OTC bottle specifications demand EMA and FDA drug master file alignment with resin traceability systems. European and North American pharmaceutical packaging procurement is consolidating around converters with dedicated cleanroom blow molding lines and validated sterilization protocols.
- Consumer Goods:Personal care and household chemical containers compete on clarity and decoration flexibility where PP substitution pressures standard PE grades.
- Automotive:Fuel tanks, washer fluid reservoirs, and HVAC ducts specify ESCR-resistant HDPE with multilayer EVOH barrier construction for 15-year permeation warranties.
Food & beverage holds the largest volume position, while automotive posts the steepest expansion trajectory.
End User:
Channel structure determines working capital cycles and mold ownership arrangements, with direct manufacturer relationships displacing distributor intermediaries in agrochemical supply chains.
- Retailers:Private-label bottled water and edible oil programs specify volume commitments and recycled content thresholds that favor integrated converters with captive resin supply.
- Wholesalers:Industrial chemical and lubricant drum procurement concentrates in North American and Western European distribution networks where three formulators control majority volume allocation.
- Manufacturers:Tier 1 automotive suppliers in Germany and the United States qualify blow molded reservoirs through PPAP processes with 18–24 month development cycles.
- Distributors:Regional packaging resellers face margin compression as multinational formulators consolidate procurement through direct sourcing agreements specifying resin grade and mold ownership terms.
Manufacturers command the highest technical qualification barriers, with retailers driving the fastest volume growth.
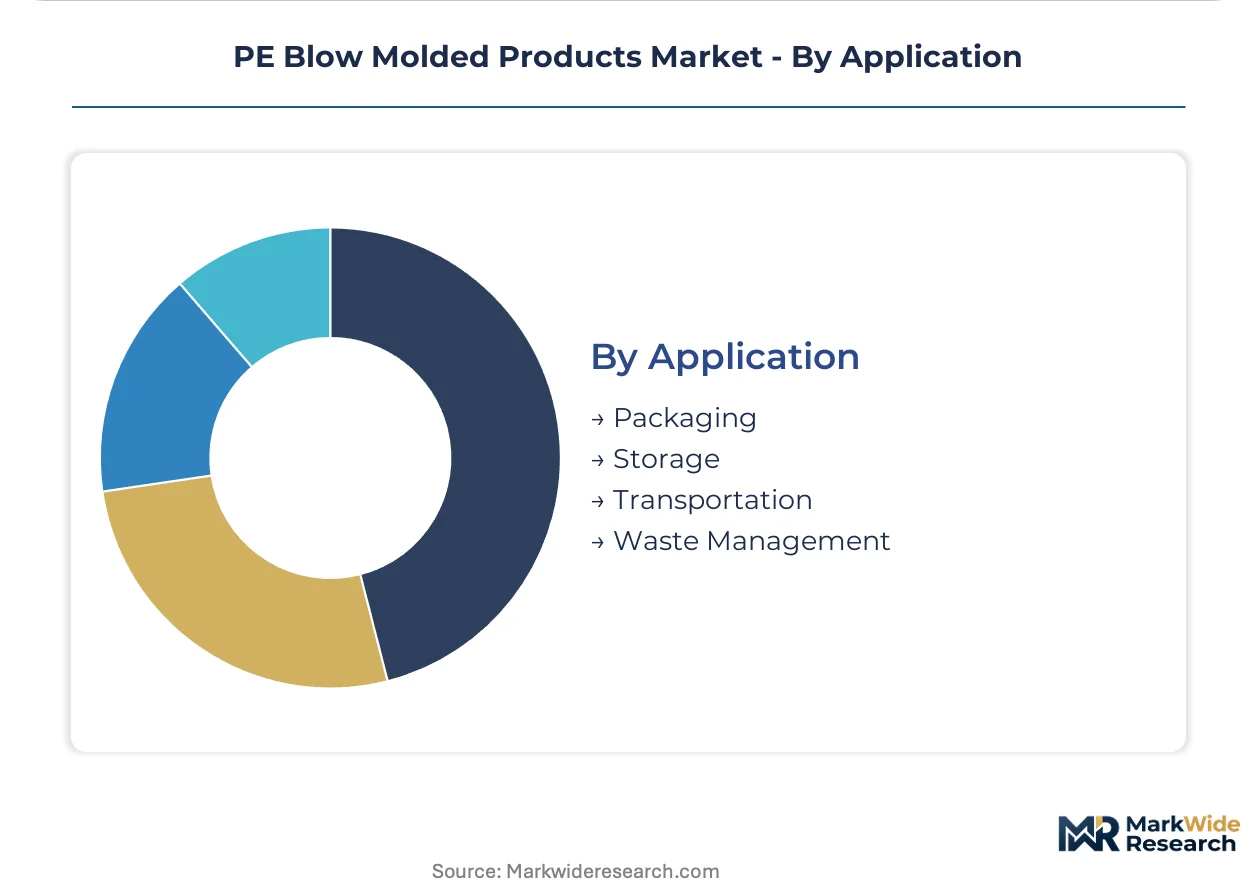
Application:
Functional performance requirements differentiate specification intensity, with transportation and waste management applications tolerating broader resin grade ranges than pharmaceutical packaging.
- Packaging:Primary and secondary containment for liquids, powders, and semi-solids spans food contact, pharmaceutical, and agrochemical end-uses with tiered compliance requirements.
- Storage:Intermediate bulk containers and drum designs for chemical warehousing emphasize stack-load performance and UV stabilization for outdoor exposure.
- Transportation:UN-certified drums and intermediate bulk containers for hazardous goods logistics require drop-test validation and closure torque specifications.
- Waste Management:Refuse containers and recycling bins utilize post-consumer recycled PE streams with relaxed aesthetic requirements compared to consumer-facing packaging.
Packaging dominates absolute volume, with waste management gaining share fastest on circular economy policy tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing belt concentrates advanced blow molding demand as OEMs specify lightweight PE reservoirs for EV platforms. Regulatory divergence across major economies is fragmenting resin certification requirements and redirecting trade flows toward qualified supply corridors.
United States
Automotive lightweighting mandates from NHTSA and EPA fuel economy standards accelerate PE substitution for metal fuel tanks and fluid reservoirs. FDA food contact regulations govern pharmaceutical bottle specifications with strict permeation thresholds. The Gulf Coast petrochemical corridor supplies critical HDPE grades, though hurricane vulnerability concentrates supply risk.
Germany
REACH substance restrictions from ECHA redirect compounders toward certified recycled PE streams for agrochemical packaging. Tier 1 automotive suppliers in Bavaria and Baden-Württemberg qualify multilayer EVOH barrier structures for 15-year permeation warranties. KBA vehicle certification requirements validate blow molded component performance for export markets.
China
NMPA packaging standards and GB food contact regulations tighten migration limits for polyethylene articles. The Yangtze River Delta and Pearl River Delta manufacturing clusters expand blow molding capacity to serve domestic edible oil and pharmaceutical demand. SAMR enforcement of technical specifications accelerates certified resin tracking system adoption.
India
FSSAI packaging mandates create qualified-supplier gaps that certified PE converters target for domestic edible oil and dairy markets. Maharashtra and Gujarat industrial corridors attract blow molding investment to substitute imported packaging. BIS standards alignment with international food contact protocols determines export qualification timelines.
Vietnam
Appliance and agrochemical export manufacturing clusters expand dedicated blow molding capacity for ASEAN and Australian distribution networks. The country's central bank monitors currency stability for resin import financing. Ho Chi Minh City and Hanoi industrial zones concentrate converter investment serving regional supply chain relocation.
PE Blow Molded Products Market Competitive Environment
Capacity expansion dominates the current landscape as converters retool for higher-performance polyethylene grades and multilayer coextrusion capabilities. The vendor base stratifies across integrated resin producers with captive compound operations, independent converters with regional extrusion networks, and specialized automotive Tier 2 suppliers with PPAP-qualified manufacturing lines. Strategic archetypes include resin-integrated players controlling formulation IP, geography-focused converters leveraging logistics proximity, and automotive specialists with validated barrier-layer expertise. M&A activity and direct-to-manufacturer channel expansion represent the dominant competitive vectors reshaping market access.
Within the resin-integrated tier, LyondellBasell Industries Holdings B.V. and Dow Inc. exemplify catalyst technology differentiation for large-part and downgauged applications. Berry Global Inc. occupies a position among North American multi-site converters with food packaging network density. These three entities represent distinct strategic postures: polyolefin innovation leadership, geographic coverage scale, and end-use vertical integration respectively.
| Leading Market Players |
|---|
| LyondellBasell Industries Holdings B.V. |
| Berry Global Inc. |
| INEOS Group |
| Magna International Inc. |
| Dow Inc. |
| Comar LLC |
| Inpress Plastics Ltd. |
| Graham Packaging Company |
| Amcor Limited |
| Others |
Value Chain & Pricing Dynamics
Multinational agrochemical formulators consolidating procurement through direct sourcing agreements dictate contract-based pricing structures that tie resin grade specifications to volume commitments and mold ownership terms. This buyer concentration shifts pricing power toward converters with captive HDPE supply and documented UN certification capabilities.
Pricing Analysis
Ethylene feedstock volatility passes through to finished product pricing via naphtha and ethane cost indices that integrated producers hedge more effectively than independent converters. Pricing stratifies across UN-certified drums, FDA-validated pharmaceutical bottles, and standard industrial containers based on certification investment and barrier-layer complexity. Cost compression in standard-grade containers is intensifying as polypropylene substitution captures premium cosmetic segments. Retail private-label programs exhibit highest price sensitivity, while automotive Tier 1 suppliers with 18–24 month PPAP cycles prioritize performance consistency over unit cost.
Supply Chain Analysis
Skilled blow molding technician availability constrains capacity expansion in Vietnam, Indonesia, and India's emerging manufacturing clusters where appliance and agrochemical export demand outpaces vocational training pipelines. Critical HDPE grades for large-part automotive and drum applications draw from the US Gulf Coast, Germany's Ruhr industrial corridor, and China's Yangtze River Delta petrochemical complexes. Single-site supply concentration along the Gulf Coast exposes the market to hurricane disruption risk. Distribution runs through direct-to-manufacturer channels for agrochemical and lubricant formulators, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PE blow molded products market functions as a stable compounder anchored by automotive lightweighting mandates that lock in decade-long specification cycles for fuel tanks and fluid reservoirs.
For Market Incumbents: To counter polypropylene substitution in premium cosmetic and hot-fill food containers, deepen barrier-layer coextrusion capabilities for pharmaceutical and agrochemical packaging while securing backward integration into certified recycled PE resin streams to meet REACH and EU Packaging Directive thresholds. For New Entrants and Emerging Players: Enter via India's FSSAI-compliant edible oil and dairy packaging segment where qualified-supplier gaps persist, targeting Maharashtra and Gujarat industrial corridors with dedicated cleanroom blow molding lines and third-party audit certifications as the primary go-to-market pathway. For Investors and Strategic Acquirers: Resin-integrated packaging conglomerates are the most active acquirer in this space, seeking mid-scale converters with automotive PPAP qualifications and multilayer EVOH expertise. The long-term viability window favors targets with demonstrated regulatory navigation across FDA, REACH, and NMPA jurisdictions. Monitor China's GB standards enforcement intensity as the inflection signal for certified resin tracking system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capacity Expansion | Enables 15-year permeation warranties for automotive fuel tanks under KBA and NHTSA validation protocols. |
| Certified Recycled PE Integration | Aligns formulation strategies with ECHA SVHC restrictions and EU Packaging Directive recyclability mandates. |
| Direct-to-Manufacturer Channel Development | Bypasses distributor intermediaries for agrochemical formulators, compressing working capital cycles and improving margin capture. |
| Automotive PPAP Qualification Investment | Secures Tier 1 supplier status with German and US OEMs specifying lightweight PE reservoirs for EV platforms. |
| Regulatory Compliance Infrastructure | Accelerates multi-jurisdiction certification timelines for pharmaceutical bottles requiring simultaneous FDA, EMA, and NMPA alignment. |
Study Parameters
Direct dialogue with blow molding plant managers, procurement leads at agrochemical formulators, automotive Tier 1 supplier engineers, and distribution channel partners grounded the qualitative assessment, supplemented by customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from resin-integrated players, and SAMR technical specification databases. Bottom-up and top-down triangulation validated volume estimates across product categories.
The analytical lens combined bottom-up capacity modeling by extrusion line count with top-down demand estimation from end-use consumption patterns across the projection horizon. Segmentation dimensions included product type, industry vertical, end-user channel structure, and regional production hub. CAGRs were derived from fitted growth curves incorporating automotive lightweighting program timelines, regulatory compliance phase-in schedules, and resin substitution elasticity parameters.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time resin inventory data and converter capacity utilization rates introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions regarding ethylene feedstock price stability and enforcement continuity for extended producer responsibility frameworks. Material deviation in China's GB standards migration limit enforcement or Gulf Coast hurricane frequency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market