
 South Africa Flexible Packaging Market | 2026-2036
South Africa Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Flexible Packaging Market Analytics
Aftermarket technical service and film recycling revenue is tilting toward converters with integrated collection networks. Mondi plc leverages its Richards Bay pulp-to-film complex to sustain captive resin supply for polyethylene laminates. Nampak Limited anchors beverage pouch growth through its Roodepoort flexible operations. Transpaco Limited competes on shrink-wrap specialization for industrial palletization.
Flexible packaging comprises pliable substrates—polyethylene, polypropylene, paper, and aluminum foil—formed into bags, pouches, films, and wraps through extrusion, lamination, or printing processes, designed to protect contents from moisture, oxygen, and mechanical damage while minimizing material weight versus rigid alternatives. Polyethylene films occupy the largest volume share due to cost efficiency in bread and frozen food wrapping, though pouches claim expanding margin pools in single-serve sauces and retorted meals. Food and beverage end users dominate offtake, while pharmaceutical blister lidding and medical sterilization films represent faster-growing niches with stricter barrier specifications.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that mandate post-consumer collection targets for plastic packaging, while the Bureau of Standards administers SANS mark certification for food-contact materials and migration limits. These frameworks elevate compliance costs for imported films while creating preferential demand for locally tested substrates. Stakeholders must monitor amendment timelines for biodegradable content mandates and decide whether to retrofit extrusion lines for mono-material compatibility or absorb premium sourcing costs from certified European suppliers.
Market Dynamics
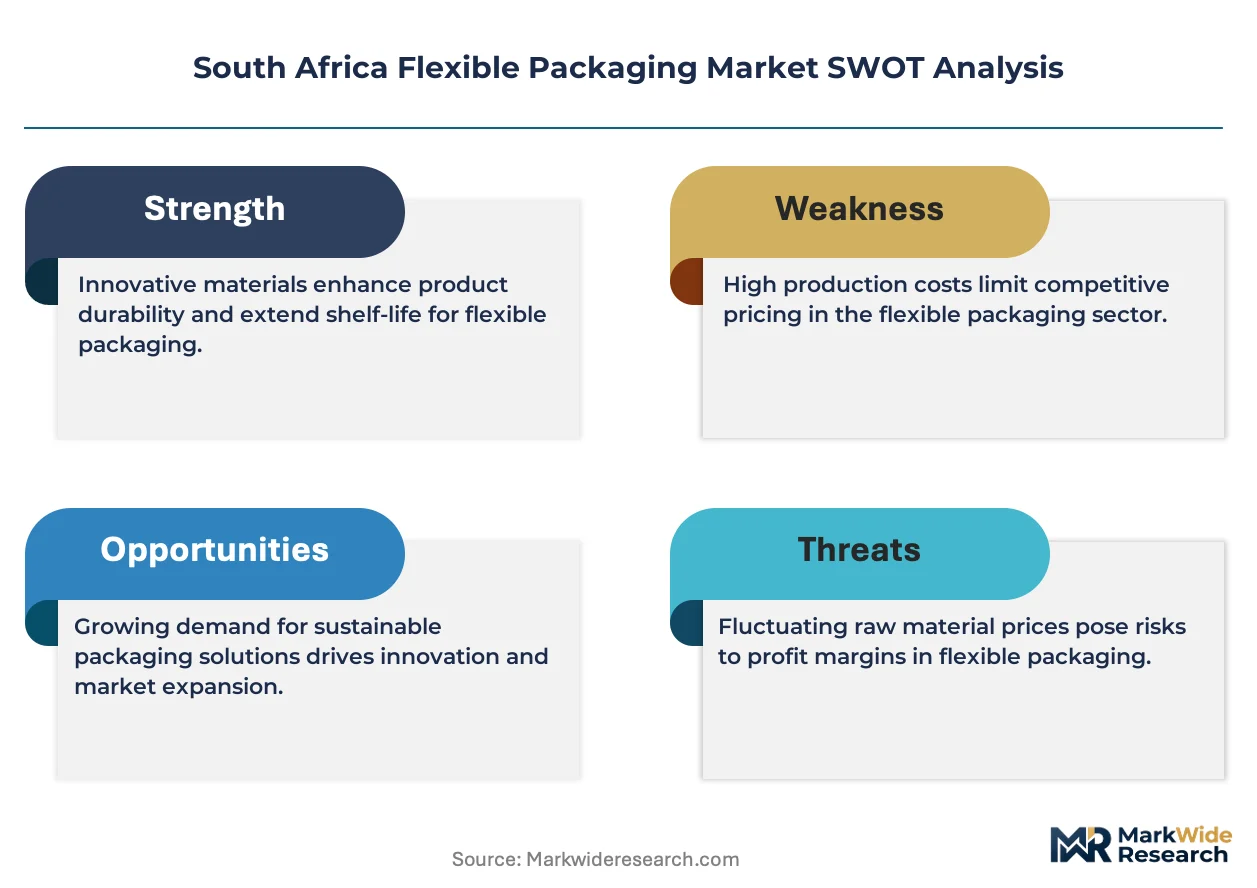
Extended producer responsibility regulations from South Africa's Department of Forestry, Fisheries and the Environment are redirecting capital flows toward recyclable multilayer structures, compressing demand for legacy non-recyclable laminates while elevating compliance costs across the converter base.
Growth Catalysts
- EPR Collection Targets:South Africa's mandated post-consumer plastic recovery obligations are accelerating investment in mono-material extrusion lines capable of mechanical recycling.
- Retort Pouch Demand:Food manufacturers in Gauteng province are expanding single-serve sauce and ready-meal packaging volumes, pulling higher-margin barrier film purchases.
- Richards Bay Resin Integration:Captive polyethylene supply from KwaZulu-Natal's integrated pulp-to-film complex is insulating domestic converters from import volatility.
Market Restraints
- Multilayer Recycling Technical Barrier:Current mechanical separation processes cannot recover value from adhesive-laminated polyethylene-polyamide structures, limiting circular economy participation.
- Imported Barrier Film Dependence:Specialized ethylene vinyl alcohol and metallized substrates remain concentrated among European and Asian suppliers, exposing converters to currency and freight cost swings.
- Biodegradable Certification Friction:SANS mark requirements for compostable claims lack harmonization with EU EN 13432 standards, forcing dual testing burdens on exporters.
Strategic Opportunities
- Western Cape Pharmaceutical Expansion:Cape Town's emerging bioscience cluster is generating sterilization film and blister lidding demand with stricter barrier specifications and premium pricing.
- Chemical Recycling Partnerships:Pyrolysis infrastructure development for contaminated flexible waste streams offers converters vertical integration into circular feedstock supply.
- Industrial Palletization Specialization:Shrink-wrap applications for mining and agricultural logistics in Mpumalanga and Limpopo remain underpenetrated by technical service providers.
Industry Challenges
- Mono-Material Retrofit Capex Burden:Extrusion line reconfiguration for recyclable single-substrate compatibility demands capital commitments that mid-tier converters struggle to finance.
- Migration Testing Talent Scarcity:SANS certification for food-contact materials requires specialized analytical chemists in short supply within South Africa's technical labor market.
- Collection Network Integration Complexity:Post-consumer film recovery systems must coordinate informal waste picker cooperatives with formal municipal infrastructure, creating operational friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Flexible Packaging Market |
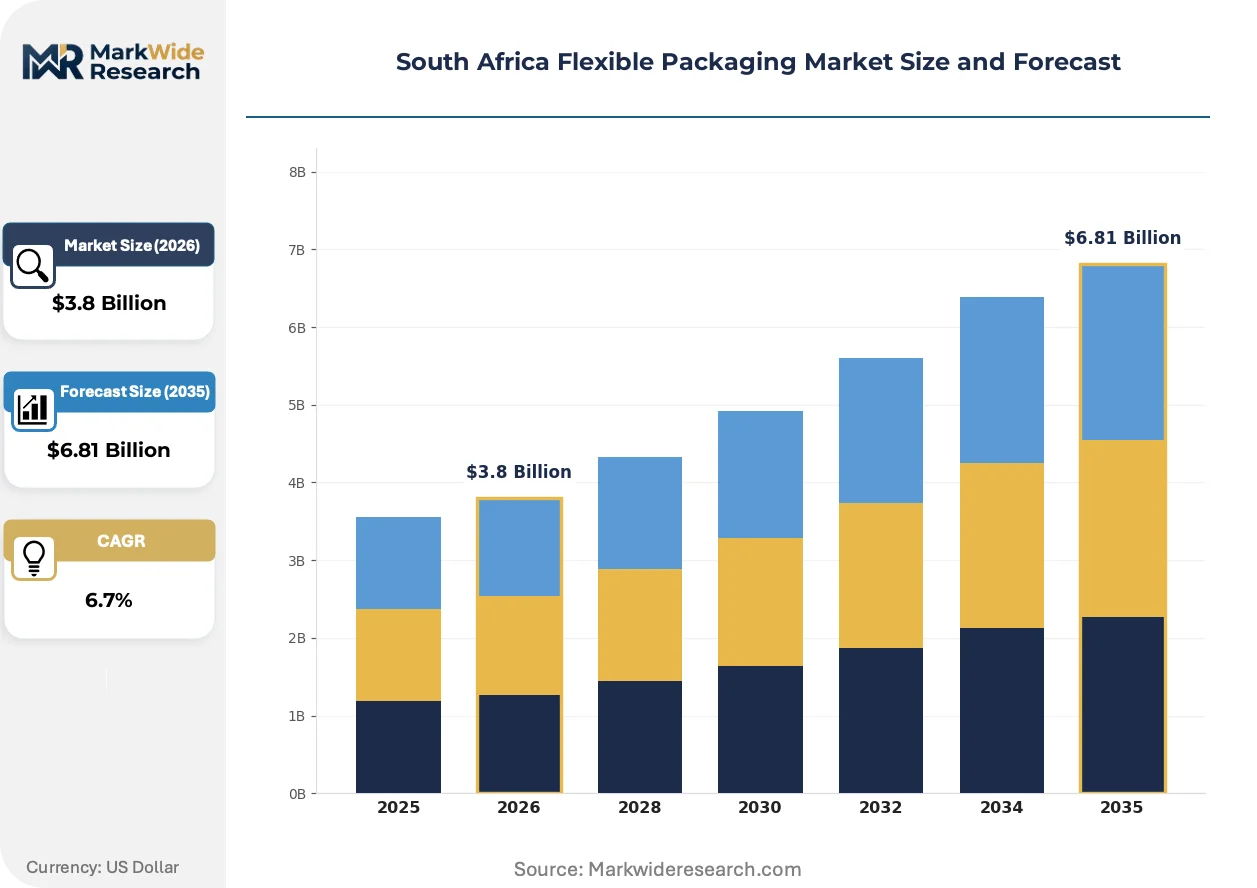
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Wraps Material: Polyethylene, Polypropylene, Paper, Aluminum Foil End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Application: Retail Packaging, Industrial Packaging, Protective Packaging, Medical Packaging |
| Companies Covered | Huhtamaki Oyj, Transpaco Limited, Nampak Limited, CTP Flexibles (Pty) Ltd, Novus Holdings Ltd, Mondi plc, Constantia Flexibles Group GmbH, Sonoco Products Company, Amcor plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Flexible Packaging Market Evolving Landscape
Material science advances and regulatory compliance pressures are converging to transform substrate selection and converting processes across South African flexible packaging operations.
High-barrier mono-material polyethylene structures are migrating from niche pharmaceutical applications toward mainstream food packaging. Retail chains in Johannesburg and Pretoria are adopting these substrates for private-label frozen goods to preempt EPR penalties. The technology is migrating from premium niches to volume segments, compressing demand for conventional multilayer laminates that lack mechanical recycling pathways.
South Africa's Department of Forestry, Fisheries and the Environment is tightening biodegradable content mandates through amendment timelines expected to accelerate compliance deadlines. This regulatory trajectory is forcing converters to decide between domestic extrusion line retrofits and premium sourcing from certified European suppliers. Food-contact pouch manufacturers in Gauteng face the most acute certification timeline pressure as major retailers advance sustainable packaging commitments.
Brand-led sustainable packaging specifications are reshaping procurement relationships between FMCG buyers and converter networks. Long-term supply agreements now incorporate post-consumer recycled content targets and carbon accounting disclosures that displace transactional spot purchasing. This pattern concentrates most visibly among beverage and condiment manufacturers supplying major supermarket chains in South Africa's urban corridors.
South Africa Flexible Packaging Market Segmentation
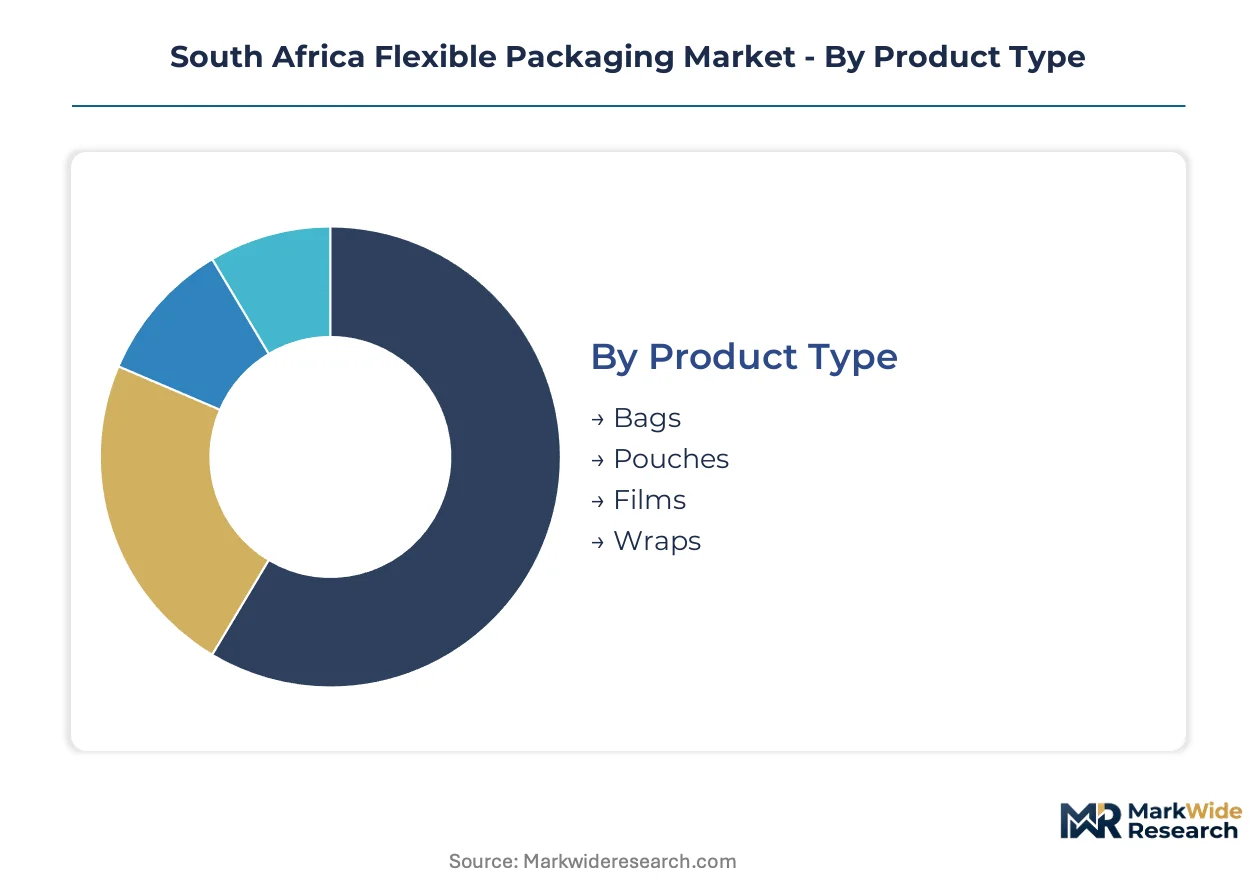
Segmentation in South African flexible packaging reveals how converter capabilities and regulatory pressures fragment across product forms and material specifications. Technical service intensity and recycling logistics vary sharply between commodity films and specialized barrier structures.
Product Type:
After-sales technical support requirements diverge substantially across product categories, with complex pouch formats demanding film welding expertise and print registration troubleshooting that simple wraps rarely require.
- Pouches:Multi-layer stand-up and flat pouches incorporate zipper closures, spouts, or fitments requiring precision heat-sealing equipment. Gauteng food manufacturers are expanding single-serve sauce and ready-meal formats, pulling specialized barrier film purchases toward retort-capable structures.
- Films:Roll-stock polyethylene and polypropylene films serve bread wrapping, frozen food overwrap, and industrial palletization with minimal converting complexity. Demand concentrates in Johannesburg and Pretoria retail distribution centers where high-volume throughput favors standardized specifications.
- Bags:Pre-formed gusseted and wicketed bags target bakery, produce, and dry goods applications with intermediate technical requirements for print quality and seal integrity.
- Wraps:Stretch and shrink-wrap formats dominate mining and agricultural logistics in Mpumalanga and Limpopo, with technical service focused on equipment compatibility rather than material engineering.
By volume, Films leads. By growth pace, Pouches is ahead.
Material:
Cost tier positioning determines converter equipment investment and resin sourcing strategy, with commodity polymers competing against premium substrates on fundamentally different margin structures.
- Polyethylene:Low-density and linear low-density polyethylene films occupy the largest volume position due to cost efficiency in bread wrapping and frozen food applications. The Department of Forestry, Fisheries and the Environment's EPR regulations are accelerating investment in mono-material polyethylene extrusion lines capable of mechanical recycling.
- Polypropylene:Biaxially oriented polypropylene delivers clarity and stiffness for snack food and confectionery packaging where visual shelf appeal commands premium positioning. KwaZulu-Natal's integrated pulp-to-film complex provides captive resin supply insulating domestic converters from import volatility.
- Paper:Kraft and grease-resistant papers serve fast-food and dry goods segments with renewable content claims that preempt retailer sustainability penalties.
- Aluminum Foil:Ultra-high barrier foil laminates target pharmaceutical blister lidding and retort applications where oxygen and moisture exclusion justifies material cost premiums.
Polyethylene dominates tonnage. Aluminum Foil captures the steepest expansion trajectory in pharmaceutical applications.
End User:
Application maturity shapes procurement relationships, with established food sector buyers driving hard on specifications while emerging pharmaceutical demand tolerates longer qualification timelines.
- Food & Beverage:Bread, frozen goods, sauces, and beverages generate the majority of flexible packaging offtake through Johannesburg and Pretoria retail distribution. Major supermarket chains are embedding post-consumer recycled content targets into long-term supply agreements that displace transactional spot purchasing.
- Pharmaceuticals:Sterilization films, blister lidding, and medical device packaging demand stricter barrier specifications with premium pricing and extended validation protocols. Cape Town's emerging bioscience cluster is generating specialized demand that outpaces converter qualification capacity.
- Personal Care:Sachets and pouches for shampoo, lotion, and cosmetic samples prioritize print quality and dispensing functionality over barrier performance.
- Household Products:Detergent and cleaning chemical packaging requires chemical resistance and child-resistant closure compatibility.
Food & Beverage anchors volume. Pharmaceuticals is expanding most quickly on specification premiums.
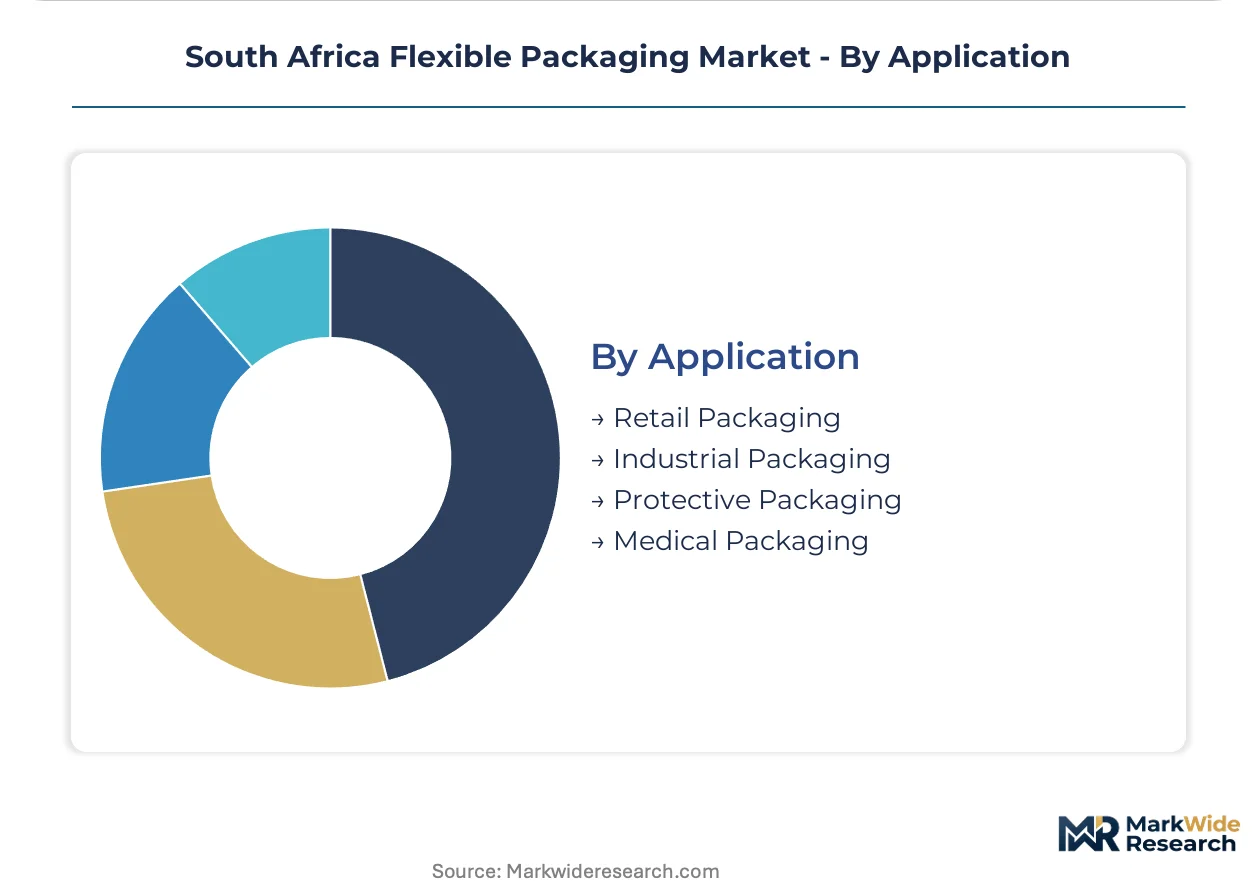
Application:
Supply concentration in Gauteng province aligns converting capacity with end-use geography, creating logistics advantages for retail-facing applications versus dispersed industrial demand.
- Retail Packaging:Printed films and pre-formed bags for supermarket shelves dominate converter output, with private-label growth in Johannesburg and Pretoria driving specification standardization.
- Industrial Packaging:Shrink-wrap and stretch film for palletization serves mining and agricultural logistics in Mpumalanga and Limpopo, remaining underpenetrated by technical service providers relative to retail segments.
- Protective Packaging:Cushioning films and void-fill materials target electronics and automotive component distribution with lower barrier requirements.
- Medical Packaging:Sterilization pouches and barrier films for healthcare settings face SANS certification requirements for migration limits and biocompatibility.
Retail Packaging leads by shipment volume. Medical Packaging is gaining share fastest on regulatory barrier premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Gauteng's retail corridors negotiate aggressively on polyethylene film specifications, while pharmaceutical converters in the Western Cape absorb premium pricing for barrier-certified substrates without comparable price elasticity.
Gauteng
Johannesburg and Pretoria host the densest concentration of flexible packaging converting capacity and FMCG distribution infrastructure. The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that mandate post-consumer collection targets for plastic packaging. Roodepoort flexible operations anchor beverage pouch growth through integrated converting networks serving major supermarket chains.
Western Cape
Cape Town's emerging bioscience cluster generates sterilization film and blister lidding demand with stricter barrier specifications than commodity food applications. SANS mark certification requirements for food-contact materials and migration limits elevate compliance costs for imported films. The region's pharmaceutical packaging segment tolerates longer qualification timelines and premium pricing relative to Gauteng's retail-facing converters.
KwaZulu-Natal
Richards Bay's integrated pulp-to-film complex provides captive polyethylene resin supply insulating domestic converters from import volatility. The Department of Forestry, Fisheries and the Environment's EPR regulations are accelerating investment in mono-material extrusion lines capable of mechanical recycling. Durban's port infrastructure supports resin import alternatives when Richards Bay output falls short of converter demand.
Mpumalanga and Limpopo
Mining and agricultural logistics in these provinces drive shrink-wrap and stretch film applications for industrial palletization. SANS certification requirements apply less stringently to non-food industrial packaging than to retail-facing substrates. Technical service providers remain underpenetrated relative to Gauteng's retail corridor, creating whitespace for specialized industrial packaging distributors.
South Africa Flexible Packaging Market Competitive Landscape
Integrated resin-to-film operators and specialized converting houses split the market into distinct competitive spheres. The vendor base concentrates around three archetypes: multinational packaging conglomerates with African regional headquarters, domestic integrated paper and plastics groups, and mid-tier flexible specialists competing on shrink-wrap and industrial applications. Consolidation pressure is accelerating through extended producer responsibility compliance costs that favor scale, while portfolio diversification into recyclable mono-material structures represents the dominant competitive move.
Among domestic integrated groups, Mondi plc and Nampak Limited exemplify the resin-integrated archetype, with Richards Bay pulp-to-film operations and Roodepoort beverage pouch capacity respectively. Transpaco Limited occupies a position within the specialized industrial tier, competing on shrink-wrap applications for mining and agricultural logistics. These three anchors demonstrate how geographic concentration in Gauteng and KwaZulu-Natal shapes competitive positioning around captive supply chains versus specialized service models.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Transpaco Limited |
| Nampak Limited |
| CTP Flexibles (Pty) Ltd |
| Novus Holdings Ltd |
| Mondi plc |
| Constantia Flexibles Group GmbH |
| Sonoco Products Company |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
Richards Bay's integrated pulp-to-film complex anchors polyethylene resin supply for Gauteng converters, translating captive feedstock control into pricing leverage against import-dependent competitors. The Department of Forestry, Fisheries and the Environment's extended producer responsibility regulations compress margins on non-recyclable multilayer structures while rewarding mono-material investments with compliance cost avoidance.
Pricing Analysis
Aftermarket technical service revenue—including film recycling collection and extrusion line maintenance contracts—drives lifetime value differentiation among South African converters. Three-tier pricing structure across premium barrier-certified, standard food-contact, and economy industrial grades reflects SANS certification investment and resin integration depth. Cost compression in commodity polyethylene films intensifies as Richards Bay output expands and import alternatives multiply. Retail chains in Johannesburg and Pretoria exhibit acute price sensitivity on high-volume bread and frozen food wrapping, while pharmaceutical buyers in the Western Cape absorb premium pricing for sterilization films without comparable elasticity.
Supply Chain Analysis
Extended payment terms from resin suppliers to mid-tier converters—often 90-120 days—function as supply-chain finance facilities that ease working capital strain during extrusion line retrofits. Raw material flows draw from Saudi Arabia and Qatar for polyethylene feedstock, Belgium and Germany for specialized ethylene vinyl alcohol barrier resins, and China for metallized substrates. Single-source vulnerability concentrates in high-barrier imported films where European suppliers dominate technical specifications. Distribution runs through Johannesburg and Pretoria retail distribution centers for FMCG-facing output, with Durban port infrastructure enabling resin import alternatives when Richards Bay supply tightens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material extrusion engineering talent and SANS-certified analytical chemistry capacity represent binding constraints that separate viable competitors from stranded legacy operators. The market rewards firms that internalize these scarce capabilities before regulatory deadlines harden.
For Market Incumbents: Entrench position by retrofitting Gauteng extrusion lines for recyclable polyethylene structures ahead of Department of Forestry, Fisheries and the Environment amendment timelines. Secure backward integration into Richards Bay resin supply or long-term offtake agreements to insulate against import volatility. Threat substitution from European certified suppliers intensifies as biodegradable mandate deadlines approach.
For New Entrants and Emerging Players: Mpumalanga and Limpopo industrial palletization markets remain underpenetrated by technical service providers relative to Gauteng's retail corridor. Target shrink-wrap and stretch film applications for mining and agricultural logistics with equipment compatibility expertise rather than material engineering complexity. Partner with informal waste picker cooperatives to build post-consumer collection networks that satisfy extended producer responsibility obligations.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with demonstrated mono-material qualification capacity and integrated collection infrastructure. Long-term viability hinges on circular feedstock access through mechanical or chemical recycling pathways. Watch for pyrolysis infrastructure development announcements as inflection indicators for vertical integration opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Retrofit | Department of Forestry, Fisheries and the Environment compliance cost avoidance locks in mechanical recycling participation. |
| Captive Resin Supply Integration | Richards Bay pulp-to-film complex insulation from import volatility secures margin stability. |
| Post-Consumer Collection Network Buildout | Extended producer responsibility targets require coordination with informal waste picker cooperatives. |
| SANS Certification Investment | Food-contact migration testing capacity differentiates qualified suppliers from import-dependent competitors. |
| Pharmaceutical Barrier Film Qualification | Cape Town bioscience cluster demand outpaces converter validation capacity at premium pricing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of converter production data, resin import customs records, and Department of Forestry, Fisheries and the Environment regulatory filings. Primary interviews engaged extrusion line engineers, procurement managers at Johannesburg and Pretoria retail chains, SANS certification laboratory directors, and waste picker cooperative coordinators. Secondary validation drew from Bureau of Standards technical bulletins, pulp-to-film complex output disclosures, and extended producer responsibility implementation progress reports. Bottom-up capacity modeling triangulates against top-down demand aggregation from FMCG distribution data.
Forecast inputs include polyethylene resin price trajectories, mono-material extrusion line installation rates, and pharmaceutical packaging qualification timelines across the analysis window. Segmentation dimensions span product type, material substrate, end-use industry, and geographic demand cluster. CAGRs derive from elasticity-adjusted volume projections and value-per-ton trends by specification tier. Industry-specific inputs incorporate EPR compliance deadline acceleration scenarios and biodegradable content mandate amendment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by resin-integrated multinationals or chemical recycling infrastructure developers would shift outcomes. Macroeconomic deviation in rand-dollar exchange rates, regulatory amendment acceleration, or breakthrough barrier mono-material technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Plastic-Free Packs Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Canada Plastic Bottles Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
FFS Rigid Films Market