
 Thailand Rigid Plastic Packaging Market | 2026-2036
Thailand Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Rigid Plastic Packaging Market Insights
Lightweighting technology is narrowing the performance gap between PET and traditional glass containers for premium food applications. SCG Packaging Public Company Limited leverages its integrated resin-to-container supply chain across Thailand's Eastern Seaboard. Thai Plaspac Public Company Limited anchors its position through specialized pharmaceutical-grade blow molding capabilities. Amcor Group GmbH competes on global technical standards transferred to its Thai operations.
Thailand Rigid Plastic Packaging comprises injection-molded, blow-molded, and thermoformed containers with wall thicknesses typically exceeding 0.25 millimeters, engineered to protect contents from moisture, oxygen, and mechanical damage during distribution. PET bottles command the largest volume share due to their clarity, barrier properties, and compatibility with Thailand's recycling infrastructure. Polypropylene containers represent the fastest-expanding material category as heat-resistant grades penetrate ready-meal and hot-fill beverage segments. Food & Beverage end users generate the dominant revenue pool, though pharmaceutical packaging carries the highest per-unit margins.
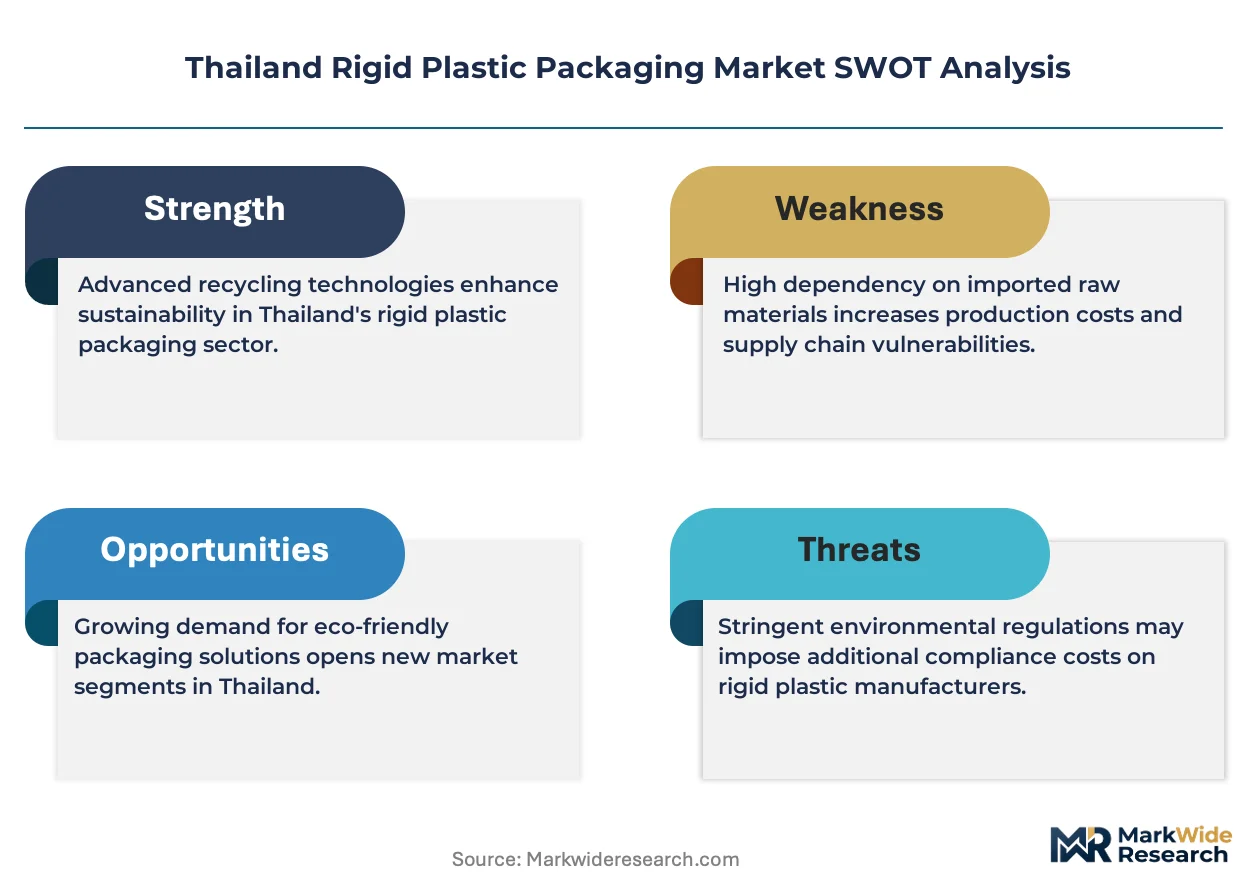
Thailand's Ministry of Natural Resources and Environment enforces plastic waste management regulations that mandate recycled content thresholds for rigid containers sold domestically. The Thai Industrial Standards Institute certifies food-contact safety under TIS standards, creating compliance barriers for unqualified imports. BIS-equivalent testing protocols for migration limits shape formulation decisions among local compounders. Stakeholders must track enforcement intensity around extended producer responsibility schemes before committing to capacity expansion in the Central Plains or Rayong industrial zones.
Market Dynamics
Thailand's Ministry of Natural Resources and Environment is tightening recycled content mandates for rigid containers, forcing domestic converters to reconfigure resin sourcing and blowing equipment specifications across Bangkok and Rayong production corridors.
Growth Catalysts
- Extended producer responsibility schemes:Thailand's waste management regulations now assign collection and recycling accountability to brand owners, creating captive demand for post-consumer PET flake from domestic reclaimers.
- Hot-fill polypropylene grades:Heat-resistant PP resins are penetrating ready-meal packaging as Thai food processors expand retortable bowl and tray formats for export markets.
- Eastern Economic Corridor infrastructure:Deep-water port capacity at Laem Chabang and Map Ta Phut is shortening export lead times for blow-molded pharmaceutical containers bound for ASEAN markets.
Market Restraints
- Imported virgin PET price volatility:Thai converters remain exposed to MEG-PTA feedstock cost swings from Middle Eastern and Northeast Asian suppliers with limited local aromatic production.
- Food-contact certification bottlenecks:Thai Industrial Standards Institute migration testing protocols create 4-6 month approval timelines for new barrier additive formulations.
- Glass returnable bottle systems:Premium beverage brands in Bangkok maintain refillable glass loops for carbonated soft drinks, constraining PET penetration in high-margin segments.
Strategic Opportunities
- Isaan region underpenetration:Northeastern Thailand's growing agro-processing base lacks localized rigid packaging capacity, creating white space for thermoformed tray and pail production near Khon Kaen.
- Pharmaceutical serialization mandates:Track-and-trace regulations from Thailand's FDA-equivalent authority will require tamper-evident closures and molded-in authentication features on prescription containers.
- Digital printing convergence:Direct-to-object inkjet systems combined with blow molding lines enable lot-specific customization for contract manufacturing organizations without label inventory.
Industry Challenges
- Recycled-content compounding expertise:Local compounders lack rPET viscosity stabilization capabilities for pharmaceutical-grade applications, forcing reliance on imported preforms.
- Blow molding retrofit capex:Existing SBM equipment requires screw and hot-runner modifications to process 30%+ recycled flake without clarity degradation.
- Multi-layer barrier patent thickets:Oxygen-scavenging adhesive tie-layer technologies remain controlled by foreign licensors, complicating in-house barrier development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Rigid Plastic Packaging Market |
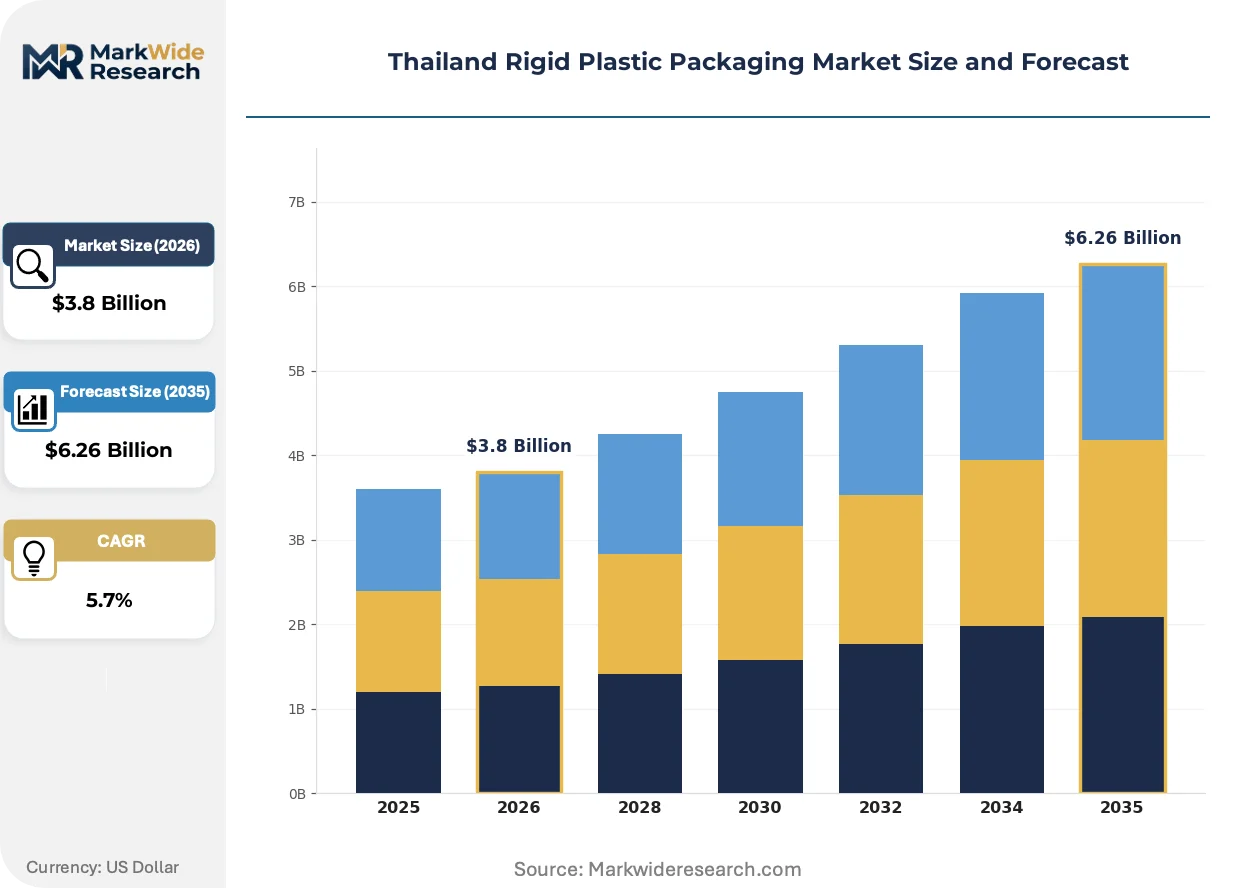
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Material: Polyethylene, Polypropylene, PET, Polystyrene End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Union Thai Polyplast Co. Ltd., Amcor Group GmbH, Berry Global Inc., ALPLA Werke Alwin Lehner GmbH & Co KG, Thai Plaspac Public Company Limited, Nakarin Packaging Co. Ltd., SCG Packaging Public Company Limited, InnoPack, Sealed Air Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Rigid Plastic Packaging Market Trends and Innovations
Lightweighting and barrier engineering are converging to redefine performance thresholds across Thailand's rigid packaging value chain, with equipment suppliers and resin producers racing to meet specifications that were unattainable five years ago.
Mono-material PET barrier structures incorporating plasma-enhanced chemical vapor deposition are collapsing the traditional separation between premium glass and commodity plastic in edible oil and sauce categories. Thai food exporters targeting Japanese retail channels are adopting these formats to reduce freight cube while maintaining 12-month shelf stability. The technology is collapsing glass converter margins in segments where clarity and oxygen transmission rates were previously disqualifying.
Thailand's Ministry of Natural Resources and Environment is phasing in mandatory recycled content thresholds for rigid containers sold domestically, with enforcement intensity accelerating post-certification of domestic mechanical recycling capacity. Local brand owners are pre-qualifying suppliers against these standards ahead of formal deadlines to secure shelf placement in modern retail. The pharmaceutical segment faces the steepest compliance curve due to FDA-equivalent purity requirements that conflict with current rPET feedstock quality.
Consolidated procurement by Bangkok-based food and beverage conglomerates is compressing supplier rosters and demanding integrated design-to-delivery service models. Mid-sized converters are responding by embedding technical sales engineers at customer innovation centers rather than competing on unit pricing alone. The Central Plains region exhibits the most pronounced buyer concentration, with three processing groups controlling majority PET bottle offtake for domestic carbonated and still water categories.
Thailand Rigid Plastic Packaging Market Segmentation
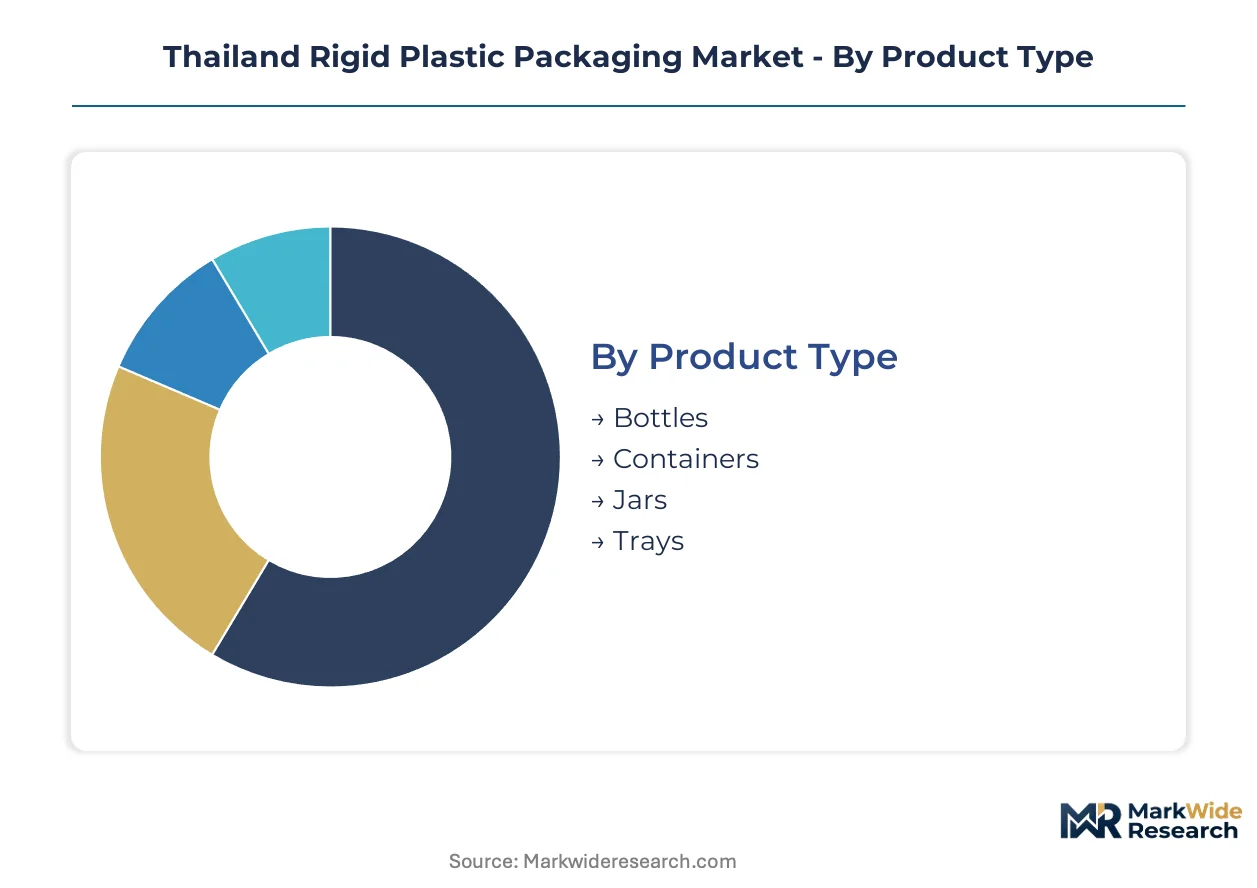
Thailand's rigid plastic packaging market fragments across four structural dimensions that determine resin selection, barrier engineering, and route-to-market economics. Each segmentation layer reveals distinct margin profiles and regulatory exposure patterns across Bangkok's processing corridors and the Eastern Economic Corridor.
Product Type:
Cost tier differentiation separates commodity formats from precision-engineered pharmaceutical and food-contact containers requiring specialized blow molding or thermoforming investments.
- Bottles:PET bottles dominate procurement volumes from Bangkok-based beverage conglomerates, with lightweighting technology narrowing the historical performance gap against glass in premium edible oil and sauce categories. SCG Packaging and Thai Plaspac anchor capacity along Thailand's Eastern Seaboard to serve carbonated soft drink and bottled water manufacturers facing Ministry of Natural Resources and Environment recycled content mandates.
- Containers:Injection-molded pails and tight-head drums concentrate in Rayong industrial zones, supplying agro-chemical and lubricant blenders with UN-certified transport packaging. Heat-sealed polypropylene variants are penetrating retortable ready-meal formats as Thai food processors expand export-oriented production.
- Jars:Wide-mouth PET and polystyrene jars serve confectionery and condiment segments with clarity requirements that mechanical recycling feedstocks struggle to satisfy.
- Trays:Thermoformed PET and polystyrene trays cluster near fresh produce packing houses in the Central Plains, with mono-material designs gaining preference under extended producer responsibility sorting protocols.
Bottles holds installed capacity. Containers is rotating up the share rankings.
Material:
Application-specific barrier and thermal requirements drive resin selection, with regulatory compliance timelines creating formulation lock-in effects across food-contact and pharmaceutical segments.
- Polyethylene:HDPE pails and drums anchor industrial chemical packaging demand from Map Ta Phut petrochemical complexes, with blow molding grade availability tied to regional ethylene cracker operating rates.
- Polypropylene:Heat-resistant grades represent the steepest expansion trajectory as retortable bowl and hot-fill beverage applications displace traditional metal can formats in Thai ready-meal exports. Random copolymer specifications from Eastern Economic Corridor resin producers are narrowing the clarity gap with PET in transparent containers.
- PET:Bottle-grade resin commands dominant volume share due to compatibility with Thailand's mechanical recycling infrastructure and Thai Industrial Standards Institute food-contact certification pathways.
- Polystyrene:Crystal and high-impact grades persist in dairy and confectionery trays despite regulatory pressure on single-use formats, with domestic styrene monomer supply constraints affecting pricing volatility.
PET holds installed capacity. Polypropylene is rotating up the share rankings.
End User:
Customer type determines certification burden, with pharmaceutical and food-contact segments imposing the steepest compliance curves against FDA-equivalent and TIS migration testing protocols.
- Food & Beverage:Carbonated soft drink, bottled water, and edible oil manufacturers generate dominant procurement volumes, with consolidated buying power among three Bangkok processing groups compressing supplier margins and demanding integrated design-to-delivery service models.
- Personal Care:Cosmetic and home care brand owners specify high-clarity PET and decorated PP containers with pump and trigger closure compatibility, with e-commerce shipment durability requirements driving wall thickness specifications above traditional retail formats.
- Pharmaceuticals:Prescription and over-the-counter drug packaging carries the highest per-unit margins, with Thailand FDA-equivalent serialization mandates forcing tamper-evident closure investments and creating barriers for converters lacking pharmaceutical-grade cleanroom blow molding capability.
- Household Products:Agro-chemical and cleaning compound distributors specify chemical-resistant HDPE containers with child-resistant closure compatibility, with UN transport certification requirements limiting qualified supplier pools.
Food & Beverage holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Distribution Channel:
Volume concentration and order fragmentation patterns shape converter sales force deployment, with direct account management yielding to platform-based procurement in emerging segments.
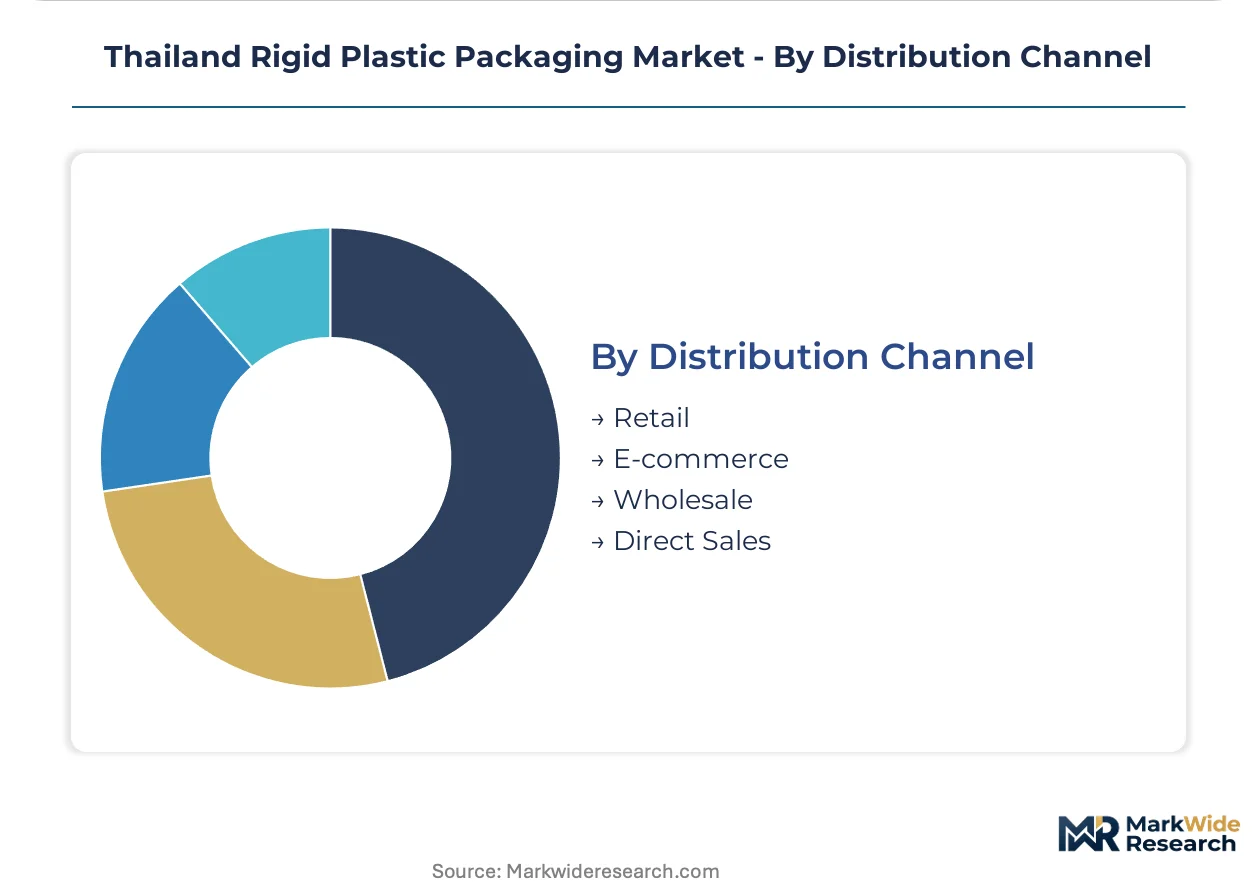
- Retail:Modern trade and traditional trade offtake dominates finished goods packaging demand, with shelf placement negotiations driving brand owners to pre-qualify suppliers against anticipated recycled content mandates ahead of formal regulatory deadlines.
- E-commerce:Direct-to-consumer shipment formats are expanding secondary packaging specifications for damage resistance, with corrugated-integrated rigid containers and returnable tote systems penetrating Bangkok metropolitan fulfillment networks.
- Wholesale:Bulk institutional and foodservice procurement concentrates in Central Plains distribution hubs, with private-label converters competing on volume scale and lead time reliability rather than technical differentiation.
- Direct Sales:Contract manufacturing organizations and specialized pharmaceutical packers negotiate direct supply agreements with blow molding specialists, embedding technical sales engineers at customer innovation centers to secure multi-year capacity allocations.
Retail holds installed capacity. E-commerce is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai rigid plastic packaging exports flow primarily to ASEAN neighbors and Japanese retail channels, with Bangkok-based converters leveraging Laem Chabang port capacity to shorten lead times for blow-molded pharmaceutical containers and retortable food trays.
Central Plains
Carbonated soft drink and bottled water manufacturers cluster around Bangkok's distribution hubs, driving dominant PET bottle procurement volumes. Thailand's Ministry of Natural Resources and Environment recycled content mandates force converters here to reconfigure resin sourcing ahead of formal deadlines. Three processing groups control majority offtake, compressing supplier margins and demanding integrated design-to-delivery service models.
Eastern Economic Corridor
Deep-water port capacity at Laem Chabang and Map Ta Phut anchors export-oriented production for pharmaceutical and food-contact containers. SCG Packaging and Thai Plaspac operate integrated resin-to-container supply chains along this corridor. The Thai Industrial Standards Institute certification pathways here create compliance barriers for unqualified imports.
Rayong Industrial Zone
Injection-molded pails and tight-head drums concentrate to serve agro-chemical and lubricant blenders with UN-certified transport packaging. Random copolymer polypropylene specifications from Eastern Economic Corridor resin producers narrow clarity gaps with PET. Enforcement intensity around extended producer responsibility schemes shapes capacity expansion decisions.
Isaan Region
Northeastern Thailand's growing agro-processing base lacks localized rigid packaging capacity, creating white space for thermoformed tray and pail production. Khon Kaen sits at the center of this underpenetrated zone. Track-and-trace regulations from Thailand's FDA-equivalent authority will require tamper-evident closures for contract manufacturing organizations.
Southern Peninsula
Rubber and palm oil processing clusters generate specialized container demand for chemical-resistant HDPE formats. Provincial distribution networks remain fragmented compared to Central Plains concentration. Local compounders struggle with rPET viscosity stabilization for pharmaceutical-grade applications, forcing reliance on imported preforms.
Thailand Rigid Plastic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Thailand's rigid plastic packaging value chain. Bangkok-based beverage conglomerates consolidate procurement, compressing supplier rosters and embedding technical sales engineers at customer innovation centers. Three strategic archetypes dominate: integrated petrochemical-to-converter conglomerates, specialized pharmaceutical-grade blow molding specialists, and global technical standard-bearers with Thai operations. Competitive moves center on recycled-content compounding investments and digital printing convergence with blow molding lines.
Among Thailand-based public limited companies, SCG Packaging Public Company Limited and Thai Plaspac Public Company Limited anchor domestic capacity with integrated and specialized capabilities respectively. Amcor Group GmbH represents the global technical standards archetype, transferring international specifications to Thai manufacturing footprints. These three exemplify the tiered structure where local integration competes with global scale.
| Leading Market Players |
|---|
| Union Thai Polyplast Co. Ltd. |
| Amcor Group GmbH |
| Berry Global Inc. |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Thai Plaspac Public Company Limited |
| Nakarin Packaging Co. Ltd. |
| SCG Packaging Public Company Limited |
| InnoPack |
| Sealed Air Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Rayong's blow molding corridor is forcing converters to absorb resin cost volatility while ceding pricing power to Bangkok-based beverage conglomerates with consolidated procurement leverage. Thailand's Ministry of Natural Resources and Environment recycled content mandates are layering compliance premiums onto base resin costs, compressing margins for converters lacking backward integration into compounding.
Pricing Analysis
Next-generation mono-material PET barrier structures command 15-25% premiums over conventional multilayer formats, while legacy glass-competitive lightweighting grades face downward pressure from imported preform competition. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial formats separates converters by Thai Industrial Standards Institute certification tier and cleanroom capability. Cost compression in commodity PET bottles is intensifying because Middle Eastern MEG-PTA feedstock volatility transmits directly to converter P&Ls. Food & Beverage procurement teams exhibit highest price sensitivity, while pharmaceutical packers prioritize barrier performance and serialization readiness over unit economics.
Supply Chain Analysis
Tariff exposure between Thailand and regional ASEAN competitors dominates supply chain risk calculus for export-oriented converters serving Japanese retail channels. Geographic supply concentration centers on Saudi Arabia and South Korea for purified terephthalic acid, with domestic ethylene crackers in Map Ta Phut feeding polypropylene expansion. Raw material dependencies include bottle-grade PET resin, heat-stabilized polypropylene copolymers, and oxygen-scavenging adhesive tie-layers subject to foreign licensor control. Single-source vulnerability in pharmaceutical-grade rPET compounding expertise forces reliance on imported preforms. Distribution runs through Laem Chabang deep-water port for ASEAN pharmaceutical exports, with Central Plains road networks serving domestic beverage offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass returnable bottle systems in Bangkok's premium beverage segment represent a persistent substitution threat that rigid plastic incumbents must navigate through barrier performance and sustainability positioning. Incumbents face margin compression from consolidated buyer power and regulatory compliance layering.
For Market Incumbents: Build captive rPET compounding capabilities to secure Ministry of Natural Resources and Environment compliance ahead of formal recycled content deadlines. SCG Packaging's integrated resin-to-container model demonstrates how backward integration into mechanical recycling feedstock quality control defends margin structure against imported preform price volatility. Pharmaceutical-grade cleanroom blow molding capacity represents a defendable moat as Thailand FDA-equivalent serialization mandates steepen compliance curves. For New Entrants and Emerging Players: Isaan region's thermoformed tray and pail production gap offers first-mover positioning near Khon Kaen's agro-processing clusters. Khon Kaen sits at the center of Thailand's most underpenetrated rigid packaging zone, with localized capacity able to capture provincial distribution cost advantages against Bangkok-sourced supply. Contract manufacturing organization relationships provide the most penetrable entry path, embedding technical sales engineers at customer innovation centers to secure multi-year capacity allocations without competing on unit pricing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade blow molding as Thailand FDA-equivalent track-and-trace regulations mandate tamper-evident closure investments and molded-in authentication features. Long-term viability favors converters with demonstrated Thai Industrial Standards Institute certification pathways and established relationships with Bangkok-based beverage conglomerates. Watch enforcement intensity around extended producer responsibility schemes as the signal for capacity rationalization versus expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Compounding Investment | Captive rPET feedstock quality secures Ministry compliance and defends margin structure against imports. |
| Pharmaceutical Cleanroom Capacity Expansion | Thailand FDA-equivalent serialization mandates create barriers for uncertified competitors in prescription packaging. |
| Digital Printing Convergence | Direct-to-object inkjet integration with blow molding lines enables lot-specific customization without label inventory. |
| Isaan Regional Manufacturing Footprint | Localized production near Khon Kaen agro-processors captures distribution cost advantages in underpenetrated Northeast. |
| Extended Producer Responsibility Pre-qualification | Early supplier certification against anticipated mandates secures shelf placement in modern retail consolidation. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Plant managers at Eastern Economic Corridor converters, procurement leads at Bangkok beverage conglomerates, distribution channel partners in Central Plains logistics hubs, and technical R&D directors at resin compounders provided operating-level perspective. Secondary sources included Thai Industrial Standards Institute certification records, customs trade data for PET resin and preform imports, SEC filings from Thailand-based packaging public limited companies, and Ministry of Natural Resources and Environment regulatory announcements. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Forecast inputs considered product type segmentation across bottles, containers, jars, and trays; material categories spanning PET, polypropylene, polyethylene, and polystyrene; end-user verticals from Food & Beverage through pharmaceuticals; and distribution channel dynamics including retail, e-commerce, wholesale, and direct sales. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trends across the analysis window. Industry-specific inputs included recycled content mandate phase-in schedules and hot-fill polypropylene grade adoption curves in ready-meal export formats.
Practitioners should monitor Ministry enforcement intensity around extended producer responsibility schemes and domestic mechanical recycling capacity certification for early signals of compliance cost inflection. Forecasts reflect assumptions regarding regulatory timeline adherence, feedstock price transmission mechanisms, and buyer consolidation trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Poland Plastic Packaging Tubes Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
South Africa Plastic Packaging Films Market